Monday's crude outlook bought a dip into 87.80 to 88.10, and it did not end well. December WTI traded into the band overnight and dipped to 87.59 in the 10:00 PM ET bar, then reached the first objective at 89.15 with the 89.47 high of the 1:30 AM ET bar. That was as good as it got. The session high of 89.49 in the 3:30 AM ET bar fell 0.86 short of the second objective at 90.35, and the 86.75 stop first traded in the 9:30 AM ET bar, which reached 86.67, before the 10:00 AM ET bar extended the decline to 86.33.
The objective was worth 1.35 points from the bottom of the band. A position held for the second objective lost 1.05 points from the bottom of the band and 1.35 from the top. We count that as a loss.
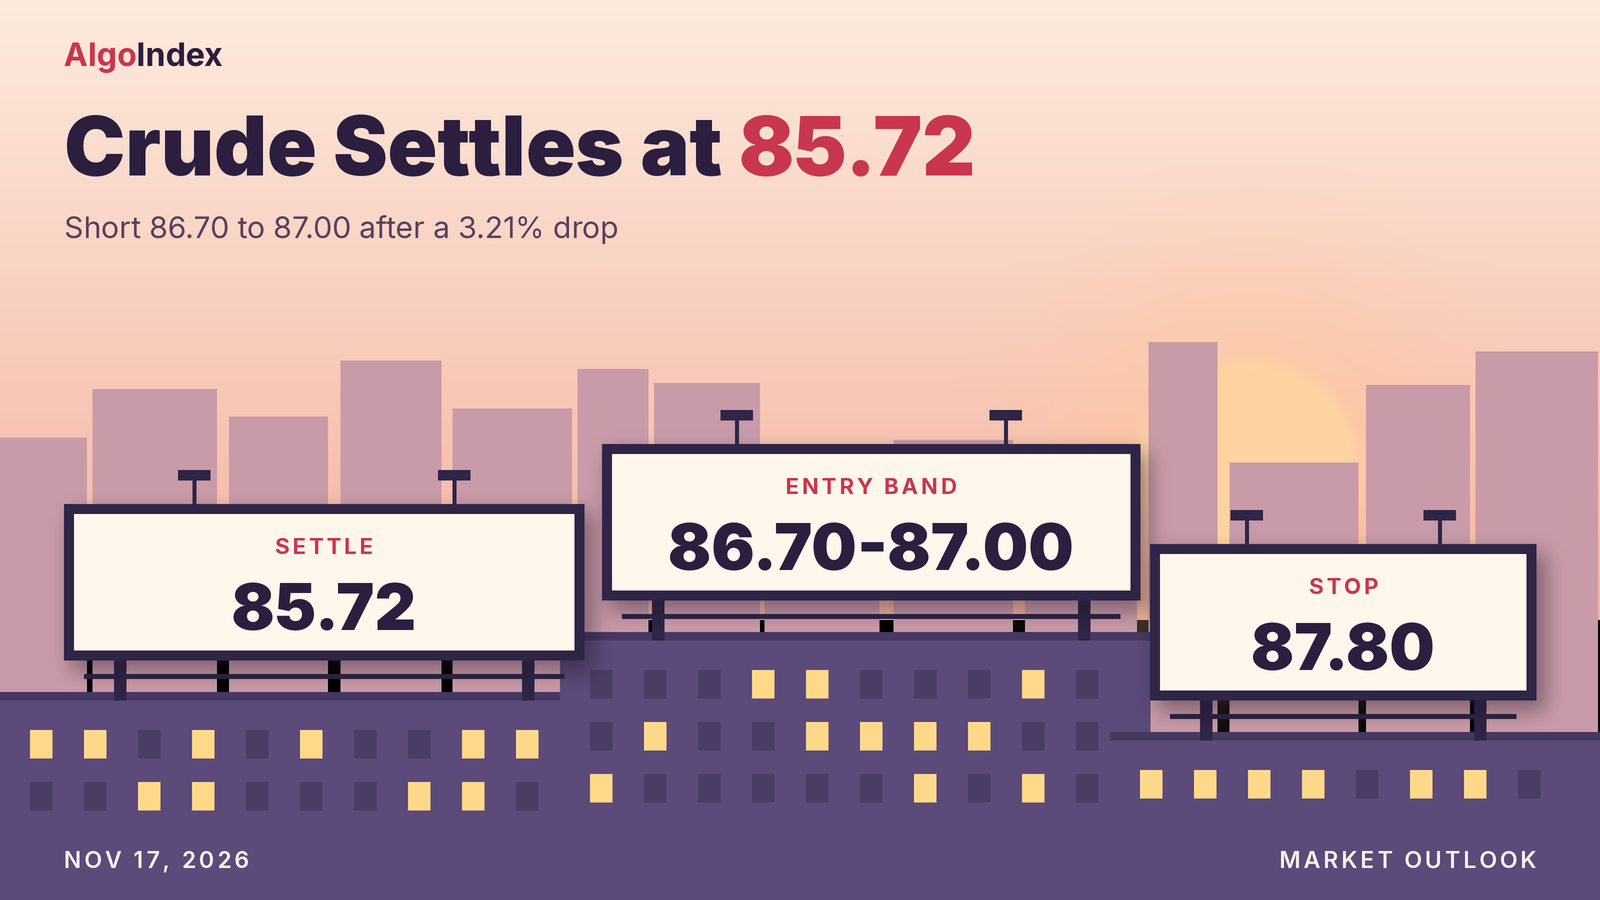
Crude settled at 85.72, down 2.84 or 3.21 percent, its lowest settle since 09/04/26. For Tuesday the plan flips: it sells a rebound into 86.70 to 87.00.
At a glance
- Settle 85.72, down 2.84; range 85.02 to 89.49; widest range since 11/09/26.
- Tuesday's setup: short 86.70 to 87.00, stop 87.80, objectives 85.90, 84.95 and an extended 84.00.
- Thesis negated on a settle above two standard deviation resistance at 87.74; two consecutive 30-minute closes above 87.00 remove the edge.
- The settle sits beneath the 5-day, 9-day, 20-day and 50-day averages and above the 100-day and 200-day.
- Calendar: US retail sales 8:30 AM ET; tanker reports from the Strait of Hormuz are the main headline risk.
How Monday traded: a high at 3:30 AM ET, then lower lows into the settle
Europe set the top. The 3:00 AM ET bar rose 0.60 to 89.29 and the 3:30 AM ET bar printed the 89.49 high across 1.04 points, the widest bar of the session, before closing 0.60 lower. The 4:00 AM ET bar fell another 0.60 to 88.11.
The US morning added to it. The 9:00 AM ET bar fell 0.64 to 87.05, the largest decline of any bar, and from 11:00 AM ET through 1:30 PM ET each bar printed a lower low than the one before, from 86.51 to 85.34. The settle was fixed at 85.72 at 2:30 PM ET and the 4:30 PM ET bar printed the 85.02 low after the settle.
Monday's high sat 0.15 beneath Friday's 89.64 and its low 2.78 beneath Friday's 87.80. Volume eased to 177,330 contracts from 201,766.
Supply worries and a strong dollar outweighed the tanker headlines
Published commentary pointed to the international energy agency's projected surplus this quarter and to a US estimate that crude and fuel flows through the Strait of Hormuz rose 7 percent in the third quarter to 9.1 million barrels a day. The dollar index closed at 103.55, described as a 1.5-year high.
The headlines that usually lift crude arrived late. Iranian state media reported a fourth tanker striking a mine in the strait at 3:16 PM and 3:25 PM ET, and a maritime security report at 4:35 PM ET described an attack that disabled a tanker. The electronic session fell anyway, to 85.16 in the 4:00 PM ET bar and 85.02 in the 4:30 PM ET bar.
Products fell harder. Heating oil's December contract dropped 4.15 percent to 4.0818 dollars a gallon and gasoline 3.19 percent to 2.5379. December's premium over January narrowed to 1.25 from 1.27. Managed money held 148,092 long against 122,378 short in the latest weekly report.
The trade map for Tuesday
The setup sells a rebound into 86.70 to 87.00, at the Pivot Point at 86.74 and beneath one standard deviation resistance at 87.15. The stop at 87.80 sits above two standard deviation resistance at 87.74, at the 87.80 retracement from the 13-week low.
Objectives sit at 85.90, above Monday's 85.72 settle; 84.95, beneath Monday's 85.02 low; and an extended 84.00, at Pivot S1 at 84.00. From the 86.85 midpoint, risk is 0.95 points and the objectives sit 0.95, 1.90 and 2.85 points away.
Confirmed attacks on tankers or Gulf infrastructure, a reversal lower in the dollar or a strong retail sales report could lift the contract through 87.80. The 9-day average at 87.99 is then the next reference, well inside the 14-day average true range of 4.17.
| Item | Detail |
|---|---|
| Direction | Short |
| Entry zone | 86.70 to 87.00 |
| Stop | 87.80 (above two standard deviation resistance at 87.74, at the 87.80 retracement from the 13-week low) |
| Objective 1 | 85.90 (above Monday's 85.72 settle) |
| Objective 2 | 84.95 (beneath Monday's 85.02 session low) |
| Objective 3 (extended) | 84.00 (at Pivot S1 at 84.00) |
| Risk from band midpoint | 0.95 points |
| Invalidation | A settle above two standard deviation resistance at 87.74 negates the thesis. Short of that, the edge is removed by acceptance above the entry band rather than by a touch, defined as two consecutive 30-minute closes above 87.00. |
| What could change it | Confirmed attacks on tankers or Gulf infrastructure, a reversal lower in the dollar, or a strong retail sales report would lift the contract. In that scenario a move through the 87.80 stop invalidates the short before the targets, and the 9-day average at 87.99 becomes the reference, 0.19 beyond the stop and well inside one 14-day average true range of 4.17. |
How Tuesday could unfold
Night Session (6:00 PM ET Monday to 3:00 AM ET Tuesday, Globex/Asia)
Globex reopened at 6:00 PM ET on Monday at 85.16, beneath Monday's 85.72 settle, after the post-settle reports of a disabled tanker in the Strait of Hormuz. The Reserve Bank of Australia minutes are listed for 7:30 PM ET on Monday by the news-feed calendar, unconfirmed. In our judgment the overnight session is likely to hold between one standard deviation support at 84.29 and the Pivot Point at 86.74, with further Gulf reports the main source of a move outside it; expected band roughly 84.40 to 86.60.
London Session (3:00 AM to 8:00 AM ET Tuesday)
UK labor market figures are listed for 2:00 AM ET on Tuesday and the German investor sentiment survey for 5:00 AM ET by the news-feed calendar, unconfirmed. Bias neutral to lower beneath the Pivot Point at 86.74, expected band roughly 84.50 to 86.70, with the dollar's direction after Monday's 1.5-year high, attributed to the published commentary, the main cross-asset input.
Morning Session (9:00 AM to 12:00 PM ET Tuesday, US Open / Pit Session)
The US retail sales report and import prices are scheduled for 8:30 AM ET on Tuesday, November 17, 2026, and the news-feed calendar lists a 0.1 percent monthly consensus for retail sales against 0.8 percent previously, unconfirmed. Industrial production follows at 9:15 AM ET on Tuesday, November 17, 2026. The cash open at 9:30 AM ET sets the first directional test for the related markets. Expected band roughly 84.20 to 87.00, with the 86.70 to 87.00 setup band at the upper edge.
Afternoon Session (12:00 PM to 2:30 PM ET Tuesday, NYMEX Pit Close)
Remarks by New York Fed President Williams are listed for 2:25 PM ET on Tuesday by the news-feed calendar, unconfirmed. The settlement at 2:30 PM ET fixes the reference, with Pivot S1 at 84.00 the lower reference and expected band roughly 84.00 to 86.80.
Night Session Forward (6:00 PM ET Tuesday)
NVIDIA's results conference call is scheduled for 5:00 PM ET on Tuesday, November 17, 2026, and the reaction in equity index futures may carry into crude through the risk channel. The weekly petroleum status report at 10:30 AM ET on Wednesday, November 18, 2026, is the next crude-specific release, and the December contract's expiration on 11/20/26, listed by the data service, approaches.
Most Likely Path
In our analyst judgment, the most probable path holds beneath the Pivot Point at 86.74 overnight, rebounds toward the 86.70 to 87.00 band around the US data and fails there, then trades back toward Monday's 85.02 low and one standard deviation support at 84.29. A settle near the low, a lower high, a lower low, the composite at "24% SELL" and the settle beneath the 9-day, 20-day and 50-day averages support that reading, while the 11 consecutive settles beneath the 9-day average and a 9-day relative strength of 33.42 argue that the decline is extended and that a test of Pivot S1 at 84.00 is more likely than a run beneath it.
The alternative that would invalidate this reading is a settle above two standard deviation resistance at 87.74, which would bring the 9-day average at 87.99 and Pivot R1 at 88.47 back into play; further confirmed attacks on tankers in the Gulf or a reversal in the dollar are the inputs most likely to drive that alternative. On the other side, a weak retail sales report and a further dollar advance could carry the contract through Pivot S1 at 84.00 toward the 83.88 one-month low without the rebound the setup needs.
The complete data picture
Every level behind Tuesday's plan, charted first; the full numeric reference from Monday's review follows underneath.
| Resistance, top to bottom | Support, top to bottom |
|---|---|
| 89.49 Monday's high | 85.63 Published target price |
| 88.47 Pivot R1 | 85.02 Session low, 4:30 PM ET bar |
| 88.20 Three standard deviation resistance | 84.29 One standard deviation support |
| 88.12 9-day average stall | 84.00 Pivot S1 |
| 87.99 9-day average | 83.88 One-month low of 11/10/26 |
| 87.80 Retracement from the 13-week low | 83.70 Two standard deviation support |
| 87.74 Two standard deviation resistance | 83.66 Crossover stall |
| 87.37 Stochastic stall | 83.24 Three standard deviation support |
| 87.19 High of the 10:30 AM ET bar | 82.27 Pivot S2 |
| 87.15 One standard deviation resistance | 80.31 Midpoint of the 52-week range |
| 87.12 5-day average | 79.53 Pivot S3 |
| 86.94 Low of the 9:00 AM ET bar | |
| 86.74 Pivot Point | |
| 85.74 Close of the 2:00 PM ET bar |
- Pivot ladder: R3 92.94, R2 91.21, R1 88.47, Pivot Point 86.74, S1 84.00, S2 82.27, S3 79.53.
- Monday versus prior sessions: settle 3.77 beneath the high and 0.70 above the low; down 1.13 or 1.30 percent over five sessions; largest decline since the 4.38 percent drop of 11/09/26; lowest settle since 85.46 on 09/04/26.
Full numeric reference: every remaining figure from Monday's review
Executive Summary
The December crude contract settled at 85.72 on Monday, down 2.84 or 3.21 percent from Friday's settle of 88.56, after trading between 89.49 and 85.02, a 4.47 point daily range. The settle finished 0.70 above the low and 3.77 beneath the high. Monday printed a lower high, 0.15 beneath Friday's 89.64, and a lower low, 2.78 beneath Friday's 87.80, and the 4.47 point range was the widest since the 6.40 point range of 11/09/26, against a published 14-day average daily range of 4.52 points.
Monday was the second consecutive lower settle, the 85.72 settle is the lowest since the 85.46 settle of 09/04/26, and the 3.21 percent decline is the largest since the 4.38 percent decline of 11/09/26. Over five sessions the contract is down 1.13 from the 86.85 settle of 11/09/26, a decline of 1.30 percent. The settle sits above the 100-day and 200-day settlement averages and beneath the 5-day, 9-day, 20-day and 50-day, and it is the first settle beneath the 5-day average after two settles above it.
The session high of 89.49 printed in the 3:30 AM ET bar, and from there the contract traded lower through the European morning and the US cash hours. Each 30-minute bar from 11:00 AM ET through 1:30 PM ET printed a lower low than the bar before it, and the settle was fixed at 85.72 at 2:30 PM ET.
The news feed carried Iranian state media reports at 3:16 PM ET and 3:25 PM ET of a fourth tanker striking a mine in the Strait of Hormuz within 24 hours, and at 4:35 PM ET a report from the UK maritime security agency of an attack that disabled a tanker transiting the strait. Those reports arrived after the 2:30 PM ET settle, and the electronic session did not rise on them: the 4:00 PM ET bar fell to 85.16 and the 4:30 PM ET bar printed the session low of 85.02 before closing at 85.06, 0.66 beneath the settle.
The composite multi-indicator read published on Monday evening is "24% SELL" with strength "Minimum" and direction "Average", from "16% SELL" a session earlier. Tuesday's setup is a short from the 86.70 to 87.00 band, at the Pivot Point at 86.74 and beneath one standard deviation resistance at 87.15, stopped at 87.80, with objectives at 85.90, 84.95 and an extended 84.00. In our judgment the dollar and the surplus narrative were the first-order inputs on Monday, and Tuesday's 8:30 AM ET retail sales report, together with Gulf tanker reports, are the inputs into Tuesday.
Price Action & Technical Structure
Intraday and Session Review
The Monday session opened at 88.65 at the Sunday 6:00 PM ET reopen, 0.09 above Friday's settle and 0.27 beneath the 88.92 close of Friday's 4:30 PM ET bar. Between the 6:00 PM ET reopen and 3:00 AM ET the 30-minute series held between 87.59, in the 10:00 PM ET bar, and 89.47, in the 1:30 AM ET bar, and the window closed at 88.71 in the 2:30 AM ET bar.
From 3:00 AM ET to 9:30 AM ET the contract traded between 86.94 and 89.49. The 3:00 AM ET bar rose 0.60 to 89.29, the 3:30 AM ET bar carried the session high of 89.49 and spanned 1.04 points, the widest of any bar in the session, before closing 0.60 lower, and the 4:00 AM ET bar fell a further 0.60 to 88.11. The 8:30 AM ET bar, which spans the New York manufacturing survey listed for 8:30 AM ET on Monday by the news-feed calendar, unconfirmed, traded across 0.43 and closed at 87.70. The 9:00 AM ET bar fell 0.64 to 87.05, the largest decline of any bar in the session, and printed the 86.94 low of the window.
Across the hours from 9:30 AM ET to the 2:30 PM ET settlement the bars held between 85.34, in the 1:30 PM ET bar, and 87.19, in the 10:30 AM ET bar. The 10:00 AM ET bar traded down to 86.33, the 10:30 AM ET bar recovered to 87.19 and closed at 86.71, and each bar from 11:00 AM ET through 1:30 PM ET then printed a lower low than the bar before it, from 86.51 to 85.34. The 2:00 PM ET bar closed at 85.74 and the settle was fixed at 2:30 PM ET at 85.72.
After the settle the 2:30 PM ET bar closed at 85.56, the 3:00 PM ET and 3:30 PM ET bars held between 85.44 and 85.66, the 4:00 PM ET bar fell to 85.16 and the 4:30 PM ET bar printed the session low of 85.02 before closing at 85.06. Globex reopened at 6:00 PM ET, so the published overview, read at 6:18 PM ET, already carries the new session dated Tuesday, with an open of 85.16, a high of 85.59, a low of 85.06 and a previous close field of 85.72; those three prices belong to Tuesday's session, not to Monday's.
The published Pivot Point is 86.74.
Daily Structure
Monday printed a lower high and a lower low against Friday and settled 2.84 lower, 0.70 above the low and in the lower sixth of the range. Settlements over the last six sessions read 86.85, 86.04, 86.53, 88.74, 88.56 and 85.72, so Monday erased the 2.70 point gain of Wednesday and Thursday and settled 0.32 beneath Tuesday's 86.04.
The 85.02 low is the lowest since the 83.88 low of 11/10/26, which the data service publishes as the one-month low. The data service publishes 104.99 as the 52-week, 13-week and one-month high and 77.18 as the 13-week low. The settle sits 0.41 beneath the 86.13 level published as the 61.8 percent retracement from the 52-week low and 2.08 beneath the 87.80 level published as the 38.2 percent retracement from the 13-week low.
In our interpretation a wide range day with a settle near the low, a lower high and a lower low ends the three-session recovery from the 83.88 low and leaves the settle 1.84 above it. The structure of lower highs from the 104.99 high of 10/30/26 is unchanged, with the settle beneath the 9-day, 20-day and 50-day averages.
4-Hour and Swing Structure
The 4.47 point range followed ranges of 2.93 on Wednesday, 4.02 on Thursday and 1.84 on Friday. In the 30-minute series one bar, at 3:30 AM ET, spanned more than 1.00 from high to low, and three bars, at 3:30 AM ET, 4:00 AM ET and 9:00 AM ET, each fell 0.60 or more from open to close.
The swing sequence since the 104.99 high of 10/30/26 shows lower highs at 91.42 on 11/09/26 and 86.93 on 11/10/26, three higher highs at 88.74, 89.15 and 89.64 from 11/11/26 to 11/13/26, and Monday's 89.49 high beneath Friday's. The lows read 83.88 on 11/10/26, 85.81 on 11/11/26, 85.13 on 11/12/26, 87.80 on 11/13/26 and 85.02 on Monday, so Monday's low held 1.14 above the 83.88 one-month low.
Daily ranges over the last ten sessions, from 11/03/26, ran 5.23, 10.02, 4.67, 3.46, 6.40, 3.05, 2.93, 4.02, 1.84 and 4.47. The published grid places the 3-10 day average crossover stall at 83.66, the 14 day stochastic stall at 87.37, the 40-day average stall at 87.98 and the 9-day average stall at 88.12.
Moving Averages
The 5-day average stands at 87.12, the 9-day at 87.99, the 20-day at 94.64, the 50-day at 92.63, the 100-day at 84.68 and the 200-day at 79.25.
The 85.72 settle sits 1.40 beneath the 5-day average, 2.27 beneath the 9-day, 8.92 beneath the 20-day and 6.91 beneath the 50-day, and 1.04 above the 100-day and 6.47 above the 200-day. It is the first settle beneath the 5-day average after two settles above it, the eleventh consecutive settle beneath the 9-day and the 20-day averages, the last settle above both on 10/30/26, and the ninth consecutive settle beneath the 50-day, the last settle above it on 11/03/26. The 5-day average fell from Friday's 87.34 as Monday's settle replaced the 86.85 settle of 11/09/26, and the 9-day fell from 89.14 as the 96.09 settle of 11/03/26 left the window.
The 5-day average sits beneath the 20-day because the 15 older settlements in the 20-day window averaged higher, at 97.14. The 20-day average sits above the 50-day because the 30 older settlements in the 50-day window averaged lower, at 91.28. The 50-day sits above the 100-day because the 50 older settlements in the 100-day window averaged lower, at 76.74, and the 100-day sits above the 200-day because the 100 older settlements in the 200-day window averaged lower, at 73.81.
Oscillator and Trend Readings
The 9-day relative strength reads 33.42, the 14-day relative strength 38.19 and the 20-day relative strength 42.07.
The 9-day raw stochastic reads 13.87 percent and the 14-day raw stochastic 8.72 percent, while the 14-day stochastic %K reads 17.97 percent and the 14-day stochastic %D 17.50 percent. The 9-day directional index ADX reads 44.08 with the 9-day +DI at 12.25 and the 9-day -DI at 31.98, and the 14-day directional index ADX reads 34.45 with the 14-day +DI at 14.45 and the 14-day -DI at 27.89, so negative direction leads on both systems. The 9-day historic volatility reads 53.51 percent and the 14-day historic volatility 55.74 percent.
The composite multi-indicator read published on Monday evening is "24% SELL", with signal strength "Minimum" and direction "Average". The snapshot history reads "16% SELL" for the prior session, "24% SELL" a week ago and "100% BUY" a month ago. The short horizon group averages "60% SELL", the medium group "25% SELL" and the long group "67% BUY", and the trend composite reads "SELL".
Volatility and Expected Range
The published 14-day average true range stands at 4.17 points and the 14-day average daily range at 4.52 points; the 9-day average true range is 4.21 with a 9-day average daily range of 4.54, and the 20-day average true range is 4.05 with a 20-day average daily range of 4.36. Monday's 4.47 point range sat just inside the 14-day average daily range.
Adding and subtracting the 14-day average true range of 4.17 from the 85.72 settle frames Tuesday between 81.55 and 89.89. The published standard-deviation bands, built from five settlements, span 84.29 to 87.15 at one deviation, 83.70 to 87.74 at two and 83.24 to 88.20 at three. These bands describe dispersion, not intraday reach. In our judgment Tuesday's retail sales report and the Gulf tanker reports keep a range near the 14-day average more likely than a contraction, with the December contract's expiration on 11/20/26 adding roll flows during the week.
Key Levels
Resistance
Above the 85.72 settle, the first references are the 85.74 close of the 2:00 PM ET bar and the Pivot Point at 86.74, with the 86.94 low of the 9:00 AM ET bar and the 87.12 five-day average just above. One standard deviation resistance at 87.15, the 87.19 high of the 10:30 AM ET bar and the 87.37 stochastic stall form the next band, followed by two standard deviation resistance at 87.74 and the 87.80 retracement from the 13-week low. The 9-day average at 87.99, the 88.12 stall of the 9-day average and three standard deviation resistance at 88.20 follow, with Pivot R1 at 88.47 and Monday's 89.49 high beyond them.
Support
Beneath the settle sit the 85.63 target price published by the data service and the 85.02 session low of the 4:30 PM ET bar. One standard deviation support at 84.29 and Pivot S1 at 84.00 form the next band, followed by the 83.88 one-month low of 11/10/26, two standard deviation support at 83.70 and the 83.66 crossover stall. Three standard deviation support at 83.24 and Pivot S2 at 82.27 are the deeper references, with the 80.31 midpoint of the 52-week range and Pivot S3 at 79.53 beyond them.
Macro Drivers
OPEC and Supply Policy (Quotas, Compliance, Saudi/Russia Signals)
No producer-group statement was recorded on Monday. The 69th joint ministerial monitoring committee meeting of the producer group is listed for November 29, 2026.
EIA and API Inventory (Crude Stocks, Gasoline, Distillates, Cushing, SPR)
No US petroleum inventory figures were released on Monday on the calendars. The published commentary said the US energy agency estimated that crude oil and fuel flows through the Strait of Hormuz rose 7 percent quarter on quarter in the third quarter to 9.1 million barrels a day, against 21.4 million a year earlier, and tied the acceleration of Monday's losses to that estimate; those are attributed figures. The next weekly petroleum status report is scheduled for 10:30 AM ET on Wednesday, November 18, 2026, and the news-feed calendar lists a draw of 1.483 million barrels as the consensus against a 4.657 million barrel build previously, figures that are unconfirmed.
Geopolitical Backdrop (Middle East, Iran, Russia/Ukraine, Venezuela)
At 3:16 PM ET and 3:25 PM ET the news feed carried Iranian state media reports that a tanker caught fire after striking a mine in the Strait of Hormuz, described as the fourth affected vessel in 24 hours. At 4:34 PM ET and 4:35 PM ET it carried reports from the UK maritime security agency of an incident 7 nautical miles north of Khasab in Oman and of an attack that disabled a tanker transiting the strait with an engine room fire, and at 4:38 PM ET a report of sirens after a drone flew over the Khor Mor gas field in Iraqi Kurdistan. These reports arrived after the 2:30 PM ET settle, and the 30-minute series shows the contract trading down to 85.02 in the 4:30 PM ET bar; the reports and that decline coincided, and the series does not show a supply premium returning after the settle.
During the session the news feed carried at 2:09 PM ET a US military statement that the aircraft carrier Theodore Roosevelt is operating in the Central Command area on a scheduled deployment, at 2:19 PM ET and 2:35 PM ET reports that Iran's foreign minister travelled from Islamabad to Oman, and at 2:26 PM ET a clip of the Vice President saying the United States would not let Iran become even a two-year commitment. These are reports carried by the feeds, and the settlement series does not establish that any single item caused a particular move.
Demand and Refining (Refinery Utilization, Crack Spreads, Seasonal Pattern)
Heating oil's December contract settled at 4.0818 dollars a gallon, down 4.15 percent, and gasoline's December contract at 2.5379, down 3.19 percent, against crude's 3.21 percent decline. Measured on the December contracts, the heating oil margin over December WTI narrowed to 85.72 dollars a barrel from 90.30, and the gasoline margin narrowed to 20.87 from 21.54. The published commentary described gasoline at an 8.25-month low and the crude crack spread at a 7-month low, which is attributed commentary. Natural gas's December contract settled at 3.122, down 3.34 percent. In our interpretation narrowing product margins on a day crude fell more than 3 percent point to weaker product demand rather than to crude-specific selling alone.
Dollar and Cross-Asset (DXY, Commodities Complex, Equity Risk-On/Off)
The dollar index's daily record closed at 103.55, up 0.14 points or 0.14 percent, and the published commentary described a new 1.5-year high, which is attributed commentary. The ten-year yield index closed at 5.12, down from 5.15 on Friday. Gold's December contract fell 0.86 percent, silver's December contract fell 4.61 percent and the S&P 500 cash index fell 1.92 percent, with the semiconductor index down 5.28 percent and the volatility index up 3.61 points to 22.91.
The US manufacturing survey for New York state printed 7.80 against a forecast of 18 and 25.50 previously, released at 8:30 AM ET on Monday per the news-feed calendar and unconfirmed, and the published commentary said the lower crude price reduces inflation expectations. In our interpretation a firmer dollar and broad selling in risk assets weighed on crude through the US session, while the Gulf tanker reports did not lift prices after the settle.
Institutional Positioning (COT, Money Manager vs Commercial Hedger, Speculator Length)
The latest weekly positioning report on the published overview, for the week to Tuesday, November 10, 2026, shows managed money at 148,092 long, up 710, against 122,378 short, down 3,276, as listed. Monday's December volume was 177,330 contracts against 201,766 on Friday, per the settlement record. December's premium over January narrowed to 1.25 from 1.27 as January WTI fell 2.82 to 84.47, and Brent's January premium over January WTI narrowed to 7.97 from 8.55 as Brent's January contract settled at 92.44, down 3.40. The data service lists 11/20/26 as the December contract's expiration date and 11/24/26 as its first notice date.
No Liquid Options Proxy
There is no gamma map, no options concentration levels and no flow attribution, and none is inferred from any other instrument. Every level originates in published pivot arithmetic, published standard-deviation bands, published retracement and moving-average projections, settlement averages computed from the published daily record, or the completed-session extremes described.
The positioning inputs used for crude are the Brent spread, the front calendar spread, the product margins, the volume record and the weekly positioning figures.
Forecast
Night Session (6:00 PM ET Monday to 3:00 AM ET Tuesday, Globex/Asia)
Globex reopened at 6:00 PM ET on Monday at 85.16, beneath Monday's 85.72 settle, after the post-settle reports of a disabled tanker in the Strait of Hormuz. The Reserve Bank of Australia minutes are listed for 7:30 PM ET on Monday by the news-feed calendar, unconfirmed. In our judgment the overnight session is likely to hold between one standard deviation support at 84.29 and the Pivot Point at 86.74, with further Gulf reports the main source of a move outside it; expected band roughly 84.40 to 86.60.
London Session (3:00 AM to 8:00 AM ET Tuesday)
UK labor market figures are listed for 2:00 AM ET on Tuesday and the German investor sentiment survey for 5:00 AM ET by the news-feed calendar, unconfirmed. Bias neutral to lower beneath the Pivot Point at 86.74, expected band roughly 84.50 to 86.70, with the dollar's direction after Monday's 1.5-year high, attributed to the published commentary, the main cross-asset input.
Morning Session (9:00 AM to 12:00 PM ET Tuesday, US Open / Pit Session)
The US retail sales report and import prices are scheduled for 8:30 AM ET on Tuesday, November 17, 2026, and the news-feed calendar lists a 0.1 percent monthly consensus for retail sales against 0.8 percent previously, unconfirmed. Industrial production follows at 9:15 AM ET on Tuesday, November 17, 2026. The cash open at 9:30 AM ET sets the first directional test for the related markets. Expected band roughly 84.20 to 87.00, with the 86.70 to 87.00 setup band at the upper edge.
Afternoon Session (12:00 PM to 2:30 PM ET Tuesday, NYMEX Pit Close)
Remarks by New York Fed President Williams are listed for 2:25 PM ET on Tuesday by the news-feed calendar, unconfirmed. The settlement at 2:30 PM ET fixes the reference, with Pivot S1 at 84.00 the lower reference and expected band roughly 84.00 to 86.80.
Night Session Forward (6:00 PM ET Tuesday)
NVIDIA's results conference call is scheduled for 5:00 PM ET on Tuesday, November 17, 2026, and the reaction in equity index futures may carry into crude through the risk channel. The weekly petroleum status report at 10:30 AM ET on Wednesday, November 18, 2026, is the next crude-specific release, and the December contract's expiration on 11/20/26, listed by the data service, approaches.
Expected Range (Tuesday Full Session)
- Low-range scenario: 84.60 to 86.90
- Mid-range scenario (most likely): 83.90 to 87.60
- High-range scenario: 82.80 to 88.50
Most Likely Path
In our analyst judgment, the most probable path holds beneath the Pivot Point at 86.74 overnight, rebounds toward the 86.70 to 87.00 band around the US data and fails there, then trades back toward Monday's 85.02 low and one standard deviation support at 84.29. A settle near the low, a lower high, a lower low, the composite at "24% SELL" and the settle beneath the 9-day, 20-day and 50-day averages support that reading, while the 11 consecutive settles beneath the 9-day average and a 9-day relative strength of 33.42 argue that the decline is extended and that a test of Pivot S1 at 84.00 is more likely than a run beneath it.
The alternative that would invalidate this reading is a settle above two standard deviation resistance at 87.74, which would bring the 9-day average at 87.99 and Pivot R1 at 88.47 back into play; further confirmed attacks on tankers in the Gulf or a reversal in the dollar are the inputs most likely to drive that alternative. On the other side, a weak retail sales report and a further dollar advance could carry the contract through Pivot S1 at 84.00 toward the 83.88 one-month low without the rebound the setup needs.
Tuesday Economic Calendar
Monday's releases are complete. The New York manufacturing survey was released at 8:30 AM ET on Monday at 7.80 against a forecast of 18 and 25.50 previously, per the news-feed calendar and unconfirmed, and Canadian consumer inflation printed 3.1 percent against a 3.2 percent forecast at the same time, per the news-feed calendar, unconfirmed. Fed Chair Warsh gave opening remarks at 12:00 PM ET on Monday, November 16, 2026, and their content was not available. The news feed carried remarks by Cleveland Fed President Hammack from 2:16 PM ET to 2:27 PM ET, favoring successive rate increases, a news-feed report that is unconfirmed. December WTI settled at 2:30 PM ET at 85.72.
Tuesday brings the US retail sales report and import prices at 8:30 AM ET on Tuesday, November 17, 2026, and industrial production at 9:15 AM ET on Tuesday, November 17, 2026. Remarks by Fed Governor Waller are listed for 9:10 AM ET on Tuesday by the news-feed calendar, unconfirmed. Business inventories follow at 10:00 AM ET on Tuesday, November 17, 2026.
Remarks by St. Louis Fed President Musalem are listed for 7:30 AM ET on Tuesday and by Cleveland Fed President Hammack for 9:30 AM ET on Tuesday by the news-feed calendar, unconfirmed. Remarks by New York Fed President Williams are listed for 2:25 PM ET on Tuesday by the news-feed calendar, unconfirmed. NVIDIA's quarterly results are listed for 4:20 PM ET on Tuesday by the news-feed calendar, unconfirmed, and the results conference call is scheduled for 5:00 PM ET on Tuesday, November 17, 2026.
Later in the week, the weekly petroleum status report is scheduled for 10:30 AM ET on Wednesday, November 18, 2026, and the FOMC minutes for 2:00 PM ET on Wednesday, November 18, 2026. In our judgment the dollar and the 8:30 AM ET retail sales report on Tuesday, are the first-order scheduled inputs for crude, with Gulf tanker reports the main unscheduled one.
Sources and methodology
Prices, settlements and volume come from the exchange settlement record and the daily series for the December contract (CLZ26). Session timing comes from Monday's 30-minute bars. Moving averages were computed from completed daily settlements; oscillators, the composite read and the pivot ladder are quoted as published. Crude levels come from pivot arithmetic, standard-deviation bands, retracements and moving averages; no options positioning map is used for crude.
The prior card is graded only on its own levels, across Monday's full session, and a stop that traded counts as a loss in full.
The tanker headlines failed to lift crude on Monday, and Tuesday's band sits right where the selling started.
This article is market commentary for educational purposes and is not investment advice. Futures and options trading involves substantial risk of loss and is not suitable for every investor. Past results do not guarantee future results.