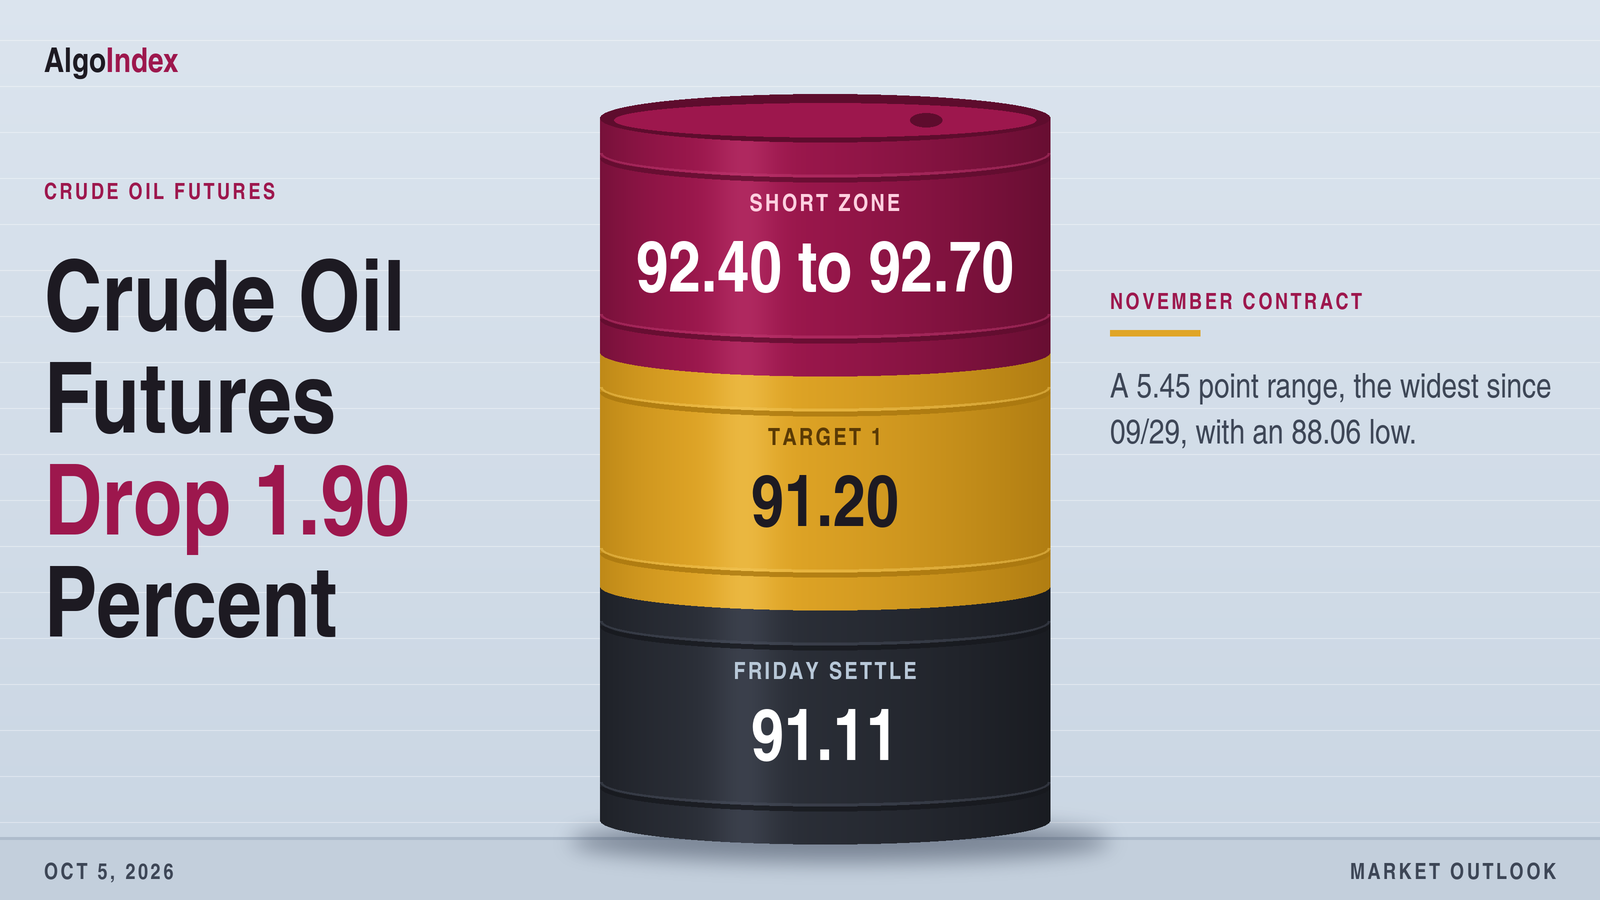
At the Thursday 6:00 PM ET reopen, November crude opened at 93.46 and printed 93.51 inside the first 30-minute bar. Nothing traded higher all session. The contract slid through the European morning to 88.83 in the 5:00 AM ET bar, and the 9:00 AM ET bar printed the 88.06 session low. It settled at 91.11 at 2:30 PM ET, down 1.76 points or 1.90 percent from Thursday's 92.87. It finished 3.05 above the low. Volume printed 326,828 contracts on the provider's dated daily record for Friday, against 337,181 on Thursday's row.
Friday traded between 93.51 and 88.06, a 5.45 point range, and finished at 56.0 percent of it. That range was 1.18 times the published 14-day average daily range of 4.62 points. It was the widest since the 5.96 point session of 09/29. The low was the lowest print since the 85.92 low of 09/04. Provider commentary attributed the decline to an announcement by the Group of Seven and its partners of a release of up to 100 million barrels of crude and diesel from strategic reserves over the next four months. It attributed the recovery from the worst level to press reports that Saudi Arabia plans an offensive against Houthi militants in Yemen. Neither item carried a time stamp on the feeds captured for this session. No bar is tied to either.
The employment report at 8:30 AM ET showed payrolls up 29,000 against a 90,000 forecast, per the news-feed calendar. The dollar index lost 0.17 percent. The ten-year yield index closed five basis points higher at 5.28 percent. Gasoline fell 2.65 percent. Heating oil fell 3.04 percent. Brent's December contract was nearly unchanged at 102.25, so Brent's premium over November WTI widened to 11.14 from 9.44. Crude remains the most volatile of the four instruments covered here. Its published 14-day average true range of 4.27 points is 4.69 percent of the settle. Two days of headline exposure separate Friday's 2:30 PM ET settle from the 6:00 PM ET Sunday reopen.
November WTI settled at 91.11, down 1.90 percent, at 56.0 percent of a 93.51 to 88.06 range. Globex reopens at 6:00 PM ET Sunday. A weekend gap can open outside the published deviation bands. Overhead sit the 91.28 5-day average, the 91.79 to 91.94 group, one deviation resistance at 92.58 and Thursday's 92.87 settle. Support starts at the 90.89 Pivot Point, then the 90.79 stochastic threshold and one deviation support at 89.64. The primary setup is a short from 92.40 to 92.70, stop 93.90, targets 91.20, 89.85 and 88.50. The calendar lists the services survey at 10:00 AM ET Monday, per the news-feed calendar and unconfirmed. Sunday's reopen is the first-order event.
Friday's long, graded against the bar
Friday's outlook set a long from a pullback into 91.80 to 92.10, around the 91.78 Pivot Point and the 91.87 average crossing, with a stop at 90.60, targets at 93.30, 94.65 and 96.00, and an outright invalidation on a settle beneath three standard deviations support at 90.19. Friday opened at 93.46, marked a 93.51 high and an 88.06 low, and settled at 91.11; the dated 10/02 row of the provider's daily record carries the same four prices. The high came before the band. The 93.51 print sits in the first bar after the Thursday 6:00 PM ET reopen. The band first traded in the 2:00 AM ET bar, whose 92.09 low sat a cent inside its top.
We put the stop at 90.60. The 3:30 AM ET bar traded through it to 90.10, 50 cents beneath the stop, and the 9:00 AM ET bar later printed the 88.06 session low. No target traded after the band. From the 2:00 AM ET bar onward the highest print was that bar's own 92.66 high, 64 cents short of the 93.30 first target. The 93.51 session high, 21 cents above the first target, had come earlier, in the 6:00 PM ET bar. The 30-minute series shows that order across bars. It does not show fills, and this outlook asserts no result for the card.
A clause defined acceptance beneath one deviation support as two consecutive 30-minute closes beneath 91.32. The 2:30 AM ET bar closed at 91.66, above it. The 3:00 AM ET and 3:30 AM ET bars closed at 91.22 and 90.22, the first such pair. So by the card's own terms the edge was gone at the close of the 3:30 AM ET bar, the same bar that traded through 90.60. The series cannot order the two inside that bar. The outright invalidation did not trigger. The settle sat 92 cents above 90.19.
The macro override named three headline risks: a confirmed agreement to reopen the Strait of Hormuz, a coordinated release of fuel stocks, or a sharp dollar advance after the employment report. Commentary reported the second. Provider commentary described a Group of Seven release of up to 100 million barrels of crude and diesel from strategic reserves. That item carried no time stamp on the feeds captured for this session, so no bar is tied to it. No agreement on the Strait was captured in the headlines. The dollar index slipped 0.17 percent.
The range work missed low. The low-range case, 91.50 to 94.20, held the high and lost the rest: the 88.06 low ran 3.44 points beneath its bottom and the settle 39 cents beneath it. The most likely band, 90.60 to 95.10, held the high and the settle. Its bottom gave way by 2.54. The high-range case, 88.70 to 97.00, also held the high and the settle, and the low broke its bottom by 64 cents.
The path call missed too. That outlook weighted a pullback toward the 91.78 to 91.94 group that holds above a break beneath it, and Friday settled at 91.11, 67 cents beneath the 91.78 Pivot Point. The 30-minute series scores the session bands. Globex, 92.40 to 94.40, traded 91.64 to 93.51 through the 2:30 AM ET bar, 76 cents through the bottom. London, 92.00 to 94.80, traded 88.83 to 91.74 from the 3:00 AM ET bar through the 7:30 AM ET bar, wholly beneath it. The United States morning, 91.40 to 94.60, traded 88.06 to 91.02 through the 11:30 AM ET bar. The afternoon, 91.20 to 94.80, ran 90.42 to 92.02 through the 2:00 PM ET bar, 78 cents through the bottom.
A first-bar high, a 9:00 AM ET low
Friday opened at 93.46 at the Thursday 6:00 PM ET reopen, 59 cents above Thursday's settle, and the first bar printed the 93.51 session high. Asia drifted lower in small steps. From the 6:30 PM ET bar through the 9:00 PM ET bar the contract held between 92.78 and 93.24. It eased to 92.49 in the 11:00 PM ET bar and to 92.13 in the 1:00 AM ET bar. The 2:00 AM ET bar closed at 92.14.
Europe carried the decisive leg. The 2:30 AM ET bar closed at 91.66 and the 3:00 AM ET bar at 91.22. The 3:30 AM ET bar traded down to 90.10 and closed at 90.22, the 4:00 AM ET bar reached 89.29 and the 5:00 AM ET bar printed 88.83. From the 92.49 open of the 2:00 AM ET bar to that low the contract fell 3.66 points in seven bars.
Then it stalled. From the 5:30 AM ET bar through the 8:00 AM ET bar the contract held between 88.98 and 90.17. The 8:30 AM ET bar, which contained the employment report, traded between 89.18 and 89.84 and closed at 89.29. The 9:00 AM ET bar traded down to the 88.06 session low before closing at 89.16. The 9:30 AM ET bar rose to 90.37, and the 10:00 AM ET bar returned to 88.20 before closing at 88.74.
The recovery began in the 10:30 AM ET bar. The 11:00 AM ET bar reached 90.65, the 11:30 AM ET bar 91.02, the 12:00 PM ET bar 91.42 and the 1:00 PM ET bar 91.92. The 2:00 PM ET bar pushed to 92.02 before closing at 91.10. The settle was 91.11.
After the settle, trade held between 90.91 and 91.61 from the 2:30 PM ET bar through the 4:00 PM ET bar, and the 4:30 PM ET bar closed at 91.26. Those prints came after the settlement and are not used as the settle anywhere here. Globex reopens at 6:00 PM ET Sunday.
The extremes are the completed-session inputs behind the published pivot ladder, back-solved from its outer pairs. The third resistance point at 99.18 minus the third support point at 82.83, divided by three, returns 5.45, and 96.34 minus 85.44, divided by two, returns the same. Three times the 90.89 Pivot Point less the 91.11 settle gives a 181.56 high-plus-low sum. That is one cent from the 181.57 of the solved pair, because the published pivot is rounded. The pair of 93.51 and 88.06 reproduces all seven rungs. The ladder checks out. No Globex session has reopened, so the provider's overview page still shows the completed Friday session, with a 93.51 high, an 88.06 low and a 93.46 open. The chart's completed Friday bar and the settlement row carry the same four figures.
Both extremes stepped down. The 93.51 high sits 17 cents beneath Thursday's 93.68, and the 88.06 low 73 cents beneath Thursday's 88.79. Session highs since Monday read 96.54, 94.74, 91.96, 93.68 and 93.51. The lows read 91.25, 88.78, 88.58, 88.79 and 88.06. The week's settlements ran 92.60, 89.38, 90.42, 92.87 and 91.11, and across the week the contract lost 1.30 points or 1.41 percent from the 92.41 settle of 09/25. The prior week, September 21 through September 25, spanned 97.22 to 88.67. Friday's low traded beneath it. The settle sits inside.
The 52-week, 13-week and one-month high of 101.69 sits 10.58 points above the settle, and the one-month low of 85.92 sits 5.19 points beneath it. No prior-quarter high or low was captured, so the 13-week extremes stand in as the quarterly reference. Fourteen settles tell the swing since the 09/15 peak: 100.75, 97.51, 97.23, 96.08, 92.37, 90.52, 92.16, 94.61, 92.41, 92.60, 89.38, 90.42, 92.87 and 91.11. Friday ended a two-settle rise. Daily ranges for the last seven sessions ran 5.55, 3.24, 5.29, 5.96, 3.38, 4.89 and 5.45.
The retracement grid published for Monday places the 38.2 percent retracement from the four-week low at 91.94. That sits 83 cents overhead. The 50 percent retracement of the four-week range sits at 93.81 and the 38.2 percent retracement from the four-week high at 95.67. Beneath the settle, the 38.2 percent retracement from the 13-week high sits at 88.70 and the 50 percent retracement of the 13-week range at 84.69. No four-hour series was captured. The 30-minute series is the only intraday evidence.
The averages come from the provider's daily settlement series for the November contract, 260 completed sessions through Friday. The 5-day stands at 91.28, the 9-day at 91.79, the 20-day at 93.66, the 50-day at 85.85, the 100-day at 81.79 and the 200-day at 74.99. The settle sits 17 cents beneath the 5-day, 68 cents beneath the 9-day and 2.55 points beneath the 20-day. It sits 5.26 points above the 50-day.
All three short averages now sit overhead. The 5-day fell 26 cents from Thursday's 91.54 as the 09/25 settle of 92.41 left its window and 91.11 replaced it. The 9-day fell 14 cents from 91.93 as the 09/21 settle of 92.37 left, and the 20-day rose 15 cents from 93.50 as the 09/03 settle of 88.03 left. The projection grid puts Monday's 9-day crossing at 91.94. The 18-day crossing sits at 94.21 and the 40-day at 88.41.
Momentum sits near the middle. Oscillators are cited as published for the Friday session; because no Globex session reopens until Sunday, the page was read with the Friday settle as its most recent value. Relative strength reads 47.49 on the 9-day, 51.08 on the 14-day and 53.29 on the 20-day. The 14-day stochastic sits in the lower part of its range. The 9-day raw stochastic reads 34.98 percent and the 14-day 22.38 percent, with the 14-day %K at 23.05 percent and %D at 19.00 percent. The 14-3 day raw stochastic's 30 percent threshold sits at 92.15 and its 20 percent threshold at 90.79.
Direction still leans positive. On the 9-day the directional index reads 23.87 with positive direction at 17.91 and negative at 14.48; the 14-day reads 26.29, positive at 20.40 over negative at 14.72. Historic volatility runs 35.17 percent on the 9-day and 38.43 percent on the 14-day. The composite multi-indicator read for the Friday session held at 32 percent buy, unchanged from the prior session's snapshot. Signal strength is described as average and direction as weakening. It read 64 percent a week ago and 80 percent a month ago. The short-horizon group averages 20 percent buy, the medium-horizon group 25 percent and the long-horizon group 67 percent. The composite trend indicator reads hold.
Volatility sets the scale. The published 14-day average true range stands at 4.27 points and the 14-day average daily range at 4.62; the 9-day figures are 4.55 and 4.81, the 20-day figures 4.02 and 4.51. A one-range projection from 91.11 on the 14-day average true range frames Monday between 86.84 and 95.38. The published deviation bands are narrower because they are built from five settlements. One deviation spans 89.64 to 92.58, two spans 89.03 to 93.19 and three spans 88.56 to 93.66. The bands describe settlement dispersion, not intraday reach. A weekend gap can open outside them.
A reserve release, a Yemen report and a payroll miss
Consuming nations supplied the supply headline. No producer-alliance statement was captured on Friday's feeds. Provider commentary said the Group of Seven and its partners announced a release of up to 100 million barrels of crude and diesel from strategic reserves, coordinated by the energy agency and spread over the next four months. That figure comes from provider commentary and was not measured here. The same commentary attributed Friday's decline to the announcement. The item was untimed on the feeds captured for this session, so no bar is tied to it.
The rebound had its own attribution. Provider commentary said renewed Middle East tension supported prices off the low, citing press reports that Saudi Arabia plans an offensive against Houthi militants in Yemen. That item was untimed too. A news-feed item without a captured time said investigators found evidence that hackers accessed the propulsion system of a supertanker approaching the Texas coast. These are reports carried by those sources. None was confirmed here.
Thursday's escalation reports, including the tanker struck in the Strait of Hormuz after Thursday's settle, were followed on Friday by the 93.51 high in the first bar after the reopen and then by the European-morning decline. The series shows that sequence and nothing about its cause.
More arrived after the settle. An energy-news article on the feed at 3:01 PM ET said Iranian oil has started flowing to Tajikistan despite the risk of United States sanctions. The President said at 3:58 PM ET that Iran is not doing well. At 4:00 PM ET and 4:01 PM ET he said a diesel export ban was never really on the table and will not be imposed, and that Europe is making a major contribution. No Venezuela or Russian supply item with a production figure was captured.
Products fell harder than crude. The November gasoline contract settled at 3.3124 dollars a gallon, down 0.0902 or 2.65 percent, and November heating oil settled at 4.5011, down 0.1409 or 3.04 percent, per the provider's daily record. On the settlement arithmetic the gasoline margin, 42 gallons times the gasoline settle less the WTI settle, narrowed to 48.01 from 50.04. The heating oil margin narrowed to 97.94 from 102.09. No refinery utilisation figure and no seasonal demand series were captured.
Inventories were quiet. The captured calendars carry no petroleum inventory entry for Friday, and the strategic release is the reserve item of the day. The calendar lists the next weekly petroleum status report at 10:30 AM ET on October 7, 2026. It lists the short-term energy outlook with the winter fuels outlook on October 6, 2026, with its clock time marked as not confirmed.
Payrolls missed. The employment report at 8:30 AM ET, on the calendar, showed payrolls up 29,000 against a 90,000 forecast and 162,000 previously. The unemployment rate printed 4.2 percent against 4.1 percent, and average hourly earnings rose 0.1 percent on the month against 0.3 percent, all per the news-feed calendar. Provider commentary said August payrolls were revised to 133,000 from 162,000. Factory orders at 10:00 AM ET, on the calendar, rose 0.1 percent against a 0.2 percent forecast, per the news-feed calendar.
The dollar slipped. The dollar index closed at 101.93, down 0.17 points or 0.17 percent, after a session range of 101.67 to 102.13, per the provider's daily record. The ten-year yield index closed at 5.28 percent, up five basis points. Provider commentary said Treasury yields erased an early decline and that hawkish remarks from a regional Federal Reserve president supported the dollar.
Brent barely moved. Its December contract settled at 102.25, down six cents, so its premium over November WTI widened to 11.14 from 9.44. The S&P 500 cash index closed at 7,722.72, up 0.73 percent, and gold's December contract settled at 4,162.3, down 40.0 points or 0.95 percent.
Speculators cut length. The positioning report as of September 29, 2026, released Friday, shows managed money long 209,028 contracts, down 14,162, against short 129,436, up 8,074. That is a net long of 79,592 against 101,828 a week earlier, so speculative length fell by 22,236 contracts. Commercials held 873,637 long against 1,016,255 short, a net short of 142,618, and swap dealers 113,558 long against 575,715 short. The provider's overview shows open interest on the November contract at 276,494, which is Thursday's figure on the dated 10/01 row. Friday's open interest had not been reported, so no change in open interest is asserted for Friday.
One gap is deliberate. No dealer-positioning dataset was read for crude: no gamma map, no options concentration levels and no flow attribution, and none is borrowed from another instrument. The positioning inputs for crude are the weekly positioning report, the weekly inventory report, the Brent spread and the product margins.
The trade map for Monday
Overhead, the references start close. The settle at 91.11 sits 17 cents beneath the 5-day settlement average at 91.28. The first overhead references are the 91.79 9-day settlement average and the 9-day average crossing at 91.94, which coincides with the 38.2 percent retracement from the four-week low. The 92.02 afternoon high in the 2:00 PM ET bar and the stochastic 30 percent threshold at 92.15 follow. One deviation resistance at 92.58 and Thursday's 92.87 settle sit 29 cents apart, with two deviation resistance at 93.19 above them. Friday's 93.51 high, three deviation resistance at 93.66, the 20-day settlement average at 93.66 and Pivot R1 at 93.73 form a tight band 22 cents wide. The 50 percent retracement of the four-week range at 93.81 and the 18-day average crossing at 94.21 come next. Pivot R2 at 96.34 and Pivot R3 at 99.18 are the extended references beneath the 101.69 52-week high.
Support starts at the pivot. The settle sits 22 cents above the Pivot Point at 90.89, and the stochastic 20 percent threshold at 90.79 sits ten cents beneath the pivot, with the 14-day relative-strength 50 percent line at 90.58 under both. One deviation support at 89.64 and two deviation support at 89.03 come next. Three deviation support at 88.56 sits 50 cents above the 88.06 session low in the 9:00 AM ET bar. The 38.2 percent retracement from the 13-week high at 88.70 and the 40-day average crossing at 88.41 sit between them. Pivot S1, 88.28, sits above the low. The one-month low at 85.92, Pivot S2 at 85.44 and the 50 percent retracement of the 13-week range at 84.69 are the deeper references.
The primary setup is a short from a rally into 92.40 to 92.70, around one deviation resistance at 92.58 and beneath Thursday's 92.87 settle. Friday settled beneath the 5-day, 9-day and 20-day settlement averages after a lower high and a lower low. The composite read held at 32 percent buy with direction weakening, and the strategic release described in provider commentary adds supply over four months. A rally into one deviation resistance offers a short with a defined risk point above Pivot R1 at 93.73. The recovery from the 88.06 low on Middle East reports shows the geopolitical premium is still active. So the setup is an analyst judgment against live weekend headline risk. Risk is 1.35 from the 92.55 midpoint.
The entry band sits 1.29 points above the settle. Globex reopens at 6:00 PM ET Sunday. Two days of headline exposure on the Strait of Hormuz, the talks with Iran, the reported Saudi plans in Yemen and the timing of the strategic release come first. The President is listed to speak at 7:00 PM ET Friday, after the settle, per the news-feed calendar and unconfirmed. Japanese services purchasing managers' data follow at 8:30 PM ET Sunday, also per the news-feed calendar and unconfirmed. Gap references above the settle are one deviation resistance at 92.58, two deviation resistance at 93.19 and the 93.51 to 93.73 band. Beneath it sit one deviation support at 89.64, two deviation support at 89.03 and the 88.06 Friday low. Bias is neutral to lower beneath 91.94. The expected Globex band is roughly 89.60 to 92.60, absent a weekend shock.
Final services purchasing managers' surveys for France, Germany, the euro area and the United Kingdom are listed between 3:50 AM ET and 4:30 AM ET. Investor confidence is listed at 4:30 AM ET and euro area producer prices at 5:00 AM ET, forecast 7.6 percent on the year against 5.8 percent, all per the news-feed calendar and unconfirmed. Friday's decisive decline came in this window, between the 2:00 AM ET and 5:00 AM ET bars. The London hours carry the most recent evidence of selling. Bias is neutral to lower. The expected band runs roughly 89.20 to 92.40.
The services survey from the purchasing managers' institute is listed at 10:00 AM ET, forecast 55.2 against 55.4, with its employment component forecast at 49 against 47.8, per the news-feed calendar and unconfirmed. It reaches crude through the dollar and yields. Friday's morning made the session low in the 9:00 AM ET bar and then reversed. The 88.06 low and the 90.89 Pivot Point frame the morning. Expected band roughly 89.00 to 92.60.
Crude settles at 2:30 PM ET. Friday's afternoon carried the contract to the 92.02 high in the 2:00 PM ET bar before the settle, so the afternoon carries headline risk in both directions into the settle. Expected band roughly 89.40 to 92.80.
The calendar lists the trade balance at 8:30 AM ET on October 6, 2026, the next weekly petroleum status report at 10:30 AM ET on October 7, 2026, and the minutes of the September policy meeting at 2:00 PM ET on October 7, 2026. The captured calendars carry no petroleum inventory entry and no mega-capitalisation earnings entry for Monday. The provider lists the November contract's expiration as 10/20/26.
Three scenarios frame the full session. The low-range case runs 89.60 to 92.60, the mid-range case, which is the most likely, 88.80 to 93.40, and the high-range case 86.80 to 95.40. None carries a derived frequency. In our analyst judgment the most probable path opens the Sunday session within the two-deviation band and leaves the contract beneath the 91.79 to 91.94 group of the 9-day average and its crossing price, with the strategic release weighing on rallies. In the same judgment, a test of the 90.89 Pivot Point through the European morning is weighted above an extension toward 93.19. Three readings carry that weighting. Friday settled beneath the 5-day, 9-day and 20-day settlement averages. The composite read was unchanged at 32 percent buy with direction weakening, and speculative length fell by 22,236 contracts in the week to September 29. Through the United States morning, the 10:00 AM ET services survey, per the news-feed calendar and unconfirmed, decides the dollar's next step. One alternative invalidates the reading. A weekend escalation in the Strait or a Saudi strike in Yemen that gaps the contract through 93.73 would do it.
In our judgment the single first-order event for crude on Monday is the Sunday reopen itself. Two days of geopolitical and supply headlines sit between the settle and the next price. In the same judgment, the 10:00 AM ET services survey, per the news-feed calendar and unconfirmed, is the scheduled driver through the dollar.
Friday's stop level gave way in a 3:30 AM ET bar. Monday's entry band sits 1.29 points above the settle, with a weekend of headlines in between.
The complete data picture
Every number behind Monday’s plan, charted first, then the full level lists, then the complete numeric reference underneath.
Full numeric reference, every remaining figure from the session review
Carried below in the review’s own order: the level notes from sections 3.1 and 3.2, the executive summary from section 1, sections 2.1 to 2.6, sections 4.1 to 4.6, the coverage note from section 5, the session-by-session forecast from section 6, the Monday calendar from section 7 and the primary setup from section 8.
3.1 Resistance and 3.2 Support, level notes
The settle at 91.11 sits 22 cents above the Pivot Point at 90.89. The first overhead references are the 91.79 9-day settlement average and the 9-day average crossing at 91.94, which coincides with the 38.2 percent retracement from the four-week low at 91.94, followed by the 92.02 afternoon high in the 2:00 PM ET bar and the stochastic 30 percent threshold at 92.15.
One standard deviation resistance at 92.58 and Thursday's 92.87 settle sit 29 cents apart, with two standard deviations resistance at 93.19 above them. Friday's 93.51 high, three standard deviations resistance at 93.66, the 20-day settlement average at 93.66 and Pivot R1 at 93.73 form a tight band 22 cents wide. The 50 percent retracement of the four-week range at 93.81 and the 18-day average crossing at 94.21 follow, with Pivot R2 at 96.34 and Pivot R3 at 99.18 the extended references beneath the 101.69 52-week high.
Beneath the settle, the Pivot Point at 90.89 and the stochastic 20 percent threshold at 90.79 sit ten cents apart, with the 14-day relative-strength 50 percent line at 90.58 beneath them. One standard deviation support at 89.64 and two standard deviations support at 89.03 come next. Three standard deviations support at 88.56 sits 50 cents above the 88.06 session low in the 9:00 AM ET bar, and the 38.2 percent retracement from the 13-week high at 88.70 and the 40-day average crossing at 88.41 sit between them. Pivot S1 at 88.28 is the last reference above the low. The one-month low at 85.92, Pivot S2 at 85.44 and the 50 percent retracement of the 13-week range at 84.69 are the deeper references.
1. Executive Summary
The November crude contract settled at 91.11 on Friday, down 1.76 points or 1.90 percent from Thursday's 92.87 settle, after trading between 93.51 and 88.06, a 5.45 point daily range. The settle finished at 56.0 percent of the range, and the 5.45 point range was 1.18 times the published 14-day average daily range of 4.62 points. The range was the widest since the 5.96 point session of 09/29, and the 88.06 low was the lowest print since the 85.92 low of 09/04. Across the week the contract lost 1.30 points or 1.41 percent from the 92.41 settle of 09/25.
The provider's 30-minute series fixes the order. The 93.51 session high printed in the very first bar after the Thursday 6:00 PM ET reopen, the contract slid through the European morning from the 2:00 AM ET bar to an 88.83 low in the 5:00 AM ET bar, and the 9:00 AM ET bar printed the 88.06 session low. From there the contract recovered to a 92.02 high in the 2:00 PM ET bar before settling at 91.11 at 2:30 PM ET, 3.05 points above the low. Provider commentary attributed the decline to an announcement by the Group of Seven and its partners of a release of up to 100 million barrels of crude and diesel from strategic reserves over the next four months, coordinated by the energy agency, and attributed the recovery from the worst level to press reports that Saudi Arabia plans an offensive against Houthi militants in Yemen. Neither item carried a time stamp on the feeds captured for this session, so no bar is tied to either.
The employment report released at 8:30 AM ET, on the calendar, showed payrolls rising 29,000 against a 90,000 forecast, per the news-feed calendar. The dollar index slipped 0.17 percent to 101.93 while the ten-year yield index closed five basis points higher at 5.28 percent. Gasoline fell 2.65 percent and heating oil fell 3.04 percent, while Brent's December contract was nearly unchanged at 102.25, so Brent's premium over November WTI widened to 11.14 from 9.44.
Crude remains the most volatile of the four instruments covered here; the published 14-day average true range of 4.27 points is 4.69 percent of the settle. Two days of headline exposure separate Friday's 2:30 PM ET settle from the 6:00 PM ET Sunday reopen. The Primary Setup below is a short from the 92.40 to 92.70 band, around one standard deviation resistance at 92.58 and beneath Thursday's 92.87 settle, stopped at 93.90, with objectives at 91.20, 89.85 and an extended 88.50; the stop sits above Pivot R1 at 93.73.
2.1 Intraday and Session Review
The Friday session opened at 93.46 at the Thursday 6:00 PM ET reopen, 59 cents above Thursday's settle, marked a daily high of 93.51 and a daily low of 88.06, and settled at 91.11 at 2:30 PM ET. The provider's 30-minute series, 46 bars from the reopen through the 4:30 PM ET bar, places the high in the 6:00 PM ET Thursday bar and the low in the 9:00 AM ET Friday bar.
The Asian hours drifted lower in small steps. After the first bar, the contract held between 92.78 and 93.24 from the 6:30 PM ET bar through the 9:00 PM ET bar, eased to a 92.49 low in the 11:00 PM ET bar and a 92.13 low in the 1:00 AM ET bar, and the 2:00 AM ET bar closed at 92.14. The European morning carried the decisive leg: the 2:30 AM ET bar closed at 91.66, the 3:00 AM ET bar at 91.22, the 3:30 AM ET bar traded down to 90.10 and closed at 90.22, the 4:00 AM ET bar reached 89.29, and the 5:00 AM ET bar printed 88.83. From the 92.49 open of the 2:00 AM ET bar to the 88.83 low, the contract fell 3.66 points in seven bars.
The contract then held between 88.98 and 90.17 from the 5:30 AM ET bar through the 8:00 AM ET bar. The 8:30 AM ET bar, which contained the employment report, traded between 89.18 and 89.84 and closed at 89.29, and the 9:00 AM ET bar traded down to the 88.06 session low before closing at 89.16. The 9:30 AM ET bar rose to 90.37, and the 10:00 AM ET bar returned to 88.20 before closing at 88.74. The recovery began in the 10:30 AM ET bar: the 11:00 AM ET bar reached 90.65, the 11:30 AM ET bar 91.02, the 12:00 PM ET bar 91.42, the 1:00 PM ET bar 91.92 and the 2:00 PM ET bar 92.02 before closing at 91.10. The settlement at 2:30 PM ET was 91.11.
After the 2:30 PM ET settlement, electronic trade held between 90.91 and 91.61 from the 2:30 PM ET bar through the 4:00 PM ET bar, and the 4:30 PM ET bar closed at 91.26. These prints came after the settle and are not used as the settlement anywhere here. Globex does not reopen until 6:00 PM ET Sunday.
The session extremes used here are the completed-session inputs behind the published pivot ladder rather than an independently read bar, back-solved from the outer pivot pairs and verified against every rung. The third resistance point at 99.18 minus the third support point at 82.83, divided by three, returns 5.45, and the second resistance point at 96.34 minus the second support point at 85.44, divided by two, returns the same 5.45. Three times the Pivot Point of 90.89 less the 91.11 settle gives a high plus low sum of 181.56, one cent from the 181.57 of the solved pair because the published pivot is rounded, and the pair of 93.51 and 88.06 reproduces all seven published rungs. Independent corroboration is direct: because no Globex session has reopened, the provider's overview page still shows the completed Friday session, with a day high of 93.51, a day low of 88.06 and an open of 93.46, and the chart's completed Friday daily bar and the provider's settlement row carry the same four figures.
2.2 Daily Structure
Friday printed a lower high and a lower low against Thursday: the 93.51 high sits 17 cents beneath Thursday's 93.68, and the 88.06 low sits 73 cents beneath Thursday's 88.79. The sequence of session highs since Monday reads 96.54, 94.74, 91.96, 93.68 and 93.51, and the sequence of session lows reads 91.25, 88.78, 88.58, 88.79 and 88.06.
The prior week, September 21 through September 25, spanned 97.22 to 88.67. Friday's 88.06 low traded beneath that prior-week low, while the settle sits inside the range. The 52-week, 13-week and one-month high of 101.69 sits 10.58 points above the settle, and the one-month low of 85.92 sits 5.19 points beneath it. The week's settlements ran 92.60, 89.38, 90.42, 92.87 and 91.11.
No prior-quarter high or low was captured, so the 13-week extremes serve as the available quarterly reference.
2.3 4-Hour and Swing Structure
The daily settlement sequence after the 09/15 peak reads 100.75, 97.51, 97.23, 96.08, 92.37, 90.52, 92.16, 94.61, 92.41, 92.60, 89.38, 90.42, 92.87 and 91.11. Friday ended a run of two higher settles. Daily ranges for the last seven sessions ran 5.55, 3.24, 5.29, 5.96, 3.38, 4.89 and 5.45.
The retracement grid published for Monday places the 38.2 percent retracement from the four-week low at 91.94, 83 cents above the settle, the 50 percent retracement of the four-week range at 93.81 and the 38.2 percent retracement from the four-week high at 95.67. Beneath the settle, the 38.2 percent retracement from the 13-week high sits at 88.70 and the 50 percent retracement of the 13-week range at 84.69. No four-hour series was captured; the 30-minute series in section 2.1 is the only intraday evidence used.
2.4 Moving Averages
The averages cited in this subsection were computed from the provider's daily settlement series for the November contract, 260 completed sessions through Friday. The 5-day average stands at 91.28, the 9-day at 91.79, the 20-day at 93.66, the 50-day at 85.85, the 100-day at 81.79 and the 200-day at 74.99.
The 91.11 settle sits 17 cents beneath the 5-day average, 68 cents beneath the 9-day and 2.55 points beneath the 20-day, and 5.26 points above the 50-day. The 5-day average fell 26 cents from Thursday's 91.54, because the 09/25 settle of 92.41 left the window and was replaced by 91.11. The 9-day average fell 14 cents from 91.93 as the 09/21 settle of 92.37 left its window, and the 20-day rose 15 cents from 93.50 as the 09/03 settle of 88.03 left.
The projection grid gives the prices at which each average would be crossed on Monday: 91.94 for the 9-day, 94.21 for the 18-day and 88.41 for the 40-day.
2.5 Oscillator and Trend Readings
The oscillator figures below are as published on the provider's technical page dated for the Friday session. Because no Globex session reopens until Sunday, the page was read with the Friday settle as its most recent value. Relative strength reads 47.49 on the 9-day, 51.08 on the 14-day and 53.29 on the 20-day.
The 14-day stochastic sits in the lower part of its range. The 9-day raw stochastic reads 34.98 percent and the 14-day 22.38 percent, with the 14-day %K at 23.05 percent and %D at 19.00 percent. The published grid places the 14-3 day raw stochastic 30 percent threshold at 92.15 and its 20 percent threshold at 90.79.
The directional system still reads positive direction above negative direction. On the 9-day the directional index reads 23.87 with positive direction at 17.91 and negative direction at 14.48; on the 14-day it reads 26.29 with positive direction at 20.40 over negative at 14.72. Historic volatility reads 35.17 percent on the 9-day and 38.43 percent on the 14-day.
The composite multi-indicator read published for the Friday session is 32 percent buy, unchanged from the prior session's snapshot, with signal strength described as average and direction as weakening. The snapshot history reads 64 percent buy a week ago and 80 percent buy a month ago. The short-horizon group averages 20 percent buy, the medium-horizon group 25 percent buy and the long-horizon group 67 percent buy, and the composite trend indicator reads hold.
2.6 Volatility and Expected Range
The published 14-day average true range stands at 4.27 points and the 14-day average daily range at 4.62 points; the 9-day figures are 4.55 and 4.81, and the 20-day figures 4.02 and 4.51. Friday's 5.45 point range was 1.18 times the 14-day average daily range.
A one-range projection from the 91.11 settle using the 14-day average true range frames Monday between 86.84 and 95.38. The published standard-deviation bands are narrower because they are built from five settlements: one deviation spans 89.64 to 92.58, two spans 89.03 to 93.19 and three spans 88.56 to 93.66. These bands describe settlement dispersion, not intraday reach, and a weekend gap can open outside them.
4.1 OPEC and Supply Policy (Quotas, Compliance, Saudi and Russia Signals)
No producer-alliance statement was captured on Friday's feeds. The supply item of the day came from consuming nations: provider commentary said the Group of Seven and its partners announced a release of up to 100 million barrels of crude and diesel from strategic reserves, coordinated by the energy agency and spread over the next four months. That is a description from provider commentary, not a figure measured here. An energy-news article on the feed at 3:01 PM ET said Iranian oil has started flowing to Tajikistan despite the risk of United States sanctions.
4.2 Inventory Data (Crude Stocks, Gasoline, Distillates, Cushing, Strategic Reserve)
The captured calendars carry no petroleum inventory entry for Friday. The strategic release described in section 4.1 is the reserve item of the day. The next weekly petroleum status report is scheduled for 10:30 AM ET on October 7, 2026, on the calendar, and the short-term energy outlook with the winter fuels outlook is listed for October 6, 2026, on the calendar, which marks its clock time as not confirmed.
4.3 Geopolitical Backdrop (Middle East, Iran, Russia and Ukraine, Venezuela)
Provider commentary said renewed Middle East tension supported prices off the low, citing press reports that Saudi Arabia plans an offensive against Houthi militants in Yemen. The President said at 3:58 PM ET that Iran is not doing well, after the settle. A news-feed item without a captured time said investigators found evidence that hackers accessed the propulsion system of a supertanker approaching the Texas coast. These are reports carried by those sources rather than events confirmed here.
Thursday's escalation reports, including the tanker struck in the Strait of Hormuz after Thursday's settle, were followed on Friday by the 93.51 high in the first bar after the reopen and then by the European-morning decline described in section 2.1; the series shows that sequence, not its cause. No Venezuela or Russian supply item with a production figure was captured on Friday.
4.4 Demand and Refining (Refinery Utilisation, Crack Spreads, Seasonal Pattern)
The product complex fell harder than crude. The November gasoline contract settled at 3.3124 dollars a gallon, down 0.0902 or 2.65 percent, and the November heating oil contract settled at 4.5011, down 0.1409 or 3.04 percent, per the provider's daily record. On the settlement arithmetic the gasoline margin, 42 gallons times the gasoline settle less the WTI settle, narrowed to 48.01 from 50.04, and the heating oil margin narrowed to 97.94 from 102.09.
The President said at 4:00 PM ET and 4:01 PM ET that a diesel export ban was never really on the table and will not be imposed, and that Europe is making a major contribution. No refinery utilisation figure and no seasonal demand series were captured, so neither is asserted.
4.5 Dollar and Cross-Asset (Dollar Index, Commodities Complex, Equity Risk Appetite)
The employment report at 8:30 AM ET, on the calendar, showed payrolls up 29,000 against a 90,000 forecast and 162,000 previously, the unemployment rate at 4.2 percent against 4.1 percent, and average hourly earnings up 0.1 percent on the month against 0.3 percent, all per the news-feed calendar. Provider commentary said August payrolls were revised to 133,000 from 162,000. Factory orders at 10:00 AM ET, on the calendar, rose 0.1 percent against a 0.2 percent forecast, per the news-feed calendar.
The dollar index closed at 101.93, down 0.17 points or 0.17 percent, after a session range of 101.67 to 102.13, per the provider's daily record. The ten-year yield index closed at 5.28 percent, up five basis points; provider commentary said Treasury yields erased an early decline and that hawkish remarks from a regional Federal Reserve president supported the dollar. Brent's December contract settled at 102.25, down six cents, so its premium over November WTI widened to 11.14 from 9.44. The S&P 500 cash index closed at 7,722.72, up 0.73 percent, and gold's December contract settled at 4,162.3, down 40.0 points or 0.95 percent.
4.6 Institutional Positioning (Commitments Data, Money Manager and Commercial Hedger, Speculator Length)
The positioning report as of September 29, 2026, released Friday and shown on the provider's overview, shows managed money long 209,028 contracts, down 14,162, against short 129,436, up 8,074, a net long of 79,592 against 101,828 a week earlier. Commercials held 873,637 long against 1,016,255 short, a net short of 142,618, and swap dealers held 113,558 long against 575,715 short. Speculative length therefore fell by 22,236 contracts in the week to September 29.
The provider's overview shows open interest on the November contract at 276,494, which is Thursday's figure; Friday's open interest had not been reported at the time of capture, so no change in open interest is asserted for Friday.
The dated 10/01 row of the provider's daily record carries the same 276,494 open interest, and the 10/02 row carries no open interest value. Volume on the dated 10/02 row was 326,828 contracts, against 337,181 on the 10/01 row.
5. No liquid options proxy
Crude is covered here without a positioning dataset. There is no dealer-positioning surface read for this instrument, no gamma map, no options concentration levels and no flow attribution, and none is inferred from any other instrument. Every level in section 3 originates in published pivot arithmetic, published standard-deviation bands, published retracement and moving-average projections, settlement averages computed from the provider's daily record, the completed-session extremes described in section 2.1, or bars in the provider's 30-minute series.
This is a statement about coverage, not about the existence of listed crude options. No such dataset was read, so no claim resting on one appears anywhere in this outlook. The positioning inputs used for crude are the weekly positioning report, the weekly inventory report, the Brent spread and the product margins.
Night Session (6:00 PM ET Sunday to 3:00 AM ET Monday, Globex and Asia)
The contract reopens at 6:00 PM ET Sunday after two days of headline exposure on the Strait of Hormuz, the talks with Iran, the reported Saudi plans in Yemen and the timing of the strategic release. Japanese services purchasing managers' data are listed at 8:30 PM ET Sunday, per the news-feed calendar and unconfirmed. Gap references above the settle are one standard deviation resistance at 92.58, two standard deviations resistance at 93.19 and the 93.51 to 93.73 band; beneath it, one standard deviation support at 89.64, two standard deviations support at 89.03 and the 88.06 Friday low. Bias neutral to lower beneath 91.94, expected Globex band roughly 89.60 to 92.60 absent a weekend shock.
London Session (3:00 AM ET to 8:00 AM ET Monday)
Final services purchasing managers' surveys for France, Germany, the euro area and the United Kingdom are listed between 3:50 AM ET and 4:30 AM ET, investor confidence at 4:30 AM ET and euro area producer prices at 5:00 AM ET, forecast 7.6 percent on the year against 5.8 percent, all per the news-feed calendar and unconfirmed. Friday's decisive decline came in this window, between the 2:00 AM ET and 5:00 AM ET bars, so the London hours carry the most recent evidence of selling. Bias neutral to lower, expected band roughly 89.20 to 92.40.
Morning Session (9:00 AM ET to 12:00 PM ET Monday, United States Open and Pit Session)
The services survey from the purchasing managers' institute is listed at 10:00 AM ET, forecast 55.2 against 55.4, per the news-feed calendar and unconfirmed. It reaches crude through the dollar and yields. Friday's morning made the session low in the 9:00 AM ET bar and then reversed, so the 88.06 low and the 90.89 Pivot Point frame the morning. Expected band roughly 89.00 to 92.60.
Afternoon Session (12:00 PM ET to 2:30 PM ET Monday, NYMEX Pit Close)
Crude's settlement falls at 2:30 PM ET. Friday's afternoon carried the contract to the 92.02 high in the 2:00 PM ET bar before the settle, so the afternoon carries headline risk in both directions into the settle. Expected band roughly 89.40 to 92.80.
Night Session Forward (6:00 PM ET Monday)
The trade balance is scheduled for 8:30 AM ET on October 6, 2026, on the calendar. The next weekly petroleum status report follows at 10:30 AM ET on October 7, 2026, on the calendar, and the minutes of the September policy meeting at 2:00 PM ET on October 7, 2026, on the calendar.
Expected Range (Monday Full Session)
Low-range scenario: 89.60 to 92.60 Mid-range scenario (most likely): 88.80 to 93.40 High-range scenario: 86.80 to 95.40
Most Likely Path
In our analyst judgment the most probable path opens the Sunday session within the two-deviation band and leaves the contract beneath the 91.79 to 91.94 group of the 9-day average and its crossing price, with the strategic release weighing on rallies. A test of the 90.89 Pivot Point through the European morning is weighted above an extension toward 93.19, because Friday settled beneath the 5-day, 9-day and 20-day settlement averages, the composite read was unchanged at 32 percent buy with direction weakening and speculative length fell by 22,236 contracts in the week to September 29. Through the United States morning the 10:00 AM ET services survey, per the news-feed calendar and unconfirmed, decides the dollar's next step. The alternative that would invalidate this reading is a weekend escalation in the Strait or a Saudi strike in Yemen that gaps the contract through 93.73.
7. Monday Economic Calendar
The Monday session reopens at 6:00 PM ET Sunday. The President is listed to speak at 7:00 PM ET Friday, after the settle, per the news-feed calendar and unconfirmed. Japanese services purchasing managers' data are listed at 8:30 PM ET Sunday, per the news-feed calendar and unconfirmed.
The European morning lists final services purchasing managers' surveys between 3:50 AM ET and 4:30 AM ET and euro area producer prices at 5:00 AM ET, both per the news-feed calendar and unconfirmed. The United States morning carries the services survey from the purchasing managers' institute at 10:00 AM ET, forecast 55.2 against 55.4, with its employment component forecast at 49 against 47.8, per the news-feed calendar and unconfirmed. Crude settles at 2:30 PM ET. The captured calendars carry no petroleum inventory entry and no mega-capitalisation earnings entry for Monday.
The November contract's expiration is listed as 10/20/26 by the provider. In our judgment the single first-order event for crude on Monday is the Sunday reopen itself, because two days of geopolitical and supply headlines sit between the settle and the next price, with the 10:00 AM ET services survey, per the news-feed calendar and unconfirmed, the scheduled driver through the dollar. The next weekly petroleum status report follows at 10:30 AM ET on October 7, 2026, on the calendar.
8. Primary Trade Setup
Direction: Short
Rationale: Friday settled beneath the 5-day, 9-day and 20-day settlement averages after a lower high and a lower low, the composite read held at 32 percent buy with direction weakening, and the strategic release adds supply over four months; a rally into one standard deviation resistance beneath Thursday's settle offers a short with a defined risk point above Pivot R1 at 93.73. The recovery from the 88.06 low on Middle East reports shows the geopolitical premium is still active, so the setup is an analyst judgment against live weekend headline risk.
Entry Zone: 92.40 to 92.70
Stop Loss: 93.90 (above Pivot R1 at 93.73 and the 93.51 Friday high)
Target 1 (T1): 91.20 (nine cents above the 91.11 Friday settle)
Target 2 (T2): 89.85 (21 cents above one standard deviation support at 89.64)
Target 3 (T3, extended): 88.50 (six cents beneath three standard deviations support at 88.56)
Risk-to-Reward: Approximately 1:1 to T1, 1:2 to T2, 1:3 to T3
Invalidation: A settle above Pivot R1 at 93.73 negates the thesis. Short of that, the edge is removed by acceptance above 93.19 rather than by a touch, defined as two consecutive 30-minute closes above 93.19.
Macro override: A weekend escalation in the Strait of Hormuz, a Saudi strike in Yemen that threatens Red Sea traffic, or a collapse of the talks with Iran would restore the supply premium. In that scenario a Sunday gap above the 93.90 stop removes the short before entry, and the 94.21 to 96.34 band becomes the reference within one 14-day average true range of 4.27 points.
Sources and methodology
This outlook is built from our session review of the November NYMEX WTI crude contract, CLX26, the November ’26 month, tracked on the continuous CL1! chart and prepared after Friday’s close on October 2, 2026 for the Monday, October 5, 2026 session. The contract domain was checked before any level was used: the daily chart’s reading of 91.11 with its stated change of minus 1.76 returns 92.87, the provider’s published previous close, and the chart’s completed Friday bar equals the provider’s settlement row, so chart and levels sit on the same November contract. No Globex session had reopened when the data were read, so the day high, day low and open on the provider’s overview page belong to Friday’s completed session and agree with the settlement row.
Friday’s session extremes are the completed-session inputs behind the published pivot ladder, back-solved from the outer pivot pairs, checked against all seven published rungs and reproduced by the chart’s daily bar. The 5-day, 9-day, 20-day, 50-day, 100-day and 200-day averages were computed from the provider’s 260-session daily settlement series. Volume and open interest are quoted from the dated rows of that daily record for 09/30, 10/01 and 10/02; the 10/02 row carries volume 326,828 but no open interest value, so no Friday open interest is stated. The 10/01 row now reads volume 337,181 and open interest 276,494, where Friday’s outlook cited the 308,429 volume published on that row at the time. Oscillator readings are cited as published. Every intraday ordering claim rests on the provider’s 30-minute series for Friday, 46 bars from the Thursday 6:00 PM ET reopen through the 4:30 PM ET bar. No dealer-positioning dataset was read for crude, so no gamma, dealer-positioning or options-flow claim is made. Items marked unconfirmed come from the news-feed calendar captured for this session; catalysts whose time had passed at 6:16 PM ET, when collection began, are recorded as completed. Scenario ranges are analyst judgment and carry no calibration. Friday’s grade uses Friday’s open, high, low and settle as stated in tonight’s review and the dated 10/02 row of the daily record, which agree, the 30-minute series for the order of prints, and the setup card as published on Friday’s outlook.
Not captured, and stated nowhere as a figure: a four-hour series, a prior-quarter high or low, a producer-alliance statement, a petroleum inventory entry for Friday, a refinery utilisation figure, a seasonal demand series, a Venezuela or Russian production figure, Friday’s open interest, and a time stamp for the strategic release or the Yemen report.
Friday’s outlook for this contract is here, and Friday’s gold outlook is here. Outlooks for the equity index, technology index, gold and crude contracts are collected on the market outlook page, and our forward trading record is on the performance statement.