At 2:00 AM ET on Thursday the December Nasdaq-100 contract printed 31,151.50, its highest level since the 31,293.50 high of 06/22. The climb had run through the Asian hours almost without pause, from the 30,707.00 reopen to 30,953.75 in the 12:00 AM ET bar and 31,067.50 in the 1:00 AM ET bar. It did not last. The 3:00 AM ET bar fell 220.50 points, from 31,024.25 to 30,803.75. About nine hours after the high, the 11:00 AM ET bar printed the 30,529.25 low.
December Nasdaq-100 futures still settled higher. The contract finished at 30,760.50, up 61.75 points or 0.20 percent from Wednesday's 30,698.75, its third consecutive higher settle. The 622.25 point range was 1.30 times the published 14-day average daily range of 477.89 points and the widest since the 958.75 point range of 09/21. The settle sat at 37.2 percent of that range, 391.00 points beneath the high. The cash index closed at 30,501.56, up 0.31 percent, and the semiconductor index rose 1.59 percent. Friday brings the employment report at 8:30 AM ET, which the calendar lists, with the ten-year yield index at 5.24 percent after a 5.34 percent session peak.
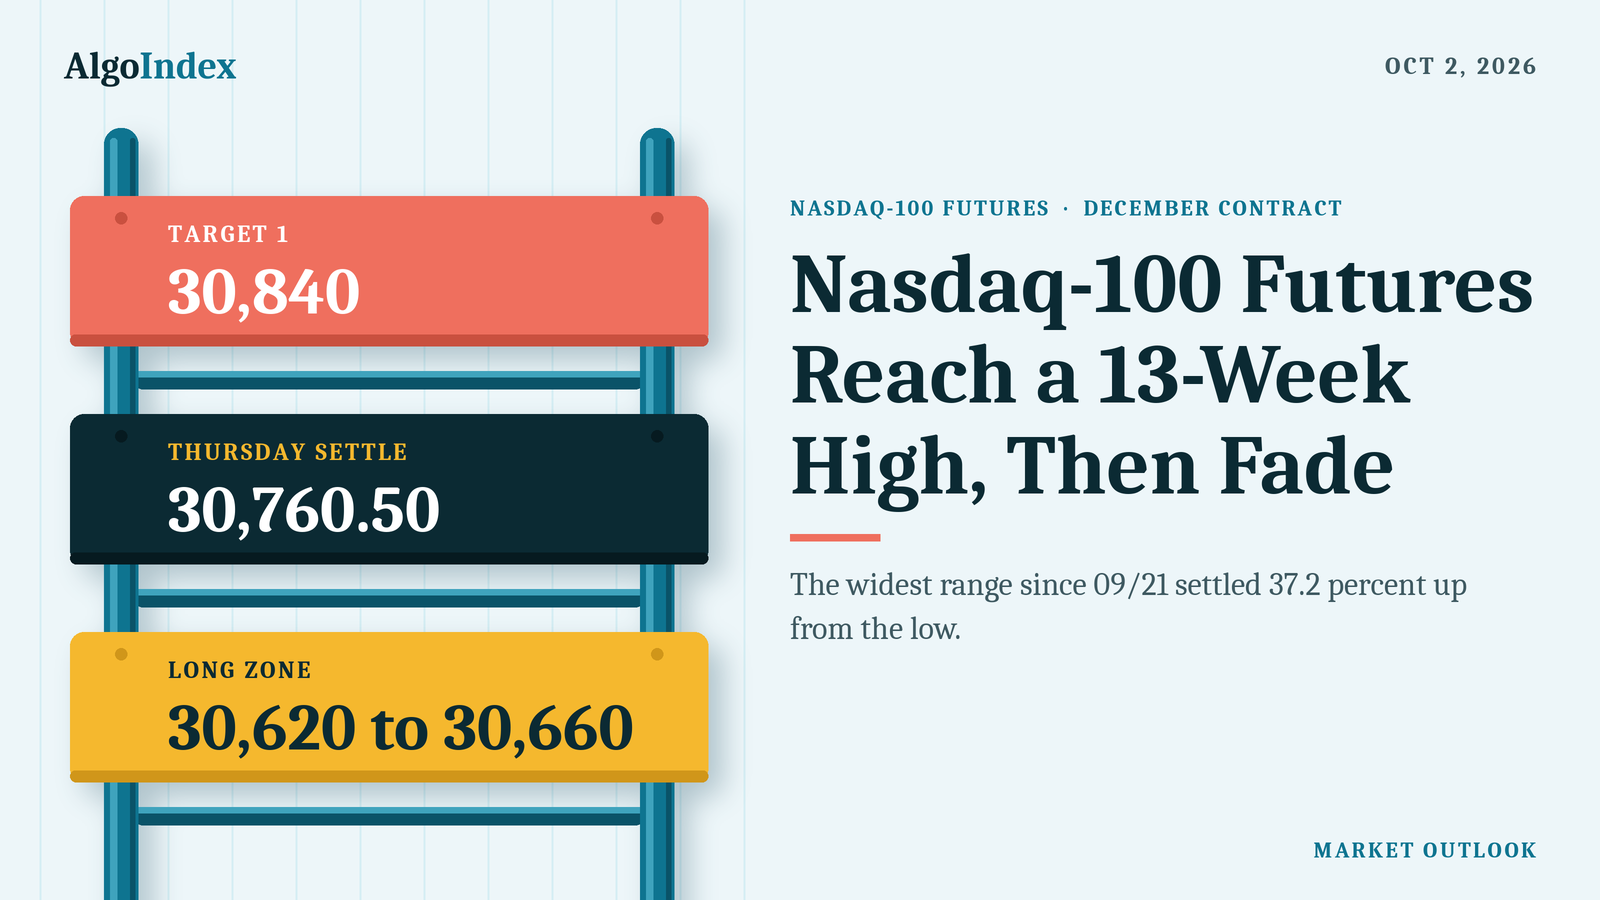
December Nasdaq-100 futures settled at 30,760.50, up 61.75 points, at 37.2 percent of a 622.25 point range and 53.25 points beneath the Pivot Point at 30,813.75. Preliminary volume was 787,504 contracts, per the provider's daily record. Thursday's open interest is not yet published. Wednesday's row reads 273,230. The composite multi-indicator read holds at 80 percent buy with direction strongest. The settle sits above the 5-day, 20-day, 50-day, 100-day and 200-day averages and 3.14 points beneath the 9-day. Overhead: the 30,761.00 9-day crossing, the 30,771.25 reopen, the 30,784.75 stall price, the Pivot Point, the 30,826.89 target price and the 30,883.50 to 30,887.71 pair. Beneath: the 30,758.94 strike conversion, the 30,684.34 to 30,633.29 group, the 30,580.59 to 30,529.25 group and Pivot S1 at 30,476.00. The primary setup is a long from 30,620 to 30,660, stop 30,440, targets 30,840, 31,040 and 31,240. The first-order event is the 8:30 AM ET employment report, which the calendar lists.
Thursday settled 120.50 points above the 30,600 to 30,640 long band
Our Thursday outlook set a long from 30,600 to 30,640 with a stop at 30,420 and targets at 30,820, 31,020 and 31,220. Thursday's completed bar, on the provider's daily record, opened at 30,707.00, marked a high of 31,151.50 and a low of 30,529.25, and settled at 30,760.50. Tonight's review states the same open, high, low and settle. Price traded through the whole band. The low printed 70.75 points beneath its lower edge and stopped 109.25 points above the stop, which was never reached. The high ran 331.50 points through the 30,820 first target level and 131.50 through the 31,020 second. The 31,220 extension stayed 68.50 points away.
Order matters on this card. The 30-minute series shows prints above both target levels before any bar reached the band. The 7:30 PM ET bar was the first to trade above 30,820, reaching 30,834.25, and the 1:00 AM ET bar the first above 31,020, at 31,067.50. The 31,151.50 high followed in the 2:00 AM ET bar. No bar traded into the band until the 10:00 AM ET bar, eight hours after the high, whose low of 30,560.75 sat 39.25 points beneath it. The 30,529.25 low came in the 11:00 AM ET bar. After the 10:00 AM ET bar the highest print was 30,883.50, in the 1:30 PM ET bar, 63.50 points above 30,820 and 136.50 short of 31,020. Bars show sequence only. No fill and no result is asserted here. Settlement landed at 30,760.50, 120.50 points above the band's upper edge.
We weighted a Thursday settle between 30,570.83 and 30,920.31 over a settle outside that band. Thursday settled inside it, 189.67 points above its bottom and 159.81 beneath its top. The overnight sketch held only in part. We had the Globex session holding above the 30,648.67 target price, and its lowest print, 30,684.50 in the 6:00 PM ET bar, stayed 35.83 points above it. The expected Globex band of 30,600 to 30,840 did not contain the session. Its 31,151.50 high ran 311.50 points over the top. The European pullback toward the 30,570.83 to 30,640 area never came. The lowest print in the bars from 3:00 AM to 8:00 AM ET, 30,757.75, stayed 117.75 points above that area.
Neither invalidation test triggered. The settle finished 255.17 points above the 30,505.33 Pivot S1 threshold, and the low stayed 17.00 points above 30,512.25, so no 30-minute close could fall beneath it. The macro override named three conditions. The desk note said the memory-chip maker rose 3 percent after its results, so the first was not met. The prices-paid component printed 77.9 against a 73 forecast, per the news-feed calendar. The ten-year yield index peaked at 5.34 percent and closed at 5.24 percent, down five basis points; the review does not time the peak. A press report at 1:54 PM ET said the President expects to resume bombing Iran, and the volatility index reached 17.59 before closing at 16.39. We grade the card as written.
A 31,151.50 high overnight, a 30,529.25 low by late morning
Thursday opened at 30,707.00 at the Wednesday 6:00 PM ET reopen, 8.25 points above Wednesday's settle. Asian hours climbed almost without pause. The 12:00 AM ET bar reached 30,953.75, the 1:00 AM ET bar 31,067.50 and the 2:00 AM ET bar the 31,151.50 high. The 2:30 AM ET bar closed at 31,025.00. Then the 3:00 AM ET bar fell from 31,024.25 to 30,803.75, with a low of 30,796.50. The crude and gold contracts also moved sharply in that bar. No headline captured on the feeds is time-matched to it, so no cause is asserted.
Europe went sideways. The European morning held between 30,757.75 and 30,949.75, a 192.00 point band. The United States morning extended the decline. The 9:30 AM ET bar, which contained the cash open, traded between 30,700.50 and 30,856.00 and closed at 30,746.00. The 10:00 AM ET bar contained the manufacturing survey release. It fell from 30,748.50 to 30,619.75, with a low of 30,560.75, and the 11:00 AM ET bar printed the 30,529.25 low. From the 11:00 AM ET bar through the 12:30 PM ET bar the contract held between 30,529.25 and 30,680.50.
Then the afternoon turned. The 1:00 PM ET bar rose from 30,595.25 to 30,799.00, and the 1:30 PM ET bar, which contained the Federal Reserve vice chair's remarks, reached 30,883.50, 354.25 points above the low. The final bars held between 30,705.00 and 30,856.50. The 3:30 PM ET bar closed at 30,772.75 ahead of the 4:00 PM ET settlement at 30,760.50. After the settle the 4:00 PM ET and 4:30 PM ET bars traded between 30,762.00 and 30,815.75 and closed at 30,771.25. The preserved provider series holds 46 bars from the reopen through that bar. The settle finished 53.50 points above the open, 391.00 beneath the high and 231.25 above the low.
Those extremes also come from the ladder. They are the completed-session inputs behind the published pivot ladder, back-solved from the outer pivot pairs and verified against every rung. The third resistance point at 31,720.50 minus the third support point at 29,853.75, divided by three, returns 622.25. The second pair, 31,436.00 and 30,191.50, divided by two, returns the same 622.25. Three times the 30,813.75 Pivot Point less the settle gives a high plus low sum of 61,680.75. The pair of 31,151.50 and 30,529.25 reproduces all seven rungs. The chart's completed Thursday bar reads 30,707.00, 31,151.50, 30,529.25 and 30,760.50.
Against Wednesday the bar stepped up at both ends. The high is 245.50 points above Wednesday's 30,906.00, and the low 17.00 above Wednesday's 30,512.25. Travel widened sharply. The 622.25 point range compares with 393.75 on Wednesday. Preliminary volume rose to 787,504 contracts from 610,055 on Wednesday, per the provider's daily record. Wednesday's row now carries open interest of 273,230, the figure the provider's overview also shows, and Thursday's is not yet published.
Last week's top gave way overnight. The prior week, September 21 through September 25, spanned 31,094.75 to 29,904.00. Thursday's high exceeded it by 56.75 points before the reversal, and the settle sits back inside it. Across five sessions the contract lost 6.25 points from the 30,766.75 settle of 09/24. The 31,151.50 high is now the published 13-week and one-month high, and the one-month low of 29,053.00, set on 09/16, sits 1,707.50 points beneath the settle. No prior-quarter high or low was captured, so the 13-week extremes serve as the available quarterly reference. Thursday was the first session of the fourth quarter. The 52-week high on the December contract stands at 31,336, 184.50 points above Thursday's high.
Three higher settles in a row. The sequence from 09/22 reads 31,028.50, 30,764.75, 30,766.75, 30,889.25, 30,566.25, 30,613.25, 30,698.75 and 30,760.50. The last three gains total 194.25 points and recover 60.1 percent of Monday's 323.00 point decline. Daily ranges for the last seven sessions ran 452.00, 457.50, 320.50, 564.00, 353.50, 393.75 and 622.25. The retracement grid published for Friday places the 38.2 percent retracement from the four-week high at 30,349.87 and the 50 percent retracement of the four-week range at 30,102.25, both beneath the settle. No four-hour series was captured. The 30-minute series is the only intraday evidence used.
One average sits overhead. Computed from the provider's daily settlement series for the December contract, 259 completed sessions through Thursday, the 5-day stands at 30,705.60, the 9-day at 30,763.64, the 20-day at 30,142.55, the 50-day at 29,768.24, the 100-day at 29,959.59 and the 200-day at 28,049.35. The settle is 3.14 points beneath the 9-day. It sits 54.90 above the 5-day, 617.95 above the 20-day, 992.26 above the 50-day, 800.91 above the 100-day and 2,711.15 above the 200-day.
Window arithmetic explains the jumps. The 9-day rose 93.69 points from Wednesday's 30,669.94 as the 09/18 settle of 29,917.25 left its window, and the 20-day rose 64.16 points from 30,078.39 as the 09/02 settle of 29,477.25 left. The 5-day fell 1.25 points from 30,706.85 as the 09/24 settle of 30,766.75 left. The 100-day sits 191.35 points above the 50-day because the older 50 of the last 100 settles averaged 30,150.94, higher than the latest 50. Crossing prices come next. The projection grid gives the prices at which each average would be crossed on Friday: 30,761.00 for the 9-day, 30,196.34 for the 18-day and 30,009.56 for the 40-day.
Momentum firmed again. The oscillator figures are as published on the provider's technical page dated for the Friday session, read after the 6:00 PM ET reopen, so the most recent value in each may include live Globex trade after the settle. Relative strength reads 63.15 on the 9-day, 60.59 on the 14-day and 58.17 on the 20-day. Stochastics sit high. The 14-day raw stochastic reads 81.37 percent, with %K at 79.46 percent above %D at 78.89 percent, and the 9-day raw stochastic reads 68.66 percent.
Direction reads positive above negative. On the 9-day the directional index reads 24.34, with positive direction at 28.95 and negative at 14.98; on the 14-day it reads 16.67, with positive direction at 26.97 against negative at 16.87. Historic volatility reads 16.60 percent on the 9-day and 15.90 percent on the 14-day. The composite multi-indicator read published for Friday is 80 percent buy, unchanged from the prior session's snapshot, with signal strength described as soft and direction as strongest. A week ago it read 88 percent buy. A month ago, 16 percent sell. The short-horizon group averages 80 percent buy, the medium-horizon group 100 percent and the long-horizon group 33 percent.
Volatility frames Friday. The published 14-day average true range stands at 466.67 points, 1.52 percent of the settle, and the 14-day average daily range at 477.89; the 9-day figures are 466.15 and 501.97, and the 20-day figures 478.69 and 450.13. One 14-day average true range either side of the settle spans 30,293.83 to 31,227.17. The published standard-deviation bands, built from five settlements, sit well inside it. One deviation spans 30,633.29 to 30,887.71, two span 30,580.59 to 30,940.41 and three span 30,540.16 to 30,980.84. Those bands describe settlement dispersion only.
A 5.34 percent ten-year peak, a 5.24 percent close and a chip rally
Start with yields. The ten-year yield index closed at 5.24 percent, down five basis points. Its session peak of 5.34 percent was described by provider commentary as a 24-year high, and the thirty-year yield index closed at 5.60 percent. The manufacturing survey from the purchasing managers' institute printed 54.5 against a 55 forecast, with its prices-paid component at 77.9 against 73, and initial jobless claims came in at 197,000 against 200,000, all per the news-feed calendar. No real-yield series was captured.
The calendar lists the Federal Reserve vice chair at 1:30 PM ET. Provider commentary said his remark that the central bank may take more time to judge further increases sparked short covering in Treasuries and cut the priced chance of a rate increase at this month's policy meeting to 26 percent from 70 percent on Monday. The contract's 1:30 PM ET bar, which contained the remarks, reached the 30,883.50 afternoon high. The dollar index closed 0.64 percent higher at 102.10.
Chips led. The desk note published at 4:59 PM ET said the memory-chip maker rose 3 percent after a large earnings beat, with its gross-margin guidance pointing to strong data-centre demand, igniting a rally across semiconductors, up 2 percent, and the memory group, up 3 percent, with equipment makers higher as well. The semiconductor index closed at 12,829.00, up 200.38 points or 1.59 percent, per the provider's daily record. The cash index gained 0.31 percent.
Other technology headlines ran through the afternoon. News-feed items at 12:12 PM ET and 12:32 PM ET carried artificial-intelligence product releases from a large software company and a large internet-search company. Two more reports followed. At 1:28 PM ET, reports said an artificial-intelligence developer is weighing an initial public offering as soon as November. A report carried at 2:17 PM ET said a large chip designer and a Japanese technology investor made a final 20 billion dollar investment in a second developer's latest round. None of these items is time-matched to a measured move. None is used as a level input.
Iran ran through the afternoon and the evening. A press report carried on the news feed at 1:54 PM ET said the President told aides he expects to resume bombing Iran, and crude rose 2.71 percent. After the cash close the maritime security agency reported at 4:02 PM ET a tanker struck by a projectile in the Strait of Hormuz. At 4:18 PM ET the President said the Iran conflict will be ending soon, one way or the other. The equity reaction to these items is not captured beyond the post-settlement bars.
The broad market trailed. The S&P 500 cash index closed at 7,666.45, up 0.19 percent, so the Nasdaq-100 outperformed. The volatility index closed at 16.39 after a session high of 17.59, and the volatility-of-volatility index at 92.01, up 2.83 percent. The technology fund closed at 742.03, up 0.31 percent, per the provider's daily record. The desk note said the implied volatility for Friday's S&P 500 expiration rose by one volatility point while later expirations declined, and put Friday's at-the-money implied volatility at 16 percent, implying a move of roughly 1.0 percent.
Positioning comes next. The levels come from two surfaces, the technology fund and the cash index, used here as the proxy for the positioning dataset available. They reach futures only through the measured basis of 258.94 points, Thursday's 30,760.50 settlement less the 30,501.56 cash close, both at 4:00 PM ET. No positioning report for the contract was captured, so none is asserted.
The desk note used is the 4:59 PM ET edition for Thursday, read at 6:17 PM ET. Its reference prices are the prior session's closes. The cash index reference of 30,408 equals Wednesday's 30,408.50 cash close, and the fund reference of 739 equals Wednesday's 739.77. Every level is therefore read against Thursday's closes, 30,501.56 for the cash index and 742.03 for the fund.
On the cash index the largest gamma concentration sits at 30,000, 501.56 points beneath the cash close. The modeled gamma-flip level at 29,878 and the modeled volatility threshold at 29,460 both sit beneath it, and the primary put-side support base is 28,000. The key strikes are 30,000, 29,475, 31,000 and 30,500, and the combination levels 31,230, 30,834, 30,621 and 30,013. Gamma tilt reads 1.612 with a gamma notional of 8.615 million dollars, close to flat, and the 25-delta risk reversal reads minus 0.047. One oddity repeats. The call-side ceiling field reads 29,475, beneath both the close and the modeled gamma-flip level, so it is excluded from the level structure.
The fund reads differently. Its largest gamma concentration sits at 740, the modeled gamma-flip level at 738 and the modeled volatility threshold at 742, with the primary call-side ceiling at 760 and the primary put-side support base at 730. The fund closed at 742.03, at the 742 threshold and above the 738 flip. Gamma tilt reads 1.045 and the gamma notional minus 117.172 million dollars, so the proxy's dealers carry a net short gamma position, and the 25-delta risk reversal reads minus 0.031. Put volume of 1.425 million contracts exceeded call volume of 1.01 million. The fund console dated 2026-10-01 attributes 11.69 percent of the fund's gamma and 2.05 percent of its delta to the nearest expiration. Its high and low volatility point fields are treated as low confidence and excluded.
At the measured closing basis, cash 31,000 corresponds to 31,258.94 on the December contract, cash 30,500 to 30,758.94, cash 30,000 to 30,258.94 and the modeled gamma-flip level at 29,878 to 30,136.94. These are conversions made by this review. The source publishes no Nasdaq futures pair, and the modeled thresholds are not listed strikes. In this review's interpretation the settle sits almost exactly at the 30,500 key strike conversion, 1.56 points above it, and the proxy's net short gamma at the 742 threshold leaves room for larger moves on Friday's report in either direction.
The trade map for Friday
The primary setup is a long from 30,620 to 30,660, a pullback into one standard deviation support at 30,633.29 and the 30,645.64 crossover stall. The case rests on the bar. Thursday printed a higher high and a higher low with a third consecutive higher settle, the composite read stands at 80 percent buy with direction strongest, and the settle sits 617.95 points above the 20-day settlement average. The stop at 30,440 sits beneath Pivot S1 at 30,476.00 and the 30,529.25 session low. The session also reversed 391.00 points from its high and closed at 37.2 percent of its range. So the setup is an analyst judgment against a fresh intraday rejection. The 14-day average true range of 466.67 points compares with a 200 point stop distance from the 30,640 midpoint. The 30,771.25 reopen sits 111.25 points above the top of the zone.
Overhead the references start almost at the settle. The 9-day average crossing at 30,761.00 sits 0.50 above it, with the 9-day average at 30,763.64 and the 30,771.25 reopen just beyond and the 9-day stall price at 30,784.75 after them. The Pivot Point at 30,813.75, the 30,815.75 post-settlement high and the published target price at 30,826.89 form the next group. The 30,883.50 afternoon high and one standard deviation resistance at 30,887.71 sit 4.21 points apart. Wednesday's 30,906.00 high, two standard deviations resistance at 30,940.41 and three at 30,980.84 sit above them. Pivot R1 at 31,098.25 and Thursday's 31,151.50 high come next. The cash 31,000 strike converts to 31,258.94, and the 31,336 52-week high, Pivot R2 at 31,436.00 and Pivot R3 at 31,720.50 are the extended references.
Support starts 1.56 points beneath the settle, at the 30,758.94 conversion of the cash 30,500 strike. The 5-day average at 30,705.60 follows. The 30,684.34 stall price published for the 14-day %K is the first published reference beneath the settle, followed by the MACD stall at 30,647.36 and the 3-10 day crossover stall at 30,645.64, with one standard deviation support at 30,633.29 12.35 points beneath them. Two standard deviations support at 30,580.59, three at 30,540.16 and the 30,529.25 session low sit within 51.34 points of one another. The stochastic 70 percent threshold at 30,521.95, Wednesday's 30,512.25 low and Pivot S1 at 30,476.00 follow. Lower down sit the 38.2 percent retracement at 30,349.87, the cash 30,000 concentration at 30,258.94, the 18-day crossing at 30,196.34 and Pivot S2 at 30,191.50. The 20-day average at 30,142.55, the gamma-flip conversion at 30,136.94, the 50 percent retracement at 30,102.25, the 40-day crossing at 30,009.56 and Pivot S3 at 29,853.75 are the deeper references.
Globex has reopened. The Friday session opened at 30,771.25 at 6:00 PM ET, 10.75 points above the settle and 42.50 points beneath the Pivot Point. The provider's overview showed a high of 30,810.25 and a low of 30,760.25 for the new session at the time of reading. None of those values is used as Thursday's range. Tokyo consumer prices and Japanese unemployment are listed at 7:30 PM ET, on the news-feed calendar and unconfirmed. Thursday's high printed in the Asian hours and was then sold, so the night session opens beneath the 30,813.75 Pivot Point with the 30,633.29 to 30,684.34 group beneath. Bias reads neutral, with an expected Globex band of roughly 30,650 to 30,900.
Europe follows. Euro area flash consumer prices are listed at 5:00 AM ET, forecast 3.7 percent against 3.2 percent, on the news-feed calendar and unconfirmed. Thursday's 3:00 AM ET bar fell 220.50 points, so the European open has carried abrupt moves this week. Bias reads neutral, with an expected band of roughly 30,600 to 30,950.
Then the report. The calendar lists the employment report at 8:30 AM ET. The news-feed calendar lists payrolls at a 90,000 forecast against 162,000 previously, the unemployment rate at 4.1 percent and average hourly earnings at a 0.3 percent monthly forecast, all unconfirmed. The cash open at 9:30 AM ET sets the session's first directional test after the report. The calendar lists factory orders at 10:00 AM ET, and a Federal Reserve bank president is listed to speak at the same time, on the news-feed calendar and unconfirmed. A hold above one standard deviation support at 30,633.29 keeps the 30,883.50 afternoon high and Pivot R1 at 31,098.25 in reach. A break beneath 30,529.25 opens Pivot S1 at 30,476.00. The morning band runs roughly 30,450 to 31,050.
The weekend waits behind the settle. Thursday's afternoon recovered 354.25 points from the low as yields reversed, so the afternoon carries the yield reaction to the morning report into the weekend. The afternoon band runs roughly 30,500 to 31,000 into the 4:00 PM ET settle. Two days of headline exposure on the Iran conflict then sit between the settle and the 6:00 PM ET Sunday reopen. The next scheduled United States release is the trade balance. The calendar lists it at 8:30 AM ET on October 6, 2026. For Friday the review singles out one first-order event: the 8:30 AM ET employment report, read through the ten-year yield, with Iran headlines the unscheduled risk and the weekend gap risk after the settle.
Three scenarios frame the day. Across the full session the low-range case runs 30,600 to 30,950, the mid-range and most likely case 30,480 to 31,100 and the high-range case 30,290 to 31,230. All three nest. In this review's analyst judgment the most probable path holds the Globex session between the 30,633.29 deviation support and the 30,813.75 Pivot Point ahead of the 8:30 AM ET employment report. In the same judgment a dip toward the 30,633.29 to 30,684.34 group that holds is weighted above a break of the 30,529.25 low, on three grounds. The composite read stands at 80 percent buy with direction strongest. Positive direction leads negative direction. The settle sits well above the 20-day settlement average. A report that drives yields back toward Thursday's 5.34 percent session peak would invalidate this reading, putting Pivot S1 at 30,476.00 and the 30,349.87 retracement in play.
The settle sits 1.56 points above the converted 30,500 strike, and the jobs report lands before the weekend does.
The complete data picture
Every number behind Friday’s plan, charted first, then the full level map, then the complete numeric reference underneath.
Cash-index levels at the measured 258.94 point basis: the 31,000 key strike translates to 31,258.94 in futures, the 30,500 key strike to 30,758.94, the 30,000 gamma concentration to 30,258.94 and the 29,878 modeled gamma flip to 30,136.94. No other cash level is translated.
Full numeric reference, every remaining figure from the session review
3.1 Resistance, level by level
The reopened session trades at 30,771.25, just above the settle and 10.25 points above the 9-day average crossing at 30,761.00. The first overhead references are the 9-day stall price at 30,784.75, the Pivot Point at 30,813.75, the 30,815.75 post-settlement high and the published target price at 30,826.89.
The 30,883.50 afternoon high in the 1:30 PM ET bar and one standard deviation resistance at 30,887.71 sit 4.21 points apart, with two standard deviations resistance at 30,940.41 and three standard deviations resistance at 30,980.84 above them. Pivot R1 at 31,098.25 and the 31,151.50 session high are the next references, and Pivot R2 at 31,436.00 sits above the 31,336 52-week high on the December contract.
3.2 Support, level by level
The 30,684.34 stall price published for the 14-day %K is the first published reference beneath the settle, followed by the MACD stall at 30,647.36 and the 3-10 day crossover stall at 30,645.64, with one standard deviation support at 30,633.29 12.35 points beneath them. Two standard deviations support at 30,580.59, three standard deviations support at 30,540.16 and the 30,529.25 session low sit within 51.34 points of one another.
The stochastic 70 percent threshold at 30,521.95 and Pivot S1 at 30,476.00 follow. The 38.2 percent retracement from the four-week high at 30,349.87, the 18-day average crossing at 30,196.34 and Pivot S2 at 30,191.50 are the deeper references.
1. Executive Summary
The December Nasdaq-100 contract settled at 30,760.50 on Thursday, up 61.75 points or 0.20 percent from Wednesday's 30,698.75 settle, after trading between 31,151.50 and 30,529.25, a 622.25 point daily range. It was a third consecutive higher settle. The settle finished at 37.2 percent of the range, and the 622.25 point range was 1.30 times the published 14-day average daily range of 477.89 points and the widest daily range since the 958.75 point range of 09/21. The 31,151.50 high is the contract's highest print since the 31,293.50 high of 06/22 and is now the published 13-week and one-month high.
The session had two halves. The contract climbed through the Asian hours to the 31,151.50 high in the 2:00 AM ET bar, fell 220.50 points in the 3:00 AM ET bar, and sold off again from the 9:30 AM ET cash open into the 10:00 AM ET manufacturing survey, printing the 30,529.25 low in the 11:00 AM ET bar. The afternoon recovered 354.25 points from that low to 30,883.50 in the 1:30 PM ET bar, which contained the Federal Reserve vice chair's remarks, before settling at 30,760.50 at 4:00 PM ET. The Nasdaq-100 cash index closed at 30,501.56, up 0.31 percent, and the semiconductor index rose 1.59 percent.
The cross-asset backdrop was a yield reversal. The ten-year yield index closed at 5.24 percent, down five basis points; its session peak of 5.34 percent was described by provider commentary as a 24-year high. The dollar index closed 0.64 percent higher at 102.10. Provider commentary said the vice chair's remark that the central bank may take more time to judge further increases cut the chance of a rate increase at this month's policy meeting to 26 percent from 70 percent on Monday. The desk note said the memory-chip maker rose 3 percent after its results, lifting semiconductors 2 percent and the memory group 3 percent.
The composite multi-indicator read published for Friday is 80 percent buy with direction strongest, and the settle sits 617.95 points above the 20-day settlement average, but the session reversed 391.00 points from its high. The Primary Setup below is a long from the 30,620 to 30,660 band around one standard deviation support and the crossover stall, stopped beneath Pivot S1 at 30,476.00, with objectives at 30,840, 31,040 and an extended 31,240.
2.1 Intraday and Session Review
The Thursday session opened at 30,707.00 at the Wednesday 6:00 PM ET reopen, marked a daily high of 31,151.50 and a daily low of 30,529.25, and settled at 30,760.50 at 4:00 PM ET. The preserved 30-minute provider series, 46 bars from the reopen through the 4:30 PM ET bar, places the high in the 2:00 AM ET bar and the low in the 11:00 AM ET bar, so the session made its high first and its low about nine hours later.
The Asian hours rose almost without pause. From the 6:00 PM ET reopen the contract climbed to 30,953.75 in the 12:00 AM ET bar, 31,067.50 in the 1:00 AM ET bar and the 31,151.50 high in the 2:00 AM ET bar. The 2:30 AM ET bar closed at 31,025.00, and the 3:00 AM ET bar fell from 31,024.25 to 30,803.75, with a low of 30,796.50. The crude and gold contracts also moved sharply in the 3:00 AM ET bar, but no headline captured on the feeds is time-matched to it, so no cause is asserted. The European morning held between 30,757.75 and 30,949.75.
The United States morning extended the decline. The 9:30 AM ET bar, which contained the cash open, traded between 30,700.50 and 30,856.00 and closed at 30,746.00. The 10:00 AM ET bar, which contained the manufacturing survey release, fell from 30,748.50 to 30,619.75 with a low of 30,560.75, and the 11:00 AM ET bar printed the 30,529.25 low. From the 11:00 AM ET bar through the 12:30 PM ET bar the contract held between 30,529.25 and 30,680.50. The 1:00 PM ET bar rose from 30,595.25 to 30,799.00, and the 1:30 PM ET bar reached 30,883.50. The final bars held between 30,705.00 and 30,856.50, and the 3:30 PM ET bar closed at 30,772.75 ahead of the 4:00 PM ET settlement at 30,760.50.
After the settlement, the 4:00 PM ET and 4:30 PM ET bars traded between 30,762.00 and 30,815.75 and closed at 30,771.25. The Friday session reopened at 30,771.25.
The session extremes used here are the completed-session inputs behind the published pivot ladder and were not read independently from a bar, back-solved from the outer pivot pairs and verified against every rung. The third resistance point at 31,720.50 minus the third support point at 29,853.75, divided by three, returns 622.25, and the second resistance point at 31,436.00 minus the second support point at 30,191.50, divided by two, returns the same 622.25. Three times the Pivot Point of 30,813.75 less the 30,760.50 settle gives a high plus low sum of 61,680.75, and the resulting pair of 31,151.50 and 30,529.25 reproduces all seven published rungs. The chart's completed Thursday daily bar reads 30,707.00, 31,151.50, 30,529.25 and 30,760.50, an independent confirmation of the same values, and the provider's settlement row carries the same four figures.
Because Globex reopened at 6:00 PM ET, the provider's overview page now shows the Friday session: its open of 30,771.25, high of 30,810.25 and low of 30,760.25 belong to the new session and are not used as Thursday's range anywhere in this review.
2.2 Daily Structure
Thursday printed a higher high and a higher low against Wednesday: the 31,151.50 high sits 245.50 points above Wednesday's 30,906.00, and the 30,529.25 low sits 17.00 points above Wednesday's 30,512.25. The high sits 184.50 points beneath the 52-week high on the December contract, 31,336.
The settle sits inside the prior week's range, September 21 through September 25, which spanned 31,094.75 to 29,904.00; Thursday's high exceeded that week's high by 56.75 points before the reversal. The one-month low of 29,053.00, set on 09/16/26, sits 1,707.50 points beneath the settle. Across five sessions the contract lost 6.25 points from the 30,766.75 settle of 09/24.
No prior-quarter high or low was captured, so the 13-week extremes serve as the available quarterly reference. Thursday is the first session of the fourth quarter.
2.3 4-Hour and Swing Structure
The daily settlement sequence across the last eight sessions reads 31,028.50, 30,764.75, 30,766.75, 30,889.25, 30,566.25, 30,613.25, 30,698.75 and 30,760.50. The three higher settles total 194.25 points and recover 60.1 percent of Monday's 323.00 point decline. Daily ranges for the last seven sessions ran 452.00, 457.50, 320.50, 564.00, 353.50, 393.75 and 622.25.
The retracement grid published for Friday places the 38.2 percent retracement from the four-week high at 30,349.87 and the 50 percent retracement of the four-week range at 30,102.25, both beneath the settle. No four-hour series was captured; the 30-minute series in section 2.1 is the only intraday evidence used.
2.4 Moving Averages
The averages cited in this subsection were computed from the provider's daily settlement series for the December contract, which holds 259 completed sessions through Thursday. The 5-day average stands at 30,705.60, the 9-day at 30,763.64, the 20-day at 30,142.55, the 50-day at 29,768.24, the 100-day at 29,959.59 and the 200-day at 28,049.35.
The 30,760.50 settle sits 54.90 points above the 5-day average, 3.14 points beneath the 9-day, 617.95 above the 20-day and 992.26 above the 50-day. The 9-day average rose 93.69 points from Wednesday's 30,669.94, because the 09/18 settle of 29,917.25 left the window and was replaced by 30,760.50. The 20-day rose 64.16 points from 30,078.39 as the 09/02 settle of 29,477.25 left, and the 5-day fell 1.25 points from 30,706.85 as the 09/24 settle of 30,766.75 left. The 100-day average stands 191.35 points above the 50-day because the 50 settlements before the most recent 50 averaged 30,150.94, higher than the most recent 50.
The projection grid gives the prices at which each average would be crossed on Friday: 30,761.00 for the 9-day, 30,196.34 for the 18-day and 30,009.56 for the 40-day.
2.5 Oscillator and Trend Readings
The oscillator figures below are as published on the provider's technical page dated for the Friday session, which was read after the 6:00 PM ET reopen, so the most recent value in each may include live Globex trade after the settle. Relative strength reads 63.15 on the 9-day, 60.59 on the 14-day and 58.17 on the 20-day.
The 14-day raw stochastic reads 81.37 percent, with the 14-day %K at 79.46 percent and %D at 78.89 percent; the 9-day raw stochastic reads 68.66 percent. The directional system reads positive direction above negative direction. On the 9-day the directional index reads 24.34 with positive direction at 28.95 and negative direction at 14.98; on the 14-day it reads 16.67 with positive direction at 26.97 over negative at 16.87. Historic volatility reads 16.60 percent on the 9-day and 15.90 percent on the 14-day.
The composite multi-indicator read published for Friday is 80 percent buy, unchanged from the prior session's snapshot, with signal strength described as soft and direction as strongest. The snapshot history reads 88 percent buy a week ago and 16 percent sell a month ago. The short-horizon group averages 80 percent buy, the medium-horizon group 100 percent buy and the long-horizon group 33 percent buy.
2.6 Volatility and Expected Range
The published 14-day average true range stands at 466.67 points and the 14-day average daily range at 477.89 points; the 9-day figures are 466.15 and 501.97, and the 20-day figures 478.69 and 450.13. Thursday's 622.25 point range was 1.30 times the 14-day average daily range.
Applying the 14-day average true range of 466.67 points to the 30,760.50 settle frames Friday between 30,293.83 and 31,227.17. The published standard-deviation bands are built from five settlements: one deviation spans 30,633.29 to 30,887.71, two spans 30,580.59 to 30,940.41 and three spans 30,540.16 to 30,980.84. These bands describe settlement dispersion, not intraday reach.
4.1 Mag7 Earnings and AI Capex Cycle
A report carried on the news feed at 2:17 PM ET said a large chip designer and a Japanese technology investor made a final 20 billion dollar investment in an artificial-intelligence developer's latest round, and reports carried at 1:28 PM ET said a second artificial-intelligence developer is weighing an initial public offering as soon as November. A large software company and a large internet-search company announced artificial-intelligence product releases during the session, per news-feed items at 12:12 PM ET and 12:32 PM ET. None of these items is time-matched to a measured move, and none is used as a level input.
4.2 Semiconductor Cycle and Tech Sector Rotation
The desk note published at 4:59 PM ET said the memory-chip maker rose 3 percent after a large earnings beat, with its gross-margin guidance pointing to strong data-centre demand, igniting a rally across semiconductors, up 2 percent, and the memory group, up 3 percent, with equipment makers higher as well. The semiconductor index closed at 12,829.00, up 200.38 points or 1.59 percent, per the provider's daily record, against the Nasdaq-100 cash index's 0.31 percent gain.
4.3 Fed Policy and Real Yields (Duration Sensitivity)
The ten-year yield index closed at 5.24 percent, down five basis points; its session peak of 5.34 percent was described by provider commentary as a 24-year high; the thirty-year yield index closed at 5.60 percent. The manufacturing survey from the purchasing managers' institute printed 54.5 against a 55 forecast, with its prices-paid component at 77.9 against 73, and initial jobless claims came in at 197,000 against 200,000, all per the news-feed calendar. The Federal Reserve vice chair spoke at 1:30 PM ET, as the calendar lists it; provider commentary said his remark that the central bank may take more time to judge further increases sparked short covering in Treasuries and reduced the chance of a rate increase at this month's policy meeting to 26 percent from 70 percent on Monday. No real-yield series was captured.
4.4 Geopolitical Backdrop
A press report carried on the news feed at 1:54 PM ET said the President told aides he expects to resume bombing Iran, and crude rose 2.71 percent. After the cash close the maritime security agency reported at 4:02 PM ET a tanker struck by a projectile in the Strait of Hormuz, and at 4:18 PM ET the President said the Iran conflict will be ending soon, one way or the other. The equity reaction to these items is not captured beyond the post-settlement bars in section 2.1.
4.5 Cross-Asset and Volatility
The S&P 500 cash index closed at 7,666.45, up 0.19 percent, so the Nasdaq-100 outperformed. The volatility index closed at 16.39; its session high was 17.59, and the volatility-of-volatility index at 92.01, up 2.83 percent. The dollar index closed at 102.10, up 0.64 percent. The QQQ fund closed at 742.03, up 0.31 percent, per the provider's daily record. The desk note said the implied volatility for Friday's S&P 500 expiration rose by one volatility point while later expirations declined, and put Friday's at-the-money implied volatility at 16 percent, implying a move of roughly 1.0 percent.
4.6 Institutional Positioning
The measured futures basis at the close was 258.94 points, the 30,760.50 settlement at 4:00 PM ET less the 30,501.56 cash close at 4:00 PM ET, both from the provider's daily records. No positioning report for the contract was captured. The provider's overview shows open interest on the December contract at 273,230, the figure on Wednesday's 09/30 daily row; the daily row for Thursday carries no open interest figure, so no change is asserted.
5. QQQ Options Flow Context (Proxy)
The desk note read for this section is the 4:59 PM ET edition for Thursday, read at 6:17 PM ET. Its reference prices are the prior session's closes, not Thursday's: NDX 30,408 equals Wednesday's 30,408.50 cash close and QQQ 739 equals Wednesday's 739.77, so every level below is read against Thursday's 30,501.56 cash close and 742.03 fund close and not against the reference column.
On the Nasdaq-100 index the largest gamma concentration sits at NDX 30,000, 501.56 points beneath the cash close, and the modeled gamma-flip level at NDX 29,878 and the modeled volatility threshold at NDX 29,460 both sit beneath it. The primary put side support base is NDX 28,000. The call-side ceiling field reads NDX 29,475, beneath both the close and the modeled gamma-flip level, the same inverted reading recorded in earlier editions, so it is excluded from the level structure. The note lists NDX 30,000, 29,475, 31,000 and 30,500 as key strikes and NDX 31,230, 30,834, 30,621 and 30,013 as combination levels. Gamma tilt on the index reads 1.612 with a gamma notional of 8.615 million dollars, close to flat, and the 25-delta risk reversal reads minus 0.047.
On the QQQ proxy the largest gamma concentration sits at 740, the modeled gamma-flip level at 738 and the modeled volatility threshold at 742, with the primary call side ceiling at 760 and the primary put side support base at 730. The fund closed at 742.03, at the 742 threshold and above the 738 flip. Gamma tilt reads 1.045 and the gamma notional minus 117.172 million dollars, so the proxy's dealers carry a net short gamma position, and the 25-delta risk reversal reads minus 0.031. Put volume of 1.425 million contracts exceeded call volume of 1.01 million. The QQQ console dated 2026-10-01 attributes 11.69 percent of the fund's gamma and 2.05 percent of its delta to the nearest expiration; its high and low volatility point fields are treated as low-confidence and excluded.
At the measured closing basis of 258.94 points, NDX 31,000 corresponds to 31,258.94 on the December contract, NDX 30,500 to 30,758.94, NDX 30,000 to 30,258.94 and the modeled gamma-flip level at NDX 29,878 to 30,136.94. These are conversions made by this review; the source publishes no Nasdaq futures pair, and the modeled thresholds are not listed strikes. The review uses the QQQ fund as the positioning proxy for the Nasdaq-100 contract, a choice made for the dataset available, and it remains secondary to technical structure and to the large-cap and semiconductor drivers in section 4. In this review's interpretation the settle sits almost exactly at the NDX 30,500 key strike conversion, and the proxy's net short gamma at the 742 threshold leaves room for larger moves on Friday's report in either direction.
6.1 Night Session (6:00 PM ET Thursday to 3:00 AM ET Friday, Globex and Asia)
The Friday session reopened at 30,771.25 at 6:00 PM ET, 10.75 points above the settle and 42.50 points beneath the Pivot Point at 30,813.75. Tokyo consumer prices are listed at 7:30 PM ET, per the news-feed calendar and unconfirmed. Thursday's high printed in the Asian hours and was then sold, so the night session opens beneath the 30,813.75 Pivot Point with the 30,633.29 to 30,684.34 group beneath. Bias neutral, expected Globex band roughly 30,650 to 30,900.
6.2 London Session (3:00 AM to 8:00 AM ET Friday)
Euro area flash consumer prices are listed at 5:00 AM ET, forecast 3.7 percent against 3.2 percent, per the news-feed calendar and unconfirmed. Thursday's 3:00 AM ET bar fell 220.50 points, so the European open has carried abrupt moves this week. Bias neutral, expected band roughly 30,600 to 30,950.
6.3 Morning Session (9:30 AM to 12:00 PM ET Friday, RTH Open)
The employment report is scheduled for 8:30 AM ET and factory orders for 10:00 AM ET, both of which the calendar lists. A Federal Reserve bank president is listed to speak at 10:00 AM ET, per the news-feed calendar and unconfirmed. The cash open at 9:30 AM ET sets the session's first directional test after the report. A hold above one standard deviation support at 30,633.29 keeps the 30,883.50 afternoon high and Pivot R1 at 31,098.25 in reach; a break beneath 30,529.25 opens Pivot S1 at 30,476.00. Expected band roughly 30,450 to 31,050.
6.4 Afternoon Session (12:00 PM to 4:00 PM ET Friday)
The contract settles at 4:00 PM ET. Thursday's afternoon recovered 354.25 points from the low as yields reversed, so the afternoon carries the yield reaction to the morning report into the weekend. Expected band roughly 30,500 to 31,000.
6.5 Night Session Forward (6:00 PM ET Friday)
The weekend separates Friday's 4:00 PM ET settlement from the 6:00 PM ET Sunday reopen, so two days of headline exposure on the Iran conflict sit between the settle and the next session. The next scheduled United States release the calendar lists is the trade balance at 8:30 AM ET on October 6, 2026.
6.6 Expected Range (Friday Full Session)
Low-range scenario: 30,600 to 30,950; Mid-range scenario (most likely): 30,480 to 31,100; High-range scenario: 30,290 to 31,230.
6.7 Most Likely Path
In this review's analyst judgment the most probable path holds the Globex session between the 30,633.29 deviation support and the 30,813.75 Pivot Point ahead of the 8:30 AM ET employment report, as the calendar lists it. A dip toward the 30,633.29 to 30,684.34 group that holds is weighted above a break of the 30,529.25 low, because the composite read stands at 80 percent buy with direction strongest, positive direction leads negative direction and the settle sits well above the 20-day settlement average. The alternative that would invalidate this reading is a report that drives yields back toward Thursday's session peak of 5.34 percent, which would put Pivot S1 at 30,476.00 and the 30,349.87 retracement in play.
7. Friday Economic Calendar
The Friday session reopened at 6:00 PM ET Thursday. Tokyo consumer prices and Japanese unemployment are listed at 7:30 PM ET, per the news-feed calendar and unconfirmed. Euro area flash consumer prices are listed at 5:00 AM ET, per the news-feed calendar and unconfirmed.
The United States morning carries the employment report at 8:30 AM ET, as the calendar lists it, with the news-feed calendar listing payrolls at a 90,000 forecast against 162,000 previously, the unemployment rate at 4.1 percent and average hourly earnings at a 0.3 percent monthly forecast, per the news-feed calendar and unconfirmed. The cash open follows at 9:30 AM ET. Factory orders are scheduled for 10:00 AM ET, as the calendar lists it, and a Federal Reserve bank president speaks at 10:00 AM ET, per the news-feed calendar and unconfirmed. The contract settles at 4:00 PM ET.
The single first-order event for the Nasdaq-100 on Friday is the 8:30 AM ET employment report, as the calendar lists it, through the ten-year yield, with Iran headlines the unscheduled risk and the weekend gap risk after the settle.
8. Primary Trade Setup
Direction: Long
Rationale: Thursday printed a higher high and a higher low with a third consecutive higher settle, the composite read stands at 80 percent buy with direction strongest and the settle sits 617.95 points above the 20-day settlement average; a pullback into one standard deviation support and the crossover stall offers a long with a defined risk point beneath Pivot S1 at 30,476.00. The session reversed 391.00 points from its high and closed at 37.2 percent of its range, so the setup is an analyst judgment against a fresh intraday rejection.
Entry Zone: 30,620 to 30,660
Stop Loss: 30,440 (below Pivot S1 at 30,476.00 and the 30,529.25 session low)
Target 1 (T1): 30,840 (26.25 above the Pivot Point at 30,813.75)
Target 2 (T2): 31,040 (58.25 beneath Pivot R1 at 31,098.25)
Target 3 (T3, extended): 31,240 (18.94 beneath the NDX 31,000 key strike conversion at 31,258.94)
Risk-to-Reward: Approximately 1:1 to T1, 1:2 to T2, 1:3 to T3
Invalidation: A settle beneath Pivot S1 at 30,476.00 negates the thesis. Short of that, the edge is removed by acceptance beneath 30,529.25 and not by a touch, defined as two consecutive 30-minute closes beneath 30,529.25.
Macro override: A strong employment report with firm wages that drives yields back toward Thursday's 5.34 percent session peak, or a sharp escalation in the Iran conflict over the session, would pressure duration-sensitive technology shares. In that scenario the long is wrong immediately, and the 30,349.87 to 30,191.50 band becomes the reference within one 14-day average true range of 466.67 points.
Alternate setup: the session review states none.
Sources and methodology
This outlook is built from our session review of the December E-mini Nasdaq-100 contract, NQZ26, the December ’26 contract, prepared after Thursday's close on October 1, 2026 for the Friday, October 2 session. The contract was verified before any level was used: the daily chart title read 30,781.50 with a stated change of plus 0.07 percent, which returns 30,760.0, within title rounding of the provider's published previous close of 30,760.50, and the chart's completed Thursday bar equals the provider's settlement row for the explicit December symbol. Because Globex reopened at 6:00 PM ET, the day high, day low and open on the provider's overview belong to the Friday session and are never presented as Thursday's range. Thursday's extremes are the completed-session inputs behind the published pivot ladder, back-solved from the outer pivot pairs, verified against all seven rungs and reproduced by the chart's daily bar. Statements about the order of prices within Thursday's session rest on the preserved 30-minute provider series, which also orders the prints used to grade the prior card.
The settlement averages were computed from the provider's 259-row daily settlement series and are shown to two decimals; that series also supplies the seven closes charted above. Volume and open interest come from the provider's daily record: the 2026-10-01 row reads preliminary volume of 787,504 contracts with open interest not yet published, and the 2026-09-30 row now reads volume of 610,055 and open interest of 273,230, where Thursday's outlook carried a preliminary 598,965 and no open interest. The open interest of 273,230 that the review cites from the provider's overview is that 09/30 figure. The oscillator readings are cited as published, with the reopen caveat. The desk note is the 4:59 PM ET edition for Thursday, read at 6:17 PM ET, and the fund console is dated 2026-10-01; the desk note's reference prices are Wednesday's closes and are used as such. Cash-denominated levels are translated with the measured 258.94 point basis, the 4:00 PM ET settlement against the 4:00 PM ET cash close from the same provider. The inverted cash-index call-side field and the console's volatility-point fields are excluded from the level structure. The gold and volatility-index changes are computed from the provider's Thursday and Wednesday closes. The 52-week high cited is 31,336 on the December contract. Scenario ranges, session bands and the path weighting are analyst judgment and carry no calibration. Items marked unconfirmed come from the news-feed calendar or press reports and were not matched on the calendar used for confirmed times.
Thursday’s outlook for this contract is here and the broad-index outlook for the same date is here. Outlooks for ES, NQ, GC and CL are collected on the market outlook page, and our forward trading record is on the performance statement.