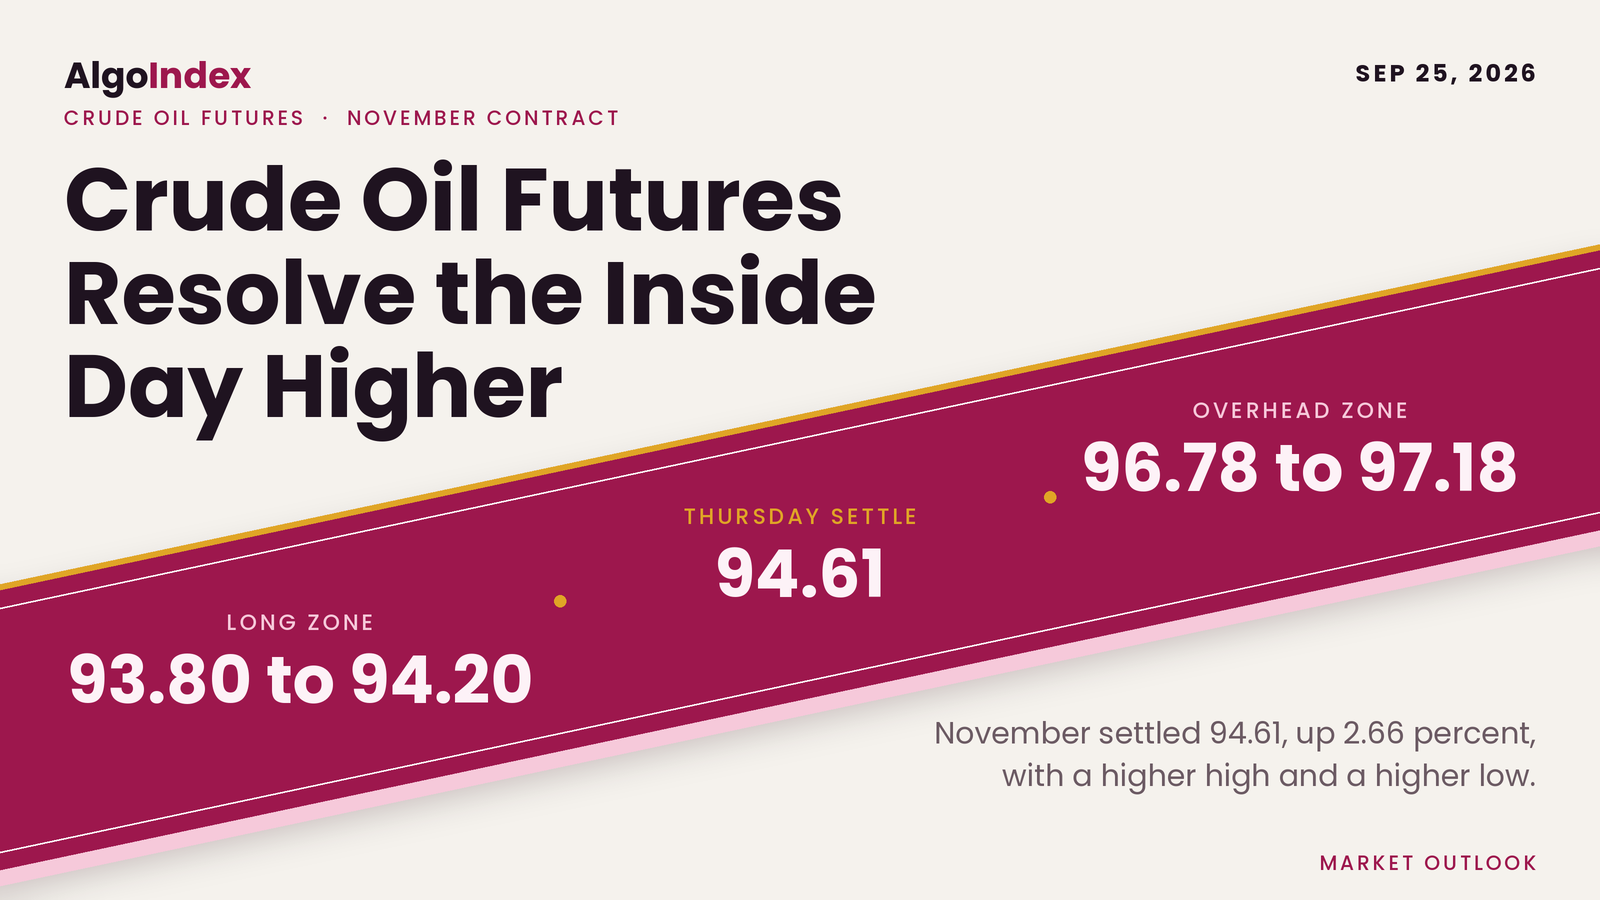
At 2:30 PM ET on Thursday, November crude settled at 94.61, up 2.45 points or 2.66 percent from Wednesday's 92.16. Two in a row. It was the second consecutive higher settle, after the run of five lower closes that followed the 09/15 settle of 100.75. The session traded a 5.55 point band between 96.78 and 91.23 and settled at 60.9 percent of it. Volume printed 390,676 contracts on the provider's dated daily record for Thursday, a preliminary figure, against 370,714 on Wednesday.
The supply-risk narrative carried the session. Press commentary published after the settle attributed the early strength to a senior Iranian military official warning of a wider conflict and to Saudi reports of missile fire from Yemen toward the Red Sea port of Yanbu and the city of Taif. The same commentary tied the retreat from the best levels to a report that United States and Iranian negotiators were exploring a phased arrangement to reopen the Strait of Hormuz; the news feed carried it at 12:15 PM ET. Brent's November contract settled at 106.60, up 3.52 points or 3.41 percent, per an item stamped 02:45 PM ET. The Brent to WTI spread widened to 11.99 from 10.92. Headlines and price coincided. No time-stamped intraday price series was captured, so this outlook asserts no ordering between them.
Friday asks whether a two-session recovery that has reclaimed the 5-day settlement average can carry into the 97 area without a fresh supply shock. The composite multi-indicator read rose to 64 percent buy from 40 percent on Wednesday. On the 9-day, positive direction now reads 24.43 over negative direction at 17.22. The settle sits 1.46 points above the 5-day average and 2.80 above the 20-day. Two things push back. The product contracts settled lower while crude rose, and the phased-deal report is a live, unresolved path to de-escalation. Crude also remains the most volatile of the four instruments covered here: its 14-day average true range of 4.00 points is 4.23 percent of price.
November WTI settled at 94.61. The session ran 96.78 to 91.23 and closed at 60.9 percent of the range, with a higher high and a higher low against Wednesday. The first overhead references are the 94.81 target price and the 95.15 9-day crossing, then the 96.78 to 97.18 zone, five references inside 40 cents. Support starts at the 94.21 Pivot Point and the 93.81 to 93.84 pair. Beneath them sit 92.85 to 93.06, the 91.51 to 91.98 group and Thursday's 91.23 low. Every directional horizon now favours positive direction. The primary setup is a long from 93.80 to 94.20, stop 92.30, targets 95.70, 97.40 and 99.10. Friday carries the durable goods report at 8:30 AM ET, no crude inventory release, and the last settle before the weekend.
Thursday's long, graded against the bar
Thursday's outlook set a long from 91.30 to 91.70 around the 91.31 Pivot Point, with a stop at 89.50, targets at 93.50, 95.50 and 97.50, and an outright invalidation on a settle beneath 88.67. Thursday opened at 92.72, marked 96.78 and 91.23, and settled at 94.61. The band traded. Thursday's range covered all of 91.30 to 91.70, reaching seven cents beneath its bottom and 5.08 above its top. The stop was never reached. The low held 1.73 above 89.50.
We set the first target at 93.50 and the second at 95.50. The high went through both, by 3.28 and 1.28 points. It stopped 72 cents short of the 97.50 third target. The settle finished 1.11 above the first target and 89 cents beneath the second. The session opened 1.02 above the top of the band, so the daily bar cannot show whether the dip into the band came before or after the high. This outlook asserts no fill and no order between the band trade, the targets and the low.
Our closing line named 91.13 as the level that decided Thursday. The low printed 91.23, ten cents above it and 74 cents above the 90.49 published target price. The card's acceptance clause needed two consecutive 30-minute closes beneath 91.13 with 90.49 also lost, and Thursday's prices never went there. The settle sat 5.94 above the 88.67 invalidation.
The range work missed high. Every scenario band was drawn too low for the session's top. The low-range case, 91.00 to 93.20, held the low by 23 cents. Its top gave way by 3.58. The most likely band, 90.40 to 93.90, held the low with 83 cents to spare; the high cleared it by 2.88 and the settle by 71 cents. The high-range case, 89.20 to 95.10, kept the settle 49 cents inside its top, yet the high overshot it by 1.68.
The path call missed too. That outlook judged a settle between the pivot and the 93.81 to 93.91 zone more likely than a settle through it. The settle went through, 70 cents above 93.91. Its session-by-session bands cannot be scored from a daily bar. The macro override named a confirmed de-escalation in the Strait. Thursday produced only a press report of phased talks. That goes on the record as well.
A higher high, a higher low and the 5-day restored
Upside only. Tuesday and Wednesday together spanned 93.84 to 88.67. Thursday's high at 96.78 cleared the top of that envelope by 2.94 points, while its low at 91.23 stayed 2.56 above the bottom. Against Wednesday alone the bar made a higher high, 3.72 points above 93.06, and a higher low, 2.52 above 88.71, so the inside-day pause resolved upward on the first test. The 88.67 to 88.71 shelf defended on Tuesday and Wednesday now sits 2.52 points beneath Thursday's low. The active line now sits higher.
No intraday series was captured, so the order of the extremes is unknown and no path is drawn. What the bar fixes is geometry. The open at 92.72 sat 56 cents above Wednesday's settle. The settle finished 1.89 points above that open, 3.38 above the low and 2.17 beneath the high. Press commentary said the market retreated from its best levels. A settle 2.17 beneath the high is consistent with that account, which remains press commentary without a captured series behind it.
The extremes themselves are back-solved from the published pivot ladder. The third resistance point at 102.73 minus the third support point at 86.08, divided by three, returns 5.55, and the second pair, 99.76 and 88.66, divided by two, returns the same. Three times the unrounded 94.2067 pivot, published as 94.21, less the settle gives a 188.01 high-plus-low sum, and 96.78 with 91.23 reproduces all seven rungs to the cent. The provider's daily record returns the same 92.72, 96.78, 91.23 and 94.61. A news-feed item stamped 02:31 PM ET carried the settle with its 2.45 point gain.
Zoom out and the recovery is partial. The prior week, September 14 through September 18, spanned 101.69 at the high and 94.64 at the low. Thursday's high re-entered that range. The settle stopped three cents beneath the prior week's low, so crude has probed back into the structure it vacated on Monday without settling inside it. The 52-week, 13-week and one-month high of 101.69, set on 09/15/26, sits 7.08 points above the settle. No prior-quarter high or low was captured, so the 13-week extremes stand in: 101.69 above and 67.09 below, with the settle 27.52 points above the low.
Eight settles tell the swing: 100.75, 97.51, 97.23, 96.08, 92.37, 90.52, 92.16 and then 94.61. The last two are the first back-to-back gains since the peak. Together they recover 4.09 points of the 10.23 point decline, 40.0 percent of it. Daily ranges ran 3.18 on Friday, 6.03 on Monday, 5.17 on Tuesday, 4.35 on Wednesday and 5.55 on Thursday. Two sessions of contraction ended in an expansion. Thursday's band was 1.25 times the published 14-day average daily range of 4.43 points, the widest session since Monday's 6.03 and the first expansion day since then.
The retracement grid published for Friday puts the 38.2 percent retracement from the four-week high at 92.85 and the 50 percent retracement of the four-week range at 90.12. Both now sit beneath the market. The 38.2 percent retracement from the 13-week high is at 88.47. On the upside the grid carries no retracement line between the settle and the 101.69 high, so pivot, deviation and projection levels do the work overhead.
The averages were computed from the provider's daily settlement series for the November contract: 5-day 93.15, 9-day 95.37, 20-day 91.81 and 50-day 84.44. The captured history covers 60 completed sessions, so no 100-day or 200-day average is cited. Price sits 1.46 points above the 5-day and 2.80 above the 20-day, and 76 cents beneath the 9-day. On Wednesday the contract had settled 1.51 points beneath its 5-day average. One session restored it. The 50-day sits 10.17 points beneath the settle, so the medium-horizon structure is intact and positive.
Crossing prices tighten the picture. The projection grid puts Friday's crossings at 95.15 for the 9-day average and 93.44 for the 18-day, with the 40-day at 85.91. The 9-day crossing is the nearest average-based line overhead, 54 cents above the settle.
Oscillators come as published for the Friday session. Relative strength reads 56.80 on the 9-day, 58.95 on the 14-day, 59.62 on the 20-day, 57.93 on the 50-day and 56.48 on the 100-day. The published 14-day grid places its 50 percent line at 90.09 and its 70 percent line at 103.90, so the 14-day reading sits mid-band. Stochastics climbed out of the lower half. The 9-day raw reading is 45.62 percent and the 14-day 55.10 percent, with %K at 41.28 and %D at 42.86; the 20-day reads 68.32 percent and the 50-day 76.11 percent. The published grid places the 14-3 day raw stochastic's 50 percent threshold at 93.81 and its 70 percent threshold at 96.96. The settle sits between them.
Direction has turned on every horizon read. On the 9-day the directional index reads 34.47 with positive direction at 24.43 and negative at 17.22; on Wednesday that horizon still had negative direction on top. The 14-day index reads 30.44 with positive at 25.79 over negative at 16.47, and the 20-day 25.33, positive at 26.40 over negative at 16.36. Historic volatility runs 39.77 percent on the 9-day, 43.38 percent on the 14-day and 39.40 percent on the 20-day.
The composite multi-indicator read published for Friday is 64 percent buy, with signal strength described as average and the short-term direction as strongest. The composite indicator itself reads buy. Underneath it the short-horizon group averages 60 percent buy, the medium-horizon group 25 percent buy, where the 50-day parabolic reading is the lone sell, and the long-horizon group 100 percent buy.
Volatility sets the scale. The published 14-day average true range stands at 4.00 points and the 14-day average daily range at 4.43; the 9-day figures are 4.32 and 4.47, the 20-day figures 3.77 and 3.94. A one-range projection from 94.61 on the 14-day average true range frames Friday between 90.61 and 98.61. The published deviation bands are tighter, and each is centred on the settle. One deviation spans 92.42 to 96.80, two spans 91.51 to 97.71 and three spans 90.81 to 98.41. The one-deviation top is 96.80. Two cents above Thursday's high. Bands and price structure point at the same place on the upside.
Escalation, a phased-deal report and a soft product side
Thursday carried escalation and de-escalation reporting in the same session. None of it is settled fact. On the escalation side, press commentary cited a warning by a senior member of Iran's Revolutionary Guard Corps and the Saudi missile reports. The news feed carried claims by the Yemeni group of attacks on facilities at Yanbu and on a target in Riyadh. Those items were stamped 03:02 PM and 03:03 PM ET, after the 02:30 PM ET settlement. The United States Senate rejected a resolution curbing the administration's Iran war powers, per an item stamped 02:38 PM ET.
Then the other side. The 12:15 PM ET report described the United States and Iran discussing a phased deal to reopen the Strait and end the United States blockade, and press commentary described Qatari officials as mediators. The asymmetry flagged in the prior two outlooks has shifted. On Tuesday the de-escalation premium had been priced and escalation risk had not. Wednesday and Thursday priced escalation back in, with Brent up 7.35 points across the two sessions. The phased-deal report is now the unpriced side, and in our judgment it is the scenario that would reverse Thursday's move fastest. Nothing captured any Venezuela or Russia-Ukraine supply development.
Supply policy stays blank. No producer-group quota decision, compliance table or Russian policy signal was captured, and the Saudi items are security reports. A defense official's account of Wednesday's traffic, in items stamped 02:51 PM and 02:54 PM ET, said some 60 commercial vessels transited the Strait of Hormuz carrying the highest daily crude volume since early July, about 40 of them coordinating with the United States military for protection. That measures supply still moving under protection. Producer-group policy is a separate question.
Inventories were quiet. No release fell on Thursday on the captured calendars. The latest official weekly figure remains Wednesday's crude build of 2.969 million barrels against a consensus draw of 0.69 million, per the news-feed calendar record, and the next weekly petroleum status report lands at 10:30 AM ET on September 30. At 02:27 PM ET the French president said coordinated releases of strategic reserves could be considered. No reserve release decision was captured.
Products lagged, which reverses Wednesday's pattern. The October gasoline contract settled at 3.5646 dollars a gallon against 3.5870 on Wednesday, and October diesel at 4.7303 against 4.7764, per items stamped 02:32 PM ET on both days, while crude rose 2.45 points. Press commentary described November gasoline as closing down 0.22 percent. Refining margins narrowed. The Energy Secretary had contacted executives at several refineries to gauge support for a voluntary restriction amid narrow options to curb diesel prices, and the French president said at 02:27 PM ET that a United States diesel export ban would be bad. A headline stamped 06:01 PM ET put the national average diesel price at a record 6.52 dollars a gallon. The export question is open again, one day after the White House denial. No refinery utilisation figure or seasonal demand series was captured.
The dollar and yields edged up. The dollar index closed at 101.29, up 0.19 points or 0.19 percent, inside a 101.00 to 101.40 range. The ten-year yield index closed at 5.16 percent, up 5 basis points from Wednesday's 5.11, after a 5.09 to 5.18 range, and the thirty-year at 5.46 percent. The seven-year note auction stopped at a 5.085 percent high yield with a 2.420 bid-to-cover against 2.500 previously, per the news-feed calendar and unconfirmed. Weekly jobless claims printed 197,000 against a 200,000 consensus, per the news-feed calendar and unconfirmed.
Equities barely moved. The S&P 500 cash index closed at 7,704.13, down 1.90 points, and the Nasdaq-100 cash index at 30,478.86, up 8.57. The volatility index closed at 15.67, up 0.49. Gold's December contract settled at 4,298.0, down 20.4 points or 0.47 percent. Crude and Brent rose, yields and the dollar edged higher, gold slipped and equities finished flat, the crude-to-yields transmission at a smaller magnitude than on Wednesday. After the close, the Chinese president described a new joint trade arrangement with the United States as good news, per items stamped 04:16 PM and 04:24 PM ET, a risk-positive item for demand expectations.
Positioning is stale. The report as of September 15, 2026 remains the latest captured, and it predates the whole decline and recovery since the 101.69 high. Managed money held 221,896 contracts long against 115,617 short, a net long of 106,279. Commercials held 895,203 long against 1,060,061 short, a net short of 164,858, and swap dealers 118,240 long against 590,507 short. Open interest on November stood at 311,804 on the latest published row, for 09/23, down from 312,460 on 09/22 and 323,775 on 09/21. The 09/24 row carries no open-interest figure yet. A decline in open interest through a rebound is consistent with short covering rather than fresh length. That reading is our interpretation, and no attribution was measured.
One gap is deliberate. No dealer-positioning dataset was read for crude: no gamma map, no options concentration levels and no flow attribution, and none is borrowed from another instrument. Every level here comes from published pivot arithmetic, published deviation bands, published retracement and average projections, settlement averages reproduced from the daily record, or the back-solved session extremes. The equity-index outlooks for the same date carry a dealer-positioning section. Its absence here carries no implied neutral reading.
The trade map for Friday
Overhead, the published target price at 94.81 comes first, 20 cents above the settle, followed by the 9-day crossing at 95.15. The next shelf is 96.78 to 97.18. It holds Thursday's 96.78 high, one standard deviation resistance at 96.80, the stochastic 70 percent threshold at 96.96, the 9-day average stall at 97.14 and Pivot R1 at 97.18. Five references sit inside 40 cents. That makes it the densest overhead zone on the grid and the first place a Friday advance is tested. Two deviation resistance at 97.71 and three at 98.41 follow, with the stochastic 80 percent threshold at 98.54 thirteen cents higher. Pivot R2 at 99.76 is the practical top of a single session. The 101.69 annual high and Pivot R3 at 102.73 are extended references only; neither is a Friday objective.
Beneath the settle, the 94.21 Pivot Point is the first support, 40 cents down and six cents beneath the reopened session's 94.27 low. The 3-10-16 day convergence stall at 93.84 and the stochastic midpoint at 93.81 form a three-cent pair. The 18-day crossing at 93.44 and the 14-day %k stall at 93.18 follow, and Wednesday's 93.06 high with the 92.85 retracement close the upper support group. Thursday's 92.72 open and one deviation support at 92.42 come next. Then the densest mid-level group, all within 47 cents: the 91.98 crossover stall, the 91.81 20-day average, 91.63 Pivot S1 and two deviation support at 91.51. Thursday's low at 91.23 sits beneath it, and a settle below 91.23 would undo the higher low. Three deviation support at 90.81, the 90.12 half retracement and 88.66 Pivot S2, beside the old 88.67 to 88.71 shelf, are the extended references.
The primary setup is a long from a pullback into 93.80 to 94.20, the band around the 94.21 pivot and the 93.81 stochastic midpoint. Five readings carry it. Thursday made a higher high and a higher low against Wednesday on a 1.25 times expansion of the average daily range. It reclaimed the 5-day settlement average. The 9-day directional reading turned positive, and the composite rose to 64 percent buy. Brent outran WTI again, and the spread widened to 11.99. The stop at 92.30 sits 12 cents beneath one deviation support at 92.42. It also sits beneath the 92.85 retracement and Wednesday's 93.06 high. The first objective sits above the 95.15 crossing and beneath the 96.78 to 97.18 zone, the second above Pivot R1 and beneath the 97.71 band, the third above the 98.41 band and beneath Pivot R2 at 99.76. The 14-day average true range is 4.00 points. The stop sits 1.70 from the middle of the band.
The reopen sat close to the settle. The new Globex session reopened at 6:00 PM ET and was trading between 94.27 and 94.75 at the time of reading, with the provider showing a day open of 94.75; those prints belong to Friday's session. The reopen sits just above the 94.21 pivot. It carries the after-settle headlines: the Yemeni group's claims at 03:02 PM and 03:03 PM ET and the Chinese president's description of a new joint trade arrangement at 04:16 PM ET. The captured news-feed calendar carries no Asian release for the Thursday evening window. Bias is neutral to mildly firm above the 94.21 pivot, with an expected Globex band of roughly 93.40 to 95.60.
London works through the dollar. Euro-area money-supply growth prints at 04:00 AM ET, forecast 3.5 percent against 3.4 percent, and the New York Federal Reserve president speaks at 05:15 AM ET, both per the news-feed calendar and unconfirmed. An overnight Strait or Red Sea headline would matter more. Bias is neutral, with an expected band of roughly 93.20 to 95.80, and a reclaim of the 95.15 9-day crossing would change the character of the morning.
New York opens with the advance durable goods report at 08:30 AM ET, per the verified forward calendar. The headline consensus is a 0.3 percent decline against a prior 1.1 percent gain, and core orders are forecast up 0.6 percent against a prior 0.4 percent, per the news-feed calendar and unconfirmed. The final University of Michigan survey prints at 10:00 AM ET with sentiment forecast at 47.5 against 47.8, five-year inflation expectations forecast at 3.4 percent and one-year expectations previously 4.6 percent, per the news-feed calendar and unconfirmed. Neither is a crude release. The transmission runs through the dollar and the ten-year yield, which reached 5.18 percent on Thursday. The Strait negotiation is the headline most likely to move the contract. A hold above 94.21 through the pit open keeps the 96.78 to 97.18 zone in reach; a loss of 93.81 returns the contract toward the 92.85 to 93.06 pair. Expected band roughly 92.80 to 96.60.
The afternoon carries a European Central Bank speaker and the Cleveland Federal Reserve president, both at 02:00 PM ET and per the news-feed calendar and unconfirmed. Crude settles at 02:30 PM ET. That settlement is the last before a weekend in which the Strait negotiation and the Red Sea security situation can move without a market open. It leaves the Friday settle exposed to position squaring in both directions. Expected band roughly 93.00 to 96.40.
Globex does not reopen on Friday evening. The next session opens at 6:00 PM ET on Sunday, so two days of headline exposure separate Friday's close from the reopen. A de-escalation weekend points to the 92.42 one-deviation support and the 91.81 20-day average as the first gap references; an escalation weekend points to 97.18 Pivot R1 and the 97.71 two-deviation resistance. The following week has its own anchors. Personal income and outlays print at 08:30 AM ET on September 30, 2026, and the weekly petroleum status report at 10:30 AM ET the same day. The employment report follows at 08:30 AM ET on October 2, all per the verified forward calendar. No crude expiry falls on Friday; the provider lists the November contract's expiration as 10/20/26.
Three scenarios frame the full session: 93.30 to 95.90 on the low-range case, 92.60 to 96.80 on the mid-range case, which is the most likely, and 91.20 to 98.40 on the high-range case. The most probable path holds the reopened session near the 94.21 pivot through Asia and Europe, with the dollar the main mechanical input and Strait headlines the main source of surprise. Through the United States morning the contract tests the 95.15 crossing. In our analyst judgment, a settle between the pivot and the 96.78 to 97.18 zone is more likely than a settle through it. The product contracts did not confirm Thursday's move, and the phased-deal report caps enthusiasm into a weekend. A settle beneath the 93.81 to 93.84 pair would invalidate this reading and put the 92.42 to 92.85 group back in play.
Thursday's high stopped two cents under the one-deviation line at 96.80, and Friday's settle is the last price before two days of Strait headlines.
The complete data picture
Every number behind Friday’s plan, charted first, then the full level lists, then the complete numeric reference underneath.
Full numeric reference, every remaining figure from the session review
Carried below in the review’s own order: the executive summary from section 1, sections 2.1 to 2.6, the level notes from sections 3.1 and 3.2, sections 4.1 to 4.6, the coverage note from section 5, the session-by-session forecast from section 6, the Friday calendar from section 7 and the primary setup from section 8.
3.1 Resistance and 3.2 Support, level notes
The first overhead reference is the published target price at 94.81, 20 cents above the settle, followed by the 9-day average crossing price at 95.15. The next shelf is the 96.78 to 97.18 band, which holds Thursday's session high at 96.78, one standard deviation resistance at 96.80, the 14-3 day raw stochastic 70 percent threshold at 96.96, the 9-day average stall at 97.14 and Pivot R1 at 97.18. Five references inside 40 cents make it the densest overhead zone on the grid and the first place a Friday advance is tested.
Above that, two standard deviations resistance sits at 97.71 and three standard deviations resistance at 98.41, with the 14-3 day raw stochastic 80 percent threshold at 98.54 thirteen cents higher. Pivot R2 at 99.76 is the practical top of a single session. The 101.69 annual high and Pivot R3 at 102.73 are extended references only and are not Friday objectives. The published 14-day relative-strength 70 percent line at 103.90 sits beyond them, and the prior week's 94.64 low sits three cents above the settle.
The Pivot Point at 94.21 is the first support, 40 cents beneath the settle and six cents beneath the 94.27 low of the reopened session at the time of reading. Beneath it the 3-10-16 day moving-average convergence stall at 93.84 and the 14-3 day raw stochastic 50 percent threshold at 93.81 form a three-cent pair, and the 18-day average crossing price at 93.44 and the 14-day %k stall at 93.18 follow. Wednesday's high at 93.06 and the 38.2 percent retracement from the four-week high at 92.85 close the upper support group.
The 92.72 Thursday open and one standard deviation support at 92.42 are the next references. The three-and-ten day crossover stall at 91.98, the 20-day settlement average at 91.81, Pivot S1 at 91.63 and two standard deviations support at 91.51 sit within 47 cents of each other and form the densest mid-level group, with Thursday's low at 91.23 beneath it. A settle beneath 91.23 would undo Thursday's higher low. Beneath it, three standard deviations support at 90.81, the 50 percent retracement of the four-week range at 90.12 and Pivot S2 at 88.66 are the extended references, with the old 88.67 to 88.71 shelf alongside Pivot S2.
1. Executive Summary
The November crude contract settled at 94.61 on Thursday, up 2.45 points or 2.66 percent from Wednesday's 92.16 settle, the second consecutive higher settle after the run of five lower closes that followed the 09/15 settle of 100.75. The completed session traded a 5.55 point band between 96.78 and 91.23 and settled at 60.9 percent of that range. Against Wednesday the bar made both a higher high, 3.72 points above Wednesday's 93.06, and a higher low, 2.52 points above Wednesday's 88.71, so the inside-day pause recorded in the prior outlook has resolved upward on the first test. The 5.55 point range was 1.25 times the published 14-day average daily range of 4.43 points, which makes Thursday the widest session since Monday's 6.03 and the first expansion day since then.
The supply-risk narrative carried the session. Press commentary published after the settle attributed the early strength to a senior Iranian military official warning of a wider conflict and to Saudi reports of missile fire from Yemen toward the Red Sea port of Yanbu and the city of Taif, and attributed the retreat from the best levels to a press report that United States and Iranian negotiators were exploring a phased arrangement to reopen the Strait of Hormuz and lift the blockade of Iranian ports; the news feed carried that report at 12:15 PM ET. Brent's November contract settled at 106.60, up 3.52 points or 3.41 percent, per a news-feed item stamped 02:45 PM ET, and the Brent to WTI spread on the November contracts widened to 11.99 from 10.92. The headlines and the price path coincided; no time-stamped intraday price series was captured, so no causal ordering is asserted.
The structural question into Friday is whether a two-session recovery that has now reclaimed the 5-day settlement average can carry into the 97 area without a fresh supply shock. The composite multi-indicator read rose to 64 percent buy from 40 percent on Wednesday, the 9-day directional reading now shows positive direction at 24.43 above negative direction at 17.22, and the settle sits 1.46 points above the 5-day average and 2.80 points above the 20-day. Against that, the product contracts settled lower on the day while crude rose, and the phased-deal report is a de-escalation path that is live and unresolved. Crude remains the most volatile of the four instruments covered here; the published 14-day average true range of 4.00 points is 4.23 percent of price.
The primary setup is a long from the 93.80 to 94.20 band around the standard pivot, stopped beneath one standard deviation support, with objectives at 95.70, 97.40 and an extended 99.10.
2.1 Intraday and Session Review
The completed Thursday session opened at 92.72, 56 cents above Wednesday's 92.16 settle, marked a high of 96.78 and a low of 91.23, and settled at 94.61. No intraday series was captured, so the order in which those extremes were reached is not asserted and no path claim appears anywhere in this outlook. What the daily bar establishes is geometry: the settle finished 1.89 points above the open, 3.38 points above the low and 2.17 points beneath the high, which places it at 60.9 percent of the 5.55 point range. The press account that the market retreated from its best levels is consistent with a settle 2.17 points beneath the high, but it is press commentary and not a captured series.
The session extremes used here are the completed-session inputs behind the published pivot ladder rather than an independently read bar, back-solved from the outer pivot pairs and verified against every rung. The third resistance point at 102.73 minus the third support point at 86.08, divided by three, returns 5.55, and the second resistance point at 99.76 minus the second support point at 88.66, divided by two, returns the same 5.55. Three times the unrounded Pivot Point of 94.2067, published as 94.21, less the 94.61 settle gives a high plus low sum of 188.01, and the resulting pair of 96.78 and 91.23 reproduces all seven published rungs to the cent. The provider's own published daily record for the contract returns 92.72, 96.78, 91.23, 94.61, and a news-feed item stamped 02:31 PM ET carried the 94.61 settle with the 2.45 point gain. The pivot ladder and the daily record are surfaces of the same vendor, so they confirm internal consistency; the news-feed settle is an independent confirmation of the close only.
The same dated daily record shows Thursday's volume at 390,676 contracts, a preliminary figure, against 370,714 on Wednesday; the Thursday row carries no open-interest figure yet.
The provider's overview page, dated for the Friday session, showed a day open of 94.75, a day high of 94.75 and a day low of 94.27 at the time of reading. Those belong to the new Globex session that reopened at 6:00 PM ET and are not Thursday's range; they are cited only as the reopen context in the session forecast below.
2.2 Daily Structure
Thursday broke the two-session envelope on the upside only. Tuesday and Wednesday together spanned 93.84 to 88.67; Thursday's high at 96.78 cleared the top of that envelope by 2.94 points while its low at 91.23 stayed 2.56 points above the bottom of it. The 88.67 to 88.71 shelf defended on Tuesday and Wednesday is now 2.52 points beneath Thursday's low rather than the active line.
The prior week, September 14 through September 18, spanned 101.69 at the high and 94.64 at the low. Thursday's high at 96.78 re-entered that range, and the settle at 94.61 sits three cents beneath the prior week's low, so the contract has probed back into the structure it vacated on Monday without yet settling inside it. The 52-week, 13-week and one-month high of 101.69, set on 09/15/26, sits 7.08 points above the settle.
For the quarterly reference the 13-week extremes serve as the available proxy, because no prior-quarter high or low was captured. The 13-week high stands at 101.69 and the 13-week low at 67.09, and the settle sits 27.52 points above the 13-week low.
2.3 4-Hour and Swing Structure
The daily settlement sequence after the 09/15 peak reads 100.75, 97.51, 97.23, 96.08, 92.37, 90.52, 92.16 and then 94.61. The last two settles are the first back-to-back gains since the peak, and together they recover 4.09 points of the 10.23 point decline from 100.75 to 90.52, or 40.0 percent of it. Daily ranges ran 3.18 on Friday, 6.03 on Monday, 5.17 on Tuesday, 4.35 on Wednesday and 5.55 on Thursday, so Thursday ended two sessions of contraction with an expansion.
The retracement grid published for Friday places the 38.2 percent retracement from the four-week high at 92.85 and the 50 percent retracement of the four-week range at 90.12, both now beneath the market. The 38.2 percent retracement from the 13-week high sits at 88.47. On the upside the grid carries no retracement line between the settle and the 101.69 high; the overhead references are pivot, deviation and projection levels, listed in the level notes above.
2.4 Moving Averages
The averages cited here were computed from the provider's daily settlement series for the November contract: the 5-day average stands at 93.15, the 9-day at 95.37, the 20-day at 91.81 and the 50-day at 84.44. The captured history covers 60 completed sessions, so no 100-day or 200-day average is cited.
The 94.61 settle sits 1.46 points above the 5-day average and 2.80 points above the 20-day, and 76 cents beneath the 9-day. On Wednesday the contract settled 1.51 points beneath its 5-day average, so Thursday restored it above the shortest average in one session. The 50-day average sits 10.17 points beneath the settle, so the medium-horizon structure is intact and positive.
The projection grid gives the prices at which each average would be crossed on Friday: 95.15 for the 9-day and 93.44 for the 18-day, with the 40-day crossing at 85.91. The 9-day crossing at 95.15 is the nearest average-based line overhead, 54 cents above the settle.
2.5 Oscillator and Trend Readings
The oscillator figures below are as published on the provider's technical page for the Friday session. Relative strength reads 56.80 on the 9-day, 58.95 on the 14-day, 59.62 on the 20-day, 57.93 on the 50-day and 56.48 on the 100-day. The published 14-day relative-strength grid places the 50 percent line at 90.09 and the 70 percent line at 103.90, so the 14-day reading sits in the middle of its band rather than near an extreme.
Stochastics recovered from the lower half. The 9-day raw stochastic reads 45.62 percent and the 14-day 55.10 percent, with the 14-day %K at 41.28 and %D at 42.86; the 20-day reads 68.32 percent and the 50-day 76.11 percent. The published grid places the 14-3 day raw stochastic 50 percent threshold at 93.81 and its 70 percent threshold at 96.96, so the settle sits between them.
The directional system now points the same way on every horizon read. On the 9-day the directional index reads 34.47 with positive direction at 24.43 and negative direction at 17.22; on Wednesday the same horizon showed negative direction above positive, so the shortest horizon has turned. On the 14-day the index reads 30.44 with positive direction at 25.79 over negative at 16.47, and on the 20-day 25.33 with positive at 26.40 over negative at 16.36. Historic volatility reads 39.77 percent on the 9-day, 43.38 percent on the 14-day and 39.40 percent on the 20-day.
The composite multi-indicator read published for Friday is 64 percent buy, with the signal strength described as average and the short-term direction as strongest. The composite indicator itself reads buy. Underneath it the short-horizon group averages 60 percent buy, the medium-horizon group 25 percent buy, where the 50-day parabolic reading is the lone sell, and the long-horizon group 100 percent buy.
2.6 Volatility and Expected Range
The published 14-day average true range stands at 4.00 points and the 14-day average daily range at 4.43 points; the 9-day figures are 4.32 and 4.47, and the 20-day figures 3.77 and 3.94. Thursday's realised 5.55 point range was 1.25 times the 14-day average daily range, an expansion day for this contract.
A one-range projection from the 94.61 settle using the 14-day average true range of 4.00 points frames Friday between 90.61 and 98.61. The published standard-deviation bands are tighter, and each is centred on the 94.61 settle, 2.19, 3.10 and 3.80 points either side: one deviation spans 92.42 to 96.80, two spans 91.51 to 97.71 and three spans 90.81 to 98.41. The one-deviation resistance at 96.80 sits two cents above Thursday's 96.78 high, so the bands and the price structure point at the same place on the upside.
4.1 OPEC and Supply Policy (Quotas, Compliance, Saudi and Russia Signals)
No producer-group quota decision, compliance table or Russian policy signal was captured. The Saudi items captured are security reports rather than policy: press commentary described Saudi Arabia reporting missile fire from Yemen toward Yanbu and Taif, and the news feed carried claims by the Yemeni group of attacks on facilities at Yanbu and on a target in Riyadh in items stamped 03:02 PM and 03:03 PM ET, after the 02:30 PM ET settlement. Separately, a news-feed item on Wednesday's traffic reported by a United States defense official said some 60 commercial vessels transited the Strait of Hormuz on Wednesday carrying the highest daily crude volume since early July, about 40 of them coordinating with the United States military for protection, per items stamped 02:51 PM and 02:54 PM ET. That is a measure of supply still moving under protection and not a producer-group decision.
4.2 Inventory Data (Crude Stocks, Gasoline, Distillates, Cushing, Strategic Reserve)
No inventory release fell on Thursday on the captured calendars. The most recent official weekly figure remains Wednesday's crude build of 2.969 million barrels against a consensus draw of 0.69 million, per the news-feed calendar record. The next weekly petroleum status report is scheduled for 10:30 AM ET on September 30, per the verified forward calendar. A news-feed item stamped 02:27 PM ET carried remarks by the French president that coordinated releases of strategic reserves could be considered; no reserve release decision was captured.
4.3 Geopolitical Backdrop (Middle East, Iran, Russia and Ukraine, Venezuela)
Thursday's backdrop carried escalation and de-escalation reporting in the same session, and every element of it is reporting rather than settled fact. On the escalation side, press commentary cited a warning by a senior member of Iran's Revolutionary Guard Corps, the Saudi missile reports described above, and the Yemeni group's claims of attacks at Yanbu and in Riyadh after the settle. The United States Senate rejected a resolution curbing the administration's Iran war powers, per a news-feed item stamped 02:38 PM ET. On the de-escalation side, the news feed carried a press report at 12:15 PM ET that the United States and Iran were discussing a phased deal to reopen the Strait of Hormuz and end the United States blockade, and press commentary described Qatari officials as mediators.
The asymmetry flagged in the prior two outlooks has shifted. On Tuesday the de-escalation premium had been priced and escalation risk had not; Wednesday and Thursday together priced escalation back in, with Brent up 7.35 points across the two sessions. The phased-deal report is now the unpriced side, and it is the scenario that would reverse the Thursday move fastest. Nothing captured any Venezuela or Russia-Ukraine supply development.
4.4 Demand and Refining (Refinery Utilisation, Crack Spreads, Seasonal Pattern)
Products lagged crude on Thursday, which reverses Wednesday's pattern. The October gasoline contract settled at 3.5646 dollars a gallon against 3.5870 on Wednesday and the October diesel contract at 4.7303 against 4.7764, per news-feed items stamped 02:32 PM ET on both days, while crude rose 2.45 points; press commentary described November gasoline as closing down 0.22 percent. Refining margins therefore narrowed on the day. A news-feed item reported that the Energy Secretary had contacted executives at several refineries to gauge support for a voluntary restriction amid narrow options to curb diesel prices, and the French president said at 02:27 PM ET that a United States decision to ban diesel exports would be bad. An energy-news headline stamped 06:01 PM ET put the national average diesel price at a record 6.52 dollars a gallon. The diesel export question is therefore open again one day after the White House denial recorded in the prior outlook.
No refinery utilisation figure was captured, and no seasonal demand series was read, so neither is asserted.
4.5 Dollar and Cross-Asset (Dollar Index, Commodities Complex, Equity Risk Appetite)
The dollar index closed at 101.29, up 0.19 points or 0.19 percent, inside a 101.00 to 101.40 range. The ten-year yield index closed at 5.16 percent, up 5 basis points from Wednesday's 5.11, after a 5.09 to 5.18 range, and the thirty-year at 5.46 percent. The seven-year note auction stopped at a 5.085 percent high yield with a 2.420 bid-to-cover against 2.500 previously, per the news-feed calendar and unconfirmed. Weekly jobless claims printed 197,000 against a 200,000 consensus, per the news-feed calendar and unconfirmed.
The equity indices held steady against the crude move. The S&P 500 cash index closed at 7,704.13, down 1.90 points, and the Nasdaq-100 cash index at 30,478.86, up 8.57 points. The volatility index closed at 15.67, up 0.49 points. Gold's December contract settled at 4,298.0, down 20.4 points or 0.47 percent. The transmission from crude to yields continued at a smaller magnitude than on Wednesday: crude and Brent rose, yields and the dollar edged higher, gold slipped and equities finished flat. After the close, the Chinese president described a new joint trade arrangement with the United States as good news, per news-feed items stamped 04:16 PM and 04:24 PM ET, a risk-positive item for demand expectations.
4.6 Institutional Positioning (Commitments Data, Money Manager and Commercial Hedger, Speculator Length)
The positioning report as of September 15, 2026 remains the latest captured, and it predates the whole decline and recovery since the 101.69 high. It showed managed money long 221,896 contracts against short 115,617, a net long of 106,279. Commercials held 895,203 long against 1,060,061 short, a net short of 164,858, and swap dealers held 118,240 long against 590,507 short.
Open interest on the November contract stood at 311,804 on the latest published row for 09/23, down from 312,460 on 09/22 and 323,775 on 09/21; the 09/24 row carries no open-interest figure yet. The decline in open interest through a rebound is consistent with short covering rather than fresh length, and that reading is interpretation, not a measured attribution.
5. No liquid options proxy
Crude is covered here without a positioning dataset. No dealer-positioning surface was read for this instrument, no gamma map, no options concentration levels and no flow attribution, and none is inferred from any other instrument. Every level in this outlook originates in published pivot arithmetic, published standard-deviation bands, published retracement and moving-average projections, settlement averages reproduced from the provider's daily record, or the back-solved session extremes described in section 2.1.
This is a statement about coverage, not about the existence of listed crude options. No such dataset was read, so no claim resting on one appears anywhere in this outlook. The equity-index outlooks for the same date carry a dealer-positioning section; its absence here is deliberate and is not an implied neutral reading.
Night Session (6:00 PM ET Thursday to 3:00 AM ET Friday, Globex and Asia)
The Globex reopen carries the after-settle headlines: the Yemeni group's claims of attacks at Yanbu and in Riyadh at 03:02 PM and 03:03 PM ET, and the Chinese president's description of a new joint trade arrangement at 04:16 PM ET. The reopened session was trading between 94.27 and 94.75 at the time of reading, with the provider showing a day open of 94.75, so the reopen sat close to the 94.61 settle and just above the 94.21 pivot. The captured news-feed calendar carries no Asian release for the Thursday evening window. Bias neutral to mildly firm above the 94.21 pivot, expected Globex band roughly 93.40 to 95.60.
London Session (3:00 AM to 8:00 AM ET Friday)
The European morning carries euro-area money-supply data at 04:00 AM ET, forecast 3.5 percent against 3.4 percent, and remarks by the New York Federal Reserve president at 05:15 AM ET, both per the news-feed calendar and unconfirmed. For crude the European window matters mainly through the dollar and through any overnight Strait or Red Sea headline. Bias neutral, expected band roughly 93.20 to 95.80, with the 95.15 9-day crossing as the level whose reclaim would change the character of the morning.
Morning Session (9:00 AM to 12:00 PM ET Friday, United States Open and Pit Session)
The United States morning opens with the advance durable goods report at 08:30 AM ET, per the verified forward calendar, with a headline consensus decline of 0.3 percent against a prior gain of 1.1 percent and a core consensus gain of 0.6 percent, per the news-feed calendar and unconfirmed. The final University of Michigan sentiment survey prints at 10:00 AM ET with a consensus of 47.5 against 47.8 and five-year inflation expectations forecast at 3.4 percent, per the news-feed calendar and unconfirmed. Neither is a crude-specific release; the transmission to crude runs through the dollar and the ten-year yield, which reached 5.18 percent on Thursday. The Strait negotiation is the headline most likely to move the contract. A hold above 94.21 through the pit open keeps the 96.78 to 97.18 zone in reach; a loss of 93.81 returns the contract toward the 92.85 to 93.06 pair. Expected band roughly 92.80 to 96.60.
Afternoon Session (12:00 PM to 2:30 PM ET Friday, NYMEX Pit Close)
The afternoon carries remarks by the Cleveland Federal Reserve president at 02:00 PM ET, per the news-feed calendar and unconfirmed. Crude's pit settlement falls at 02:30 PM ET, and it is the last settlement before a weekend in which the Strait negotiation and the Red Sea security situation can move without a market open. That makes the Friday settle vulnerable to position squaring in both directions. Expected band roughly 93.00 to 96.40.
Night Session Forward (6:00 PM ET Friday)
Globex does not reopen on Friday evening; the next session opens at 6:00 PM ET on Sunday, so two days of headline exposure separate Friday's close from the reopen. Gap levels both ways: a de-escalation weekend points to the 92.42 one-deviation support and the 91.81 20-day average as the first gap references, and an escalation weekend points to the 97.18 Pivot R1 and the 97.71 two-deviation resistance. The forward anchor for the following week is the personal income and outlays report at 08:30 AM ET on September 30, 2026 and the weekly petroleum status report at 10:30 AM ET on September 30, 2026, followed by the employment report at 08:30 AM ET on October 2, all per the verified forward calendar.
Expected Range (Friday Full Session)
Low-range scenario: 93.30 to 95.90
Mid-range scenario (most likely): 92.60 to 96.80
High-range scenario: 91.20 to 98.40
Most Likely Path
The most probable path holds the reopened session near the 94.21 pivot through the Asian and European windows, with the dollar the main mechanical input and Strait headlines the main source of surprise. Through the United States morning the contract tests the 95.15 9-day crossing, and in our analyst judgment a settle between the pivot and the 96.78 to 97.18 zone is more likely than a settle through it, because the product contracts did not confirm Thursday's crude move and the phased-deal report caps enthusiasm into a weekend. The alternative that would invalidate this reading is a settle beneath the 93.81 to 93.84 pair, which would put the 92.42 to 92.85 group back in play.
7. Friday Economic Calendar
The captured news-feed calendar carries no Asian release for the Thursday evening window. The European morning carries euro-area money-supply growth at 04:00 AM ET, forecast 3.5 percent against a prior 3.4 percent, per the news-feed calendar and unconfirmed, and remarks by the New York Federal Reserve president at 05:15 AM ET, per the news-feed calendar and unconfirmed.
The United States morning carries the advance durable goods report at 08:30 AM ET, per the verified forward calendar, with headline orders forecast at minus 0.3 percent against a prior 1.1 percent and core orders forecast at plus 0.6 percent against a prior 0.4 percent, per the news-feed calendar and unconfirmed. The final University of Michigan survey prints at 10:00 AM ET, with sentiment forecast at 47.5 against 47.8, five-year inflation expectations forecast at 3.4 percent and one-year expectations previously 4.6 percent, per the news-feed calendar and unconfirmed. In the afternoon a European Central Bank speaker appears at 02:00 PM ET and the Cleveland Federal Reserve president speaks at 02:00 PM ET, both per the news-feed calendar and unconfirmed.
The captured calendars carry no crude inventory release for Friday; the next weekly petroleum status report is at 10:30 AM ET on September 30, per the verified forward calendar. No structural crude expiry falls on Friday; the provider lists the November contract's expiration as 10/20/26. The single first-order event for crude on Friday is not a scheduled release but the Strait negotiation reported on Thursday, with the durable goods report at 08:30 AM ET on September 25, 2026 the first-order scheduled item for the dollar and yield channel.
8. Primary Trade Setup
Direction: Long
Rationale: Thursday made a higher high and a higher low against Wednesday on a 1.25 times expansion of the average daily range, reclaimed the 5-day settlement average, turned the 9-day directional reading positive and lifted the composite read to 64 percent buy, while Brent outran WTI again and the spread widened to 11.99; a pullback into the pivot and the stochastic midpoint offers a long with a defined risk point beneath one standard deviation support.
Entry Zone: 93.80 to 94.20
Stop Loss: 92.30 (beneath one standard deviation support at 92.42 and beneath the 92.85 retracement and Wednesday's 93.06 high)
Target 1 (T1): 95.70 (above the 95.15 9-day crossing and beneath the 96.78 to 97.18 zone)
Target 2 (T2): 97.40 (above Pivot R1 at 97.18 and beneath two standard deviations resistance at 97.71)
Target 3 (T3, extended): 99.10 (beneath Pivot R2 at 99.76 and above three standard deviations resistance at 98.41)
Risk-to-Reward: Approximately 1:1 to T1, 1:2 to T2, 1:3 to T3
Invalidation: A settle beneath Thursday's 91.23 low negates the thesis outright, because it would erase the higher low. Short of that, the edge is removed by acceptance beneath the 93.06 Wednesday high, distinguished from a touch: two consecutive 30-minute closes beneath 93.06 with the 92.85 retracement also lost. A single trade beneath 93.80 that is recovered inside one 30-minute bar is the entry condition described above; only acceptance as defined converts it into invalidation.
Macro override: A confirmed agreement to reopen the Strait of Hormuz would remove the supply-risk premium that Wednesday and Thursday restored. In that scenario the long is wrong immediately, and the 91.81 20-day average becomes the next test within one 14-day average true range of 4.00 points. A coordinated strategic reserve release announcement would carry the same risk.
Sources and methodology
This outlook is built from our session review of the November NYMEX WTI crude contract, CLX26, the November ’26 month, tracked on the continuous CL1! chart and prepared after Thursday’s close on September 24, 2026 for the Friday, September 25, 2026 session. The contract domain was checked before any level was used: the daily chart’s quote of 94.28 with its stated change of minus 0.33 returns 94.61, the published previous close, and the chart’s new-session open of 94.75 and high of 94.75 equal the provider’s day open and day high, so chart and levels sit on the same November contract. The day high, day low and open shown on the data provider’s overview page belong to the new Globex session dated September 25 and are not presented anywhere here as Thursday’s range.
Thursday’s session extremes are the completed-session inputs behind the published pivot ladder rather than an independently read bar, back-solved from the outer pivot pairs, checked against all seven published rungs and reproduced by the data provider’s published daily record, a second surface of the same provider that confirms internal consistency; the settle is independently confirmed by the news-feed settlement item. The 5-day, 9-day, 20-day and 50-day averages were reproduced from that daily settlement series, and no 100-day or 200-day average is cited because 60 sessions do not support one. Volume and open interest are quoted from the dated rows of that daily record: Thursday’s volume is preliminary and Thursday’s open interest is not yet published, so the latest open interest quoted is the 09/23 row. Oscillator readings are cited as published. No intraday series was captured, so no intraday path is asserted. No dealer-positioning dataset was read for crude, so no gamma, dealer-positioning or options-flow claim is made. Items marked unconfirmed come from the news-feed calendar captured for this session; catalysts whose time had passed at 6:16 PM ET, when collection began, are recorded with their result. Scenario ranges are analyst judgment and carry no calibration.
Not captured, and stated nowhere as a figure: any intraday price series, a prior-quarter high or low, any producer-group quota decision, compliance table or Russian policy signal, a refinery utilisation figure, a seasonal demand series, a strategic reserve release decision, Thursday’s open interest, and any Venezuela or Russia-Ukraine supply development.
Thursday’s outlook for this contract is here, and Thursday’s gold outlook is here. Outlooks for the equity index, technology index, gold and crude contracts are collected on the market outlook page, and our forward trading record is on the performance statement.