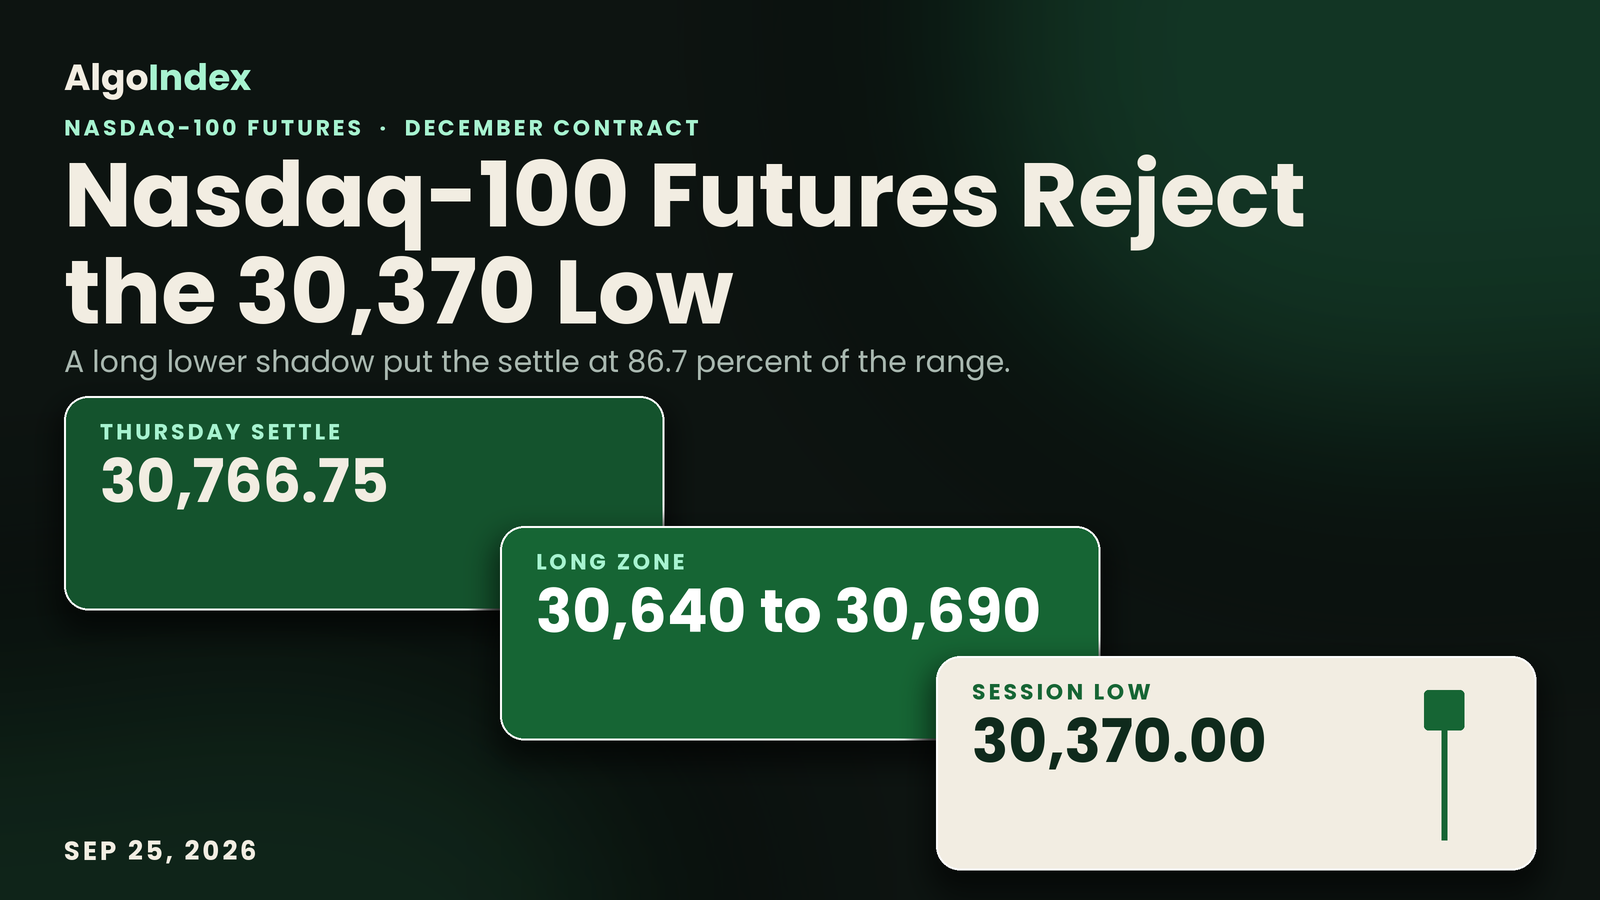
At 5.18 percent, the ten-year yield index touched what press commentary described as a 19-year high on Thursday. It closed at 5.16 percent, up 5 basis points. Crude rose 2.66 percent on Middle East supply risk, and press commentary quoted two regional Federal Reserve presidents leaning toward further tightening. December Nasdaq-100 futures settled at 30,766.75. That is up 2.00 points from Wednesday's 30,764.75. Effectively unchanged.
The bar carries the rest of the story. Thursday traded a 457.50 point band between 30,370.00 and 30,827.50 and settled at 86.7 percent of it, 396.75 points above the low. A long lower shadow. The review reads that shape as a rejection of lower prices, printed as a single lower-high, lower-low bar after Wednesday's 31,094.75 three-month high. The cash index closed at 30,478.86, up 8.57 points or 0.03 percent. Press commentary tied a recovery in stocks to short covering after a report, carried on the news feed at 12:15 PM ET, that United States and Iranian negotiators were exploring a phased arrangement to reopen the Strait of Hormuz. Those items and the price path coincided. No time-stamped intraday price series was captured, so no causal ordering is asserted.
December Nasdaq-100 futures settled at 30,766.75, up 2.00 points, at 86.7 percent of a 457.50 point range and 112.00 points above the Pivot Point at 30,654.75. Preliminary volume was 658,722 contracts. Thursday's open interest is not yet published. The latest reading is 274,125 for 09/23. The composite multi-indicator read is 88 percent buy with strength good and direction weakening, and the 9-day directional system reads 29.87 positive against 17.14 negative. Overhead: the 30,787.89 futures equivalent of the 30,500 cash concentration, Thursday's 30,827.50 high, Pivot R1 at 30,939.50 and the 31,094.75 to 31,112.25 zone. Beneath: the 30,642.75 to 30,654.75 group, Pivot S1 at 30,482.00 and Thursday's 30,370.00 low. The primary setup is a long from 30,640 to 30,690, stop 30,470, targets 30,860, 31,055 and 31,250. The first-order release is the durable goods report at 08:30 AM ET, per the verified forward calendar, and Globex stays shut from Friday's close until 6:00 PM ET on Sunday.
The 30,840 short band stayed 12.50 points out of reach
Our Thursday outlook set a short from 30,840 to 30,940 with a stop at 31,110 and targets at 30,670, 30,450 and 30,230. Thursday opened at 30,780.00, 60.00 points beneath the band. The session high printed at 30,827.50. That is 12.50 points short of the band's lower edge, so the entry zone never traded. The stop sat 282.50 points above the high. The low at 30,370.00 ran through the 30,670 and 30,450 target levels and held 140.00 points above the 30,230 third target. With no print inside the band the card never became active, so those target prints carry no result. The settle at 30,766.75 landed 73.25 points beneath the band and 343.25 beneath the stop.
We named the 30,834.08 Pivot Point as the first ceiling in that outlook. Thursday's high stopped 6.58 points beneath it. The same outlook called the 38.2 percent retracement at 30,314.80 the first retracement line of the swing. The low held 55.20 points above it, 12.08 points beneath the 30,382.08 Pivot S2 we listed. Neither invalidation test triggered. The settle sat 328.00 points beneath the 31,094.75 settle test, and the high stayed 197.92 points beneath Pivot R1 at 31,025.42, so no 30-minute close could reach it.
The macro override named a well-received developer conference and a seven-year auction that stops through its when-issued level. Tonight's review records the seven-year note at a 5.085 percent high yield with a 2.420 bid-to-cover against 2.500 previously, per the news-feed calendar and unconfirmed. No when-issued level was captured. The review also records a large megacap platform company up about 5 percent after its product launch event, without tying that event to the conference the card named. Neither condition is scored. We grade the card as written: the band never traded, the stop and the settle test were never reached, and no fill is asserted.
A rejection candle at 86.7 percent of the range
Thursday opened at 30,780.00, 15.25 points above Wednesday's 30,764.75 settle, and marked a high of 30,827.50 and a low of 30,370.00. The settle finished 13.25 points beneath the open, 60.75 beneath the high and 396.75 above the low. A small body. The review reads a small body near the top of the range with a long lower shadow as a rejection of lower prices. No intraday series was captured, so the order in which the two extremes printed is not asserted anywhere here.
Against Wednesday the bar is a lower high and a lower low. The high sits 267.25 points beneath Wednesday's 31,094.75 and the low 272.75 beneath Wednesday's 30,642.75. Then look at the close. Wednesday settled at 27.0 percent of its range; Thursday settled at 86.7 percent. Travel held steady: the 457.50 point range was 1.03 times the 14-day average daily range of 445.68, an ordinary session for this contract, against Wednesday's 452.00. Preliminary volume rose to 658,722 contracts from 543,487 on Wednesday, per the provider's daily record, and Thursday's open interest is not yet published.
Those extremes come from the ladder. They are the completed-session inputs behind the published pivot ladder, back-solved from the outer pivot pairs. Pivot R3 at 31,397.00 minus Pivot S3 at 30,024.50, divided by three, returns 457.50. Pivot R2 at 31,112.25 minus Pivot S2 at 30,197.25, divided by two, returns the same figure. The provider's daily record repeats 30,780.00, 30,827.50, 30,370.00 and 30,766.75. Both surfaces belong to the same vendor, so they confirm internal consistency only.
Zoom out and the swing holds. From the 09/16 low at 29,053.00 to Wednesday's 31,094.75 high the advance measured 2,041.75 points. Thursday's low retraced 724.75 of it, 35.5 percent. The settle gives back 328.00, or 16.1 percent. The published 38.2 percent retracement from the four-week high at 30,314.80 sits 55.20 points beneath the low, so the pullback stopped short of the first standard retracement line. The prior week, September 14 through September 18, spanned 29,053.00 to 29,993.25, and the settle sits 773.50 points above that week's high. The contract has not re-entered the range it left on Monday.
Settlements tell the same story. From the 09/16 low the sequence reads 29,256.75, 29,743.00, 29,917.25, 30,784.75, 31,028.50, 30,764.75 and then 30,766.75. On the quarterly proxy the 13-week and one-month high is 31,094.75, set on 09/23/26, and the 13-week low 27,482.00; the settle sits 328.00 points beneath the top and 3,284.75 above the bottom. The proxy stands in because no prior-quarter high or low was captured. The 52-week high on the December contract stands at 31,336, 569.25 points above the settle.
Every average sits beneath price. Computed from the provider's daily settlement series, the 5-day stands at 30,652.40, the 9-day at 30,106.44, the 20-day at 29,890.14 and the 50-day at 29,632.93. The settle clears them by 114.35, 660.31, 876.61 and 1,133.82 points. The 50-day carries a caveat. The December contract was the deferred month until mid-September, so its window includes thinly traded sessions. The captured history covers 60 completed sessions, so no 100-day or 200-day average is cited. The 5-day sits 2.35 points beneath the Pivot Point, which makes the 30,652 to 30,655 pair the first average-based support. Crossing prices project at 30,188.56 for the 9-day, 29,895.10 for the 18-day and 29,861.09 for the 40-day.
Momentum runs high and slows at the edges. Relative strength reads 67.26 on the 9-day, 62.66 on the 14-day, 59.22 on the 20-day, 55.16 on the 50-day and 54.64 on the 100-day, as published for the Friday session. The 14-day grid places its 70 percent line at 31,553.01 and its 50 percent line at 29,953.93. Stochastics stay elevated. The raw stochastic reads 83.94 percent on the 9-day, 14-day and 20-day and 90.92 percent on the 50-day, and the 14-day %K at 88.64 sits beneath its %D at 91.47. The settle sits above the 80 percent threshold at 30,686.40; the 70 percent threshold is 30,482.22.
Direction still leans up on the short horizon. The 9-day index reads 25.76 with positive direction at 29.87 over negative at 17.14. The 14-day reads 16.74, positive 26.83 over 18.55, and the 20-day 13.11, positive 24.63 over 19.83. Only the 9-day index clears 20. The composite multi-indicator read is 88 percent buy, strength good, direction weakening, and the composite indicator itself reads buy. Short-horizon and medium-horizon groups each average 100 percent buy; the long-horizon group averages 33 percent buy, where the 50-100 day crossover reads sell. Historic volatility reads 18.24 percent on the 9-day, 16.38 percent on the 14-day and 16.01 percent on the 20-day.
Volatility sets the frame. The 14-day average true range stands at 470.86 points and the 14-day average daily range at 445.68; the 9-day figures are 470.04 and 492.94, the 20-day 485.53 and 427.26. One average true range either side of the settle spans 30,295.89 to 31,237.61. The published deviation bands are tighter. One deviation spans 30,340.98 to 31,192.52, two span 30,164.62 to 31,368.88 and three span 30,029.30 to 31,504.20.
Flat against a 5.18 percent ten-year
Rates leaned on the contract all session. The ten-year yield index traded 5.09 to 5.18 percent and closed at 5.16, up 5 basis points, and the thirty-year closed at 5.46 percent. Press commentary quoted the New York Federal Reserve president as saying the central bank has a lot of work to do to contain inflation. It quoted the Philadelphia Federal Reserve president as saying some modest further tightening may be warranted. The desk note cited fed funds futures pricing a roughly 71 percent likelihood of an October increase, against roughly 55 percent a week earlier. Long-duration growth equities feel that channel most. The contract finished flat anyway. The review calls that the relative-strength signal of the day.
Headlines cut both ways. A press report carried on the news feed at 12:15 PM ET said the United States and Iran were discussing a phased deal to reopen the Strait of Hormuz, and press commentary tied short covering in stocks to that report. The news feed also carried claims by Yemen's Houthis of attacks at Yanbu and in Riyadh at 03:02 PM and 03:03 PM ET. Crude settled at 94.61, up 2.66 percent. After the close the Chinese president described a new joint trade arrangement with the United States as good news and said the two countries could continue artificial-intelligence dialogue, per news-feed items stamped 04:13 PM through 04:24 PM ET. The review counts that as constructive for the technology complex.
Megacap strength helped. The positioning desk note recorded a large megacap platform company up about 5 percent after its product launch event, closing at 778 and up about 14 percent on the week. Longer-dated call buying concentrated in that name, with single-stock hedging delta of plus 2 billion dollars. Spending headlines kept coming. An item stamped 04:04 PM ET reported a 12 billion dollar compute agreement between an artificial-intelligence developer and a content-delivery network company, and one stamped 12:01 PM ET a five-year artificial-intelligence agreement between a European bank and a large cloud provider. After the close a large warehouse retailer reported fiscal fourth-quarter earnings of 6.75 dollars a share against a 6.53 estimate and revenue of 95.72 billion dollars against 94.92 billion, per an item stamped 04:18 PM ET. The verified forward calendar lists it as an after-close release on September 24, 2026.
Chips left no reading. No semiconductor-specific print or sector flow figure was captured, so no rotation inside technology is asserted. The cash index beat the broad market by 0.05 percentage points, a small margin. The S&P 500 cash index closed at 7,704.13, down 1.90 points. The volatility index closed at 15.67, up 0.49 points, and the desk note recorded the volatility-of-volatility index up 2 points at 90.57. The dollar index rose 0.19 percent to 101.29, and gold settled at 4,298.0, down 0.47 percent. The broad-index outlook reads the same session from the S&P 500 side.
Positioning sits on two surfaces, the cash index and the technology fund, and their levels reach futures only through the measured basis. Thursday's basis is the 30,766.75 settle less the 30,478.86 cash close, 287.89 points. The desk note's reference column carries the prior session's close, and it checks out. The cash reference of 30,470 matches Wednesday's 30,470.29 close, and the fund's 741 matches the provider's 741.21.
On the cash index the model reads a volatility threshold at 29,460, a gamma-flip level at 29,938 and a primary gamma concentration at 30,500, with gamma tilt 1.606 and gamma notional 14.591 million dollars. The cash close sits 21.14 points beneath 30,500 and 540.86 above the flip. Converted at the basis, 30,500 becomes 30,787.89 in futures, between the settle and Thursday's high, and 29,938 becomes 30,225.89, between the retracement group and Pivot S2. The mapped key levels are 30,500, 30,000, 29,475 and 31,000, and 31,000 converts to 31,287.89. The mapped confluence levels are 30,257, 30,013, 30,836 and 31,232. One oddity. The published call-side and put-side fields, 29,475 and 29,500, both sit beneath the cash close and invert their usual order, so they are recorded and left out of the level structure.
The fund sits a dollar above its concentration. The model reads a volatility threshold at 739, a gamma-flip level at 739, a primary gamma concentration at 740, a call-side ceiling at 760 and a put-side base at 736, with gamma tilt 0.928 and gamma notional 12.158 million dollars. The fund closed at 741.10 on the provider's daily record, 1.10 above the concentration and 2.10 above the two modeled thresholds. A second model disagrees. A separate positioning console, updated Thursday on a different model, showed a current price of 740.50 against a previous close of 741.17. It carried call gamma of minus 832 million dollars, put gamma of minus 3.7 billion and next-expiry gamma at 17.99 percent of the total. So the console reads negative and the desk table positive. The two sit side by side, unreconciled, and no level in the ladder rests on either sign. The console's volatility-point fields, published as 737 and 520, are excluded as low confidence.
Hedging flow stayed short-dated. The desk note recorded index-level hedging delta of minus 12 billion dollars on the day, mostly in same-day expiries, after minus 20 billion on Wednesday, and characterised it as tactical hedging. Those are the note's characterisations, and no timestamp-aligned flow series was captured. The latest positioning report, as of September 15, 2026, shows leveraged funds at 52,680 long against 59,067 short, a net short of 6,387, after covering 20,479 shorts on the week. Asset managers held 105,199 long against 38,388 short, net long 66,811, and dealers 52,437 long against 131,666 short. Open interest on the December contract stood at 274,125 on the latest published row for 09/23, against 285,475 on 09/22. The report predates Thursday by seven sessions and describes a starting condition.
The trade map for Friday
The primary setup is a long from 30,640 to 30,690, a pullback into the band around the Pivot Point at 30,654.75, the 5-day average at 30,652.40 and Wednesday's 30,642.75 low. The case is the bar. It tested 457.50 points lower and settled at 86.7 percent of its range, above the pivot and the 5-day average, with the composite at 88 percent buy, the 9-day directional reading positive and the contract flat against a 5.18 percent ten-year high. The stop at 30,470 sits 12.00 points beneath Pivot S1 at 30,482.00 and 12.22 beneath the 70 percent threshold at 30,482.22. The 14-day average true range of 470.86 points compares with a 195 point stop distance. Targets step up through Thursday's high, the three-month high zone and an extended 31,250.
Overhead the references start close. The published target price at 30,812.61 and Thursday's 30,827.50 high sit 45.86 and 60.75 points above the settle. The 30,787.89 equivalent of the 30,500 cash concentration sits between the settle and the high. Pivot R1 at 30,939.50 is the next ceiling. The 31,035.70 stall projection of the 14-day %K line comes next. Wednesday's 31,094.75 three-month high and Pivot R2 at 31,112.25 form the zone a Friday advance has to clear to resume the swing. Beyond it, one standard deviation resistance at 31,192.52 and the 31,287.89 equivalent of the 31,000 cash level are the extended references. Two standard deviations resistance at 31,368.88 and Pivot R3 at 31,397.00 sit above them.
Support stacks tightly. The raw stochastic 80 percent threshold at 30,686.40 sits 80.35 points beneath the settle. Then the Pivot Point at 30,654.75, the 5-day average at 30,652.40 and Wednesday's low at 30,642.75 form the first support group, inside 12.00 points of each other. The entry band sits on it. Pivot S1 at 30,482.00 and the 70 percent threshold at 30,482.22 form the next pair, with Thursday's 30,370.00 low beneath. One standard deviation support at 30,340.98 and the 30,314.80 retracement make the first retracement group. The 30,225.89 equivalent of the cash gamma flip, Pivot S2 at 30,197.25, the 9-day crossing at 30,188.56 and two standard deviations support at 30,164.62 follow. Pivot S3 at 30,024.50 and three standard deviations support at 30,029.30 are the extended references.
Globex has already reopened. It opened at 30,726.50 and was trading between 30,708.50 and 30,765.25 at the time of reading, above the 30,654.75 pivot. Those prints belong to the new session and sit outside Thursday's range. The reopen carries the after-close items: the warehouse retailer at 04:18 PM ET, the compute agreement at 04:04 PM ET and the Chinese president's remarks from 04:13 PM ET. The captured news-feed calendar carries no Asian release for the evening. Bias reads constructive above 30,654.75, and the Globex band is framed at roughly 30,600 to 30,900. London is framed at roughly 30,550 to 30,950, neutral to constructive above the 30,642.75 to 30,654.75 group, with European yields the main transmission.
Data arrives early. Euro-area money-supply growth prints at 04:00 AM ET, forecast 3.5 percent against a prior 3.4 percent, and the New York Federal Reserve president speaks at 05:15 AM ET, both per the news-feed calendar and unconfirmed. The advance durable goods report lands at 08:30 AM ET on the verified forward calendar. Headline orders are forecast at minus 0.3 percent against a prior 1.1 percent and core at plus 0.6 percent against 0.4 percent, per the news-feed calendar and unconfirmed. It is the single first-order event, read through its effect on the ten-year yield. The final University of Michigan survey prints at 10:00 AM ET, with sentiment forecast at 47.5 against 47.8 and five-year inflation expectations at 3.4 percent, per the news-feed calendar and unconfirmed.
Then the cash open. At 09:30 AM ET it sets the session's first directional test against 30,787.89, the futures equivalent of the 30,500 cash concentration. A hold above 30,654.75 keeps the 30,939.50 Pivot R1 in reach. A loss of 30,482.00 returns the contract toward Thursday's low. The morning band runs roughly 30,450 to 31,000. A European Central Bank speaker and the Cleveland Federal Reserve president both appear at 02:00 PM ET, per the news-feed calendar and unconfirmed, and the afternoon band runs roughly 30,500 to 30,950.
After that comes the weekend. Globex does not reopen on Friday evening; the next session opens at 6:00 PM ET on Sunday, so two days of headline exposure separate the close from the reopen with a Middle East negotiation still open. The review reads that as an argument for position squaring into the close. A constructive weekend points to the 31,094.75 to 31,112.25 zone, and a risk-off weekend points to the 30,314.80 retracement and the 30,197.25 Pivot S2. No structural index expiry falls on Friday; the provider lists the December contract's expiration as 12/18/26. The following week carries personal income and outlays at 08:30 AM ET on September 30, 2026, and a memory-chip maker's results at 04:30 PM ET that day, per the verified forward calendar. The employment report follows at 08:30 AM ET on October 2, 2026, on the same calendar.
The scenario bands stay wide. Across the full session the low-range case runs 30,600 to 30,940, the mid-range and most likely case 30,480 to 31,040 and the high-range case 30,315 to 31,195. The most probable path holds Globex above the 30,654.75 pivot. A test of the 30,812.61 to 30,827.50 references follows the United States data. In this review's analyst judgment a settle between the pivot and Pivot R1 at 30,939.50 is more likely than a move through the 31,094.75 high on Friday, because the rate channel has not turned and the weekend argues for squaring. That weighting carries no measured frequency. A settle beneath Pivot S1 at 30,482.00 would negate Thursday's rejection candle.
The durable goods report at 08:30 AM ET is the first test of whether yields get their next push.
The complete data picture
Every number behind Friday’s plan, charted first, then the full level map, then the complete numeric reference underneath.
Cash-index levels at the measured 287.89 point basis: the 30,500 cash level converts to 30,787.89 in futures, the 29,938 modeled gamma flip to 30,225.89 and the 31,000 cash level to 31,287.89. No other cash level is translated.
Full numeric reference, every remaining figure from the session review
3.1 Resistance, level by level
30,787.89 is the futures equivalent of the cash index's 30,500 primary gamma concentration at the measured basis of 287.89 points, between the settle and the session high. The published target price at 30,812.61 and Thursday's high at 30,827.50 are the first overhead references, 45.86 and 60.75 points above the settle.
30,939.50 is Pivot R1, the next ceiling, and the 31,035.70 stall projection of the 14-day %K line comes next. Target 1 at 30,860 sits above Thursday's high and beneath Pivot R1.
31,094.75 is Wednesday's three-month high and 31,112.25 Pivot R2; together they form the zone a Friday advance has to clear to resume the swing. Target 2 at 31,055 sits beneath the high and above the stall projection.
31,192.52 is one standard deviation resistance and 31,287.89 the cash index's 31,000 mapped level converted at the measured basis, the extended references, with Target 3 at 31,250 between them. Two standard deviations resistance at 31,368.88 and Pivot R3 at 31,397.00 sit beyond them, and the 52-week high on the December contract stands at 31,336.
3.2 Support, level by level
30,686.40 is the 14-3 day raw stochastic 80 percent threshold, 80.35 points beneath the settle.
30,654.75 is the Pivot Point, 30,652.40 the 5-day settlement average and 30,642.75 Wednesday's low; the three sit inside 12.00 points of each other and form the first support group. The 30,640 to 30,690 entry band sits on it.
30,482.00 is Pivot S1 and 30,482.22 the stochastic 70 percent threshold, the next pair, with the 30,470 stop beneath both. Thursday's low at 30,370.00 follows.
30,340.98 is one standard deviation support and 30,314.80 the 38.2 percent retracement from the four-week high, the first retracement group. The cash index's modeled gamma-flip level at 29,938 converts to 30,225.89 at the measured basis and sits between that group and Pivot S2; the source publishes that threshold in cash terms only.
30,197.25 is Pivot S2, 30,188.56 the 9-day average crossing and 30,164.62 two standard deviations support. Pivot S3 at 30,024.50 and three standard deviations support at 30,029.30 are the extended references.
1. Executive Summary
The December Nasdaq-100 contract settled at 30,766.75 on Thursday, up 2.00 points from Wednesday's 30,764.75, which is effectively unchanged. The completed session traded a 457.50 point band between 30,827.50 and 30,370.00 and settled at 86.7 percent of that range, 396.75 points above the low. The bar made a lower high and a lower low against Wednesday, so Thursday is a single lower-high, lower-low bar after Wednesday's 31,094.75 three-month high; its settle position reverses Wednesday's 27.0 percent close and shows the lower prices were rejected by the close. The Nasdaq-100 cash index closed at 30,478.86, up 8.57 points or 0.03 percent.
The session ran against a rate backdrop that was hostile on paper. The ten-year yield index closed at 5.16 percent after a 5.18 percent high that press commentary described as a 19-year high, crude rose 2.66 percent on Middle East supply risk, and press commentary quoted two regional Federal Reserve presidents leaning toward further tightening. Press commentary attributed a recovery in stocks to short covering after a report that United States and Iranian negotiators were exploring a phased arrangement to reopen the Strait of Hormuz, which the news feed carried at 12:15 PM ET. The positioning desk note recorded a large megacap platform company rising about 5 percent after its product launch event, with longer-dated call buying concentrated in that name. These items and the price path coincided; no time-stamped intraday price series was captured this run, so no causal ordering is asserted.
The structural question into Friday is whether a rejection candle at the 30,370 low can hold against a rate channel that has not turned. The composite multi-indicator read is 88 percent buy, published with strength good and direction weakening. The contract settled 114.35 points above its 5-day settlement average and 876.61 points above its 20-day, and it sits above the Pivot Point at 30,654.75 by 112.00 points. The desk note's proxy table places the cash index 21.14 points beneath its 30,500 primary gamma concentration and well above its modeled gamma-flip level at 29,938.
The Primary Setup is a long from a pullback into the 30,640 to 30,690 band around the Pivot Point at 30,654.75, the 5-day average and Wednesday's low, stopped at 30,470 beneath Pivot S1 at 30,482.00, with objectives at 30,860, 31,055 and an extended 31,250.
2.1 Intraday and Session Review
The completed Thursday session opened at 30,780.00, 15.25 points above Wednesday's 30,764.75 settle, marked a high of 30,827.50 and a low of 30,370.00, and settled at 30,766.75. No intraday series was captured this run, so the order in which those extremes were reached is not asserted and no path claim appears anywhere in this outlook. What the daily bar establishes is geometry: the settle finished 13.25 points beneath the open, 60.75 points beneath the high and 396.75 points above the low, which places it at 86.7 percent of the 457.50 point range. A small body near the top of the range with a long lower shadow is the shape of a rejection of lower prices.
The session extremes used here are the completed-session inputs behind the published pivot ladder, back-solved from the outer pivot pairs and verified against every rung; they were not read independently from a bar. Pivot R3 at 31,397.00 minus Pivot S3 at 30,024.50, divided by three, returns 457.50, and Pivot R2 at 31,112.25 minus Pivot S2 at 30,197.25, divided by two, returns the same 457.50. Three times the Pivot Point at 30,654.75 less the 30,766.75 settle gives a high plus low sum of 61,197.50, and the resulting pair of 30,827.50 and 30,370.00 reproduces all seven published rungs. The provider's own published daily record returns 30,780.00, 30,827.50, 30,370.00, 30,766.75 for the December contract, with preliminary volume of 658,722 contracts; Thursday's open interest is not yet published on that record. Both are surfaces of the same vendor, so they confirm internal consistency and do not authenticate the quote.
The provider's overview page, dated for the Friday session, showed a day open of 30,726.50, a day high of 30,765.25 and a day low of 30,708.50 at the time of reading. Those belong to the new Globex session that reopened at 6:00 PM ET and sit outside Thursday's range.
2.2 Daily Structure
Thursday's high at 30,827.50 sits 267.25 points beneath Wednesday's 31,094.75 high and its low at 30,370.00 sits 272.75 points beneath Wednesday's 30,642.75 low, so the bar is a lower high and lower low with a close near its high. The prior week, September 14 through September 18, spanned 29,993.25 at the high and 29,053.00 at the low, and the settle remains 773.50 points above that week's high, so the contract has not re-entered the range it left on Monday.
For the quarterly reference the 13-week extremes serve as the available proxy, because no prior-quarter high or low was captured this run. The 13-week and one-month high stands at 31,094.75, set on 09/23/26, and the 13-week low at 27,482.00. The settle sits 328.00 points beneath the 13-week high and 3,284.75 points above the 13-week low. The 52-week high on the December contract stands at 31,336.
2.3 4-Hour and Swing Structure
The settlement sequence from the 09/16 low reads 29,256.75, 29,743.00, 29,917.25, 30,784.75, 31,028.50, 30,764.75 and then 30,766.75. The swing from the 09/16 low of 29,053.00 to Wednesday's 31,094.75 high spanned 2,041.75 points; Thursday's low at 30,370.00 retraced 724.75 points of it, or 35.5 percent, and the settle retraces 328.00 points, or 16.1 percent. The published 38.2 percent retracement from the four-week high sits at 30,314.80, 55.20 points beneath Thursday's low, so the pullback stopped short of the first standard retracement line.
2.4 Moving Averages
The averages cited in this subsection were computed this run from the provider's daily settlement series for the December contract: the 5-day average stands at 30,652.40, the 9-day at 30,106.44, the 20-day at 29,890.14 and the 50-day at 29,632.93. The December contract was the deferred month until mid-September, so the 50-day window includes thinly traded sessions; the figure is cited with that caveat. The captured history covers 60 completed sessions, so no 100-day or 200-day average is cited.
The 30,766.75 settle sits 114.35 points above the 5-day average, 660.31 above the 9-day, 876.61 above the 20-day and 1,133.82 above the 50-day. The 5-day average sits 2.35 points beneath the Pivot Point at 30,654.75, which makes the 30,652 to 30,655 pair the first average-based support. The projection grid gives the 9-day crossing at 30,188.56, the 18-day crossing at 29,895.10 and the 40-day crossing at 29,861.09.
2.5 Oscillator and Trend Readings
The oscillator figures below are as published on the provider's technical page for the Friday session. Relative strength reads 67.26 on the 9-day, 62.66 on the 14-day, 59.22 on the 20-day, 55.16 on the 50-day and 54.64 on the 100-day. The published 14-day relative-strength grid places the 70 percent line at 31,553.01 and the 50 percent line at 29,953.93.
Stochastics remain elevated. The 9-day, 14-day and 20-day raw stochastic each read 83.94 percent, with the 14-day %K at 88.64 and %D at 91.47; the 50-day reads 90.92 percent. The published grid places the 14-3 day raw stochastic 80 percent threshold at 30,686.40 and the 70 percent threshold at 30,482.22, so the settle sits above the 80 percent line.
The directional system reads a developing uptrend on the short horizon. On the 9-day the directional index reads 25.76 with positive direction at 29.87 above negative direction at 17.14; on the 14-day 16.74 with positive at 26.83 over negative at 18.55; and on the 20-day 13.11 with positive at 24.63 over negative at 19.83. Historic volatility reads 18.24 percent on the 9-day, 16.38 percent on the 14-day and 16.01 percent on the 20-day.
The composite multi-indicator read published for Friday is 88 percent buy, with strength good and direction weakening. The composite indicator itself reads buy. The short-horizon and medium-horizon groups each average 100 percent buy, and the long-horizon group 33 percent buy, where the 50-100 day crossover reads sell.
2.6 Volatility and Expected Range
The published 14-day average true range stands at 470.86 points and the 14-day average daily range at 445.68 points; the 9-day figures are 470.04 and 492.94, and the 20-day figures 485.53 and 427.26. Thursday's realised 457.50 point range was 1.03 times the 14-day average daily range, an ordinary session for this contract.
A one-range projection from the 30,766.75 settle using the 14-day average true range of 470.86 points frames Friday between 30,295.89 and 31,237.61. The published standard-deviation bands are tighter: one deviation spans 30,340.98 to 31,192.52, two spans 30,164.62 to 31,368.88 and three spans 30,029.30 to 31,504.20.
4.1 Mag7 Earnings and AI Capex Cycle
The positioning desk note recorded that a large megacap platform company rose about 5 percent on Thursday after its product launch event, closing at 778 and up about 14 percent on the week, with longer-dated call buying concentrated in that name and single-stock hedging delta of plus 2 billion dollars. On the artificial-intelligence capital-spending side, a news-feed item stamped 04:04 PM ET reported a 12 billion dollar compute agreement between an artificial-intelligence developer and a content-delivery network company, and an item stamped 12:01 PM ET reported a five-year artificial-intelligence agreement between a European bank and a large cloud provider.
After the close, a large warehouse retailer reported fiscal fourth-quarter earnings of 6.75 dollars a share against a 6.53 estimate and revenue of 95.72 billion dollars against 94.92 billion, per a news-feed item stamped 04:18 PM ET, which the verified forward calendar lists as an after-close release on September 24, 2026.
4.2 Semiconductor Cycle and Tech Sector Rotation
No semiconductor-specific print or sector flow figure was captured this run, so no rotation inside technology is asserted. The only sector-level read available is the cash index outperforming the broad market by 0.05 percentage points on the day, a small margin. The next scheduled semiconductor catalyst on the verified forward calendar is a memory-chip maker's results at 04:30 PM ET on September 30, 2026.
4.3 Fed Policy and Real Yields (Duration Sensitivity)
The ten-year yield index closed at 5.16 percent, up 5 basis points, after a 5.09 to 5.18 range, and the thirty-year closed at 5.46 percent. The seven-year note auction stopped at a 5.085 percent high yield with a 2.420 bid-to-cover against 2.500 previously, per the news-feed calendar and unconfirmed. Press commentary quoted the New York Federal Reserve president as saying the central bank has a lot of work to do to contain inflation and the Philadelphia Federal Reserve president as saying some modest further tightening may be warranted, and the desk note cited fed funds futures pricing a roughly 71 percent likelihood of an October increase against roughly 55 percent a week earlier. Long-duration growth equities are the most sensitive to that channel, and the contract finishing flat against it is the relative-strength signal of the day.
4.4 Geopolitical Backdrop
The Middle East carried both escalation and de-escalation reporting. A press report carried on the news feed at 12:15 PM ET said the United States and Iran were discussing a phased deal to reopen the Strait of Hormuz, and press commentary tied short covering in stocks to that report. The news feed carried claims by Yemen's Houthis of attacks at Yanbu and in Riyadh at 03:02 PM and 03:03 PM ET.
After the close, the Chinese president described a new joint trade arrangement with the United States as good news and said the two countries could continue artificial-intelligence dialogue, per news-feed items stamped 04:13 PM through 04:24 PM ET, a constructive item for the technology complex.
4.5 Cross-Asset and Volatility
The S&P 500 cash index closed at 7,704.13, down 1.90 points, and the Nasdaq-100 cash index at 30,478.86, up 8.57 points. The volatility index closed at 15.67, up 0.49 points, and the desk note recorded the volatility-of-volatility index up 2 points at 90.57. The dollar index rose 0.19 percent to 101.29. Crude settled at 94.61, up 2.66 percent, and gold at 4,298.0, down 0.47 percent. The basis measured this session is the 30,766.75 futures settle less the 30,478.86 cash close, 287.89 points.
4.6 Institutional Positioning
The positioning report as of September 15, 2026 remains the latest captured. Leveraged funds held 52,680 long against 59,067 short, a net short of 6,387, after covering 20,479 shorts on the week. Asset managers held 105,199 long against 38,388 short, a net long of 66,811, and dealers held 52,437 long against 131,666 short. Open interest on the December contract stood at 274,125 on the latest published row for 09/23, against 285,475 on 09/22. The report predates Thursday by seven sessions and describes a starting condition; the current book was not captured.
5. QQQ Options Flow Context (Proxy)
The technology exchange-traded fund and the cash index are the flow surfaces for this contract. Levels from them are cash or fund values and are translated into futures terms only with the measured basis of 287.89 points stated.
The desk note's reference price column is the prior session's close, and this was verified: the cash index reference of 30,470 matches Wednesday's 30,470.29 cash close, and the fund's reference of 741 matches the provider's 741.21 close for Wednesday. For the fund the model reads a modeled volatility threshold at 739, a modeled gamma-flip level at 739, a primary gamma concentration at 740, a call-side ceiling at 760 and a put-side base at 736, with gamma tilt 0.928 and gamma notional 12.158 million dollars. The fund closed at 741.10 on the provider's daily record, 1.10 above the primary gamma concentration and 2.10 above the two modeled thresholds.
For the cash index the model reads a modeled volatility threshold at 29,460, a modeled gamma-flip level at 29,938 and a primary gamma concentration at 30,500, with gamma tilt 1.606 and gamma notional 14.591 million dollars. The published call-side and put-side fields for the cash index, 29,475 and 29,500, both sit beneath the cash close and invert their usual order, so they are recorded and left out of the level structure. The mapped key levels are 30,500, 30,000, 29,475 and 31,000, and the mapped confluence levels are 30,257, 30,013, 30,836 and 31,232. The cash close of 30,478.86 sits 21.14 points beneath 30,500 and 540.86 points above the modeled gamma-flip level. The source publishes these thresholds in cash terms only; the futures equivalents in the level lists use the measured basis.
The fund's positioning console, updated on Thursday, carries a different model and a different sign. It showed a current price of 740.50 against a previous close of 741.17, call gamma of minus 832 million dollars, put gamma of minus 3.7 billion dollars and next-expiry gamma at 17.99 percent of the total. That console's aggregate reads negative while the desk table's gamma notional reads positive; the two are recorded side by side and left unreconciled, and no level in the level lists rests on either sign. The console's high-volatility-point and low-volatility-point fields, published as 737 and 520, are excluded as low-confidence because that pair of fields is known to be unreliable.
On flow, the desk note recorded index-level hedging delta of minus 12 billion dollars on the day, mostly in same-day expiries, following minus 20 billion on Wednesday, and characterised it as tactical hedging with little longer-dated demand. These are the desk note's characterisations and are carried as such; no timestamp-aligned flow series was captured.
6.1 Night Session (6:00 PM ET Thursday to 3:00 AM ET Friday, Globex and Asia)
The Globex reopen carries the after-close items: the warehouse retailer's results at 04:18 PM ET, the compute agreement at 04:04 PM ET and the Chinese president's trade and artificial-intelligence remarks from 04:13 PM ET. The reopened session was trading between 30,708.50 and 30,765.25 at the time of reading, above the 30,654.75 pivot. The captured news-feed calendar carries no Asian release for the Thursday evening window. Bias constructive above 30,654.75, expected Globex band roughly 30,600 to 30,900.
6.2 London Session (3:00 AM to 8:00 AM ET Friday)
The European morning carries euro-area money-supply data at 04:00 AM ET and remarks by the New York Federal Reserve president at 05:15 AM ET, both per the news-feed calendar and unconfirmed. European yields are the main transmission. Bias neutral to constructive above the 30,642.75 to 30,654.75 group, expected band roughly 30,550 to 30,950.
6.3 Morning Session (9:30 AM to 12:00 PM ET Friday, RTH Open)
The United States morning opens with the advance durable goods report at 08:30 AM ET, per the verified forward calendar, with headline orders forecast at minus 0.3 percent and core at plus 0.6 percent, per the news-feed calendar and unconfirmed. The final University of Michigan survey prints at 10:00 AM ET, per the news-feed calendar and unconfirmed. The cash open at 09:30 AM ET sets the session's first directional test against the 30,787.89 futures equivalent of the 30,500 cash concentration. A hold above 30,654.75 keeps the 30,939.50 Pivot R1 in reach; a loss of 30,482.00 returns the contract toward Thursday's low. Expected band roughly 30,450 to 31,000.
6.4 Afternoon Session (12:00 PM to 4:00 PM ET Friday)
The afternoon carries the Cleveland Federal Reserve president at 02:00 PM ET, per the news-feed calendar and unconfirmed. The cash close precedes a weekend with an open Middle East negotiation, which the review reads as an argument for position squaring into the close. Expected band roughly 30,500 to 30,950.
6.5 Night Session Forward (6:00 PM ET Friday)
Globex does not reopen on Friday evening; the next session opens at 6:00 PM ET on Sunday, so two days of headline exposure separate Friday's close from the reopen. Gap levels both ways: a constructive weekend points to the 31,094.75 to 31,112.25 zone, and a risk-off weekend points to the 30,314.80 retracement and the 30,197.25 Pivot S2. The following week carries the personal income and outlays report at 08:30 AM ET on September 30, 2026, per the verified forward calendar. A memory-chip maker reports results at 04:30 PM ET on September 30, 2026, per the verified forward calendar. The employment report follows at 08:30 AM ET on October 2, 2026, per the verified forward calendar.
6.6 Expected Range (Friday Full Session)
Low-range scenario: 30,600 to 30,940
Mid-range scenario (most likely): 30,480 to 31,040
High-range scenario: 30,315 to 31,195
6.7 Most Likely Path
The most probable path holds the Globex session above the 30,654.75 pivot, followed by a test of the 30,812.61 to 30,827.50 references after the United States data. In this review's analyst judgment a settle between the pivot and Pivot R1 at 30,939.50 is more likely than a move through the 31,094.75 high on Friday, because the rate channel has not turned and the weekend argues for squaring; that weighting is judgment and carries no measured frequency. The alternative that would invalidate this reading is a settle beneath Pivot S1 at 30,482.00, which would negate Thursday's rejection candle.
7. Friday Economic Calendar
The captured news-feed calendar carries no Asian release for the Thursday evening window. The European morning carries euro-area money-supply growth at 04:00 AM ET, forecast 3.5 percent against a prior 3.4 percent, per the news-feed calendar and unconfirmed, and remarks by the New York Federal Reserve president at 05:15 AM ET, per the news-feed calendar and unconfirmed.
The United States morning carries the advance durable goods report at 08:30 AM ET, per the verified forward calendar, with headline orders forecast at minus 0.3 percent against a prior 1.1 percent and core orders forecast at plus 0.6 percent against a prior 0.4 percent, per the news-feed calendar and unconfirmed. The final University of Michigan survey prints at 10:00 AM ET, with sentiment forecast at 47.5 against 47.8 and five-year inflation expectations forecast at 3.4 percent, per the news-feed calendar and unconfirmed. In the afternoon a European Central Bank speaker and the Cleveland Federal Reserve president both appear at 02:00 PM ET, per the news-feed calendar and unconfirmed.
The single first-order event for the contract on Friday is the durable goods report at 08:30 AM ET on September 25, 2026, per the verified forward calendar, read through its effect on the ten-year yield. No structural index expiry falls on Friday; the provider lists the December contract's expiration as 12/18/26.
8. Primary Trade Setup
Direction: Long
Rationale: Thursday's bar rejected a 457.50 point test lower and settled at 86.7 percent of its range, above the Pivot Point at 30,654.75 and the 5-day average, with the composite at 88 percent buy, the 9-day directional reading positive and the contract finishing flat against a 5.18 percent ten-year high; a pullback into the pivot group offers a long with a defined risk point beneath Pivot S1.
Entry Zone: 30,640 to 30,690
Stop Loss: 30,470 (beneath Pivot S1 at 30,482.00 and the stochastic 70 percent threshold at 30,482.22)
Target 1 (T1): 30,860 (above Thursday's 30,827.50 high and beneath Pivot R1 at 30,939.50)
Target 2 (T2): 31,055 (beneath Wednesday's 31,094.75 high and above the 31,035.70 stall projection of the 14-day %K line)
Target 3 (T3, extended): 31,250 (above one standard deviation resistance at 31,192.52 and beneath the 31,287.89 futures equivalent of the 31,000 cash level)
Risk-to-Reward: Approximately 1:1 to T1, 1:2 to T2, 1:3 to T3, measured from the 30,665 midpoint of the entry zone against the 30,470 stop, which is 195 points of risk.
Invalidation: A settle beneath Thursday's 30,370.00 low negates the thesis outright, because it would erase the rejection. Short of that, two consecutive 30-minute closes beneath Pivot S1 at 30,482.00 remove the edge before the stop is reached.
Macro override: A further jump in yields on a strong durable goods print or a hawkish Federal Reserve speaker, with the ten-year index back above 5.18 percent, invalidates the setup in real time, as would a Strait escalation that sends crude sharply higher into the weekend.
Alternate setup: the session review states none.
Sources and methodology
This outlook is built from our session review of the December E-mini Nasdaq-100 contract, NQZ26, prepared after Thursday's close on September 24, 2026 for the Friday, September 25 session. The contract was verified before any level was used: the daily chart legend read 30,722.00 with a stated change of minus 44.75, which returns 30,766.75, equal to the provider's published previous close of 30,766.75, and the chart's new-session open of 30,726.50 and high of 30,765.25 equal the provider's day open and day high. Chart and provider are therefore on the same December contract. The day high, day low and open on the provider's overview page belong to the new Globex session dated September 25 and are never presented as Thursday's range. Thursday's extremes are the completed-session inputs behind the published pivot ladder, back-solved from the outer pivot pairs, verified against all seven rungs and reproduced by the provider's daily record, a second surface of the same vendor that confirms internal consistency. No intraday series was captured, so no sequence within the session is asserted.
The moving averages were computed from the provider's daily settlement series, which also supplies the seven closes charted above and the preliminary volume; the oscillator readings are cited as published for the Friday session. Cash and fund levels are converted to futures only at the measured basis of 287.89, because the source publishes no futures column for the cash index. The desk note's reference column was verified as the prior session's close. The fund console and the desk table carry opposite gamma signs from different models and are recorded side by side; the console's volatility-point fields and the inverted cash-index call-side and put-side fields are excluded from the level structure. The 52-week high cited is 31,336 on the December contract. Every catalyst whose release time had passed at the time of writing is recorded as completed with its result. Scenario ranges, session bands and the path weighting are analyst judgment and carry no calibration. Items marked unconfirmed come from the news-feed calendar or the desk note and were not reconciled to the verified forward calendar.
Thursday’s outlook for this contract is here and the broad-index outlook for the same date is here. Outlooks for ES, NQ, GC and CL are collected on the market outlook page, and our forward trading record is on the performance statement.