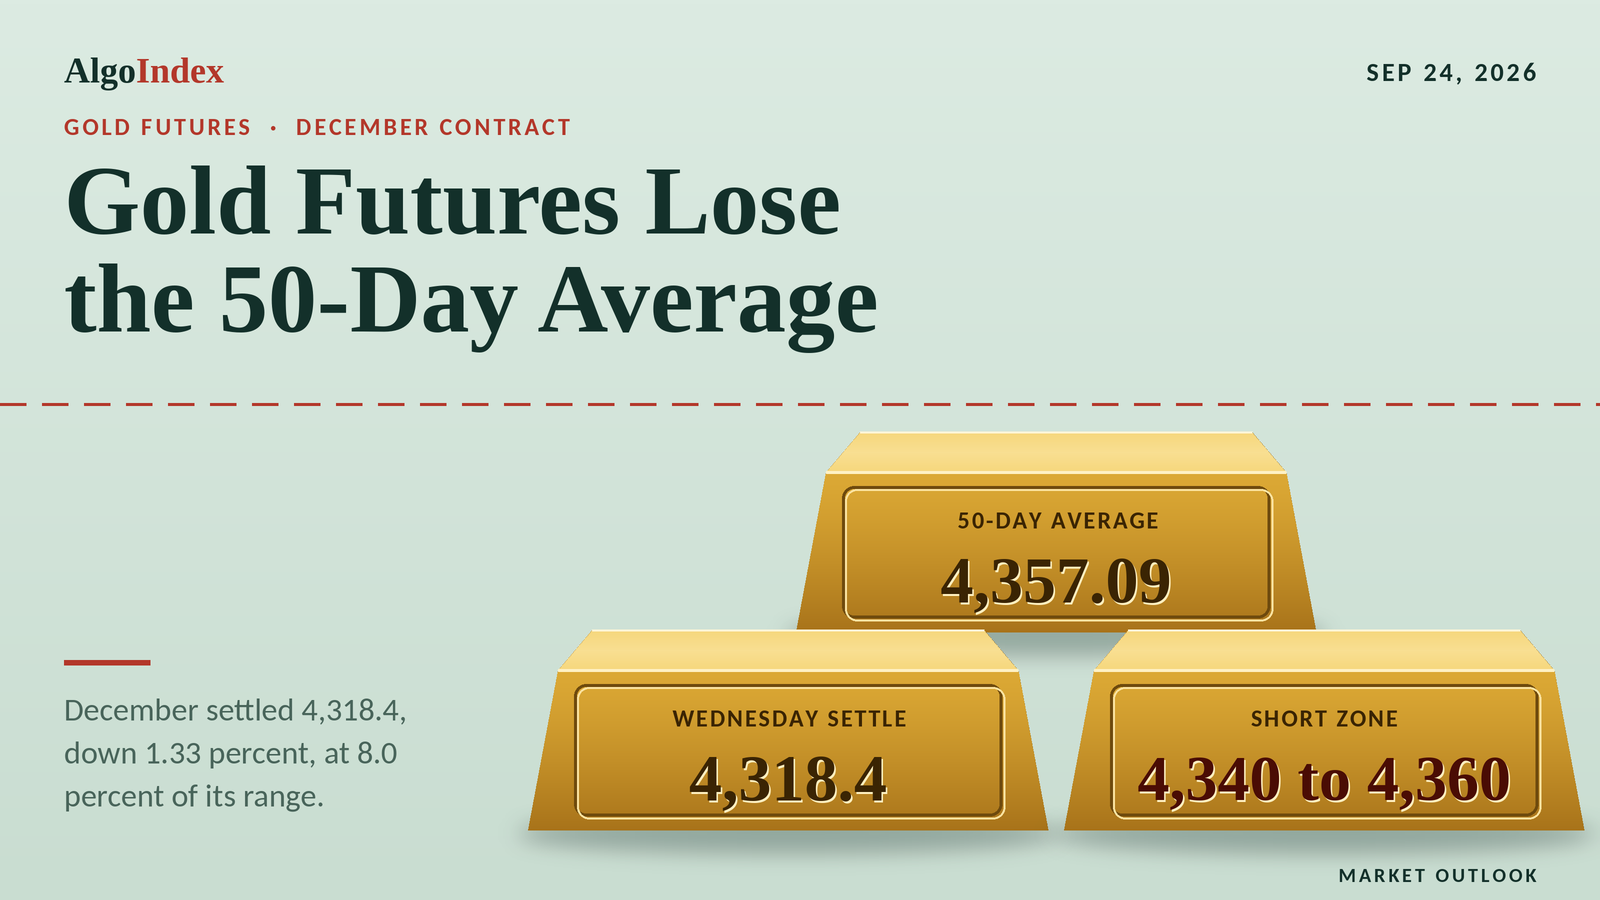
At 4,310.7 on Wednesday, December gold printed the low of its session. The settlement came in just 7.7 points above it. The contract opened at 4,394.7, marked a high of 4,407.5 and settled at 4,318.4, down 58.0 points or 1.33 percent from Tuesday's 4,376.4. That was the lowest settle since 08/06/26, when the contract settled at 4,299.6. It was also the third consecutive lower close. The settle sat at 8.0 percent of a 96.8 point range, the weakest close by position since 03/04/26, when the contract settled at 6.0 percent of its range.
Rates did the damage. The ten-year yield closed at 5.11 percent after a 5.14 percent intraday high, up 15 basis points, and press commentary described the move as a 19-year high. The dollar index rose 0.50 percent to 101.10. The United States flash manufacturing survey printed 57.0 against a 53.7 forecast at 09:45 AM ET, per the news-feed record and unconfirmed against an official calendar. Press commentary put the market-implied probability of an October rate increase at 69 percent, up from 53 percent on Tuesday. Those headlines and the decline coincided. No time-stamped intraday price series was captured, so no causal ordering is asserted here. The settle now sits beneath every settlement moving average from the 5-day through the 200-day. Thursday's primary setup is a short from 4,340 to 4,360 on a retracement toward the 4,345.5 pivot.
December gold settled at 4,318.4, 38.69 points beneath the 50-day settlement average at 4,357.09 that Tuesday's settle held above. The Pivot Point for Thursday is 4,345.5, 27.1 points over the settle, and the first ceiling is the stochastic threshold at 4,330.3. The first supports are the 4,310.7 session low and the 4,296.1 to 4,298.1 pair. The one-month low at 4,273.3 is the last structural reference above the 13-week range. The 14-day directional index reads 14.66, negative 17.77 over positive 13.80. No trend, a downward lean. The primary setup is a short from 4,340 to 4,360, stop 4,390, targets 4,310, 4,270 and 4,230. Thursday's first-order events are weekly jobless claims at 08:30 AM ET and a seven-year note auction at 01:00 PM ET, per the news-feed calendar and unconfirmed.
Wednesday's long, scored against the bar
Our Wednesday outlook set a long from 4,358 to 4,374, stop 4,326, with targets at 4,406, 4,446 and 4,486. Wednesday's range ran from 4,310.7 to 4,407.5. That covered the whole entry band. The session opened at 4,394.7, 20.7 points above the top of the band, and settled at 4,318.4, 39.6 points beneath its bottom, so the band traded during the session. The stop level traded too. The 4,310.7 low went 15.3 points through 4,326. The first target traded as well, with the 4,407.5 high sitting 1.5 points above 4,406. The second and third targets never came close; the high stopped 38.5 points short of 4,446.
Sequence is the gap in that account. No intraday series was captured this run. Nothing here says whether the 4,407.5 high printed before or after the band traded, or whether the first target printed before the stop level. The settlement needs no sequence. At 4,318.4 it finished 7.6 points beneath the stop and 9.2 points beneath 4,327.6, the settle line the card named as its invalidation. The thesis was negated at the close. The settle also finished 34.9 points beneath the 4,353.3 50-day reference the card leaned on.
Those extremes carry a provenance note. They are the completed-session inputs behind the published pivot ladder, back-solved from its outer pairs. Pivot R3 at 4,477.2 less Pivot S3 at 4,186.8, divided by three, returns 96.8. Pivot R2 at 4,442.3 less Pivot S2 at 4,248.7, divided by two, returns the same 96.8. Three times the unrounded Pivot Point of 4,345.53, published as 4,345.5, less the 4,318.4 settle gives a high-plus-low sum of 8,718.2. The pair of 4,407.5 and 4,310.7 then reproduces all seven published rungs. The provider's own daily record returns 4,394.7, 4,407.5, 4,310.7 and 4,318.4 on 143,873 contracts. Both are surfaces of the same vendor, so they confirm internal consistency only.
The bar itself is plain. The settle finished 76.3 points beneath the open and 89.1 points beneath the high, so the body is long and dark relative to the range. Wednesday's low undercut Tuesday's 4,327.6 low by 16.9 points. Its high sat 6.6 points beneath Tuesday's 4,414.1. Lower high, lower low. That is a clean continuation shape on the daily frame. The size of the day was ordinary: 96.8 points is 1.03 times the 14-day average daily range of 94.0. The close is what stood out.
Beneath every average, above the one-month low
Last week, September 14 through September 18, spanned 4,439.8 to 4,273.3. The settle is still inside that range, 45.1 points above its low. The 13-week extremes stand in for the quarter, because no prior-quarter high or low was captured this run. The 13-week and one-month high is 4,755.0, set on 08/25/26, and the 13-week low is 4,015.6, set on 06/30/26. The settle sits 302.8 points above that low. Further out, the 52-week high of 5,781.8, set on 01/29/26, stands 1,463.4 points or 33.89 percent above the settle. The 52-week low of 3,916.0 sits 402.4 points or 9.32 percent beneath it. Both distances are measured from the settle.
Look at the settlements in order. The published record reads 4,332.8 on 09/15, then 4,387.5, 4,399.7 and 4,424.9 on 09/18, then 4,383.9, 4,376.4 and 4,318.4. The three sessions since 09/18 removed 106.5 points, or 2.41 percent. Wednesday alone delivered 58.0 of them, more than half. The advance from the 09/16 low has now failed: the contract rallied from 4,273.3 into the 4,439.8 high of 09/18 and has given back 121.4 points of that 166.5 point climb. That is 72.9 percent, measured from the high to Wednesday's settle.
Two references now sit almost on top of each other beneath the market. The retracement grid for Thursday places the 38.2 percent retracement from the 13-week low at 4,298.1, 20.3 points beneath the settle. The published target price for Thursday is 4,296.1. Two points separate them. The 50 percent retracement of the 13-week range sits overhead at 4,385.3, so the settle sits between the two lines.
Every average is overhead. The figures come from the provider's published daily settlement series, computed this run. Its technical page is dated for Thursday and substitutes the reopened-session last price for a close. On settlements through Wednesday the 5-day average stands at 4,380.66, the 20-day at 4,442.38, the 50-day at 4,357.09, the 100-day at 4,400.25 and the 200-day at 4,648.37. The distances are wide. The settle sits 62.26 points beneath the 5-day, 123.98 beneath the 20-day, 38.69 beneath the 50-day, 81.85 beneath the 100-day and 329.97 beneath the 200-day. The 50-day is the nearest. It is also the one Wednesday took away. Computed through Tuesday it stood at 4,353.28, beneath Tuesday's 4,376.4 settle. The projection grid puts Thursday's crossing prices at 4,371.9 for the 9-day, 4,411.8 for the 18-day and 4,426.5 for the 40-day, all overhead.
Momentum leans soft. The oscillator figures are cited as published on the provider's technical page for Thursday, which substitutes the reopened-session price for a close. Relative strength reads 37.14 on the 9-day, 42.25 on the 14-day, 45.33 on the 20-day, 47.73 on the 50-day and 49.09 on the 100-day. Every horizon sits beneath 50, and the shortest sits lowest. The published 14-day relative-strength grid places the 50 percent line at 4,412.4 and the 30 percent line at 4,107.1. Stochastics are more stretched. The 9-day raw stochastic reads 31.47 percent, the 14-day 19.81 percent and the 20-day 12.35 percent, with the 50-day at 41.67 percent. The grid places the 14-3 day raw stochastic 20 percent threshold at 4,330.3 and its 30 percent threshold at 4,358.9. The settle sits beneath the 20 percent line.
Trend strength barely registers. The directional index reads 18.69 on the 9-day, with positive direction 11.14 and negative direction 17.28. The 14-day reads 14.66, with 13.80 and 17.77, and the 20-day 12.99, with 15.51 and 18.21. Negative direction sits above positive on every horizon published. Every index reading is beneath 20. The market leans lower without trending. The composite multi-indicator read published for Thursday is 24 percent sell. A week ago it read 16 percent sell. A month ago it read 72 percent buy.
Volatility is ordinary. The published 14-day average true range stands at 97.0 points and the 14-day average daily range at 94.0. The 9-day figures are 91.1 and 83.4, and the 20-day figures 100.1 and 102.7. Historic volatility reads 13.02 percent on the 9-day and 12.73 percent on the 14-day, rising to 19.24 percent on the 20-day. One range from the 4,318.4 settle, using the 14-day average true range of 97.0 points, frames Thursday between 4,221.4 and 4,415.4. The published standard-deviation bands are tighter. One deviation spans 4,274.3 to 4,362.5, two span 4,256.0 to 4,380.8 and three span 4,242.0 to 4,394.8.
Five percent yields outweighed the Strait
Start with the rate channel. The ten-year nominal yield closed at 5.11 percent after a 4.98 to 5.14 range, up 15 basis points from Tuesday's 4.96 percent. The desk note described the level as the highest since July 2007. The dollar index closed at 101.10, up 0.50 points or 0.50 percent, after a 100.54 to 101.23 range, and press commentary called it a 1.75-month high. For gold the level matters as much as the change. A ten-year yield above 5 percent is a heavy carrying cost for a metal that pays nothing.
How much of that move was real yield is unknown. No inflation-protected yield or breakeven series was captured this run, so the split between real yields and inflation expectations is not measured here. Press commentary attributed part of the yield move to firmer crude lifting inflation expectations. That would place some of it in the breakeven component. The attribution is carried as commentary, and it is not a measurement.
The auction calendar added a second signal. The five-year note auction at 01:00 PM ET stopped at a 5.033 percent high yield, a tail of 3.1 basis points above the when-issued level of 5.002 percent. The bid-to-cover came in at 2.21 against a prior 2.37. Both figures are per the news-feed record and unconfirmed against an official calendar.
Policy commentary pushed the same way. The Federal Reserve governor's housing remarks were scheduled at 10:05 AM ET, per the verified forward calendar. Press commentary quoted him as saying that further policy adjustments are likely to be needed to ensure inflation comes down to target in a timely fashion. Rate pricing moved with it. The market-implied probability of a rate increase at the October policy meeting rose to 69 percent from 53 percent on Tuesday, by press commentary. The projections published on September 16 showed 12 of 18 officials expecting one more quarter-point increase this year. Four expected two. Two expected none. That breakdown comes from a news-feed item stamped 02:00 PM ET that day. The next policy meeting is scheduled for October 28 at 02:00 PM ET, per the news-feed calendar and unconfirmed.
The flash surveys supplied the data side of that repricing. United States manufacturing printed 57.0 against a 53.7 forecast and a 53.9 prior. Services printed 58.7 against 55.8. The composite came in at 58.4 against 55.3 and a 56.0 prior. All three landed at 09:45 AM ET, per the news-feed record and unconfirmed against an official calendar. Press commentary described the manufacturing reading as the fastest expansion in four and a quarter years.
Then came the Strait. Press accounts carried remarks by the United States Secretary of State that Iran fired at commercial vessels in the Strait of Hormuz and that talks were being impeded. Brent crude settled at 103.08, up 3.86 percent, per a news-feed item stamped 02:40 PM ET. That backdrop would ordinarily support gold. Gold fell anyway. The market treated the escalation as an inflation shock, and the haven bid it might have produced was overwhelmed by the rates channel. That is the most important relationship in Wednesday's session. A news-feed headline stamped 07:45 PM ET described the Iranian president sending a defiant message to the United States over potential talks.
China supplied two threads. A news-feed item stamped 04:10 PM ET reported that China had taken possession of sensitive military aircraft parts diverted to Hong Kong. Then the calendar. The Chinese leader was scheduled to arrive at the White House at 6:00 PM ET, per the news-feed calendar and unconfirmed. After the settle came the trade news. A news-feed report stamped 08:15 PM ET said the United States and China had extended their trade truce through January 10. On the demand side, a bank metals note carried on the news feed, without a captured timestamp, reported Chinese gold imports up 39.3 percent year on year to 141.7 tonnes in August. Year-to-date imports reached a record 1,141.2 tonnes, up 72.2 percent. That is the structural demand argument. It works on a horizon of months, and Thursday is one session.
No central bank purchase figure, reference-rate fixing or exchange-traded fund holdings series was captured this run. None is asserted. The bullion exchange-traded fund proxy closed at 392.88, down 1.80 percent from 400.07 on the provider's daily record. That is a larger percentage decline than the futures contract's 1.33 percent. The gap is a timing and basis artefact between an equity-hours close and a futures settlement. It is not read as a flow signal.
Crude was the origin of the day's cross-asset move. The November WTI contract settled at 92.16, up 1.81 percent, with Brent at 103.08. Equities fell. The S&P 500 cash index closed at 7,706.03, down 0.75 percent, and the Nasdaq-100 cash index at 30,470.29, down 0.85 percent. The volatility index closed at 15.18, up 6.83 percent. Silver was reported by a news-feed headline stamped 02:30 PM ET as moving toward 64 dollar support on hawkish Federal Reserve commentary. Higher crude, higher yields, a firmer dollar and lower equities leave gold with the least support from any direction. Its inflation-hedge argument is offset by the yield it forgoes. Its haven argument is offset by the dollar. Its risk-appetite channel is absent.
Positioning explains how far a rates move can travel in gold. The report as of September 15, 2026 remains the latest captured. Managed money held 142,394 contracts long against 9,278 short, a net long of 133,116, after reducing longs by 3,410 and shorts by 1,554 on the week. Commercials held 56,417 long against 318,138 short, a net short of 261,721. Swap dealers held 14,690 long against 248,350 short. Open interest on the December contract stood at 315,425 at the latest published reading. The book is heavily one-sided. That is the condition in which a macro shock to the carry cost produces long liquidation, the mechanical reason a rates move can travel further in gold than the rates move alone would suggest. The report predates Wednesday by six sessions, so it describes a starting condition.
The bullion fund's options book is read qualitatively only. It tracks bullion with a fee drag and at a ratio that has no clean basis to the futures contract, so no level from it becomes a futures price. The positioning console for the fund, updated on Wednesday, showed a current price of 393.19 against a previous close of 400.07, a daily change of minus 1.72 percent, on 6,466,737 shares. Call gamma read minus 287 million dollars and put gamma 174 million dollars. The book sits in longer tenors. Next-expiry gamma was 2.75 percent of the total, and the largest gamma expiry is dated January 15, 2027. The console's high-volatility-point and low-volatility-point fields, published as 449 and 314, are excluded as low-confidence. With so little gamma in the next expiry, short-dated hedging flows are unlikely to dominate Thursday's price action in the fund. No gamma-derived level is used for the futures contract.
The trade map for Thursday
The setup follows the rate channel. The contract settled beneath every settlement average computed this run, including the 50-day that Tuesday's settle held above. It settled at 8.0 percent of a normal-sized range, on a day when the ten-year yield closed above 5 percent and the dollar rose 0.50 percent. Every directional horizon has negative direction above positive direction. A retracement into the pivot therefore offers a short at better prices than the close. The entry zone runs 4,340 to 4,360. It brackets the 4,345.5 Pivot Point and sits beneath the 50-day at 4,357.09. The stop at 4,390 sits above Pivot R1 at 4,380.4 and two standard deviations resistance at 4,380.8, and beneath three standard deviations resistance at 4,394.8. From the entry midpoint the stop sits 40 points away, against a 14-day average true range of 97.0 points.
The reopen sets the first test. The Globex session that reopened at 6:00 PM ET opened at 4,324.4. At the time of reading it was trading between 4,320.2 and 4,328.8. Two diplomatic items frame it. The Chinese leader's arrival at the White House was set for 6:00 PM ET, per the news-feed calendar and unconfirmed. A report stamped 08:15 PM ET said the United States and China extended their trade truce through January 10. Japanese flash purchasing-manager surveys print at 08:30 PM ET, prior manufacturing 54.9 and composite 53.5. Australian labour data follows at 09:30 PM ET, with the unemployment rate forecast at 4.5 percent and the employment change forecast at 20,000 against a prior decline of 15,800. Both are per the news-feed calendar and unconfirmed. Asian physical demand at lower prices is the main support argument overnight. The night session, 6:00 PM ET Wednesday to 3:00 AM ET Thursday, carries a bias of neutral to slightly lower beneath the 4,345.5 pivot, with an expected Globex band of roughly 4,295 to 4,350.
London brings the policy decisions. Its window runs from 3:00 AM to 8:00 AM ET. French confidence surveys print at 02:45 AM ET. The Swiss and Swedish decisions land at 03:30 AM ET, the Swiss forecast at zero and the Swedish at 1.75 percent. The Norwegian decision follows at 04:00 AM ET with a forecast of 4.5 percent against a current 4.25 percent. Norway is the one gold watches. The German business climate survey prints at the same time, forecast 89 against a prior 88.8. A Federal Reserve speaker appears at 04:10 AM ET and a Bank of England speaker at 05:30 AM ET. All of it is per the news-feed calendar and unconfirmed. A Norwegian increase would add to the global tightening narrative that pressured gold on Wednesday. Bias lower while the 4,345.5 pivot caps. Expected band roughly 4,285 to 4,355.
Then the United States morning, 9:30 AM to 12:00 PM ET, and the data that matters most. Weekly jobless claims print at 08:30 AM ET with a consensus of 200,000 against a prior 196,000, per the news-feed calendar and unconfirmed. The second-quarter international transactions release lands at the same time, per the verified forward calendar. Federal Reserve speakers appear at 08:30 AM, 08:50 AM and 10:10 AM ET, per the news-feed calendar and unconfirmed. New home sales print at 10:00 AM ET, per the verified forward calendar. Gold reads claims most directly. A low print supports the rate-increase repricing and the dollar. A high one would give the metal its first relief from the rates channel. A tentative Treasury liquidity buyback is listed for 11:00 AM ET, per the news-feed calendar and unconfirmed. Expected band roughly 4,270 to 4,360, with the 4,296.1 to 4,298.1 pair as the first test.
The afternoon, 12:00 PM to 4:00 PM ET, carries the seven-year note auction at 01:00 PM ET. The prior auction stopped at a 4.512 percent high yield, per the news-feed calendar and unconfirmed. After Wednesday's 3.1 basis point tail on the five-year, it is the most direct read on demand for duration. A dealer financing survey is published at 02:00 PM ET, per the verified forward calendar. Expected band roughly 4,275 to 4,355.
Residual bias into the 6:00 PM ET Thursday reopen depends on whether the one-month low at 4,273.3 held. The forward anchor is the durable goods report at 08:30 AM ET on September 25, 2026, per the verified forward calendar. The final consumer sentiment reading comes at 10:00 AM ET that Friday. Its one-year inflation expectation carries a prior of 4.6 percent, per the news-feed calendar and unconfirmed. Further out sit the personal income and outlays report at 08:30 AM ET on September 30 and the employment report at 08:30 AM ET on October 2, both per the verified forward calendar. The state visit runs all day Thursday, per the news-feed calendar and unconfirmed. No structural gold expiry falls on Thursday on the captured calendars.
The first-order event for gold on Thursday is the pairing of the 08:30 AM ET claims release and the 01:00 PM ET seven-year auction, because both act through the rate channel that drove Wednesday, per the news-feed calendar and unconfirmed. Three scenario bands frame the full session. The low-range case runs 4,290 to 4,350, the mid-range case, the most likely, 4,265 to 4,365, and the high-range case 4,230 to 4,395.
The most probable path holds the reopened session beneath the 4,345.5 pivot through Asia and Europe. The trade truce extension offers modest support, and a Norwegian rate decision leans the other way. The claims release at 08:30 AM ET is the first United States test. In analyst judgment, the heaviest-weighted path has the contract test the 4,296.1 to 4,298.1 pair and then the 4,273.3 to 4,283.6 group during the United States session, without a settle beneath 4,273.3. Why no breakdown? The managed-money book is long, and the directional index is too weak to argue for a trending day. A settle above the 4,380.4 to 4,380.8 pair would invalidate that reading and reverse Wednesday's shape.
Gold fell 1.33 percent on a day built for a haven bid, and Thursday's short asks the rate channel to keep winning that argument.
The complete data picture
Every number behind Thursday’s plan, charted first, then the full level lists, then the complete numeric reference underneath.
Full numeric reference, every remaining figure from the session review
Carried below in the review's own order: the executive summary from section 1, sections 2.1 to 2.6, the level notes behind sections 3.1 and 3.2, sections 4.1 to 4.6, the fund options context from section 5, the session-by-session forecast from section 6, the Thursday calendar from section 7 and the primary setup from section 8.
Level notes (3.1 Resistance and 3.2 Support)
4,330.3, the 14-3 day raw stochastic 20 percent threshold, is the first overhead reference, 11.9 points above the settle, followed by the Pivot Point at 4,345.5 and the 50-day settlement average at 4,357.09. The 4,345.5 to 4,358.9 band, which also holds the stochastic 30 percent threshold, separates a corrective Thursday from a continuation one.
4,362.5, one standard deviation resistance, and 4,371.9, the 9-day average crossing price, lead to the 4,380.4 to 4,380.8 pair of Pivot R1 and two standard deviations resistance, the level a relief move would have to clear to change the daily shape. The 5-day settlement average at 4,380.66 sits inside that pair.
4,385.3, the 50 percent retracement of the 13-week range, three standard deviations resistance at 4,394.8 and Wednesday's session high at 4,407.5 form the next group, with the 18-day crossing at 4,411.8 and the relative-strength 50 percent line at 4,412.4 immediately above it. Pivot R2 at 4,442.3 and Pivot R3 at 4,477.2 are extended references.
4,310.7, the session low, is the first support, 7.7 points beneath the settle. The 38.2 percent retracement from the 13-week low at 4,298.1 and the published target price at 4,296.1 form a two point pair beneath it, and that pair is where a continuation is first tested.
4,283.6, Pivot S1, one standard deviation support at 4,274.3 and the one-month low at 4,273.3 sit within 10.3 points of each other and form the densest support group in the instrument. A settle beneath 4,273.3 would take out the low of the 09/16 session and remove the last structural reference above the 13-week range.
4,256.0, two standard deviations support, Pivot S2 at 4,248.7 and three standard deviations support at 4,242.0 follow, then Pivot S3 at 4,186.8. The relative-strength 30 percent line at 4,107.1 and the 13-week low at 4,015.6 are the extended references.
1. Executive Summary
The December gold contract settled at 4,318.4 on Wednesday, down 58.0 points or 1.33 percent from Tuesday's 4,376.4, the lowest settle since 08/06/26, when the contract settled at 4,299.6, and the third consecutive lower close. The completed session traded a 96.8 point band between 4,407.5 and 4,310.7 and settled at 8.0 percent of that range, 7.7 points above the low, the weakest close by position since 03/04/26, when the contract settled at 6.0 percent of its range. The settle sits 45.1 points above the one-month low of 4,273.3 set on 09/16/26, and beneath every settlement moving average computed this run, from the 5-day through the 200-day.
The driver was rates and the dollar, with no gold-specific development. The ten-year yield closed at 5.11 percent after a 5.14 percent intraday high, up 15 basis points on the session, and press commentary described the move as a 19-year high. The dollar index closed at 101.10, up 0.50 percent, which press commentary called a 1.75-month high. The United States flash manufacturing survey printed 57.0 against a 53.7 forecast at 09:45 AM ET, per the news-feed record and unconfirmed against an official calendar, and press commentary quoted a Federal Reserve governor speaking at 10:05 AM ET as saying further policy adjustments are likely to be needed to bring inflation to target. Press commentary also put the market-implied probability of a rate increase at the October policy meeting at 69 percent, up from 53 percent on Tuesday. A metal that pays nothing sold off into higher nominal yields and a firmer dollar on the same day, and the headline times and the price move coincided; no time-stamped intraday price series was captured this run, so no causal ordering is asserted.
The structural picture heading into Thursday is a trendless market that has just taken a directional step. The directional index reads beneath 20 on every horizon published, and on every one of them negative direction sits above positive direction. The composite multi-indicator read is 24 percent sell. The contract settled 38.69 points beneath its 50-day settlement average of 4,357.09, a line Tuesday's 4,376.4 settle held above when the 50-day stood at 4,353.28, and it now has the one-month low as the only structural reference between the settle and the 13-week low of 4,015.6.
The primary setup is a short from a retracement into the 4,340 to 4,360 band around the standard pivot, stopped above the first standard pivot resistance, with objectives at the session low, beneath the one-month low and an extended 4,230.
2.1 Intraday and Session Review
The completed Wednesday session opened at 4,394.7, 18.3 points above Tuesday's 4,376.4 settle, marked a high of 4,407.5 and a low of 4,310.7, and settled at 4,318.4. No intraday series was captured this run, so the order in which those extremes were reached is not asserted and no path claim appears anywhere in this outlook. What the daily bar establishes is geometry: the settle finished 76.3 points beneath the open and 89.1 points beneath the high, so the body of the bar is long and dark relative to its range.
The session extremes are the completed-session inputs behind the published pivot ladder, back-solved from the outer pivot pairs and verified against every rung. Pivot R3 at 4,477.2 minus Pivot S3 at 4,186.8, divided by three, returns 96.8, and Pivot R2 at 4,442.3 minus Pivot S2 at 4,248.7, divided by two, returns the same 96.8. Three times the unrounded Pivot Point of 4,345.53, published as 4,345.5, less the 4,318.4 settle gives a high plus low sum of 8,718.2, and the resulting pair of 4,407.5 and 4,310.7 reproduces all seven published rungs. The provider's own published daily record for the contract returns 4,394.7, 4,407.5, 4,310.7, 4,318.4 on 143,873 contracts. Both are surfaces of the same vendor, so they confirm internal consistency only.
The provider's overview page shows a day open of 4,324.4, a day high of 4,328.8 and a day low of 4,320.2 at the time of reading. Those belong to the new Globex session that reopened at 6:00 PM ET and are not Wednesday's range.
2.2 Daily Structure
Wednesday's low at 4,310.7 sits 16.9 points beneath Tuesday's 4,327.6 low and its high at 4,407.5 sits 6.6 points beneath Tuesday's 4,414.1 high, so the bar made a lower high and a lower low, a clean continuation shape on the daily frame. The prior week, September 14 through September 18, spanned 4,439.8 at the high and 4,273.3 at the low, so the settle remains inside that weekly range, 45.1 points above its low.
The 13-week extremes serve as the quarterly proxy, because no prior-quarter high or low was captured this run. The 13-week and one-month high stands at 4,755.0, set on 08/25/26, and the 13-week low at 4,015.6, set on 06/30/26. The settle sits 302.8 points above the 13-week low. The 52-week high of 5,781.8, set on 01/29/26, sits 1,463.4 points or 33.89 percent above the settle, measured from the settle; the 52-week low of 3,916.0 sits 402.4 points or 9.32 percent beneath it, measured from the settle.
2.3 4-Hour and Swing Structure
The settlement sequence over the captured window reads 4,332.8 on 09/15, 4,387.5, 4,399.7, 4,424.9 on 09/18, and then 4,383.9, 4,376.4 and 4,318.4. The three sessions since the 09/18 settle have removed 106.5 points, or 2.41 percent, and the latest session delivered more than half of that on its own. The swing structure is therefore a failed advance from the 09/16 low: the contract rallied from the 4,273.3 low into the 4,439.8 high of 09/18 and has now given back 121.4 points of that 166.5 point advance, or 72.9 percent of it, measured from the 4,439.8 high to Wednesday's settle.
The retracement grid published for Thursday places the 38.2 percent retracement from the 13-week low at 4,298.1 and the 50 percent retracement of the 13-week range at 4,385.3. The settle sits between them, 20.3 points above the lower line. The published target price for Thursday is 4,296.1, two points beneath that retracement, so the two nearest references beneath the settle sit within two points of each other.
2.4 Moving Averages
Computed this run from the provider's published daily settlement series for the December contract, because the provider's technical page is dated for the Thursday session and substitutes the reopened-session last price for a close. Through Wednesday: 5-day 4,380.66, 20-day 4,442.38, 50-day 4,357.09, 100-day 4,400.25, 200-day 4,648.37.
The 4,318.4 settle sits beneath all five: 62.26 points beneath the 5-day, 123.98 beneath the 20-day, 38.69 beneath the 50-day, 81.85 beneath the 100-day and 329.97 beneath the 200-day. The 50-day is the nearest, and it is also the average whose relationship changed on Wednesday: computed through Tuesday it stood at 4,353.28, beneath Tuesday's 4,376.4 settle. The projection grid gives the prices at which each average would be crossed on Thursday: 4,371.9 for the 9-day, 4,411.8 for the 18-day and 4,426.5 for the 40-day, all overhead.
2.5 Oscillator and Trend Readings
Cited as published on the provider's technical page for the Thursday session, which substitutes the reopened-session price for a close. Relative strength: 37.14 on the 9-day, 42.25 on the 14-day, 45.33 on the 20-day, 47.73 on the 50-day and 49.09 on the 100-day, every horizon beneath 50. The published 14-day relative-strength grid places the 50 percent line at 4,412.4 and the 30 percent line at 4,107.1.
Raw stochastic: 31.47 percent on the 9-day, 19.81 percent on the 14-day, 12.35 percent on the 20-day and 41.67 percent on the 50-day. The 14-3 day raw stochastic 20 percent threshold sits at 4,330.3 and its 30 percent threshold at 4,358.9, so the settle sits beneath the 20 percent line.
Directional system: 9-day index 18.69 with positive direction 11.14 and negative direction 17.28; 14-day 14.66 with 13.80 and 17.77; 20-day 12.99 with 15.51 and 18.21. Every horizon has negative direction above positive direction and every index reading beneath 20, so the market leans lower without trending. Historic volatility: 13.02 percent on the 9-day and 12.73 percent on the 14-day, rising to 19.24 percent on the 20-day.
Composite multi-indicator read published for Thursday: 24 percent sell. Snapshot history: 16 percent sell one week ago and 72 percent buy one month ago.
2.6 Volatility and Expected Range
14-day average true range 97.0 points and 14-day average daily range 94.0 points; 9-day 91.1 and 83.4; 20-day 100.1 and 102.7. Wednesday's realised 96.8 point range was 1.03 times the 14-day average daily range, a normal-sized session with an unusually one-sided close.
A one-range projection from the 4,318.4 settle using the 14-day average true range of 97.0 points frames Thursday between 4,221.4 and 4,415.4. The published standard-deviation bands are tighter: one deviation spans 4,274.3 to 4,362.5, two spans 4,256.0 to 4,380.8 and three spans 4,242.0 to 4,394.8.
4.1 Dollar and Real Yields
Dollar index 101.10, up 0.50 points or 0.50 percent, after a 100.54 to 101.23 range. Ten-year nominal yield 5.11 percent after a 4.98 to 5.14 range, up 15 basis points from Tuesday's 4.96 percent. No inflation-protected yield or breakeven series was captured this run, so the split of that move between real yields and inflation expectations is not measured here. Press commentary attributed part of the yield move to firmer crude lifting inflation expectations, which would place some of it in the breakeven component; that attribution is carried as commentary, not as a measurement.
A ten-year yield above 5 percent is a heavy carrying cost for a non-yielding asset, and the desk note described the level as the highest since July 2007. The five-year note auction at 01:00 PM ET stopped at a 5.033 percent high yield, a tail of 3.1 basis points above the when-issued level of 5.002 percent, with a 2.21 bid-to-cover against a prior 2.37, per the news-feed record and unconfirmed against an official calendar.
4.2 Fed and Monetary Policy
The Federal Reserve governor's housing remarks were scheduled at 10:05 AM ET on Wednesday, per the verified forward calendar, and press commentary quoted him as saying that further policy adjustments are likely to be needed to ensure inflation comes down to target in a timely fashion. Press commentary put the market-implied probability of a rate increase at the October policy meeting at 69 percent, against 53 percent on Tuesday. The projections published on September 16 showed 12 of 18 officials expecting one more quarter-point increase this year, four expecting two and two expecting none, per a news-feed item stamped 02:00 PM ET that day.
Flash surveys, all at 09:45 AM ET, per the news-feed record and unconfirmed against an official calendar: manufacturing 57.0 against a 53.7 forecast and a 53.9 prior, services 58.7 against 55.8, composite 58.4 against 55.3 and a 56.0 prior. Press commentary described the manufacturing reading as the fastest expansion in four and a quarter years. The next policy meeting is scheduled for October 28 at 02:00 PM ET, per the news-feed calendar and unconfirmed.
4.3 Geopolitical Backdrop
The Middle East backdrop moved toward risk on Wednesday, which would ordinarily support gold, and gold fell anyway. Press accounts carried remarks by the United States Secretary of State that Iran fired at commercial vessels in the Strait of Hormuz and that talks were being impeded, and Brent crude settled at 103.08, up 3.86 percent, per a news-feed item stamped 02:40 PM ET. A news-feed headline stamped 07:45 PM ET described the Iranian president sending a defiant message to the United States over potential talks. The haven bid that this backdrop might have produced was overwhelmed by the rates channel: on Wednesday the market treated a geopolitical escalation as an inflation shock.
A news-feed item stamped 04:10 PM ET reported that China had taken possession of sensitive military aircraft parts diverted to Hong Kong, and the Chinese leader was scheduled to arrive at the White House at 6:00 PM ET, per the news-feed calendar and unconfirmed.
4.4 China and Structural Demand (Central Bank Buying, Reference Fixing, Fund Flows)
A bank metals note carried on the news feed, without a captured timestamp, reported Chinese gold imports up 39.3 percent year on year to 141.7 tonnes in August, taking year-to-date imports to a record 1,141.2 tonnes, up 72.2 percent. That is the structural demand argument, and it operates on a horizon of months. No central bank purchase figure, reference-rate fixing or exchange-traded fund holdings series was captured this run, so none is asserted.
The gold exchange-traded fund proxy closed at 392.88, down 1.80 percent from 400.07 on the provider's daily record, a larger percentage decline than the futures contract's 1.33 percent; the difference is a timing and basis artefact between an equity-hours close and a futures settlement and is not read as a flow signal. After the settle, a news-feed report stamped 08:15 PM ET said the United States and China had extended their trade truce through January 10.
4.5 Energy and Cross-Asset
November WTI settled at 92.16, up 1.81 percent, and Brent at 103.08, up 3.86 percent. S&P 500 cash index 7,706.03, down 0.75 percent; Nasdaq-100 cash index 30,470.29, down 0.85 percent; volatility index 15.18, up 6.83 percent. Silver was reported by a news-feed headline stamped 02:30 PM ET as moving toward 64 dollar support on hawkish Federal Reserve commentary.
Higher crude, higher yields, a firmer dollar and lower equities is the configuration in which gold has the least support from any direction: its inflation-hedge argument is offset by the yield it forgoes, its haven argument by the dollar, and its risk-appetite channel is absent.
4.6 Institutional Positioning (Futures Report, Fund Holdings, Speculator Length)
As of September 15, 2026, the latest captured: managed money long 142,394 against short 9,278, net long 133,116, after reducing longs by 3,410 and shorts by 1,554 on the week. Commercials 56,417 long against 318,138 short, net short 261,721. Swap dealers 14,690 long against 248,350 short. Open interest on the December contract 315,425 at the latest published reading.
A managed-money short position of 9,278 contracts against a long position of 142,394 is a heavily one-sided book, the condition in which a macro shock to the carry cost produces long liquidation, and the mechanical reason a rates move can travel further in gold than the rates move alone would suggest. The report predates Wednesday by six sessions, so it describes a starting condition.
5. Bullion Fund Options Flow Context (Proxy)
Qualitative only: the fund tracks bullion with a fee drag and at a ratio that has no clean basis to the futures contract, so no level from it is translated into a futures price anywhere in this outlook.
The positioning console for the fund, updated on Wednesday, showed a current price of 393.19 against a previous close of 400.07, a daily change of minus 1.72 percent, share volume of 6,466,737, call gamma of minus 287 million dollars and put gamma of 174 million dollars, with next-expiry gamma at 2.75 percent of the total and the largest gamma expiry dated January 15, 2027. The console's high-volatility-point and low-volatility-point fields, published as 449 and 314, are excluded as low-confidence per the known defect in that pair of fields.
The fund's options book is concentrated in longer tenors, with only 2.75 percent of gamma in the next expiry, so short-dated hedging flows are unlikely to dominate Thursday's price action in the fund. No gamma-derived level is used for the futures contract, and nothing in the resistance and support lists originates from this proxy.
6. Forecast, session by session
Night Session (6:00 PM ET Wednesday to 3:00 AM ET Thursday, Globex and Asia). The reopen carries the Chinese leader's arrival at the White House at 6:00 PM ET, per the news-feed calendar and unconfirmed, and the after-settle report stamped 08:15 PM ET that the United States and China extended their trade truce through January 10. The reopened session was trading between 4,320.2 and 4,328.8 at the time of reading. Japanese flash purchasing-manager surveys at 08:30 PM ET, prior composite 53.5, and Australian labour data at 09:30 PM ET with the unemployment rate forecast at 4.5 percent, both per the news-feed calendar and unconfirmed. Asian physical demand at lower prices is the main support argument overnight. Bias neutral to slightly lower beneath the 4,345.5 pivot, expected Globex band roughly 4,295 to 4,350.
London Session (3:00 AM to 8:00 AM ET Thursday). Swiss rate statement at 03:30 AM ET with a zero percent forecast, Norwegian decision at 04:00 AM ET with a forecast of 4.5 percent against a current 4.25 percent, and a Federal Reserve speaker at 04:10 AM ET, all per the news-feed calendar and unconfirmed. A Norwegian increase would add to the global tightening narrative that pressured gold on Wednesday. Bias lower while the 4,345.5 pivot caps, expected band roughly 4,285 to 4,355.
Morning Session (9:30 AM to 12:00 PM ET Thursday, US Open). Weekly jobless claims at 08:30 AM ET, consensus 200,000 against a prior 196,000, per the news-feed calendar and unconfirmed; second-quarter international transactions at 08:30 AM ET, per the verified forward calendar. Federal Reserve speakers at 08:30 AM, 08:50 AM and 10:10 AM ET, per the news-feed calendar and unconfirmed; new home sales at 10:00 AM ET, per the verified forward calendar. A low claims print supports the rate-increase repricing and the dollar, and a high one would give the metal its first relief from the rates channel. Expected band roughly 4,270 to 4,360, with the 4,296.1 to 4,298.1 pair as the first test.
Afternoon Session (12:00 PM to 4:00 PM ET Thursday). Seven-year note auction at 01:00 PM ET, prior high yield 4.512 percent, per the news-feed calendar and unconfirmed, the most direct read on demand for duration after Wednesday's 3.1 basis point tail on the five-year. Dealer financing survey at 02:00 PM ET, per the verified forward calendar. Expected band roughly 4,275 to 4,355.
Night Session Forward (6:00 PM ET Thursday). Residual bias depends on whether the one-month low at 4,273.3 held. Forward anchor: durable goods at 08:30 AM ET on September 25, 2026, per the verified forward calendar, and the final consumer sentiment reading at 10:00 AM ET that Friday, one-year inflation expectation prior 4.6 percent, per the news-feed calendar and unconfirmed. Larger forward grouping: personal income and outlays at 08:30 AM ET on September 30 and the employment report at 08:30 AM ET on October 2, both per the verified forward calendar.
Expected Range (Thursday full session). Low-range scenario 4,290 to 4,350. Mid-range scenario, the most likely, 4,265 to 4,365. High-range scenario 4,230 to 4,395.
Most Likely Path. The reopened session holds beneath the 4,345.5 pivot through Asia and Europe, with the trade truce extension offering modest support against a Norwegian rate decision that leans the other way; the claims release at 08:30 AM ET is the first United States test. The path carrying the most weight in analyst judgment tests the 4,296.1 to 4,298.1 pair and then the 4,273.3 to 4,283.6 group during the United States session without a settle beneath 4,273.3, because the managed-money book is long and the directional index is too weak to argue for a trending day. A settle above the 4,380.4 to 4,380.8 pair would invalidate this reading and reverse Wednesday's shape.
7. Thursday Economic Calendar
Overnight: the Chinese leader's arrival at the White House at 6:00 PM ET Wednesday and the state visit running all day Thursday, both per the news-feed calendar and unconfirmed. Japanese flash purchasing-manager surveys at 08:30 PM ET Wednesday, prior manufacturing 54.9 and composite 53.5; Australian employment data at 09:30 PM ET, employment change forecast at 20,000 against a prior decline of 15,800; both per the news-feed calendar and unconfirmed.
European morning, all per the news-feed calendar and unconfirmed: French confidence surveys at 02:45 AM ET; Swiss and Swedish policy decisions at 03:30 AM ET, the Swiss forecast at zero and the Swedish at 1.75 percent; the Norwegian decision at 04:00 AM ET, forecast 4.5 percent against a current 4.25 percent; the German business climate survey at 04:00 AM ET, forecast 89 against a prior 88.8; a Federal Reserve speaker at 04:10 AM ET and a Bank of England speaker at 05:30 AM ET.
United States: weekly jobless claims at 08:30 AM ET, consensus 200,000 against a prior 196,000, per the news-feed calendar and unconfirmed; second-quarter international transactions at 08:30 AM ET, per the verified forward calendar; Federal Reserve speakers at 08:30 AM, 08:50 AM and 10:10 AM ET, per the news-feed calendar and unconfirmed; new home sales at 10:00 AM ET, per the verified forward calendar; a tentative Treasury liquidity buyback at 11:00 AM ET and a seven-year note auction at 01:00 PM ET, per the news-feed calendar and unconfirmed; a dealer financing survey at 02:00 PM ET, per the verified forward calendar.
The single first-order event for gold is the combination of the 08:30 AM ET claims release and the 01:00 PM ET seven-year auction, because both act through the rate channel that drove Wednesday, per the news-feed calendar and unconfirmed. No structural gold expiry falls on Thursday on the captured calendars. The next first-order release is the durable goods report at 08:30 AM ET on September 25, 2026, per the verified forward calendar.
8. Primary Trade Setup
Direction: Short
Rationale: The contract settled beneath every settlement moving average computed this run, including the 50-day that Tuesday's settle held above, at 8.0 percent of a normal-sized range, on a day when the ten-year yield closed above 5 percent and the dollar rose 0.50 percent; every directional horizon has negative direction above positive direction, and a retracement into the pivot offers a short at better prices than the close.
Entry Zone: 4,340 to 4,360
Stop Loss: 4,390 (above Pivot R1 at 4,380.4 and two standard deviations resistance at 4,380.8, and beneath three standard deviations resistance at 4,394.8)
Target 1: 4,310 (Wednesday's session low at 4,310.7)
Target 2: 4,270 (beneath the one-month low at 4,273.3 and one standard deviation support at 4,274.3)
Target 3 (extended): 4,230 (beneath Pivot S2 at 4,248.7 and three standard deviations support at 4,242.0)
Risk-to-Reward: Approximately 1:1 to T1, 1:2 to T2, 1:3 to T3
Invalidation: A settle above 4,380.8 negates the thesis, because it would recover the first standard pivot resistance and the 5-day settlement average together. Short of that, acceptance above the 50-day settlement average, defined as two consecutive 30-minute closes above 4,357.09, removes the edge. A single print above 4,360 that is rejected inside one 30-minute bar is consistent with the entry band and is not the invalidation.
Macro override: A weak claims print, or a seven-year auction that stops well through its when-issued level, both scheduled per the news-feed calendar and unconfirmed, would ease the rate channel that drove Wednesday and would undercut a short thesis that rests on it. A second override is the Strait: if an escalation were read as a safety event rather than an inflation event, gold could recover its haven bid quickly against a managed-money book that is still heavily long.
Sources and methodology
This outlook is built from our session review of the December COMEX gold contract, GCZ26, the December '26 contract, prepared after Wednesday's close on September 23, 2026 for the Thursday, September 24 session. The contract domain was checked before any level was used: the chart read 4,324.3 with a stated change of plus 0.14 percent, which returns a prior close of 4,318.3, within a tenth of the published previous close of 4,318.4, and the provider's own quote at the same time read 4,324.5, up 6.1, so chart and data sit on the same December contract. The day high, day low and open shown on the data overview page belong to the new Globex session and are not presented anywhere here as Wednesday's range.
Wednesday's extremes are the completed-session inputs behind the published pivot ladder, back-solved from its outer pairs, verified against all seven published rungs and reproduced by the provider's own daily record, a second surface of the same vendor that confirms internal consistency only. The moving averages were computed from that daily settlement series, and the oscillator readings are cited as published with the reopened-session caveat stated. The bullion exchange-traded fund is used qualitatively only; no level in this outlook originates in it, and its two volatility-point fields are excluded. Scenario ranges and path weightings are analyst judgment. Catalysts whose release time had passed are recorded as completed with their result, and items marked per the news-feed calendar and unconfirmed, or per the verified forward calendar, carry that qualification exactly as the review states it. An intraday price series, inflation-protected yields and breakevens, central bank purchase data, a reference-rate fixing, fund holdings and a prior-quarter high and low were not captured in this run, and no figure is stated for any of them.
Wednesday’s outlook for this contract is here, and the same session's crude read is here. Outlooks for ES, NQ, GC and CL are collected on the market outlook page, and our forward trading record is on the performance statement.