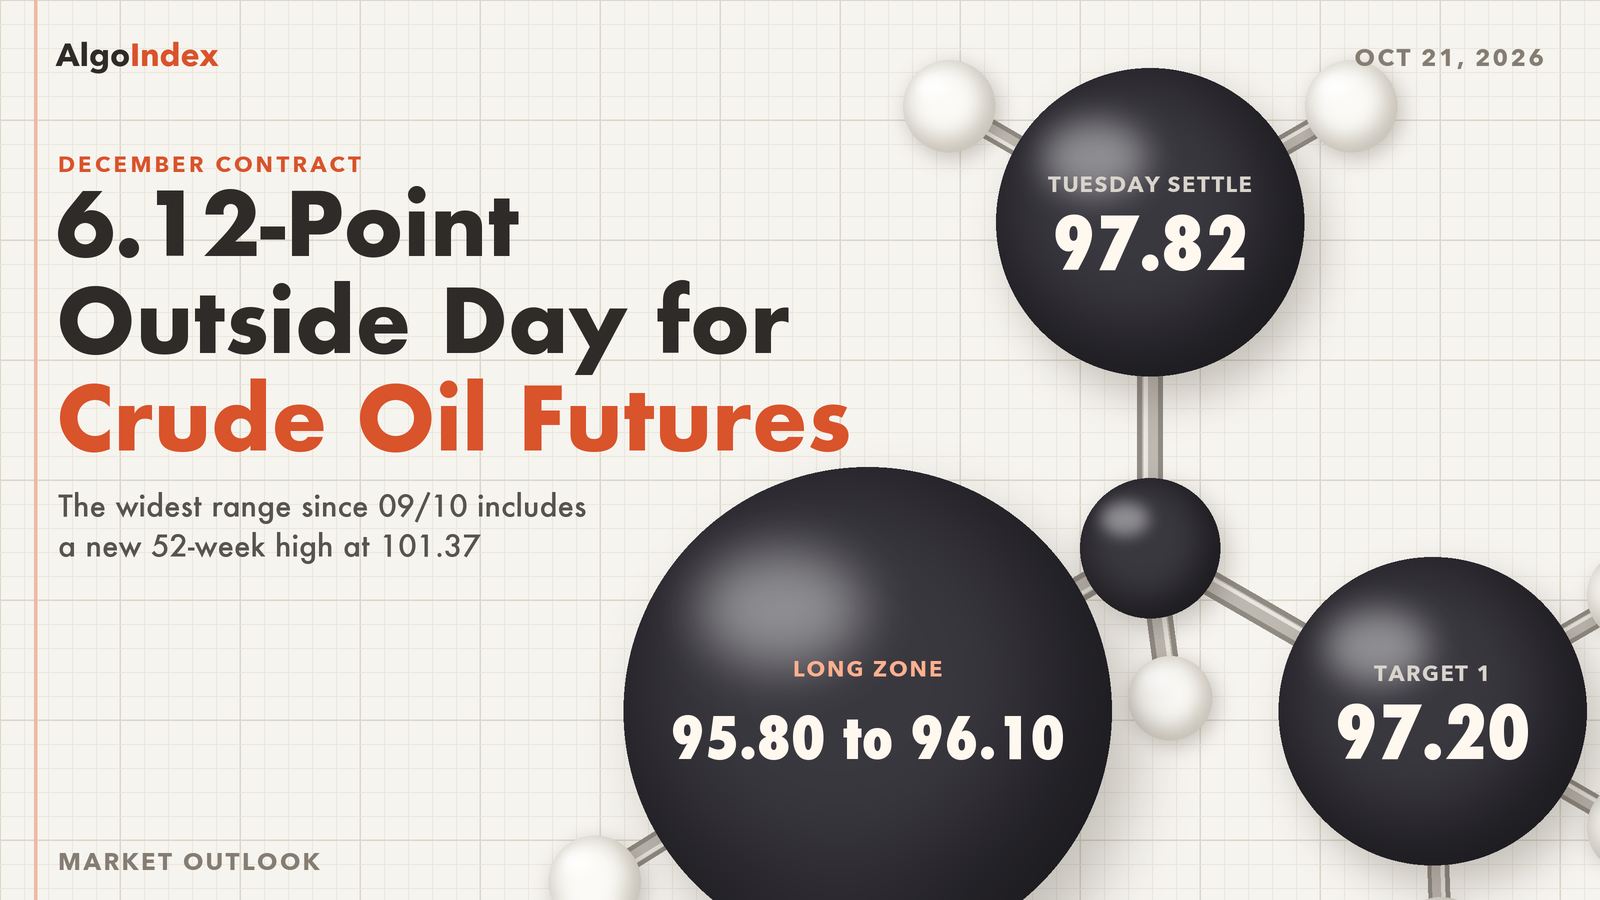
Between 101.37 and 95.25, December crude covered 6.12 points on Tuesday, its widest daily range since the 6.38 point range of 09/10. It settled at 97.82, down 0.72 or 0.73 percent, at 42.0 percent of that range. The 101.37 high is the new 52-week high for December on the provider's overview, 1.66 above Monday's 99.71. The 95.25 low sat 1.47 beneath Monday's 96.72. An outside day, then. It was also the second lower settle in a row.
The swing ran through most of Tuesday's card. That card was already on December, so it is graded on December's own bar. The session opened at 98.24, inside the 98.00 to 98.30 band. The 95.25 low went 1.60 through the 96.85 stop, the 101.37 high cleared the first two targets, and the settle finished 18 cents beneath the band. No intraday series was preserved for the session. So the order of those prints cannot be shown.
The news flow ran in both directions. The news feed carried Iranian media reports of tankers catching fire in the southern corridor of the Strait of Hormuz at 10:36 AM ET and 12:51 PM ET. At 10:11 AM ET it carried a press report that a proposal carried by Pakistan's army chief had received US approval and preliminary Iranian agreement. At 11:12 AM ET a diplomat was quoted saying reports that a deal is close are wrong. Provider commentary attributed the lower settle to long liquidation after an unconfirmed report of a fresh mediation proposal and to a crack spread at a 3.75-month low. That is the commentary's account.
The expiring November contract posted its final settle at 101.79, down 1.87 or 1.80 percent per the news feed at 2:30 PM ET. December is now the front month. After the settle, the industry inventory survey at 4:39 PM ET showed a crude draw of 4.93 million barrels against a forecast draw of 1.3 million.
December crude settled at 97.82, down 0.72, at 42.0 percent of a 95.25 to 101.37 range. It sits above all six settlement averages, 66 cents over the 5-day. Resistance starts at the Pivot Point at 98.15, then Monday's 98.54 settle, the 98.79 target price, Monday's 99.71 high and one standard deviation resistance at 99.87. Support starts at the 97.16 5-day average and Monday's 96.72 low, then one standard deviation support at 95.77, the 95.50 retracement, the 95.35 crossing price and Tuesday's 95.25 low, with Pivot S1 at 94.92 beneath. The setup is a long on the December contract. It runs from 95.80 to 96.10, stop 94.70, targets 97.20, 98.45 and an extended 99.70. The whole band sits beneath the settle, its top 1.72 under it, and the 97.20 first target sits 62 cents beneath the settle too. The calendar lists the weekly petroleum status report at 10:30 AM ET on Wednesday.
Tuesday's 6.12 point range covered the band, the stop and two targets
First, the grading. In Tuesday's outlook we set a long on the December contract from 98.00 to 98.30, stop 96.85, with targets at 99.45, 100.75 and an extended 102.05. A settle beneath Pivot S1 at 96.94 would negate it. Two consecutive 30-minute closes beneath 98.00 would remove the edge. The card was written on December, so it is graded on December's Tuesday bar.
Then December traded. Its bar, from the provider's settlement row, opened at 98.24 at the Monday 6:00 PM ET reopen, 30 cents beneath Monday's settle. That open sat inside the band, 24 cents above its bottom and 6 cents beneath its top. The bar marked a high of 101.37 and a low of 95.25, and settled at 97.82. The range covered the whole band. It covered the stop too. The 95.25 low sat 1.60 beneath the 96.85 stop and 1.69 beneath Pivot S1 at 96.94.
So the stop level traded. The 97.82 settle sat 88 cents above 96.94, so the invalidation settle never printed. It finished 18 cents beneath the band's bottom and 33 cents beneath the 98.15 midpoint.
Order is the open question. No intraday series was preserved for Tuesday. The daily bar cannot show whether the dip through the stop came before or after the highs. The 101.37 high cleared the 99.45 first target by 1.92 and the 100.75 second target by 62 cents. It stopped 68 cents short of the extended 102.05. Whether either target printed before the stop is unknown. The bar also cannot show whether two 30-minute closes printed beneath 98.00. No fill and no result is asserted.
Our ranges were too narrow for the day. The low-range case of 97.40 to 99.70 gave way on both sides, by 2.15 at the bottom and 1.67 at the top. The most likely case of 96.90 to 100.40 broke by 1.65 and by 97 cents. The high-range case of 95.30 to 101.90 held the top with 53 cents to spare. Its bottom gave way by 5 cents. The one deviation band of 95.89 to 101.19 broke both ways, by 64 cents and 18 cents. Two deviations held. That band, 94.80 to 102.28, kept 45 cents at the bottom and 91 cents at the top. One average true range around Monday's settle, 95.09 to 101.99, held with 16 cents and 62 cents. The session bands for Globex, London, the morning and the afternoon need an intraday series, so they are not graded.
The weighted path expected a hold between Pivot S1 at 96.94 and Pivot R1 at 99.93, with a dip toward the band holding above 96.97. The range broke both ends. The high ran 1.44 through 99.93 and the low 1.69 beneath 96.94. The named alternative was a move beneath Pivot S1 toward one standard deviation support at 95.89. Its levels traded, with the low 64 cents beneath 95.89, and the settle stayed above 96.94. The card's macro override named a confirmed de-escalation between Washington and Tehran or a reopening of Strait of Hormuz traffic. Three items on the news feed touched it. One was a press report that a proposal presented by Pakistan's army chief received US approval and preliminary Iranian agreement. Another was a diplomat's statement that reports of a close deal are wrong. The third was the US Secretary of State's statement that oil moving through Hormuz is nearly equal to pre-war levels. These are statements carried by the news feed rather than confirmed events.
The December band at 95.80 to 96.10, just above one deviation support
The map moved down 2.20 points, the gap between the two midpoints. Every price here is the December contract. The new band, 95.80 to 96.10, sits just above one standard deviation support at 95.77, its bottom 3 cents over it, and 30 cents above the 38.2 percent retracement at 95.50. The settle sits 1.72 above the band's top and 2.02 above its bottom. Only a dip reaches it. The stop at 94.70 sits 22 cents beneath Pivot S1 at 94.92, which coincides with two standard deviations support, and 44 cents above three standard deviations support at 94.26.
The reopen printed well above the band. Globex reopened at 6:00 PM ET on Tuesday for the Wednesday session, and the provider's overview showed that session's open, high and low at 98.19, 98.43 and 98.04. The low sits 1.94 above the band's top. The provider's last quote at 6:20 PM ET was 98.15, and the chart showed 98.00 at 6:26 PM ET. Those are reopened-session quotes and they are excluded from Tuesday's range.
Tuesday was an outside day. Its 101.37 high sits 1.66 above Monday's 99.71 and its 95.25 low 1.47 beneath Monday's 96.72. The settle beneath the 98.24 open leaves a body of 42 cents. The upper shadow runs 3.13 above the open and the lower shadow 2.57 beneath the settle. The settle is the lowest since the 96.50 settle of 10/15, and the low the lowest since the 92.46 low of 10/15. Eight sessions of settlements read 90.75, 91.01, 92.86, 93.17, 93.90, 96.50, 99.02 and 98.54 before Tuesday's 97.82. Highs over six sessions climbed from 94.09 through 94.87, 96.74, 99.34 and 99.71 to 101.37. Lows read 90.85, 93.06, 92.46, 95.29, 96.72 and 95.25.
Resistance starts 33 cents up. The Pivot Point at 98.15 comes first, then Monday's 98.54 settle and the published target price at 98.79, 97 cents above the settle. Monday's 99.71 high and one standard deviation resistance at 99.87 follow. Then a tight pair. Two standard deviations resistance at 100.72 and the 3-10 day crossover stall level at 100.74 sit 2 cents apart, with Pivot R1 at 101.04 above them. Tuesday's 101.37 high, also the one-month, 13-week and 52-week high, sits 1 cent beneath three standard deviations resistance at 101.38 and 3.55 above the settle. The 101.46 top of one average true range comes next. Pivot R2 at 104.27 and Pivot R3 at 107.16 form the extended band.
Support starts 66 cents down at the 5-day average of 97.16, with Monday's 96.72 low beneath. Then the band's neighbours. One standard deviation support at 95.77 and the 38.2 percent retracement from the four-week high at 95.50, 2.32 beneath the settle, come first. The 9-day average crossing price at 95.35 sits just above Tuesday's 95.25 low, 10 cents over it. Pivot S1 at 94.92 coincides with two standard deviations support, 33 cents beneath the low, and the 9-day average at 94.84 sits 8 cents under them. Three standard deviations support at 94.26 and the 94.18 bottom of one average true range follow. At 93.68 two references coincide, the 50 percent retracement of the four-week range and the 14-3 day raw stochastic projection. Then the long tail. Pivot S2 at 92.03, the 18-day crossing at 91.92 and the 91.87 retracement from the four-week low lie further down. So do the 20-day at 91.59, the 89.77 retracement from the 13-week high, the 40-day crossing at 89.70 and Pivot S3 at 88.80. Six more sit far beneath. They are the 50-day at 87.62, the 86.00 one-month low, the 100-day at 81.29, the 200-day at 75.88, the 71.00 13-week low and the provider's 55.63 52-week low.
Every average still sits beneath price. The settle is 66 cents above the 5-day at 97.16, 2.98 above the 9-day at 94.84, 6.23 above the 20-day at 91.59 and 10.20 above the 50-day at 87.62. The gaps to the 100-day at 81.29 and the 200-day at 75.88 are 16.53 and 21.94. The 5-day rose 93 cents from 96.23 as the 10/13 settle of 93.17 left the window and 97.82 replaced it. The 20-day rose 49 cents from 91.10 as the 09/22 settle of 87.98 left. The 50-day rose 39 cents from 87.23. The order holds. The 30 older settlements in the 50-day window averaged 84.97, the 50 older ones in the 100-day window 74.95 and the 100 older ones in the 200-day window 70.47. Wednesday's crossing prices are 95.35 for the 9-day, 91.92 for the 18-day and 89.70 for the 40-day.
Momentum stays high. Relative strength reads 71.21 on the 9-day, 67.60 on the 14-day and 65.29 on the 20-day. The raw stochastics read 73.66 percent on the 9-day and 76.90 percent on the 14-day. The 14-day %K at 88.66 percent sits beneath %D at 93.03 percent, in the upper part of the range. Positive direction leads on both windows. It reads 29.44 against 4.44 on the 9-day with the ADX at 44.27, and 27.72 against 6.71 on the 14-day with the ADX at 35.66. Historic volatility reads 20.71 percent and 25.77 percent. The composite multi-indicator read for Wednesday holds at 100 percent buy, unchanged from the prior session, with signal strength described as strong and direction as strengthening. It read 88 percent buy a week ago and 72 percent a month ago. All three horizon groups average 100 percent buy, and the trend indicator reads buy. These are the provider's published readings, read at 6:20 PM ET after the 6:00 PM ET reopen, so they may include the first minutes of the Wednesday session.
Tuesday ran wide. The 14-day average true range stands at 3.64 points and the 14-day average daily range at 3.65. Tuesday's 6.12 was 1.68 times that. The 9-day figures are 3.77 and 3.70 and the 20-day 3.51 and 3.74. One average true range either side of the settle spans 94.18 to 101.46. The deviation bands, built from five settlements, run 95.77 to 99.87, 94.92 to 100.72 and 94.26 to 101.38. They describe settlement dispersion only. A headline gap can open outside any of them. Eight sessions of daily ranges read 1.99, 4.53, 3.24, 1.81, 4.28, 4.05, 2.99 and 6.12.
Hormuz reports, a mediation proposal and a larger draw
Hormuz headlines ran through the day. At 10:36 AM ET the news feed carried an Iranian media report that a tanker violating regulations caught fire in the southern corridor of the Strait of Hormuz. At 12:51 PM ET it carried an Iranian media report that a supertanker carrying over 2 million barrels hit a sea mine and caught fire there. Provider commentary said Iran reported three tankers struck mines on the southern route. At 3:38 PM ET the feed carried an Iranian general's statement that operational control of the strait is in the hands of Iran's armed forces. It had carried the US Secretary of State's statement, at 11:43 AM ET, that oil moving through Hormuz is nearly equal to pre-war levels.
Diplomacy pulled the other way. At 10:11 AM ET the news feed carried a press report that a proposal presented by Pakistan's army chief received US approval and preliminary Iranian agreement. At 11:12 AM ET it carried a diplomat's statement that reports of a close deal are wrong. At 2:42 PM ET the President said he has to make a final decision on Iran. At 4:59 PM ET to 5:01 PM ET Iran's foreign minister said negotiations through Pakistan and Qatar continue and that the US wanted to add conditions. These are statements carried by the news feed rather than confirmed events. No price move is tied to them here.
Saudi Arabia came into it. At 4:24 PM ET the feed carried an Iranian media report that Yemen's Houthis consider a ground attack on Saudi Arabia an option, and at 10:25 AM ET a Saudi-led coalition statement that it intercepted a drone over Riyadh. These are claims carried by the news feed rather than supply losses measured for this review. No producer-group statement was carried on the feeds read, so no quota or compliance change is asserted. On the Russian side, the feed carried at 11:26 AM ET a statement from the US Energy Secretary that Russian diesel, if it comes to the US, would likely go to New England. At 1:47 PM ET it carried a report that US envoys plan to visit Russia on October 21. At 2:49 PM ET to 2:57 PM ET it carried the President's remarks on Ukraine talks.
The draw came after the settle. At 4:39 PM ET the news feed carried the industry inventory survey's crude draw of 4.93 million barrels, against a forecast draw of 1.3 million and a prior draw of 11.21 million. At 4:40 PM ET it carried a Cushing build of 0.936 million barrels, at 4:41 PM ET a gasoline draw of 2.577 million and at 4:45 PM ET a distillate draw of 2.6 million. The calendar lists the official weekly petroleum status report at 10:30 AM ET on Wednesday, October 21, 2026. The news-feed calendar lists a forecast draw of 0.34 million barrels against a prior draw of 8.557 million.
Products split. The November heating oil contract settled at 4.9250 dollars a gallon and November gasoline at 3.1172, per the news feed at 2:31 PM ET. Paired with the November WTI final settle of 101.79, the heating oil margin stands at 105.06 dollars a barrel against 102.98 on Monday. The gasoline margin stands at 29.13 against 30.38. On the December contracts in the provider's daily record, heating oil settled at 4.7141 and gasoline at 3.0441, margins of 100.17 and 30.03 against December WTI. Provider commentary said December gasoline fell 1.95 percent to a seven-week low. The November natural gas contract settled at 2.9630, per the news feed. No refinery utilisation figure and no seasonal demand series were captured.
The dollar eased. The dollar index closed at 101.73 in the provider's daily record, down 0.25 from Monday's 101.98, after trading between 101.51 and 101.98. Provider commentary tied part of the dollar's decline to the housing data and a stronger Chinese yuan. The ten-year yield index traded between 5.07 and 5.14 percent and closed at 5.12 percent against 5.13 percent on Monday. Housing starts and pending home sales came in under forecast. Housing starts printed at 8:30 AM ET at 1.221 million against a 1.305 million forecast, per the news-feed calendar, and building permits at 1.400 million against 1.385 million. Pending home sales printed at 10:00 AM ET at minus 7.3 percent against minus 0.5 percent, per the news-feed calendar. A softer dollar is a modest support for dollar-priced crude; the size of that effect is not measured here.
The curve narrowed at the front. December Brent settled at 108.79, down 0.76 or 0.69 percent, and its premium over December WTI stood at 10.97 against 11.01 on Monday. The expiring November contract settled 3.97 above December, against 5.12 on Monday. The front of the curve remained in backwardation while that spread narrowed. With November expired, December is now the front month. Elsewhere, December gold settled at 4,142.6, down 0.42 percent. The S&P 500 cash index closed at 7,712.57, up 0.28 percent, and the Nasdaq-100 cash index closed down 0.13 percent.
Positioning data is thin. No weekly positioning report was captured, so no change in managed-money or producer length is asserted. December open interest stood at 308,314 for Monday, and Tuesday's figure had not been reported. Tuesday's December volume was 363,268 contracts. No dealer-positioning dataset was read for crude. The positioning inputs are the Brent spread, the November to December spread, the product margins and the open-interest and volume record.
The trade map for Wednesday
The review's setup is a long on the December contract. It runs from 95.80 to 96.10. The settle sits above every settlement average from the 5-day to the 200-day, and positive direction leads on the 9-day and 14-day directional systems. The composite holds at 100 percent buy. The after-settle survey showed a crude draw of 4.93 million barrels against a 1.3 million forecast. That is the trend case. The band sits just above one standard deviation support at 95.77, and the stop at 94.70 sits beneath Pivot S1 and two standard deviations support, both at 94.92. The first target, 97.20, sits 62 cents beneath Tuesday's 97.82 settle. The second, 98.45, sits above the Pivot Point at 98.15, and the extended 99.70 sits beneath one standard deviation resistance at 99.87. Two caveats sit against it. Tuesday's outside day settled in the lower half of its range, and a mediation proposal remains open. The review calls the setup an analyst judgment that dips are bought while supply headlines persist, not a measured edge.
Now the arithmetic. From the 95.95 midpoint the risk to the stop is 1.25, 34.3 percent of the 14-day average true range of 3.64. The targets sit 1.25, 2.50 and 3.75 above the midpoint. Exact multiples, on paper. The whole band sits beneath the settle, its top 1.72 and its bottom 2.02 under it. Its bottom sits 55 cents above Tuesday's 95.25 low. The 97.20 first target sits 1.10 above the band's top and 4 cents above the 5-day average at 97.16. The 98.45 second target sits 9 cents beneath Monday's 98.54 settle, and the extended 99.70 sits 1 cent beneath Monday's 99.71 high. A headline gap can open through the stop.
Scenario ranges in the review are analyst judgment. The low-range case runs 96.40 to 99.60, the most likely 95.30 to 100.70 and the high-range case 94.20 to 101.40. Then by session. Through Globex the review's judgment expects roughly 96.40 to 99.60, with a neutral bias above the Pivot Point at 98.15. The reopen quoted 98.15 at 6:20 PM ET, after the larger-than-forecast inventory draw in the 4:39 PM ET survey. Gulf headlines remain the main overnight risk in both directions. London follows at roughly 96.00 to 99.90. One standard deviation support at 95.77 is its first meaningful support beneath, and one standard deviation resistance at 99.87 its first meaningful resistance above. The morning band runs 95.30 to 100.70, with Pivot S1 at 94.92 beneath and two standard deviations resistance at 100.72 above. The afternoon runs 95.00 to 101.00 into the 2:30 PM ET settle.
Wednesday's calendar starts on Tuesday evening. The President is listed to speak at 7:00 PM ET and Japan's trade balance at 7:50 PM ET, both per the news-feed calendar and unconfirmed. UK consumer prices are listed at 2:00 AM ET with a 3.4 percent forecast and the Bank of England governor at 9:00 AM ET, both per the news-feed calendar and unconfirmed. The volatility index options expiration is listed by the desk note at 9:30 AM ET, unconfirmed. Then the main event. The calendar lists the weekly petroleum status report at 10:30 AM ET on Wednesday, October 21, 2026. The ECB president is listed at 12:00 PM ET and the 20-year Treasury auction at 1:00 PM ET, per the news-feed calendar and unconfirmed. Crude settles at 2:30 PM ET. A social-media company and a chipmaker are listed at 4:00 PM ET and an electric-vehicle maker at 4:15 PM ET on the news-feed calendar, unconfirmed, and the calendar places all three after Wednesday's close without a confirmed time. Weekly jobless claims are listed at 8:30 AM ET on Thursday, per the news-feed calendar and unconfirmed. The calendar lists the FOMC statement at 2:00 PM ET on Wednesday, October 28, 2026.
The review also weighs the path. In the review's analyst judgment the most probable path holds the contract between Pivot S1 at 94.92 and Pivot R1 at 101.04, with a dip toward the 95.80 to 96.10 band that holds above that pivot level weighted slightly above a break lower. It names an alternative. Confirmation of the mediation proposal between Washington and Tehran would remove part of the supply premium and carry the contract beneath Pivot S1 at 94.92 toward three standard deviations support at 94.26. The review also flags a pullback. Tuesday's outside day settled in the lower half of a 6.12 point range, and %K sits beneath %D, so a further pullback before any extension is a live alternative. Then the schedule. In the review's judgment the first-order scheduled event for crude on Wednesday is the 10:30 AM ET weekly petroleum status report, with Gulf headlines the unscheduled risk.
Tuesday's swing ran through the old band and its stop; Wednesday's band waits 1.72 beneath the settle, 3 cents above one deviation support.
The complete data picture
Every number behind Wednesday’s plan, charted first, then the full level lists, then the complete numeric reference underneath. Every price is the December contract unless November is named.
Full numeric reference, every remaining figure from the session review
1. Executive Summary
The December crude contract settled at 97.82 on Tuesday, down 0.72 or 0.73 percent from Monday's settle of 98.54, after trading between 101.37 and 95.25, a 6.12 point daily range. The settle finished at 42.0 percent of the range, and the 6.12 point range was 1.68 times the published 14-day average daily range of 3.65 points. Tuesday was an outside day against Monday, with a higher high and a lower low, and the lower settle was the second consecutive lower settle for the December contract.
The 101.37 high is the new 52-week high for December on the provider's overview and the highest print in the preserved settlement series, above Monday's 99.71. The 6.12 point range was the widest daily range since the 6.38 point range of 09/10. The November contract expired on Tuesday and its final settle was 101.79, down 1.87 or 1.80 percent per the news feed at 2:30 PM ET, so November finished 3.97 above December against 5.12 on Monday. Brent's December contract settled at 108.79, down 0.76 or 0.69 percent, and its premium over December WTI stood at 10.97 against 11.01 on Monday.
The day's news flow ran in both directions. The news feed carried Iranian media reports of tankers catching fire in the southern corridor of the Strait of Hormuz at 10:36 AM ET and 12:51 PM ET, and at 10:11 AM ET a press report that a proposal carried by Pakistan's army chief had received US approval and preliminary Iranian agreement; at 11:12 AM ET a diplomat was quoted saying reports that a deal is close are wrong. Provider commentary attributed the lower settle to long liquidation after an unconfirmed report of a fresh mediation proposal and to a crack spread at a 3.75-month low. After the settle the industry inventory survey at 4:39 PM ET showed a crude draw of 4.93 million barrels against a forecast draw of 1.3 million.
The dollar index closed at 101.73 against 101.98 on Monday, and the ten-year yield index closed at 5.12 percent against 5.13 percent. Equities were mixed: the S&P 500 cash index closed at 7,712.57, up 0.28 percent, and the Nasdaq-100 cash index closed down 0.13 percent. The published 14-day average true range is 3.64 points. The Primary Setup below is a long from the 95.80 to 96.10 band above one standard deviation support at 95.77, stopped at 94.70 beneath Pivot S1 at 94.92, with objectives at 97.20, 98.45 and an extended 99.70.
2. Price Action & Technical Structure
2.1 Intraday and Session Review
The Tuesday session opened at 98.24 at the Monday 6:00 PM ET reopen, 30 cents beneath Monday's settle, marked a daily high of 101.37 and a daily low of 95.25, and settled at 97.82 at 2:30 PM ET. No intraday series was preserved for this session in this review, so this review does not describe the order in which the high and the low printed, and no timed price path is asserted; the daily bar alone fixes the open, the extremes and the settle.
The news feed's settlement item at 2:30 PM ET carried the expiring November contract's final settle. This review records only that the 101.37 high and the 95.25 low both belong to Tuesday's completed session and that the settle sits 2.57 points above the low and 3.55 points beneath the high.
Globex reopened at 6:00 PM ET on Tuesday for the Wednesday session, so the open, high and low shown on the provider's overview, 98.19, 98.43 and 98.04, belong to the new Wednesday session and are not Tuesday's range. The provider's last quote at 6:20 PM ET was 98.15, and the chart showed 98.00 at 6:26 PM ET; these are reopened-session quotes, not settlements.
Tuesday's completed-session extremes are taken from the settlement row, and they are also the completed-session inputs behind the published pivot ladder rather than an independently read bar. Pivot R3 at 107.16 minus Pivot S3 at 88.80, divided by three, returns 6.12, and Pivot R2 at 104.27 minus Pivot S2 at 92.03, divided by two, returns the same 6.12. Three times the Pivot Point of 98.15 less the 97.82 settle gives a high plus low sum of 196.63, which the pair of 101.37 and 95.25 reproduces to the published rounding at 196.62, and that pair reproduces all seven published rungs.
Independent corroboration: the provider's settlement row, the chart's completed daily bar on the continuous symbol and the provider's 52-week, 13-week and one-month high of 101.37 carry the same 101.37 high, and the settlement row and the chart's bar carry the same 95.25 low.
2.2 Daily Structure
Tuesday was an outside day: the 101.37 high sits 1.66 points above Monday's 99.71, and the 95.25 low sits 1.47 points beneath Monday's 96.72. The settle beneath the 98.24 open leaves a body of 42 cents, an upper shadow of 3.13 points above the open and a lower shadow of 2.57 points beneath the settle.
Settlements over the last eight sessions ran 90.75, 91.01, 92.86, 93.17, 93.90, 96.50, 99.02 and 98.54 before Tuesday's 97.82, so Tuesday's settle was the lowest since the 96.50 settle of 10/15, and the 95.25 low was the lowest since the 92.46 low of 10/15. The sequence of session highs over the last six sessions reads 94.09, 94.87, 96.74, 99.34, 99.71 and 101.37, and the sequence of session lows reads 90.85, 93.06, 92.46, 95.29, 96.72 and 95.25.
The one-month high, 13-week high and 52-week high all sit at Tuesday's 101.37, 3.55 points above the settle, and the provider's 52-week low of 55.63 sits far beneath. The one-month low of 86.00 and the 13-week low of 71.00 frame the lower side. No prior-quarter high or low was captured for this review, so the 13-week extremes serve as the available quarterly reference.
2.3 4-Hour and Swing Structure
Daily ranges for the last eight sessions ran 1.99, 4.53, 3.24, 1.81, 4.28, 4.05, 2.99 and 6.12. The settlement changes over the same eight sessions read plus 0.26, plus 1.85, plus 0.31, plus 0.73, plus 2.60, plus 2.52, minus 0.48 and minus 0.72.
The retracement grid published for Wednesday places the 38.2 percent retracement from the four-week high at 95.50, 2.32 points beneath the settle, and the 50 percent retracement of the four-week range at 93.68. Further beneath, the 38.2 percent retracement from the four-week low sits at 91.87 and the 38.2 percent retracement from the 13-week high at 89.77. No four-hour series was captured for this review, so swing structure here rests on daily bars only.
2.4 Moving Averages
The averages cited in this subsection were computed for this review from the provider's daily settlement series for the December contract, which holds 259 completed sessions through Tuesday; the partial Wednesday row returned after the 6:00 PM ET reopen was dropped before counting. The 5-day average stands at 97.16, the 9-day at 94.84, the 20-day at 91.59, the 50-day at 87.62, the 100-day at 81.29 and the 200-day at 75.88.
The 97.82 settle sits 66 cents above the 5-day average, 2.98 points above the 9-day, 6.23 points above the 20-day and 10.20 points above the 50-day. The 5-day average rose 93 cents from Monday's 96.23, because the 10/13 settle of 93.17 left the window and was replaced by 97.82. The 20-day rose 49 cents from 91.10, because the 09/22 settle of 87.98 left that window, and the 50-day rose 39 cents from 87.23.
The 20-day average sits above the 50-day because the last 20 settlements averaged 91.59 against 87.62 for the full 50, which means the 30 older settlements in the 50-day window averaged lower, at 84.97. The 50-day sits above the 100-day because the 50 older settlements in the 100-day window averaged lower, at 74.95, and the 100-day sits above the 200-day because the 100 older settlements in the 200-day window averaged lower, at 70.47. The projection grid gives the prices at which each average would be crossed on Wednesday: 95.35 for the 9-day, 91.92 for the 18-day and 89.70 for the 40-day.
2.5 Oscillator and Trend Readings
The oscillator figures below are as published on the provider's technical page, read at 6:20 PM ET after the 6:00 PM ET reopen, so they may include the first minutes of the Wednesday session rather than the settle alone; they are the provider's published readings, not this review's computations. The 9-day relative strength reads 71.21, the 14-day relative strength 67.60 and the 20-day relative strength 65.29.
The 9-day raw stochastic reads 73.66 percent and the 14-day raw stochastic 76.90 percent, while the 14-day stochastic %K reads 88.66 percent and the 14-day stochastic %D 93.03 percent, so %K sits beneath %D in the upper part of the range.
The 9-day directional index ADX reads 44.27 with the 9-day +DI at 29.44 and the 9-day -DI at 4.44; the 14-day directional index ADX reads 35.66 with the 14-day +DI at 27.72 and the 14-day -DI at 6.71, so positive direction leads on both and the 9-day ADX reads above the 14-day. The 9-day historic volatility reads 20.71 percent and the 14-day historic volatility 25.77 percent.
The composite multi-indicator read published for the Wednesday session is 100 percent buy, unchanged from the prior session's snapshot of 100 percent buy, with signal strength described as strong and direction as strengthening. The snapshot history reads 88 percent buy a week ago and 72 percent buy a month ago. The short-horizon, medium-horizon and long-horizon groups each average 100 percent buy, and the composite trend indicator reads buy.
2.6 Volatility and Expected Range
The published 14-day average true range stands at 3.64 points and the 14-day average daily range at 3.65 points; the 9-day average true range is 3.77 with a 9-day average daily range of 3.70, and the 20-day average true range is 3.51 with a 20-day average daily range of 3.74. Tuesday's 6.12 point range was 1.68 times the 14-day average daily range.
Adding and subtracting the 14-day average true range of 3.64 points from the 97.82 settle frames Wednesday between 94.18 and 101.46. The published standard-deviation bands are built from five settlements: one deviation spans 95.77 to 99.87, two spans 94.92 to 100.72 and three spans 94.26 to 101.38. These bands describe settlement dispersion, not intraday reach, and a headline gap can open outside any of them.
3. Key Levels
3.1 Resistance
Above the 97.82 settle, the first overhead reference is the Pivot Point at 98.15, followed by Monday's 98.54 settle and the published target price at 98.79. One standard deviation resistance at 99.87 and Monday's 99.71 high come next, then the 3-10 day crossover stall level at 100.74, two standard deviations resistance at 100.72 and Pivot R1 at 101.04. Tuesday's 101.37 high, which is also the one-month, 13-week and 52-week high, sits beside three standard deviations resistance at 101.38, and Pivot R2 at 104.27 and Pivot R3 at 107.16 form the extended band.
3.2 Support
Beneath the settle sits one standard deviation support at 95.77, with the 38.2 percent retracement from the four-week high at 95.50 and the 9-day average crossing price at 95.35 next, just above Tuesday's 95.25 low. Pivot S1 at 94.92, which coincides with two standard deviations support at 94.92, and three standard deviations support at 94.26 follow, then the 50 percent retracement of the four-week range and the 14-3 day raw stochastic projection, both at 93.68. Pivot S2 at 92.03 and the 18-day average crossing price at 91.92 form the deeper band, with Pivot S3 at 88.80 the extended reference.
4. Macro Drivers
4.1 OPEC and Supply Policy (Quotas, Compliance, Saudi/Russia Signals)
No producer-group statement was carried on the feeds read for this review, so no quota or compliance change is asserted. The news feed carried at 4:24 PM ET an Iranian media report that Yemen's Houthis consider a ground attack on Saudi Arabia an option, and at 10:25 AM ET a Saudi-led coalition statement that it intercepted a drone over Riyadh. These are claims carried by the news feed rather than supply losses measured for this review.
On the Russian side, the feed carried at 11:26 AM ET a statement from the US Energy Secretary that Russian diesel, if it comes to the US, would likely go to New England, and at 1:47 PM ET a report that US envoys plan to visit Russia on October 21. At 2:49 PM ET to 2:57 PM ET it carried the President's remarks on Ukraine talks.
4.2 EIA and API Inventory (Crude Stocks, Gasoline, Distillates, Cushing, SPR)
The industry inventory survey printed after the settle: at 4:39 PM ET the news feed carried a crude draw of 4.93 million barrels against a forecast draw of 1.3 million and a prior draw of 11.21 million, at 4:40 PM ET a Cushing build of 0.936 million barrels, at 4:41 PM ET a gasoline draw of 2.577 million and at 4:45 PM ET a distillate draw of 2.6 million. The official weekly petroleum status report is scheduled for 10:30 AM ET on Wednesday, October 21, 2026, as the calendar lists it, and the news-feed calendar lists a forecast draw of 0.34 million barrels against a prior draw of 8.557 million.
4.3 Geopolitical Backdrop (Middle East, Iran, Russia/Ukraine, Venezuela)
The news feed carried at 10:36 AM ET an Iranian media report that a tanker violating regulations caught fire in the southern corridor of the Strait of Hormuz, and at 12:51 PM ET an Iranian media report that a supertanker carrying over 2 million barrels hit a sea mine and caught fire there; provider commentary said Iran reported three tankers struck mines on the southern route. At 3:38 PM ET the feed carried an Iranian general's statement that operational control of the strait is in the hands of Iran's armed forces, and at 11:43 AM ET the US Secretary of State's statement that oil moving through Hormuz is nearly equal to pre-war levels.
On diplomacy, the news feed carried at 10:11 AM ET a press report that a proposal presented by Pakistan's army chief received US approval and preliminary Iranian agreement, and at 11:12 AM ET a diplomat's statement that reports of a close deal are wrong. At 4:59 PM ET to 5:01 PM ET Iran's foreign minister said negotiations through Pakistan and Qatar continue and that the US wanted to add conditions. At 2:42 PM ET the President said he has to make a final decision on Iran. These are statements carried by the news feed rather than events confirmed for this review.
4.4 Demand and Refining (Refinery Utilization, Crack Spreads, Seasonal Pattern)
The November heating oil contract settled at 4.9250 dollars a gallon and the November gasoline contract at 3.1172, per the news feed at 2:31 PM ET. Pairing the November products with the November WTI final settle of 101.79, the heating oil margin, 42 gallons times the heating oil settle less the WTI settle, stands at 105.06 dollars a barrel against 102.98 on Monday, and the gasoline margin at 29.13 against 30.38.
On the December contracts in the provider's daily record, December heating oil settled at 4.7141 and December gasoline at 3.0441, which against the December WTI settle give margins of 100.17 and 30.03 dollars a barrel. Provider commentary said December gasoline fell 1.95 percent to a seven-week low. The November natural gas contract settled at 2.9630 per the news feed. No refinery utilisation figure and no seasonal demand series were captured, so neither is asserted.
4.5 Dollar and Cross-Asset (DXY, Commodities Complex, Equity Risk-On/Off)
The dollar index closed at 101.73 in the provider's daily record, down 0.25 from Monday's 101.98, after trading between 101.51 and 101.98. The ten-year yield index traded between 5.07 and 5.14 percent and closed at 5.12 percent against 5.13 percent on Monday. Housing starts printed at 8:30 AM ET at 1.221 million against a 1.305 million forecast and building permits at 1.400 million against 1.385 million, and pending home sales printed at 10:00 AM ET at minus 7.3 percent against minus 0.5 percent, all per the news-feed calendar.
Provider commentary tied part of the dollar's decline to the housing data and a stronger Chinese yuan. Gold's December contract settled at 4,142.6, down 0.42 percent, and the S&P 500 cash index closed at 7,712.57, up 0.28 percent. A softer dollar is a modest support for dollar-priced crude; the size of that effect is not measured here.
4.6 Institutional Positioning (COT, Money Manager and Commercial Hedger, Speculator Length)
No weekly positioning report was captured for this review, so no change in managed-money or producer length is asserted. Open interest on the December contract is shown at 308,314 for Monday in the provider's record, and Tuesday's open interest had not been reported at the time of capture; Tuesday's December volume was 363,268 contracts.
The curve read is the clearest positioning signal captured. The expiring November contract settled 3.97 above December, against 5.12 on Monday, so the front of the curve remained in backwardation while that spread narrowed. With November expired, December is now the front month.
5. No Liquid Options Proxy
This review covers crude without a positioning dataset. There is no dealer-positioning surface read for this instrument in this review, no gamma map, no options concentration levels and no flow attribution, and none is inferred from any other instrument. Every level in section 3 originates in published pivot arithmetic, published standard-deviation bands, published retracement and moving-average projections, settlement averages computed from the provider's daily record, or the completed-session extremes described in section 2.1.
This is a statement about coverage, not about the existence of listed crude options. No such dataset was read for this review, so no claim resting on one appears anywhere in this review or in this outlook. The positioning inputs used for crude are the Brent spread, the November to December spread, the product margins and the open-interest and volume record.
6. Forecast
6.1 Night Session (6:00 PM ET Tuesday to 3:00 AM ET Wednesday, Globex/Asia)
Globex reopened at 6:00 PM ET on Tuesday with December as the front month and quoted 98.15 at 6:20 PM ET, after the larger-than-forecast inventory draw in the 4:39 PM ET survey. The President is listed to speak at 7:00 PM ET and Japan's trade balance at 7:50 PM ET, both per the news-feed calendar and unconfirmed, and Gulf headlines remain the main overnight risk in both directions. Bias neutral above the Pivot Point at 98.15, expected Globex band roughly 96.40 to 99.60.
6.2 London Session (3:00 AM to 8:00 AM ET Wednesday)
UK consumer prices are listed at 2:00 AM ET and the Bank of England governor at 9:00 AM ET, both per the news-feed calendar and unconfirmed. Bias neutral, expected band roughly 96.00 to 99.90, with one standard deviation support at 95.77 the first meaningful support beneath and one standard deviation resistance at 99.87 the first meaningful resistance above.
6.3 Morning Session (9:00 AM to 12:00 PM ET Wednesday, US Open / Pit Session)
The official weekly petroleum status report prints at 10:30 AM ET on Wednesday, October 21, 2026, as the calendar lists it, and is the first-order scheduled event for crude. The volatility index options expiration is listed by the desk note at 9:30 AM ET, unconfirmed. Expected band roughly 95.30 to 100.70, with Pivot S1 at 94.92 beneath and two standard deviations resistance at 100.72 above.
6.4 Afternoon Session (12:00 PM to 2:30 PM ET Wednesday, NYMEX Pit Close)
The ECB president is listed at 12:00 PM ET and the 20-year Treasury auction at 1:00 PM ET, both per the news-feed calendar and unconfirmed, and crude settles at 2:30 PM ET. Expected band roughly 95.00 to 101.00.
6.5 Night Session Forward (6:00 PM ET Wednesday)
Globex reopens at 6:00 PM ET on Wednesday. A social-media company and a chipmaker are listed at 4:00 PM ET and an electric-vehicle maker at 4:15 PM ET, per the news-feed calendar and unconfirmed, with the calendar placing all three after the close without a confirmed time.
6.6 Expected Range (Wednesday Full Session)
Low-range scenario: 96.40 to 99.60
Mid-range scenario (most likely): 95.30 to 100.70
High-range scenario: 94.20 to 101.40
6.7 Most Likely Path
In this review's analyst judgment the most probable path holds the contract between Pivot S1 at 94.92 and Pivot R1 at 101.04, with a dip toward the 95.80 to 96.10 band that holds above that pivot level weighted slightly above a break lower. The settle remains above every settlement average from the 5-day to the 200-day, positive direction leads on both directional systems, the composite holds at 100 percent buy, and the after-settle inventory survey showed a crude draw larger than forecast.
The alternative that would invalidate this reading is confirmation of the mediation proposal between Washington and Tehran, which would remove part of the supply premium and carry the contract beneath Pivot S1 at 94.92 toward three standard deviations support at 94.26. Tuesday's outside day settled in the lower half of a 6.12 point range, and %K sits beneath %D, so a further pullback before any extension is a live alternative.
7. Wednesday Economic Calendar
Tuesday's releases are complete. Housing starts and building permits printed at 8:30 AM ET on Tuesday at 1.221 million and 1.400 million, per the news-feed calendar, and pending home sales printed at 10:00 AM ET at minus 7.3 percent. Crude settled at 2:30 PM ET, and the industry inventory survey printed at 4:39 PM ET with a crude draw of 4.93 million barrels.
On Tuesday evening the President is listed to speak at 7:00 PM ET and Japan's trade balance at 7:50 PM ET, both per the news-feed calendar and unconfirmed. On Wednesday UK consumer prices are listed at 2:00 AM ET, with a 3.4 percent forecast on the news-feed calendar, and the Bank of England governor at 9:00 AM ET, both unconfirmed. The volatility index options expiration is listed by the desk note at 9:30 AM ET, unconfirmed. The official weekly petroleum status report prints at 10:30 AM ET on Wednesday, October 21, 2026, as the calendar lists it. The ECB president is listed at 12:00 PM ET and the 20-year Treasury auction at 1:00 PM ET, per the news-feed calendar and unconfirmed. Crude settles at 2:30 PM ET.
Later in the window, a social-media company and a chipmaker are listed at 4:00 PM ET and an electric-vehicle maker at 4:15 PM ET on the news-feed calendar and unconfirmed, with the calendar placing them after Wednesday's close without a confirmed time. Weekly jobless claims are listed at 8:30 AM ET on Thursday per the news-feed calendar and unconfirmed, and the FOMC statement is scheduled for 2:00 PM ET on Wednesday, October 28, 2026, as the calendar lists it. In this review's judgment the first-order scheduled event for crude on Wednesday is the 10:30 AM ET weekly petroleum status report, with Gulf headlines the unscheduled risk.
8. Primary Trade Setup
Direction: Long
Rationale: The settle remains above every settlement average from the 5-day to the 200-day, positive direction leads on the 9-day and 14-day directional systems, the composite holds at 100 percent buy, and the after-settle inventory survey showed a crude draw of 4.93 million barrels against a 1.3 million forecast. A dip into one standard deviation support at 95.77 offers a long with a defined risk point beneath Pivot S1 at 94.92. Tuesday's outside day settled in the lower half of its range and a mediation proposal remains open, so the setup is an analyst judgment that dips are bought while supply headlines persist, not a measured edge.
Entry Zone: 95.80 to 96.10
Stop Loss: 94.70 (beneath Pivot S1 at 94.92 and two standard deviations support at 94.92)
Target 1 (T1): 97.20 (62 cents beneath Tuesday's 97.82 settle)
Target 2 (T2): 98.45 (above the Pivot Point at 98.15)
Target 3 (T3, extended): 99.70 (beneath one standard deviation resistance at 99.87)
Risk-to-Reward: Approximately 1:1 to T1, 1:2 to T2, 1:3 to T3
Invalidation: A settle beneath Pivot S1 at 94.92 negates the thesis. Short of that, the edge is removed by acceptance beneath the entry band rather than by a touch, defined as two consecutive 30-minute closes beneath 95.80.
Macro override: Confirmation of the mediation proposal between Washington and Tehran, or a verified reopening of Strait of Hormuz traffic, would remove part of the supply premium. In that scenario a move through the 94.70 stop invalidates the long before the targets, and three standard deviations support at 94.26 and the 93.68 retracement become the references within one 14-day average true range of 3.64 points of the stop.
Sources and methodology
This outlook is built from our session review of the December WTI crude contract (CLZ26), prepared after Tuesday's close on October 20, 2026 for the Wednesday, October 21, 2026 session. The November contract expired on Tuesday, and December, which the chart's continuous symbol tracks, is the front month. Tuesday's completed extremes are the inputs behind the published pivot ladder: Pivot R3 at 107.16 less Pivot S3 at 88.80, divided by three, and Pivot R2 at 104.27 less Pivot S2 at 92.03, divided by two, both return 6.12, and three times the 98.15 Pivot Point less the 97.82 settle gives 196.63, which the 101.37 high and 95.25 low reproduce at 196.62 to the published rounding. The provider's settlement row and the chart's completed Tuesday bar carry the same extremes. No intraday series was preserved for Tuesday, so no timed price path is asserted, and no price move is tied to a headline except where provider commentary is quoted as its own account.
Tuesday's card was written on the December contract and is graded only on the provider's December settlement row for 10/20 (open 98.24, high 101.37, low 95.25, settle 97.82, volume 363,268). The daily bar fixes the open, the extremes and the settle, so the order of events within Tuesday cannot be shown, and the card's 30-minute acceptance condition and its session bands are not graded.
The moving averages were computed from the provider's 259-session daily settlement series for December; the oscillators are cited as published, read at 6:20 PM ET after the reopen. Tuesday's volume and the open-interest figures equal the provider's dated rows. Monday's 10/19 row has been revised: December volume now reads 319,879 against the 288,743 cited in Tuesday's outlook, and open interest, not reported then, reads 308,314. Tuesday's open interest had not been reported. No weekly positioning report was captured. No dealer-positioning dataset was read for crude; the positioning inputs are the Brent spread, the November to December spread, the product margins and the open-interest and volume record. The macro override's one average true range is measured from the stop: 94.26 sits 44 cents and 93.68 sits 1.02 beneath 94.70. Scenario ranges are analyst judgment, and items marked unconfirmed come from the news-feed calendar or the desk note.
Tuesday’s outlook for this contract is here, and the gold contract’s Tuesday outlook covers the metal whose December contract settled at 4,142.6 on Tuesday, down 0.42 percent. Outlooks for ES, NQ, GC and CL are collected on the market outlook page, and our forward trading record is on the performance statement.