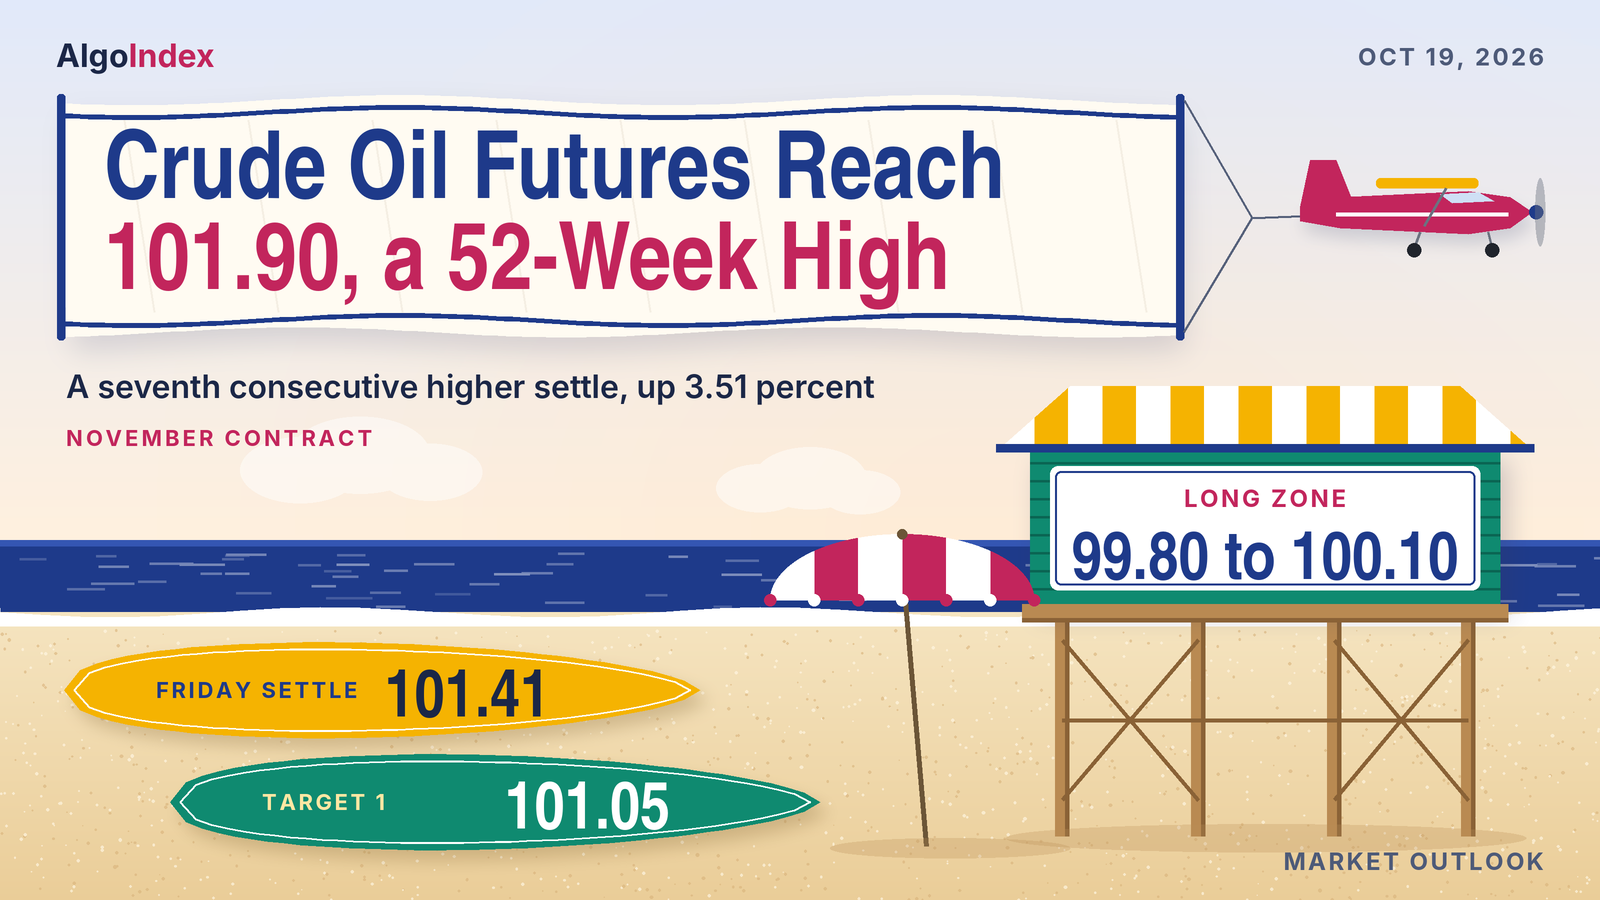
At 2:30 PM ET on Friday, the November crude contract settled at 101.41, up 3.44 or 3.51 percent. It was the seventh higher settle in a row. The session ran from 96.85 to 101.90, a 5.05 point range, and the 101.90 high is a new 52-week high on the provider's overview, 21 cents above the 101.69 high of 09/15. The 3.44 gain was the largest since the 3.61 gain of 09/15. Over the week the contract rose 9.56 points.
Friday's card never came into play. The long from 96.40 to 96.70 waited beneath a market that dipped early and then left. The 96.85 low, in the 4:30 AM ET bar, held 15 cents above the band's top, so the band never traded.
The advance came in the afternoon. In the 30-minute bars the 11:00 AM ET bar closed at 97.90, and the 11:30 AM ET bar traded up to 99.07 and closed at 99.01. The 12:00 PM ET bar closed at 99.93. The 12:30 PM ET bar reached 101.02. Provider commentary said prices rose to their highs on Friday afternoon after US lawmakers introduced a bill to block a deal with Russia to release several hundred million barrels of diesel fuel. That is the commentary's account. The 101.90 high itself printed in the 4:00 PM ET bar, after the settlement.
November crude settled at 101.41, up 3.44, at 90.3 percent of a 96.85 to 101.90 range. It sits above all six settlement averages. Resistance starts at Friday's 101.90 high, then the 102.01 relative strength projection, Pivot R1 at 103.26 and the 103.54 target price. Support starts at the Pivot Point at 100.05, inside the new band, then the 98.89 stochastic projection, Pivot S1 at 98.21 and one deviation support at 98.19, with Thursday's 97.97 settle beneath. The setup is a long. It runs from 99.80 to 100.10, stop 98.85, targets 101.05, 102.15 and an extended 103.25. The whole band sits beneath the settle, its top 1.31 under it, and the first target sits 36 cents beneath the settle too. Globex reopens at 6:00 PM ET on Sunday. The November contract expires on 10/20/26, per the provider.
Friday's low stopped 15 cents above the band, which never traded
First, the grading. In Friday's outlook we set a long from 96.40 to 96.70, stop 95.60, with targets at 97.50, 98.45 and an extended 99.40. The band wrapped the Pivot Point at 96.62. A settle beneath one standard deviation support at 95.73 would negate it. Two consecutive 30-minute closes beneath 96.40 would remove the edge.
Then Friday traded. Its bar, from the review, opened at 97.55 at the Thursday 6:00 PM ET reopen, 85 cents above the band's top, marked a high of 101.90 and a low of 96.85, and settled at 101.41 at 2:30 PM ET. The dip came early. It fell short. The 30-minute bars place the 96.85 low in the 4:30 AM ET bar, which closed at 97.00. That low sat 15 cents above the band's top and 45 cents above its bottom. No bar traded inside the band.
So the card never came into play. The 95.60 stop stayed 1.25 beneath the low, and the 95.73 invalidation line 1.12 beneath it. The acceptance rule never came close. The lowest 30-minute close was 96.96, in the 5:00 AM ET bar, 56 cents above 96.40. No fill and no result is asserted.
The target levels traded anyway. The 97.50 first target sat inside the first bar, which ran from 97.40 to 97.90. The 98.45 second target first traded in the 7:30 AM ET bar, which reached 98.50. The extended target took longer. The 11:30 AM ET bar stopped 33 cents short of 99.40 at 99.07, and the 12:00 PM ET bar reached 100.01. The settle finished 2.01 above 99.40. None of those prints came after the band traded, because it never did.
Our ranges held the low and gave way at the top. The high-range case of 94.10 to 101.90 contained the session, its bottom 2.75 beneath the low, and the 101.90 high matched its top exactly. The narrower ones broke high. The most likely case of 95.70 to 100.20 held the low by 1.15 and gave way by 1.70. The one deviation band of 95.73 to 100.21 gave way by 1.69. The low-range case of 96.40 to 99.70 held the low by 45 cents and broke at the top by 2.20.
Session by session, the early bands held. From the 6:00 PM ET reopen to 3:00 AM ET the bars ranged 97.02 to 97.90, inside the 96.60 to 98.40 Globex band by 42 and 50 cents. London's bars, 3:00 AM to 8:00 AM ET, ran 96.85 to 98.50, inside 96.40 to 98.60 with 10 cents to spare at the top. The morning held too. Its bars from 9:00 AM ET to 12:00 PM ET ran 97.20 to 99.07, inside 95.70 to 99.70. The afternoon broke. Its bars into the settle ran 98.95 to 101.53, 1.33 above the top of 95.70 to 100.20.
The weighted path expected a hold between one standard deviation support at 95.73 and one standard deviation resistance at 100.21, with a dip toward the band holding above 95.73. The dip came within 15 cents. It held by 1.12. The high then ran 1.69 through 100.21. The named alternative, a move through Pivot S1 at 94.93 toward Thursday's 93.58 low, did not come, and the low stayed 1.92 above 94.93. The card's macro override named a firmer dollar after import prices; the dollar index closed 0.16 lower, at 101.84.
The 99.80 to 100.10 band and the Pivot Point at 100.05
The map moved up again. The new band wraps the Pivot Point at 100.05, 25 cents above its bottom and 5 cents beneath its top. The 98.89 stochastic projection sits 91 cents beneath the band. The stop at 98.85 sits 4 cents under that projection, 64 cents above Pivot S1 at 98.21 and 66 cents above one standard deviation support at 98.19. The settle sits 1.31 above the band's top and 1.61 above its bottom. Friday's 96.85 low sits 2.95 beneath the band.
The last bars ran higher. After the settle the 2:30 PM ET bar traded up to 101.82, the 4:00 PM ET bar marked the 101.90 high and the 4:30 PM ET bar closed at 101.84, 43 cents above the settle. Those quotes are not the settlement. Globex closed at 5:00 PM ET and reopens at 6:00 PM ET on Sunday, October 18, 2026, so two days of headline exposure separate the settle from the next print.
Resistance starts 49 cents up. Friday's 101.90 high, also the one-month, 13-week and 52-week high, is the first reference, then the 14-day relative strength projection at 70 percent at 102.01, 60 cents above the settle. Pivot R1 at 103.26 and the published target price at 103.54 come next, 1.85 and 2.13 above the settle. One deviation resistance at 104.63 and Pivot R2 at 105.10 follow. The extended band holds the 105.40 top of one average true range, two deviations resistance at 105.96, three deviations resistance at 106.98 and the 3-10 day crossover stall level at 107.04. Pivot R3 at 108.31 lies beyond.
Support starts 1.36 down at the Pivot Point. The 98.89 stochastic projection comes next, then Thursday's 98.32 high, then Pivot S1 at 98.21 and one deviation support at 98.19, 2 cents apart. Thursday's 97.97 settle follows. Then a tight band. The 97.42 bottom of one average true range, the 97.39 stochastic projection and the 14-day %K stall level at 97.11 sit within 31 cents, with two deviations support at 96.86 and Friday's 96.85 low beneath. The deeper band follows. The 5-day average at 96.47, the 96.15 retracement from the four-week high, three deviations support at 95.84 and Pivot S2 at 95.00 make it up. The 50 percent retracement at 94.38, the 9-day crossing at 94.25, the 9-day average at 93.71, Thursday's 93.58 low, 93.20, the top of last week's span, and Pivot S3 at 93.16 come next. Then the long tail. The 18-day crossing at 92.72, the 92.61 retracement from the four-week low, the 20-day at 92.56, the 40-day crossing at 91.36 and the 90.50 retracement from the 13-week high lie further down. This week's 89.61 low, the 50-day at 89.13, last week's 86.86 low, the 100-day at 82.67, the 200-day at 76.81 and the 72.05 13-week low sit far beneath.
Every average sits beneath price. The settle is 4.94 above the 5-day at 96.47, 7.70 above the 9-day at 93.71, 8.85 above the 20-day at 92.56 and 12.28 above the 50-day at 89.13. The gaps to the 100-day at 82.67 and the 200-day at 76.81 are 18.74 and 24.60. The 5-day rose 1.91 from 94.56 as the 10/09 settle of 91.85 left the window and 101.41 replaced it. The 20-day rose 27 cents from 92.30 as the 09/18 settle of 96.08 left, and the 50-day rose 53 cents from 88.60. The order holds. The 30 older settlements in the 50-day window averaged 86.85, and the 50 older settlements in the 100-day window 76.20. Monday's crossing prices are 94.25 for the 9-day, 92.72 for the 18-day and 91.36 for the 40-day.
Momentum is stretched. Relative strength reads 76.20 on the 9-day, 69.23 on the 14-day and 65.71 on the 20-day. Both raw stochastics read 96.74 percent, and the 14-day %K at 92.90 percent sits above %D at 84.65 percent, near the top of the range. Positive direction leads on both windows. It reads 33.12 against 7.21 on the 9-day with the ADX at 31.29, and 29.54 against 9.50 on the 14-day with the ADX at 27.19. Historic volatility reads 22.78 percent and 33.42 percent. The composite multi-indicator read rose to 100 percent buy from 96, with signal strength described as maximum and direction as strongest; it read 32 percent buy a week ago and 100 percent a month ago. All three horizon groups average 100 percent buy. The trend indicator reads buy. These readings were published on the provider's technical page for the Friday session, with no new session open, so the page reflects the settle.
Friday ran wide. The 14-day average true range stands at 3.99 points, shown as 3.94 percent on the provider's page, and the 14-day average daily range also at 3.99. Friday's 5.05 was 1.27 times that, the widest since the 5.62 point range of 10/02. The 9-day figures are 4.02 and 3.65 and the 20-day 3.90 and 4.27. One average true range either side of the settle spans 97.42 to 105.40, and the deviation bands, built from five settlements, run 98.19 to 104.63, 96.86 to 105.96 and 95.84 to 106.98. They describe settlement dispersion only. A weekend gap can open outside any of them. Eight sessions of daily ranges read 3.02, 4.43, 2.16, 4.75, 3.41, 2.09, 4.74 and 5.05. Last week, October 5 through October 9, spanned 86.86 to 93.20, and this week spanned 89.61 to 101.90. The daily bar left an upper shadow of 49 cents above the settle and a lower shadow of 70 cents beneath the 97.55 open. Friday's high sat 3.58 above Thursday's 98.32. Its low sat 3.27 above Thursday's 93.58.
A reserve offer, Hormuz statements and a softer dollar
Supply headlines came first. At 10:27 AM ET the news feed carried that the United States offers as much as 17 million barrels of crude from the Strategic Petroleum Reserve. The 10:00 AM ET bar, which contains that headline, traded down to 97.20 and closed at 97.37, and the contract then rose through the afternoon. No cause is asserted. At 11:34 AM ET the feed carried a sourced report that a primary unit at Russia's Ryazan refinery has been halted since the October 15 drone attack.
Diesel came next. Provider commentary said prices rose to their highs on Friday afternoon after US lawmakers introduced a bill to block a deal with Russia to release several hundred million barrels of diesel fuel. These are statements carried by the news feed and provider commentary rather than volumes measured for this review. The 17 million barrel reserve offer carried at 10:27 AM ET adds to the reserve releases reported earlier in the week. No producer-group statement was carried on the feeds read, so no quota or compliance change is asserted.
Hormuz statements followed. At 2:09 PM ET the news feed carried a US statement that about 400 merchant vessels went through the Strait of Hormuz in the past seven days. At 2:10 PM ET it carried that the US has helped move more than 100 million barrels through the strait in that period. Both figures are US statements. At 2:11 PM ET it carried a statement by the US regional commander that Iran has no maritime exports or imports because of the US naval blockade. Provider commentary said more than 40 vessels moved through the strait over the past 24 hours. Then Aden. At 2:56 PM ET the feed carried Iranian media reports that three missiles were fired at the Aden airport, and at 3:15 PM ET reports of explosions in Aden. At 3:58 PM ET it carried Iranian media reports of explosions in Damascus.
Two items came after the settle. At 4:30 PM ET the feed carried press reports citing the US regional commander that Iran-backed militias are sending money back to Iran's revolutionary guard, and at 4:44 PM ET the President's remark that Iran will be over very soon. These are statements carried by the news feed rather than events confirmed for this review. Provider commentary attributed Friday's strength to a weaker dollar and to concern that escalating hostilities in the Middle East could disrupt regional supplies, and cited investment-bank commentary estimating a 24 dollar a barrel risk premium. That is the commentary's account.
The dollar eased. The dollar index closed at 101.84 in the provider's daily record, down 0.16 from Thursday's 102.00, after trading as low as 101.58. Provider commentary said the dollar fell after the Federal Reserve Chair gave no guidance on policy in a speech at the annual International Monetary Fund meeting, which reduced the priced chance of a rate increase this month to 13 percent from 27 percent. Yields edged up. The ten-year yield index traded between 5.07 and 5.13 percent and closed at 5.10 percent against 5.08 percent on Thursday.
The data came in above forecast. September import prices rose 1.1 percent at 8:30 AM ET against a 1.0 percent forecast, per the news-feed calendar, and industrial production rose 0.7 percent at 9:15 AM ET against a 0.4 percent forecast, per the news-feed calendar; the calendar lists both releases. The 8:30 AM ET bar, which contains the import price release, traded between 97.38 and 97.71 and closed at 97.55. A weaker dollar is a supportive input for dollar-priced crude; the size of that effect is not measured here.
Products rose less than crude. The November heating oil contract settled at 4.8991 dollars a gallon, up 0.0535, and November gasoline at 3.2354, up 0.0552 or 1.74 percent, per the news feed at 2:32 PM ET and the provider. On settlement arithmetic the heating oil margin stands at 104.35 dollars a barrel against 105.55 on Thursday, and the gasoline margin at 34.48 against 35.60. Both narrowed slightly. Per barrel, heating oil rose 2.25 and gasoline 2.32 while crude rose 3.44. The November natural gas contract settled at 3.116, down 0.120. No refinery utilisation figure and no seasonal demand series were captured.
Thursday's official report still frames stocks. The most recent weekly petroleum status report printed at 12:00 PM ET on Thursday, October 15, 2026. The news feed carried a crude draw of 8.557 million barrels against a forecast build of 0.15 million, with gasoline up 3.518 million barrels, distillates down 2.527 million and Cushing up 1.862 million. The captured calendars carry no official inventory report for Friday. The calendar lists the next one at 10:30 AM ET on Wednesday, October 21, 2026.
Brent ran harder. December Brent settled at 109.86, up 3.94 or 3.72 percent, widening its premium over November WTI to 8.45 from 7.95. The front spread widened too. December WTI settled at 99.02, so November sits 2.39 above it, against 1.47 on Thursday, and the front of the curve remained in backwardation. Elsewhere, the S&P 500 cash index closed at 7,659.44, down 1.09 percent, and December gold settled at 4,181.1, up 0.26 percent.
Positioning lags the move. The weekly positioning report shown on the provider's overview, as of October 13, 2026, puts managed-money longs at 171,973 contracts, down 6,380, and managed-money shorts at 131,399, up 6,644, so managed-money net length narrowed to 40,574 contracts. Producer longs rose 42,215 to 660,971 and producer shorts rose 24,082 to 307,828. The report predates the 7.27 point rise in the November contract over the three sessions through Friday.
Roll activity continues. The November contract expires on 10/20/26, per the provider, with first notice on 10/22/26, so Monday is the second to last session for November. Liquidity has moved to December, and the chart's continuous symbol already tracks December, so every level here is read on the November contract itself. Friday's volume was 81,673 contracts in November against 304,249 in December. Open interest reads 84,922 for Thursday, down from 113,474 on Wednesday. Friday's figure was not yet reported. December's open interest stood at 309,217 on Thursday. No dealer-positioning dataset was read for crude.
The trade map for Monday
The review's setup is a long. It runs from 99.80 to 100.10. Friday settled at 90.3 percent of its range for a seventh consecutive higher settle and a new 52-week high, and the settle sits above every settlement average from the 5-day to the 200-day. Positive direction leads on the 9-day and 14-day directional systems, and the composite reached 100 percent buy with strength described as maximum. That is the trend case. The band wraps the Pivot Point at 100.05, with the 98.89 stochastic projection 91 cents beneath its bottom. The stop sits at 98.85, beneath that projection, with targets at 101.05, 36 cents beneath Friday's 101.41 settle, 102.15, 25 cents above Friday's 101.90 high, and an extended 103.25, 1 cent beneath Pivot R1 at 103.26. Two caveats sit against it. The 9-day relative strength reads 76.20, and two weekend days of headlines separate the settle from the reopen. The review calls the setup an analyst judgment that dips are bought while supply headlines persist, not a measured edge.
Now the arithmetic. From the 99.95 midpoint the risk to the stop is 1.10, 27.6 percent of the 14-day average true range of 3.99. The targets sit 1.10, 2.20 and 3.30 above the midpoint. Exact multiples, on paper. The whole band sits beneath the settle, its top 1.31 and its bottom 1.61 under it. The 101.05 first target sits 36 cents beneath the settle itself and 95 cents above the band's top. A weekend gap can open through the stop.
Scenario ranges in the review are analyst judgment. The low-range case runs 99.00 to 102.80, the most likely 98.20 to 103.60 and the high-range case 96.80 to 105.40. Then by session. Through Globex the review's judgment expects roughly 99.20 to 102.60 absent a weekend shock, with a neutral to higher bias above the Pivot Point at 100.05. A gap above 101.90 opens the way toward 102.01 and Pivot R1 at 103.26. A gap beneath 100.05 brings Pivot S1 at 98.21 and Thursday's 97.97 settle into view. London follows at roughly 99.00 to 102.80. The band is its first meaningful support and Friday's 101.90 high its first meaningful resistance. The morning band runs 98.20 to 103.30, with Pivot R1 at 103.26 the first meaningful resistance above Friday's high. The afternoon runs 97.90 to 103.60 into the 2:30 PM ET settle.
Monday's calendar starts on Sunday evening. Globex reopens at 6:00 PM ET on Sunday, October 18, 2026, and China's third-quarter growth, industrial output and retail sales figures are listed at 10:00 PM ET, per the news-feed calendar and unconfirmed. A European Central Bank board member is listed at 1:50 AM ET Monday, per the news-feed calendar and unconfirmed. Then North America. Canadian consumer prices are listed at 8:30 AM ET and the homebuilder sentiment index at 10:00 AM ET, both per the news-feed calendar and unconfirmed, with a forecast of 31 for the homebuilder index. Crude settles at 2:30 PM ET. November enters its final session on Tuesday after this settle, and Globex reopens for it at 6:00 PM ET on Monday. The November contract expires on 10/20/26, per the provider. The calendar lists housing starts at 8:30 AM ET on Tuesday, October 20, 2026, and the next weekly petroleum status report at 10:30 AM ET on Wednesday, October 21, 2026.
The review also weighs the path. In the review's analyst judgment the most probable path holds the contract between one standard deviation support at 98.19 and Pivot R1 at 103.26, with weekend headlines deciding the side of the open. A dip toward the 99.80 to 100.10 band that holds above 98.89 is weighted above a break lower in that judgment. It names an alternative. A de-escalation headline over the weekend, consistent with the President's remark that Iran will be over very soon, or progress on Russian diesel supply, would open the contract beneath Pivot S1 at 98.21 and carry it toward Thursday's 97.97 settle. The review reads the contract as extended, with the 9-day relative strength at 76.20 and an 8.85 point gap to the 20-day average, so a pullback before any extension is a live alternative. Headlines lead. In the review's judgment the first-order influence on crude on Monday is the weekend's Gulf, Red Sea and Russian diesel headlines, priced at the 6:00 PM ET Sunday reopen, with the November expiry on Tuesday shaping liquidity.
Friday's dip stopped 15 cents short of the old band; Monday's band sits 1.31 beneath the settle.
The complete data picture
Every number behind Monday’s plan, charted first, then the full level lists, then the complete numeric reference underneath.
Full numeric reference, every remaining figure from the session review
1. Executive Summary
The November crude contract settled at 101.41 on Friday, up 3.44 or 3.51 percent from Thursday's settle of 97.97, after trading between 101.90 and 96.85, a 5.05 point daily range. The settle finished at 90.3 percent of the range, and the 5.05 point range was 1.27 times the published 14-day average daily range of 3.99 points. Friday printed a higher high and a higher low against Thursday, and the settle was the seventh consecutive higher settle for the November contract.
The 101.90 high is the new 52-week high on the provider's overview, above the prior 52-week high of 101.69 set on 09/15. The 3.44 point gain was the largest since the 3.61 point gain of 09/15, and the 5.05 point range the widest since the 5.62 point range of 10/02. Over the week the contract rose 9.56 points from last Friday's 91.85 settle, matching the provider's five-day change of plus 9.56, or plus 10.41 percent.
The advance came in the afternoon. In the recorded 30-minute series the 11:00 AM ET bar closed at 97.90, the 11:30 AM ET bar traded up to 99.07 and closed at 99.01, the 12:00 PM ET bar closed at 99.93 and the 12:30 PM ET bar traded up to 101.02. The news feed recorded the settlement at 101.41 at 2:31 PM ET, and the session high of 101.90 printed in the 4:00 PM ET bar, after the settlement.
Brent's December contract settled at 109.86, up 3.94, so Brent's premium over November WTI widened to 8.45 from 7.95. The December WTI contract settled at 99.02, leaving November 2.39 above December against 1.47 on Thursday. The dollar index closed at 101.84, down 0.16, and the ten-year yield index closed at 5.10 percent against 5.08 percent on Thursday.
Globex reopens at 6:00 PM ET on Sunday, so two days of headline exposure separate Friday's settle from the next print. The published 14-day average true range is 3.99 points, shown as 3.94 percent on the provider's page. The November contract expires on 10/20/26, per the provider, so Monday is the second to last session for November. The Primary Setup below is a long from the 99.80 to 100.10 band around the Pivot Point at 100.05, stopped at 98.85 beneath the 14-3 day raw stochastic projection at 98.89, with objectives at 101.05, 102.15 and an extended 103.25.
2. Price Action & Technical Structure
2.1 Intraday and Session Review
The Friday session opened at 97.55 at the Thursday 6:00 PM ET reopen, 42 cents beneath Thursday's settle, marked a daily high of 101.90 and a daily low of 96.85, and settled at 101.41 at 2:30 PM ET. The recorded 30-minute series for the session places the session low of 96.85 in the 4:30 AM ET bar, which closed at 97.00, and the session high of 101.90 in the 4:00 PM ET bar, which closed at 101.65.
The 7:30 AM ET bar traded up to 98.50 and closed at 98.12, and the 8:00 AM ET bar closed at 97.48. The 8:30 AM ET bar, which contains the import price release, traded between 97.38 and 97.71 and closed at 97.55. The 10:00 AM ET bar traded down to 97.20 and closed at 97.37, and the 11:00 AM ET bar closed at 97.90. The 11:30 AM ET bar traded between 97.70 and 99.07 and closed at 99.01, the 12:00 PM ET bar closed at 99.93, the 12:30 PM ET bar traded up to 101.02 and closed at 100.75, and the 2:00 PM ET bar traded up to 101.53 and closed at 101.40.
The news feed recorded the NYMEX settlement at 101.41, up 3.44, at 2:31 PM ET. After the settle the 2:30 PM ET bar traded up to 101.82, the 4:00 PM ET bar marked the 101.90 high and the 4:30 PM ET bar closed at 101.84; those post-settlement quotes are not used as the settlement anywhere in this review. Friday's Globex session ends at 5:00 PM ET and does not reopen until 6:00 PM ET on Sunday, so the provider's displayed open, high and low of 97.55, 101.90 and 96.85 belong to the completed Friday session.
The session extremes are also the completed-session inputs behind the published pivot ladder for Monday, back-solved from the outer pivot pairs and verified against every rung. Pivot R3 at 108.31 minus Pivot S3 at 93.16, divided by three, returns 5.05, and Pivot R2 at 105.10 minus Pivot S2 at 95.00, divided by two, returns the same 5.05. Three times the Pivot Point of 100.05 less the 101.41 settle gives a high plus low sum of 198.74, which the pair of 101.90 and 96.85 reproduces to the published rounding at 198.75, and that pair reproduces all seven published rungs.
Independent corroboration: the provider's settlement row, the provider's overview, the chart's completed Friday daily bar on the explicit November symbol and the extremes of the recorded 30-minute series carry the same 101.90 high and 96.85 low.
2.2 Daily Structure
Friday printed a higher high and a higher low against Thursday: the 101.90 high sits 3.58 points above Thursday's 98.32, and the 96.85 low sits 3.27 points above Thursday's 93.58. The settle at 90.3 percent of the range leaves an upper shadow of 49 cents above the settle and a lower shadow of 70 cents beneath the 97.55 open on the daily bar.
The sequence of session highs over the last six sessions reads 92.17, 94.36, 95.11, 96.06, 98.32 and 101.90, and the sequence of session lows reads 90.01, 89.61, 91.70, 93.97, 93.58 and 96.85. Settlements over the last seven sessions ran 91.49, 91.85, 93.74, 94.14, 95.09, 97.97 and 101.41, each above the one before.
Last week, October 5 through October 9, spanned 93.20 to 86.86, and this week spanned 101.90 to 89.61. The one-month high, 13-week high and 52-week high now all sit at Friday's 101.90, 49 cents above the settle. The 13-week low of 72.05 and the one-month low of 86.86 frame the lower side.
No prior-quarter high or low was captured for this review, so the 13-week extremes serve as the available quarterly reference: 101.90 above and 72.05 beneath.
2.3 4-Hour and Swing Structure
Daily ranges for the last eight sessions ran 3.02, 4.43, 2.16, 4.75, 3.41, 2.09, 4.74 and 5.05. The settlement changes over the same eight sessions read minus 1.16, plus 3.21, plus 0.36, plus 1.89, plus 0.40, plus 0.95, plus 2.88 and plus 3.44.
The retracement grid published for Monday places the 38.2 percent retracement from the four-week high at 96.15, 5.26 points beneath the settle, and the 50 percent retracement of the four-week range at 94.38. Further beneath, the 38.2 percent retracement from the four-week low sits at 92.61 and the 38.2 percent retracement from the 13-week high at 90.50. No four-hour series was captured for this review, so swing structure here rests on daily bars and the recorded 30-minute session.
2.4 Moving Averages
The averages cited in this subsection were computed for this review from the provider's daily settlement series for the November contract, which holds 260 completed sessions through Friday. The 5-day average stands at 96.47, the 9-day at 93.71, the 20-day at 92.56, the 50-day at 89.13, the 100-day at 82.67 and the 200-day at 76.81.
The 101.41 settle sits 4.94 points above the 5-day average, 7.70 points above the 9-day, 8.85 points above the 20-day and 12.28 points above the 50-day. The 5-day average rose 1.91 from Thursday's 94.56, because the 10/09 settle of 91.85 left the window and was replaced by 101.41. The 20-day rose 27 cents from 92.30, because the 09/18 settle of 96.08 left that window, and the 50-day rose 53 cents from 88.60.
The 20-day average sits above the 50-day because the last 20 settlements averaged 92.56 against 89.13 for the full 50, which means the 30 older settlements in the 50-day window averaged lower, at 86.85. The 50-day sits above the 100-day because the 50 older settlements in the 100-day window averaged lower, at 76.20. The projection grid gives the prices at which each average would be crossed on Monday: 94.25 for the 9-day, 92.72 for the 18-day and 91.36 for the 40-day.
2.5 Oscillator and Trend Readings
The oscillator figures below are as published on the provider's technical page dated for the Friday session. The Friday Globex session had closed and no new session had opened at the time of capture, so the page reflects the settle; they remain the provider's published readings rather than this review's computations. The 9-day relative strength reads 76.20, the 14-day relative strength 69.23 and the 20-day relative strength 65.71.
The 9-day raw stochastic and the 14-day raw stochastic both read 96.74 percent, while the 14-day stochastic %K reads 92.90 percent and the 14-day stochastic %D 84.65 percent, so %K sits above %D near the top of the range.
The 9-day directional index ADX reads 31.29 with the 9-day +DI at 33.12 and the 9-day -DI at 7.21; the 14-day directional index ADX reads 27.19 with the 14-day +DI at 29.54 and the 14-day -DI at 9.50, so positive direction leads on both and the 9-day ADX reads above the 14-day. The 9-day historic volatility reads 22.78 percent and the 14-day historic volatility 33.42 percent.
The composite multi-indicator read published for the Friday session is 100 percent buy, up from 96 percent buy in the prior session's snapshot, with signal strength described as maximum and direction as strongest. The snapshot history reads 32 percent buy a week ago and 100 percent buy a month ago. The short-horizon, medium-horizon and long-horizon groups each average 100 percent buy, and the composite trend indicator reads buy.
2.6 Volatility and Expected Range
The published 14-day average true range stands at 3.99 points and the 14-day average daily range at 3.99 points; the 9-day average true range is 4.02 with a 9-day average daily range of 3.65, and the 20-day average true range is 3.90 with a 20-day average daily range of 4.27. Friday's 5.05 point range was 1.27 times the 14-day average daily range.
Adding and subtracting the 14-day average true range of 3.99 points from the 101.41 settle frames Monday between 97.42 and 105.40. The published standard-deviation bands are built from five settlements: one deviation spans 98.19 to 104.63, two spans 96.86 to 105.96 and three spans 95.84 to 106.98. These bands describe settlement dispersion, not intraday reach, and a weekend gap can open outside any of them.
3. Key Levels
3.1 Resistance
Above the 101.41 settle, Friday's 101.90 high, which is also the one-month, 13-week and 52-week high, is the first reference, followed by the 14-day relative strength projection at 70 percent at 102.01. Pivot R1 at 103.26 and the published target price at 103.54 come next, followed by one standard deviation resistance at 104.63 and Pivot R2 at 105.10. Two standard deviations resistance at 105.96, three standard deviations resistance at 106.98 and the 3-10 day crossover stall level at 107.04 form the extended band, with Pivot R3 at 108.31 beyond.
3.2 Support
Beneath the settle sits the Pivot Point at 100.05, with the 14-3 day raw stochastic projection at 98.89 next and Pivot S1 at 98.21 and one standard deviation support at 98.19 beneath it. Thursday's 97.97 settle, the 14-3 day raw stochastic projection at 97.39 and the 14-day %K stall level at 97.11 follow, then two standard deviations support at 96.86 and Friday's 96.85 low. The 38.2 percent retracement from the four-week high at 96.15, three standard deviations support at 95.84 and Pivot S2 at 95.00 form the deeper band, with the 9-day average crossing price at 94.25 and Pivot S3 at 93.16 the extended references.
4. Macro Drivers
4.1 OPEC and Supply Policy (Quotas, Compliance, Saudi/Russia Signals)
No producer-group statement was carried on the feeds read for this review, so no quota or compliance change is asserted. The news feed carried at 10:27 AM ET that the United States offers as much as 17 million barrels of crude from the Strategic Petroleum Reserve. The 10:00 AM ET bar, which contains that headline, traded down to 97.20 and closed at 97.37, and the contract then rose through the afternoon.
At 11:34 AM ET the feed carried a sourced report that a primary unit at Russia's Ryazan refinery has been halted since the October 15 drone attack. Provider commentary said prices rose to their highs on Friday afternoon after US lawmakers introduced a bill to block a deal with Russia to release several hundred million barrels of diesel fuel. These are statements carried by the news feed and provider commentary rather than volumes measured for this review.
4.2 EIA and API Inventory (Crude Stocks, Gasoline, Distillates, Cushing, SPR)
The captured calendars carry no official inventory report for Friday. The most recent official weekly petroleum status report printed at 12:00 PM ET on Thursday, October 15, 2026, and the news feed carried a crude draw of 8.557 million barrels against a forecast build of 0.15 million, with gasoline up 3.518 million barrels, distillates down 2.527 million and Cushing up 1.862 million.
The 17 million barrel reserve offer carried at 10:27 AM ET adds to the reserve releases reported earlier in the week. The next official report is scheduled for 10:30 AM ET on Wednesday, October 21, 2026, as the calendar lists it.
4.3 Geopolitical Backdrop (Middle East, Iran, Russia/Ukraine, Venezuela)
The news feed carried at 2:09 PM ET a US statement that about 400 merchant vessels went through the Strait of Hormuz in the past seven days, at 2:10 PM ET that the US has helped move more than 100 million barrels through the strait in that period, and at 2:11 PM ET a statement by the US regional commander that Iran has no maritime exports or imports because of the US naval blockade. Provider commentary said more than 40 vessels moved through the strait over the past 24 hours.
At 2:56 PM ET the feed carried Iranian media reports that three missiles were fired at the Aden airport, and at 3:15 PM ET reports of explosions in Aden. At 3:58 PM ET it carried Iranian media reports of explosions in Damascus. After the settle, at 4:30 PM ET, the feed carried press reports citing the US regional commander that Iran-backed militias are sending money back to Iran's revolutionary guard, and at 4:44 PM ET the President's remark that Iran will be over very soon. These are statements carried by the news feed rather than events confirmed for this review. Provider commentary attributed Friday's strength to a weaker dollar and to concern that escalating hostilities in the Middle East could disrupt regional supplies, and cited investment-bank commentary estimating a 24 dollar a barrel risk premium.
4.4 Demand and Refining (Refinery Utilization, Crack Spreads, Seasonal Pattern)
The November heating oil contract settled at 4.8991 dollars a gallon, up 0.0535, and the November gasoline contract at 3.2354, up 0.0552 or 1.74 percent, per the news feed at 2:32 PM ET and the provider. On the settlement arithmetic the heating oil margin, 42 gallons times the heating oil settle less the WTI settle, stands at 104.35 dollars a barrel against 105.55 on Thursday, and the gasoline margin at 34.48 against 35.60.
Both margins narrowed slightly because crude rose more than either product. The November natural gas contract settled at 3.116, down 0.120. No refinery utilisation figure and no seasonal demand series were captured, so neither is asserted.
4.5 Dollar and Cross-Asset (DXY, Commodities Complex, Equity Risk-On/Off)
The dollar index closed at 101.84 in the provider's daily record, down 0.16 from Thursday's 102.00, after trading as low as 101.58. The ten-year yield index traded between 5.07 and 5.13 percent and closed at 5.10 percent against 5.08 percent on Thursday. September import prices rose 1.1 percent at 8:30 AM ET against a 1.0 percent forecast, per the news-feed calendar, and industrial production rose 0.7 percent at 9:15 AM ET against a 0.4 percent forecast, both releases listed on the calendar.
Provider commentary said the dollar fell after the Federal Reserve Chair gave no guidance on policy in a speech at the annual International Monetary Fund meeting, which reduced the priced chance of a rate increase this month to 13 percent from 27 percent. Brent's December contract settled at 109.86, up 3.72 percent. The S&P 500 cash index closed at 7,659.44, down 1.09 percent, and gold's December contract settled at 4,181.1, up 0.26 percent. A weaker dollar is a supportive input for dollar-priced crude; the size of that effect is not measured here.
4.6 Institutional Positioning (COT, Money Manager and Commercial Hedger, Speculator Length)
The weekly positioning report shown on the provider's overview, as of October 13, 2026, puts managed-money longs at 171,973 contracts, down 6,380, and managed-money shorts at 131,399, up 6,644, so managed-money net length narrowed to 40,574 contracts. Producer longs rose 42,215 to 660,971 and producer shorts rose 24,082 to 307,828. The report predates the 7.27 point rise in the November contract over the three sessions through Friday.
Open interest on the November contract is shown at 84,922 for Thursday, down from 113,474 on Wednesday; Friday's open interest had not been reported at the time of capture. Friday's volume was 81,673 contracts in November against 304,249 in December, whose Thursday open interest stood at 309,217. The November contract expires on 10/20/26, per the provider, with first notice on 10/22/26, so liquidity has moved to December and the chart's continuous series already tracks December. November settled 2.39 above December, against 1.47 on Thursday, so the front of the curve remained in backwardation and the spread widened.
5. No Liquid Options Proxy
This review covers crude without a positioning dataset. There is no dealer-positioning surface read for this instrument in this review, no gamma map, no options concentration levels and no flow attribution, and none is inferred from any other instrument. Every level in section 3 originates in published pivot arithmetic, published standard-deviation bands, published retracement and moving-average projections, settlement averages computed from the provider's daily record, or the completed-session extremes described in section 2.1.
This is a statement about coverage, not about the existence of listed crude options. No such dataset was read for this review, so no claim resting on one appears anywhere in this review or in this outlook. The positioning inputs used for crude are the weekly positioning report shown on the provider's overview, the Brent spread, the November to December spread, the product margins and the open-interest record.
6. Forecast
6.1 Night Session (6:00 PM ET Sunday to 3:00 AM ET Monday, Globex/Asia)
Globex reopens at 6:00 PM ET on Sunday, October 18, 2026, after two days of headline exposure from the Gulf, the Red Sea and the Russian diesel debate. A gap above Friday's 101.90 high opens the way toward the 70 percent relative strength projection at 102.01 and Pivot R1 at 103.26, while a gap beneath the Pivot Point at 100.05 brings Pivot S1 at 98.21 and Thursday's 97.97 settle into view. China's third-quarter output, retail and growth figures are listed at 10:00 PM ET on Sunday, per the news-feed calendar and unconfirmed. Bias neutral to higher above the Pivot Point at 100.05, expected Globex band roughly 99.20 to 102.60 absent a weekend shock.
6.2 London Session (3:00 AM to 8:00 AM ET Monday)
A European Central Bank board member is listed at 1:50 AM ET, per the news-feed calendar and unconfirmed. Bias neutral to higher, expected band roughly 99.00 to 102.80, with the 99.80 to 100.10 band the first meaningful support and Friday's 101.90 high the first meaningful resistance.
6.3 Morning Session (9:00 AM to 12:00 PM ET Monday, US Open / Pit Session)
Canadian consumer prices are listed at 8:30 AM ET and the homebuilder sentiment index at 10:00 AM ET, both per the news-feed calendar and unconfirmed, with a forecast of 31 for the homebuilder index. Expected band roughly 98.20 to 103.30, with Pivot R1 at 103.26 the first meaningful resistance above Friday's high.
6.4 Afternoon Session (12:00 PM to 2:30 PM ET Monday, NYMEX Pit Close)
Crude settles at 2:30 PM ET, and November enters its final session on Tuesday after this settle. The captured calendars carry no crude-specific scheduled release for this window. Expected band roughly 97.90 to 103.60.
6.5 Night Session Forward (6:00 PM ET Monday)
Globex reopens at 6:00 PM ET on Monday for the November contract's final session; the November contract expires on 10/20/26, per the provider. Housing starts print at 8:30 AM ET on Tuesday, October 20, 2026, as the calendar lists them, and the next official weekly petroleum status report is scheduled for 10:30 AM ET on Wednesday, October 21, 2026, as the calendar lists it.
6.6 Expected Range (Monday Full Session)
Low-range scenario: 99.00 to 102.80
Mid-range scenario (most likely): 98.20 to 103.60
High-range scenario: 96.80 to 105.40
6.7 Most Likely Path
In this review's analyst judgment the most probable path holds the contract between one standard deviation support at 98.19 and Pivot R1 at 103.26, with weekend headlines deciding the side of the open. A dip toward the 99.80 to 100.10 band that holds above 98.89 is weighted above a break lower, because Friday settled at 90.3 percent of its range for a seventh consecutive higher settle and a new 52-week high, the settle sits above every settlement average from the 5-day to the 200-day, positive direction leads on the 9-day and 14-day directional systems, and the composite reached 100 percent buy with strength described as maximum.
The alternative that would invalidate this reading is a de-escalation headline over the weekend, consistent with the President's remark that Iran will be over very soon, or progress on Russian diesel supply, that opens the contract beneath Pivot S1 at 98.21 and carries it toward Thursday's 97.97 settle. The 9-day relative strength at 76.20 and the 8.85 point gap to the 20-day average leave the contract extended, so a pullback before any extension is a live alternative.
7. Monday Economic Calendar
Friday's releases are complete. September import prices printed at 8:30 AM ET on Friday, October 16, 2026, as the calendar lists it, with the news-feed calendar showing 1.1 percent against a 1.0 percent forecast, and industrial production printed at 9:15 AM ET on Friday, October 16, 2026, as the calendar lists it, with the news-feed calendar showing 0.7 percent against a 0.4 percent forecast. Crude settled at 2:30 PM ET.
Over the weekend, China's third-quarter growth, industrial output and retail sales figures are listed at 10:00 PM ET on Sunday, per the news-feed calendar and unconfirmed, and Globex reopens at 6:00 PM ET on Sunday. On Monday, a European Central Bank board member is listed at 1:50 AM ET, per the news-feed calendar and unconfirmed. Canadian consumer prices are listed at 8:30 AM ET on Monday, per the news-feed calendar and unconfirmed. The homebuilder sentiment index is listed at 10:00 AM ET on Monday, per the news-feed calendar and unconfirmed. Crude settles at 2:30 PM ET.
Later in the window, the November contract expires on 10/20/26, per the provider, housing starts print at 8:30 AM ET on Tuesday, October 20, 2026, as the calendar lists them, and the next weekly petroleum status report is scheduled for 10:30 AM ET on Wednesday, October 21, 2026, as the calendar lists it. In this review's judgment the first-order influence on crude on Monday is the weekend's Gulf, Red Sea and Russian diesel headlines, priced at the 6:00 PM ET Sunday reopen, with the November expiry on Tuesday shaping liquidity.
8. Primary Trade Setup
Direction: Long
Rationale: Friday settled at 90.3 percent of its range for a seventh consecutive higher settle and a new 52-week high, the settle sits above every settlement average from the 5-day to the 200-day, positive direction leads on the 9-day and 14-day directional systems, and the composite reached 100 percent buy with strength described as maximum; a dip into the Pivot Point at 100.05 offers a long with a defined risk point beneath the 14-3 day raw stochastic projection at 98.89. The 9-day relative strength reads 76.20 and two weekend days of headlines separate the settle from the reopen, so the setup is an analyst judgment that dips are bought while supply headlines persist, not a measured edge.
Entry Zone: 99.80 to 100.10
Stop Loss: 98.85 (beneath the 14-3 day raw stochastic projection at 98.89)
Target 1 (T1): 101.05 (36 cents beneath Friday's 101.41 settle)
Target 2 (T2): 102.15 (25 cents above Friday's 101.90 high)
Target 3 (T3, extended): 103.25 (1 cent beneath Pivot R1 at 103.26)
Risk-to-Reward: Approximately 1:1 to T1, 1:2 to T2, 1:3 to T3
Invalidation: A settle beneath Pivot S1 at 98.21 negates the thesis. Short of that, the edge is removed by acceptance beneath the entry band rather than by a touch, defined as two consecutive 30-minute closes beneath 99.80.
Macro override: A weekend de-escalation headline around Iran, Yemen or the Strait of Hormuz, or progress on Russian diesel supply, would remove part of the supply premium. In that scenario a gap through the 98.85 stop invalidates the long before the targets, and Pivot S1 at 98.21 and Thursday's 97.97 settle become the references within one 14-day average true range of 3.99 points.
Sources and methodology
This outlook is built from our session review of the November WTI crude contract, the November ’26 contract (CLX26), prepared after Friday's close on October 16, 2026 for the Monday, October 19, 2026 session. The chart's continuous symbol tracks the December contract, so every price here is the November contract's. Friday's completed extremes are the inputs behind the published pivot ladder: Pivot R3 at 108.31 less Pivot S3 at 93.16, divided by three, and Pivot R2 at 105.10 less Pivot S2 at 95.00, divided by two, both return 5.05, and three times the 100.05 Pivot Point less the 101.41 settle gives 198.74, which the 101.90 high and 96.85 low reproduce at 198.75 to the published rounding. The provider's settlement row, the chart's completed Friday bar and the 30-minute bars carry the same extremes. Those figures, the 46 30-minute bars from the 6:00 PM ET Thursday reopen to the 4:30 PM ET Friday bar and the review's statements are used to grade Friday's card, which is graded as published. Every timed intraday statement rests on those bars, and no price move is tied to a headline except where provider commentary is quoted as its own account.
The moving averages were computed from the provider's 260-session daily settlement series; the oscillators are cited as published for the Friday session. Friday's volume and the open-interest figures equal the provider's dated rows. Thursday's 10/15 row has been revised: volume now reads 222,965 against the 197,019 cited in Friday's outlook, and open interest, not reported then, reads 84,922. Friday's open interest had not been reported, and the December open-interest figure of 309,217 is Thursday's. The weekly positioning report is as of October 13, 2026. No dealer-positioning dataset was read for crude; the positioning inputs are the weekly positioning report, the Brent spread, the November to December spread, the product margins and the open-interest record. Scenario ranges are analyst judgment, and items marked unconfirmed come from the news-feed calendar.
Friday’s outlook for this contract is here, and the gold contract’s Friday outlook covers the metal whose December contract settled at 4,181.1 on Friday, up 0.26 percent. Outlooks for ES, NQ, GC and CL are collected on the market outlook page, and our forward trading record is on the performance statement.