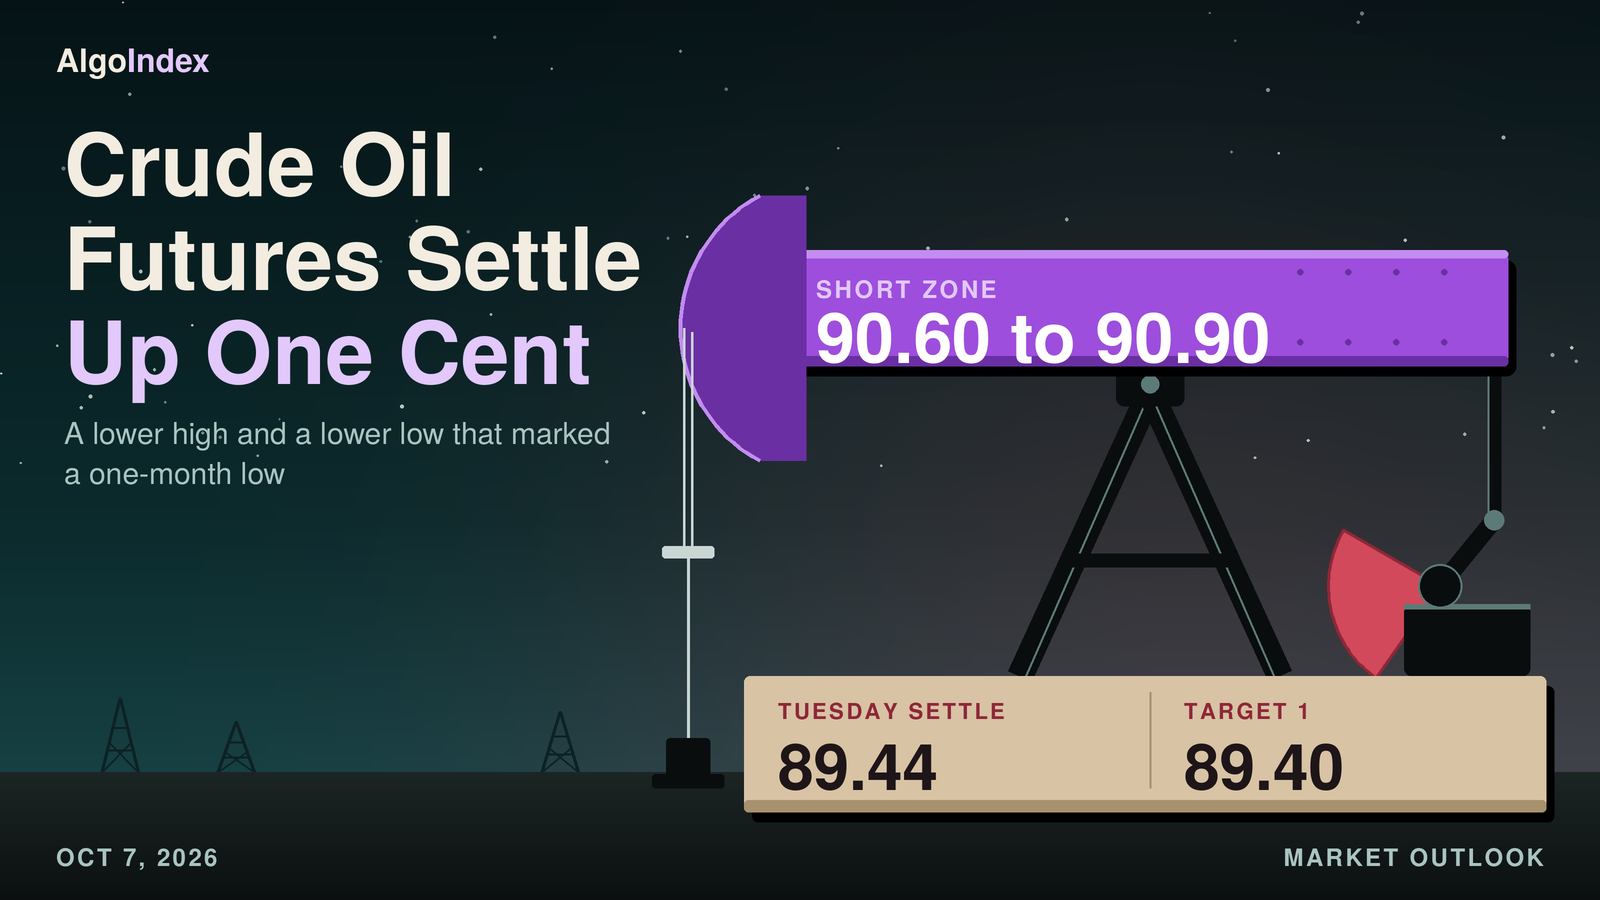
November crude set a one-month low on Tuesday and still settled higher. The contract traded between 90.05 and 86.86, its lowest print since the 85.92 low of 09/04. It settled at 89.44 at 2:30 PM ET. That was up 0.01 point, or 0.01 percent, from Monday’s 89.43. Volume printed 234,969 contracts on the provider’s dated daily record for Tuesday, against 274,982 on Monday’s revised row.
The settle finished at 80.9 percent of a 3.19 point range. The range was 0.72 times the published 14-day average daily range of 4.43 points. Against Monday’s 91.88 to 88.74, Tuesday printed a lower high and a lower low. Even so, the one-cent gain was the first higher settle after two lower settles. A long lower shadow. The 90.05 high belongs to electronic trade after the settle; the 4:30 PM ET bar carries it. No intraday series was preserved for the rest of the day, so the order of the other prints is not stated here.
Provider commentary said crude erased its losses and settled higher on short covering after reports that Iran has stepped up attacks on tankers in the Strait of Hormuz. It cited a weaker dollar as well. The same commentary tied the slide to the one-month low to signs that more crude is leaving the Middle East and to Yemeni government forces retaking the port of Mokha. Neither headline carried a time stamp. No price move is tied to either. The dollar index fell 0.33 percent to 101.83 and the ten-year yield index closed five basis points lower at 5.26 percent. December Brent rose 0.26 to 100.58. Crude remains the most volatile of the four instruments covered here. Its published 14-day average true range of 4.13 points is 4.62 percent of the settle.
November WTI settled up one cent. It finished at 89.44, at 80.9 percent of a 90.05 to 86.86 range that set a one-month low. Overhead sit the 89.82 stochastic stall price, the 90.05 post-settlement high, the 90.21 stochastic threshold, the 90.42 relative-strength line, the 90.65 5-day average, Pivot R1 at 90.71 and one deviation resistance at 90.87. Support starts at the 89.09 stochastic threshold, the 89.03 13-week retracement and the 88.89 40-day crossing, then the 88.78 Pivot Point and one deviation support at 88.01. The primary setup is a short from 90.60 to 90.90, stop 92.10, targets 89.40, 88.05 and 86.70. The calendar lists the weekly petroleum status report at 10:30 AM ET Wednesday, in our judgment the first-order event for crude.
Tuesday’s short, graded against the bar
Tuesday’s card was a short. That outlook set it from a rally into 90.70 to 91.00, around one standard deviation resistance at 90.87 and beneath Pivot R1 at 91.29. It carried a stop at 92.00, targets at 89.70, 88.55 and 87.40, and an outright invalidation on a settle above Pivot R1. Tuesday opened at 89.27, marked a 90.05 high and an 86.86 low, and settled at 89.44. The dated 10/06 row of the provider’s daily record carries the same four prices.
We put the entry band at 90.70 to 91.00. It never traded. Tuesday’s 90.05 high stopped 65 cents beneath the band’s bottom, and that high belongs to post-settlement trade in the 4:30 PM ET bar. The 92.00 stop sat 1.95 points above it. All three target levels sit inside the daily range. The 89.70 first target lies 35 cents beneath the high. The 86.86 low reached 1.69 points through 88.55 and 54 cents through 87.40. With the entry band untouched, those prints describe price only. The daily bar cannot show the order in which they came. This outlook asserts no result for the card.
Neither exit clause came into play. The card defined acceptance above two deviation resistance as two consecutive 30-minute closes above 91.47. No intraday series was preserved for Tuesday. None is needed for this clause. No 30-minute close could sit above 91.47 on a day whose high was 90.05. The outright invalidation stayed out of reach as well. The settle sat 1.85 points beneath 91.29.
The macro override named a confirmed escalation between Saudi Arabia and the Houthis that threatens Red Sea or Gulf tanker traffic, or an abrupt reversal in the dollar. Its test was a gap above the 92.00 stop. No such gap came. The Monday 6:00 PM ET reopen printed 89.27, 16 cents beneath Monday’s settle and 2.73 points beneath the stop. Provider commentary did report stepped-up Iranian attacks on tankers in the Strait of Hormuz. That item was untimed. The dollar index fell 0.33 percent on the day.
The range work was mixed. The low-range case, 88.40 to 90.60, held the 90.05 high and the 89.44 settle. The 86.86 low broke its bottom by 1.54 points. The most likely band, 87.90 to 91.30, also held the high and the settle, with the low 1.04 points beneath it. Only the high-range case, 85.20 to 93.60, held the whole session.
The path call is harder to score. That outlook expected the contract to hold beneath the 90.02 Pivot Point through the overnight hours and offered a test of the 88.70 to 88.74 group before the 12:00 PM ET energy outlook. The daily bar cannot show either timing. It does show the low running through that group, through Pivot S1 at 88.15 and through one deviation support at 87.99. That move was weighted above a recovery through 91.29, and the high stopped 1.24 points short of 91.29. The alternative, a lift through 91.92, never came. The settle sat 58 cents beneath 90.02; the post-settlement high sat three cents above it.
The session bands cannot be scored. Globex at 88.40 to 90.60, London at 88.30 to 90.90, the United States morning at 88.20 to 91.00 and the afternoon at 88.00 to 90.80 each need an intraday series. None was preserved for Tuesday.
A one-month low, a one-cent gain
Tuesday opened at 89.27 at the Monday 6:00 PM ET reopen, 16 cents beneath Monday’s settle. It marked a daily high of 90.05 and a daily low of 86.86, and settled at 89.44 at 2:30 PM ET. No intraday series was preserved for crude. This outlook makes no claim about the order in which the extremes printed during the regular session, or about the path between them.
One sub-daily record survives. The chart’s 30-minute bars read after the close show post-settlement electronic trade between 89.53 and 90.05 from the 3:00 PM ET bar through the 4:30 PM ET bar. The 4:30 PM ET bar traded from 89.81 to 90.05 and closed at 89.91. Its 90.05 high equals the high on the provider’s settlement row. So the daily high belongs to post-settlement electronic trade, outside the settlement window. Those quotes are not used as the settlement anywhere here. Wednesday’s session reopened at 6:00 PM ET Tuesday. The provider’s day open, high and low of 89.96, 89.96 and 89.62, shown when the data were read, belong to that new session.
The extremes are the completed-session inputs behind the published pivot ladder, back-solved from its outer pairs. The third resistance point at 93.90 minus the third support point at 84.33, divided by three, returns 3.19. So does 91.97 less 85.59, halved. Three times the 88.78 Pivot Point less the 89.44 settle gives a 176.90 high-plus-low sum. That is one cent from the 176.91 of the solved pair, because the published pivot is rounded. The pair of 90.05 and 86.86 reproduces all seven rungs. The settlement row and the chart’s completed Tuesday bar carry the same high and low. The provider’s one-month low reads 86.86, dated 10/06/26.
Both extremes sit beneath Monday’s. The 90.05 high sits 1.83 points beneath Monday’s 91.88, and the 86.86 low 1.88 points beneath Monday’s 88.74. Session highs over the last six sessions read 94.74, 91.96, 93.68, 93.51, 91.88 and 90.05. The lows read 88.78, 88.58, 88.79, 87.89, 88.74 and 86.86. Settlements ran 89.38, 90.42, 92.87, 91.11, 89.43 and 89.44. A settle in the upper fifth of a range that set a one-month low leaves a long lower shadow on the daily bar.
The prior week, September 28 through October 2, spanned 96.54 to 87.89. Tuesday’s 86.86 low traded beneath it. The settle sits inside it. The 52-week, 13-week and one-month high of 101.69, dated 09/15/26, sits 12.25 points above the settle. No prior-quarter high or low was captured, so the 13-week extremes stand in: 101.69 above and 68.55, dated 07/07/26, beneath. Sixteen settles tell the swing since the 09/15 peak: 100.75, 97.51, 97.23, 96.08, 92.37, 90.52, 92.16, 94.61, 92.41, 92.60, 89.38, 90.42, 92.87, 91.11, 89.43 and 89.44. Daily ranges for the last seven sessions ran 5.29, 5.96, 3.38, 4.89, 5.62, 3.14 and 3.19.
The retracement grid published for Wednesday places the 38.2 percent retracement from the 13-week high at 89.03. That is 41 cents beneath the settle. The 50 percent retracement of the 13-week range sits at 85.12. Above the settle, the 38.2 percent retracement from the four-week low sits at 92.53, the 50 percent retracement of the four-week range at 94.28 and the 38.2 percent retracement from the four-week high at 96.02. No four-hour series was captured. Swing structure here rests on daily bars only.
The averages come from the provider’s daily settlement series for the November contract, 259 completed sessions through Tuesday. The 5-day stands at 90.65, the 9-day at 91.36, the 20-day at 93.66, the 50-day at 86.23, the 100-day at 81.89 and the 200-day at 75.33. The settle sits 1.21 points beneath the 5-day, 1.92 beneath the 9-day and 4.22 beneath the 20-day. It sits 3.21 points above the 50-day.
Short-term averages barely moved. The 5-day rose one cent from Monday’s 90.64 as the 09/29 settle of 89.38 left its window and 89.44 replaced it. The 9-day fell 30 cents from 91.67 as the 09/23 settle of 92.16 left. The 20-day fell four cents from 93.70 as the 09/08 settle of 90.19 left. The projection grid puts Wednesday’s 9-day crossing at 90.96, the 18-day crossing at 93.30 and the 40-day at 88.89.
Momentum leans soft. The oscillator figures are as published on the provider’s technical page dated for the Wednesday session, read after the 6:00 PM ET reopen. That page may carry the live Globex price, so the readings are quoted as published. Relative strength reads 42.90 on the 9-day, 47.85 on the 14-day and 50.86 on the 20-day. The stochastics sit low in their ranges. The 9-day raw stochastic reads 26.01 percent and the 14-day 23.14 percent, with the 14-day %K at 19.53 percent and %D at 21.87 percent. The 14-3 day raw stochastic’s 20 percent threshold sits at 89.09, 35 cents beneath the settle, and its 30 percent threshold at 90.21.
The short directional system turned. On the 9-day the directional index reads 20.45, with negative direction at 17.41 over positive at 15.06. The 14-day reads 23.94, positive at 18.19 over negative at 16.63. Historic volatility runs 33.19 percent on the 9-day and 32.52 percent on the 14-day. The composite multi-indicator read for the Wednesday session fell to 16 percent buy from 24 percent in the prior session’s snapshot. Signal strength is described as soft and direction as weakening. It read 24 percent a week ago and 80 percent a month ago. The short-horizon group averages 20 percent sell, the medium-horizon group 25 percent buy and the long-horizon group 67 percent buy. The composite trend indicator reads hold.
Volatility sets the scale. The published 14-day average true range stands at 4.13 points and the 14-day average daily range at 4.43. The 9-day figures are 4.27 and 4.47, the 20-day figures 3.95 and 4.53. A one-range projection from 89.44 on the 14-day average true range frames Wednesday between 85.31 and 93.57. The published deviation bands are narrower because they are built from five settlements. One deviation spans 88.01 to 90.87, two spans 87.42 to 91.46 and three spans 86.97 to 91.91. The bands describe settlement dispersion, not intraday reach.
Tanker attacks, a softer dollar and a Yemen port
Supply news cut both ways. Provider commentary attributed the slide to the one-month low to signs that more crude is leaving the Middle East. It cited Kuwait pumping about 75 percent of its pre-war level and Iraq seeking extra vessels. It also cited Saudi-backed Yemeni government forces retaking the port of Mokha near the Bab el-Mandeb Strait.
The same commentary said crude erased its losses and settled higher on short covering after reports that Iran has stepped up attacks on tankers attempting to transit the Strait of Hormuz. It cited a United Kingdom maritime agency count of nine vessels targeted over recent days. It said a weaker dollar also supported energy. Neither item carried a time stamp on the feeds captured for this session. No price move here is tied to either headline.
Producer policy held steady. Provider commentary said the producer alliance agreed on Sunday to keep production quotas unchanged for November. It said Saudi crude exports stood at 5.28 million barrels a day in September. That was the highest in seven months, according to tracking data. It said Saudi Arabia restored about 3.5 million barrels a day of its East-West crude line’s 7 million barrel capacity on Monday after repairs. The same commentary recalled Monday’s Saudi cut to its November official selling price for Arab Light crude sold to Asia, 5 dollars a barrel below the regional benchmark against expectations of a 5 dollar increase. These come from provider commentary and were not measured here.
A private survey pointed to a draw. The news feed carried it at 4:50 PM ET, after the settle. It reported a crude draw of 2.1 million barrels against a prior build of 1.019 million, a gasoline draw of 1.4 million barrels, a distillate build of 0.461 million and a Cushing build of 0.866 million. The calendar listed the short-term energy outlook with the winter fuels outlook at 12:00 PM ET on Tuesday, October 6, 2026. No figures from it were captured, so none is quoted. The calendar lists the weekly petroleum status report at 10:30 AM ET on Wednesday, October 7, 2026. The news-feed calendar lists a forecast build of 2 million barrels against a prior build of 0.922 million.
Words piled up after the settle. The news feed carried presidential remarks at 3:10 PM ET and 3:11 PM ET that Iran is doing very poorly and that oil keeps flowing through Hormuz. It carried a report at 3:23 PM ET of an explosion heard in Sulaymaniyah in northern Iraq. At 3:58 PM ET it reported flames and smoke at Venezuela’s Cardon refinery, attributed to four sources. Between 4:04 PM ET and 4:24 PM ET the President said the United States still has to finish its campaign against Iran. At 4:20 PM ET he said the Russia and Ukraine war is getting closer to ending. At 4:42 PM ET the Treasury Secretary said Iran has not loaded a single barrel of crude onto a vessel since August 25. These are statements carried by the news feed. None was confirmed here. All of them came after the 2:30 PM ET settle.
The product complex firmed. The November gasoline contract settled at 3.2732 dollars a gallon, up 0.0270 or 0.83 percent. November heating oil settled at 4.5694, up 0.0242 or 0.53 percent, per the provider’s records. On the settlement arithmetic the gasoline margin, 42 gallons times the gasoline settle less the WTI settle, widened to 48.03 from 46.91. The heating oil margin widened to 102.47 from 101.47. At 3:18 PM ET the President said he had been told the federal gasoline tax needs suspending and that he is thinking about it, per the news feed. No refinery utilisation figure and no seasonal demand series were captured.
The dollar softened. The trade deficit, released at 8:30 AM ET, widened to 105.6 billion dollars against a 102.05 billion forecast, per the news-feed calendar. The dollar index closed at 101.83, down 0.34 points or 0.33 percent, after a session range of 101.75 to 102.29, per the provider’s quote. Provider commentary tied the decline to the wider trade deficit and lower Treasury yields. The ten-year yield index closed at 5.26 percent, down five basis points from Monday’s close. A three-year note auction, per the news-feed calendar and unconfirmed, stopped at a high yield of 4.932 percent with a bid-to-cover of 2.620.
Brent firmed less than the products. Its December contract settled at 100.58, up 0.26 or 0.26 percent, so its premium over November WTI widened to 11.14 from 10.89. The S&P 500 cash index closed at 7,818.93, up 0.58 percent. Gold’s December contract settled at 4,187.1, up 30.3 points or 0.73 percent.
Positioning data are a week old. The latest report on the provider’s overview is still the one as of September 29, 2026: managed money long 209,028 contracts against short 129,436, a net long of 79,592, with commercials 873,637 long against 1,016,255 short. No change in positioning is asserted for Tuesday. The overview shows open interest on the November contract at 248,138. That is Monday’s figure, on the dated 10/05 row, down from 258,251 on Friday’s 10/02 row. Tuesday’s open interest had not been reported.
One gap is deliberate. No dealer-positioning dataset was read for crude: no gamma map, no options concentration levels and no flow attribution, and none is borrowed from another instrument. The positioning inputs for crude are the weekly positioning report, the private and official inventory reports, the Brent spread and the product margins.
The trade map for Wednesday
Overhead, the references stack tight. The settle at 89.44 sits 66 cents above the Pivot Point at 88.78, so the first resistance is overhead supply. The 14-day stochastic %K stall price at 89.82 comes first, then the 90.05 post-settlement high and the stochastic 30 percent threshold at 90.21. The 14-day relative-strength 50 percent line at 90.42 and the 5-day settlement average at 90.65 follow. Pivot R1 at 90.71 and one deviation resistance at 90.87 form the band that anchors the setup. The 9-day average crossing at 90.96 and the 9-day settlement average at 91.36 sit above it. Two deviation resistance at 91.46, Monday’s 91.88 high, three deviation resistance at 91.91 and Pivot R2 at 91.97 come next. The 38.2 percent retracement from the four-week low at 92.53, the 18-day average crossing at 93.30, the 20-day settlement average at 93.66 and Pivot R3 at 93.90 are the extended references.
Support starts within cents. The stochastic 20 percent threshold at 89.09, the 38.2 percent retracement from the 13-week high at 89.03 and the 40-day average crossing at 88.89 come first, then the Pivot Point at 88.78. The published target price of 88.44, the 3-10 day average crossover stall price at 88.17 and one deviation support at 88.01 follow. Pivot S1 at 87.52 and two deviation support at 87.42 sit together. Three deviation support at 86.97 and Tuesday’s 86.86 low, the one-month low, come next. The 50-day settlement average at 86.23 sits beneath that low. Pivot S2 at 85.59, the 50 percent retracement of the 13-week range at 85.12, Pivot S3 at 84.33 and the 61.8 percent retracement from the 52-week low at 84.10 are the deeper references.
The primary setup is a short from a rally into 90.60 to 90.90, around Pivot R1 at 90.71 and one deviation resistance at 90.87. It needs a rally first. Tuesday settled beneath the 5-day, 9-day and 20-day settlement averages. The composite read fell to 16 percent buy with direction weakening, and the 9-day directional system turned negative. A rally into that band offers a short with a defined risk point above Pivot R2 at 91.97. In our reading, the long lower shadow and the reported tanker attacks show buyers still respond to Hormuz headlines. So the setup is an analyst judgment against live headline risk. Risk is 1.35 from the 90.75 midpoint.
The entry band sits 1.16 points above the settle. Wednesday’s session reopened at 6:00 PM ET Tuesday with the 4:50 PM ET private survey draw of 2.1 million barrels and the Treasury Secretary’s remark on Iranian loadings already out. A regional Federal Reserve president is listed at 7:00 PM ET Tuesday and German industrial production at 2:00 AM ET Wednesday, both per the news-feed calendar and unconfirmed. Bias is neutral above the 88.78 Pivot Point. The expected Globex band is roughly 88.60 to 90.60, absent a headline shock. Gulf and Hormuz headlines are the gap risk in both directions.
Europe’s list holds nothing for crude. The captured calendars carry no crude-specific entry inside the London window, and the 10:30 AM ET weekly petroleum report is the next scheduled crude event. Tuesday’s 3.19 point range shows that two-way swings of more than three points remain possible inside a single session. Bias is neutral, with an expected band of roughly 88.40 to 90.80.
The calendar lists the weekly petroleum status report at 10:30 AM ET, the first-order crude event of the day. The news-feed calendar lists a forecast build of 2 million barrels. The private survey’s 2.1 million barrel draw is the marker against it. A regional inflation-expectations survey is listed at 11:00 AM ET, per the news-feed calendar and unconfirmed. Expected band roughly 87.80 to 91.00, with the 90.71 to 90.87 band the first resistance.
The afternoon brings the dollar events. A ten-year note auction is listed at 1:00 PM ET, per the news-feed calendar and unconfirmed. The calendar lists the minutes of the September policy meeting at 2:00 PM ET. Crude settles at 2:30 PM ET, so the minutes land inside the final half hour before the settle. Expected band roughly 87.80 to 90.80.
Consumer credit is on the calendar at 3:00 PM ET Wednesday, after the crude settle. The calendar lists a Federal Reserve governor on the economic outlook at 4:30 AM ET on Thursday, October 8, 2026, inside the following overnight window. The captured calendars carry no mega-capitalisation earnings entry for Wednesday. The provider lists the November contract’s expiration as 10/20/26, with first notice on 10/22/26.
Three scenarios frame the full session. The low-range case runs 88.60 to 90.60, the mid-range case, which is the most likely, 87.50 to 91.00, and the high-range case 85.30 to 93.60. None carries a derived frequency. In our analyst judgment the most probable path holds the contract between the 88.78 Pivot Point and the 90.71 to 90.87 resistance band into the 10:30 AM ET weekly petroleum report. In the same judgment the report decides the side. A rally into that band that fails beneath Pivot R2 at 91.97 is weighted above a sustained break higher. Three readings carry that weighting. Tuesday settled beneath the 5-day, 9-day and 20-day settlement averages. The composite read fell to 16 percent buy with direction weakening. The 9-day directional system turned negative. One alternative invalidates the reading. A confirmed Hormuz escalation or a large official draw that lifts the contract through 91.97 and toward the 92.53 retracement would do it.
In our judgment the single first-order event for crude on Wednesday is the 10:30 AM ET weekly petroleum status report. Hormuz and Gulf headlines are the unscheduled risk in both directions. The minutes at 2:00 PM ET reach crude through the dollar.
Tuesday’s high stopped 65 cents short of the last entry band. Wednesday’s band starts ten cents lower.
The complete data picture
Every number behind Wednesday’s plan, charted first, then the full level lists, then the complete numeric reference underneath.
Full numeric reference, every remaining figure from the session review
Carried below in the review’s own order: the level notes from sections 3.1 and 3.2, the executive summary from section 1, sections 2.1 to 2.6, sections 4.1 to 4.6, the coverage note from section 5, the session-by-session forecast from section 6, the Wednesday calendar from section 7 and the primary setup from section 8.
3.1 Resistance and 3.2 Support, level notes
The settle at 89.44 sits 66 cents above the Pivot Point at 88.78, so the first resistance is overhead supply. The 14-day stochastic %K stall price at 89.82 comes first, then the post-settlement high of 90.05 and the 14-3 day raw stochastic 30 percent threshold at 90.21. The 14-day relative-strength 50 percent line at 90.42 and the 5-day settlement average at 90.65 follow, with Pivot R1 at 90.71 and one standard deviation resistance at 90.87 forming the band that anchors the setup.
The 9-day average crossing price at 90.96 and the 9-day settlement average at 91.36 sit above it, then two standard deviations resistance at 91.46, Monday’s 91.88 high, three standard deviations resistance at 91.91 and Pivot R2 at 91.97. The 38.2 percent retracement from the four-week low at 92.53, the 18-day average crossing at 93.30, the 20-day settlement average at 93.66 and Pivot R3 at 93.90 are the extended references.
Beneath the settle, the 38.2 percent retracement from the 13-week high at 89.03 and the 40-day average crossing price at 88.89 come first, followed by the Pivot Point at 88.78. The published target price of 88.44, the 3-10 day average crossover stall price at 88.17 and one standard deviation support at 88.01 follow. Pivot S1 at 87.52 and two standard deviations support at 87.42 sit together, then three standard deviations support at 86.97 and Tuesday’s 86.86 low, the one-month low. The 50-day settlement average at 86.23 sits beneath that low and above Pivot S2 at 85.59; the 50 percent retracement of the 13-week range at 85.12, Pivot S3 at 84.33 and the 61.8 percent retracement from the 52-week low at 84.10 are the deeper references.
1. Executive Summary
The November crude contract settled at 89.44 on Tuesday, up 0.01 point or 0.01 percent from Monday’s 2:30 PM ET settle of 89.43, after trading between 90.05 and 86.86, a 3.19 point daily range. The settle finished at 80.9 percent of the range, and the 3.19 point range was 0.72 times the published 14-day average daily range of 4.43 points. The 86.86 low was the lowest print since the 85.92 low of 09/04 and is the provider’s one-month low, while the 90.05 high sat 1.83 points beneath Monday’s 91.88, so Tuesday printed a lower high and a lower low. The one-cent gain was the first higher settle after two lower settles.
Provider commentary said crude erased its losses and settled higher on short covering after reports that Iran has stepped up attacks on tankers attempting to transit the Strait of Hormuz, citing a United Kingdom maritime agency count of nine vessels targeted over recent days, and that a weaker dollar also supported energy. The same commentary attributed the slide to the one-month low to signs that more crude is leaving the Middle East, including Kuwait pumping about 75 percent of its pre-war level and Iraq seeking extra vessels, and to Saudi-backed Yemeni government forces retaking the port of Mokha near the Bab el-Mandeb Strait. Neither item carried a time stamp on the feeds captured for this session, and no intraday series was preserved, so no price move here is tied to either headline.
The dollar index fell 0.33 percent to 101.83 and the ten-year yield index closed five basis points lower at 5.26 percent. The trade deficit, released at 8:30 AM ET, widened to 105.6 billion dollars against a 102.05 billion forecast, per the news-feed calendar. Brent’s December contract settled at 100.58, up 0.26, so Brent’s premium over November WTI widened to 11.14 from 10.89. Gasoline rose 0.83 percent and heating oil 0.53 percent. After the settle, the news feed carried a private inventory survey at 4:50 PM ET showing a crude draw of 2.1 million barrels against a prior build of 1.019 million.
Crude remains the most volatile of the four instruments covered here; the published 14-day average true range of 4.13 points is 4.62 percent of the settle. The Primary Setup below is a short from the 90.60 to 90.90 band, around Pivot R1 at 90.71 and one standard deviation resistance at 90.87, stopped at 92.10 above Pivot R2 at 91.97, with objectives at 89.40, 88.05 and an extended 86.70.
2.1 Intraday and Session Review
The Tuesday session opened at 89.27 at the Monday 6:00 PM ET reopen, 16 cents beneath Monday’s settle, marked a daily high of 90.05 and a daily low of 86.86, and settled at 89.44 at 2:30 PM ET. No intraday series was preserved for crude for this session, so this outlook makes no claim about the order in which the extremes printed during the regular session or about the path between them; only the daily bar, the settlement and the chart’s post-settlement 30-minute bars are used.
The chart’s 30-minute bars read after the close show post-settlement electronic trade between 89.53 and 90.05 from the 3:00 PM ET bar through the 4:30 PM ET bar. The 4:30 PM ET bar traded from 89.81 to 90.05 and closed at 89.91, and its 90.05 high equals the high on the provider’s settlement row, so the daily high belongs to post-settlement electronic trade, outside the settlement window. These post-settlement quotes are not used as the settlement anywhere here. The Wednesday session reopened at 6:00 PM ET Tuesday; the provider’s day open, high and low of 89.96, 89.96 and 89.62 shown when the data were read belong to that new session, not to Tuesday.
The session extremes used here are the completed-session inputs behind the published pivot ladder, back-solved from the outer pivot pairs and verified against every rung. The third resistance point at 93.90 minus the third support point at 84.33, divided by three, returns 3.19, and the second resistance point at 91.97 minus the second support point at 85.59, divided by two, returns the same 3.19. Three times the Pivot Point of 88.78 less the 89.44 settle gives a high plus low sum of 176.90, one cent from the 176.91 of the solved pair because the published pivot is rounded, and the pair of 90.05 and 86.86 reproduces all seven published rungs. Independent corroboration: the provider’s settlement row and the chart’s completed Tuesday daily bar carry the same 90.05 high and 86.86 low, and the provider’s one-month low reads 86.86 dated 10/06/26.
2.2 Daily Structure
Tuesday printed a lower high and a lower low against Monday: the 90.05 high sits 1.83 points beneath Monday’s 91.88, and the 86.86 low sits 1.88 points beneath Monday’s 88.74. The sequence of session highs over the last six sessions reads 94.74, 91.96, 93.68, 93.51, 91.88 and 90.05, and the sequence of session lows reads 88.78, 88.58, 88.79, 87.89, 88.74 and 86.86. The settle in the upper fifth of a range that set a one-month low leaves a long lower shadow on the daily bar.
The prior week, September 28 through October 2, spanned 96.54 to 87.89, and Tuesday’s 86.86 low traded beneath it while the settle sits inside it. The 52-week, 13-week and one-month high of 101.69, dated 09/15/26, sits 12.25 points above the settle. Settlements over the last six sessions ran 89.38, 90.42, 92.87, 91.11, 89.43 and 89.44.
No prior-quarter high or low was captured, so the 13-week extremes serve as the available quarterly reference: 101.69 above and 68.55, dated 07/07/26, beneath.
2.3 4-Hour and Swing Structure
The daily settlement sequence after the 09/15 peak reads 100.75, 97.51, 97.23, 96.08, 92.37, 90.52, 92.16, 94.61, 92.41, 92.60, 89.38, 90.42, 92.87, 91.11, 89.43 and 89.44. Daily ranges for the last seven sessions ran 5.29, 5.96, 3.38, 4.89, 5.62, 3.14 and 3.19.
The retracement grid published for Wednesday places the 38.2 percent retracement from the 13-week high at 89.03, 41 cents beneath the settle, and the 50 percent retracement of the 13-week range at 85.12. Above the settle, the 38.2 percent retracement from the four-week low sits at 92.53, the 50 percent retracement of the four-week range at 94.28 and the 38.2 percent retracement from the four-week high at 96.02. No four-hour series was captured and no intraday series was preserved, so swing structure here rests on daily bars only.
2.4 Moving Averages
The averages cited in this subsection were computed from the provider’s daily settlement series for the November contract, which holds 259 completed sessions through Tuesday. The 5-day average stands at 90.65, the 9-day at 91.36, the 20-day at 93.66, the 50-day at 86.23, the 100-day at 81.89 and the 200-day at 75.33.
The 89.44 settle sits 1.21 points beneath the 5-day average, 1.92 points beneath the 9-day and 4.22 points beneath the 20-day, and 3.21 points above the 50-day. The 5-day average rose one cent from Monday’s 90.64, because the 09/29 settle of 89.38 left the window and was replaced by 89.44. The 9-day average fell 30 cents from 91.67 as the 09/23 settle of 92.16 left its window, and the 20-day fell four cents from 93.70 as the 09/08 settle of 90.19 left.
The projection grid gives the prices at which each average would be crossed on Wednesday: 90.96 for the 9-day, 93.30 for the 18-day and 88.89 for the 40-day.
2.5 Oscillator and Trend Readings
The oscillator figures below are as published on the provider’s technical page dated for the Wednesday session, read after the 6:00 PM ET reopen; the page may carry the live Globex price, so they are quoted as published. The 9-day relative strength reads 42.90, the 14-day relative strength 47.85 and the 20-day relative strength 50.86.
The stochastics sit low in their ranges. The 9-day raw stochastic reads 26.01 percent and the 14-day raw stochastic 23.14 percent, while the 14-day stochastic %K reads 19.53 percent and the 14-day stochastic %D 21.87 percent. The published grid places the 14-3 day raw stochastic 20 percent threshold at 89.09 and its 30 percent threshold at 90.21.
The short directional system turned. The 9-day directional index reads 20.45 with the 9-day positive direction at 15.06 and the 9-day negative direction at 17.41, so negative direction now leads on the 9-day; the 14-day directional index reads 23.94 with positive direction at 18.19 and negative direction at 16.63. The 9-day historic volatility reads 33.19 percent and the 14-day historic volatility 32.52 percent.
The composite multi-indicator read published for the Wednesday session is 16 percent buy, down from 24 percent buy in the prior session’s snapshot, with signal strength described as soft and direction as weakening. The snapshot history reads 24 percent buy a week ago and 80 percent buy a month ago. The short-horizon group averages 20 percent sell, the medium-horizon group 25 percent buy and the long-horizon group 67 percent buy, and the composite trend indicator reads hold.
2.6 Volatility and Expected Range
The published 14-day average true range stands at 4.13 points and the 14-day average daily range at 4.43 points; the 9-day average true range is 4.27 with a 9-day average daily range of 4.47, and the 20-day average true range is 3.95 with a 20-day average daily range of 4.53. Tuesday’s 3.19 point range was 0.72 times the 14-day average daily range.
A one-range projection from the 89.44 settle using the 14-day average true range frames Wednesday between 85.31 and 93.57. The published standard-deviation bands are narrower because they are built from five settlements: one deviation spans 88.01 to 90.87, two spans 87.42 to 91.46 and three spans 86.97 to 91.91. These bands measure how settlements have dispersed, and the high and low can run beyond them.
4.1 OPEC and Supply Policy (Quotas, Compliance, Saudi and Russia Signals)
Provider commentary said the producer alliance agreed on Sunday to keep production quotas unchanged for November, that Saudi crude exports stood at 5.28 million barrels a day in September, the highest in seven months according to tracking data, and that Saudi Arabia restored about 3.5 million barrels a day of the East-West crude line’s 7 million barrel capacity on Monday after repairs. The same commentary recalled Monday’s Saudi cut to its November official selling price for Arab Light crude sold to Asia, 5 dollars a barrel below the regional benchmark against expectations of a 5 dollar increase. These are descriptions from provider commentary and were not measured here.
4.2 Inventory Data (Crude Stocks, Gasoline, Distillates, Cushing, Strategic Reserve)
A private inventory survey carried by the news feed at 4:50 PM ET reported a crude draw of 2.1 million barrels against a prior build of 1.019 million, a gasoline draw of 1.4 million barrels, a distillate build of 0.461 million and a Cushing build of 0.866 million. The short-term energy outlook with the winter fuels outlook was scheduled for 12:00 PM ET on Tuesday, October 6, 2026, on the calendar; no figures from it were captured, so none is quoted. The weekly petroleum status report is scheduled for 10:30 AM ET on Wednesday, October 7, 2026, on the calendar, and the news-feed calendar lists a forecast build of 2 million barrels against a prior build of 0.922 million.
4.3 Geopolitical Backdrop (Middle East, Iran, Russia and Ukraine, Venezuela)
Provider commentary tied the recovery to reports that Iran has increased attacks on tankers in the Strait of Hormuz and the slide to the Yemeni government’s recapture of Mokha. After the settle, the news feed carried presidential remarks at 3:10 PM ET and 3:11 PM ET that Iran is doing very poorly and that oil keeps flowing through Hormuz, a report at 3:23 PM ET of an explosion heard in Sulaymaniyah in northern Iraq, a report at 3:58 PM ET of flames and smoke at Venezuela’s Cardon refinery attributed to four sources, presidential remarks between 4:04 PM ET and 4:24 PM ET that the United States still has to finish its campaign against Iran, a remark at 4:20 PM ET that the Russia and Ukraine war is getting closer to ending, and a statement by the Treasury Secretary at 4:42 PM ET that Iran has not loaded a single barrel of crude onto a vessel since August 25. These are statements carried by the news feed, none confirmed here, and all of them came after the 2:30 PM ET settle.
4.4 Demand and Refining (Refinery Utilisation, Crack Spreads, Seasonal Pattern)
The product complex firmed. The November gasoline contract settled at 3.2732 dollars a gallon, up 0.0270 or 0.83 percent, and the November heating oil contract settled at 4.5694, up 0.0242 or 0.53 percent, per the provider’s records. On the settlement arithmetic the gasoline margin, 42 gallons times the gasoline settle less the WTI settle, widened to 48.03 from 46.91, and the heating oil margin widened to 102.47 from 101.47.
At 3:18 PM ET the President said he had been told the federal gasoline tax needs suspending and that he is thinking about it, per the news feed. No refinery utilisation figure and no seasonal demand series were captured, so neither is asserted.
4.5 Dollar and Cross-Asset (Dollar Index, Commodities Complex, Equity Risk Appetite)
The dollar index closed at 101.83, down 0.34 points or 0.33 percent, after a session range of 101.75 to 102.29, per the provider’s quote, and provider commentary tied the decline to the wider trade deficit and lower Treasury yields. The ten-year yield index closed at 5.26 percent, down five basis points from Monday’s close. A three-year note auction, per the news-feed calendar and unconfirmed, stopped at a high yield of 4.932 percent with a bid-to-cover of 2.620.
Brent’s December contract settled at 100.58, up 0.26 or 0.26 percent, so its premium over November WTI widened to 11.14 from 10.89. The S&P 500 cash index closed at 7,818.93, up 0.58 percent, and gold’s December contract settled at 4,187.1, up 30.3 points or 0.73 percent.
4.6 Institutional Positioning (Commitments Data, Money Manager and Commercial Hedger, Speculator Length)
The latest positioning report on the provider’s overview is still the one as of September 29, 2026: managed money long 209,028 contracts against short 129,436, a net long of 79,592, with commercials 873,637 long against 1,016,255 short, a net short of 142,618. The overview read for this session shows that September 29 report as its latest, so no change in positioning is asserted for Tuesday.
Open interest on the November contract is shown at 248,138, which is Monday’s figure on the dated 10/05 row, down from 258,251 on Friday’s 10/02 row; Tuesday’s open interest had not been reported at the time of capture, and the dated 10/06 row carries no open interest value. Tuesday’s volume was 234,969 contracts against Monday’s 274,982, on the dated 10/06 and 10/05 rows.
5. No liquid options proxy
Crude is covered here without a positioning dataset. There is no dealer-positioning surface read for this instrument, no gamma map, no options concentration levels and no flow attribution, and none is inferred from any other instrument. Every level in section 3 originates in published pivot arithmetic, published standard-deviation bands, published retracement and moving-average projections, settlement averages computed from the provider’s daily record, or the completed-session extremes described in section 2.1.
This is a statement about coverage, and listed crude options do exist. No such dataset was read, so no claim resting on one appears anywhere in this outlook. The positioning inputs used for crude are the weekly positioning report, the private and official inventory reports, the Brent spread and the product margins.
Night Session (6:00 PM ET Tuesday to 3:00 AM ET Wednesday, Globex and Asia)
The contract reopened at 6:00 PM ET Tuesday with the 4:50 PM ET private survey draw of 2.1 million barrels and the Treasury Secretary’s remark on Iranian loadings already released. A regional Federal Reserve president is listed at 7:00 PM ET Tuesday and German industrial production at 2:00 AM ET Wednesday, both per the news-feed calendar and unconfirmed. Bias neutral above the 88.78 Pivot Point, expected Globex band roughly 88.60 to 90.60 absent a headline shock, with Gulf and Hormuz headlines the gap risk in both directions.
London Session (3:00 AM ET to 8:00 AM ET Wednesday)
The captured calendars carry no crude-specific entry inside the London window; the 10:30 AM ET weekly petroleum report, on the calendar, is the next scheduled crude event. Tuesday’s 3.19 point range shows that two-way swings of more than three points remain possible inside a single session. Bias neutral, expected band roughly 88.40 to 90.80.
Morning Session (9:00 AM ET to 12:00 PM ET Wednesday, United States Open and Pit Session)
The weekly petroleum status report is scheduled for 10:30 AM ET on Wednesday, October 7, 2026, on the calendar, the first-order crude event of the day; the news-feed calendar lists a forecast build of 2 million barrels, against which the private survey’s 2.1 million barrel draw is the marker. A regional inflation-expectations survey is listed at 11:00 AM ET, per the news-feed calendar and unconfirmed. Expected band roughly 87.80 to 91.00, with the 90.71 to 90.87 band the first resistance.
Afternoon Session (12:00 PM ET to 2:30 PM ET Wednesday, NYMEX Pit Close)
A ten-year note auction is listed at 1:00 PM ET, per the news-feed calendar and unconfirmed, and the minutes of the September policy meeting follow at 2:00 PM ET on Wednesday, October 7, 2026, on the calendar. Crude settles at 2:30 PM ET, so the minutes land inside the final half hour before the settle. Expected band roughly 87.80 to 90.80.
Night Session Forward (6:00 PM ET Wednesday)
Consumer credit is scheduled for 3:00 PM ET on Wednesday, October 7, 2026, on the calendar, after the crude settle. A Federal Reserve governor speaks on the economic outlook at 4:30 AM ET on Thursday, October 8, 2026, on the calendar, inside the following overnight window.
Expected Range (Wednesday Full Session)
Low-range scenario: 88.60 to 90.60. Mid-range scenario (most likely): 87.50 to 91.00. High-range scenario: 85.30 to 93.60.
Most Likely Path
In our analyst judgment the most probable path holds the contract between the 88.78 Pivot Point and the 90.71 to 90.87 resistance band into the 10:30 AM ET weekly petroleum report, with the report deciding the side. A rally into that resistance band that fails beneath Pivot R2 at 91.97 is weighted above a sustained break higher, because Tuesday settled beneath the 5-day, 9-day and 20-day settlement averages, the composite read fell to 16 percent buy with direction weakening, and the 9-day directional system turned negative. The alternative that would invalidate this reading is a confirmed Hormuz escalation or a large official draw that lifts the contract through 91.97 and toward the 92.53 retracement.
7. Wednesday Economic Calendar
The Wednesday session reopened at 6:00 PM ET Tuesday. A regional Federal Reserve president is listed at 7:00 PM ET Tuesday, and the managing director of the International Monetary Fund and German industrial production are listed at 2:00 AM ET Wednesday, all per the news-feed calendar and unconfirmed.
The weekly petroleum status report is scheduled for 10:30 AM ET on Wednesday, October 7, 2026, on the calendar. A regional inflation-expectations survey and a European Central Bank speaker are listed at 11:00 AM ET, and a ten-year note auction at 1:00 PM ET, all per the news-feed calendar and unconfirmed. The minutes of the September policy meeting are scheduled for 2:00 PM ET on Wednesday, October 7, 2026, on the calendar. Crude settles at 2:30 PM ET, and consumer credit follows at 3:00 PM ET on Wednesday, October 7, 2026, on the calendar. The captured calendars carry no mega-capitalisation earnings entry for Wednesday.
The November contract’s expiration is listed as 10/20/26 by the provider, with first notice on 10/22/26. In our judgment the single first-order event for crude on Wednesday is the 10:30 AM ET weekly petroleum status report, on the calendar, with Hormuz and Gulf headlines the unscheduled risk in both directions. The minutes at 2:00 PM ET reach crude through the dollar.
8. Primary Trade Setup
Direction: Short
Rationale: Tuesday’s settle in the upper part of a range that reached a one-month low still sits beneath the 5-day, 9-day and 20-day settlement averages, the composite read fell to 16 percent buy with direction weakening, and the 9-day directional system turned negative; a rally into Pivot R1 at 90.71 and one standard deviation resistance at 90.87 offers a short with a defined risk point above Pivot R2 at 91.97. The long lower shadow and the reported tanker attacks show buyers still respond to Hormuz headlines, so the setup is an analyst judgment against live headline risk.
Entry Zone: 90.60 to 90.90
Stop Loss: 92.10 (above Pivot R2 at 91.97, three standard deviations resistance at 91.91 and Monday’s 91.88 high)
Target 1 (T1): 89.40 (four cents beneath the 89.44 Tuesday settle)
Target 2 (T2): 88.05 (four cents above one standard deviation support at 88.01)
Target 3 (T3, extended): 86.70 (16 cents beneath the 86.86 Tuesday low)
Risk-to-Reward: Approximately 1:1 to T1, 1:2 to T2, 1:3 to T3
Invalidation: A settle above Pivot R2 at 91.97 negates the thesis. Short of that, the edge is removed by acceptance above 91.46, defined as two consecutive 30-minute closes above 91.46.
Macro override: A confirmed escalation in the Strait of Hormuz that halts tanker traffic, or a weekly petroleum report with a draw far larger than the private survey’s 2.1 million barrels, would restore the supply premium. In that scenario a gap above the 92.10 stop removes the short before entry, and the 92.53 to 93.66 band becomes the reference within one 14-day average true range of 4.13 points.
Sources and methodology
This outlook is built from our session review of the November NYMEX WTI crude contract, CLX26, the November ’26 month, tracked on the continuous CL1! chart and prepared after Tuesday’s close on October 6, 2026 for the Wednesday, October 7, 2026 session. The contract domain was checked before any level was used: the daily chart’s completed Tuesday bar equals the provider’s settlement row, and the chart’s current Wednesday bar opened at 89.96, equal to the provider’s day open, while the provider’s published previous close of 89.44 equals the settlement, so chart and levels sit on the same November contract. The Globex session reopened at 6:00 PM ET Tuesday, so the day high, day low and open on the provider’s overview page belong to the Wednesday session and are not used as Tuesday’s range.
Tuesday’s session extremes are the completed-session inputs behind the published pivot ladder, back-solved from the outer pivot pairs, checked against all seven published rungs and reproduced by the chart’s daily bar and the settlement row. The 5-day, 9-day, 20-day, 50-day, 100-day and 200-day averages were computed from the provider’s 259-session daily settlement series, which leaves out the partial Wednesday row. Volume and open interest are quoted from the dated rows of that daily record for 10/02, 10/05 and 10/06; the 10/06 row carries volume 234,969 but no open interest value, so no Tuesday open interest is stated. The provider revised the 10/05 row after Tuesday’s outlook was written: it now reads volume 274,982 and open interest 248,138, where that outlook cited 247,100 contracts and no open interest value. This outlook uses the revised row. Oscillator readings are cited as published. No intraday series was preserved for Tuesday, so no claim is made about the order of Tuesday’s prints; the only sub-daily evidence used is the chart’s post-settlement 30-minute bars, 3:00 PM ET through 4:30 PM ET. No dealer-positioning dataset was read for crude, so no gamma, dealer-positioning or options-flow claim is made. Items marked unconfirmed come from the news-feed calendar captured for this session; catalysts whose time had passed when collection began are recorded as completed. Scenario ranges are analyst judgment and carry no calibration. Tuesday’s grade uses Tuesday’s open, high, low and settle as stated in tonight’s review and the dated 10/06 row of the daily record, which agree, and the setup card as published on Tuesday’s outlook.
Not captured, and stated nowhere as a figure: an intraday series for Tuesday, a four-hour series, a prior-quarter high or low, figures from the short-term energy outlook, a refinery utilisation figure, a seasonal demand series, Tuesday’s open interest, a positioning report newer than September 29, and a time stamp for the tanker reports or the Mokha recapture.
Tuesday’s outlook for this contract is here, and Tuesday’s gold outlook is here. Outlooks for the equity index, technology index, gold and crude contracts are collected on the market outlook page, and our forward trading record is on the performance statement.