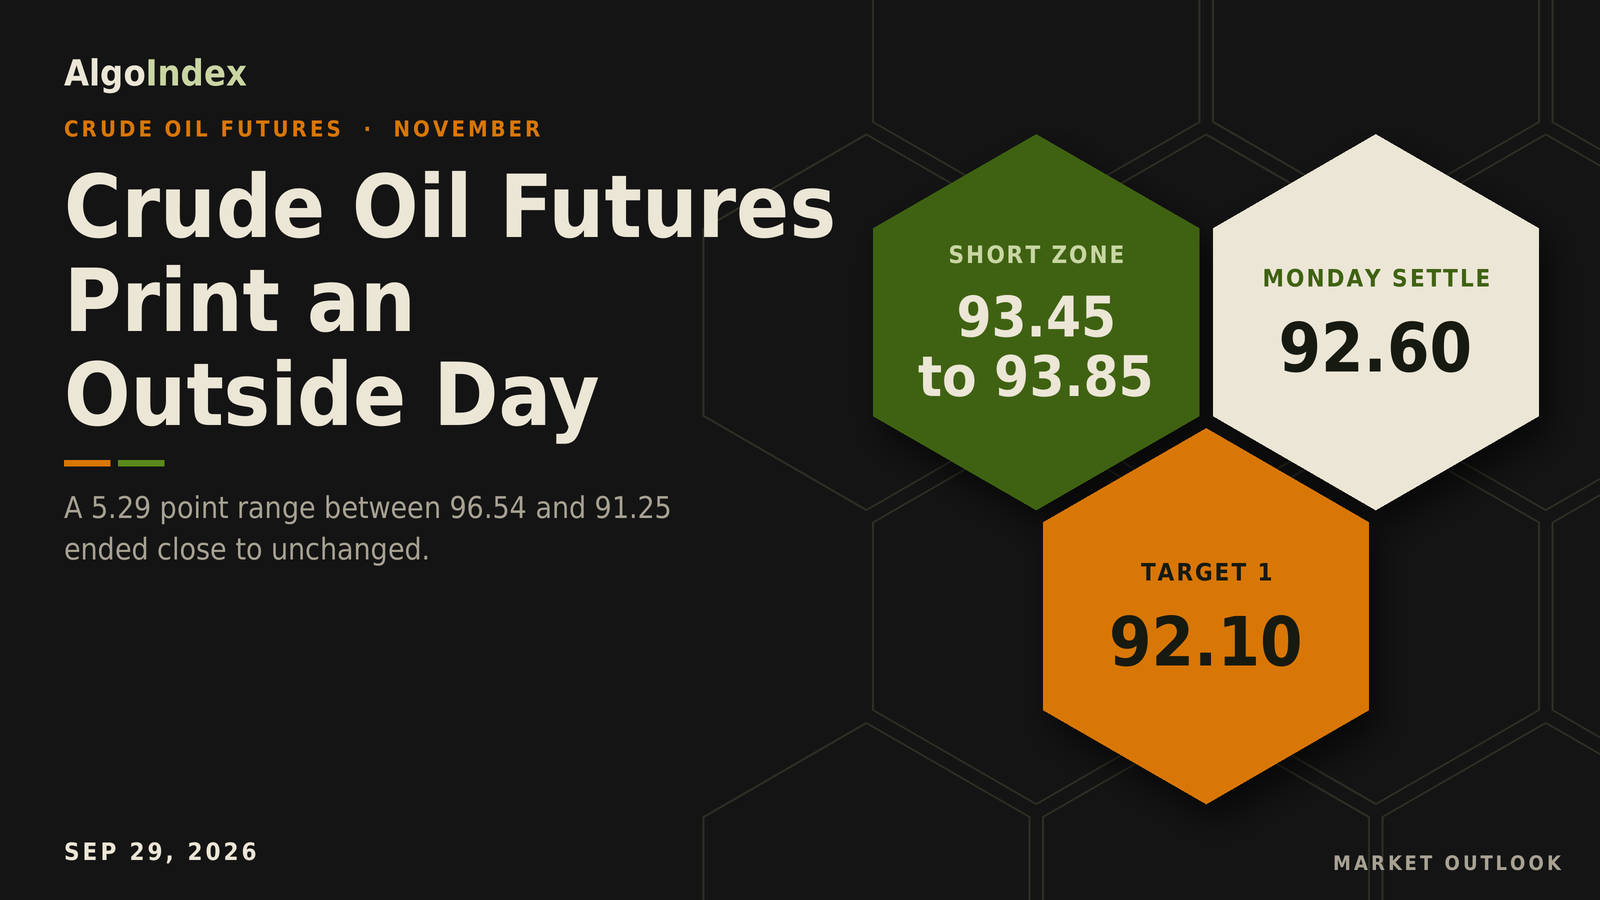
At 2:30 PM ET on Monday, November crude settled at 92.60, up 0.19 points or 0.21 percent from Friday's 92.41. The quiet close hid a violent day. The contract traded a 5.29 point band between 96.54 and 91.25, printed its high in the 7:00 AM ET bar and its low in the 1:00 PM ET bar, about six hours later, and settled at 25.5 percent of the range. Volume printed 348,010 contracts on the provider's dated daily record for Monday, against 345,783 on Friday.
Iran headlines ran both ways. The session opened after President Trump's weekend rejection of Iran's latest proposal, and crude climbed through the Asian and European hours while press reports carried it. At 12:16 PM ET the news feed quoted a United States official. Talks with Iran continue through intermediaries, the official said, and there would be no agreement without addressing the nuclear issue. Provider commentary attributed the reversal to a United States official saying the President is willing to offer sanctions relief in exchange for concrete nuclear progress. At 1:11 PM ET a press report said Iran had agreed to halt enrichment in exchange for eased sanctions. Those headlines and the drop fell in the same 30-minute bars. The series does not establish causation.
Then the reporting turned. After the settle an Iranian official called reports of nuclear flexibility incorrect at 3:29 PM ET. The news feed carried an explosion at Qeshm Island at 3:56 PM ET. At 4:26 PM ET Iranian state television described warning shots fired at vessels in the Strait of Hormuz. Electronic trade after the settle rose to 93.29 by the close of the 4:30 PM ET bar, and the Tuesday session reopened at 93.53. Brent's November contract settled at 105.28, up 0.96 points or 0.92 percent, so its premium over November WTI widened to 12.68 from 11.91. Crude remains the most volatile of the four instruments covered here. Its published 14-day average true range of 4.04 points is 4.36 percent of the settle.
November WTI settled at 92.60 after an outside day from 96.54 to 91.25. It closed at 25.5 percent of the range. The first overhead group runs 93.32 to 93.50: the target price, the 93.46 Pivot Point and the 9-day crossing, with 93.69, the 93.96 18-day crossing and 94.06 one-deviation resistance above. Support starts at 92.58 and the 92.46 5-day average, then 92.08 and the 91.14 to 91.27 group around Monday's low. The primary setup is a short from 93.45 to 93.85, stop 95.20, targets 92.10, 90.55 and 89.00. Tuesday carries the job openings report at 10:00 AM ET. No crude inventory release is listed. The mediated United States and Iran talks are the first-order event.
Friday's long, graded against the bar
Friday's outlook set a long from 93.80 to 94.20 around the 94.21 Pivot Point, with a stop at 92.30, targets at 95.70, 97.40 and 99.10, and an outright invalidation on a settle beneath Thursday's 91.23 low. Friday opened at 94.75, which was also its high, marked a 91.51 low and settled at 92.41. The band traded. Friday's range covered all of 93.80 to 94.20, reaching 55 cents above its top and 2.29 points beneath its bottom.
We put the stop at 92.30. Friday's low printed 91.51, 79 cents beneath it, and the settle finished 11 cents above it. No target traded. The high stopped 95 cents short of the 95.70 first target. A daily bar cannot show the order in which the band and the stop level were reached, so this outlook asserts no fill and no result for the card.
The outright invalidation held. Friday's low sat 28 cents above 91.23 and the settle 1.18 above it. The card's acceptance clause needed two consecutive 30-minute closes beneath 93.06 with the 92.85 retracement also lost. Friday settled 65 cents beneath 93.06 and 44 cents beneath 92.85; no Friday 30-minute series is part of tonight's data, so that clause cannot be scored. The macro override named a confirmed agreement to reopen the Strait of Hormuz. No such agreement appears in the reporting available tonight.
The range work missed low. The low-range case, 93.30 to 95.90, lost its bottom by 1.79 points at the low and by 89 cents at the settle. The most likely band, 92.60 to 96.80, gave way by 1.09 at the low and by 19 cents at the settle. Only the high-range case, 91.20 to 98.40, held the whole bar, with 31 cents to spare at the low.
The path call missed too. That outlook judged a settle between the pivot and the 96.78 to 97.18 zone the likelier outcome, and it named a settle beneath the 93.81 to 93.84 pair as the case that would put the 92.42 to 92.85 group back in play. Friday settled at 92.41, 1.40 beneath 93.81 and one cent under that group. The session-by-session bands cannot be scored from a daily bar.
No outlook was published for Monday. Monday's session follows without a card to grade.
An outside day, the high first and the low about six hours later
Monday swallowed Friday. The 96.54 high sat 1.79 points above Friday's 94.75 high and the 91.25 low 26 cents beneath Friday's 91.51 low, which makes Monday an outside day, and the settle landed 19 cents above Friday's. The high was the best print since Thursday's 96.78 and the low the weakest since Thursday's 91.23. Monday touched the edges of Thursday's range on both sides and broke neither. Its 5.29 point band was 1.15 times the published 14-day average daily range of 4.60 points, the widest session since the 5.55 point day of 09/24.
The provider's 30-minute series, 46 bars from the reopen through the 4:30 PM ET bar, fixes the order. The Sunday 6:00 PM ET reopen came at 93.58, 1.17 points above Friday's settle, and the bars through midnight ET held between 92.68 and 94.33. Europe did the lifting. The 4:30 AM ET bar reached 95.61, the 6:00 AM ET bar 96.47 and the 7:00 AM ET bar the 96.54 high. The 8:00 AM ET to 10:00 AM ET bars gave the move back to a 93.70 low. A second push reached 95.70 in the 10:30 AM ET bar.
Midday broke it. The 12:00 PM ET bar fell from 95.02 to a 91.99 low, 3.14 points beneath its own 95.13 high. The 1:00 PM ET bar marked the 91.25 session low and closed at 92.84. Settlement at 2:30 PM ET came at 92.60, 3.94 points beneath the high, so a session that carried the contract to its best level since Thursday ended close to unchanged.
The extremes are the completed-session inputs behind the published pivot ladder, back-solved from its outer pairs. The third resistance point at 100.97 minus the third support point at 85.10, divided by three, returns 5.29, and 98.75 minus 88.17, divided by two, returns the same. Three times the 93.46 Pivot Point less the 92.60 settle gives a 187.78 high-plus-low sum, and 96.54 with 91.25 reproduces all seven rungs. The ladder checks out. The chart's completed Monday bar reads 93.58, 96.54, 91.25 and 92.60. The provider's overview page now shows Tuesday's session, with a 93.53 open, a 93.77 high and a 93.12 low, and none of those is used as Monday's range.
Zoom out and Monday stayed in the box. The prior week, September 21 through September 25, spanned 97.22 to 88.67, and Monday sat entirely inside it. The 52-week, 13-week and one-month high of 101.69, set on 09/15/26, sits 9.09 points above the settle, and the one-month low of 82.47, set on 08/31/26, 10.13 points beneath it. Across five sessions the contract gained 0.23 points or 0.25 percent from the 92.37 settle of 09/21. No prior-quarter high or low was captured, so the 13-week extremes stand in as the quarterly reference.
Ten settles tell the swing: 100.75, 97.51, 97.23, 96.08, 92.37, 90.52, 92.16, 94.61, 92.41 and 92.60. The swing low is still the 90.52 settle of 09/22, with the 88.67 intraday low the same day. Thursday's 96.78 remains the swing high inside the decline. Monday approached it and fell short. Daily ranges for the last six sessions ran 6.03, 5.17, 4.35, 5.55, 3.24 and 5.29.
The retracement grid published for Tuesday places the 38.2 percent retracement from the four-week high at 94.35, the 50 percent retracement of the four-week range at 92.08 and the 38.2 percent retracement from the four-week low at 89.81. The 38.2 percent retracement from the 13-week high sits at 88.47. No four-hour series was captured. The 30-minute series is the only intraday evidence.
The averages come from the provider's daily settlement series for the November contract, 259 completed sessions through Monday. The 5-day stands at 92.46, the 9-day at 93.94, the 20-day at 92.87, the 50-day at 85.03, the 100-day at 81.38 and the 200-day at 74.32. The settle sits 14 cents above the 5-day, 27 cents beneath the 20-day and 1.34 points beneath the 9-day; the 50-day sits 7.57 points beneath the settle. On Friday the 20-day stood at 92.34 and the 5-day at 92.41.
The window mechanics matter here. Monday's settle replaced the 09/21 settle of 92.37 in the 5-day window and the 08/28 settle of 81.83 in the 20-day window, so the 20-day rose 54 cents while the settle rose 19. The 9-day fell to 93.94 from 94.85 as the 09/15 settle of 100.75 left its window. The projection grid puts Tuesday's crossings at 93.50 for the 9-day, 93.96 for the 18-day and 86.70 for the 40-day.
Oscillators are cited as published for the Tuesday session. That page was read after the 6:00 PM ET reopen, so the latest value in each may include live Globex trade. Relative strength reads 50.68 on the 9-day, 54.56 on the 14-day, 56.33 on the 20-day and 56.49 on the 50-day. Stochastics sit in the lower half. The 9-day raw stochastic reads 32.91 percent and the 14-day 30.18 percent, with %K at 38.87 percent and %D at 40.71 percent; the 20-day reads 52.71 percent. The 14-3 day raw stochastic's 30 percent threshold sits at 92.58, two cents beneath the settle, and its 50 percent threshold at 95.18.
Direction still points up. On the 9-day the directional index reads 31.99 with positive direction at 23.90 and negative at 13.61; the 14-day reads 29.74, positive at 25.17 over negative at 14.05. Historic volatility runs 32.39 percent on the 9-day and 44.54 percent on the 14-day. The composite multi-indicator read for Tuesday fell to 48 percent buy from 64 percent in the prior session's snapshot. It read 48 percent a week ago and 24 percent a month ago, with signal strength and direction both described as average. The short-horizon group averages 20 percent buy, the medium-horizon group 25 percent and the long-horizon group 100 percent.
Volatility sets the scale. The published 14-day average true range stands at 4.04 points and the 14-day average daily range at 4.60; the 9-day figures are 4.32 and 4.49, the 20-day figures 3.82 and 4.13. Monday's range expanded after Friday's 3.24 point contraction. A one-range projection from 92.60 on the 14-day average true range frames Tuesday between 88.56 and 96.64. The published deviation bands are narrower because they are built from five settlements: one deviation spans 91.14 to 94.06, two spans 90.54 to 94.66 and three spans 90.08 to 95.12. Monday's 96.54 high sat 1.42 points above that top band. The bands describe settlement dispersion and say nothing about intraday reach.
Iran headlines both ways and a split product side
Every element of Monday's reporting is reporting, and none of it is settled fact. The session opened after the weekend rejection of Iran's seven-day proposal, and at 8:04 AM ET the news feed reported that mediators expected to hold separate talks with the United States and Iran on Monday or Tuesday. The 12:16 PM ET item and the 1:11 PM ET press report both leaned toward de-escalation. Both coincided with the bars in which crude fell from 95.13 to 91.25.
After the settle the reporting turned harder. At 3:18 PM ET an Iranian lawmaker said parliament is weighing a bill to leave the nuclear non-proliferation treaty. At 3:29 PM ET and 3:30 PM ET an Iranian official called reports of nuclear flexibility incorrect. At 3:43 PM ET Iraq's Hezbollah said a continued air embargo on Iran after October 1 would close Iraqi border crossings with sanctioning countries. At 3:55 PM ET a press report said the new Iranian proposal carries no nuclear commitments until after its first phase. At 3:56 PM ET the news feed carried an explosion heard at Qeshm Island.
Then came the Strait. At 4:03 PM ET and 4:04 PM ET the deputy chairman of Iran's national security committee said the Strait of Hormuz is now at the center of negotiations in place of the nuclear file, and that the United States must accept Iran's conditions first. At 4:26 PM ET Iranian state television described warning shots fired at vessels in the Strait. Electronic crude traded higher after these items, from the 92.60 settle to 93.29 at the close of the 4:30 PM ET bar. Nothing captured a Venezuela or Russia-Ukraine supply development.
Supply policy is quiet. No producer-group quota decision, compliance table or Saudi or Russian policy signal was captured. A 3:32 PM ET item said the Saudi foreign minister and the United States Secretary of State discussed the region and Yemen, which is diplomatic context. At 6:01 PM ET an energy-news item, attributed to an investment-bank note, argued that record long positions held by systematic trend-following funds are capping crude's upside. That is commentary. No measured positioning figure stands behind it.
Inventories were quiet too. No release fell on Monday on the captured calendars, and the news-feed calendar lists the previous weekly crude change as a build of 2.969 million barrels. The next weekly petroleum status report is scheduled for 10:30 AM ET on September 30, 2026, per the verified forward calendar. No strategic reserve decision was captured.
The product complex split. November gasoline settled at 3.1578 dollars a gallon, down 0.0297 or 0.93 percent. November heating oil settled at 4.4953, up 0.0332 or 0.74 percent, per the provider's daily record. Provider commentary described the crude crack spread as falling to a one-month low, which discourages refiners from buying crude, a demand-side negative for the flat price. The diesel policy question advanced as well. A 12:38 PM ET press report said the White House is weighing tax relief on red-dyed diesel, and a 12:42 PM ET item said the Texas governor waived dyed-diesel restrictions. No refinery utilisation figure or seasonal demand series was captured.
Yields rose. The dollar index closed at 101.20, up 0.23 points or 0.23 percent. The ten-year yield index closed at 5.24 percent, up 6 basis points, after a 5.20 to 5.27 range, and provider commentary described the 5.27 percent high as a 19-year high; the thirty-year closed at 5.56 percent. Provider commentary cited market pricing of a 70 percent chance of a quarter-point rate increase at the October 27 to 28 policy meeting, and reported that a Federal Reserve governor said the labour market seems well positioned to handle higher rates.
Equities and metals fell. The S&P 500 cash index closed at 7,683.69, down 59.72 points or 0.77 percent, and the Nasdaq-100 cash index at 30,276.81, down 1.08 percent. The volatility index closed at 16.07, up 1.20 points. Gold's December contract settled at 4,168.4, down 152.8 points or 3.54 percent, and silver's December contract fell 4.76 percent. Crude was the only one of the four instruments covered here to settle higher, which in our interpretation reflects the Strait premium offsetting the rates and dollar pressure that hit the others.
The positioning report as of September 22, 2026 is the same snapshot cited a week ago. Managed money held 223,190 contracts long against 121,362 short, a net long of 101,828. Commercials held 847,389 long against 1,017,278 short, a net short of 169,889, and swap dealers 111,924 long against 584,713 short. The next report covers positions as of Tuesday, September 29. Open interest on November stood at 294,853 on Monday's row, 282 contracts above Friday's 294,571. In our interpretation a near-unchanged open interest across an outside day with a 5.29 point range points to turnover more than net new positions; that is a reading of two rows, with no attribution of who traded.
One gap is deliberate. No dealer-positioning dataset was read for crude: no gamma map, no options concentration levels and no flow attribution, and none is borrowed from another instrument. Every level here comes from published pivot arithmetic, published deviation bands, published retracement and average projections, settlement averages computed from the daily record, or the back-solved session extremes.
The trade map for Tuesday
Overhead, three references sit inside 18 cents. They are the published target price at 93.32, the Pivot Point at 93.46 and the 9-day crossing at 93.50. The moving-average convergence stall at 93.69 and the 18-day crossing at 93.96 sit above them, and one deviation resistance at 94.06 closes that group. The 9-day average itself stands at 93.94. The next band runs from the 94.35 retracement through the 94.45 %k stall to two deviation resistance at 94.66, with Friday's 94.75 high just above. Three deviation resistance at 95.12, the stochastic 50 percent threshold at 95.18 and Pivot R1 at 95.68 form the upper band, and Monday's 95.70 secondary high sits two cents above R1. The extended references are Monday's 96.54 high, Thursday's 96.78 and the 97.22 prior-week high. Pivot R2 at 98.75 lies beyond them.
Beneath the settle, the 92.58 stochastic threshold and the 92.46 5-day average come first, then the 92.08 half retracement. Monday's 91.25 low and the 91.27 stochastic 20 percent threshold sit two cents apart, with Thursday's 91.23 low beneath them and one deviation support at 91.14 closing that group; Friday's 91.51 low sits above it. Then a 23 cent group: the 90.62 crossover stall, two deviation support at 90.54, the 90.43 relative-strength 50 percent line and Pivot S1 at 90.39, with the 90.52 swing-low settle inside it. Three deviation support at 90.08 sits beneath. The 89.81 retracement, the 88.67 low of 09/22, the 88.47 retracement and Pivot S2 at 88.17 are the deeper references.
The primary setup is a short from a rebound into 93.45 to 93.85. That band sits around the 93.46 Pivot Point and beneath the 93.96 18-day crossing. Monday's outside day finished at 25.5 percent of a 5.29 point range, beneath the 93.46 Pivot Point and the 20-day settlement average of 92.87. Gasoline fell. The composite read dropped from 64 to 48 percent buy. A rebound into the target price and pivot group offers a short with a defined risk point above the three-deviation band. The directional readings remain positive and the Strait headlines after the settle argue the other way, so the setup is an analyst judgment against a live escalation risk. The 14-day average true range is 4.04 points. The stop sits 1.55 from the 93.65 entry midpoint.
The reopen sits near the entry band. The Tuesday session reopened at 93.53 at 6:00 PM ET. Post-settlement trade had already lifted the contract from 92.60 to 93.29. The Reserve Bank of Australia decision is listed for 12:30 AM ET Tuesday, forecast 4.6 percent against 4.35 percent, per the news-feed calendar and unconfirmed. The night session starts just above the 93.32 to 93.50 group, so the first test is whether the post-settlement rebound holds above it. Bias is neutral to mildly lower beneath 93.96. The expected Globex band is roughly 91.90 to 94.70, and a fresh Strait incident is the risk that would carry it above 94.75.
Europe carries Swiss business survey data at 3:00 AM ET, a European Central Bank board member at 4:00 AM ET and Bank of England consumer credit at 4:30 AM ET, all per the news-feed calendar and unconfirmed. The same calendar lists potential United States and Iran talks as tentative at 8:00 AM ET, unconfirmed. Monday's high printed in this window. The European hours are where the Strait premium has been priced most recently. Bias is neutral, with an expected band of roughly 91.80 to 94.90.
New York brings the job openings report at 10:00 AM ET, per the verified forward calendar, and the Conference Board consumer confidence index at 10:00 AM ET, forecast 89.1 against 89.4, per the news-feed calendar and unconfirmed. A Federal Reserve vice chair's pre-recorded remarks follow at 11:00 AM ET, per the verified forward calendar. The transmission to crude runs through the dollar and the ten-year yield, which printed a 5.27 percent high on Monday. A hold beneath 93.96 through the morning keeps the 91.14 to 92.08 group in reach; acceptance above 94.06 returns the contract toward the 94.66 to 95.18 band. Expected band roughly 91.20 to 95.00.
The afternoon holds the reversal risk. A Federal Reserve governor speaks on the economic outlook at 12:40 PM ET, per the verified forward calendar, and further regional Federal Reserve presidents are listed at 1:00 PM ET, 1:30 PM ET and 2:00 PM ET, per the news-feed calendar and unconfirmed. Crude settles at 2:30 PM ET. Monday's reversal came in this window, so a headline in the negotiations is the main source of range expansion. Expected band roughly 91.00 to 94.80.
Once the pit closes, a Federal Reserve governor speaks on payments at 3:00 PM ET, per the verified forward calendar, while the electronic session is still open. Tuesday evening's Globex session leads into Chinese manufacturing survey data at 9:30 PM ET, per the news-feed calendar and unconfirmed. The weekly anchor for crude is the weekly petroleum status report at 10:30 AM ET on September 30, 2026. Personal income and outlays print at 08:30 AM ET the same day and the employment report at 08:30 AM ET on October 2, 2026, all per the verified forward calendar. The provider lists the November contract's expiration as 10/20/26.
Three scenarios frame the full session: 91.80 to 93.90 on the low-range case, 90.90 to 94.70 on the mid-range case, which is the most likely, and 89.40 to 96.60 on the high-range case. In our analyst judgment the most probable path holds Globex beneath the 93.96 18-day crossing as the post-settlement Strait headlines are digested, and rotates between the 92.08 retracement and the 93.46 Pivot Point through the European hours. Through the United States morning the contract tests the 91.14 to 91.27 group around Monday's 91.25 low. A settle between 90.54 and 93.46 is weighted above a settle outside that band. The weighting rests on three readings. Monday's outside day finished at 25.5 percent of its range, gasoline fell while crude held, and the composite read dropped to 48 percent buy. A security incident in the Strait or a collapse of the mediated talks would invalidate this reading and put the 94.66 to 95.68 band back in play.
Monday's high stopped 24 cents under Thursday's and its low two cents over Thursday's. Tuesday reopened between them at 93.53.
The complete data picture
Every number behind Tuesday’s plan, charted first, then the full level lists, then the complete numeric reference underneath.
Full numeric reference, every remaining figure from the session review
Carried below in the review’s own order: the executive summary from section 1, sections 2.1 to 2.6, the level notes from sections 3.1 and 3.2, sections 4.1 to 4.6, the coverage note from section 5, the session-by-session forecast from section 6, the Tuesday calendar from section 7 and the primary setup from section 8.
3.1 Resistance and 3.2 Support, level notes
The first overhead references are the published target price at 93.32, the Pivot Point at 93.46 and the 9-day average crossing at 93.50, three references inside 18 cents, with the moving-average convergence stall at 93.69 and the 18-day average crossing at 93.96 above them. One standard deviation resistance at 94.06 closes that group.
The next band runs from the 38.2 percent retracement at 94.35 through the 14-day %k stall at 94.45 to two standard deviations resistance at 94.66, with Friday's 94.75 high just above. Three standard deviations resistance at 95.12, the stochastic 50 percent threshold at 95.18 and Pivot R1 at 95.68 form the upper band, and Monday's 95.70 secondary high in the 10:30 AM ET bar sits two cents above Pivot R1. Monday's 96.54 high, Thursday's 96.78 high and the 97.22 high of the prior week are the extended references, with Pivot R2 at 98.75 beyond them.
The stochastic 30 percent threshold at 92.58 and the 5-day settlement average at 92.46 sit directly beneath the settle, and the 50 percent retracement of the four-week range at 92.08 follows. Monday's 91.25 low and the stochastic 20 percent threshold at 91.27 sit two cents apart, with Thursday's 91.23 low beneath them and one standard deviation support at 91.14 closing that group.
Beneath that, the three-and-ten day crossover stall at 90.62, two standard deviations support at 90.54, the relative-strength 50 percent line at 90.43 and Pivot S1 at 90.39 cover 23 cents, and three standard deviations support at 90.08 sits beneath them. The 38.2 percent retracement from the four-week low at 89.81, the 88.67 low of 09/22, the 38.2 percent retracement from the 13-week high at 88.47 and Pivot S2 at 88.17 are the deeper references.
1. Executive Summary
The November crude contract settled at 92.60 on Monday, up 0.19 points or 0.21 percent from Friday's 92.41 settle, after trading a 5.29 point band between 96.54 and 91.25. The settle finished at 25.5 percent of that range, 3.94 points beneath the session high, so a session that carried the contract to its highest level since Thursday ended close to unchanged. Monday's high sits 1.79 points above Friday's 94.75 high and its low sits 26 cents beneath Friday's 91.51 low, which makes Monday an outside day, and the 5.29 point range was 1.15 times the published 14-day average daily range of 4.60 points and the widest daily range since the 5.55 point session of 09/24.
The session had two halves, and the provider's 30-minute series shows them. From the Sunday 6:00 PM ET reopen at 93.58 the contract climbed through the Asian and European hours to the 96.54 session high in the 7:00 AM ET bar, as press reports carried President Trump's weekend rejection of Iran's latest proposal. The advance then faded, a second push reached 95.70 in the 10:30 AM ET bar, and the 12:00 PM ET bar fell from 95.02 to a 91.99 low. That bar coincided with a news-feed item at 12:16 PM ET quoting a United States official that talks with Iran continue through intermediaries and that there would be no agreement without addressing the nuclear issue; provider commentary attributed the reversal to a United States official saying the President is willing to offer sanctions relief in exchange for concrete nuclear progress. The 1:00 PM ET bar printed the 91.25 session low and contained a 1:11 PM ET press report that Iran had agreed to halt uranium enrichment in exchange for eased sanctions. The headlines and the moves coincided in the same bars; the series does not establish causation.
After the 2:30 PM ET settle the diplomatic reporting turned the other way. An Iranian official called reports of nuclear flexibility incorrect at 3:29 PM ET, the news feed carried an explosion at Qeshm Island at 3:56 PM ET, and Iranian state television described warning shots fired at vessels in the Strait of Hormuz at 4:26 PM ET. Electronic trade after the settle rose to 93.29 by the close of the 4:30 PM ET bar, and the Tuesday session reopened at 93.53. Brent's November contract settled at 105.28, up 0.96 points or 0.92 percent, so the Brent premium over the November WTI contract widened to 12.68 from 11.91 on Friday. Crude remains the most volatile of the four instruments covered here; the published 14-day average true range of 4.04 points is 4.36 percent of the settle.
The primary setup is a short from the 93.45 to 93.85 band around the standard Pivot Point, stopped above the three-deviation band, with objectives at 92.10, 90.55 and an extended 89.00.
2.1 Intraday and Session Review
The Monday session opened at 93.58 at the Sunday 6:00 PM ET reopen, 1.17 points above Friday's settle, marked a high of 96.54 and a low of 91.25, and settled at 92.60. The provider's 30-minute series, 46 bars from the reopen through the 4:30 PM ET bar, fixes the order of those extremes: the high printed in the 7:00 AM ET bar and the low printed in the 1:00 PM ET bar, so the session made its high first and its low about six hours later.
The Asian hours were contained, with the bars from the reopen through midnight ET holding between 92.68 and 94.33. The advance came in the European morning: the 4:30 AM ET bar reached 95.61, the 6:00 AM ET bar 96.47 and the 7:00 AM ET bar 96.54. The 8:00 AM ET to 10:00 AM ET bars gave back the move to a 93.70 low, the 10:30 AM ET bar recovered to 95.70, and the 12:00 PM ET bar fell 3.14 points from its 95.13 high to its 91.99 low. The 1:00 PM ET bar marked the 91.25 low and closed at 92.84, and the settlement at 2:30 PM ET was 92.60.
The session extremes used here are also the completed-session inputs behind the published pivot ladder, back-solved from the outer pivot pairs and verified against every rung. The third resistance point at 100.97 minus the third support point at 85.10, divided by three, returns 5.29, and the second resistance point at 98.75 minus the second support point at 88.17, divided by two, returns the same 5.29. Three times the Pivot Point of 93.46 less the 92.60 settle gives a high plus low sum of 187.78, and the resulting pair of 96.54 and 91.25 reproduces all seven published rungs. The chart's completed Monday daily bar reads 93.58, 96.54, 91.25 and 92.60, an independent confirmation of the same values.
The same dated daily record shows Monday's volume at 348,010 contracts against 345,783 on Friday, and open interest at 294,853 against 294,571.
Because Globex reopened at 6:00 PM ET, the provider's overview page now shows the Tuesday session: its open of 93.53, high of 93.77 and low of 93.12 belong to the new session and are not used as Monday's range anywhere in this outlook.
2.2 Daily Structure
Monday is an outside day against Friday: the 96.54 high exceeds Friday's 94.75 and the 91.25 low undercuts Friday's 91.51, and the settle landed 19 cents above Friday's. The high is the highest print since Thursday's 96.78 and the low the lowest since Thursday's 91.23, so Monday retraced to the edges of Thursday's range on both sides without breaking either.
The prior week, September 21 through September 25, spanned 97.22 to 88.67. Monday's session sits entirely inside that weekly range. The 52-week, 13-week and one-month high of 101.69, set on 09/15/26, sits 9.09 points above the settle, and the one-month low of 82.47, set on 08/31/26, sits 10.13 points beneath it. Across five sessions the contract gained 0.23 points or 0.25 percent from the 92.37 settle of 09/21.
No prior-quarter high or low was captured, so the 13-week extremes serve as the available quarterly reference.
2.3 4-Hour and Swing Structure
The daily settlement sequence after the 09/15 peak reads 100.75, 97.51, 97.23, 96.08, 92.37, 90.52, 92.16, 94.61, 92.41 and 92.60. The swing low remains the 90.52 settle of 09/22 with the 88.67 intraday low of the same day, and the swing high inside the decline remains Thursday's 96.78, which Monday's 96.54 approached without exceeding. Daily ranges for the last six sessions ran 6.03, 5.17, 4.35, 5.55, 3.24 and 5.29.
The retracement grid published for Tuesday places the 38.2 percent retracement from the four-week high at 94.35, the 50 percent retracement of the four-week range at 92.08 and the 38.2 percent retracement from the four-week low at 89.81. The 38.2 percent retracement from the 13-week high sits at 88.47. No four-hour series was captured; the 30-minute series in section 2.1 is the only intraday evidence used.
2.4 Moving Averages
The averages cited in this subsection were computed from the provider's daily settlement series for the November contract, which holds 259 completed sessions through Monday. The 5-day average stands at 92.46, the 9-day at 93.94, the 20-day at 92.87, the 50-day at 85.03, the 100-day at 81.38 and the 200-day at 74.32.
The 92.60 settle sits 14 cents above the 5-day average, 27 cents beneath the 20-day and 1.34 points beneath the 9-day, while the 50-day average sits 7.57 points beneath the settle. On Friday the 20-day stood at 92.34 and the 5-day at 92.41; Monday's settle replaced the 09/21 settle of 92.37 in the 5-day window and the 08/28 settle of 81.83 in the 20-day window, so the 20-day rose 54 cents while the settle rose 19 cents. The 9-day fell to 93.94 from 94.85 as the 09/15 settle of 100.75 left its window.
The projection grid gives the prices at which each average would be crossed on Tuesday: 93.50 for the 9-day, 93.96 for the 18-day and 86.70 for the 40-day.
2.5 Oscillator and Trend Readings
The oscillator figures below are as published on the provider's technical page dated for the Tuesday session, which was read after the 6:00 PM ET reopen, so the most recent value in each may include live Globex trade. Relative strength reads 50.68 on the 9-day, 54.56 on the 14-day, 56.33 on the 20-day and 56.49 on the 50-day.
Stochastics sit in the lower half. The 9-day raw stochastic reads 32.91 percent and the 14-day 30.18 percent, with the 14-day %K at 38.87 percent and %D at 40.71 percent; the 20-day raw stochastic reads 52.71 percent. The published grid places the 14-3 day raw stochastic 30 percent threshold at 92.58, two cents beneath the settle, and its 50 percent threshold at 95.18.
The directional system still points up on every horizon read. On the 9-day the directional index reads 31.99 with positive direction at 23.90 and negative direction at 13.61; on the 14-day it reads 29.74 with positive direction at 25.17 over negative at 14.05. Historic volatility reads 32.39 percent on the 9-day and 44.54 percent on the 14-day.
The composite multi-indicator read published for Tuesday is 48 percent buy, down from 64 percent buy in the prior session's snapshot, with signal strength and direction both described as average. The snapshot history reads 48 percent buy a week ago and 24 percent buy a month ago. Underneath the headline the short-horizon group averages 20 percent buy, the medium-horizon group 25 percent buy and the long-horizon group 100 percent buy.
2.6 Volatility and Expected Range
The published 14-day average true range stands at 4.04 points and the 14-day average daily range at 4.60 points; the 9-day figures are 4.32 and 4.49, and the 20-day figures 3.82 and 4.13. Monday's 5.29 point range was 1.15 times the 14-day average daily range, an expansion after Friday's 3.24 point contraction.
A one-range projection from the 92.60 settle using the 14-day average true range frames Tuesday between 88.56 and 96.64. The published standard-deviation bands are narrower because they are built from five settlements: one deviation spans 91.14 to 94.06, two spans 90.54 to 94.66 and three spans 90.08 to 95.12, each centred on the settle, 1.46, 2.06 and 2.52 points either side. Monday's 96.54 high sat above the upper three-deviation value, which is a reminder that these bands describe settlement dispersion, not intraday reach.
4.1 OPEC and Supply Policy (Quotas, Compliance, Saudi and Russia Signals)
No producer-group quota decision, compliance table or Saudi or Russian policy signal was captured. The news feed carried a statement at 3:32 PM ET that the Saudi foreign minister and the United States Secretary of State discussed the region and Yemen, which is diplomatic context rather than supply policy. An energy-news item in the feed at 6:01 PM ET, attributed to an investment-bank note, argued that record long positions held by systematic trend-following funds are capping crude's upside; that is commentary, not a measured positioning figure.
4.2 Inventory Data (Crude Stocks, Gasoline, Distillates, Cushing, Strategic Reserve)
No inventory release fell on Monday on the captured calendars. The news-feed calendar lists the previous weekly crude change as a build of 2.969 million barrels. The next weekly petroleum status report is scheduled for 10:30 AM ET on September 30, 2026, per the verified forward calendar. No strategic reserve decision was captured.
4.3 Geopolitical Backdrop (Middle East, Iran, Russia and Ukraine, Venezuela)
Monday's reporting ran in both directions and every element of it is reporting rather than settled fact. The session opened after President Trump's weekend rejection of Iran's seven-day proposal, and the news feed at 8:04 AM ET reported that mediators expected to hold separate talks with the United States and Iran on Monday or Tuesday. The 12:16 PM ET item quoting a United States official and the 1:11 PM ET press report that Iran had agreed to halt enrichment in exchange for eased sanctions both leaned toward de-escalation, and both coincided with the bars in which crude fell from 95.13 to 91.25.
After the settle the reporting turned harder. At 3:29 PM ET and 3:30 PM ET an Iranian official said reports of flexibility on the nuclear stance were incorrect; at 3:55 PM ET a press report said the new Iranian proposal carries no nuclear commitments until after its first phase; at 4:03 PM ET and 4:04 PM ET the deputy chairman of Iran's national security committee said the Strait of Hormuz, not the nuclear file, is now at the center of negotiations and that the United States must accept Iran's conditions first. The news feed carried an explosion heard at Qeshm Island at 3:56 PM ET and, at 4:26 PM ET, Iranian state television describing warning shots fired at vessels in the Strait. An Iranian lawmaker said at 3:18 PM ET that parliament is weighing a bill to leave the nuclear non-proliferation treaty, and Iraq's Hezbollah said at 3:43 PM ET that a continued air embargo on Iran after October 1 would close Iraqi border crossings with sanctioning countries. Electronic crude traded higher after these items, from the 92.60 settle to 93.29 at the close of the 4:30 PM ET bar. Nothing captured a Venezuela or Russia-Ukraine supply development.
4.4 Demand and Refining (Refinery Utilisation, Crack Spreads, Seasonal Pattern)
The product complex split. The November gasoline contract settled at 3.1578 dollars a gallon, down 0.0297 or 0.93 percent, while the November heating oil contract settled at 4.4953, up 0.0332 or 0.74 percent, per the provider's daily record. Provider commentary described the crude crack spread as falling to a one-month low, which discourages refiners from buying crude, a demand-side negative for the flat price.
The diesel policy question advanced at the state and federal level: the news feed carried a press report at 12:38 PM ET that the White House is weighing tax relief on red-dyed diesel and a 12:42 PM ET item that the Texas governor waived dyed-diesel restrictions. No refinery utilisation figure and no seasonal demand series were captured, so neither is asserted.
4.5 Dollar and Cross-Asset (Dollar Index, Commodities Complex, Equity Risk Appetite)
The dollar index closed at 101.20, up 0.23 points or 0.23 percent. The ten-year yield index closed at 5.24 percent, up 6 basis points, after a 5.20 to 5.27 range, and provider commentary described the 5.27 percent high as a 19-year high; the thirty-year closed at 5.56 percent. Provider commentary cited market pricing of a 70 percent chance of a quarter-point rate increase at the October 27 to 28 policy meeting and reported that a Federal Reserve governor said the labour market seems well positioned to handle higher rates.
Equities and metals fell. The S&P 500 cash index closed at 7,683.69, down 59.72 points or 0.77 percent, and the Nasdaq-100 cash index at 30,276.81, down 1.08 percent. The volatility index closed at 16.07, up 1.20 points. Gold's December contract settled at 4,168.4, down 152.8 points or 3.54 percent, and silver's December contract fell 4.76 percent. Crude was the only one of the four instruments covered here to settle higher, which in this outlook's interpretation reflects the Strait premium offsetting the rates and dollar pressure that hit the others.
4.6 Institutional Positioning (Commitments Data, Money Manager and Commercial Hedger, Speculator Length)
The positioning report as of September 22, 2026, unchanged since the prior week's outlook, shows managed money long 223,190 contracts against short 121,362, a net long of 101,828. Commercials held 847,389 long against 1,017,278 short, a net short of 169,889, and swap dealers held 111,924 long against 584,713 short. The next report covers positions as of Tuesday, September 29.
Open interest on the November contract stood at 294,853 on Monday's row, 282 contracts above Friday's 294,571. In this outlook's interpretation a near-unchanged open interest across an outside day with a 5.29 point range points to turnover rather than net new positions; that is a reading of the two rows, not an attribution of who traded.
5. No liquid options proxy
Crude is covered here without a positioning dataset. There is no dealer-positioning surface read for this instrument, no gamma map, no options concentration levels and no flow attribution, and none is inferred from any other instrument. Every level in this outlook originates in published pivot arithmetic, published standard-deviation bands, published retracement and moving-average projections, settlement averages computed from the provider's daily record, or the completed-session extremes described in section 2.1.
This is a statement about coverage, not about the existence of listed crude options. No such dataset was read, so no claim resting on one appears anywhere in this outlook. The positioning inputs used for crude are the weekly positioning report, the weekly inventory report, the Brent spread and the product cracks.
Night Session (6:00 PM ET Monday to 3:00 AM ET Tuesday, Globex and Asia)
The Tuesday session reopened at 93.53 at 6:00 PM ET after post-settlement trade had already lifted the contract from 92.60 to 93.29 following the Strait headlines. The Reserve Bank of Australia decision is listed for 12:30 AM ET Tuesday, forecast 4.6 percent against 4.35 percent, per the news-feed calendar and unconfirmed. The night session starts just above the 93.32 to 93.50 group of target price, Pivot Point and 9-day crossing, so the first test is whether the post-settlement rebound holds above that group. Bias neutral to mildly lower beneath 93.96, expected Globex band roughly 91.90 to 94.70, with a fresh Strait incident the risk that would carry it above 94.75.
London Session (3:00 AM ET to 8:00 AM ET Tuesday)
The European morning carries Swiss business survey data at 3:00 AM ET and Bank of England credit data at 4:30 AM ET, both per the news-feed calendar and unconfirmed, and the news-feed calendar lists potential United States and Iran talks as tentative at 8:00 AM ET, unconfirmed. Monday's high printed in this window, so the European hours are where the Strait premium has been priced most recently. Bias neutral, expected band roughly 91.80 to 94.90.
Morning Session (9:00 AM ET to 12:00 PM ET Tuesday, United States Open and Pit Session)
The job openings report is scheduled for 10:00 AM ET, per the verified forward calendar, and the Conference Board consumer confidence index is listed at 10:00 AM ET with a forecast of 89.1 against 89.4, per the news-feed calendar and unconfirmed. A Federal Reserve vice chair's pre-recorded remarks are listed at 11:00 AM ET, per the verified forward calendar. The transmission to crude runs through the dollar and the ten-year yield, which printed a 5.27 percent high on Monday. A hold beneath 93.96 through the morning keeps the 91.14 to 92.08 group in reach; acceptance above 94.06 returns the contract toward the 94.66 to 95.18 band. Expected band roughly 91.20 to 95.00.
Afternoon Session (12:00 PM ET to 2:30 PM ET Tuesday, NYMEX Pit Close)
A Federal Reserve governor speaks on the economic outlook at 12:40 PM ET, per the verified forward calendar, and further Federal Reserve speakers are listed at 1:00 PM ET, 1:30 PM ET and 2:00 PM ET, per the news-feed calendar and unconfirmed. Crude's pit settlement falls at 2:30 PM ET. Monday's reversal came in this window, so a headline in the negotiations is the main source of range expansion. Expected band roughly 91.00 to 94.80.
Night Session Forward (6:00 PM ET Tuesday)
A Federal Reserve governor speaks on payments at 3:00 PM ET, per the verified forward calendar, while the electronic session is still open. The Tuesday evening Globex session leads into Chinese manufacturing survey data at 9:30 PM ET, per the news-feed calendar and unconfirmed. The weekly anchor for crude is the weekly petroleum status report at 10:30 AM ET on September 30, 2026, per the verified forward calendar. The personal income and outlays report is scheduled for 08:30 AM ET on September 30, 2026, and the employment report for 08:30 AM ET on October 2, 2026, both per the verified forward calendar.
Expected Range (Tuesday Full Session)
Low-range scenario: 91.80 to 93.90
Mid-range scenario (most likely): 90.90 to 94.70
High-range scenario: 89.40 to 96.60
Most Likely Path
In our analyst judgment the most probable path holds the Globex session beneath the 93.96 18-day crossing as the post-settlement Strait headlines are digested, and rotates between the 92.08 retracement and the 93.46 Pivot Point through the European hours. Through the United States morning the contract tests the 91.14 to 91.27 group around Monday's 91.25 low, and a settle between 90.54 and 93.46 is weighted above a settle outside that band, because Monday's outside day finished at 25.5 percent of its range, gasoline fell while crude held, and the composite read dropped to 48 percent buy. The alternative that would invalidate this reading is a security incident in the Strait or a collapse of the mediated talks, which would put the 94.66 to 95.68 band back in play.
7. Tuesday Economic Calendar
The Tuesday session reopened at 6:00 PM ET Monday. The Reserve Bank of Australia decision is listed at 12:30 AM ET, with a forecast of 4.6 percent against 4.35 percent, per the news-feed calendar and unconfirmed. The European morning lists Swiss business survey data at 3:00 AM ET, a European Central Bank board member at 4:00 AM ET and Bank of England consumer credit at 4:30 AM ET, all per the news-feed calendar and unconfirmed, and the same calendar lists potential United States and Iran talks as tentative at 8:00 AM ET, unconfirmed.
The United States morning carries the job openings report at 10:00 AM ET and a Federal Reserve vice chair's pre-recorded remarks at 11:00 AM ET, both per the verified forward calendar, with the Conference Board consumer confidence index at 10:00 AM ET, forecast 89.1 against 89.4, per the news-feed calendar and unconfirmed. In the afternoon a Federal Reserve governor speaks at 12:40 PM ET and another at 3:00 PM ET, per the verified forward calendar, and further regional Federal Reserve presidents are listed at 1:00 PM ET, 1:30 PM ET and 2:00 PM ET, per the news-feed calendar and unconfirmed. Chinese manufacturing survey data follow at 9:30 PM ET, per the news-feed calendar and unconfirmed.
The captured calendars carry no crude inventory release for Tuesday; the next weekly petroleum status report is at 10:30 AM ET on September 30, 2026, per the verified forward calendar. The November contract's expiration is listed as 10/20/26 by the provider. The single first-order event for crude on Tuesday is not a scheduled release but the direction of the mediated United States and Iran talks, with the Strait incident reports from Monday evening as the immediate test.
8. Primary Trade Setup
Direction: Short
Rationale: Monday's outside day finished at 25.5 percent of a 5.29 point range, beneath the 93.46 Pivot Point and the 20-day settlement average of 92.87, while gasoline fell and the composite read dropped from 64 to 48 percent buy; a rebound into the target price and pivot group offers a short with a defined risk point above the three-deviation band. The directional readings remain positive and the Strait headlines after the settle argue the other way, so the setup is an analyst judgment against a live escalation risk.
Entry Zone: 93.45 to 93.85
Stop Loss: 95.20 (above three standard deviations resistance at 95.12 and the 14-day %k stall at 94.45, beneath Pivot R1 at 95.68)
Target 1 (T1): 92.10 (two cents above the 50 percent retracement of the four-week range at 92.08)
Target 2 (T2): 90.55 (one cent above two standard deviations support at 90.54 and above Pivot S1 at 90.39)
Target 3 (T3, extended): 89.00 (beneath the 38.2 percent retracement from the four-week low at 89.81 and above Pivot S2 at 88.17)
Risk-to-Reward: Approximately 1:1 to T1, 1:2 to T2, 1:3 to T3, from the 93.65 entry midpoint against a 1.55 point stop distance
Invalidation: A settle above Pivot R1 at 95.68 negates the thesis outright. Short of that, the edge is removed by acceptance above the 18-day average crossing at 93.96 rather than by a touch, defined as two consecutive 30-minute closes above 93.96 with the 94.06 one-deviation resistance also cleared.
Macro override: A confirmed attack on vessels in the Strait of Hormuz, an Iranian withdrawal from the talks or a United States military response would restore the full supply-risk premium. In that scenario the short is wrong immediately, and the 95.68 to 96.54 band becomes the reference within one 14-day average true range of 4.04 points.
Sources and methodology
This outlook is built from our session review of the November NYMEX WTI crude contract, CLX26, the November ’26 month, tracked on the continuous CL1! chart and prepared after Monday’s close on September 28, 2026 for the Tuesday, September 29, 2026 session. The contract domain was checked before any level was used: the reopened daily chart’s quote of 93.23 with its stated change of plus 0.63 returns 92.60, the provider’s published previous close, and the chart’s reopened open of 93.53 equals the provider’s, while the chart’s completed Monday bar equals the provider’s settlement row, so chart and levels sit on the same November contract. The day high, day low and open shown on the provider’s overview page belong to the Tuesday session and are not presented anywhere here as Monday’s range.
Monday’s session extremes are the completed-session inputs behind the published pivot ladder, back-solved from the outer pivot pairs, checked against all seven published rungs and reproduced by the chart’s daily bar. The 5-day, 9-day, 20-day, 50-day, 100-day and 200-day averages were computed from the provider’s 259-session daily settlement series. Volume and open interest are quoted from the dated rows of that daily record for 09/25 and 09/28; the partial row dated 09/29 belongs to the reopened session and is not used. Oscillator readings are cited as published, with the reopen caveat stated. Every intraday ordering claim rests on the provider’s 30-minute series for Monday. No dealer-positioning dataset was read for crude, so no gamma, dealer-positioning or options-flow claim is made. Items marked unconfirmed come from the news-feed calendar captured for this session; catalysts whose time had passed at 6:16 PM ET, when collection began, are recorded as completed. Scenario ranges are analyst judgment and carry no calibration. Friday’s grade uses Friday’s high, low and settle as stated in tonight’s review and the dated 09/25 row of the daily record, which agree, and the setup card as published on Friday’s outlook.
Not captured, and stated nowhere as a figure: a four-hour series, a prior-quarter high or low, any producer-group quota decision, compliance table or Saudi or Russian policy signal, a refinery utilisation figure, a seasonal demand series, a strategic reserve decision, a Friday 30-minute series, and any Venezuela or Russia-Ukraine supply development.
Friday’s outlook for this contract is here, and Friday’s gold outlook is here. Outlooks for the equity index, technology index, gold and crude contracts are collected on the market outlook page, and our forward trading record is on the performance statement.