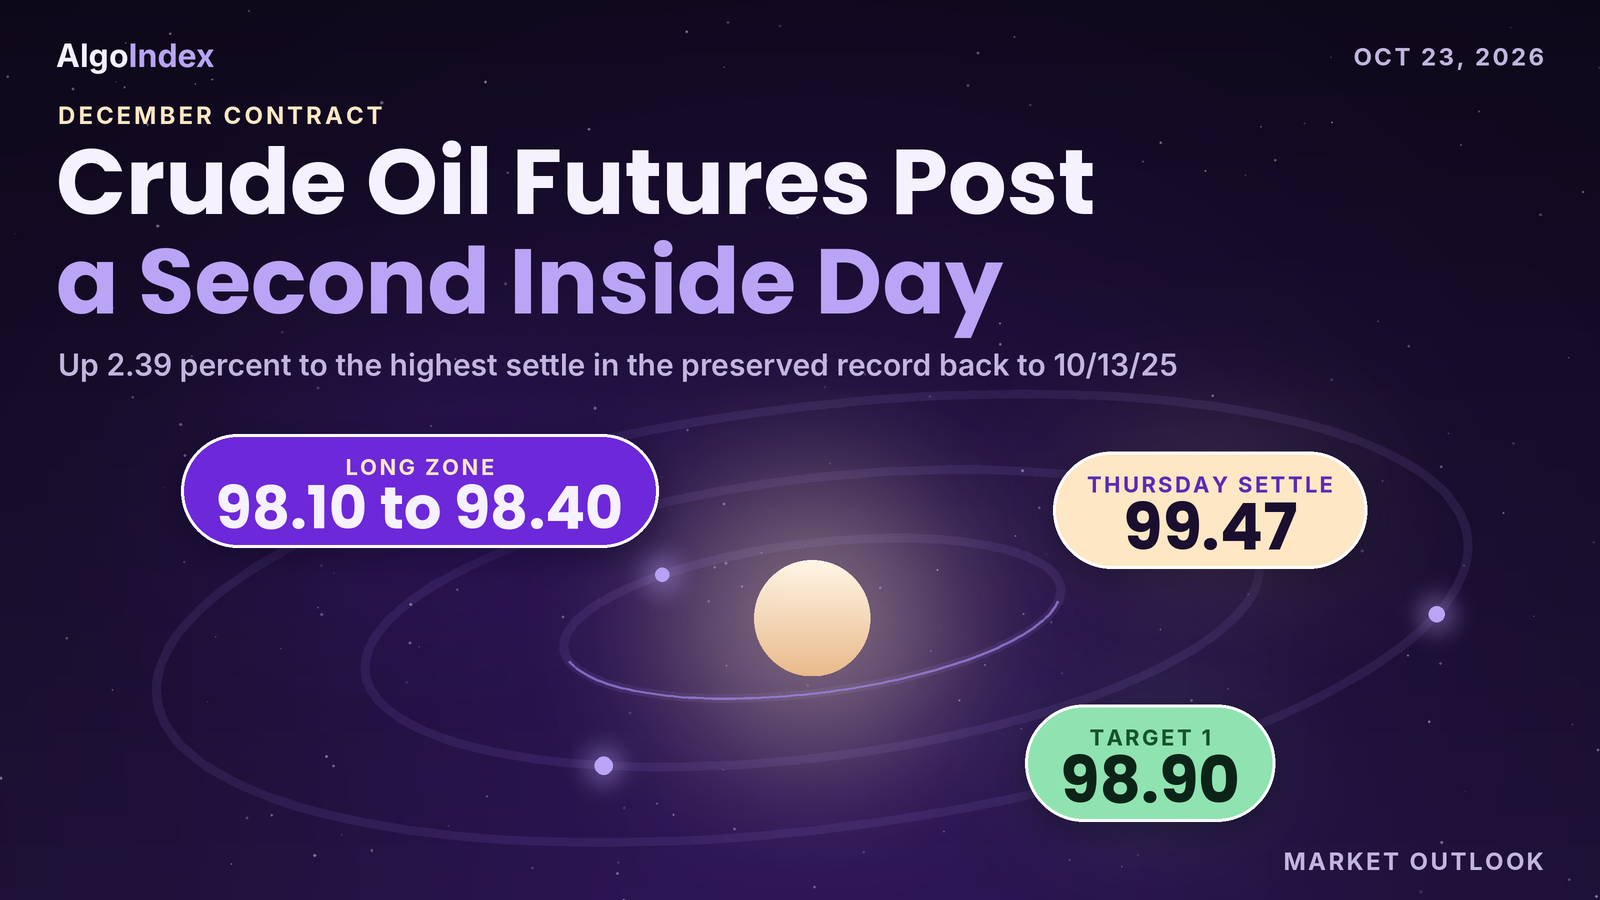
On Thursday December crude settled at 99.47, up 2.32 or 2.39 percent, after a 2.45 point session between 97.72 and 100.17. The settle finished at 71.4 percent of that range. It was a second straight inside day. The 100.17 high sat 23 cents beneath Wednesday's 100.40, and the 97.72 low sat 1.46 above Wednesday's 96.26. The gain was the largest since the 2.52 point rise of 10/16. The settle is above every settle in the provider's record, which runs back to 10/13/25.
Our Thursday card never came into play. Its long band, 96.15 to 96.45, sat beneath the whole day, and the 97.72 low stopped 1.27 above its top. The rally ran 87 cents past the extended 99.30 target without an entry from the card. No intraday series was preserved, so the order of the day's prints cannot be shown. Here that order does not change the grade.
Brent moved further. Its December contract settled at 113.17, up 4.35 or 4.0 percent, per the news feed at 2:43 PM ET and the provider's daily record. Its premium over December WTI widened to 13.70 from 11.67. December heating oil rose 3.5 percent to 4.7366 dollars a gallon and December gasoline 1.7 percent to 3.0893, in the provider's daily record.
Gulf headlines dominated. At 8:01 AM ET to 8:02 AM ET the news feed carried claims by Yemen's Houthis of attacks on the Saudi Defence Ministry in Riyadh, on the state oil company at Yanbu and on King Fahd airport in Dammam. One item came after the settle. At 4:43 PM ET to 4:44 PM ET the feed carried the President's invocation of the Defense Production Act for petroleum capacity. These items coincided with the session and its aftermath; no intraday series was preserved, so no move is attributed to any one of them.
December crude settled at 99.47, up 2.32. That is 71.4 percent of a 97.72 to 100.17 inside day, the second in a row. It sits above all six settlement averages, 1.07 above the 5-day at 98.40. Resistance starts at the 99.74 target price, then the 99.82 %K stall level, the 99.91 relative strength projection and Thursday's 100.17 high, with one standard deviation resistance at 100.40. Support starts at the 99.12 Pivot Point, then one standard deviation support at 98.54, the 98.30 stochastic projection, two standard deviations support at 98.16 and Pivot S1 at 98.07. The setup is a long on the December contract. It runs from 98.10 to 98.40, stop 97.60, targets 98.90, 99.55 and an extended 100.20. The whole band sits beneath the settle, its top 1.07 under it, and the 98.90 first target sits 57 cents beneath the settle too. The US flash purchasing managers' surveys are listed at 9:45 AM ET on Friday, per the news-feed calendar and unconfirmed.
Thursday's inside day stayed 1.27 above the band
First, the grading. In Thursday's outlook we set a long on the December contract from 96.15 to 96.45, stop 95.30, with targets at 97.30, 98.30 and an extended 99.30. A settle beneath Pivot S1 at 95.47 would negate it. Two consecutive 30-minute closes beneath 96.15 would remove the edge. The card is graded on December's Thursday bar.
Then December traded. Its bar, from the provider's settlement row, opened at 97.78 at the Wednesday 6:00 PM ET reopen, 1.33 above the band's top. It marked a high of 100.17 and a low of 97.72, and settled at 99.47. The low stopped 1.27 above 96.45. The band was never reached. Nor was the stop. The low sat 2.42 above 95.30 and 2.25 above Pivot S1 at 95.47.
So the card's entry condition was not met on the daily bar. The whole bar sat above the 97.30 first target, its low 42 cents over it. The high also cleared 98.30 and the extended 99.30, finishing 87 cents above 99.30. With the band untouched, those prints came without an entry from the card. The settle finished 17 cents above 99.30 and 3.02 above the band's top. No invalidation settle printed. The acceptance condition could not print either. A 30-minute close beneath 96.15 needs a print beneath 96.15, and the low held at 97.72. No intraday series was preserved for Thursday, so the daily bar cannot show whether the high or the low came first. No fill and no result is asserted.
Our ranges were too low. The low-range case of 96.10 to 98.60 broke at the top by 1.57, while its bottom held by 1.62. The most likely case of 95.40 to 99.60 broke at the top by 57 cents and kept 2.32 at the bottom. The high-range case of 93.80 to 101.40 held, with 3.92 and 1.23 to spare. All three deviation bands broke at the top. One deviation, 96.13 to 98.17, gave way by 2.00. Two deviations, 95.71 to 98.59, gave way by 1.58, and three deviations, 95.39 to 98.91, by 1.26. Their bottoms held by 1.59, 2.01 and 2.33. One average true range around Wednesday's settle, 93.47 to 100.83, held with 4.25 and 66 cents. The session bands for Globex, London, the morning and the afternoon need an intraday series, so they are not graded.
The weighted path expected a hold between Pivot S2 at 93.80 and Pivot R1 at 99.61. The high broke it by 56 cents. The settle finished 14 cents beneath that pivot. The dip toward the band did not arrive, since the low stopped 1.27 above it. The named alternative, a move beneath Pivot S1 at 95.47 toward Pivot S2 at 93.80, did not happen. The card's macro override named a confirmed de-escalation between Washington and Tehran or a verified reopening of Strait of Hormuz traffic on agreed terms. The review records neither. At 11:54 AM ET the news feed carried a discussion between Qatar's prime minister and the US Secretary of State on efforts to reduce tensions. At 1:17 PM ET it carried a State Department statement reaffirming freedom of navigation through the strait. These are statements carried by the news feed rather than events confirmed for this review.
The December band at 98.10 to 98.40, just above Pivot S1
The map moved up 1.95, the gap between the two midpoints. Every price here is the December contract. The new band, 98.10 to 98.40, sits just above Pivot S1 at 98.07, its bottom 3 cents over it. It holds two standard deviations support at 98.16 and the 98.30 stochastic projection, and its top sits at the 98.40 5-day average. Thursday's 97.72 low sits 38 cents beneath the bottom. The settle sits 1.07 above the band's top and 1.37 above its bottom. The stop at 97.60 sits 26 cents beneath three standard deviations support at 97.86. It sits 12 cents beneath Thursday's 97.72 low.
The reopen printed beneath the settle. Globex reopened at 6:00 PM ET on Thursday for the Friday session, and the provider's overview showed that session's open, high and low at 99.10, 99.23 and 99.02. That low sits 62 cents above the band's top and 10 cents beneath the Pivot Point. The provider's last quote at about 6:29 PM ET was 99.02, 45 cents beneath the settle. The chart showed 99.03 at about 6:33 PM ET. Those are reopened-session quotes and they are excluded from Thursday's range.
Thursday was a second straight inside day. Its 100.17 high sits 23 cents beneath Wednesday's 100.40 and its 97.72 low 1.46 above Wednesday's 96.26. Wednesday was itself inside Tuesday's 101.37 to 95.25 range. The settle above the 97.78 open leaves a body of 1.69. The upper shadow runs 70 cents above the settle and the lower shadow 6 cents beneath the open. Over ten sessions the settlements read 91.01, 92.86, 93.17, 93.90, 96.50, 99.02, 98.54, 97.82 and 97.15 before Thursday's 99.47. That ended a run of three lower settles. Highs over six sessions read 96.74, 99.34, 99.71, 101.37, 100.40 and 100.17. Lows read 92.46, 95.29, 96.72, 95.25, 96.26 and 97.72. Tuesday's 101.37 remains the one-month, 13-week and 52-week high, 1.90 above the settle. The one-month low is 86.00 and the 13-week low 71.00. No prior-quarter high or low was captured, so the 13-week extremes serve as the quarterly reference.
Resistance starts 27 cents up. The published target price at 99.74 comes first, then the 14-day %K stall level at 99.82 and the 14-day relative strength projection at 70 percent, 99.91. Thursday's 100.17 high follows. One standard deviation resistance at 100.40 matches Wednesday's 100.40 high. Pivot R1 at 100.52, two standard deviations resistance at 100.78 and three at 101.08 come next. Tuesday's 101.37 high precedes Pivot R2 at 101.57. The 3-10 day crossover stall level at 102.17, Pivot R3 at 102.97 and the 103.10 top of one average true range are the extended references.
Support starts 35 cents down, at the 99.12 Pivot Point. One standard deviation support at 98.54 follows, then the 98.30 stochastic projection, two standard deviations support at 98.16 and Pivot S1 at 98.07. Three standard deviations support at 97.86 and Thursday's 97.72 low form the next band. Wednesday's 97.15 settle and the 96.95 crossing price for the 9-day lie beneath them. The deeper band is tight. The 96.76 stochastic projection, Pivot S2 at 96.67, the 9-day average at 96.49 and Wednesday's 96.26 low sit within 50 cents. The 95.84 bottom of one average true range, Pivot S3 at 95.62 and the 38.2 percent retracement from the four-week high at 95.50 are the extended references; that retracement sits 3.97 beneath the settle. Then the long tail. The 50 percent retracement of the four-week range at 93.68, the 18-day crossing at 93.12, the 20-day at 92.40 and the 91.87 retracement from the four-week low lie further down. So do the 40-day crossing at 90.65, the 89.77 retracement from the 13-week high and the 50-day at 88.41. Five more sit far beneath. They are the 86.00 one-month low, the 100-day at 81.67, the 200-day at 76.29, the 71.00 13-week low and the provider's 55.63 52-week low. No four-hour series was captured, so swing structure rests on daily bars only.
Every average now sits beneath price. The settle is 1.07 above the 5-day at 98.40, 2.98 above the 9-day at 96.49, 7.07 above the 20-day at 92.40 and 11.06 above the 50-day at 88.41. The gaps to the 100-day at 81.67 and the 200-day at 76.29 are 17.80 and 23.18. The 5-day rose 59 cents from 97.81. The 10/15 settle of 96.50 left the window and 99.47 replaced it. The 20-day rose 43 cents from 91.97 as the 09/24 settle of 90.90 left, and the 50-day rose 41 cents from 87.99. The order holds. The 30 older settlements in the 50-day window averaged 85.74, the 50 older ones in the 100-day window 74.93 and the 100 older ones in the 200-day window 70.92. Friday's crossing prices are 96.95 for the 9-day, 93.12 for the 18-day and 90.65 for the 40-day.
Momentum readings run high. Relative strength reads 73.17 on the 9-day, 69.28 on the 14-day and 66.67 on the 20-day. The raw stochastics read 84.76 percent on the 9-day and 87.64 percent on the 14-day. The 14-day %K at 79.03 percent sits beneath %D at 82.66 percent, in the upper part of the range. Positive direction leads on both windows. It reads 23.55 against 3.56 on the 9-day with the ADX at 50.46, and 23.97 against 5.81 on the 14-day with the ADX at 39.16. Historic volatility reads 20.21 percent and 24.10 percent. The composite multi-indicator read for Friday holds at 100 percent buy, unchanged from the prior session. Its signal strength is described as maximum and its direction as strongest. It read 100 percent buy a week ago and 48 percent a month ago. All three horizon groups average 100 percent buy, and the trend indicator reads buy. These are the provider's published readings, read at about 6:29 PM ET after the 6:00 PM ET reopen, so they may include the first minutes of the Friday session.
Thursday ran narrower than average. The 14-day average true range stands at 3.63 points and the 14-day average daily range at 3.44. Thursday's 2.45 was 0.71 times that daily average. It was the narrowest range since the 1.81 of 10/14. The 9-day figures are 3.72 and 3.73 and the 20-day 3.52 and 3.68. One average true range either side of the settle spans 95.84 to 103.10. The deviation bands, built from five settlements, run 98.54 to 100.40, 98.16 to 100.78 and 97.86 to 101.08. They describe settlement dispersion only. A headline gap can open outside any of them. Ten sessions of daily ranges read 1.99, 4.53, 3.24, 1.81, 4.28, 4.05, 2.99, 6.12, 4.14 and 2.45.
Houthi claims, a 13.70 Brent premium and a post-settle order
The Gulf set the tone overnight. At 3:09 AM ET the news feed carried a statement by Iran's Revolutionary Guards navy that continued US insistence on pushing vessels through what it called illegal routes in the Gulf would lead to confrontation against US regional bases. At 5:30 AM ET news-feed commentary reported that the Guards' navy claimed seven vessels had been hit in the Gulf. Then the Houthis. At 8:01 AM ET to 8:02 AM ET the feed carried Houthi claims of attacks on the Saudi Defence Ministry in Riyadh, on the state oil company at Yanbu and on King Fahd airport in Dammam.
Saudi statements ran through the day. At 4:56 AM ET the news feed carried a Saudi-led coalition statement that it intercepted a drone in the Riyadh region. At 11:47 AM ET it carried a Saudi warning of potential danger in Najran, and at 11:49 AM ET a statement that the danger had passed. At 2:32 PM ET it carried a coalition statement that it destroyed a Houthi missile aimed at Najran. Strait traffic got a mention too. At 10:19 AM ET the feed carried a refiner's statement that it is seeing sustained higher flows through the Strait of Hormuz. No producer-group statement was carried on the feeds read, so no quota or compliance change is asserted.
Washington weighed in. At 11:42 AM ET the news feed carried the President's post that Iran was making up hits and mines to drive up the price of oil. Diplomacy ran alongside. At 11:54 AM ET it carried a discussion between Qatar's prime minister and the US Secretary of State on efforts to reduce tensions. At 1:17 PM ET it carried a State Department statement reaffirming US commitment to Qatar's security and to freedom of navigation through the Strait of Hormuz. Later the President spoke again. At 4:26 PM ET the President said of Iran that the US may go a little further, as the feed carried it. These are statements carried by the news feed rather than events confirmed for this review. They coincided with the session and its aftermath; no move is attributed to any one of them.
Russia featured as well. At 2:36 PM ET the feed carried remarks by the Russian President that trilateral talks would address the security of Russia and Ukraine. It also carried an undated item that Russian gasoline and diesel output had increased. These are statements carried by the news feed rather than supply changes measured for this review.
Then came the order. After the settle, at 4:43 PM ET to 4:44 PM ET, the news feed carried the President's invocation of the Defense Production Act for petroleum capacity. It also carried a memo to the Defense Secretary on the act and oil, and a waiver of section 303 rules to expand oil capacity. No detail of volumes or timing was captured, so its effect on supply is not assessed here.
Inventories were quiet. The captured calendars carry no crude inventory entry for Thursday. Wednesday's official weekly petroleum status report showed a crude draw of 3.060 million barrels on the news-feed calendar against a forecast draw of 0.34 million. The calendar lists the next report at 10:30 AM ET on Wednesday, October 28, 2026. No gasoline, distillate, Cushing or strategic reserve figure was captured, so none is asserted.
Products firmed on December. In the provider's daily record, December heating oil settled at 4.7366 dollars a gallon against 4.5772 on Wednesday, and December gasoline at 3.0893 against 3.0390. The heating oil margin is 42 gallons times the heating oil settle less the WTI settle. Against December WTI it stands at 99.47 dollars a barrel against 95.09 on Wednesday. That matches the settle, by coincidence. The gasoline margin stands at 30.28 against 30.49. The news feed's settlement items carried November diesel at 4.9321, November gasoline at 3.1765 and November natural gas at 2.7960. A refiner's guidance carried by the news feed put fourth-quarter refinery runs at 80 to 83 percent of capacity. No national refinery utilisation figure and no seasonal demand series were captured.
The dollar eased. The dollar index closed at 101.61 in the provider's daily record, down 0.17 from Wednesday's 101.78. Yields fell too. The ten-year yield index closed at 4.95 percent against 5.14 percent. Weekly jobless claims printed at 194,000 against a 200,000 forecast at 8:30 AM ET, per the news-feed calendar and unconfirmed. The 5-year inflation-protected Treasury auction at 1:00 PM ET drew a high yield of 2.367 percent against 1.955 percent previously, per the news-feed calendar and unconfirmed. A softer dollar is a modest support for dollar-priced crude; the size of that effect is not measured here.
Equities split. The S&P 500 cash index closed at 7,663.43, down 1.21 percent, with the volatility index at 19.03 against 16.68. The Nasdaq-100 cash index fell 2.90 percent and the semiconductor index 6.72 percent. The Dow industrials closed little changed, up 0.02 percent. Metals fell. Gold's December contract settled at 4,060.4, down 2.16 percent, while silver's December contract fell 4.68 percent and copper's 2.76 percent.
Positioning data is thin. No weekly positioning report was captured, so no change in managed-money or producer length is asserted. December open interest stood at 313,678 for Wednesday in the provider's record, and Thursday's open interest had not been reported. Thursday's December volume was 280,425 contracts against 332,174 on Wednesday. The review calls the cross-market read the clearest positioning signal captured. Brent's December premium over December WTI widened to 13.70 from 11.67. The December heating oil margin widened by 4.38 dollars a barrel while the gasoline margin narrowed by 21 cents. No dealer-positioning dataset was read for crude.
The trade map for Friday
The review's setup is a long on the December contract. It runs from 98.10 to 98.40. The settle sits above every settlement average from the 5-day to the 200-day, and positive direction leads on the 9-day and 14-day directional systems. The composite holds at 100 percent buy, and Brent's December premium over WTI widened to 13.70. That is the trend case. The band sits just above Pivot S1 at 98.07 and holds two standard deviations support at 98.16 and the 98.30 stochastic projection. The stop at 97.60 sits beneath three standard deviations support at 97.86 and Thursday's 97.72 low. The first target, 98.90, sits beneath the Pivot Point at 99.12. The second, 99.55, sits above Thursday's 99.47 settle and beneath the published target price at 99.74. The extended 100.20 sits just above Thursday's 100.17 high and beneath one standard deviation resistance at 100.40. Two caveats sit against it. Two consecutive inside days and a reopened-session quote beneath the settle leave room for a pullback. The review calls the setup an analyst judgment that dips are bought while supply headlines persist, not a measured edge.
Now the arithmetic. From the 98.25 midpoint the risk to the stop is 0.65, 17.9 percent of the 14-day average true range of 3.63. The targets sit 0.65, 1.30 and 1.95 above the midpoint. Exact multiples, on paper. The whole band sits beneath the settle, its top 1.07 and its bottom 1.37 under it. The 98.90 first target also sits beneath the settle, by 57 cents, and 50 cents above the band's top. The 99.55 second target sits 8 cents above the settle and 19 cents beneath the 99.74 target price. The extended 100.20 sits 3 cents above Thursday's high and 20 cents beneath 100.40. A headline gap can open through the stop.
Scenario ranges in the review are analyst judgment. The low-range case runs 98.10 to 100.40, the most likely 97.70 to 100.80 and the high-range case 96.60 to 101.60. Then by session. Through Globex the review's judgment expects roughly 98.10 to 100.20, with a bias neutral to higher above Pivot S1 at 98.07. The reopen quoted 99.02 at about 6:29 PM ET, after the post-settle Defense Production Act headlines. Gulf headlines remain the main overnight risk in both directions. London follows at roughly 97.90 to 100.40, with a neutral bias. Three standard deviations support at 97.86 is its first meaningful support beneath. One standard deviation resistance at 100.40 is its first meaningful resistance above Thursday's high. The morning band runs roughly 97.70 to 100.80. Thursday's 97.72 low and two standard deviations resistance at 100.78 each sit 2 cents inside its edges. The afternoon runs roughly 97.70 to 101.10 into the 2:30 PM ET settle. A Friday settle carries weekend headline exposure, which in the review's judgment can keep positioning light into the close.
Friday's calendar starts on Thursday evening. Japan's consumer prices are listed at 7:30 PM ET and Japan's flash purchasing managers' surveys at 8:30 PM ET, both per the news-feed calendar and unconfirmed. UK retail sales are listed at 2:00 AM ET, per the news-feed calendar and unconfirmed. The French, German, euro-area and UK flash purchasing managers' surveys follow between 3:15 AM ET and 4:30 AM ET, with the euro-area surveys at 4:00 AM ET, all per the news-feed calendar and unconfirmed. The Russian central bank decision is listed at 6:30 AM ET and Canadian retail sales at 8:30 AM ET, both per the news-feed calendar and unconfirmed. Then the main release. The US flash purchasing managers' surveys are listed at 9:45 AM ET, with a composite forecast of 57.4 against 58.4 previously, per the news-feed calendar and unconfirmed. The final University of Michigan sentiment survey is listed at 10:00 AM ET, per the news-feed calendar and unconfirmed. Crude settles at 2:30 PM ET. A rating decision on France is listed as tentative at 4:00 PM ET, per the news-feed calendar and unconfirmed. The calendar lists no confirmed entry for Friday, October 23, 2026. It lists the next weekly petroleum status report at 10:30 AM ET and the FOMC statement at 2:00 PM ET, both on Wednesday, October 28, 2026.
The review also weighs the path. In the review's analyst judgment the most probable path holds the contract between Pivot S2 at 96.67 and Pivot R2 at 101.57, with a dip toward the 98.10 to 98.40 band that holds above Thursday's 97.72 low weighted slightly above a break lower. It names an alternative. A confirmed de-escalation in the Gulf, or a supply response under the Defense Production Act that the market reads as material, could carry the contract beneath Thursday's 97.72 low toward Pivot S2 at 96.67. The review also flags a pullback. Two consecutive inside days compress the range, %K sits beneath %D, and the reopened session quoted the contract 45 cents beneath the settle. So a pullback before any extension is a live alternative. In the review's judgment the first-order influence for crude on Friday is unscheduled Gulf headlines. The 9:45 AM ET US flash purchasing managers' surveys, listed by the news-feed calendar and unconfirmed, are the main scheduled macro release. The market closes for the weekend after Friday's session. Globex reopens at 6:00 PM ET on Sunday.
Thursday's rally never came back to the old band; Friday's band waits 1.07 beneath the settle, just above Pivot S1.
The complete data picture
Every number behind Friday’s plan, charted first, then the full level lists, then the complete numeric reference underneath. Every price is the December contract unless November is named.
Full numeric reference, every remaining figure from the session review
1. Executive Summary
The December crude contract settled at 99.47 on Thursday, up 2.32 or 2.39 percent from Wednesday's settle of 97.15, after trading between 100.17 and 97.72, a 2.45 point daily range. The settle finished at 71.4 percent of the range, and the 2.45 point range was 0.71 times the published 14-day average daily range of 3.44 points. Thursday was a second consecutive inside day, with a high 23 cents beneath Wednesday's 100.40 and a low 1.46 points above Wednesday's 96.26. The 2.32 point gain was the largest one-day gain since the 2.52 point gain of 10/16, and the 99.47 settle is above every settle in the preserved record back to 10/13/25.
Brent's December contract settled at 113.17, up 4.35 or 4.0 percent, per the news feed at 2:43 PM ET and the provider's daily record, so its premium over December WTI widened to 13.70 from 11.67 on Wednesday. December heating oil settled at 4.7366 dollars a gallon, up 3.5 percent, and December gasoline at 3.0893, up 1.7 percent, in the provider's daily record.
The day's news flow was dominated by the Gulf. The news feed carried at 8:01 AM ET to 8:02 AM ET claims by Yemen's Houthis of attacks on the Saudi Defence Ministry in Riyadh, on the state oil company at Yanbu and on King Fahd airport in Dammam, after a 3:09 AM ET statement by Iran's Revolutionary Guards navy warning of confrontation against US regional bases. At 11:42 AM ET the President posted that Iran was making up hits and mines to drive up the price of oil, and at 4:43 PM ET to 4:44 PM ET, after the settle, the news feed carried the President's invocation of the Defense Production Act for petroleum capacity. These items coincided with the session and its aftermath; no intraday series was preserved, so no move is attributed to any one of them.
The dollar index closed at 101.61 against 101.78 on Wednesday, and the ten-year yield index fell to 4.95 percent from 5.14 percent. Equities split: the Nasdaq-100 cash index fell 2.90 percent and the semiconductor index 6.72 percent, while the Dow industrials closed little changed, up 0.02 percent. The published 14-day average true range is 3.63 points. The Primary Setup below is a long from the 98.10 to 98.40 band just above Pivot S1 at 98.07, stopped at 97.60 beneath three standard deviations support at 97.86 and Thursday's 97.72 low, with objectives at 98.90, 99.55 and an extended 100.20.
2. Price Action & Technical Structure
2.1 Intraday and Session Review
The Thursday session opened at 97.78 at the Wednesday 6:00 PM ET reopen, 63 cents above Wednesday's settle, marked a daily high of 100.17 and a daily low of 97.72, and settled at 99.47 at 2:30 PM ET. No intraday series was preserved for this session in this review, so this review does not describe the order in which the high and the low printed, and no timed price path is asserted; the daily bar alone fixes the open, the extremes and the settle.
The news feed's settlement item at 2:31 PM ET carried the December settle at 99.47, up 2.32 or 2.39 percent. This review records only that the 100.17 high and the 97.72 low both belong to Thursday's completed session and that the settle sits 1.75 points above the low and 70 cents beneath the high.
Globex reopened at 6:00 PM ET on Thursday for the Friday session, so the open, high and low shown on the provider's overview, 99.10, 99.23 and 99.02, belong to the new Friday session and are not Thursday's range. The provider's last quote at about 6:29 PM ET was 99.02, 45 cents beneath the settle, and the chart showed 99.03 at about 6:33 PM ET; these are reopened-session quotes, not settlements.
Thursday's completed-session extremes are taken from the settlement row, and they are also the completed-session inputs behind the published pivot ladder rather than an independently read bar. Pivot R3 at 102.97 minus Pivot S3 at 95.62, divided by three, returns 2.45, and Pivot R2 at 101.57 minus Pivot S2 at 96.67, divided by two, returns the same 2.45. Three times the Pivot Point of 99.12 less the 99.47 settle gives a high plus low sum of 197.89, which the pair of 100.17 and 97.72 reproduces to the published rounding at 197.89, and that pair reproduces all seven published rungs.
Independent corroboration: the provider's settlement row and the chart's completed daily bar on the continuous symbol carry the same 97.78 open, 100.17 high, 97.72 low and 99.47 settle.
2.2 Daily Structure
Thursday was an inside day: the 100.17 high sits 23 cents beneath Wednesday's 100.40, and the 97.72 low sits 1.46 points above Wednesday's 96.26, and Wednesday was itself inside Tuesday's 101.37 to 95.25 range. The settle above the 97.78 open leaves a body of 1.69 points, an upper shadow of 70 cents above the settle and a lower shadow of 6 cents beneath the open.
Settlements over the last ten sessions ran 91.01, 92.86, 93.17, 93.90, 96.50, 99.02, 98.54, 97.82 and 97.15 before Thursday's 99.47, so Thursday ended a run of three consecutive lower settles and printed the highest settle in the preserved record, which begins on 10/13/25. The sequence of session highs over the last six sessions reads 96.74, 99.34, 99.71, 101.37, 100.40 and 100.17, and the sequence of session lows reads 92.46, 95.29, 96.72, 95.25, 96.26 and 97.72.
The one-month high, 13-week high and 52-week high all sit at Tuesday's 101.37, 1.90 points above the settle, and the provider's 52-week low of 55.63 sits far beneath. The one-month low of 86.00 and the 13-week low of 71.00 frame the lower side. No prior-quarter high or low was captured for this review, so the 13-week extremes serve as the available quarterly reference.
2.3 4-Hour and Swing Structure
Daily ranges for the last ten sessions ran 1.99, 4.53, 3.24, 1.81, 4.28, 4.05, 2.99, 6.12, 4.14 and 2.45, so Thursday's range was the narrowest since the 1.81 range of 10/14. The settlement changes over the same ten sessions read plus 0.26, plus 1.85, plus 0.31, plus 0.73, plus 2.60, plus 2.52, minus 0.48, minus 0.72, minus 0.67 and plus 2.32.
The retracement grid published for Friday places the 38.2 percent retracement from the four-week high at 95.50, 3.97 points beneath the settle, and the 50 percent retracement of the four-week range at 93.68. Further beneath, the 38.2 percent retracement from the four-week low sits at 91.87 and the 38.2 percent retracement from the 13-week high at 89.77. No four-hour series was captured for this review, so swing structure here rests on daily bars only.
2.4 Moving Averages
The averages cited in this subsection were computed for this review from the provider's daily settlement series for the December contract, which holds 259 completed sessions through Thursday; the partial Friday row returned after the 6:00 PM ET reopen was dropped before counting. The 5-day average stands at 98.40, the 9-day at 96.49, the 20-day at 92.40, the 50-day at 88.41, the 100-day at 81.67 and the 200-day at 76.29.
The 99.47 settle sits 1.07 points above the 5-day average, 2.98 points above the 9-day, 7.07 points above the 20-day and more than 11 points above the 50-day. The 5-day average rose 59 cents from Wednesday's 97.81, because the 10/15 settle of 96.50 left the window and was replaced by 99.47. The 20-day rose 43 cents from 91.97, because the 09/24 settle of 90.90 left that window, and the 50-day rose 41 cents from 87.99.
The 20-day average sits above the 50-day because the last 20 settlements averaged 92.40 against 88.41 for the full 50, which means the 30 older settlements in the 50-day window averaged lower, at 85.74. The 50-day sits above the 100-day because the 50 older settlements in the 100-day window averaged lower, at 74.93, and the 100-day sits above the 200-day because the 100 older settlements in the 200-day window averaged lower, at 70.92. The projection grid gives the prices at which each average would be crossed on Friday: 96.95 for the 9-day, 93.12 for the 18-day and 90.65 for the 40-day.
2.5 Oscillator and Trend Readings
The oscillator figures below are as published on the provider's technical page, read at about 6:29 PM ET after the 6:00 PM ET reopen, so they may include the first minutes of the Friday session rather than the settle alone; they are the provider's published readings, not this review's computations. The 9-day relative strength reads 73.17, the 14-day relative strength 69.28 and the 20-day relative strength 66.67.
The 9-day raw stochastic reads 84.76 percent and the 14-day raw stochastic 87.64 percent, while the 14-day stochastic %K reads 79.03 percent and the 14-day stochastic %D 82.66 percent, so %K sits beneath %D in the upper part of the range.
The 9-day directional index ADX reads 50.46 with the 9-day +DI at 23.55 and the 9-day -DI at 3.56; the 14-day directional index ADX reads 39.16 with the 14-day +DI at 23.97 and the 14-day -DI at 5.81, so positive direction leads on both and the 9-day ADX reads above the 14-day. The 9-day historic volatility reads 20.21 percent and the 14-day historic volatility 24.10 percent.
The composite multi-indicator read published for the Friday session is 100 percent buy, unchanged from the prior session's snapshot of 100 percent buy, with signal strength described as maximum and direction as strongest. The snapshot history reads 100 percent buy a week ago and 48 percent buy a month ago. The short-horizon, medium-horizon and long-horizon groups each average 100 percent buy, and the composite trend indicator reads buy.
2.6 Volatility and Expected Range
The published 14-day average true range stands at 3.63 points and the 14-day average daily range at 3.44 points; the 9-day average true range is 3.72 with a 9-day average daily range of 3.73, and the 20-day average true range is 3.52 with a 20-day average daily range of 3.68. Thursday's 2.45 point range was 0.71 times the 14-day average daily range.
Adding and subtracting the 14-day average true range of 3.63 points from the 99.47 settle frames Friday between 95.84 and 103.10. The published standard-deviation bands are built from five settlements: one deviation spans 98.54 to 100.40, two spans 98.16 to 100.78 and three spans 97.86 to 101.08. These bands describe settlement dispersion, not intraday reach, and a headline gap can open outside any of them.
3. Key Levels
3.1 Resistance
Above the 99.47 settle, the first overhead reference is the published target price at 99.74, followed by the 14-day %K stall level at 99.82 and the 14-day relative strength projection at 70 percent, 99.91. Thursday's 100.17 high precedes one standard deviation resistance at 100.40, which coincides with Wednesday's 100.40 high, then Pivot R1 at 100.52, two standard deviations resistance at 100.78 and three standard deviations resistance at 101.08. Tuesday's 101.37 high, which is also the one-month, 13-week and 52-week high, precedes Pivot R2 at 101.57, with the 3-10 day crossover stall level at 102.17 and Pivot R3 at 102.97 the extended references.
3.2 Support
Beneath the settle sits the Pivot Point at 99.12, then one standard deviation support at 98.54, the 14-3 day raw stochastic projection at 98.30, two standard deviations support at 98.16 and Pivot S1 at 98.07. Three standard deviations support at 97.86 and Thursday's 97.72 low form the next band, with Wednesday's 97.15 settle and the 9-day average crossing price at 96.95 beneath. The 14-3 day raw stochastic projection at 96.76, Pivot S2 at 96.67 and Wednesday's 96.26 low form the deeper band, with Pivot S3 at 95.62 and the 38.2 percent retracement from the four-week high at 95.50 the extended references.
4. Macro Drivers
4.1 OPEC and Supply Policy (Quotas, Compliance, Saudi/Russia Signals)
No producer-group statement was carried on the feeds read for this review, so no quota or compliance change is asserted. The news feed carried at 4:56 AM ET a Saudi-led coalition statement that it intercepted a drone in the Riyadh region, at 11:47 AM ET a Saudi warning of potential danger in Najran followed at 11:49 AM ET by a statement that the danger had passed, and at 2:32 PM ET a coalition statement that it destroyed a Houthi missile aimed at Najran. At 10:19 AM ET it carried a refiner's statement that it is seeing sustained higher flows through the Strait of Hormuz.
On the Russian side, the feed carried at 2:36 PM ET remarks by the Russian President that trilateral talks would address the security of Russia and Ukraine, and an undated item that Russian gasoline and diesel output had increased. These are statements carried by the news feed rather than supply changes measured for this review.
4.2 EIA and API Inventory (Crude Stocks, Gasoline, Distillates, Cushing, SPR)
The captured calendars carry no crude inventory entry for Thursday. The most recent official weekly petroleum status report, released on Wednesday, showed a crude draw of 3.060 million barrels on the news-feed calendar against a forecast draw of 0.34 million. The next official weekly petroleum status report is scheduled for 10:30 AM ET on Wednesday, October 28, 2026, as the calendar lists it. No gasoline, distillate, Cushing or strategic reserve figure was captured for this review, so none is asserted.
After the settle, the news feed carried at 4:43 PM ET to 4:44 PM ET the President's invocation of the Defense Production Act for petroleum capacity, a memo to the Defense Secretary on the act and oil, and a waiver of section 303 rules to expand oil capacity. No detail of volumes or timing was captured, so its effect on supply is not assessed here.
4.3 Geopolitical Backdrop (Middle East, Iran, Russia/Ukraine, Venezuela)
The news feed carried at 3:09 AM ET a statement by Iran's Revolutionary Guards navy that continued US insistence on pushing vessels through what it called illegal routes in the Gulf would lead to confrontation against US regional bases, and at 5:30 AM ET news-feed commentary reporting that the Guards' navy claimed seven vessels had been hit in the Gulf. At 8:01 AM ET to 8:02 AM ET it carried Houthi claims of attacks on the Saudi Defence Ministry in Riyadh, on the state oil company at Yanbu and on King Fahd airport in Dammam.
On the diplomatic side, the feed carried at 11:54 AM ET a discussion between Qatar's prime minister and the US Secretary of State on efforts to reduce tensions, at 1:17 PM ET a State Department statement reaffirming US commitment to Qatar's security and to freedom of navigation through the Strait of Hormuz, and at 11:42 AM ET the President's post that Iran was making up hits and mines to drive up the price of oil. At 4:26 PM ET the President said of Iran that the US may go a little further. These are statements carried by the news feed rather than events confirmed for this review.
4.4 Demand and Refining (Refinery Utilization, Crack Spreads, Seasonal Pattern)
On the December contracts in the provider's daily record, December heating oil settled at 4.7366 dollars a gallon against 4.5772 on Wednesday and December gasoline at 3.0893 against 3.0390. The news feed's settlement items carried November diesel at 4.9321, November gasoline at 3.1765 and November natural gas at 2.7960.
Against the December WTI settle, the heating oil margin, 42 gallons times the heating oil settle less the WTI settle, stands at 99.47 dollars a barrel against 95.09 on Wednesday, and the gasoline margin at 30.28 against 30.49. A refiner's guidance carried by the news feed put fourth-quarter refinery runs at 80 to 83 percent of capacity. No national refinery utilisation figure and no seasonal demand series were captured, so neither is asserted.
4.5 Dollar and Cross-Asset (DXY, Commodities Complex, Equity Risk-On/Off)
The dollar index closed at 101.61 in the provider's daily record, down 0.17 from Wednesday's 101.78, and the ten-year yield index fell to 4.95 percent from 5.14 percent. Weekly jobless claims printed at 194,000 against a 200,000 forecast at 8:30 AM ET, per the news-feed calendar and unconfirmed, and the 5-year inflation-protected Treasury auction at 1:00 PM ET drew a high yield of 2.367 percent against 1.955 percent previously, per the news-feed calendar and unconfirmed.
Gold's December contract settled at 4,060.4, down 2.16 percent, silver's December contract fell 4.68 percent and copper's 2.76 percent. The S&P 500 cash index closed at 7,663.43, down 1.21 percent, with the volatility index at 19.03 against 16.68. A softer dollar is a modest support for dollar-priced crude; the size of that effect is not measured here.
4.6 Institutional Positioning (COT, Money Manager and Commercial Hedger, Speculator Length)
No weekly positioning report was captured for this review, so no change in managed-money or producer length is asserted. Open interest on the December contract is shown at 313,678 for Wednesday in the provider's record, and Thursday's open interest had not been reported at the time of capture; Thursday's December volume was 280,425 contracts against 332,174 on Wednesday.
The cross-market read is the clearest positioning signal captured. Brent's December premium over December WTI widened to 13.70 from 11.67, and the December heating oil margin widened by 4.38 dollars a barrel while the gasoline margin narrowed by 21 cents.
5. No Liquid Options Proxy
This review covers crude without a positioning dataset. There is no dealer-positioning surface read for this instrument in this review, no gamma map, no options concentration levels and no flow attribution, and none is inferred from any other instrument. Every level in section 3 originates in published pivot arithmetic, published standard-deviation bands, published retracement and moving-average projections, settlement averages computed from the provider's daily record, or the completed-session extremes described in section 2.1.
This is a statement about coverage, not about the existence of listed crude options. No such dataset was read for this review, so no claim resting on one appears anywhere in this review or in this outlook. The positioning inputs used for crude are the Brent spread, the product margins and the open-interest and volume record.
6. Forecast
6.1 Night Session (6:00 PM ET Thursday to 3:00 AM ET Friday, Globex/Asia)
Globex reopened at 6:00 PM ET on Thursday and quoted the December contract at 99.02 at about 6:29 PM ET, after the post-settle Defense Production Act headlines. Japan's consumer prices are listed at 7:30 PM ET and Japan's flash purchasing managers' surveys at 8:30 PM ET, both per the news-feed calendar and unconfirmed, and Gulf headlines remain the main overnight risk in both directions. Bias neutral to higher above Pivot S1 at 98.07, expected Globex band roughly 98.10 to 100.20.
6.2 London Session (3:00 AM to 8:00 AM ET Friday)
UK retail sales are listed at 2:00 AM ET and the euro-area flash purchasing managers' surveys at 4:00 AM ET, both per the news-feed calendar and unconfirmed, and the Russian central bank decision at 6:30 AM ET, per the news-feed calendar and unconfirmed. Bias neutral, expected band roughly 97.90 to 100.40, with three standard deviations support at 97.86 the first meaningful support beneath and one standard deviation resistance at 100.40 the first meaningful resistance above Thursday's high.
6.3 Morning Session (9:00 AM to 12:00 PM ET Friday, US Open / Pit Session)
Canadian retail sales are listed at 8:30 AM ET, the US flash purchasing managers' surveys at 9:45 AM ET and the final University of Michigan sentiment survey at 10:00 AM ET, all per the news-feed calendar and unconfirmed. Expected band roughly 97.70 to 100.80, with Thursday's 97.72 low beneath and two standard deviations resistance at 100.78 above.
6.4 Afternoon Session (12:00 PM to 2:30 PM ET Friday, NYMEX Pit Close)
No scheduled release is listed on the captured calendars between noon and the settle, and crude settles at 2:30 PM ET. A Friday settle carries weekend headline exposure, which in this review's judgment can keep positioning light into the close. Expected band roughly 97.70 to 101.10.
6.5 Night Session Forward (6:00 PM ET Friday)
The market closes for the weekend after Friday's session, and Globex reopens at 6:00 PM ET on Sunday. A rating decision on France is listed as tentative at 4:00 PM ET on Friday, per the news-feed calendar and unconfirmed, and two days of Gulf headline exposure separate Friday's settle from the Sunday reopen.
6.6 Expected Range (Friday Full Session)
Low-range scenario: 98.10 to 100.40
Mid-range scenario (most likely): 97.70 to 100.80
High-range scenario: 96.60 to 101.60
6.7 Most Likely Path
In this review's analyst judgment the most probable path holds the contract between Pivot S2 at 96.67 and Pivot R2 at 101.57, with a dip toward the 98.10 to 98.40 band that holds above Thursday's 97.72 low weighted slightly above a break lower. The settle sits above every settlement average from the 5-day to the 200-day, positive direction leads on both directional systems, the composite holds at 100 percent buy with direction described as strongest, and Brent's premium widened by more than two dollars.
The alternative that would invalidate this reading is a confirmed de-escalation in the Gulf, or a supply response under the Defense Production Act that the market reads as material, either of which could carry the contract beneath Thursday's 97.72 low toward Pivot S2 at 96.67. Two consecutive inside days compress the range, %K sits beneath %D, and the reopened session quoted the contract 45 cents beneath the settle, so a pullback before any extension is a live alternative.
7. Friday Economic Calendar
Thursday's releases are complete. Weekly jobless claims printed at 194,000 at 8:30 AM ET, per the news-feed calendar and unconfirmed, the 5-year inflation-protected Treasury auction drew a high yield of 2.367 percent at 1:00 PM ET, per the news-feed calendar and unconfirmed, and crude settled at 2:30 PM ET. Australia's flash composite purchasing managers' index printed at 6:00 PM ET at 47.7 against 51.3 previously, per the news-feed calendar and unconfirmed.
On Thursday evening Japan's consumer prices are listed at 7:30 PM ET, per the news-feed calendar and unconfirmed. On Friday UK retail sales are listed at 2:00 AM ET, the French, German, euro-area and UK flash purchasing managers' surveys between 3:15 AM ET and 4:30 AM ET and the Russian central bank decision at 6:30 AM ET, all per the news-feed calendar and unconfirmed. Canadian retail sales are listed at 8:30 AM ET, the US flash purchasing managers' surveys at 9:45 AM ET, with a composite forecast of 57.4 against 58.4 previously, and the final University of Michigan sentiment survey at 10:00 AM ET, all per the news-feed calendar and unconfirmed. Crude settles at 2:30 PM ET.
Later in the window, the next official weekly petroleum status report is scheduled for 10:30 AM ET on Wednesday, October 28, 2026, as the calendar lists it, and the FOMC statement for 2:00 PM ET on Wednesday, October 28, 2026, as the calendar lists it. The calendar lists no confirmed entry for Friday, October 23, 2026. In this review's judgment the first-order influence for crude on Friday is unscheduled Gulf headlines, with the 9:45 AM ET US flash purchasing managers' surveys listed by the news-feed calendar, unconfirmed, the main scheduled macro release.
8. Primary Trade Setup
Direction: Long
Rationale: The settle sits above every settlement average from the 5-day to the 200-day, positive direction leads on the 9-day and 14-day directional systems, the composite holds at 100 percent buy, and Brent's December premium over WTI widened to 13.70. A dip toward Pivot S1 at 98.07, into the band just above it that holds two standard deviations support at 98.16 and the 98.30 stochastic projection, offers a long with a defined risk point beneath three standard deviations support at 97.86 and Thursday's 97.72 low. Two consecutive inside days and a reopened-session quote beneath the settle leave room for a pullback, so the setup is an analyst judgment that dips are bought while supply headlines persist, not a measured edge.
Entry Zone: 98.10 to 98.40
Stop Loss: 97.60 (beneath three standard deviations support at 97.86 and Thursday's 97.72 low)
Target 1 (T1): 98.90 (beneath the Pivot Point at 99.12)
Target 2 (T2): 99.55 (above Thursday's 99.47 settle and beneath the published target price at 99.74)
Target 3 (T3, extended): 100.20 (just above Thursday's 100.17 high and beneath one standard deviation resistance at 100.40)
Risk-to-Reward: Approximately 1:1 to T1, 1:2 to T2, 1:3 to T3
Invalidation: A settle beneath Thursday's 97.72 low negates the thesis. Short of that, the edge is removed by acceptance beneath the entry band rather than by a touch, defined as two consecutive 30-minute closes beneath 98.10.
Macro override: A confirmed de-escalation in the Gulf, or a material supply release announced under the Defense Production Act, would remove part of the supply premium. In that scenario a move through the 97.60 stop invalidates the long before the targets, and Pivot S2 at 96.67 becomes the reference, 93 cents beyond the stop and inside one 14-day average true range of 3.63 points.
Sources and methodology
This outlook is built from our session review of the December WTI crude contract (CLZ26), prepared after Thursday's close on October 22, 2026 for the Friday, October 23, 2026 session. December, which the chart's continuous symbol tracks, is the front month. Thursday's completed extremes are the inputs behind the published pivot ladder: Pivot R3 at 102.97 less Pivot S3 at 95.62, divided by three, and Pivot R2 at 101.57 less Pivot S2 at 96.67, divided by two, both return 2.45, and three times the 99.12 Pivot Point less the 99.47 settle gives 197.89, which the 100.17 high and 97.72 low reproduce. The provider's settlement row and the chart's completed Thursday bar carry the same open, extremes and settle. No intraday series was preserved for Thursday, so no timed price path is asserted, and no price move is tied to a headline.
Thursday's card was written on the December contract and is graded only on the provider's December settlement row for 10/22 (open 97.78, high 100.17, low 97.72, settle 99.47, volume 280,425). The daily bar fixes the open, the extremes and the settle, so the order of events within Thursday cannot be shown, and the card's session bands are not graded.
The moving averages were computed from the provider's 259-session daily settlement series for December, with the partial Friday row dropped; the oscillators are cited as published, read at about 6:29 PM ET after the reopen. Thursday's volume and the open-interest figures equal the provider's dated rows. Wednesday's 10/21 row has been revised: December volume now reads 332,174 against the 308,937 cited in Thursday's outlook, and open interest, not reported then, reads 313,678. Thursday's open interest had not been reported. No weekly positioning report was captured. No dealer-positioning dataset was read for crude; the positioning inputs are the Brent spread, the product margins and the open-interest and volume record. Scenario ranges are analyst judgment, and items marked unconfirmed come from the news-feed calendar.
Thursday’s outlook for this contract is here, and the gold contract’s Thursday outlook covers the metal whose December contract settled at 4,060.4 on Thursday, down 2.16 percent. Outlooks for ES, NQ, GC and CL are collected on the market outlook page, and our forward trading record is on the performance statement.