Last night's outlook set a short from 7,595 to 7,605. It activated early and lost. December S&P 500 futures first reached the band in the 1:30 AM ET bar, with a 7,597.50 high, and the 9:30 AM ET bar came within 0.25 of the 7,625 stop at 7,624.75. The 10:30 AM ET bar ran to 7,632.50 and took the stop: a loss of 30.00 points from the bottom of the band and 20.00 from the top. No target traded first. The nearest approach to the 7,575 first objective was 7,584.00, in the 2:00 AM ET and 2:30 AM ET bars.
Technology carried the session. The 10:30 AM ET bar rose 19.75 to 7,632.25, the largest gain of any bar, and the 1:30 PM ET bar printed the 7,671.50 high. The 2:00 PM ET bar then gave back 17.75 to 7,649.00, the largest decline of the day, and the close settled beneath the 20-day average at 7,660.50.
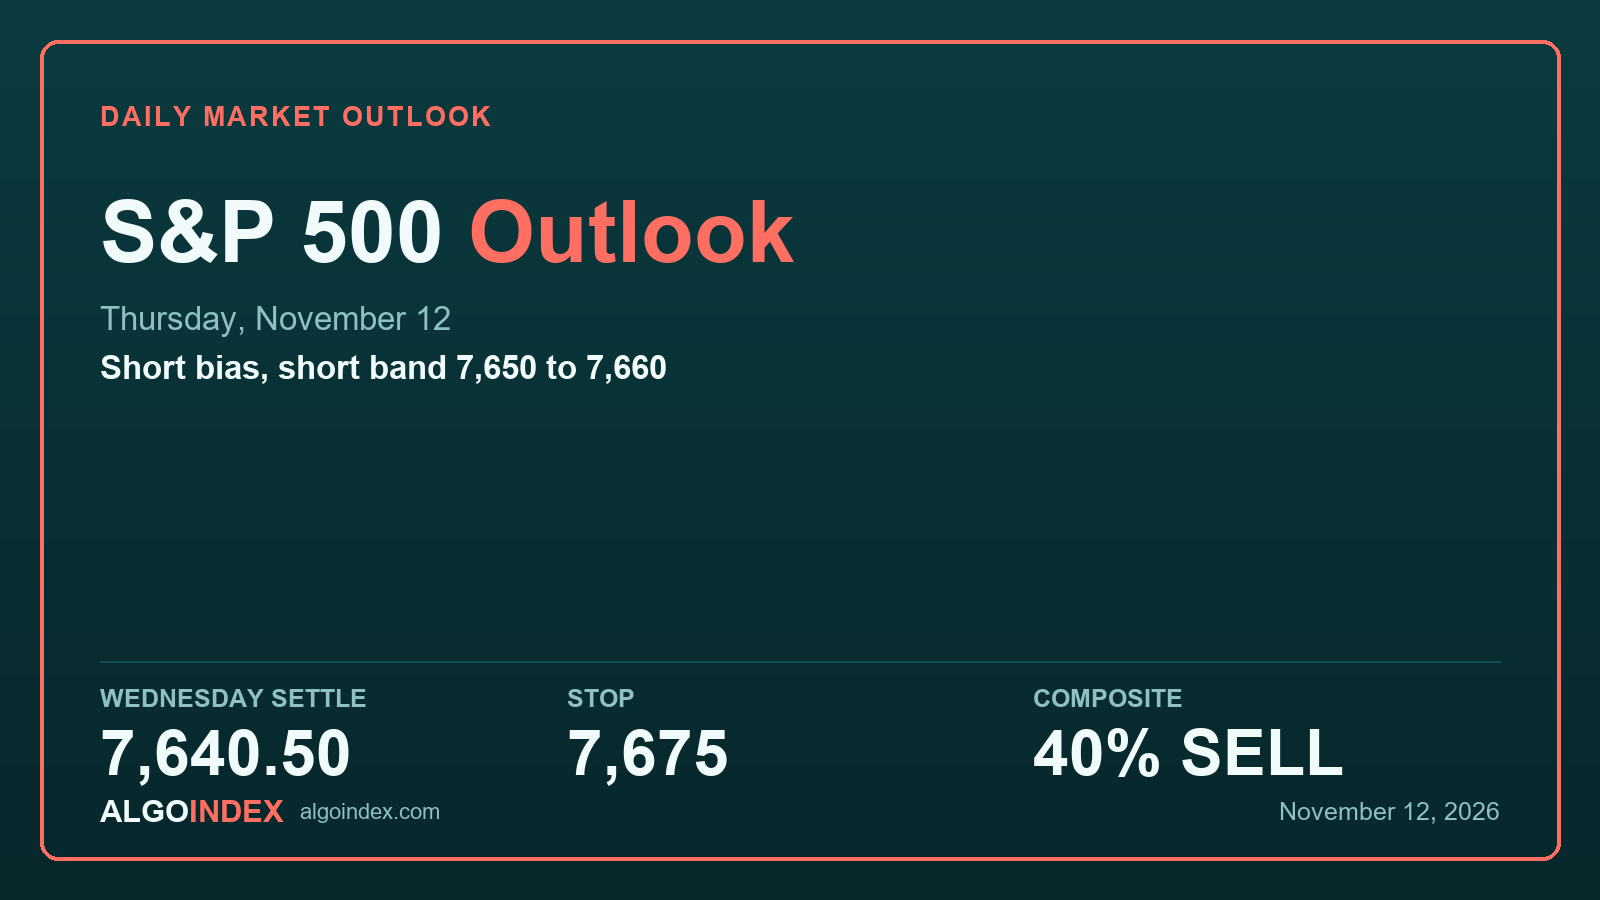
The contract settled at 7,640.50, up 96.25 or 1.28 percent, after a 124.00 point range from 7,547.50 to 7,671.50. That is the highest settle since 11/04/26. It finished at 75.0 percent of the range, and Globex reopened at 6:00 PM ET at 7,616.75, 23.75 beneath it.
- Settle 7,640.50: above the 5-day, 9-day and 200-day averages, beneath the 20-day at 7,660.50, the 50-day and the 100-day.
- Thursday's setup: short 7,650 to 7,660, stop 7,675, targets 7,635, 7,615 and an extended 7,595.
- Thesis negated on a settle above Wednesday's 7,671.50 high; acceptance above the band means two consecutive 30-minute closes above 7,660.
- Dealer map: the 7,619.38 cash close sits 19.38 above the SPX 7,600 modeled volatility threshold (ES 7,621.12) and 80.62 beneath the SPX 7,700 key strike (ES 7,721.12).
- The cash Treasury market reopens Thursday after the Veterans Day close, with weekly jobless claims listed for 8:30 AM ET.
How Wednesday traded: a quiet night, a chip rally, a stall at the 20-day
The night stayed narrow. From the Tuesday 6:00 PM ET reopen at 7,554.25 to 3:00 AM ET the bars held between 7,547.50 and 7,597.50, with the low in the first bar, and closed that window at 7,591.25. From 3:00 AM ET to the cash open the contract traded between 7,587.25 and 7,620.00. The 6:00 AM ET and 6:30 AM ET bars closed at 7,610.50 and 7,609.75, two consecutive closes above 7,605, which removed the edge on the prior card's own acceptance rule hours before the stop traded.
The cash open brought the widest bar. The 9:30 AM ET bar spanned 31.50 points, made the 7,593.25 low of the cash hours and closed at 7,608.25. Buyers took over in the next hour: the 10:30 AM ET bar rose from 7,612.50 to 7,632.25, and the 11:30 AM ET bar added 8.75 to 7,646.50.
The 1:30 PM ET bar made the 7,671.50 high and closed at 7,666.50. Sellers answered at once. From 2:00 PM ET to 4:00 PM ET the bars held between 7,636.75 and 7,667.75, the 3:30 PM ET bar closed at 7,642.50, and the settle printed at 7,640.50. The 4:30 PM ET bar closed at 7,642.25, 1.75 above the settle.
Structure improved for a third session. Wednesday printed a higher high, 72.75 above Tuesday's 7,598.75, and a higher low, 54.50 above Tuesday's 7,493.00, the third consecutive higher low since the 7,322.25 low of 11/06/26. The contract has recovered 257.50 of the 337.50 points lost on 11/05/26 and settles 80.00 beneath the 7,720.50 settle of 11/04/26. Volume was lighter, though: 1,414,528 contracts against 1,803,541 on Tuesday.
The averages split the picture. The settle sits above the 5-day at 7,508.75, the 9-day at 7,561.00 and the 200-day at 7,445.75, and beneath the 20-day at 7,660.50, the 100-day at 7,698.25 and the 50-day at 7,724.50. It is the tenth consecutive settle beneath the 20-day and the 50-day, and the first above the 9-day after a settle beneath it on 11/10/26.
Chips led while the Treasury market stayed shut
Wednesday was Veterans Day. The cash Treasury market was closed, so the rally came without a yield session. Tuesday's October consumer price index had risen 0.4 percent against a 0.3 percent forecast, and a sentiment note in the news feed at 8:54 AM ET said markets continue to price a more hawkish Fed, with investment-bank commentary expecting a second quarter-point hike in December. The dollar index closed at 102.91, up 0.67 percent. Thursday's reopen supplies the rate test Wednesday lacked.
Leadership was narrow. The semiconductor index rose 5.66 percent and the Nasdaq-100 cash index 2.28 percent, against 1.31 percent for the S&P 500 cash index at 7,619.38 and 0.49 percent for the Dow Jones Industrial Average. The provider's commentary tied the move to chipmakers and artificial-intelligence infrastructure shares after a cloud-computing provider posted strong results and raised its forecast. The volatility index fell 1.97 points, or 10.12 percent, to 17.49. Brent's January contract rose 1.39 percent to 92.76, December WTI 0.57 percent, and gold's December contract slipped 0.74 percent.
The dealer-positioning dataset, timed 5:05 PM ET and read against the cash close, places the index 19.38 points above the SPX 7,600 modeled volatility threshold (ES 7,621.12), 86.38 above the SPX 7,533 modeled gamma-flip level (ES 7,554.12) and 119.38 above the SPX 7,500 put side support base (ES 7,521.12). The SPX 7,700 key strike (ES 7,721.12) sits 80.62 above, and the largest gamma concentration is at SPX 8,000 (ES 8,021.12). Gamma notional reads minus 671.676 million dollars, one-month implied volatility 15.39 percent against realized 22.07 percent. The composite multi-indicator read eased to "40% SELL", strength "Minimum", direction "Weakest", from "64% SELL" a session earlier.
The trade map for Thursday
The setup sells a rebound into 7,650 to 7,660. That band sits just beneath the 20-day average at 7,660.50 and Wednesday's 7,671.50 high. The stop at 7,675 clears both that high and the 7,671.27 retracement from the four-week high. Globex reopened at 7,616.75, 33.25 beneath the bottom of the band, so price has to recover first.
Targets step down through known references. The first, 7,635, sits beneath the 7,640.50 settle. The second, 7,615, sits beneath the Pivot Point at 7,619.83 and the SPX 7,600 modeled volatility threshold (ES 7,621.12). The extended 7,595 sits above the 7,593.25 low of the cash hours. Measured from the 7,655 midpoint of the band, reward runs 1:1, 1:2 and 1:3.
A settle above Wednesday's 7,671.50 high negates the thesis. Short of that, two consecutive 30-minute closes above 7,660 remove the edge; a touch alone does not. A further rally in semiconductors, or a soft jobless claims figure with lower yields at the Treasury reopen, could lift the contract through the stop before any target trades. Pivot R1 at 7,692.17 then becomes the reference, 17.17 beyond the stop.
Our base case holds Thursday between Pivot S1 at 7,568.17 and the 20-day average, with a rebound into the band likely to stall beneath 7,671.50. The mid-range scenario runs 7,565 to 7,670, the low-range scenario 7,595 to 7,650 and the high-range one 7,520 to 7,700. On the downside, a broader sale of artificial-intelligence shares could carry the contract through Wednesday's 7,547.50 low toward the SPX 7,500 put side support base (ES 7,521.12) without the rebound the setup needs. The setup is an analyst judgment, not a measured edge.
The complete data picture
Every figure behind Thursday's plan, charted first; the full numeric reference follows underneath.
- S&P 500 cash index 7,619.38 up 1.31%
- Nasdaq-100 cash index up 2.28% led the gain
- Dow Jones Industrial Average up 0.49% lagged
- Semiconductor index up 5.66% group leader
- Volatility index 17.49 down 10.12%
- Dollar index 102.91 up 0.67%
- Brent, January 92.76 up 1.39%
- WTI, December up 0.57% firmer
- Gold, December down 0.74% softer
- Silver, December up 1.52% firmer
- Fri, Nov 13, 8:30 AM ET Producer price index scheduled
- Tue, Nov 17, 5:00 PM ET Largest AI chipmaker results call scheduled
Full numeric reference, every figure from the review
Executive Summary
The December S&P 500 contract settled at 7,640.50 on Wednesday, up 96.25 or 1.28 percent from Tuesday's settle of 7,544.25, after trading between 7,671.50 and 7,547.50, a 124.00 point daily range. The settle finished at 75.0 percent of the range, and the range was 0.88 multiples of the published 14-day average daily range of 141.27 points. Wednesday printed a higher high, 72.75 above Tuesday's 7,598.75, and a higher low, 54.50 above Tuesday's 7,493.00.
The settle is the highest since the 7,720.50 settle of 11/04/26, and the 7,671.50 high is the highest since the 7,738.75 high of 11/05/26. The 1.28 percent gain is the largest since the 2.33 percent gain of 11/09/26, and the 124.00 point range is the widest since the 236.75 point range of that session. The S&P 500 cash index closed at 7,619.38, up 98.45 or 1.31 percent, per the provider's daily record, after trading between 7,571.88 and 7,647.20, so the settle carried a 21.12 point premium over the cash close.
The gain came in the cash hours and was led by technology. The 30-minute series places the low of 7,547.50 in the first bar after the Tuesday 6:00 PM ET reopen and the 7,671.50 high in the 1:30 PM ET bar; the 10:30 AM ET bar rose 19.75, the largest gain of any bar, and the 2:00 PM ET bar fell 17.75, the largest decline. The Nasdaq-100 cash index rose 2.28 percent and the Dow Jones Industrial Average 0.49 percent, and the provider's commentary tied the rally to chipmakers after a cloud-computing provider's strong results, which is attributed commentary. The cash Treasury market was closed for Veterans Day.
Globex reopened at 6:00 PM ET at 7,616.75, 23.75 beneath the settle; those prices belong to Thursday's session.
The composite multi-indicator read published on Wednesday evening is "40% SELL" with strength "Minimum" and direction "Weakest", against "64% SELL" a session earlier. The settle sits above the 5-day, 9-day and 200-day settlement averages and beneath the 20-day, 50-day and 100-day. The Primary Setup in section 8 is a short from the 7,650 to 7,660 band, beneath the 20-day average at 7,660.50, stopped at 7,675 above Wednesday's high, with objectives at 7,635, 7,615 and an extended 7,595.
Price Action & Technical Structure
2.1 Intraday and Session Review
The Wednesday session opened at 7,554.25 at the Tuesday 6:00 PM ET reopen, 10.00 above Tuesday's settle, and the 30-minute series places the low of 7,547.50 in the 6:00 PM ET bar on Tuesday and the high of 7,671.50 in the 1:30 PM ET bar on Wednesday. Between the 6:00 PM ET reopen and 3:00 AM ET the bars held between 7,547.50 and 7,597.50 and closed that window at 7,591.25.
From 3:00 AM ET to the 9:30 AM ET cash open the contract traded between 7,587.25 and 7,620.00 and closed that window at 7,612.75. The 9:30 AM ET bar spanned 31.50 from high to low, the widest bar of the session, and made the 7,593.25 low of the cash hours before closing at 7,608.25. The 10:30 AM ET bar rose 19.75 from 7,612.50 to 7,632.25, the largest gain of any bar, and the 11:30 AM ET bar added 8.75 to 7,646.50.
The 1:30 PM ET bar made the 7,671.50 high and closed at 7,666.50. The 2:00 PM ET bar fell 17.75 to 7,649.00, the largest decline of any bar, and the bars from 2:00 PM ET to 4:00 PM ET held between 7,636.75 and 7,667.75; the 3:30 PM ET bar closed at 7,642.50 and the settle printed at 7,640.50. The 4:30 PM ET bar closed at 7,642.25, 1.75 above the settle.
The provider's overview page, read at 6:21 PM ET, carries an open of 7,616.75, a high of 7,627.75 and a low of 7,607.25 that belong to the Globex session that reopened at 6:00 PM ET on Wednesday, not to Wednesday's completed session; its previous close field reads 7,640.50. Wednesday's completed range is instead recovered from the published pivot ladder. Pivot R3 at 7,816.17 minus Pivot S3 at 7,444.17, divided by three, returns 124.00, and Pivot R2 at 7,743.83 minus Pivot S2 at 7,495.83, divided by two, returns the same 124.00. The published Pivot Point is 7,619.83. Three times that value, less the 7,640.50 settle, gives a high plus low sum of 15,218.99, which with the 124.00 range solves to a high of 7,671.495 and a low of 7,547.495, or 7,671.50 and 7,547.50 at the contract's tick.
That pair, with the 7,640.50 settle, reproduces all seven published rungs. These are the completed-session inputs behind the published pivot ladder rather than an independently read bar, and they are corroborated by the provider's settlement row, the chart's completed daily bar and the 30-minute series, which carry the same 7,554.25 open, 7,671.50 high, 7,547.50 low and 7,640.50 settle.
2.2 Daily Structure
Wednesday printed a higher high and a higher low against Tuesday and settled 96.25 higher, after Tuesday's inside session. Settlements over the last six sessions read 7,720.50, 7,383.00, 7,402.00, 7,574.25, 7,544.25 and 7,640.50, so the contract has recovered 257.50 of the 337.50 points lost on 11/05/26 and settles 80.00 beneath the 7,720.50 settle of 11/04/26.
The settle is the highest since the 7,720.50 settle of 11/04/26, and the 7,671.50 high is the highest since the 7,738.75 high of 11/05/26. The provider publishes 7,905.00 as the 52-week and 13-week high, 7,887.00 as the one-month high and 7,322.25 as the one-month and 13-week low. The settle sits 26.87 above the 7,613.63 midpoint of the 13-week range and 35.87 above the 7,604.63 midpoint of the four-week range, and 30.77 beneath the 7,671.27 retracement from the four-week high.
The settle finished at 75.0 percent of the day's range, 93.00 above the low and 31.00 beneath the high. In this review's interpretation a settle in the upper quarter after a gain of more than one percent describes a session that held most of its advance, while the 31.00 point give-back from the 1:30 PM ET high stopped the advance beneath the 20-day average.
2.3 4-Hour and Swing Structure
Daily ranges over the last nine sessions, from 10/30/26, ran 154.75, 123.00, 77.75, 256.25, 392.75, 146.75, 236.75, 105.75 and 124.00, so Wednesday's range expanded from Tuesday's 105.75 and is the widest since 11/09/26. In the 30-minute series no bar moved more than 19.75 from open to close, and three bars, at 9:30 AM ET, 10:30 AM ET and 2:00 PM ET, spanned 25.00 or more from high to low.
The swing sequence since the 7,322.25 low of 11/06/26 shows highs of 7,600.50 on 11/09, 7,598.75 on 11/10 and 7,671.50 on Wednesday, the highest high since 11/05/26, and lows of 7,363.75, 7,493.00 and 7,547.50, a third consecutive higher low. The published grid places the 13-week midpoint at 7,613.63, the retracement from the four-week high at 7,671.27 and the retracement from the 13-week high at 7,682.39.
2.4 Moving Averages
The averages cited here were computed this analysis from the provider's daily settlement series for the December contract, which holds 259 completed sessions from 11/03/25 through Wednesday; the partial row dated Thursday, opened by the 6:00 PM ET Globex reopen, was excluded before counting, and each average is carried at full precision and rounded once to the tick. The 200-day window contains 25 rows with zero volume from the contract's deferred months, which are included as settlements. The 5-day average stands at 7,508.75, the 9-day at 7,561.00, the 20-day at 7,660.50, the 50-day at 7,724.50, the 100-day at 7,698.25 and the 200-day at 7,445.75.
The 7,640.50 settle sits 131.75 above the 5-day average, 79.50 above the 9-day and 194.75 above the 200-day, and 20.00 beneath the 20-day, 84.00 beneath the 50-day and 57.75 beneath the 100-day. It is the first settle above the 9-day average after a settle beneath it on 11/10/26, the tenth consecutive settle beneath the 20-day and the 50-day, the last settle above both on 10/28/26, and the third consecutive settle above the 200-day, the last settle beneath it on 11/06/26.
The 50-day average sits above the 100-day because the 50 older settlements in the 100-day window averaged lower, at 7,672.2, and the 100-day sits above the 200-day because the 100 older settlements in the 200-day window averaged lower, at 7,193.17. The 20-day sits beneath the 50-day because the 30 older settlements in the 50-day window averaged higher, at 7,767.06, and the 5-day sits beneath the 20-day because the 15 older settlements in the 20-day window averaged higher, at 7,711.03. The 5-day average fell from Tuesday's 7,524.75 as Wednesday's settle replaced the 11/04 settle of 7,720.50.
2.5 Oscillator and Trend Readings
The oscillator figures below are as published on the provider's technical page, read at 6:21 PM ET on Wednesday after the Globex reopen, so they may include the live price of the reopened session; they are the provider's readings, not the computations. The 9-day relative strength reads 50.93, the 14-day relative strength 48.84 and the 20-day relative strength 48.27.
The 9-day raw stochastic reads 75.06 percent, the 14-day stochastic %K 53.11 percent and the 14-day stochastic %D 38.36 percent, with %K above %D. The 9-day directional index ADX reads 21.43 with the 9-day +DI at 22.11 and the 9-day -DI at 18.03, so positive direction leads on the 9-day system, and the 14-day directional index ADX reads 18.35 with the 14-day +DI at 20.54 and the 14-day -DI at 19.84. The 9-day historic volatility reads 30.44 percent and the 14-day historic volatility 25.01 percent.
The composite multi-indicator read published on Wednesday evening, on a page titled for Thursday, November 12, 2026, is "40% SELL", with signal strength "Minimum" and direction "Weakest". The snapshot history reads "64% SELL" for the prior session, "48% SELL" a week ago and "96% BUY" a month ago. The short horizon group averages "40% SELL", the medium group "25% SELL" and the long group "33% SELL", and the trend composite reads "SELL".
2.6 Volatility and Expected Range
The published 14-day average true range stands at 130.22 points and the 14-day average daily range at 141.27 points; the 9-day average true range is 146.54 with a 9-day average daily range of 179.75, and the 20-day average true range is 118.13 with a 20-day average daily range of 128.11. Wednesday's 124.00 point range was 0.88 multiples of the 14-day average daily range.
Adding and subtracting the 14-day average true range of 130.22 from the 7,640.50 settle frames Thursday between 7,510.28 and 7,770.72. The published standard-deviation bands, built from five settlements, span 7,528.57 to 7,752.43 at one deviation, 7,482.20 to 7,798.80 at two and 7,446.62 to 7,834.38 at three. The dataset's implied one-day move of 0.59 percent is roughly 45 points against the 7,619.38 cash close, inside the 130.22 point average true range.
Key Levels
3.1 Resistance
Above the 7,640.50 settle, the first references are the 7,645.87 projection of the 18-day crossing and the 20-day average at 7,660.50, followed by the 7,671.27 retracement from the four-week high and Wednesday's 7,671.50 high. The 7,682.39 retracement from the 13-week high and Pivot R1 at 7,692.17 form the next band, with the 7,714.53 published target price, the 7,721.12 conversion of the SPX 7,700 key strike and the 50-day average at 7,724.50 above. Pivot R2 at 7,743.83 is the deeper reference.
3.2 Support
Beneath the settle sit the source's 7,621.40 futures pair and the 7,621.12 conversion of the SPX 7,600 modeled volatility threshold, with the Pivot Point at 7,619.83 just beneath. The 7,604.63 four-week midpoint and the 7,593.25 low of the cash hours lead into Pivot S1 at 7,568.17, the 9-day average at 7,561.00 and the 7,554.12 conversion of the SPX 7,533 modeled gamma-flip level. Wednesday's 7,547.50 low, the 7,521.12 conversion of the SPX 7,500 put side support base and Pivot S2 at 7,495.83 are the deeper references.
Macro Drivers
4.1 Dollar, Rates, and Fed Policy
The October consumer price index, released at 8:30 AM ET on Tuesday, November 10, 2026, per the verified forward calendar, rose 0.4 percent against a 0.3 percent forecast, per the news-feed calendar's actual values. At 8:54 AM ET on Wednesday the news feed carried a sentiment note that markets continue to price a more hawkish Fed, and investment-bank commentary in the same feed expected a second quarter-point hike in December. The dollar index's daily record closed at 102.91, up 0.67 percent, and the cash Treasury market was closed for Veterans Day, so the equity rally came without a yield session; in this review's interpretation Thursday's Treasury reopen supplies the rate test Wednesday lacked.
4.2 Large-Cap Leadership and Earnings
The provider's commentary tied the rally to chipmakers and artificial-intelligence infrastructure shares after a cloud-computing provider posted strong results and raised its forecast, which is attributed commentary. The largest artificial-intelligence chipmaker's results are scheduled with a conference call at 5:00 PM ET on Tuesday, November 17, 2026, per the verified forward calendar, and a networking-equipment company's results are listed for 4:05 PM ET on Thursday, November 12, 2026 by the news-feed earnings table, unconfirmed.
4.3 Crude Oil
Brent's January contract rose 1.39 percent to 92.76; the index's gain came alongside firmer crude.
4.4 Sector Breadth and Rotation
The semiconductor index's daily record rose 5.66 percent and the Nasdaq-100 cash index 2.28 percent, against 1.31 percent for the S&P 500 cash index and 0.49 percent for the Dow Jones Industrial Average, so the gain was concentrated in technology rather than spread evenly. The S&P 500 cash index traded between 7,571.88 and 7,647.20, a 75.32 point range, per the provider's daily record. In this review's interpretation a rally led this heavily by one group is more exposed to news about that group, which is the setting for Thursday's open.
4.5 Cross-Asset and Volatility
The volatility index's daily record closed at 17.49, down 1.97 points or 10.12 percent from 19.46, after a 17.33 low and an 18.96 high. December WTI rose 0.57 percent, gold's December contract fell 0.74 percent and silver's December contract rose 1.52 percent. The S&P 500 positioning console shows one-month implied volatility at 15.39 percent against one-month realized volatility of 22.07 percent, with an implied volatility rank of 32.59 percent.
4.6 Institutional Positioning
The latest weekly positioning report on the provider's overview, for the week to Tuesday, November 3, 2026, shows asset managers at 1,111,721 long, up 666, against 183,137 short, down 4,469, and dealers at 182,419 long against 870,993 short, as listed and not recomputed. Wednesday's December volume was 1,414,528 contracts against 1,803,541 on Tuesday, per the settlement record, so the gain came on lower participation than Tuesday's inside session.
Options positioning
The dealer-positioning dataset read for this section, the edition timed 5:05 PM ET on Wednesday, uses Tuesday's closes as its reference prices, not Wednesday's: SPX 7,520 equals Tuesday's 7,520.93 cash close, which the positioning console also carries as its previous close. Tuesday's 7,520.93 plus 98.45 points, a 1.31 percent gain, gives the provider's 7,619.38 Wednesday close, and every level below is read against that close.
On the index the primary call side ceiling sits at SPX 8,100, the largest gamma concentration at SPX 8,000, the modeled volatility threshold at SPX 7,600, the modeled gamma-flip level at SPX 7,533 and the primary put side support base at SPX 7,500. The close sits 480.62 points beneath the ceiling and 380.62 beneath the largest concentration, and 19.38 above the threshold, 86.38 above the flip level and 119.38 above the put side base. Gamma tilt reads 0.812, gamma notional minus 671.676 million dollars and the dataset's gamma index minus 2.845, with an implied one-day move of 0.59 percent and an implied five-day move of 1.48 percent. The dataset's key strikes are SPX 8,000, 7,000, 7,500 and 7,700, and its summary block lists resistance at 7,600 and 7,700, a dealer-positioning pivot at 7,500 marked as updated on 11/11/26 and support at 7,500 and 7,300.
The dataset publishes its own December futures pair for each level, carrying the source's 21.40 point offset rather than the measured 21.12 point basis: the ceiling at 8,121.40, the largest concentration at 8,021.40, the modeled volatility threshold at 7,621.40, the modeled gamma-flip level at 7,554.40 and the put side support base at 7,521.40. These are quoted as the source's pairs. The modeled threshold and flip level are model outputs, not option strikes. At the measured basis the SPX 7,300 support converts to 7,321.12, the SPX 7,500 base to 7,521.12, the SPX 7,533 flip level to 7,554.12, the SPX 7,600 threshold to 7,621.12, the SPX 7,700 key strike to 7,721.12 and the SPX 8,000 concentration to 8,021.12.
The S&P 500 positioning console, read at 6:21 PM ET, carried Tuesday's 7,520.93 as its previous close and 7,619.15 as its current price, with call gamma of 2.97 billion dollars against put gamma of minus 6.81 billion dollars and a put to call open interest ratio of 1.33. The tracking fund's levels in the dataset are 750 for the threshold, 754 for the flip level, 740 for the put side base and 775 for the ceiling, against a 749 reference price.
In this review's interpretation a cash close 19.38 points above the SPX 7,600 threshold, with negative gamma notional and the SPX 7,700 key strike 80.62 points above, places the index between the dataset's nearest references, where the threshold is the first test beneath and the 7,700 strike the first above. The setup in section 8 sells a rebound toward the 20-day average at 7,660.50, beneath the 7,721.12 conversion of the SPX 7,700 strike, with its second objective beneath the 7,621.12 conversion of the threshold. Statements in the dataset about the order of intraday moves are not used; the session path in section 2.1 comes from the futures series.
Forecast
Night Session (6:00 PM ET Wednesday to 3:00 AM ET Thursday, Globex/Asia)
Globex reopened at 6:00 PM ET on Wednesday at 7,616.75, 23.75 beneath the settle. Japanese producer prices are listed for 6:50 PM ET on Wednesday, November 11, 2026 by the news-feed calendar, unconfirmed. Bias neutral to lower around the Pivot Point at 7,619.83, expected band roughly 7,580 to 7,645.
London Session (3:00 AM to 8:00 AM ET Thursday)
UK growth data are listed for 2:00 AM ET on Thursday, November 12, 2026 by the news-feed calendar, unconfirmed, ahead of the London session. Bias neutral beneath the 20-day average at 7,660.50, expected band roughly 7,575 to 7,650.
Morning Session (9:30 AM to 12:00 PM ET Thursday, RTH Open)
Weekly jobless claims are listed for 8:30 AM ET on Thursday, November 12, 2026 by the news-feed calendar, unconfirmed, and existing home sales are listed for 10:00 AM ET by the same calendar, also unconfirmed. The 9:30 AM ET cash open is the first cash-market response to the after-close company news at the largest artificial-intelligence chipmaker and the first session with the cash Treasury market open since Tuesday. Expected band roughly 7,565 to 7,665, with the 7,650 to 7,660 setup band near the top.
Afternoon Session (12:00 PM to 4:00 PM ET Thursday)
A 30-year bond auction is listed for 1:00 PM ET on Thursday, November 12, 2026 by the news-feed calendar, unconfirmed. Expected band roughly 7,575 to 7,660 into the 4:00 PM ET cash close.
Night Session Forward (6:00 PM ET Thursday)
A networking-equipment company's results are listed for 4:05 PM ET on Thursday, November 12, 2026 by the news-feed earnings table, unconfirmed. The evening session carries into the producer price index at 8:30 AM ET on Friday, November 13, 2026, per the verified forward calendar.
Expected Range (Thursday Full Session)
Low-range scenario: 7,595 to 7,650
Mid-range scenario (most likely): 7,565 to 7,670
High-range scenario: 7,520 to 7,700
Most Likely Path
In this review's analyst judgment, the most probable path holds the contract between Pivot S1 at 7,568.17 and the 20-day average at 7,660.50, with a rebound toward the 7,650 to 7,660 band that stalls beneath Wednesday's 7,671.50 high weighted above a settle through it. The reopened session traded 23.75 beneath the settle, the composite reads "40% SELL" and the settle sits beneath the 20-day, 50-day and 100-day averages, which in this review's interpretation favours selling a rebound into the 20-day rather than buying the reopen.
The alternative that would invalidate this reading is a settle above Wednesday's 7,671.50 high, which would bring Pivot R1 at 7,692.17 and the 7,721.12 conversion of the SPX 7,700 key strike into play; lower yields at the Treasury reopen are the input most likely to drive that alternative. On the other side, a broader sale of artificial-intelligence shares could carry the contract through Wednesday's 7,547.50 low toward the 7,521.12 conversion of the SPX 7,500 put side base without the rebound the setup needs.
Calendar
Wednesday's releases are complete. Wednesday, November 11, 2026 was the Veterans Day holiday, with CME Globex on normal hours and normal settlement times and banks closed, per the verified forward calendar, and the cash Treasury market closed while equity markets traded. The December contract settled at 7,640.50.
Thursday opens with UK growth data listed for 2:00 AM ET by the news-feed calendar, unconfirmed, and weekly jobless claims listed for 8:30 AM ET on Thursday, November 12, 2026 by the news-feed calendar, unconfirmed. Existing home sales are listed for 10:00 AM ET by the news-feed calendar, unconfirmed, and remarks by several Fed officials are listed from 9:00 AM ET through the evening by the news-feed calendar, unconfirmed. A 30-year bond auction is listed for 1:00 PM ET by the news-feed calendar, unconfirmed, and a networking-equipment company's results for 4:05 PM ET by the news-feed earnings table, unconfirmed.
Later in the week, the producer price index is scheduled for 8:30 AM ET on Friday, November 13, 2026, per the verified forward calendar. In this review's judgment the first-order input for the S&P 500 on Thursday is the cash-market response at the 9:30 AM ET open to the after-close company news at the largest chipmaker, with the reopening of the cash Treasury market as the second input.
Primary setup
Direction: Short
Rationale: The settle sits 20.00 beneath the 20-day average after a 1.28 percent gain concentrated in technology, the reopened session traded 23.75 beneath the settle after the after-close company news, and the composite reads "40% SELL". A rebound into the 7,650 to 7,660 band, beneath the 20-day average at 7,660.50 and Wednesday's 7,671.50 high, offers a short with a defined risk point above that high. Lower yields at the Treasury reopen can carry price through the band, so the setup is an analyst judgment that rebounds into the 20-day are sold, not a measured edge.
Entry Zone: 7,650 to 7,660
Stop Loss: 7,675 (above Wednesday's 7,671.50 high and the 7,671.27 retracement from the four-week high)
Target 1 (T1): 7,635 (beneath the 7,640.50 settle)
Target 2 (T2): 7,615 (beneath the Pivot Point at 7,619.83 and the 7,621.12 conversion of the SPX 7,600 threshold)
Target 3 (T3, extended): 7,595 (above the 7,593.25 low of the cash hours)
Risk-to-Reward: Approximately 1:1 to T1, 1:2 to T2, 1:3 to T3
Invalidation: A settle above Wednesday's 7,671.50 high negates the thesis. Short of that, the edge is removed by acceptance above the entry band rather than by a touch, defined as two consecutive 30-minute closes above 7,660.
Macro override: A further rally in semiconductors or a soft jobless claims figure with lower yields at the Treasury reopen would lift the contract. In that scenario a move through the 7,675 stop invalidates the short before the targets, and Pivot R1 at 7,692.17 becomes the reference, 17.17 beyond the stop and well inside one 14-day average true range of 130.22.
Sources and methodology
Prices, settlements and volume come from the exchange settlement record and the provider's daily series for the December contract (ESZ26). Session timing comes from the 30-minute bar series of Wednesday's Globex session, from the Tuesday 6:00 PM ET reopen. Moving averages were computed from 259 completed daily settlements; oscillators, the composite read and the pivot ladder are quoted as published, and the pivot ladder was checked against Wednesday's high, low and settle. Dealer-positioning levels come from an options positioning dataset timed 5:05 PM ET, read against the cash close, and are converted to futures at the measured 21.12 point basis. Economic-calendar times come from the verified forward calendar unless marked as listed and unconfirmed.
The prior card is graded only on its own levels, against the full Wednesday session from the Tuesday 6:00 PM ET reopen through the 4:30 PM ET bar; no fill is assumed, and the loss is measured from both edges of the band.
Wednesday stopped beneath the 20-day average, and Thursday's first test is whether a rebound reaches it again.