At 5.18 percent, the ten-year yield index touched what press commentary described as a 19-year high on Thursday. It closed at 5.16 percent. Press commentary quoted two regional Federal Reserve presidents leaning toward further tightening, and crude rose 2.66 percent on Middle East supply risk. Then a report crossed the news feed at 12:15 PM ET that the United States and Iran were exploring a phased deal to reopen the Strait of Hormuz, and press commentary attributed a recovery in stocks to short covering. The S&P 500 cash index finished down 1.90 points.
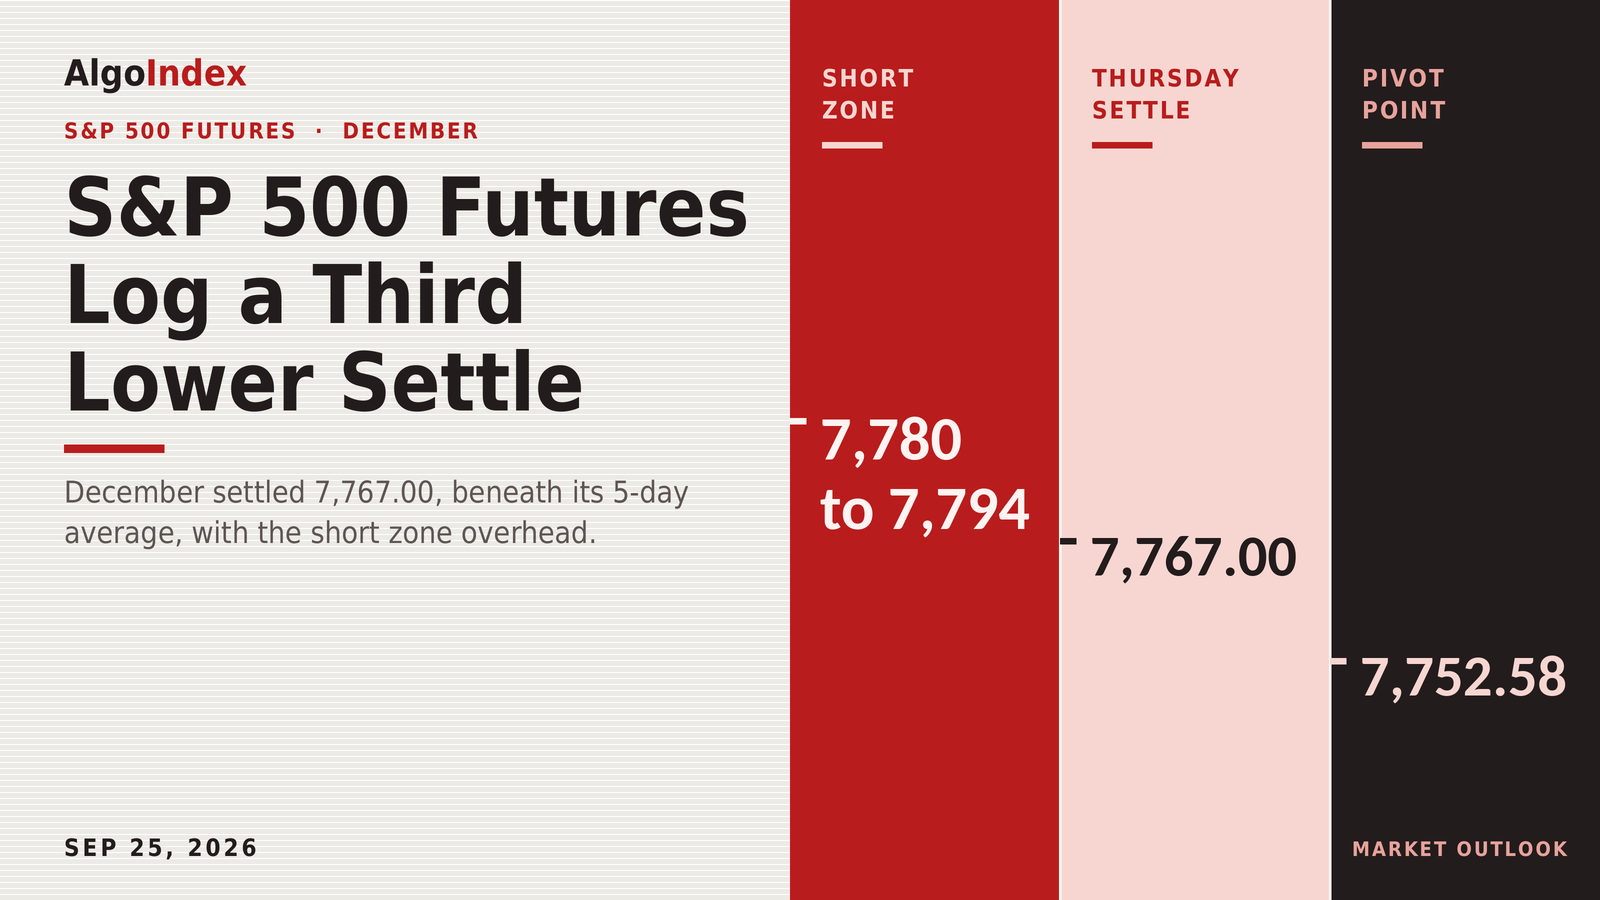
December E-mini futures settled at 7,767.00, down 5.50 points or 0.07 percent from Wednesday's 7,772.50. It was the third consecutive lower settle and the lowest since 09/18/26, when the contract settled at 7,712.50. The completed session ran from 7,783.50 to 7,707.25, a 76.25 point band worth 0.98 times the 14-day average daily range of 77.59. The settle landed at 78.4 percent of it, 59.75 points above the low. Lower high, lower low, top-quarter close. The cash index closed at 7,704.13, down 0.02 percent, after a 7,662.57 to 7,719.01 range. The headlines and the price path coincided, but no time-stamped intraday series was captured, so no causal ordering is asserted here.
December S&P 500 futures settled at 7,767.00, 14.42 points above the 7,752.58 Pivot Point and 16.45 points beneath the 5-day settlement average at 7,783.45. The first ceiling is the 7,777.87 to 7,783.50 zone. There the futures equivalent of the modeled volatility threshold (cash 7,715) meets the 5-day average and Thursday's high. The Pivot Point, whose cash equivalent lands within one point of the positioning note's 7,690 pivot, is the most important line in the instrument. The primary setup is a short from 7,780 to 7,794, stop 7,819, targets 7,755, 7,723 and 7,691. The cash index closed 10.87 points beneath the 7,715 threshold and 43.13 points above the 7,661 modeled gamma flip, the same in-between zone as Wednesday.
Thursday's short card against a 7,783.50 high
Thursday's outlook set a short from 7,782 to 7,798, stop 7,826, targets 7,754, 7,718 and 7,682. The band traded, barely. Thursday opened at 7,774.75, 7.25 points beneath the bottom of the zone, and the session high of 7,783.50 reached 1.50 points into it. The top of the band stayed 14.50 points above the high. The 7,826 stop was not touched; the high finished 42.50 points beneath it.
Two targets traded. The low at 7,707.25 sat 46.75 points beneath the 7,754 first target and 10.75 points beneath the 7,718 second. The 7,682 third target stayed 25.25 points under the low. No intraday series was captured, so whether the high came before the low is not established here, and no fill or result is asserted.
The settle gave much of the drop back. At 7,767.00 it finished 15.00 points beneath the bottom of the zone and 13.00 points above the first target. The card's invalidation line, a settle above 7,824.25, stayed 57.25 points away.
Wednesday night's map had a mixed session. We named 7,756 to 7,760 the most important support in the instrument; Thursday's low went 48.75 points through 7,756, and the settle recovered to 7.00 points above 7,760. The one-range envelope we published, 7,699.61 to 7,845.39, held the whole session, the low by 7.64 points. The one standard deviation band did not. The low went 14.75 points beneath its 7,722.00 edge, and the 7,701.09 two-deviation line sat 6.16 points under the low. Of the three scenario bands, only the high-range case, 7,700 to 7,845, contained the whole session; the low went 17.75 points beneath the 7,725 bottom of the most likely band, while the settle landed inside all three.
The card's macro override is the other check. It named a claims print followed by lower yields, or a seven-year auction that stops through its when-issued level. Claims printed 197,000 against a 200,000 consensus, per the news-feed calendar and unconfirmed. The ten-year still closed 5 basis points higher. The auction stopped at a 5.085 percent high yield; no when-issued level was captured, so that leg cannot be graded.
Geometry is what the bar does establish. The settle finished 7.75 points beneath the open, 16.50 beneath the high and 59.75 above the low. Against Wednesday, the high sat 59.75 points lower at 7,783.50 and the low 51.50 points lower. Yet the close reversed Wednesday's 16.3 percent finish. The three lower settles have removed 66.50 points from Monday's 7,833.50. The prior week, September 14 through September 18, spanned 7,575.00 to 7,739.25; Thursday's low probed back inside it while the settle held 27.75 points above its top.
The 7,752.58 pivot and a threshold at 7,777.87
Overhead, four references stack inside 5.63 points. The cash threshold of 7,715 converts to 7,777.87 at the measured basis of 62.87, the 7,767.00 settle less the 7,704.13 cash close. The positioning note's own futures pair quotes 7,779.5 (cash 7,715) at that source's fixed 64.5 offset. The 5-day average at 7,783.45 and Thursday's 7,783.50 high close the zone. The high stopped at the shortest average. A settle above that zone would put the cash index back above its threshold.
Above it the ladder climbs in pairs. The stochastic 80 percent threshold at 7,793.80 and Pivot R1 at 7,797.92 come first, 4.12 points apart. Pivot R1 converts to 7,735.05 in cash at the measured basis, the call strike of the iron condor the positioning note described. The three-and-ten day crossover stall at 7,814.57, one standard deviation resistance at 7,817.65 and Pivot R2 at 7,828.83 follow. Extended references sit higher. Wednesday's 7,843.25 high, the 7,848.50 swing high of 09/22 and the one-month high at 7,850.75, set on 08/28/26, come first, then the note's 7,800 cash ceiling at 7,862.87 at the measured basis, with the note's own pair at 7,864.5. Pivot R3 sits at 7,874.17, and the 13-week and 52-week high at 7,905.00 is 138.00 points above the settle.
Beneath price the first two references are almost touching. The stochastic 70 percent threshold at 7,766.45 and the 40-day crossing price at 7,765.78 sit 0.55 and 1.22 points under the settle. The Pivot Point at 7,752.58 is the first genuine support. At the measured basis its cash equivalent is 7,689.71, within one point of the note's own 7,690 pivot. That makes 7,752 to 7,753 the most important line in the instrument. The 38.2 percent retracement from the four-week high at 7,745.41 and the 20-day settlement average at 7,743.78 follow, with the prior week's 7,739.25 high just beneath.
Then a tight group. The 9-day crossing at 7,737.94, the 18-day crossing at 7,735.82 and the 9-day settlement average at 7,732.92 sit within 5.02 points of each other. The note's modeled gamma-flip pair quotes 7,725.5 (cash 7,661) at the 64.5 offset. Pivot S1 at 7,721.67 sits 3.83 points beneath it. The base of the week's range follows: the 50-day settlement average at 7,717.47, one standard deviation support at 7,716.35, the 50 percent four-week retracement at 7,712.88 and Thursday's 7,707.25 low. Pivot S2 at 7,676.33 and Pivot S3 at 7,645.42 are the extended references.
One average now sits overhead. The 5-day at 7,783.45 is 16.45 points above the settle. The others sit beneath it: the 20-day at 7,743.78 by 23.23 points, the 9-day at 7,732.92 by 34.08 and the 50-day at 7,717.47 by 49.54. The 50-day carries a caveat. The December contract was the deferred month until mid-September, so its window includes thinly traded sessions. The captured history covers 60 completed sessions, so no 100-day or 200-day average is cited. Distances are measured from the exact averages, 7,743.775 and 7,717.465 for the 20-day and 50-day, which are rounded once, half-up, for display.
Zoom out. The swing from the 09/16 low at 7,575.00 to the 7,848.50 high of 09/22 measured 273.50 points. Thursday's low retraced 141.25 points of it, or 51.6 percent, and the settle 81.50 points, or 29.8 percent. The published 50 percent retracement of the four-week range sits at 7,712.88, 5.63 points above the low, so the low reached the midpoint of the four-week structure. The 13-week range runs from 7,386.00 to 7,905.00, with the settle 381.00 points above its low. The one-month range runs from 7,575.00, set on 09/16/26, to 7,850.75.
A 5.18 percent yield high and a minus 12 billion dollar hedging day
The hedging flow eased. The positioning note recorded index hedging delta of minus 12 billion dollars on the day, mostly in same-day expiries, after minus 20 billion on Wednesday, and read it as tactical rather than longer-dated hedging demand. Single-stock hedging delta was plus 2 billion dollars. Longer-dated call buying drove it, concentrated in a megacap platform company that rose about 5 percent after its product launch. These are the note's characterisations; no timestamp-aligned flow series was captured.
The model still has the index between its lines. The cash close at 7,704.13 sits 10.87 points beneath the modeled volatility threshold at 7,715 and 43.13 points above the modeled gamma-flip level at 7,661, a second session in that zone. There, dealer hedging dampens movement less than it does above the threshold. That is the model's reading of the configuration; nothing captured here measures it as a cause of Friday's behaviour. The note named a source. It attributed Thursday's mean-reverting character to a 7,000-lot iron condor in the cash index at 7,735/7,740 and 7,620/7,615, which it described as adding positive dealer hedging exposure in that zone.
The rest of the stack is wide. It shows a primary gamma concentration at 8,000, a call-side ceiling at 7,800 and a put-side base at 7,500. The gamma index reads 1.391, gamma tilt 1.109 and gamma notional 404.361 million dollars, and the 25-delta risk reversal sits at minus 0.037. Puts led again. Put volume of 1.031 million contracts ran 1.31 times the 789,357 calls, and put open interest of 12.911 million ran 1.43 times the 9.059 million in calls.
The note's own summary is blunt. It lists resistance at 7,700 and 7,800, a pivot at 7,690 and support at 7,600, with mapped key levels at 8,000, 7,700, 7,000 and 7,800. It stated that the index had broken back below its 7,690 pivot during the session and that its stance was risk-off until the index crossed back above. The cash close sits 14.13 points above that pivot.
Volatility rose modestly. The volatility index closed at 15.67, up 0.49 points, and the note recorded the volatility-of-volatility index at 90.57, up 2 points, with fixed-strike volatility up 1 to 2 points as the market pulled back from record highs. The note's implied one-day move for the cash index is 0.66 percent, or 50.85 index points on Thursday's close, framing 7,653.28 to 7,754.98. It separately put at-the-money implied volatility for Friday at 13.7 percent. The note translated that into an 86 basis point implied intraday move.
Rates did the pushing. The ten-year yield index traded 5.09 to 5.18 percent and closed at 5.16 percent, up 5 basis points, and the thirty-year closed at 5.46 percent. The dollar index closed at 101.29, up 0.19 percent. The seven-year note auction stopped at a 5.085 percent high yield with a 2.420 bid-to-cover against 2.500 previously, per the news-feed calendar and unconfirmed. New home sales printed 0.684 million against 0.6155 million, per the news-feed calendar and unconfirmed. Press commentary described claims at a two-month low and sales at an eight-month high.
Fed speakers leaned the same way. Press commentary quoted the New York Federal Reserve president as saying the central bank has a lot of work to do to contain inflation, and the Philadelphia Federal Reserve president as saying some modest further tightening may be warranted. The positioning note cited fed funds futures pricing a roughly 71 percent likelihood of an October increase. A week earlier it was roughly 55 percent.
Oil carried the geopolitical risk. Crude settled at 94.61, up 2.66 percent, and Brent at 106.60, up 3.41 percent, while gold settled at 4,298.0, down 0.47 percent. The Middle East carried both escalation and de-escalation reporting. The Senate rejected a resolution curbing the administration's Iran war powers at 2:38 PM ET, and the news feed carried claims by Yemen's Houthis of attacks at Yanbu and in Riyadh at 3:02 PM and 3:03 PM ET.
Leadership narrowed. Press commentary described the Dow closing down 0.31 percent at a one-week low while the Nasdaq-100 closed up 0.03 percent, so megacap technology outperformed the industrial and cyclical names. No sector-level breadth series was captured, so no advance-decline figure is asserted. After the close, a large warehouse retailer reported fiscal fourth-quarter earnings of 6.75 dollars a share against a 6.53 estimate and revenue of 95.72 billion dollars against 94.92 billion, per a news-feed item stamped 4:18 PM ET. The verified forward calendar lists it as an after-close release on September 24, 2026. The Chinese president described a new joint trade arrangement with the United States as good news, per items stamped 4:16 PM and 4:24 PM ET.
Positioning is still lopsided. In the report as of September 15, 2026, the latest captured, leveraged funds held 161,176 long against 454,319 short, a net short of 293,143 after covering 42,302 shorts on the week. Asset managers held 1,142,075 long against 237,391 short, a net long of 904,684. Dealers held 220,012 long against 922,950 short. Open interest on the December contract stood at 1,894,151 on the latest published row, for 09/23, against 1,884,650 on 09/22. Thursday's dated row shows preliminary volume of 1,687,322 contracts, against 1,557,112 on Wednesday, and no open interest yet. The heavy leveraged-fund short keeps a squeeze available on good news. That is the review's interpretation; no flow measured it.
The trade map for Friday
The primary setup is a short from 7,780 to 7,794. The contract has made three consecutive lower settles and sits beneath its 5-day settlement average, where Thursday's high stopped. Sellers lead on every directional horizon. The cash index closed beneath its modeled volatility threshold for a second session, against a 5.16 percent ten-year yield. The band sits around the futures equivalent of that threshold, the 5-day average and Thursday's high. The stop is 7,819, above one standard deviation resistance at 7,817.65 and the three-and-ten day crossover stall at 7,814.57. The targets step down the ladder: 7,755, then 7,723, then 7,691.
From the 7,787 midpoint the risk to the stop is 32 points, 41.3 percent of the 14-day average true range of 77.46. The three targets sit 32, 64 and 96 points beneath that midpoint. Thursday's close in the top quarter of its range argues that sellers do not own the session, so the review treats T1 as the realistic objective unless the pivot fails. A one-range projection from the settle spans 7,689.54 to 7,844.46. It holds the zone, the stop and all three targets. The published one-deviation band is tighter, 7,716.35 to 7,817.65, and the stop sits 1.35 points above its top edge.
The scenario ranges are analyst judgment. None carries a calibration. The low-range case runs 7,735 to 7,790, the most likely 7,715 to 7,800 and the high-range case 7,690 to 7,830. Session by session the review expects roughly 7,740 to 7,785 through Globex, with a neutral bias above 7,752.58. London's band is 7,735 to 7,790, also neutral, with European yields the main transmission. The morning band is 7,720 to 7,800 and the afternoon 7,725 to 7,795.
So far the reopen is quiet. The Globex session that began at 6:00 PM ET opened at 7,759.00, 8.00 points beneath the settle, and was trading between 7,756.50 and 7,763.75 at the time of reading, above the 7,752.58 pivot. Those prints belong to Friday's session. They form no part of Thursday's range, and the captured news-feed calendar carries no Asian release for the Thursday evening window.
Europe brings two items. Euro-area money-supply growth prints at 4:00 AM ET, forecast 3.5 percent against a prior 3.4 percent, and the New York Federal Reserve president speaks at 5:15 AM ET, both per the news-feed calendar and unconfirmed.
Then the first-order event. The advance durable goods report lands at 8:30 AM ET on September 25, 2026, per the verified forward calendar. Headline orders are forecast at minus 0.3 percent against a prior 1.1 percent and core orders at plus 0.6 percent against a prior 0.4 percent, per the news-feed calendar and unconfirmed. The review reads the report through its effect on the ten-year yield. The cash open at 9:30 AM ET sets the first directional test against the 7,777.87 to 7,783.50 zone above and the 7,752.58 pivot beneath. The final University of Michigan survey prints at 10:00 AM ET, with sentiment forecast at 47.5 against 47.8 and five-year inflation expectations at 3.4 percent, per the news-feed calendar and unconfirmed.
Two lines frame the day. A cash recovery above the 7,715 threshold would change the character of the session. A futures settle beneath 7,752.58 would put the 7,707.25 low back in play. In the afternoon a European Central Bank speaker and the Cleveland Federal Reserve president both appear at 2:00 PM ET, per the news-feed calendar and unconfirmed. No structural index expiry falls on Friday; the December contract expires on 12/18/26.
Then comes a weekend. Globex does not reopen on Friday evening, and the next session opens at 6:00 PM ET on Sunday. Two days of headline exposure, with an open Middle East negotiation, separate Friday's close from the reopen. A constructive weekend points to Pivot R1 at 7,797.92 and Pivot R2 at 7,828.83; a risk-off weekend points to the 7,707.25 low and Pivot S2 at 7,676.33. Then the calendar thickens. The note lists the quarter end and the personal consumption expenditures report on September 30 and the employment report on October 2 as the next first-order grouping. Personal income and outlays land at 8:30 AM ET on September 30, 2026. The employment report follows at 8:30 AM ET on October 2, 2026, both per the verified forward calendar.
The most probable path holds Globex above the 7,752.58 pivot and tests the 7,777.87 to 7,783.50 zone after the United States data. As analyst judgment, a settle beneath that zone is more likely than a settle above it on Friday. Three reasons. The cash index remains beneath its modeled volatility threshold, the directional system favours sellers and the weekend argues for squaring. That weighting has no measured frequency behind it. A settle above Pivot R1 at 7,797.92 is the alternative that invalidates it, because it would put the cash index back above 7,715 and near the iron condor's call strike.
The index absorbed what press commentary called a 19-year yield high for a cash loss of 1.90 points, and the line that decides Friday sits 10.87 points above that close.
The complete data picture
Every number behind Friday’s plan, charted first, then the full level lists, then the complete numeric reference underneath.
Full numeric reference, every remaining figure from the session review
1. Executive Summary
The December S&P 500 contract settled at 7,767.00 on Thursday, down 5.50 points or 0.07 percent from Wednesday's 7,772.50, the third consecutive lower settle and the lowest since 09/18/26, when the contract settled at 7,712.50. The completed session traded a 76.25 point band between 7,783.50 and 7,707.25 and settled at 78.4 percent of that range, 59.75 points above the low. The bar made a lower high and a lower low against Wednesday, but the settle position reverses Wednesday's 16.3 percent close. The S&P 500 cash index closed at 7,704.13, down 1.90 points or 0.02 percent, after a 7,662.57 to 7,719.01 range.
The session absorbed a hostile rate backdrop. The ten-year yield index reached 5.18 percent, which press commentary described as a 19-year high, before closing at 5.16 percent, and press commentary quoted two regional Federal Reserve presidents leaning toward further tightening. Crude rose 2.66 percent on Middle East supply risk. Press commentary attributed a recovery in stocks to short covering after a press report, carried on the news feed at 12:15 PM ET, that the United States and Iran were exploring a phased deal to reopen the Strait of Hormuz. The positioning note described a 7,000-lot iron condor in the cash index with strikes at 7,735/7,740 and 7,620/7,615 as providing positive dealer hedging exposure in that zone and driving mean-reverting price action. These items and the price path coincided; no time-stamped intraday price series was captured for this session, so no causal ordering is asserted.
The structural question into Friday is whether the index can recover its modeled volatility threshold. The cash close at 7,704.13 sits 10.87 points beneath the modeled volatility threshold at 7,715 and 43.13 points above the modeled gamma-flip level at 7,661, the same in-between zone as on Wednesday. The futures settle sits 14.42 points above the Pivot Point at 7,752.58, whose cash equivalent at the measured basis is within one point of the positioning note's own 7,690 pivot, and 16.45 points beneath the 5-day settlement average. The composite multi-indicator read is 56 percent buy, published with strength weak and direction weakest.
The primary setup is a short from a retracement into the 7,780 to 7,794 band around the futures equivalent of the modeled volatility threshold, the 5-day average and Thursday's high, stopped above one standard deviation resistance, with objectives at 7,755, 7,723 and an extended 7,691.
2.1 Intraday and Session Review
The completed Thursday session opened at 7,774.75, 2.25 points above Wednesday's 7,772.50 settle, marked a high of 7,783.50 and a low of 7,707.25, and settled at 7,767.00. No intraday series was captured for this session, so the order in which those extremes were reached is not asserted and no path claim appears anywhere in this review. What the daily bar establishes is geometry: the settle finished 7.75 points beneath the open, 16.50 points beneath the high and 59.75 points above the low, which places it at 78.4 percent of the 76.25 point range.
The session extremes used here are the completed-session inputs behind the published pivot ladder rather than an independently read bar, back-solved from the outer pivot pairs and verified against every rung. Pivot R3 at 7,874.17 minus Pivot S3 at 7,645.42, divided by three, returns 76.25, and Pivot R2 at 7,828.83 minus Pivot S2 at 7,676.33, divided by two, returns the same 76.25. Three times the unrounded Pivot Point of 7,752.583, published as 7,752.58, less the 7,767.00 settle gives a high plus low sum of 15,490.75, and the resulting pair of 7,783.50 and 7,707.25 reproduces all seven published rungs. The provider's own published daily record returns 7,774.75, 7,783.50, 7,707.25, 7,767.00 for the December contract. Both are surfaces of the same vendor, so they confirm internal consistency rather than authenticating the quote.
The provider's overview page, dated for the Friday session, showed a day open of 7,759.00, a day high of 7,763.75 and a day low of 7,756.50 at the time of reading. Those belong to the new Globex session that reopened at 6:00 PM ET and are not Thursday's range.
2.2 Daily Structure
Thursday's high at 7,783.50 sits 59.75 points beneath Wednesday's 7,843.25 high and its low at 7,707.25 sits 51.50 points beneath Wednesday's 7,758.75 low, so the bar is a lower high and lower low with a close in the top quarter of its range. The prior week, September 14 through September 18, spanned 7,739.25 at the high and 7,575.00 at the low; Thursday's low probed back inside that range while the settle held 27.75 points above that week's high.
For the quarterly reference the review uses the 13-week extremes as the available proxy, because no prior-quarter high or low was captured for this session. The 13-week and 52-week high stands at 7,905.00 and the 13-week low at 7,386.00. The settle sits 138.00 points beneath the 13-week high and 381.00 points above the 13-week low. The one-month high is 7,850.75, set on 08/28/26, and the one-month low 7,575.00, set on 09/16/26.
2.3 4-Hour and Swing Structure
The settlement sequence from the 09/16 low reads 7,623.00, 7,707.25, 7,712.50, 7,833.50, 7,831.75, 7,772.50 and then 7,767.00. The last three settles have each been lower, removing 66.50 points from Monday's 7,833.50. The swing from the 09/16 low of 7,575.00 to the 7,848.50 high of 09/22 spanned 273.50 points; Thursday's low at 7,707.25 retraced 141.25 points of it, or 51.6 percent, and the settle retraces 81.50 points, or 29.8 percent. The published 50 percent retracement of the four-week range sits at 7,712.88, 5.63 points above Thursday's low, so the low reached the midpoint of the four-week structure.
2.4 Moving Averages
The averages cited in this subsection were computed for this session from the provider's daily settlement series for the December contract, preserved in the coverage receipt: the 5-day average stands at 7,783.45, the 9-day at 7,732.92, the 20-day at 7,743.78 and the 50-day at 7,717.47. The December contract was the deferred month until mid-September, so the 50-day window includes thinly traded sessions; the figure is cited with that caveat. The captured history covers 60 completed sessions, so no 100-day or 200-day average is cited. Computed averages are carried at full precision and rounded once, half-up, at display, so the exact 20-day value of 7,743.775 shows as 7,743.78 and the exact 50-day value of 7,717.465 as 7,717.47; the distances quoted below are computed before rounding.
The 7,767.00 settle sits 16.45 points beneath the 5-day average and above every longer average: 34.08 points above the 9-day, 23.23 above the 20-day and 49.54 above the 50-day. The 5-day average sits 0.05 points beneath Thursday's high, so the high stopped at the shortest average. The projection grid gives the 9-day crossing at 7,737.94, the 18-day crossing at 7,735.82 and the 40-day crossing at 7,765.78.
2.5 Oscillator and Trend Readings
The oscillator figures below are as published on the provider's technical page for the Friday session. Relative strength reads 52.95 on the 9-day, 52.38 on the 14-day, 52.46 on the 20-day, 53.80 on the 50-day and 54.31 on the 100-day, all within a few points of the midline.
Stochastics remain in the upper half. The 9-day and 14-day raw stochastic each read 70.20 percent and the 20-day 69.63 percent, with the 14-day %K at 78.76 and %D at 82.15. The published grid places the 14-3 day raw stochastic 80 percent threshold at 7,793.80 and the 70 percent threshold at 7,766.45, so the settle sits just above the 70 percent line.
The directional system reads a weak trend with sellers slightly ahead. On the 9-day the directional index reads 20.11 with negative direction at 28.09 above positive direction at 19.43; on the 14-day 14.17 with negative at 26.09 over positive at 19.32; and on the 20-day 10.61 with negative at 24.66 over positive at 19.29. Historic volatility reads 11.59 percent on the 9-day, 10.82 percent on the 14-day and 10.60 percent on the 20-day.
The composite multi-indicator read published for Friday is 56 percent buy, with strength weak and direction weakest. The composite indicator itself reads hold. The short-horizon group averages 40 percent buy, where the 7-day directional reading is a sell, the medium-horizon group 75 percent buy and the long-horizon group 67 percent buy.
2.6 Volatility and Expected Range
The published 14-day average true range stands at 77.46 points and the 14-day average daily range at 77.59 points; the 9-day figures are 78.64 and 82.36, and the 20-day figures 77.88 and 76.14. Thursday's realised 76.25 point range was 0.98 times the 14-day average daily range, an ordinary session.
The positioning note's implied one-day move on the cash index is 0.66 percent, or 50.85 index points on Thursday's cash close, framing 7,653.28 to 7,754.98 in cash terms. The positioning note's own implied-move pair of 7,720.67 and 7,619.43 has a midpoint of 7,670.05, which matches neither the close nor the reference, so it is recorded and the percentage is applied to the close instead. The positioning note separately put at-the-money implied volatility for Friday at 13.7 percent, which it translated into an 86 basis point implied intraday move. Measured from the 7,767.00 settle, a one-range projection spans 7,689.54 to 7,844.46 in futures terms, using the 14-day average true range of 77.46 points. The published standard-deviation bands span 7,716.35 to 7,817.65 at one deviation.
3.1 Resistance
The basis measured this session is the 7,767.00 futures settle less the 7,704.13 cash close, 62.87 points. The first overhead zone runs from 7,777.87 to 7,783.50: the cash modeled volatility threshold of 7,715 converts to 7,777.87 at the measured basis, the positioning note's own futures pair quotes 7,779.5 with SPX 7,715 carrying that source's 64.5 offset, and the 5-day average at 7,783.45 and Thursday's high at 7,783.50 close it. A settle above that zone would put the cash index back above its threshold.
Above that, the stochastic 80 percent threshold at 7,793.80 and Pivot R1 at 7,797.92 form the next pair; Pivot R1's cash equivalent at the measured basis is 7,735.05, the call strike of the iron condor the positioning note described. The three-and-ten day crossover stall at 7,814.57, one standard deviation resistance at 7,817.65 and Pivot R2 at 7,828.83 follow, with the one-month high at 7,850.75 and the positioning note's 7,800 cash ceiling, 7,862.87 at the measured basis, as extended references.
3.2 Support
The stochastic 70 percent threshold at 7,766.45 and the 40-day crossing price at 7,765.78 sit just beneath the settle. The Pivot Point at 7,752.58 is the first genuine support, and its cash equivalent at the measured basis is 7,689.71, within one point of the positioning note's own 7,690 pivot, which makes 7,752 to 7,753 the most important line in the instrument. The 38.2 percent retracement from the four-week high at 7,745.41 and the 20-day settlement average at 7,743.78 follow.
Beneath it, the 9-day crossing at 7,737.94, the 18-day crossing at 7,735.82 and the 9-day settlement average at 7,732.92 sit within 5.02 points of each other. The positioning note's modeled gamma-flip pair quotes 7,725.5 with SPX 7,661, carrying the source's 64.5 offset, and Pivot S1 at 7,721.67 sits 3.83 points beneath it. The 50-day settlement average at 7,717.47, one standard deviation support at 7,716.35, the 50 percent four-week retracement at 7,712.88 and Thursday's low at 7,707.25 form the base of the week's range. Pivot S2 at 7,676.33 and Pivot S3 at 7,645.42 are the extended references.
4.1 Dollar, Rates, and Fed Policy
The ten-year yield index closed at 5.16 percent, up 5 basis points, after a 5.09 to 5.18 range, and the thirty-year at 5.46 percent. The dollar index closed at 101.29, up 0.19 percent. The seven-year note auction stopped at a 5.085 percent high yield with a 2.420 bid-to-cover against 2.500 previously, per the news-feed calendar and unconfirmed. Weekly jobless claims printed 197,000 against a 200,000 consensus, and new home sales printed 0.684 million against 0.6155 million, both per the news-feed calendar and unconfirmed; press commentary described claims at a two-month low and sales at an eight-month high. Press commentary quoted the New York Federal Reserve president as saying the central bank has a lot of work to do to contain inflation and the Philadelphia Federal Reserve president as saying some modest further tightening may be warranted, and the positioning note cited fed funds futures pricing a roughly 71 percent likelihood of an October increase, against roughly 55 percent a week earlier.
4.2 Large-Cap Leadership and Earnings
The positioning note recorded single-stock hedging delta of plus 2 billion dollars on the day, driven by longer-dated call buying concentrated in a megacap platform company that rose about 5 percent after its product launch. After the close, a large warehouse retailer reported fiscal fourth-quarter earnings of 6.75 dollars a share against a 6.53 estimate and revenue of 95.72 billion dollars against 94.92 billion, per a news-feed item stamped 4:18 PM ET, which the verified forward calendar lists as an after-close release on September 24, 2026.
4.3 Geopolitical Backdrop
The Middle East carried both escalation and de-escalation reporting. The press report of a phased United States-Iran deal on the Strait of Hormuz was carried on the news feed at 12:15 PM ET, the Senate rejected a resolution curbing the administration's Iran war powers at 2:38 PM ET, and the news feed carried claims by Yemen's Houthis of attacks at Yanbu and in Riyadh at 3:02 PM and 3:03 PM ET. After the close the Chinese president described a new joint trade arrangement with the United States as good news, per news-feed items stamped 4:16 PM and 4:24 PM ET.
4.4 Sector Breadth and Rotation
Press commentary described the Dow Jones Industrial Average closing down 0.31 percent at a one-week low while the Nasdaq-100 closed up 0.03 percent, so megacap technology outperformed the industrial and cyclical names. No sector-level breadth series was captured for this session, so no advance-decline figure is asserted.
4.5 Cross-Asset and Volatility
The volatility index closed at 15.67, up 0.49 points, and the positioning note recorded the volatility-of-volatility index at 90.57, up 2 points, with fixed-strike volatility up 1 to 2 points as the market pulled back from record highs. Crude settled at 94.61, up 2.66 percent, and Brent at 106.60, up 3.41 percent. Gold settled at 4,298.0, down 0.47 percent.
4.6 Institutional Positioning
The positioning report as of September 15, 2026 remains the latest captured. Leveraged funds held 161,176 long against 454,319 short, a net short of 293,143, after covering 42,302 shorts on the week. Asset managers held 1,142,075 long against 237,391 short, a net long of 904,684, and dealers held 220,012 long against 922,950 short. Open interest on the December contract stood at 1,894,151 on the latest published row for 09/23, against 1,884,650 on 09/22. The leveraged-fund book remains heavily net short, which keeps a squeeze available on good news; that is interpretation, not a measured flow.
5. Index Options Flow Context
This is the primary flow surface for this instrument rather than a proxy, and every level quoted from it is a cash index value unless a futures pair is stated explicitly.
The reference price column requires care and was checked explicitly. That column is the prior session's close, not Thursday's: the cash index reference of 7,706 matches Wednesday's 7,706.03 close, the technology index reference of 30,470 matches Wednesday's 30,470.29, and the broad fund's reference of 767 matches the provider's 767.81 close for Wednesday. Thursday's cash close of 7,704.13 is a 0.02 percent decline from that reference.
The dealer-positioning stack reads a modeled volatility threshold at 7,715, a primary gamma concentration at 8,000, a call-side ceiling at 7,800 and a put-side base at 7,500, with a modeled gamma-flip level at 7,661. The gamma index reads 1.391, gamma tilt 1.109 and gamma notional 404.361 million dollars. The 25-delta risk reversal sits at minus 0.037. Call volume was 789,357 contracts against put volume of 1.031 million, and call open interest 9.059 million against put open interest 12.911 million. The mapped key cash levels are 8,000, 7,700, 7,000 and 7,800, and the positioning note's own summary lists resistance at 7,700 and 7,800, a pivot at 7,690 and support at 7,600. The positioning note stated that the index had broken back below its 7,690 pivot during the session and that its stance was risk-off until the index crossed back above; the cash close at 7,704.13 sits 14.13 points above that pivot.
The cash close sits 10.87 points beneath the modeled volatility threshold at 7,715 and 43.13 points above the modeled gamma-flip level at 7,661. That places the index between the two model boundaries for a second session, a zone in which dealer hedging dampens movement less than it does above the threshold; this is the model's interpretation of the configuration rather than a measured cause of Friday's behaviour. The positioning note attributed Thursday's mean-reverting character to a 7,000-lot iron condor at 7,735/7,740 and 7,620/7,615.
The futures column requires the same care as on prior sessions. The table's December futures column reads a reference of 7,770.5, a modeled volatility threshold of 7,779.5, a primary gamma concentration of 8,064.5, a call-side ceiling of 7,864.5, a put-side base of 7,564.5 and a modeled gamma-flip level of 7,725.5. Every one of those is the corresponding cash value plus exactly 64.5, so the column is a fixed-offset translation rather than an independent futures quote, and its reference of 7,770.5 is Wednesday's cash reference translated, not Wednesday's futures settle of 7,772.50. The basis measured this session is 62.87, and where a level in section 3 is quoted as a futures-and-cash pair from this source it carries the source's 64.5 offset and is labelled as such.
On flow, the positioning note recorded index hedging delta of minus 12 billion dollars on the day, mostly in same-day expiries, after minus 20 billion on Wednesday, and read it as tactical rather than longer-dated hedging demand. These are the positioning note's characterisations; no timestamp-aligned flow series was captured for this session.
The mapped confluence levels with their conviction scores give the finest-grained map available for Friday. Around the close: 7,698 at 94.96, 7,714 at 67.14 and 7,721 at 88.27. Above: 7,752 at 97.51, 7,768 at 95.17, 7,775 at 94.68, 7,783 at 96.17 and 7,799 at 99.62. Beneath: 7,675 at 95.00, 7,652 at 98.86, 7,621 at 96.01 and 7,598 at 99.10. These are cash values and conviction scores rather than calibrated frequencies, and they are treated as such.
An equity positioning dashboard row for this index, updated on Thursday, showed a previous close of 7,706.03, which agrees with the published cash series, call gamma of 4.1 billion dollars, put gamma of minus 1.4 billion dollars and next-expiry gamma at 8.47 percent. Its current-price field of 7,696.60 comes from a delayed strip and is unused, its 52-week low field reads zero and is unused, and its high-volatility-point and low-volatility-point fields, 8,000 and 9,040, are excluded as low-confidence.
6.1 Night Session (6:00 PM ET Thursday to 3:00 AM ET Friday, Globex and Asia)
The Globex reopen carries the after-close items: the warehouse retailer's results at 4:18 PM ET and the Chinese president's trade remarks from 4:16 PM ET. The reopened session was trading between 7,756.50 and 7,763.75 at the time of reading, above the 7,752.58 pivot. The captured news-feed calendar carries no Asian release for the Thursday evening window. Bias neutral above 7,752.58, expected Globex band roughly 7,740 to 7,785.
6.2 London Session (3:00 AM to 8:00 AM ET Friday)
The European morning carries euro-area money-supply data at 4:00 AM ET and remarks by the New York Federal Reserve president at 5:15 AM ET, both per the news-feed calendar and unconfirmed. European yields are the main transmission. Bias neutral, expected band roughly 7,735 to 7,790.
6.3 Morning Session (9:30 AM to 12:00 PM ET Friday, regular trading hours open)
The United States morning opens with the advance durable goods report at 8:30 AM ET, per the verified forward calendar, with headline orders forecast at minus 0.3 percent and core at plus 0.6 percent, per the news-feed calendar and unconfirmed. The final University of Michigan survey prints at 10:00 AM ET, per the news-feed calendar and unconfirmed. The cash open at 9:30 AM ET sets the first directional test against the 7,777.87 to 7,783.50 zone above and the 7,752.58 pivot beneath. A cash recovery above the 7,715 modeled volatility threshold would change the character of the session; a futures settle beneath 7,752.58 would put the 7,707.25 low back in play. Expected band roughly 7,720 to 7,800.
6.4 Afternoon Session (12:00 PM to 4:00 PM ET Friday)
The afternoon carries the Cleveland Federal Reserve president at 2:00 PM ET, per the news-feed calendar and unconfirmed. The cash close precedes a weekend with an open Middle East negotiation. Expected band roughly 7,725 to 7,795.
6.5 Night Session Forward (6:00 PM ET Friday)
Globex does not reopen on Friday evening; the next session opens at 6:00 PM ET on Sunday, so two days of headline exposure separate Friday's close from the reopen. Gap levels both ways: a constructive weekend points to Pivot R1 at 7,797.92 and Pivot R2 at 7,828.83, and a risk-off weekend points to the 7,707.25 low and Pivot S2 at 7,676.33. The following week carries the personal income and outlays report at 8:30 AM ET on September 30, 2026, per the verified forward calendar. The employment report follows at 8:30 AM ET on October 2, 2026, per the verified forward calendar.
6.6 Expected Range (Friday Full Session)
Low-range scenario: 7,735 to 7,790
Mid-range scenario (most likely): 7,715 to 7,800
High-range scenario: 7,690 to 7,830
6.7 Most Likely Path
The most probable path holds the Globex session above the 7,752.58 pivot, followed by a test of the 7,777.87 to 7,783.50 zone after the United States data. In this review's analyst judgment a settle beneath that zone is more likely than a settle above it on Friday, because the cash index remains beneath its modeled volatility threshold, the directional system favours sellers and the weekend argues for squaring. The alternative that would invalidate this reading is a settle above Pivot R1 at 7,797.92, which would put the cash index back above 7,715 and near the iron condor's call strike.
7. Friday Economic Calendar
The captured news-feed calendar carries no Asian release for the Thursday evening window. The European morning carries euro-area money-supply growth at 4:00 AM ET, forecast 3.5 percent against a prior 3.4 percent, per the news-feed calendar and unconfirmed, and remarks by the New York Federal Reserve president at 5:15 AM ET, per the news-feed calendar and unconfirmed.
The United States morning carries the advance durable goods report at 8:30 AM ET, per the verified forward calendar, with headline orders forecast at minus 0.3 percent against a prior 1.1 percent and core orders forecast at plus 0.6 percent against a prior 0.4 percent, per the news-feed calendar and unconfirmed. The final University of Michigan survey prints at 10:00 AM ET, with sentiment forecast at 47.5 against 47.8 and five-year inflation expectations forecast at 3.4 percent, per the news-feed calendar and unconfirmed. In the afternoon a European Central Bank speaker and the Cleveland Federal Reserve president both appear at 2:00 PM ET, per the news-feed calendar and unconfirmed.
The single first-order event for the contract on Friday is the durable goods report at 8:30 AM ET on September 25, 2026, per the verified forward calendar, read through its effect on the ten-year yield. No structural index expiry falls on Friday; the provider lists the December contract's expiration as 12/18/26. The positioning note's key dates list the quarter end and the personal consumption expenditures report on September 30 and the employment report on October 2 as the next first-order grouping.
8. Primary Trade Setup
Direction: Short
Rationale: The contract has made three consecutive lower settles, sits beneath its 5-day settlement average with Thursday's high stopping at it, shows sellers ahead on every directional horizon, and the cash index closed beneath its modeled volatility threshold for a second session against a 5.16 percent ten-year yield; a retracement into the futures equivalent of that threshold offers a short with a defined risk point above one standard deviation resistance.
Entry Zone: 7,780 to 7,794
Stop Loss: 7,819 (above one standard deviation resistance at 7,817.65 and the three-and-ten day crossover stall at 7,814.57)
Target 1 (T1): 7,755 (ahead of the Pivot Point at 7,752.58)
Target 2 (T2): 7,723 (above Pivot S1 at 7,721.67, beside the positioning note's modeled gamma-flip pair at 7,725.5)
Target 3 (T3, extended): 7,691 (beneath Thursday's 7,707.25 low and above Pivot S2 at 7,676.33)
Risk-to-Reward: Approximately 1:1 to T1, 1:2 to T2, 1:3 to T3
Invalidation: A settle above Pivot R1 at 7,797.92 with the cash index back above 7,715 negates the thesis. Short of that, two consecutive 30-minute closes above 7,794 remove the edge before the stop is reached. Thursday's close in the top quarter of its range argues that sellers do not own the session, so T1 is the realistic objective unless the pivot fails.
Macro override: A soft durable goods print or a dovish Federal Reserve speaker that pulls the ten-year yield back toward 5.10 percent, or a weekend Strait agreement that pulls crude lower, invalidates the setup in real time.
Sources and methodology
This outlook is built from our session review of the December E-mini S&P 500 contract, the December ’26 contract, prepared after Thursday's close on September 24, 2026 for the Friday, September 25, 2026 session. Thursday's completed extremes are recovered from the published pivot ladder: Pivot R3 at 7,874.17 less Pivot S3 at 7,645.42, divided by three, and Pivot R2 at 7,828.83 less Pivot S2 at 7,676.33, divided by two, both return 76.25, and three times the unrounded 7,752.583 pivot less the settle gives a high-plus-low sum of 15,490.75, which yields 7,783.50 and 7,707.25 and reproduces all seven published rungs. The provider's daily record agrees at 7,774.75, 7,783.50, 7,707.25 and 7,767.00, on preliminary volume of 1,687,322 contracts; it is a second surface of the same vendor, so it confirms internal consistency and not the underlying quote. Open interest is quoted from the dated rows, 1,894,151 for 09/23 and 1,884,650 for 09/22; the 09/24 row carries none yet.
The contract domain was checked before any level was used: the daily chart read 7,758.00 with a stated change of minus 9.00, which returns the provider's 7,767.00 previous close, and the chart's new-session open of 7,759.00 and high of 7,763.75 equal the provider's day open and day high. Those Friday prints, with the 7,756.50 low, are never presented as Thursday's range. The moving averages were computed from the provider's daily settlement series and rounded once, half-up, at display; the oscillators are cited as published for the Friday session. Cash index levels from the positioning note are quoted as published. Its reference column is the prior session's close: the cash reference of 7,706 matches Wednesday's 7,706.03 close, the technology index reference of 30,470 matches 30,470.29, and the broad fund's reference of 767 matches its 767.81 close. Its futures column is a fixed 64.5 translation, and its 7,770.5 reference is Wednesday's cash reference translated, not Wednesday's 7,772.50 futures settle, so any conversion made here uses the 62.87 basis measured this session. The note's implied-move pair of 7,720.67 and 7,619.43 has a midpoint of 7,670.05, which matches neither the close nor the reference, so the 0.66 percent is applied to the close instead. The note put the ten-year yield at 5.22 percent, while the yield index series and press commentary put the high at 5.18 percent; the index series is used. An equity positioning dashboard row for the index, updated Thursday, showed a previous close of 7,706.03, call gamma of 4.1 billion dollars, put gamma of minus 1.4 billion dollars and next-expiry gamma at 8.47 percent; its current-price field of 7,696.60 comes from a delayed strip and is unused, its 52-week low field reads zero and is unused, and its high-volatility-point and low-volatility-point fields, 8,000 and 9,040, are excluded as low-confidence. Conviction scores are scores, not calibrated frequencies. Scenario ranges are analyst judgment. Items marked unconfirmed come from the news-feed calendar or record. No timestamp-aligned price and flow series was captured for this session, and no order of events is asserted.
Thursday’s outlook for this contract is here, and the Nasdaq-100 contract's Thursday outlook covers the index that closed up 0.03 percent on the same session. Outlooks for ES, NQ, GC and CL are collected on the market outlook page, and our forward trading record is on the performance statement.