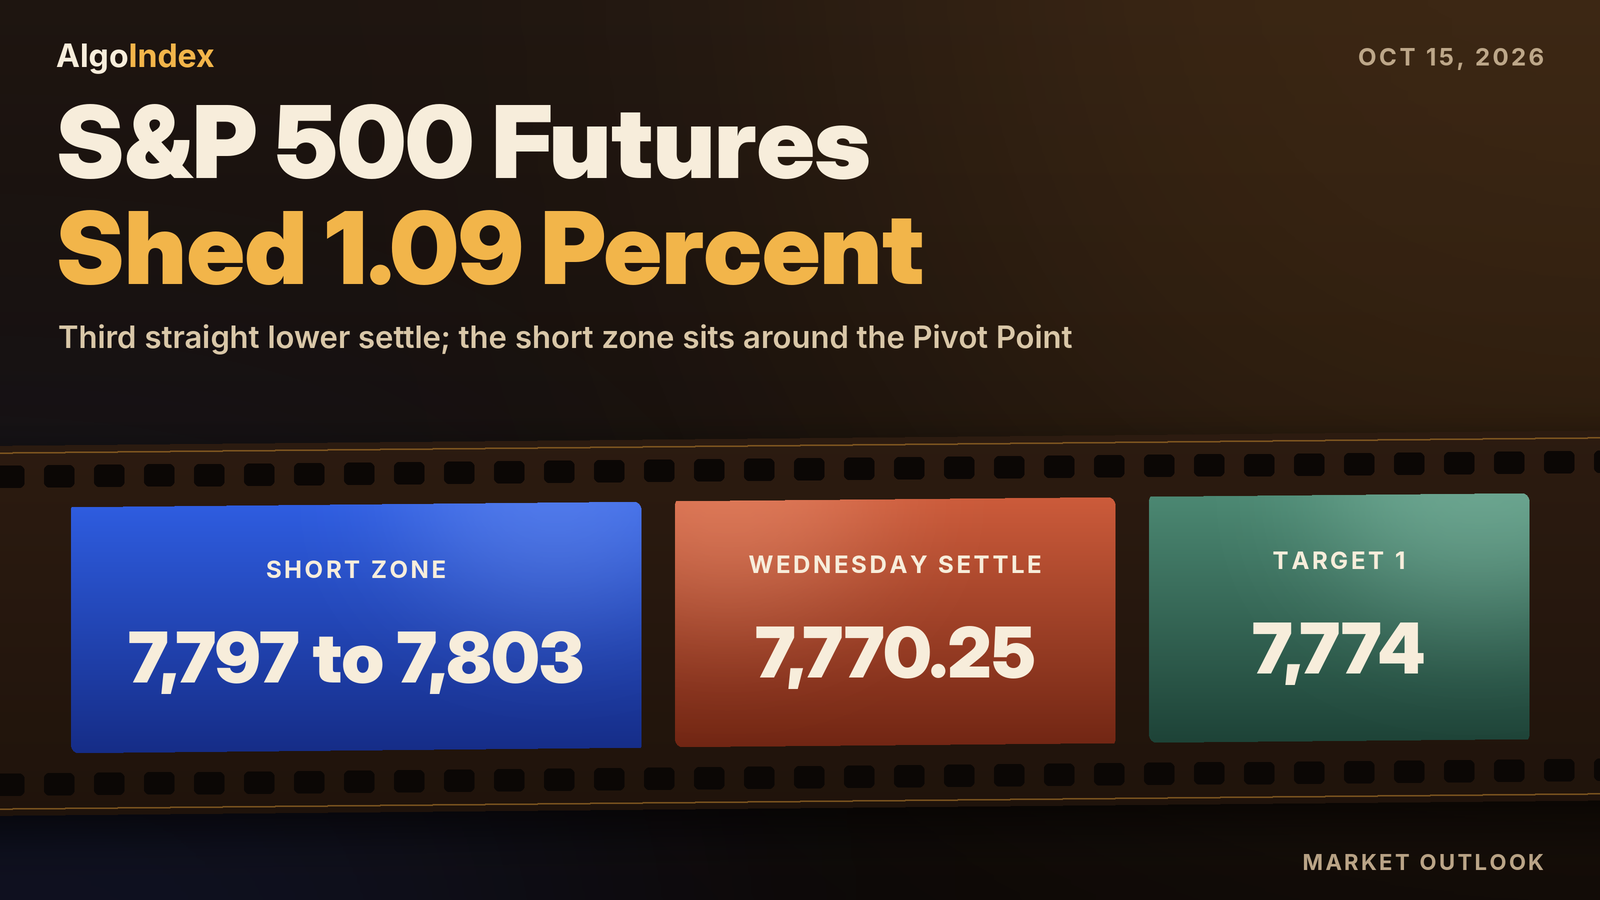
At 6:26 PM ET on Wednesday the December S&P 500 contract was quoted at 7,763.25, 7.00 points beneath the settle. Globex had reopened at 6:00 PM ET, and the new session had so far traded between 7,759.25 and 7,769.50. Thursday's short zone, 7,797 to 7,803, sits 33.75 points above that quote. The band sits above the market.
The quiet broke on Wednesday. December E-mini futures settled at 7,770.25, down 85.50 points or 1.09 percent, after a 7,741.00 to 7,879.75 session. The 138.75 point range was the widest since the 157.25 point range of 08/04. The decline was the largest since the 116.75 point decline of 07/29. Higher high, lower low. It was an outside day and the third consecutive lower settle. At 7,770.25 the settle was the lowest since the 7,724.00 settle of 10/01, and it finished at 21.1 percent of the range. The cash index closed at 7,718.94, down 1.11 percent, while the Nasdaq-100 cash index fell 2.02 percent and the semiconductor index 4.30 percent.
December S&P 500 futures settled at 7,770.25. That sits 26.75 points beneath the 7,797.00 Pivot Point and beneath the 5-day, 9-day, 20-day and 50-day settlement averages, while the 100-day at 7,691.41 and the 200-day at 7,390.77 sit beneath it. The primary setup is a short from 7,797 to 7,803 around the Pivot Point at 7,797.00 and the 18-day average crossing price at 7,799.03, stop 7,826 above 7,823.4, the desk note's futures pair for the modeled volatility threshold, targets 7,774, 7,748 and an extended 7,722. The band sits above the market. The settle sat 26.75 points beneath the band bottom and the 6:26 PM ET quote 33.75 beneath it, so the setup needs a rally to engage. The cash close sits 56.06 points beneath the 7,775 modeled volatility threshold (ES pair 7,823.4) and 17.94 above the 7,701 modeled gamma-flip level (ES pair 7,749.4), with gamma tilt at 1.326. Dealer gamma stays positive in aggregate. Producer prices and retail sales for September print at 8:30 AM ET on Thursday, as the calendar lists them, and in the review's judgment the producer price index is the first-order influence on the session.
Wednesday's 7,741.00 low ran 80.00 points through the long card's stop
In Wednesday’s outlook we set a long from 7,836 to 7,842. Its stop sat at 7,821, with targets at 7,857, 7,875 and an extended 7,893. Wednesday's completed bar, from the review and the dated 2026-10-14 row, opened at 7,856.25 at the Tuesday 6:00 PM ET reopen, marked a high of 7,879.75 and a low of 7,741.00, and settled at 7,770.25. The stop traded. The low went 95.00 points beneath the band's 7,836 bottom and 80.00 beneath the 7,821 stop. No fill and no result is asserted.
This time the 30-minute bars fix the order. From the reopen through the 8:00 AM ET bar the contract never traded beneath 7,848.75, 6.75 points above the band top. The first target printed in the first bar after the reopen, whose high reached 7,858.75. The second target came in the 8:00 AM ET bar, which reached 7,879.50 and closed at 7,878.50. Both printed before the band traded. Those prints carry no result. The 7,893 extended target never printed; the session high stopped 13.25 points short.
The inflation release came inside the 8:30 AM ET bar. Per the review, that bar set the session high of 7,879.75 before trading down to 7,822.25, and it closed at 7,824.75. The whole band traded inside it, with the low 13.75 points beneath the 7,836 bottom and 1.25 above the stop. The 9:00 AM ET bar came within 0.25 of 7,821 at 7,821.25. The 9:30 AM ET bar went through. It traded as low as 7,806.50, 14.50 points beneath the stop, and closed at 7,808.00. That bar also reached 7,837.75, inside the band, and the bars cannot show which came first within it. After the 8:30 AM ET bar the contract never returned to 7,857. Its best later high was that 7,837.75, 19.25 points short.
The card's other lines gave way too. The invalidation was a settle beneath Pivot S2 at 7,821.92, and the 7,770.25 settle finished 51.67 points beneath it. Acceptance beneath 7,823.25, the desk note's pair for the modeled volatility threshold, needed two consecutive 30-minute closes beneath that line. The 8:30 AM ET and 9:00 AM ET bars closed 1.50 and 0.75 points above it. The 9:30 AM ET bar closed at 7,808.00 and the 10:00 AM ET bar at 7,803.50, so the condition was met at that second close. The low finished 97.83 points beneath the 7,838.83 Pivot S1 the card was built around.
Our ranges missed the low. The most likely band of 7,810 to 7,898 held the high, 18.25 points under its top, and lost the low by 69.00. The low-range case of 7,830 to 7,881 held the high by 1.25 and missed the low by 89.00. Even the high-range case of 7,786 to 7,926 missed the low by 45.00. Overnight the Globex band of 7,836 to 7,868 held the low, 7,848.75, 12.75 points above its bottom. The overnight high of 7,874.25 ran 6.25 above its top.
The weighted path missed as well. Wednesday's outlook expected a hold between Pivot S3 at 7,809.33 and Pivot R3 at 7,897.83. The high stopped 18.08 points under R3, and the low went 68.33 beneath S3. The named alternative was a hot inflation print that lifts yields and carries the contract through Pivot S2 at 7,821.92 toward the 7,751.25 pair of the modeled gamma-flip level. The print came in above forecast on the annual and core monthly measures, per the news-feed calendar. The ten-year yield index traded as high as 5.33 percent but closed at 5.19 percent, down from 5.21 percent. The price leg ran its full length. The 9:00 AM ET bar first traded beneath Pivot S2, and the 1:30 PM ET bar first traded beneath 7,751.25. The 7,741.00 low, set in the 2:00 PM ET bar, went 10.25 points past it, and the settle finished 19.00 above it. We grade the card as written.
The Pivot Point at 7,797.00, the 7,797 to 7,803 band and the 7,823.4 line
The basis widened. Wednesday's 7,770.25 settle less the 7,718.94 cash close measures 51.31 points, against 50.30 on Tuesday, and every cash equivalent in this article uses the new figure. The desk note keeps its own fixed 48.4 point offset, so its published futures pairs differ: 8,048.4 for the 8,000 gamma concentration, 7,948.4 for the 7,900 call-side ceiling, 7,823.4 for the 7,775 modeled volatility threshold, 7,749.4 for the 7,701 modeled gamma-flip level and 7,548.4 for the 7,500 put-side base.
Resistance starts within 5 points. The 38.2 percent retracement from the four-week high at 7,774.30 (cash 7,722.99) sits 4.05 points above the settle. The 50-day settlement average at 7,779.24 and the 7,785.52 projection for the 14-day relative strength midpoint sit above it. Then the band's group. The 20-day average at 7,791.84 and the 40-day stall level at 7,795.00 (cash 7,743.69) sit just under 7,797. The Pivot Point at 7,797.00 (cash 7,745.69) marks the band bottom, and the 18-day average crossing price at 7,799.03 sits 3.97 points beneath the band top. One standard deviation resistance at 7,809.21 (cash 7,757.90) follows, 6.21 above the band.
The stop's group sits next. The 7,823.4 threshold pair (cash 7,775) and two standard deviations resistance at 7,825.35 (cash 7,774.04) lie 1.95 points apart. The 7,826 stop sits 2.60 above the first and 0.65 above the second. The 5-day average at 7,832.00 and the 9-day at 7,832.25 come next, with Tuesday's 7,834.50 low just above them. Three standard deviations resistance at 7,837.73 (cash 7,786.42) and the 9-day average crossing price at 7,839.13 follow. Pivot R1 at 7,853.00 (cash 7,801.69) sits 2.75 points beneath Tuesday's 7,855.75 settle (cash 7,804.44). Wednesday's 7,856.25 open, Tuesday's 7,864.00 high (cash 7,812.69) and Wednesday's 7,879.75 high (cash 7,828.44) sit above it. The 52-week and 13-week high of 7,905.00 from 08/13 sits 134.75 points above the settle. Pivot R2 at 7,935.75 (cash 7,884.44), the 7,948.4 ceiling pair (cash 7,900), Pivot R3 at 7,991.75 and the 8,048.4 concentration pair (cash 8,000) are the extended references.
Support starts close too. The 40-day average crossing price at 7,764.72 sits 5.53 points beneath the settle, and last week's 7,760.25 low sits under it. The published target price at 7,752.89 (cash 7,701.58), the 7,749.4 flip pair (cash 7,701) and the 3-10 day crossover stall level at 7,746.25 (cash 7,694.94) follow. Wednesday's 7,741.00 low (cash 7,689.69) sits 5.25 under the stall level. The 50 percent retracement of the four-week range at 7,736.25 and one standard deviation support at 7,731.29 (cash 7,679.98) come next. A tight pair follows. Two standard deviations support at 7,715.15 (cash 7,663.84) and Pivot S1 at 7,714.25 (cash 7,662.94) lie 0.90 points apart. The 38.2 percent retracement from the 13-week high at 7,706.74, three standard deviations support at 7,702.77 (cash 7,651.46) and the 38.2 percent retracement from the four-week low at 7,698.19 span 8.55 points. The deep references come last. The 100-day average at 7,691.41 and Pivot S2 at 7,658.25 lead them. Pivot S3 at 7,575.50, the 7,575.00 one-month low, the 7,548.4 put-side pair (cash 7,500), the 200-day average at 7,390.77 and the 13-week low of 7,386.00 complete the list.
Four averages sit above the settle. The 5-day stands 61.75 points over it, the 9-day 62.00, the 20-day 21.59 and the 50-day 8.99. The 100-day sits 78.84 beneath and the 200-day 379.48. The 5-day fell 16.50 points from Tuesday's 7,848.50 as the 10/07 settle of 7,852.75 left the window and 7,770.25 replaced it. The 20-day rose 7.36 from 7,784.48, because the 09/16 settle of 7,623.00 left that window. The 50-day fell 1.29 from 7,780.53 as the 08/04 settle of 7,834.75 dropped out. The 20-day still sits above the 50-day. The 30 older settlements in the 50-day window averaged 7,770.84, less than the latest 20. For Thursday the averages would be crossed at 7,839.13 for the 9-day, 7,799.03 for the 18-day and 7,764.72 for the 40-day.
Momentum cooled. Relative strength reads 44.62 on the 9-day, 48.41 on the 14-day and 50.13 on the 20-day. The raw stochastic reads 26.97 percent on the 9-day and 43.38 percent on the 14-day. The smoothed 14-day %K at 69.08 percent sits beneath %D at 75.97 percent, still in the upper half of the range. Negative direction leads on both windows. On the 9-day it reads 28.46 against 17.31 with the ADX at 15.05; on the 14-day, 25.83 against 18.47 with the ADX at 10.68. Both ADX readings stay low. Historic volatility reads 9.14 percent on the 9-day and 8.37 percent on the 14-day. These readings come from the provider's page for the Thursday session, read after the 6:00 PM ET reopen. That page can substitute the live Globex price for the settle.
The composite multi-indicator read fell to 16 percent buy from 96 percent buy, with strength described as minimum and direction as weakening. It read 80 percent buy a week ago and 16 percent sell a month ago. The short-horizon group averages 40 percent sell. The medium-horizon group reads 25 percent buy and the long-horizon group 67 percent buy, and the composite trend indicator still reads buy.
Ranges blew out. The 14-day average true range stands at 74.74 points, 0.96 percent of the settle, and the 14-day average daily range at 73.04. The 9-day figures are 74.39 and 72.14 and the 20-day figures 75.51 and 76.19. Wednesday's 138.75 point range was 1.90 times the 14-day average daily range. One average true range either side of the settle frames Thursday between 7,695.51 and 7,844.99. The deviation bands are tighter. They run 7,731.29 to 7,809.21 at one deviation, 7,715.15 to 7,825.35 at two and 7,702.77 to 7,837.73 at three. Built from five settlements, they describe settlement dispersion only. The desk note's implied one-day move of 0.50 percent equals about 38.59 points on the 7,718.94 cash close.
Zoom out. Daily ranges over the last eight sessions ran 87.25, 68.50, 68.75, 75.25, 53.50, 40.75, 29.50 and 138.75 points. Settlement changes over the same stretch read plus 49.00, plus 47.75, minus 21.25, minus 36.50, plus 43.50, minus 1.75, minus 2.25 and minus 85.50. Wednesday stands apart. The 7,879.75 high sits 15.75 points above Tuesday's 7,864.00, and the 7,741.00 low 93.50 beneath Tuesday's 7,834.50. The bar left an upper shadow of 23.50 points above the 7,856.25 open and a lower shadow of 29.25 points beneath the settle. Now the week. Last week, October 5 through October 9, spanned 7,897.50 to 7,760.25, and Wednesday's low went 19.25 points beneath it. Over five sessions the contract fell 82.50 points from the 7,852.75 settle of 10/07. The one-month low of 7,575.00 sits 195.25 points beneath the settle. No four-hour series and no prior-quarter extremes were captured. Swing structure rests on daily bars and the 30-minute session, with the 13-week high of 7,905.00 and low of 7,386.00 as the quarterly reference.
A hotter inflation report, chip losses and Gulf headlines
The September consumer price index printed at 8:30 AM ET, as the calendar listed it. The news-feed calendar showed 3.7 percent for the year against a 3.6 percent forecast, and 0.3 percent for the core month against 0.2 percent. The release fell inside the 8:30 AM ET bar, which set the session high of 7,879.75 and then traded down to 7,822.25. The bars record the timing. They record no cause.
Rate bets moved. The news feed carried at 8:31 AM ET to 8:34 AM ET that rate futures fell as traders added to bets on an October increase. At 9:05 AM ET the news feed carried that traders fully price two increases by the end of January. Per the news feed, investment-bank commentary at 9:40 AM ET added a December increase to its forecast. The desk note said the probability it assigns to an October Federal Reserve increase rose to 33 percent from 22 percent. Yields swung. The ten-year yield index traded between 5.18 and 5.33 percent and closed at 5.19 percent against 5.21 percent. The 13-week bill yield index rose to 4.09 percent from 4.05 percent, and the dollar index closed at 102.55, up 0.37.
The central bank's regional survey of economic conditions followed at 2:00 PM ET, as the calendar listed it. The survey said two of the twelve districts reported moderate growth and three noted intensifying input price pressures. At 2:36 PM ET, per the news feed, a regional Federal Reserve president called the inflation report higher than hoped. Per the news feed, another called it discouraging at 3:09 PM ET to 3:20 PM ET.
Chips led the losses. The desk note said the semiconductor fund fell 5 percent for a seventh consecutive decline, erasing roughly 1 trillion dollars of market value. In the provider's daily record the semiconductor index fell 4.30 percent and the Nasdaq-100 cash index 2.02 percent. The S&P 500 cash index fell 1.11 percent, the NYSE composite 0.50 percent and the Dow Jones Industrial Average 0.09 percent. The technology-heavy indices led the decline. The desk note said healthcare rose 3 percent and consumer staples 2 percent as capital rotated into defensive sectors. A market wrap carried by the news feed said renewed losses in semiconductor shares and the stronger inflation report lifted rate-increase expectations. That link is the wrap's reading.
Company headlines ran all day. A large investment bank reported at about 7:30 AM ET, as the calendar listed it. At 10:16 AM ET the news feed carried that bank's chief executive saying the firm remains overweight the artificial intelligence opportunity set. At 12:40 PM ET the news feed carried a 21 billion dollar semiconductor plant arrangement announced by the President. Per the news feed, the leading graphics-chip maker's chief executive spoke on artificial intelligence safety at 1:34 PM ET to 1:35 PM ET. At 1:25 PM ET and 1:50 PM ET, per the news feed, a cloud provider's chief executive said its backlog supports its debt and its share drop was irrational. The Taiwanese chipmaker reports at 2:00 AM ET on Thursday, as the calendar lists it.
Gulf headlines ran through the session. At 9:33 AM ET the news feed carried an Iranian state media report of an explosion in Riyadh with reported damage to oil facilities. At 1:38 PM ET the news feed carried a Houthi statement of a ballistic missile attack on Riyadh's main airport. Two more followed. Per the news feed, reports of an attack on and an explosion in Jeddah came at 3:03 PM ET and 3:24 PM ET. At 2:52 PM ET, per the news feed, Iran's parliament speaker said a US deal cannot prevent another attack on Iran. These are statements carried by the news feed rather than events confirmed for this review. No link between them and any price move is asserted. November WTI crude settled at 95.09, up 1.01 percent.
Implied volatility rose. The volatility index closed at 16.87, up 1.60 from 15.27, after trading as high as 17.45. The volatility-of-volatility index closed at 94.45, up 9.07. The desk note said the morning's same-day at-the-money straddle priced a 43 basis point move against a realised move more than four times larger. Per the desk note, fixed-strike implied volatility rose about one point for this week's expiration while longer-dated implied volatility was little changed. December gold settled at 4,107.9, down 1.66 percent.
The cash close sits beneath the threshold. The desk note used is the 5:20 PM ET Wednesday edition, and its reference column carries Tuesday's closes. Its 7,805 reference equals Tuesday's 7,805.45 cash close, and 7,805.45 less 1.11 percent gives 7,718.81. The note's narrative states a close of 7,719, 0.06 above the provider's 7,718.94, and this article uses the provider's figure. Against that close, the index sits 56.06 points beneath the 7,775 modeled volatility threshold (ES pair 7,823.4) and 17.94 above the 7,701 modeled gamma-flip level (ES pair 7,749.4). It sits 181.06 beneath the 7,900 call-side ceiling (ES pair 7,948.4). Gamma tilt reads 1.326 and gamma notional plus 996.435 million dollars, so dealer gamma remains positive in aggregate. The modeled threshold and flip level are model outputs; neither is an option strike.
The note draws its own map. It lists resistance at 7,820, 7,870 and 7,900, support at 7,800, 7,750 and 7,700, a desk pivot at 7,690 and key strikes at 8,000, 7,800, 7,000 and 7,700, all in cash. The desk note said the S&P 500 fell 175 basis points after the 8:30 AM ET inflation print. Per the desk note, index options flow showed about minus 1 billion dollars of cumulative delta led by longer-dated put buying as traders added hedges ahead of producer prices. Per the desk note, single-stock options flow showed about minus 5 billion dollars, including about 4 billion dollars of longer-dated call selling. The desk note's summary said a move above 7,825 could extend quickly because gamma above that level is negative. Per the desk note, support is solid down to 7,700, and beneath 7,700 the note shifts to a risk-off stance. The 7,718.94 close sits 18.94 points above 7,700 and 106.06 beneath 7,825, both in cash.
The note's implied one-day move is 0.50 percent, about 38.59 points on the 7,718.94 close, and its implied five-day move 1.22 percent. That is about 94.17 points. Its published implied one-day high and low are not symmetric around either the reference or the close, so that pair is excluded. The console adds detail. A positioning console for the cash index, stamped 2026-10-14 and read at about 6:19 PM ET, shows call gamma of 8.85 billion against put gamma of minus 1.86 billion. The console puts one-month implied volatility at 12.09 percent against realised volatility of 9.47 percent and the put-to-call open-interest ratio at 1.37. Then the review's read. In the review's interpretation, a cash close beneath the modeled volatility threshold and just above the flip level, after a session in which realised movement far exceeded the priced move, favours rallies stalling beneath the 7,823.4 source pair of that threshold. In the same interpretation, the 7,701 flip level (ES pair 7,749.4) and the note's 7,700 support mark where the environment would turn less stable.
Volume surged. Wednesday's December volume was 1,976,201 contracts, the highest since the 2,214,495 of 10/01. Tuesday's revised 2026-10-13 row reads 1,192,792, replacing the 1,143,877 carried in Wednesday's outlook, a difference of 48,915. Tuesday's open interest now reads 1,915,573 on that row, against 1,918,573 on the 2026-10-12 row. Wednesday's open interest had not been reported when the review was written. The positioning report as of October 6, 2026 puts asset managers at 1,106,717 long against 200,102 short. Leveraged funds held 113,223 long, down 12,230, against 528,310 short, up 30,368. Dealers held 201,165 long against 802,006 short.
The trade map for Thursday
The primary setup is a short from 7,797 to 7,803. The settle sits beneath the 5-day through 50-day settlement averages after an outside day that settled at 21.1 percent of its range. The cash close sits 56.06 points beneath the 7,775 modeled volatility threshold (ES pair 7,823.4). Negative direction leads on the 9-day and 14-day directional systems, and the composite fell to 16 percent buy with direction described as weakening. The band holds the Pivot Point at 7,797.00, on its bottom edge, and the 18-day average crossing price at 7,799.03. Its top sits 20.40 points beneath 7,823.4. The stop sits at 7,826, above 7,823.4 and two standard deviations resistance at 7,825.35. Targets step down. The first, 7,774, sits 0.30 beneath the 38.2 percent retracement at 7,774.30; the second, 7,748, sits 1.75 above the 3-10 day crossover stall level at 7,746.25; and the extended 7,722 sits 7.75 above Pivot S1 at 7,714.25. Dealer gamma remains positive in aggregate, and the cash close sits only 17.94 points above the flip level near the desk note's 7,700 support. Producer prices can expand the range in either direction. The review calls the setup an analyst judgment that rallies stall beneath the threshold pair. No measured edge stands behind it.
Now the arithmetic. From the 7,800 midpoint the risk to the stop is 26 points, 34.8 percent of the 14-day average true range of 74.74. The targets sit 26, 52 and 78 points beneath the midpoint. Exact multiples. The settle sat 26.75 points beneath the band bottom and 32.75 beneath its top. The 6:26 PM ET quote of 7,763.25 sits 33.75 beneath the bottom, and the new session's high so far, 7,769.50, stayed 27.50 points under the band. A one-range frame from the settle, 7,695.51 to 7,844.99, holds the band, the stop and all three targets. One detail stands out. The first target at 7,774 sits 3.75 points above the settle, and the 6:26 PM ET quote already sat 10.75 beneath it.
The session bands are the review's analyst judgment. Through Globex the review expects roughly 7,735 to 7,800, with a neutral to lower bias beneath the 7,797 to 7,803 band. London runs 7,730 to 7,805, with the band the first meaningful resistance. The morning band runs 7,715 to 7,826 and the afternoon band 7,700 to 7,840. The desk note's implied one-day move of about 38.59 index points frames the reaction. The scenario ranges run 7,731 to 7,809 for the low-range case, 7,715 to 7,825 for the most likely and 7,696 to 7,845 for the high-range case.
Thursday's calendar starts overnight. Japanese machinery orders are listed at 7:50 PM ET and Australian employment at 8:30 PM ET on Wednesday, both per the news-feed calendar and unconfirmed. A Federal Reserve vice chair speaks at 10:55 PM ET, as the calendar lists it. The Taiwanese chipmaker reports at 2:00 AM ET on Thursday, as the calendar lists it. UK output data are listed at 2:00 AM ET and euro-area industrial production at 5:00 AM ET, both per the news-feed calendar and unconfirmed. Then the main event. Producer prices and retail sales for September print at 8:30 AM ET, before the 9:30 AM ET cash open, as the calendar lists them. The news-feed calendar lists 0.6 percent for monthly producer prices and 0.3 percent for retail sales. Weekly jobless claims and the Philadelphia and New York manufacturing surveys are listed at 8:30 AM ET, per the news-feed calendar and unconfirmed. Business inventories follow at 10:00 AM ET and the weekly petroleum status report at 12:00 PM ET, as the calendar lists them. A Federal Reserve bank president is listed at 4:30 PM ET, per the news-feed calendar and unconfirmed.
The week keeps going. The Federal Reserve Chair's discussion with the International Monetary Fund's managing director is scheduled at 11:30 PM ET on Thursday, as the calendar lists it. Import prices follow at 8:30 AM ET on Friday, October 16, 2026, as the calendar lists them. Industrial production comes at 9:15 AM ET that day, as the calendar lists it. The desk note lists monthly options expiration on Friday and the volatility-index expiration on 10/21, both per the positioning note and unconfirmed. In the review's judgment the first-order influence on the S&P 500 on Thursday is the September producer price index at 8:30 AM ET, after Wednesday's hotter inflation report.
One path is weighted. In this review's analyst judgment the most probable path holds the contract between two standard deviations support at 7,715.15 and two standard deviations resistance at 7,825.35, with producer prices and the chipmaker's results deciding the side. In the same judgment, a rally that stalls beneath the 7,823.4 source pair of the modeled volatility threshold is weighted above a sustained recovery. It rests on judgment. The review weighs it that way because the cash close sits beneath that threshold and the settle beneath the 5-day through 50-day averages. Negative direction leads on both directional systems, and the composite fell to 16 percent buy. One alternative is named. The alternative that would invalidate the reading is a soft producer-price print that carries the contract back above the threshold pair toward Pivot R1 at 7,853.00, where the desk note describes negative gamma that could extend a move higher.
Wednesday's 9:30 AM ET bar went 14.50 points through the long card's stop; Thursday's card asks the 7,797 to 7,803 band to cap a rally.
The complete data picture
Every number behind Thursday’s plan, charted first, then the full level lists, then the complete numeric reference underneath.
Full numeric reference, every remaining figure from the session review
1. Executive Summary
The December S&P 500 contract settled at 7,770.25 on Wednesday, down 85.50 points or 1.09 percent from Tuesday's settle of 7,855.75, after trading between 7,879.75 and 7,741.00, a 138.75 point daily range. The settle finished at 21.1 percent of the range, and the range was 1.90 times the published 14-day average daily range of 73.04 points. Wednesday printed a higher high and a lower low against Tuesday, an outside day, and was the third consecutive lower settle. The 7,770.25 settle was the lowest since the 7,724.00 settle of 10/01, the 85.50 point decline the largest since the 116.75 point decline of 07/29, and the 138.75 point range the widest since the 157.25 point range of 08/04.
The September consumer price index printed at 8:30 AM ET, as the calendar listed it, with the news-feed calendar showing 3.7 percent for the year against a 3.6 percent forecast and 0.3 percent for the core month against 0.2 percent. In the 30-minute bars the session high of 7,879.75 printed in the 8:30 AM ET bar, which then traded down to 7,822.25 and closed at 7,824.75, and the session low of 7,741.00 printed in the 2:00 PM ET bar. The S&P 500 cash index closed at 7,718.94, down 1.11 percent, the Nasdaq-100 cash index fell 2.02 percent and the semiconductor index 4.30 percent. The desk note said the probability it assigns to an October Federal Reserve increase rose to 33 percent from 22 percent.
The cash close sits 56.06 points beneath the modeled volatility threshold at SPX 7,775 and 17.94 points above the modeled gamma-flip level at SPX 7,701, and the composite multi-indicator read fell to 16 percent buy from 96 percent buy, with strength described as minimum and direction as weakening. The volatility index closed at 16.87, up 1.60.
The Thursday session carries producer prices and retail sales at 8:30 AM ET, as the calendar lists it. The published 14-day average true range of 74.74 points is 0.96 percent of the settle. The primary setup is a short from the 7,797 to 7,803 band, around the Pivot Point at 7,797.00 and the 18-day average crossing price at 7,799.03, stopped at 7,826 above the 7,823.4 source pair of the modeled volatility threshold, with objectives at 7,774, 7,748 and an extended 7,722.
2. Price Action & Technical Structure
2.1 Intraday and Session Review
The Wednesday session opened at 7,856.25 at the Tuesday 6:00 PM ET reopen, 0.50 above Tuesday's settle, marked a daily high of 7,879.75 and a daily low of 7,741.00, and settled at 7,770.25. The 30-minute bars for the session show the 8:00 AM ET bar closing at 7,878.50 and the 8:30 AM ET bar, which contains the inflation release, setting the session high of 7,879.75 before trading down to 7,822.25 and closing at 7,824.75. The 9:30 AM ET bar traded down to 7,806.50 and closed at 7,808.00, the 2:00 PM ET bar set the session low of 7,741.00 and closed at 7,755.50, and the 3:30 PM ET bar closed at 7,771.75. The daily high and low are full Globex session extremes rather than extremes of the cash session.
After the settle, the chart's 4:30 PM ET bar closed at 7,765.25; that post-settlement quote is not used as the settlement anywhere in this review. Globex reopened at 6:00 PM ET, so the provider's displayed day open, high and low of 7,768.25, 7,769.50 and 7,759.25 belong to the new session dated Thursday, not to Wednesday, and are not used as Wednesday's range.
The session extremes used here are the completed-session inputs behind the published pivot ladder rather than an independently read bar, back-solved from the outer pivot pairs and verified against every rung. Pivot R3 at 7,991.75 minus Pivot S3 at 7,575.50, divided by three, returns 138.75, and Pivot R2 at 7,935.75 minus Pivot S2 at 7,658.25, divided by two, returns the same 138.75. Three times the Pivot Point of 7,797.00 less the 7,770.25 settle gives a high plus low sum of 15,620.75, which the pair of 7,879.75 and 7,741.00 reproduces, and that pair reproduces all seven published rungs. Independent corroboration: the provider's settlement row, the chart's completed Wednesday daily bar and the extremes of the 30-minute bars carry the same 7,879.75 high and 7,741.00 low.
2.2 Daily Structure
Wednesday printed a higher high and a lower low against Tuesday: the 7,879.75 high sits 15.75 points above Tuesday's 7,864.00, and the 7,741.00 low sits 93.50 points beneath Tuesday's 7,834.50. The settle at 21.1 percent of the range leaves an upper shadow of 23.50 points above the 7,856.25 open and a lower shadow of 29.25 points beneath the settle on the daily bar. The sequence of session highs over the last six sessions reads 7,884.50, 7,858.25, 7,870.50, 7,887.00, 7,864.00 and 7,879.75, and the sequence of session lows reads 7,815.75, 7,783.00, 7,817.00, 7,846.25, 7,834.50 and 7,741.00. Settlements over the same six sessions ran 7,852.75, 7,816.25, 7,859.75, 7,858.00, 7,855.75 and 7,770.25.
Last week, October 5 through October 9, spanned 7,897.50 to 7,760.25, and Wednesday's 7,741.00 low sits 19.25 points beneath that span. The 52-week and 13-week high of 7,905.00 from 08/13 sits 134.75 points above the settle, and the one-month low of 7,575.00 sits 195.25 points beneath it. Over five sessions the contract fell 82.50 points from the 7,852.75 settle of 10/07, matching the provider's five-day change of minus 82.50.
No prior-quarter high or low was captured for this session, so the 13-week extremes serve as the available quarterly reference: 7,905.00 above and 7,386.00 beneath.
2.3 4-Hour and Swing Structure
Daily ranges for the last eight sessions ran 87.25, 68.50, 68.75, 75.25, 53.50, 40.75, 29.50 and 138.75. The settlement changes over the same eight sessions read plus 49.00, plus 47.75, minus 21.25, minus 36.50, plus 43.50, minus 1.75, minus 2.25 and minus 85.50.
The retracement grid published for Thursday places the 38.2 percent retracement from the four-week high at 7,774.30, 4.05 points above the settle. Beneath the settle, the 50 percent retracement of the four-week range sits at 7,736.25, the 38.2 percent retracement from the 13-week high at 7,706.74 and the 38.2 percent retracement from the four-week low at 7,698.19. No four-hour series was captured for this session, so swing structure here rests on daily bars and the 30-minute session.
2.4 Moving Averages
The averages cited in this subsection were computed from the provider's daily settlement series for the December contract, which holds 259 completed sessions through Wednesday. The 5-day average stands at 7,832.00, the 9-day at 7,832.25, the 20-day at 7,791.84, the 50-day at 7,779.24, the 100-day at 7,691.41 and the 200-day at 7,390.77.
The 7,770.25 settle sits 61.75 points beneath the 5-day average, 62.00 beneath the 9-day, 21.59 beneath the 20-day and 8.99 beneath the 50-day, and 78.84 points above the 100-day and 379.48 above the 200-day. The 5-day average fell 16.50 points from Tuesday's 7,848.50, because the 10/07 settle of 7,852.75 left the window and was replaced by 7,770.25. The 20-day rose 7.36 points from 7,784.48, because the 09/16 settle of 7,623.00 left that window, and the 50-day fell 1.29 points from 7,780.53, because the 08/04 settle of 7,834.75 left that window.
The 20-day average sits above the 50-day because the last 20 settlements averaged 7,791.84 against 7,779.24 for the full 50, which means the 30 older settlements in the 50-day window averaged lower, at 7,770.84. The projection grid gives the prices at which each average would be crossed on Thursday: 7,839.13 for the 9-day, 7,799.03 for the 18-day and 7,764.72 for the 40-day.
2.5 Oscillator and Trend Readings
The oscillator figures below are as published on the provider's technical page dated for the Thursday session and read after the 6:00 PM ET reopen; the page can substitute the live Globex price for the settle, so these readings carry that caveat. The 9-day relative strength reads 44.62, the 14-day relative strength 48.41 and the 20-day relative strength 50.13.
The 9-day raw stochastic reads 26.97 percent and the 14-day raw stochastic 43.38 percent, while the 14-day stochastic %K reads 69.08 percent and the 14-day stochastic %D 75.97 percent, so %K sits beneath %D in the upper half of the range.
The 9-day directional index ADX reads 15.05 with the 9-day +DI at 17.31 and the 9-day -DI at 28.46; the 14-day directional index ADX reads 10.68 with the 14-day +DI at 18.47 and the 14-day -DI at 25.83, so negative direction leads on both while both ADX readings stay low. The 9-day historic volatility reads 9.14 percent and the 14-day historic volatility 8.37 percent.
The composite multi-indicator read published for the Thursday session is 16 percent buy, down from 96 percent buy in the prior session's snapshot, with signal strength described as minimum and direction as weakening. The snapshot history reads 80 percent buy a week ago and 16 percent sell a month ago. The short-horizon group averages 40 percent sell, the medium-horizon group 25 percent buy and the long-horizon group 67 percent buy, and the composite trend indicator reads buy.
2.6 Volatility and Expected Range
The published 14-day average true range stands at 74.74 points and the 14-day average daily range at 73.04 points; the 9-day average true range is 74.39 with a 9-day average daily range of 72.14, and the 20-day average true range is 75.51 with a 20-day average daily range of 76.19. Wednesday's 138.75 point range was 1.90 times the 14-day average daily range.
Adding and subtracting the 14-day average true range of 74.74 points from the 7,770.25 settle frames Thursday between 7,695.51 and 7,844.99. The published standard-deviation bands are narrower because they are built from five settlements: one deviation spans 7,731.29 to 7,809.21, two spans 7,715.15 to 7,825.35 and three spans 7,702.77 to 7,837.73. These bands describe settlement dispersion, not intraday reach. The desk note's implied one-day move of 0.50 percent equals about 38.59 points on the 7,718.94 cash close.
3. Key Levels
3.1 Resistance
Above the 7,770.25 settle, the 38.2 percent retracement from the four-week high at 7,774.30, the 50-day settlement average at 7,779.24 and the 7,785.52 projection for the 14-day relative strength midpoint come first. The 20-day settlement average at 7,791.84, the 40-day stall level at 7,795.00, the Pivot Point at 7,797.00 and the 18-day average crossing price at 7,799.03 form the band that anchors the setup. One standard deviation resistance at 7,809.21, the 7,823.4 source pair of the modeled volatility threshold and two standard deviations resistance at 7,825.35 form the next grouping, followed by three standard deviations resistance at 7,837.73 and the 9-day average crossing price at 7,839.13. Pivot R1 at 7,853.00, Tuesday's 7,855.75 settle and Wednesday's 7,879.75 high come next, with Pivot R2 at 7,935.75 and the 7,948.4 source pair of the primary call side ceiling the extended references.
3.2 Support
Beneath the settle, the 40-day average crossing price at 7,764.72 and the published target price at 7,752.89 come first, followed by the 7,749.4 source pair of the modeled gamma-flip level, the 3-10 day crossover stall level at 7,746.25 and Wednesday's 7,741.00 low. The 50 percent retracement of the four-week range at 7,736.25 and one standard deviation support at 7,731.29 come next, followed by two standard deviations support at 7,715.15 and Pivot S1 at 7,714.25. The 38.2 percent retracement from the 13-week high at 7,706.74, three standard deviations support at 7,702.77 and the 38.2 percent retracement from the four-week low at 7,698.19 form the next grouping, with Pivot S2 at 7,658.25 and Pivot S3 at 7,575.50 beyond.
4. Macro Drivers
4.1 Dollar, Rates, and Fed Policy
The consumer price index for September printed at 8:30 AM ET, as the calendar listed it, above forecast on the annual and core monthly measures. The news feed carried at 8:31 AM ET to 8:34 AM ET that rate futures fell as traders added to bets on an October increase, at 9:05 AM ET that traders fully price two increases by the end of January, and at 9:40 AM ET investment-bank commentary adding a December increase to its forecast. The central bank's regional survey of economic conditions, released at 2:00 PM ET as the calendar listed it, said two of the twelve districts reported moderate growth and three noted intensifying input price pressures. At 2:36 PM ET a regional Federal Reserve president called the report higher than hoped, and at 3:09 PM ET to 3:20 PM ET another called it discouraging. The ten-year yield index traded between 5.18 and 5.33 percent and closed at 5.19 percent against 5.21 percent, the 13-week bill yield index rose to 4.09 percent from 4.05 percent, and the dollar index closed at 102.55, up 0.37.
4.2 Large-Cap Leadership and Earnings
The news feed carried at 10:16 AM ET a large investment bank's chief executive saying the firm remains overweight the artificial intelligence opportunity set, after that bank's results at about 7:30 AM ET, as the calendar listed them. At 1:34 PM ET to 1:35 PM ET it carried remarks from the leading graphics-chip maker's chief executive on artificial intelligence safety, at 1:25 PM ET and 1:50 PM ET a cloud provider's chief executive saying its backlog supports its debt and its share drop was irrational, and at 12:40 PM ET a 21 billion dollar semiconductor plant arrangement announced by the President. A market wrap carried by the feed said renewed losses in semiconductor shares and the stronger inflation report lifted rate-increase expectations. The Taiwanese chipmaker reports at 2:00 AM ET on Thursday, October 15, 2026, as the calendar lists it.
4.3 Geopolitical Backdrop
The news feed carried at 9:33 AM ET an Iranian state media report of an explosion in Riyadh with reported damage to oil facilities, at 1:38 PM ET a Houthi statement of a ballistic missile attack on Riyadh's main airport, and at 3:03 PM ET and 3:24 PM ET reports of an attack on and an explosion in Jeddah. At 2:52 PM ET the news feed carried Iran's parliament speaker saying a US deal cannot prevent another attack on Iran. These are statements carried by the news feed rather than events confirmed for this review. November WTI crude settled at 95.09, up 1.01 percent.
4.4 Sector Breadth and Rotation
The desk note said the semiconductor fund fell 5 percent for a seventh consecutive decline, erasing roughly 1 trillion dollars of market value, while healthcare rose 3 percent and consumer staples 2 percent as capital rotated into defensive sectors. In the provider's daily record the semiconductor index fell 4.30 percent, the Nasdaq-100 cash index 2.02 percent, the S&P 500 cash index 1.11 percent, the NYSE composite 0.50 percent and the Dow Jones Industrial Average 0.09 percent, so the decline was led by the technology-heavy indices.
4.5 Cross-Asset and Volatility
The volatility index closed at 16.87, up 1.60 from 15.27, after trading as high as 17.45, and the volatility-of-volatility index closed at 94.45, up 9.07. The desk note said the morning's same-day at-the-money straddle priced a 43 basis point move against a realised move more than four times larger, and that fixed-strike implied volatility rose about one point for this week's expiration while longer-dated implied volatility was little changed. December gold settled at 4,107.9, down 1.66 percent, and the dollar index rose 0.37.
4.6 Institutional Positioning
The positioning report as of October 6, 2026, shown on the provider's overview, puts asset managers long at 1,106,717 contracts against short at 200,102, and leveraged funds long at 113,223, down 12,230, against short at 528,310, up 30,368. Dealers held 201,165 long against 802,006 short. Open interest on the December contract is shown at 1,915,573 for Tuesday, against 1,918,573 on Monday; Wednesday's open interest had not been reported when the review was written. Wednesday's volume of 1,976,201 contracts was the highest since the 2,214,495 of 10/01, against Tuesday's revised 1,192,792.
5. SPX Options Flow Context
The desk note read for this section is the 5:20 PM ET edition for Wednesday. Its reference prices are the prior session's closes, not Wednesday's: SPX 7,805 equals Tuesday's 7,805.45 cash close, and 7,805.45 less 1.11 percent gives 7,718.81, consistent with the provider's 7,718.94 close; the note's narrative states a close of 7,719, 0.06 above the provider's figure, and this review uses the provider's close. Every level below is read against Wednesday's 7,718.94 cash close.
On the index the primary call side ceiling sits at SPX 7,900, the largest gamma concentration at SPX 8,000, the modeled volatility threshold at SPX 7,775, the modeled gamma-flip level at SPX 7,701 and the primary put side support base at SPX 7,500. The close sits 181.06 points beneath the 7,900 ceiling, 56.06 points beneath the threshold and 17.94 points above the flip level. Gamma tilt reads 1.326 and gamma notional plus 996.435 million dollars, so dealer gamma remains positive in aggregate. The note's summary lists resistance at 7,820, 7,870 and 7,900, support at 7,800, 7,750 and 7,700 and its desk pivot at 7,690, and its key strikes are SPX 8,000, 7,800, 7,000 and 7,700.
The note publishes its own December futures pair for each level, carrying the source's 48.4 point offset rather than the measured 51.31 point basis: the ceiling at 7,948.4, the largest concentration at 8,048.4, the modeled volatility threshold at 7,823.4, the modeled gamma-flip level at 7,749.4 and the put side support base at 7,548.4. These are quoted as the source's pairs. The modeled threshold and flip level are model outputs, not option strikes.
The narrative said the S&P 500 fell 175 basis points after the 8:30 AM ET inflation print, that index options flow showed about minus 1 billion dollars of cumulative delta led by longer-dated put buying as traders added hedges ahead of producer prices, and that single-stock options flow showed about minus 5 billion dollars, including about 4 billion dollars of longer-dated call selling. Its summary adds that a move above 7,825 could extend quickly because gamma above that level is negative, that support is solid down to 7,700 and that beneath 7,700 the note shifts to a risk-off stance. The note's implied one-day move is 0.50 percent and its implied five-day move 1.22 percent, or about 94.17 points on the close. Its published implied one-day high and low are not symmetric around either the reference or the close, so that pair is excluded.
The S&P 500 positioning console, read at about 6:19 PM ET with a Date Updated stamp of 2026-10-14, shows call gamma of 8.85 billion against put gamma of minus 1.86 billion, one-month implied volatility of 12.09 percent against realised volatility of 9.47 percent and a put-to-call open-interest ratio of 1.37; these figures differ from the prior session's read, so they are treated as refreshed. Its current-price field is a post-close indicative quote, and its high and low volatility point fields are treated as low-confidence and excluded.
In this review's interpretation a cash close beneath the modeled volatility threshold and just above the flip level, after a session in which realised movement far exceeded the priced move, favours rallies stalling beneath the 7,823.4 source pair of that threshold, while the flip level at SPX 7,701 and the note's 7,700 support mark where the environment would turn less stable; the primary setup sells the 7,797 to 7,803 band beneath the threshold pair.
6. Forecast
6.1 Night Session (6:00 PM ET Wednesday to 3:00 AM ET Thursday, Globex/Asia)
Globex reopened at 6:00 PM ET and the December contract was quoted at 7,763.25 on the provider's page at 6:26 PM ET, 7.00 points beneath the settle. A Federal Reserve vice chair speaks at 10:55 PM ET, as the calendar lists it, and the Taiwanese chipmaker reports at 2:00 AM ET on Thursday, as the calendar lists it. Bias neutral to lower beneath the 7,797 to 7,803 band, expected Globex band roughly 7,735 to 7,800.
6.2 London Session (3:00 AM to 8:00 AM ET Thursday)
UK output data are listed at 2:00 AM ET and euro-area industrial production at 5:00 AM ET, both per the news-feed calendar and unconfirmed. Bias neutral to lower, expected band roughly 7,730 to 7,805, with the 7,797 to 7,803 band the first meaningful resistance.
6.3 Morning Session (9:30 AM to 12:00 PM ET Thursday, RTH Open)
Producer prices and retail sales for September print at 8:30 AM ET, as the calendar lists them, before this window opens, and the cash open at 9:30 AM ET is the first directional test of the session. Weekly jobless claims are listed at 8:30 AM ET, per the news-feed calendar and unconfirmed, and business inventories are scheduled at 10:00 AM ET, as the calendar lists them. Expected band roughly 7,715 to 7,826.
6.4 Afternoon Session (12:00 PM to 4:00 PM ET Thursday)
The weekly petroleum status report is scheduled for 12:00 PM ET, as the calendar lists it, and the cash close is at 4:00 PM ET. A Federal Reserve bank president is listed at 4:30 PM ET, per the news-feed calendar and unconfirmed. Expected band roughly 7,700 to 7,840.
6.5 Night Session Forward (6:00 PM ET Thursday)
The Friday session opens at 6:00 PM ET Thursday. The Federal Reserve Chair's discussion with the International Monetary Fund's managing director is scheduled for 11:30 PM ET, as the calendar lists it. Import prices are scheduled for 8:30 AM ET on Friday, October 16, 2026, as the calendar lists it.
6.6 Expected Range (Thursday Full Session)
Low-range scenario: 7,731 to 7,809
Mid-range scenario (most likely): 7,715 to 7,825
High-range scenario: 7,696 to 7,845
6.7 Most Likely Path
In this review's analyst judgment the most probable path holds the contract between two standard deviations support at 7,715.15 and two standard deviations resistance at 7,825.35, with producer prices and the chipmaker's results deciding the side. In the same analyst judgment, a rally that stalls beneath the 7,823.4 source pair of the modeled volatility threshold is weighted above a sustained recovery, because the cash close sits beneath that threshold, the settle sits beneath the 5-day through 50-day settlement averages, negative direction leads on the 9-day and 14-day directional systems and the composite fell to 16 percent buy with direction described as weakening. The alternative that would invalidate this reading is a soft producer-price print that carries the contract back above the threshold pair toward Pivot R1 at 7,853.00, where the desk note describes negative gamma that could extend a move higher.
7. Thursday Economic Calendar
Globex reopened at 6:00 PM ET on Wednesday. Japanese machinery orders are listed at 7:50 PM ET and Australian employment at 8:30 PM ET, both per the news-feed calendar and unconfirmed. A Federal Reserve vice chair speaks at 10:55 PM ET, as the calendar lists it.
On Thursday, the Taiwanese chipmaker reports at 2:00 AM ET, as the calendar lists it. UK output data are listed at 2:00 AM ET and euro-area industrial production at 5:00 AM ET, both per the news-feed calendar and unconfirmed. Producer prices and retail sales for September print at 8:30 AM ET, as the calendar lists them, with the news-feed calendar listing 0.6 percent for monthly producer prices and 0.3 percent for retail sales. Weekly jobless claims and the Philadelphia and New York manufacturing surveys are listed at 8:30 AM ET, per the news-feed calendar and unconfirmed. Business inventories are scheduled at 10:00 AM ET, as the calendar lists them, and the weekly petroleum status report at 12:00 PM ET, as the calendar lists it. A Federal Reserve bank president is listed at 4:30 PM ET, per the news-feed calendar and unconfirmed, and the Federal Reserve Chair's discussion with the International Monetary Fund's managing director is scheduled at 11:30 PM ET, as the calendar lists it.
Later in the window, import prices are scheduled for 8:30 AM ET on Friday, October 16, 2026, and industrial production for 9:15 AM ET on Friday, October 16, 2026, both as the calendar lists them. The desk note lists monthly options expiration on Friday, per the positioning note and unconfirmed, and the volatility-index expiration on 10/21, per the positioning note and unconfirmed. In this review's judgment the first-order influence on the S&P 500 on Thursday is the September producer price index at 8:30 AM ET, as the calendar lists it, after Wednesday's hotter inflation report.
8. Primary Trade Setup
Direction: Short
Rationale: The cash close sits 56.06 points beneath the modeled volatility threshold at SPX 7,775, the settle sits beneath the 5-day through 50-day settlement averages after an outside day that settled at 21.1 percent of its range, negative direction leads on the 9-day and 14-day directional systems, and the composite fell to 16 percent buy with direction described as weakening; a rally into the 7,797 to 7,803 band of the Pivot Point at 7,797.00 and the 18-day average crossing price at 7,799.03 offers a short with a defined risk point above the 7,823.4 source pair of that threshold. Dealer gamma remains positive in aggregate, the cash close sits only 17.94 points above the flip level near the desk note's 7,700 support, and producer prices can expand the range in either direction, so the setup is an analyst judgment that rallies stall beneath the threshold pair, not a measured edge.
Entry Zone: 7,797 to 7,803
Stop Loss: 7,826 (above the 7,823.4 source pair of the modeled volatility threshold and two standard deviations resistance at 7,825.35)
Target 1 (T1): 7,774 (0.30 beneath the 38.2 percent retracement at 7,774.30)
Target 2 (T2): 7,748 (1.75 above the 3-10 day crossover stall level at 7,746.25)
Target 3 (T3, extended): 7,722 (7.75 above Pivot S1 at 7,714.25)
Risk-to-Reward: Approximately 1:1 to T1, 1:2 to T2, 1:3 to T3
Invalidation: A settle above two standard deviations resistance at 7,825.35 negates the thesis. Short of that, the edge is removed by acceptance above the entry band rather than by a touch, defined as two consecutive 30-minute closes above 7,803.
Macro override: A soft producer-price print that pulls yields lower, or strong results from the Taiwanese chipmaker that lift semiconductor shares, would invalidate the short in real time. In that scenario a move through the 7,826 stop removes the setup, and the 9-day average crossing price at 7,839.13 and Pivot R1 at 7,853.00 become the references within one 14-day average true range of 74.74 points.
Sources and methodology
This outlook is built from our session review of the December E-mini S&P 500 contract, the December ’26 contract, prepared after Wednesday's close on October 14, 2026 for the Thursday, October 15, 2026 session. Wednesday's completed extremes are the inputs behind the published pivot ladder: Pivot R3 at 7,991.75 less Pivot S3 at 7,575.50, divided by three, and Pivot R2 at 7,935.75 less Pivot S2 at 7,658.25, divided by two, both return 138.75, and three times the 7,797.00 Pivot Point less the settle gives a high-plus-low sum of 15,620.75, which the pair of 7,879.75 and 7,741.00 reproduces. The provider's settlement row, the chart's completed Wednesday daily bar and the extremes of Wednesday's 30-minute bars carry the same high and low. Those figures, the 30-minute bars from the Tuesday 6:00 PM ET reopen through the 4:30 PM ET bar, and the review's own statements are the only evidence used to grade Wednesday's card; an order is stated only where a bar shows it. Tuesday's volume now reads 1,192,792 contracts on the revised 2026-10-13 row, which replaces the 1,143,877 carried in Wednesday's outlook, and Tuesday's open interest of 1,915,573 is now reported on that row; that post was not changed.
The moving averages were computed from the provider's 259-session daily settlement series through Wednesday; the oscillators are cited as published for the Thursday session, read after the 6:00 PM ET reopen, and that page can substitute the live Globex price for the settle. The desk note used is the 5:20 PM ET edition for Wednesday, October 14; its reference column carries Tuesday's closes and its futures column a fixed 48.4 point translation, so cash equivalents here use the 51.31 point basis measured on Wednesday, settlement against cash close. The note's implied one-day high and low pair is not symmetric around either the reference or the close and is excluded. The positioning console's gamma, volatility and open-interest figures differ from the prior session's read and are treated as refreshed; its current-price field is a post-close indicative quote, and its high and low volatility point fields are excluded as low-confidence. After the settle, the 4:30 PM ET bar closed at 7,765.25, a post-settlement quote that is not used as the settlement, and the provider's 7,768.25 open, 7,769.50 high and 7,759.25 low belong to the new session dated Thursday. Scenario ranges are analyst judgment. Items marked unconfirmed come from the news-feed calendar or the positioning note, and every catalyst whose release time had passed at the time of writing is recorded as completed.
Wednesday’s outlook for this contract is here, and the Nasdaq-100 contract’s Wednesday outlook covers the index that fell 2.02 percent in cash on Wednesday. Outlooks for ES, NQ, GC and CL are collected on the market outlook page, and our forward trading record is on the performance statement.