At 6:30 AM ET on Monday the December S&P 500 contract printed 7,760.25, its low of the session. The overnight hours had been quiet. From the 9:30 AM ET cash open the contract climbed in steps until the 3:00 PM ET bar printed 7,847.50. That was 87.25 points off the low. It was also the highest print since the 7,848.50 high of 09/22, one point away. The 3:30 PM ET bar gave back 26.50 points to 7,821.00 before the close.
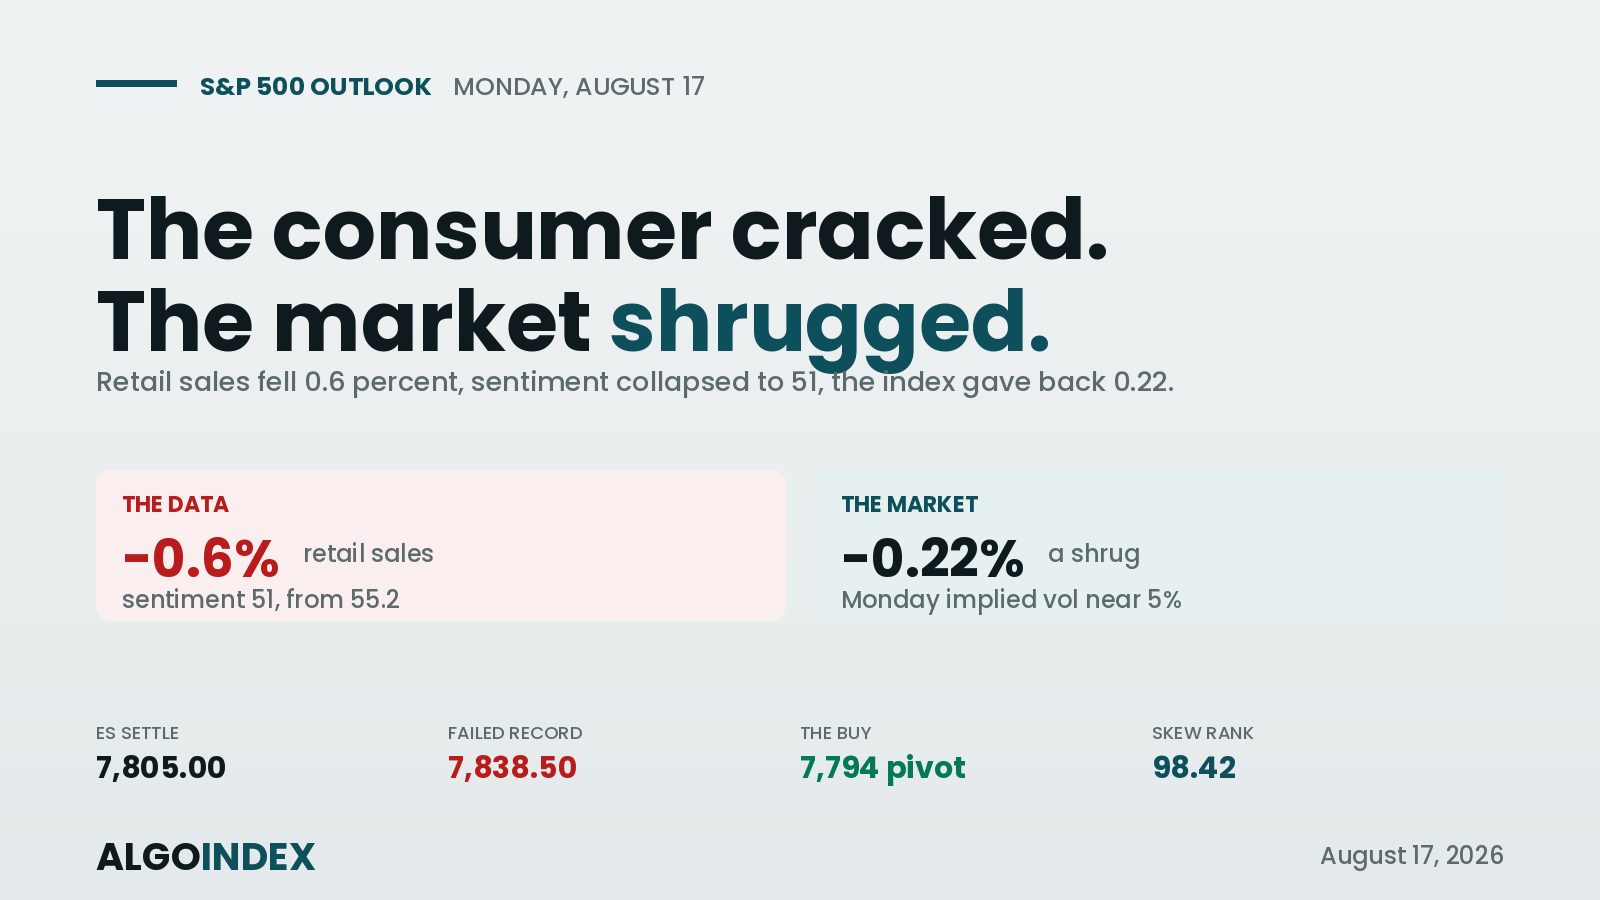
December E-mini futures settled at 7,826.25, up 49.00 points or 0.63 percent from Friday's 7,777.25. The daily row spans 7,847.50 to 7,760.25, an 87.25 point range, 1.04 times the 14-day average daily range of 83.77 points and the widest since the 95.00 point range of 10/01. Three higher settles in a row. Monday's was the highest settle since the 7,831.75 settle of 09/22, and it finished at 75.6 percent of the range. The cash index closed at 7,773.95, up 51.23 points or 0.66 percent. Provider commentary called that a 1.5-month high, on strength in the largest technology companies and on merger activity.
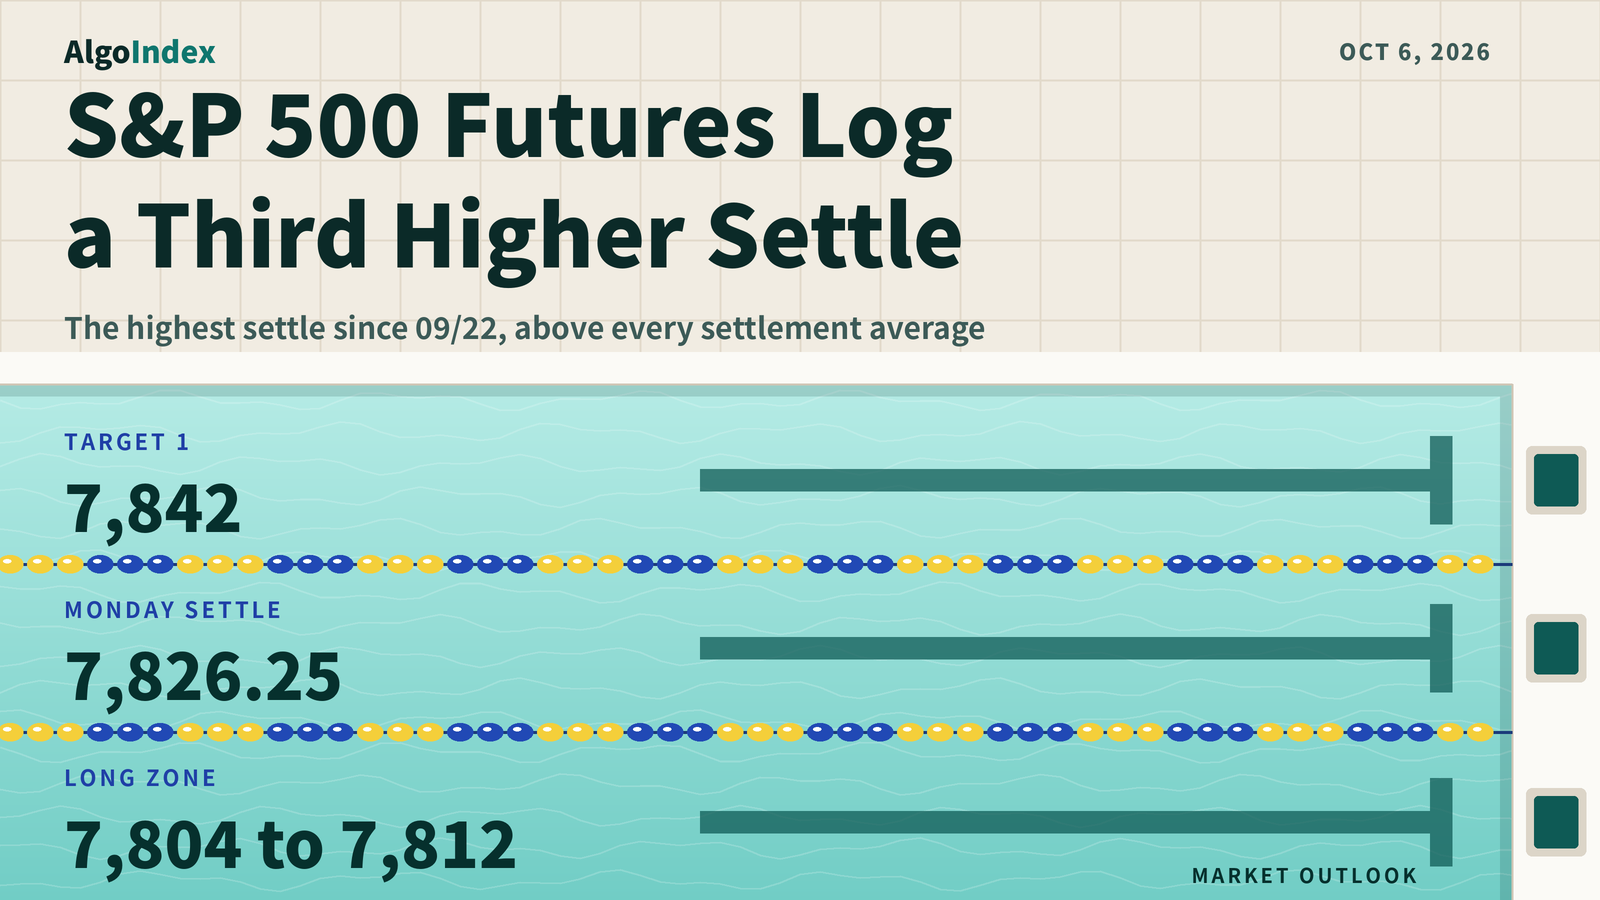
December S&P 500 futures settled at 7,826.25, 14.92 points above the 7,811.33 Pivot Point and above every settlement average from the 5-day to the 200-day. The primary setup is a long from 7,804 to 7,812 around that pivot, stop 7,774 beneath Pivot S1 at 7,775.17, targets 7,842, 7,876 and an extended 7,910. A tight band sits overhead. Monday's 7,847.50 high, the 7,848.50 one-month high, the 7,851.92 target price and the 7,854.80 source pair for the 7,800 call-side ceiling in cash span 7.30 points. The cash index closed 83.95 points above the 7,690 reference level, 53.95 points above the 7,720 modeled volatility threshold and 96.95 points above the 7,677 modeled gamma-flip level, and 26.05 points beneath the 7,800 ceiling. Tuesday's first-order event is the 1:00 PM ET three-year note auction, per the news-feed calendar and unconfirmed.
Monday's long band stayed untouched above a 7,760.25 low
Monday's outlook set a long from 7,748 to 7,756, stop 7,720, targets 7,784, 7,816 and an extended 7,848. Monday's completed bar, from tonight's review and the provider's dated 2026-10-05 row, opened at 7,781.50 at the Sunday 6:00 PM ET reopen, marked a high of 7,847.50 and a low of 7,760.25, and settled at 7,826.25. The two sources agree. Price never reached the band. The low stopped 4.25 points above its 7,756 top, and the 7,720 stop sat 40.25 points beneath that low.
Above, the high ran through two of the three target levels. It cleared the 7,784 first target level by 63.50 points and the 7,816 second by 31.50. The extension missed. The 7,848 level sat 0.50 points above the 7,847.50 high, so it did not trade.
The 30-minute series gives the order. The session opened at 7,781.50, 4.25 points above Friday's settle, and its first bar, the 6:00 PM ET Sunday bar, reached 7,788.00, 4.00 points through the 7,784 level. That came before the low. The 6:30 AM ET bar printed the 7,760.25 low and closed at 7,771.00. No bar traded into the band. The 11:30 AM ET bar was the first to reach 7,816, at 7,816.25. Bars show sequence only. With the zone untouched, no fill and no result is asserted.
Neither invalidation test triggered. The card named a settle beneath Pivot S1 at 7,730.25, and the 7,826.25 settle finished 96.00 points above it. Its acceptance line needed two consecutive 30-minute closes beneath 7,735. The lowest close of the session was 7,762.50, in the 6:00 AM ET bar.
Our top edges sat too low. In Monday's outlook we gave 7,735 to 7,820 as the most likely band. The low held inside it, 25.25 points above its bottom, while the high cleared its top by 27.50 points and the settle by 6.25. The low-range case of 7,750 to 7,805 broke by 42.50 at the top. The wider frames held. The high-range case of 7,700 to 7,855 and the one-range envelope of 7,699.63 to 7,854.87 contained the whole session, with the high 7.50 and 7.37 points beneath their tops.
The deviation bands broke upward. The high cleared one standard deviation resistance at 7,801.48 by 46.02 points, two at 7,811.52 by 35.98 and three at 7,819.23 by 28.27. The 7,760.25 low stayed inside all three bands, 7.23 points above the 7,753.02 one-deviation support.
Session by session, three of four held. The Globex bars from the reopen through the 2:30 AM ET bar spanned 7,764.00 to 7,793.00, inside the 7,750 to 7,800 band we published. London's bars, from 3:00 AM ET through the 7:30 AM ET bar, ran 7,760.25 to 7,782.75 against 7,755 to 7,805. Inside again. The morning bars, 7,778.25 to 7,816.25, held within 7,745 to 7,820 with 3.75 points to spare. The afternoon broke out. Its bars ran 7,809.25 to 7,847.50 against 7,755 to 7,810, 37.50 points over the top.
The weighted path held until midday. Monday's outlook weighted a hold above the 7,753.02 to 7,754.84 band through the Asian session and a retest of the 7,801.48 to 7,811.52 resistance band through the United States morning. Both came. The overnight low of 7,764.00 held 9.16 points above the band's top, and the 10:00 AM ET bar reached 7,811.00, inside the resistance band. That outlook read the soft composite as a reason for caution beneath Pivot R1 at 7,817.25. The 12:00 PM ET bar was the first to trade above it, at 7,818.25, and the high came 30.25 points beyond it.
The macro override did not trigger. It named a weekend shock or a jump in yields after the services survey that took the cash index back beneath the 7,680 modeled volatility threshold. The ten-year yield index did close four basis points higher, at 5.31 percent. The cash index still closed 93.95 points above 7,680, and its 7,727.59 session low held 47.59 points above it. We grade the card as written.
Monday's path reads off the series in three parts. The Asian hours were quiet. From the 6:00 PM ET Sunday bar through the 10:00 PM ET bar the contract held between 7,780.75 and 7,793.00, reaching the 7,793.00 overnight high in the 9:30 PM ET bar. The 10:30 PM ET bar fell to 7,777.50. From the 11:00 PM ET bar through the 6:00 AM ET bar the contract held between 7,760.50 and 7,779.25. Then the low. The 6:30 AM ET bar printed 7,760.25 and closed at 7,771.00, and from the 7:00 AM ET bar through the 9:00 AM ET bar the contract held between 7,764.75 and 7,782.75.
The cash open changed the session. The 9:30 AM ET bar rose from 7,778.50 to 7,791.25. The 10:00 AM ET bar, which contained the services survey, reached 7,811.00 and closed at 7,808.00. Then came small steps. The 10:30 AM ET bar held between 7,798.00 and 7,810.25, the 11:30 AM ET bar reached 7,816.25, the 12:30 PM ET bar 7,827.00 and the 1:30 PM ET bar 7,831.50. The 2:00 PM ET bar reached 7,835.25 and the 2:30 PM ET bar 7,838.25. The 3:00 PM ET bar printed the 7,847.50 high and closed at 7,842.25. The next bar gave back 26.50 points to 7,821.00 before closing at 7,831.25.
After the cash close, electronic trade held between 7,828.25 and 7,832.50 in the 4:00 PM ET and 4:30 PM ET bars, and the 4:30 PM ET bar closed at 7,830.00. The Tuesday session reopened at 6:00 PM ET Monday. Its first prints belong to Tuesday. The provider's day open, high and low of 7,831.75, 7,836.25 and 7,831.50, shown at the time of writing, belong to that new session and are not used for Monday.
Higher on both ends again. The 7,847.50 high sat 37.25 points above Friday's 7,810.25, and the 7,760.25 low sat 37.00 points above Friday's 7,723.25. Session highs over the last six sessions read 7,803.00, 7,770.75, 7,782.00, 7,767.75, 7,810.25 and 7,847.50. The lows read 7,726.00, 7,712.25, 7,705.50, 7,672.75, 7,723.25 and 7,760.25. The prior week, September 28 through October 2, spanned 7,810.25 to 7,672.75, and Monday's high cleared it by 37.25 points. Three settles added 110.75 points.
The 7,811.33 pivot and the 7,847.50 to 7,854.80 band
The basis does the translating. Monday's 7,826.25 settle less the 7,773.95 cash close measures 52.30 points, against 54.53 on Friday. The positioning note uses its own fixed 54.8 offset, and its published futures pairs carry that figure. Its 7,720 modeled volatility threshold carries a source pair of 7,774.80, its 7,690 reference level 7,744.80, its 7,677 modeled gamma-flip level 7,731.80 and its 7,800 call-side ceiling 7,854.80.
Support starts at the pullback. The 3:30 PM ET low at 7,821.00 (cash 7,768.70) sits 5.25 points beneath the settle. The Pivot Point at 7,811.33 (cash 7,759.03) comes next, 14.92 points beneath the settle and inside the 7,804 to 7,812 entry band. The 10:00 AM ET bar's 7,811.00 high sits 0.33 points under it. Beneath the band sit the 7,798.00 low of the 10:30 AM ET bar and the 7,793.00 overnight high.
Then a tight group. One standard deviation support at 7,779.82 (cash 7,727.52), Pivot S1 at 7,775.17 (cash 7,722.87) and the 7,774.80 source pair for the 7,720 modeled volatility threshold sit within 5.02 points. Friday's 7,777.25 settle sits inside that span. The 7,774 stop sits beneath all three.
Monday's lows come next. The 40-day average crossing at 7,763.09, the 9-day average at 7,762.78, the 9-day crossing at 7,761.56, two standard deviations support at 7,760.59 and Monday's 7,760.25 low (cash 7,707.95) span 2.84 points. The 5-day average sits at 7,755.00 (cash 7,702.70). A one-range frame from the settle bottoms at 7,747.94.
A second group sits lower. Three standard deviations support at 7,745.84, the 7,744.80 reference-level pair, the 18-day crossing at 7,744.06, the 38.2 percent retracement from the four-week high at 7,744.02 (cash 7,691.72) and the 50-day average at 7,743.81 span 2.03 points. The 20-day average follows at 7,738.51, with the 7,731.80 gamma-flip pair beneath it. Pivot S2 at 7,724.08 (cash 7,671.78) sits 0.83 points above Friday's 7,723.25 low.
The tail runs lower. The 50 percent retracement of the four-week range sits at 7,711.75 and Pivot S3 at 7,687.92. The prior week's 7,672.75 low sits 0.31 points above the 100-day average at 7,672.44. The put-side base pair sits at 7,554.80 (cash 7,500) and the 200-day average at 7,364.13.
Resistance starts right after the settle. The post-settlement bars reached 7,832.50 and the 4:30 PM ET bar closed at 7,830.00, with the 2:30 PM ET bar's 7,838.25 high above them. Then the band that matters. Monday's 7,847.50 high (cash 7,795.20), the 7,848.50 one-month high from 09/22 (cash 7,796.20), the 7,851.92 target price published for Tuesday (cash 7,799.62) and the 7,854.80 ceiling pair span 7.30 points. The review names the 7,847.50 to 7,854.80 band, Monday's high and the call-side ceiling pair, as the first barrier. The one-month high sits 22.25 points above the settle.
Higher references are extended. Pivot R1 sits at 7,862.42 (cash 7,810.12) and one standard deviation resistance at 7,872.68 (cash 7,820.38), 10.26 points apart. Two standard deviations resistance at 7,891.91 (cash 7,839.61) and Pivot R2 at 7,898.58 (cash 7,846.28) follow. The 52-week high of 7,905.00 from 08/13, 78.75 points above the settle, and three standard deviations resistance at 7,906.66 sit 1.66 points apart, with the one-range frame top at 7,904.56 just beneath. Pivot R3 at 7,949.67 (cash 7,897.37) is the extended reference, and the gamma concentration pair sits at 8,054.80 (cash 8,000).
Every average sits beneath. The 5-day at 7,755.00 is 71.25 points under the settle, the 9-day at 7,762.78 is 63.47 under, the 20-day at 7,738.51 is 87.74 under and the 50-day at 7,743.81 is 82.44 under. The 100-day sits at 7,672.44, 153.81 points beneath. The 200-day sits at 7,364.13, 462.12 beneath.
The short averages moved unevenly. The 5-day rose 15.90 points from Friday's 7,739.10, because the 09/28 settle of 7,746.75 left the window and 7,826.25 replaced it. The 9-day slipped 0.61 from 7,763.39 as the 09/22 settle of 7,831.75 left, and the 20-day rose 1.85 from 7,736.66 as the 09/04 settle of 7,789.25 left. The 9-day still sits 7.78 points above the 5-day. Arithmetic explains it. The four settles from 09/23 to 09/28 that the 9-day holds and the 5-day does not averaged 7,772.50. For Tuesday, the averages would be crossed at 7,761.56 for the 9-day, 7,744.06 for the 18-day and 7,763.09 for the 40-day.
Momentum sits above the midline. Relative strength reads 61.63 on the 9-day, 57.62 on the 14-day and 55.85 on the 20-day. The raw stochastic reads 87.84 percent on the 9-day and 91.86 percent on the 14-day, with the 14-day %K at 73.43 percent above %D at 62.59 percent. Trend strength is thin. The directional system is close to balanced. On the 9-day, positive direction at 22.16 leads negative at 18.73 with the index at 15.73, and on the 14-day 21.02 leads 20.28 with the index at 12.52. Historic volatility reads 8.03 percent on the 9-day and 10.15 percent on the 14-day. These readings are as published on the provider's technical page dated for the Tuesday session, read after the 6:00 PM ET reopen, so they may carry the live Globex price.
The composite multi-indicator read turned to 56 percent buy from 16 percent buy, with signal strength soft and direction strongest. It read 48 percent buy a week ago and 64 percent buy a month ago. Every group leans to buy. The short-horizon group averages 40 percent buy, the medium-horizon group 75 percent buy and the long-horizon group 67 percent buy, and the composite trend indicator reads hold.
Ranges ran near their averages. The 14-day average true range stands at 78.31 points and the 14-day average daily range at 83.77; the 9-day figures are 79.56 and 78.69 and the 20-day figures 78.27 and 79.06. One 14-day average true range either side of the settle frames Tuesday between 7,747.94 and 7,904.56. The published deviation bands are built from five settlements. One deviation spans 7,779.82 to 7,872.68, two 7,760.59 to 7,891.91 and three 7,745.84 to 7,906.66. They measure how settlements disperse and say nothing about intraday reach.
Zoom out. The settlement sequence from 09/21 reads 7,833.50, 7,831.75, 7,772.50, 7,767.00, 7,803.75, 7,746.75, 7,732.00, 7,715.50, 7,724.00, 7,777.25 and 7,826.25. The three declines that followed the 09/25 settle of 7,803.75 have been more than recovered. Daily ranges for the last seven sessions ran 66.25, 77.00, 58.50, 76.50, 95.00, 87.00 and 87.25 points. Two retracements sit beneath. The retracement grid published for Tuesday places the 38.2 percent line from the four-week high at 7,744.02 and the 50 percent line of the four-week range at 7,711.75. No prior-quarter high or low and no four-hour series were captured for this session, so the 30-minute series is the only intraday evidence used.
A 54.9 services print, a 5.31 percent yield and a technology-led day
The survey came first. The services survey from the purchasing managers' institute, released at 10:00 AM ET, printed 54.9 against a 55.0 forecast and 55.4 previously, with its employment component at 50.1 against 48.8, per the news-feed calendar. Provider commentary said its prices-paid component rose 1.4 points to 74.0, a four-year high. The release fell inside the 10:00 AM ET bar, which reached 7,811.00 and closed at 7,808.00. They share a half-hour. No causal link is drawn.
Yields rose. Provider commentary said the ten-year Treasury yield touched a 24-year high during the session and that services price pressure limited stock gains. The ten-year yield index closed at 5.31 percent, up four basis points. The dollar index rose 0.24 percent to 102.17, a 1.5-year high per provider commentary, and a news-feed article at 11:45 AM ET tied the dollar's move to French debt concerns. Investment-bank commentary on the news feed said the September employment data point to less urgency for further hikes.
Technology led. The positioning note said the largest technology companies outperformed, with the fund that tracks them up 1 percent, and that the Nasdaq-100 set a record high. The Nasdaq-100 cash index rose 0.87 percent against 0.66 percent for the S&P 500 and 0.18 percent for the Dow industrials. Chipmakers rose less. The semiconductor index added 0.27 percent, so the leadership, in the review's reading, came from the largest technology names.
Provider commentary also credited merger activity. It cited a European electrical-equipment maker agreeing to buy an industrial software company for 22.6 billion dollars and a freight brokerage agreeing to buy a trucking logistics company for 5.8 billion dollars. After the close, press reports carried by the news feed at 5:00 PM ET said banks launched a record 60 billion dollar financing for a large chipmaker and an artificial-intelligence developer. The positioning note said a Brazil equity fund rose 12 percent on election results. No advance-decline or sector breadth series was captured, so breadth beyond those index readings is not asserted.
The model has the index on its supportive side. The cash close of 7,773.95 sits 83.95 points above the note's 7,690 reference level, bearish beneath and bullish above. It sits 53.95 points above the 7,720 modeled volatility threshold and 96.95 above the 7,677 modeled gamma-flip level. The ceiling is close. The same close sits 26.05 points beneath the 7,800 primary call-side ceiling. The gamma index reads 2.272 and gamma tilt 1.19. Index notional is positive. It reads plus 619.60 million dollars, while the largest S&P 500 exchange-traded fund's reads minus 230.179 million dollars. The 25-delta risk reversal on the index reads minus 0.036.
In this review's interpretation the close above the reference level, the modeled volatility threshold and the modeled gamma-flip level, with the index gamma notional positive and the gamma index higher, places the index inside the supportive, mean-reverting part of its positioning map for Tuesday. In the same reading the 7,800 ceiling in cash is the first barrier. In that reading, the negative notional on that fund leaves room for wider moves if 7,720 in cash gives way.
Puts still led. Index put volume of 1.018 million contracts exceeded call volume of 695,544, and put open interest of 13.126 million exceeds call open interest of 9.252 million. Then the console. A positioning console for the cash index shows call gamma of 6.9 billion against put gamma of minus 3 billion and attributes 6.98 percent of the index's gamma and 0.75 percent of its delta to the nearest expiration. The positioning note said real-time hedging flow on the S&P 500 registered plus 13 billion dollars of delta on the day, mainly from same-day call buying, and described it as a momentum play rather than longer-term position building. That is the note's reading.
The note's narrative said the cash index traded an 87 basis point range. It said a block of 15,000 same-day 7,780 calls held long by dealers was pushed through around 3:00 PM ET, and that the 7,800 ceiling and a secondary dealer-positioning level at 7,720 framed the high and low of the day. The provider's quote gives the cash extremes as 7,794.35 and 7,727.59. The futures high came in the 3:00 PM ET bar. The two coincide in time only. The note also said fixed-strike implied volatilities on the index rose 1 to 2 points over the week, with implied volatility near the low end of its three-month range.
Then the note's own map. It lists resistance at 7,750 and 7,800 and support at 7,690, 7,600 and 7,400, with key strikes at 8,000, 7,000, 7,700 and 7,800, all in cash. Its highest-conviction combination levels are 7,800 (99.44), 7,900 (99.17), 8,001 (99.15), 7,846 (99.08), 8,101 (99.05), 8,047 (98.79), 7,754 (98.60) and 7,823 (98.53). Scores run from 98.53 to 99.44. The largest gamma concentration sits at 8,000, the primary call-side ceiling at 7,800 and the primary put-side support base at 7,500.
The note's reference column is Friday's close. Its 7,722 cash reference equals Friday's 7,722.72 close, and 7,722 plus the note's stated 0.7 percent gain approximates the 7,774 close it reports, against the provider's 7,773.95. Every futures figure in the note is its cash figure plus 54.8 points, the source's own offset, so cash equivalents here use the 52.30 basis measured Monday. The implied one-day move is 0.62 percent and the five-day move 1.55 percent. Applied to the 7,773.95 cash close, the one-day figure spans 7,725.75 to 7,822.15. The note's own pair of 7,678.74 and 7,774.56 is centred on neither close, so it is not used as a range anchor.
Volatility barely moved. The volatility index closed at 15.52, up 0.21, and the note gave its own volatility gauge at 85.46. Crude fell 1.84 percent. November crude settled at 89.43, and December gold eased 0.13 percent to 4,156.8.
Headlines came late. Between 3:21 PM ET and 3:31 PM ET the President said he was always open to direct talks with Iran and that a specific threat had prompted bombers to be withdrawn from a base in the United Kingdom. Two more items followed. At 3:38 PM ET the news feed carried a Treasury notice that foreign banks may be sanctioned for business with Iran. At 4:12 PM ET it carried a Houthi statement claiming three military operations in Saudi Arabia, with no Saudi confirmation. These are statements carried by the news feed, not events confirmed for this session.
Activity fell. Volume was 1,274,587 contracts on Monday's dated row against 1,859,407 on Friday's. Open interest reads 1,889,967 on Monday's row, up from 1,888,645 on Friday's. The latest weekly futures positioning report is the one as of September 29, 2026. It shows asset managers long 1,104,434 contracts against short 200,431, and leveraged funds long 125,453 against short 497,942.
The trade map for Tuesday
The primary setup is a long from 7,804 to 7,812. Monday was the third consecutive higher settle and the highest since 09/22, and the contract sits above every settlement average from the 5-day to the 200-day. The cash close sits above the reference level, the modeled volatility threshold and the modeled gamma-flip level, with positive index gamma notional. The band sits around the pivot. A pullback into it would meet the 7,811.33 Pivot Point and the 7,811.00 high of the 10:00 AM ET bar. The stop sits at 7,774, 1.17 points beneath Pivot S1 at 7,775.17 and 0.80 beneath the 7,774.80 threshold pair. The targets step up: 7,842, then 7,876, then an extended 7,910. The composite read is only 56 percent buy with soft strength and the 7,800 ceiling in cash sits just above the cash close, so the review labels the setup an analyst judgment that the positioning backdrop outweighs a soft trend signal.
From the 7,808 midpoint the risk to the stop is 34 points, 43.4 percent of the 14-day average true range of 78.31. The targets sit 34, 68 and 102 points above that midpoint. Exact multiples of the risk. The settle sits 14.25 points above the top of the band, and the review frames the entry as a pullback into it. A one-range frame from the settle spans 7,747.94 to 7,904.56. It holds the band, the stop and the first two targets. The extended 7,910 sits 5.44 points beyond its top. The published one-deviation band, 7,779.82 to 7,872.68, starts 5.82 points above the stop, and the second target sits 3.32 points above its upper edge.
The scenario ranges are analyst judgment. None carries a calibration. The low-range case runs 7,795 to 7,850, the most likely 7,775 to 7,873 and the high-range case 7,748 to 7,905. Session by session the review expects roughly 7,805 to 7,850 through Globex, with a constructive bias above the 7,811.33 Pivot Point, and 7,795 to 7,845 through London, with a neutral to constructive bias. The morning band is 7,795 to 7,860 and the afternoon 7,800 to 7,870 into the 4:00 PM ET settle.
The night comes first. Globex reopened at 6:00 PM ET Monday after the after-hours financing report and the Gulf headlines. German industrial orders are listed at 2:00 AM ET, per the news-feed calendar and unconfirmed. Monday's overnight hours through the 2:30 AM ET bar held a 7,764.00 to 7,793.00 band. Quiet, recently.
Europe brings two items. The United Kingdom construction survey is listed at 4:30 AM ET and euro-area retail sales at 5:00 AM ET, both per the news-feed calendar and unconfirmed. Monday's session low printed in the 6:30 AM ET bar, so the European morning carried the most recent selling.
Then the United States morning. The trade balance is scheduled for 8:30 AM ET, as the calendar lists it. A regional Federal Reserve president is listed at 9:05 AM ET, per the news-feed calendar and unconfirmed, and the Vice Chair for Supervision speaks at 10:45 AM ET, as the calendar lists it. The cash open at 9:30 AM ET is the first directional test, and the 7,847.50 to 7,854.80 band is the first barrier. The short-term energy outlook follows at 12:00 PM ET, as the calendar lists it.
The auction is the event. A three-year note auction is listed at 1:00 PM ET and a regional Federal Reserve president at 1:15 PM ET, both per the news-feed calendar and unconfirmed. In the review's judgment the auction is the single first-order event for the S&P 500 on Tuesday, because the ten-year yield closed near a 24-year high per provider commentary. It reaches the index through yields. Another regional president is listed at 7:00 PM ET, per the news-feed calendar and unconfirmed. The minutes of the September policy meeting follow at 2:00 PM ET on October 7, 2026, and the next consumer price report at 8:30 AM ET on October 14, 2026, both as the calendar lists them. Bank earnings begin on October 13, 2026, as the calendar lists it, and the captured calendars carry no mega-capitalisation earnings entry for Tuesday.
One path is weighted. In this review's analyst judgment the most probable path holds the contract above the 7,811.33 Pivot Point with a test of the 7,847.50 to 7,854.80 band, where positive dealer gamma beneath the 7,800 ceiling in cash favours mean reversion over a clean break. A return to the 7,775.17 to 7,779.82 pairing of Pivot S1 and one standard deviation support is weighted above an extension to Pivot R1 at 7,862.42. The reason given is a soft composite. It reads only 56 percent buy with soft strength, and the directional system is close to balanced. No measured frequency backs it. The alternative that would invalidate this reading is a yield spike around the 1:00 PM ET auction that takes the cash index back beneath 7,720.
Monday's survey bar topped out at 7,811.00, and Tuesday's long band tops out 1.00 point above it.
The complete data picture
Every number behind Tuesday’s plan, charted first, then the full level lists, then the complete numeric reference underneath.
Full numeric reference, every remaining figure from the session review
1. Executive Summary
The December S&P 500 contract settled at 7,826.25 on Monday, up 49.00 points or 0.63 percent from Friday's 7,777.25 settle, after trading between 7,847.50 and 7,760.25, an 87.25 point daily range. The settle finished at 75.6 percent of the range, and the 87.25 point range was 1.04 times the published 14-day average daily range of 83.77 points, the widest since the 95.00 point range of 10/01. Monday was the third consecutive higher settle and the highest settle since the 7,831.75 settle of 09/22, and the 7,847.50 high was the highest since the 7,848.50 high of 09/22. Against Friday, Monday printed a higher high and a higher low.
The preserved 30-minute series fixes the order. The contract reached 7,793.00 in the 9:30 PM ET Sunday bar, drifted lower to the 7,760.25 session low in the 6:30 AM ET bar, and then rose from the 9:30 AM ET cash open, with the 10:00 AM ET bar reaching 7,811.00. The advance continued in steps to the 7,847.50 session high in the 3:00 PM ET bar, and the 3:30 PM ET bar traded back to 7,821.00 before the close. The positioning note said the S&P 500 cash index traded an 87 basis point range and that a large same-day call position at 7,780 in cash was pushed through around 3:00 PM ET, and provider commentary said the index climbed to a 1.5-month high on strength in the largest technology companies and on merger activity.
The S&P 500 cash index closed at 7,773.95, up 51.23 points or 0.66 percent, per the provider's quote, which gives the cash session's extremes as 7,794.35 and 7,727.59. The services survey from the purchasing managers' institute, released at 10:00 AM ET, printed 54.9 against a 55.0 forecast, per the news-feed calendar, and provider commentary said its prices-paid component rose to a four-year high of 74.0. The ten-year yield index closed four basis points higher at 5.31 percent and the dollar index 0.24 percent higher at 102.17, while the volatility index closed at 15.52.
The cash close sits above the positioning note's reference level at 7,690 in cash, the modeled volatility threshold at 7,720 in cash and the modeled gamma-flip level at 7,677 in cash, and 26.05 points beneath the primary call side ceiling at 7,800 in cash. The primary setup is a long from the 7,804 to 7,812 band around the 7,811.33 Pivot Point, stopped at 7,774 beneath Pivot S1 at 7,775.17, with objectives at 7,842, 7,876 and an extended 7,910.
2.1 Intraday and Session Review
The Monday session opened at 7,781.50 at the Sunday 6:00 PM ET reopen, 4.25 points above Friday's settle, marked a daily high of 7,847.50 and a daily low of 7,760.25, and settled at 7,826.25. The preserved 30-minute provider series, 46 bars from the reopen through the 4:30 PM ET bar, places the low in the 6:30 AM ET bar and the high in the 3:00 PM ET bar.
The Asian hours were quiet. The contract held between 7,780.75 and 7,793.00 from the 6:00 PM ET bar through the 10:00 PM ET bar, reaching the 7,793.00 overnight high in the 9:30 PM ET bar. The 10:30 PM ET bar fell to 7,777.50 and the contract eased through the night, holding between 7,760.50 and 7,779.25 from the 11:00 PM ET bar through the 6:00 AM ET bar. The 6:30 AM ET bar printed the 7,760.25 session low and closed at 7,771.00, and from the 7:00 AM ET bar through the 9:00 AM ET bar the contract held between 7,764.75 and 7,782.75.
The cash open changed the session. The 9:30 AM ET bar rose from 7,778.50 to 7,791.25, and the 10:00 AM ET bar, which contained the services survey, rose to 7,811.00 and closed at 7,808.00. The contract then advanced in small steps: the 10:30 AM ET bar held between 7,798.00 and 7,810.25, the 11:30 AM ET bar reached 7,816.25, the 12:30 PM ET bar 7,827.00, the 1:30 PM ET bar 7,831.50, the 2:00 PM ET bar 7,835.25 and the 2:30 PM ET bar 7,838.25. The 3:00 PM ET bar printed the 7,847.50 session high and closed at 7,842.25, and the 3:30 PM ET bar traded back to 7,821.00 before closing at 7,831.25.
After the cash close, electronic trade held between 7,828.25 and 7,832.50 in the 4:00 PM ET and 4:30 PM ET bars, and the 4:30 PM ET bar closed at 7,830.00. The Tuesday session reopened at 6:00 PM ET Monday; the provider's day open, high and low of 7,831.75, 7,836.25 and 7,831.50 shown at the time of writing belong to that new session, not to Monday.
The session extremes used here are the completed-session inputs behind the published pivot ladder rather than an independently read bar, back-solved from the outer pivot pairs and verified against every rung. The third resistance point at 7,949.67 minus the third support point at 7,687.92, divided by three, returns 87.25, and the second resistance point at 7,898.58 minus the second support point at 7,724.08, divided by two, returns the same 87.25. Three times the Pivot Point of 7,811.33 less the 7,826.25 settle gives a high plus low sum of 15,607.74, one hundredth from the 15,607.75 of the solved pair because the published pivot is rounded, and the pair of 7,847.50 and 7,760.25 reproduces all seven published rungs. Independent corroboration: the provider's settlement row, the chart's completed Monday daily bar and the highest and lowest bars of the 30-minute series carry the same high and low.
2.2 Daily Structure
Monday printed a higher high and a higher low against Friday: the 7,847.50 high sits 37.25 points above Friday's 7,810.25, and the 7,760.25 low sits 37.00 points above Friday's 7,723.25. The sequence of session highs over the last six sessions reads 7,803.00, 7,770.75, 7,782.00, 7,767.75, 7,810.25 and 7,847.50, and the sequence of session lows reads 7,726.00, 7,712.25, 7,705.50, 7,672.75, 7,723.25 and 7,760.25.
The prior week, September 28 through October 2, spanned 7,810.25 to 7,672.75, and Monday's high cleared it. The one-month high of 7,848.50 from 09/22 sits 22.25 points above the settle, and the 52-week high of 7,905.00 from 08/13 sits 78.75 points above it.
No prior-quarter high or low was captured for this session, so the 13-week extremes serve as the available quarterly reference.
2.3 4-Hour and Swing Structure
Settlements over the last six sessions ran 7,746.75, 7,732.00, 7,715.50, 7,724.00, 7,777.25 and 7,826.25, so the three declines that followed the 09/25 settle of 7,803.75 have been more than recovered. Daily ranges for the last seven sessions ran 66.25, 77.00, 58.50, 76.50, 95.00, 87.00 and 87.25.
The retracement grid published for Tuesday places the 38.2 percent retracement from the four-week high at 7,744.02 and the 50 percent retracement of the four-week range at 7,711.75. No four-hour series was captured for this session; the 30-minute series in section 2.1 is the only intraday evidence used.
2.4 Moving Averages
The averages cited in this subsection were computed from the provider's daily settlement series for the December contract, which holds 259 completed sessions through Monday. The 5-day average stands at 7,755.00, the 9-day at 7,762.78, the 20-day at 7,738.51, the 50-day at 7,743.81, the 100-day at 7,672.44 and the 200-day at 7,364.13.
The 7,826.25 settle sits 71.25 points above the 5-day average, 63.47 above the 9-day, 87.74 above the 20-day, 82.44 above the 50-day, 153.81 above the 100-day and 462.12 above the 200-day. The 5-day average rose 15.90 points from Friday's 7,739.10, because the 09/28 settle of 7,746.75 left the window and was replaced by 7,826.25. The 9-day fell 0.61 points from 7,763.39 as the 09/22 settle of 7,831.75 left its window, and the 20-day rose 1.85 points from 7,736.66 as the 09/04 settle of 7,789.25 left.
The 9-day average sits 7.78 points above the 5-day because the four settlements from 09/23 to 09/28 that sit in the 9-day window but not the 5-day averaged 7,772.50, higher than the latest five. The projection grid gives the prices at which each average would be crossed on Tuesday: 7,761.56 for the 9-day, 7,744.06 for the 18-day and 7,763.09 for the 40-day.
2.5 Oscillator and Trend Readings
The oscillator figures below are as published on the provider's technical page dated for the Tuesday session, read after the 6:00 PM ET reopen; the page may carry the live Globex price rather than the settle, so they are quoted as published. Relative strength reads 61.63 on the 9-day, 57.62 on the 14-day and 55.85 on the 20-day.
The 9-day raw stochastic reads 87.84 percent and the 14-day 91.86 percent, with the 14-day %K at 73.43 percent and %D at 62.59 percent.
The directional system is close to balanced. On the 9-day the directional index reads 15.73 with positive direction at 22.16 and negative direction at 18.73; on the 14-day it reads 12.52 with positive direction at 21.02 against negative at 20.28. Historic volatility reads 8.03 percent on the 9-day and 10.15 percent on the 14-day.
The composite multi-indicator read published for the Tuesday session is 56 percent buy, up from 16 percent buy in the prior session's snapshot, with signal strength described as soft and direction as strongest. The snapshot history reads 48 percent buy a week ago and 64 percent buy a month ago. The short-horizon group averages 40 percent buy, the medium-horizon group 75 percent buy and the long-horizon group 67 percent buy, and the composite trend indicator reads hold.
2.6 Volatility and Expected Range
The published 14-day average true range stands at 78.31 points and the 14-day average daily range at 83.77 points; the 9-day figures are 79.56 and 78.69, and the 20-day figures 78.27 and 79.06. Monday's 87.25 point range was 1.04 times the 14-day average daily range.
Adding and subtracting the 14-day average true range of 78.31 points to and from the 7,826.25 settle frames Tuesday between 7,747.94 and 7,904.56. The published standard-deviation bands are narrower because they are built from five settlements: one deviation spans 7,779.82 to 7,872.68, two spans 7,760.59 to 7,891.91 and three spans 7,745.84 to 7,906.66. These bands describe settlement dispersion, not intraday reach.
3.1 Resistance
The settle at 7,826.25 sits beneath the 7,847.50 Monday high in the 3:00 PM ET bar and the 7,848.50 one-month high from 09/22, with the target price published for Tuesday at 7,851.92 and the source futures pair for the primary call side ceiling, 7,854.80 for 7,800 in cash, just above them. Pivot R1 at 7,862.42 and one standard deviation resistance at 7,872.68 come next, followed by two standard deviations resistance at 7,891.91 and Pivot R2 at 7,898.58. The 52-week high of 7,905.00 and three standard deviations resistance at 7,906.66 sit 1.66 points apart, with Pivot R3 at 7,949.67 the extended reference.
3.2 Support
Beneath the settle, the 3:30 PM ET pullback low at 7,821.00 and the Pivot Point at 7,811.33 are the first references. One standard deviation support at 7,779.82, Pivot S1 at 7,775.17 and the source futures pair for the modeled volatility threshold, 7,774.80 for 7,720 in cash, sit within 5.02 points of each other. The 7,760.25 Monday low in the 6:30 AM ET bar and two standard deviations support at 7,760.59 follow, then the 5-day settlement average at 7,755.00. The source futures pair for the positioning note's reference level, 7,744.80 for 7,690 in cash, sits beside the 38.2 percent retracement from the four-week high at 7,744.02, and the source futures pair for the modeled gamma-flip level, 7,731.80 for 7,677 in cash, and Pivot S2 at 7,724.08 are the deeper references, with the primary put side support base at 7,554.80 for 7,500 in cash.
4.1 Dollar, Rates, and Fed Policy
The services survey at 10:00 AM ET printed 54.9 against a 55.0 forecast and 55.4 previously, with its employment component at 50.1 against 48.8, per the news-feed calendar. Provider commentary said the prices-paid component rose 1.4 points to 74.0, a four-year high, that the ten-year Treasury yield touched a 24-year high during the session, and that services price pressure limited stock gains. The ten-year yield index closed at 5.31 percent, up four basis points, and the dollar index rose 0.24 percent to 102.17, a 1.5-year high per provider commentary; a news-feed article at 11:45 AM ET tied the dollar's move to French debt concerns. Investment-bank commentary on the news feed said the September employment data point to less urgency for further hikes. The minutes of the September policy meeting are scheduled for 2:00 PM ET on October 7, 2026, as the calendar lists it.
4.2 Large-Cap Leadership and Earnings
The positioning note said the largest technology companies outperformed, with the fund that tracks them up 1 percent, and that the Nasdaq-100 set a record high. Provider commentary cited merger activity, with a European electrical-equipment maker agreeing to buy an industrial software company for 22.6 billion dollars and a freight brokerage agreeing to buy a trucking logistics company for 5.8 billion dollars. After the close, press reports carried by the news feed at 5:00 PM ET said banks launched a record 60 billion dollar financing for a large chipmaker and an artificial-intelligence developer. The captured calendars carry no mega-capitalisation earnings entry for Tuesday; bank earnings begin on October 13, 2026, as the calendar lists it.
4.3 Geopolitical Backdrop
The news feed carried a Treasury notice at 3:38 PM ET that foreign banks may be sanctioned for business with Iran, and at 4:12 PM ET a Houthi statement claiming three military operations in Saudi Arabia, with no Saudi confirmation. Between 3:21 PM ET and 3:31 PM ET the President said he was always open to direct talks with Iran and that a specific threat had prompted bombers to be withdrawn from a base in the United Kingdom. These are statements carried by the news feed rather than events confirmed for this session.
4.4 Sector Breadth and Rotation
The Nasdaq-100 cash index rose 0.87 percent against 0.66 percent for the S&P 500 and 0.18 percent for the Dow industrials, and the semiconductor index rose 0.27 percent, so leadership came from the largest technology names rather than from chipmakers broadly. The positioning note said a Brazil equity fund rose 12 percent on election results. No advance-decline or sector breadth series was captured for this session, so breadth beyond those index readings is not asserted.
4.5 Cross-Asset and Volatility
The volatility index closed at 15.52, up 0.21, per the provider's quote, and the positioning note gave its own volatility gauge at 85.46. The positioning note said fixed-strike implied volatilities on the index rose 1 to 2 points over the week, with implied volatility near the low end of its three-month range. November crude fell 1.84 percent to 89.43 and December gold eased 0.13 percent to 4,156.8. The closing basis, the December settlement less the cash close, is 7,826.25 less 7,773.95, or 52.30 points.
4.6 Institutional Positioning
The positioning note said real-time hedging flow on the S&P 500 registered plus 13 billion dollars of delta on the day, mainly from same-day call buying, and described it as a momentum play rather than longer-term position building. The latest positioning report on the provider's overview is the one as of September 29, 2026, with asset managers long 1,104,434 contracts against short 200,431 and leveraged funds long 125,453 against short 497,942. Open interest reads 1,889,967 on the settlement row for Monday, up from 1,888,645 on Friday.
5. Index Options Flow Context
The positioning note used for this section is the 5:32 PM ET edition for Monday. Its reference column holds the prior session's closes, not Monday's: its 7,722 cash reference equals Friday's 7,722.72 cash close, and 7,722 plus the note's stated 0.7 percent gain approximates the 7,774 close it reports, against the provider's 7,773.95. The note's futures column equals the cash figure plus 54.8 on every row, the source's offset rather than the 52.30 point basis measured for this session.
The note's dealer-positioning reference level is 7,690 in cash, bearish beneath and bullish above, and the cash close sits 83.95 points above it. The modeled volatility threshold is 7,720 in cash (source pair 7,774.80) and the modeled gamma-flip level 7,677 in cash (source pair 7,731.80), so the close sits 53.95 points above the threshold and 96.95 above the flip. The largest gamma concentration is 8,000 in cash (source pair 8,054.80), the primary call side ceiling 7,800 in cash (7,854.80) and the primary put side support base 7,500 in cash (7,554.80). The note lists cash resistance at 7,750 and 7,800 and cash support at 7,690, 7,600 and 7,400, and key strikes at 8,000, 7,000, 7,700 and 7,800 in cash. Among the combination levels the highest conviction scores sit at 7,800 (99.44), 7,900 (99.17), 8,001 (99.15), 7,846 (99.08), 8,101 (99.05), 8,047 (98.79), 7,754 (98.60) and 7,823 (98.53).
The gamma index reads 2.272 and gamma tilt 1.19, while the index gamma notional reads plus 619.60 million dollars and the largest S&P 500 exchange-traded fund's minus 230.179 million dollars. The 25-delta risk reversal on the index reads minus 0.036. Index put volume of 1.018 million contracts exceeded call volume of 695,544, and put open interest of 13.126 million exceeds call open interest of 9.252 million. The implied one-day move is 0.62 percent and the implied five-day move 1.55 percent; applied to the 7,773.95 cash close, the one-day figure spans 7,725.75 to 7,822.15 in cash. The note's own implied-move pair of 7,678.74 and 7,774.56 is centred on neither close, so it is not used as a range anchor.
The note's narrative said a block of 15,000 same-day 7,780 cash-index calls held long by dealers was pushed through around 3:00 PM ET, and that the primary call side ceiling at 7,800 in cash and a secondary dealer-positioning level at 7,720 in cash framed the high and low of the day; the provider's quote gives the cash extremes as 7,794.35 and 7,727.59. The cash-index console shows call gamma of 6.9 billion against put gamma of minus 3 billion and attributes 6.98 percent of the index's gamma and 0.75 percent of its delta to the nearest expiration; its high and low volatility point fields are excluded as low-confidence.
In this review's interpretation the close above the reference level, the modeled volatility threshold and the modeled gamma-flip level, with the index gamma notional positive and the gamma index higher, places the index inside the supportive, mean-reverting part of its positioning map for Tuesday, with the 7,800 cash ceiling the first barrier and the negative notional on that fund leaving room for wider moves if 7,720 in cash gives way.
6.1 Night Session (6:00 PM ET Monday to 3:00 AM ET Tuesday, Globex and Asia)
The contract reopened at 6:00 PM ET Monday after the after-hours financing report and the Gulf headlines. German industrial orders are listed at 2:00 AM ET, per the news-feed calendar and unconfirmed. Monday's overnight hours through the 2:30 AM ET bar held a 7,764.00 to 7,793.00 band, so the night session has recently been quiet. Bias constructive above the 7,811.33 Pivot Point, expected Globex band roughly 7,805 to 7,850.
6.2 London Session (3:00 AM ET to 8:00 AM ET Tuesday)
The United Kingdom construction survey is listed at 4:30 AM ET and euro area retail sales at 5:00 AM ET, both per the news-feed calendar and unconfirmed. Monday's session low printed in the 6:30 AM ET bar, so the European morning carried the most recent selling. Bias neutral to constructive, expected band roughly 7,795 to 7,845.
6.3 Morning Session (9:30 AM ET to 12:00 PM ET Tuesday, regular trading hours open)
The trade balance is scheduled for 8:30 AM ET, as the calendar lists it. A regional Federal Reserve president is listed at 9:05 AM ET, per the news-feed calendar and unconfirmed, and the Vice Chair for Supervision speaks at 10:45 AM ET, as the calendar lists it. The cash open at 9:30 AM ET is the first directional test; the 7,847.50 to 7,854.80 band, Monday's high and the call side ceiling pair, is the first barrier. Expected band roughly 7,795 to 7,860.
6.4 Afternoon Session (12:00 PM ET to 4:00 PM ET Tuesday)
A three-year note auction is listed at 1:00 PM ET and a regional Federal Reserve president at 1:15 PM ET, both per the news-feed calendar and unconfirmed. The auction reaches the index through yields. Expected band roughly 7,800 to 7,870.
6.5 Night Session Forward (6:00 PM ET Tuesday)
A regional Federal Reserve president is listed at 7:00 PM ET Tuesday, per the news-feed calendar and unconfirmed. The minutes of the September policy meeting follow at 2:00 PM ET on October 7, 2026, as the calendar lists it.
6.6 Expected Range (Tuesday Full Session)
Low-range scenario: 7,795 to 7,850
Mid-range scenario (most likely): 7,775 to 7,873
High-range scenario: 7,748 to 7,905
6.7 Most Likely Path
In this review's analyst judgment the most probable path holds the contract above the 7,811.33 Pivot Point with a test of the 7,847.50 to 7,854.80 band, where positive dealer gamma beneath the 7,800 cash ceiling favours mean reversion rather than a clean break. A return to the 7,775.17 to 7,779.82 pairing of Pivot S1 and one standard deviation support is weighted above an extension to Pivot R1 at 7,862.42, because the composite read is only 56 percent buy with soft strength and the directional system is close to balanced. The alternative that would invalidate this reading is a yield spike around the 1:00 PM ET auction that takes the cash index back beneath 7,720 in cash.
7. Tuesday Economic Calendar
The Tuesday session reopened at 6:00 PM ET Monday. German industrial orders are listed at 2:00 AM ET, the United Kingdom construction survey at 4:30 AM ET and euro area retail sales at 5:00 AM ET, all per the news-feed calendar and unconfirmed.
The United States morning carries the trade balance at 8:30 AM ET, as the calendar lists it, a regional Federal Reserve president at 9:05 AM ET, per the news-feed calendar and unconfirmed, the cash open at 9:30 AM ET and the Vice Chair for Supervision at 10:45 AM ET, as the calendar lists it. The short-term energy outlook is scheduled for 12:00 PM ET, as the calendar lists it. A three-year note auction is listed at 1:00 PM ET, a regional Federal Reserve president at 1:15 PM ET and another at 7:00 PM ET, all per the news-feed calendar and unconfirmed. The captured calendars carry no mega-capitalisation earnings entry for Tuesday.
In this review's judgment the single first-order event for the S&P 500 on Tuesday is the 1:00 PM ET three-year note auction, per the news-feed calendar and unconfirmed, because the ten-year yield closed near a 24-year high per provider commentary. The minutes of the September policy meeting follow at 2:00 PM ET on October 7, 2026, as the calendar lists it, and the next consumer price report at 8:30 AM ET on October 14, 2026, as the calendar lists it.
8. Primary Trade Setup
Direction: Long
Rationale: Monday was the third consecutive higher settle and the highest settle since 09/22, the contract sits above every settlement average from the 5-day to the 200-day, and the cash close sits above the reference level, the modeled volatility threshold and the modeled gamma-flip level with positive index gamma notional; a pullback into the Pivot Point offers a long with a defined risk point beneath Pivot S1 at 7,775.17. The composite read is only 56 percent buy and the 7,800 cash ceiling sits just above the cash close, so the setup is an analyst judgment that the positioning backdrop outweighs a soft trend signal.
Entry Zone: 7,804 to 7,812 (cash 7,751.70 to 7,759.70)
Stop Loss: 7,774 (cash 7,721.70; beneath Pivot S1 at 7,775.17 and the 7,774.80 source pair for the modeled volatility threshold)
Target 1 (T1): 7,842 (cash 7,789.70; 5.50 beneath the 7,847.50 Monday high)
Target 2 (T2): 7,876 (cash 7,823.70; 3.32 above one standard deviation resistance at 7,872.68)
Target 3 (T3, extended): 7,910 (cash 7,857.70; 3.34 above three standard deviations resistance at 7,906.66)
Risk-to-Reward: Approximately 1:1 to T1, 1:2 to T2, 1:3 to T3
Invalidation: A settle beneath Pivot S1 at 7,775.17 negates the thesis. Short of that, the edge is removed by acceptance beneath 7,790 rather than by a touch, defined as two consecutive 30-minute closes beneath 7,790.
Macro override: A yield spike after the 1:00 PM ET auction, a reversal in the large technology names, or a Gulf escalation would turn the index lower. In that scenario the long is wrong immediately, and the 7,760.25 Monday low and the 7,744.80 reference-level pair become the references within one 14-day average true range of 78.31 points.
Sources and methodology
This outlook is built from our session review of the December E-mini S&P 500 contract, the December ’26 contract, prepared after Monday's close on October 5, 2026 for the Tuesday, October 6, 2026 session. Monday's completed extremes are recovered from the published pivot ladder: Pivot R3 at 7,949.67 less Pivot S3 at 7,687.92, divided by three, and Pivot R2 at 7,898.58 less Pivot S2 at 7,724.08, divided by two, both return 87.25, and three times the 7,811.33 Pivot Point less the settle gives a high-plus-low sum of 15,607.74, one hundredth from the 15,607.75 of the solved pair of 7,847.50 and 7,760.25, which reproduces all seven published rungs. The provider's dated row agrees at 7,781.50, 7,847.50, 7,760.25 and 7,826.25, on volume of 1,274,587 contracts and open interest of 1,889,967. It is a second surface of the same vendor, so it confirms internal consistency and not the underlying quote. That row, together with the preserved 30-minute series of 46 bars, is the only evidence used to grade Monday's card. Friday's row now reads volume of 1,859,407 and open interest of 1,888,645, revised figures that replace the 1,763,233 volume carried on Monday's outlook and fill its open interest, which had not been reported; that post was not changed.
The contract domain was checked before any level was used: the daily chart's current Tuesday bar and its stated change return a prior close of 7,826.25, equal to the provider's published previous close, and the chart's completed Monday bar equals the provider's settlement row. The Globex session reopened at 6:00 PM ET Monday, so the overview page's day high, day low and open belong to the Tuesday session and are not used as Monday's range. The moving averages were computed from the 259-row daily settlement series; the oscillators are cited as published for the Tuesday session. The positioning note used is the 5:32 PM ET edition for Monday, October 5, and its cash levels are quoted as published. Its reference column is the prior session's close and its futures column a fixed 54.8 translation, so any cash equivalent given here uses the 52.30 basis measured this session, settlement against cash close. The cash index extremes and the other cross-asset closes come from the provider's quote read at about 6:30 PM ET. The cash-index console's high and low volatility point fields are excluded as low-confidence, and modeled thresholds are never called strikes. Scenario ranges are analyst judgment. Items marked unconfirmed come from the news-feed calendar or press reports. Every catalyst whose release time had passed at the time of writing is recorded as completed.
Monday’s outlook for this contract is here, and the Nasdaq-100 contract's Monday outlook covers the index that rose 0.87 percent in cash on Monday. Outlooks for ES, NQ, GC and CL are collected on the market outlook page, and our forward trading record is on the performance statement.