Monday's settle never traded again on Tuesday. The December S&P 500 contract opened at 7,831.75 at the Monday 6:00 PM ET reopen, 5.50 points above Monday's 7,826.25 settle, and its 7,829.00 low stopped 2.75 points above that settle. The high reached 7,897.50. That was the highest print since the 7,898.00 high of 08/14, half a point away. No intraday series was preserved for the session, so the daily bar cannot say which extreme printed first.
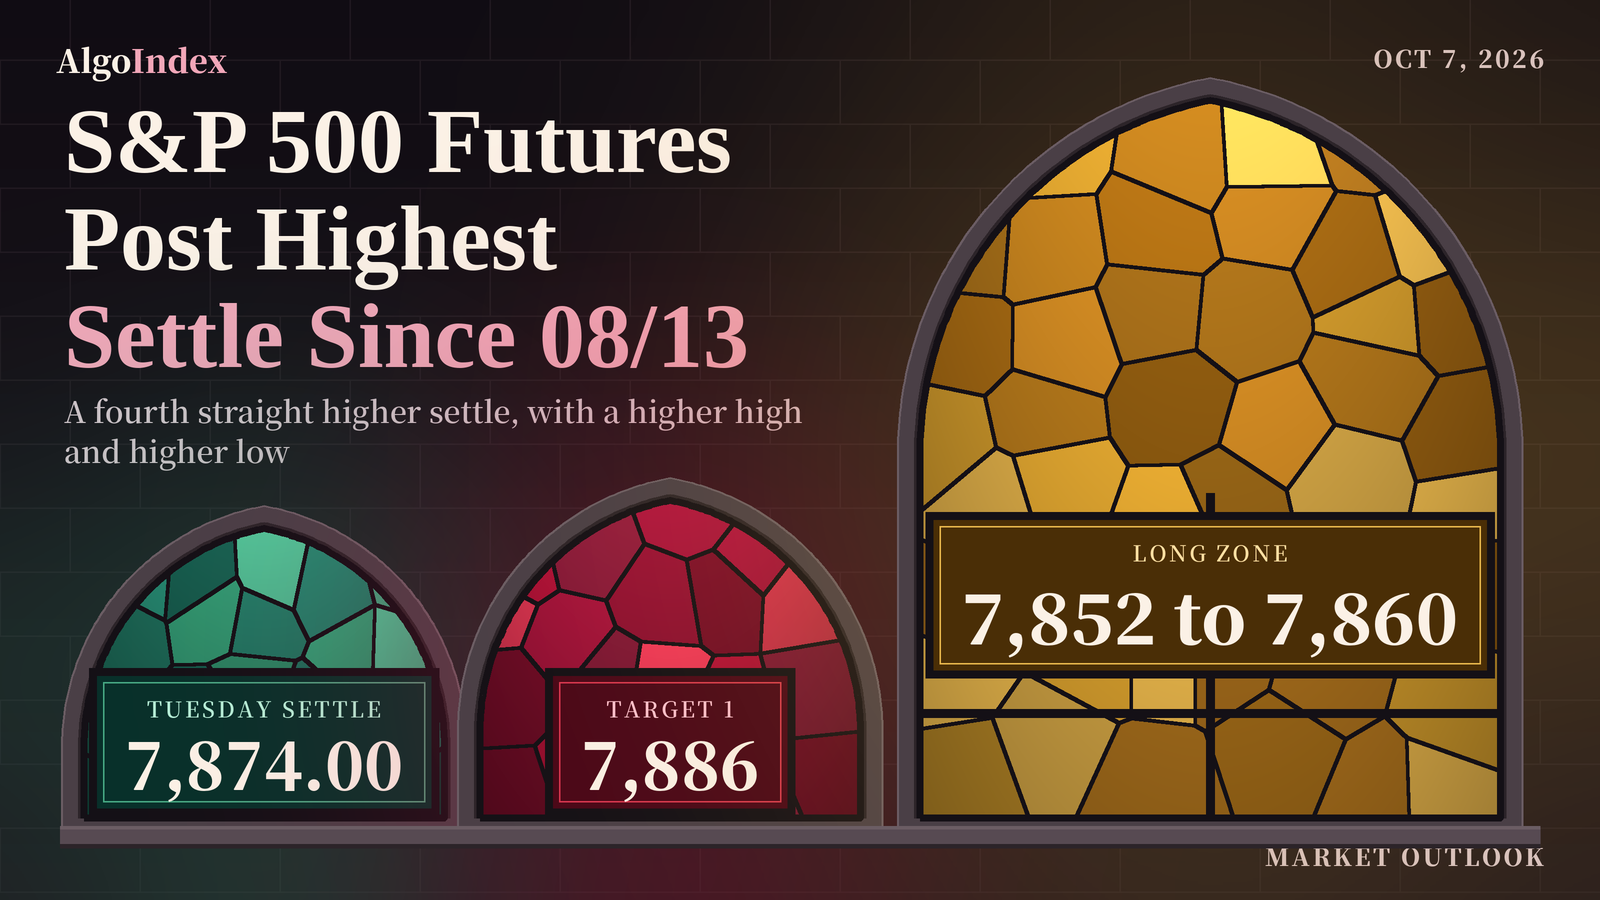
December E-mini futures settled at 7,874.00, up 47.75 points or 0.61 percent from Monday's 7,826.25. The daily row spans 7,897.50 to 7,829.00, a 68.50 point range, 0.86 times the 14-day average daily range of 79.80 points and the narrowest since the 58.50 point range of 09/29. Four higher settles in a row. Tuesday's was the highest settle since the 7,889.25 settle of 08/13, and it finished at 65.7 percent of the range. The cash index closed at 7,818.93, up 0.58 percent. The news feed called it a record close at 4:02 PM ET, the first since August 13.
December S&P 500 futures settled at 7,874.00, 7.17 points above the 7,866.83 Pivot Point and above every settlement average from the 5-day to the 200-day. The primary setup is a long from 7,852 to 7,860 around the 7,852.10 source pair of the 7,800 call-side ceiling in cash, stop 7,826 beneath Pivot S1 at 7,836.17, Tuesday's 7,829.00 low and Monday's 7,826.25 settle, targets 7,886, 7,916 and an extended 7,946. A tight band sits overhead. Tuesday's 7,897.50 high, the 7,904.11 stall price, Pivot R1 at 7,904.67 and the 7,905.00 52-week high span 7.50 points. The cash index closed 18.93 points above the 7,800 ceiling, 73.93 above the 7,745 modeled volatility threshold, 128.93 above the 7,690 reference level and 148.93 above the 7,670 modeled gamma-flip level. Wednesday's first-order event is the 2:00 PM ET release of the September policy meeting minutes, as the calendar lists it.
Tuesday's long band stayed untouched beneath a 7,829.00 low
Tuesday's outlook set a long from 7,804 to 7,812, stop 7,774, targets 7,842, 7,876 and an extended 7,910. Tuesday's completed bar, from tonight's review and the provider's dated 2026-10-06 row, opened at 7,831.75 at the Monday 6:00 PM ET reopen, marked a high of 7,897.50 and a low of 7,829.00, and settled at 7,874.00. The two sources agree. Price never reached the band. The low stopped 17.00 points above its 7,812 top, and the 7,774 stop sat 55.00 points beneath that low.
Above, the range covered two of the three target levels. The 7,842 first target level and the 7,876 second both sat inside the day's range, and the high cleared them by 55.50 and 21.50 points. The extension missed. The 7,910 level sat 12.50 points above the 7,897.50 high, so it did not trade.
The order is not on record. No intraday series was preserved for Tuesday, so the daily bar cannot show when either target level traded or which extreme printed first. Here it changes nothing. With the entry band untouched, no fill and no result is asserted.
Neither invalidation test triggered. The card named a settle beneath Pivot S1 at 7,775.17, and the 7,874.00 settle finished 98.83 points above it. Its acceptance line needed two consecutive 30-minute closes beneath 7,790. The session low sat 39.00 points above that line, so no close could print beneath it.
Our top edges sat too low for a second day. In Tuesday's outlook we gave 7,775 to 7,873 as the most likely band. The low held inside it, 54.00 points above its bottom, while the high cleared its top by 24.50 points and the settle by 1.00. The low-range case of 7,795 to 7,850 broke by 47.50 at the top. The wider frames held. The high-range case of 7,748 to 7,905 and the one-range envelope of 7,747.94 to 7,904.56 contained the whole session, with the high 7.50 and 7.06 points beneath their tops.
Two deviation bands broke upward. The high cleared one standard deviation resistance at 7,872.68 by 24.82 points and two at 7,891.91 by 5.59, then stopped 9.16 points beneath three at 7,906.66. The settle itself finished 1.32 points above the one-deviation line. Beneath, the 7,829.00 low stayed 49.18 points above the 7,779.82 one-deviation support.
The session bands cannot be graded one by one. Tuesday's outlook gave roughly 7,805 to 7,850 for Globex, 7,795 to 7,845 for London, 7,795 to 7,860 for the morning and 7,800 to 7,870 for the afternoon. Without half-hour bars, no window's own range is known. The bar does fix two edges. The 7,897.50 high sat 27.50 points above the highest of the four tops, and the 7,829.00 low sat 24.00 points above the highest of the four bottoms. Which window carried the high is not on record.
The weighted path held in part. Tuesday's outlook weighted a hold above the 7,811.33 Pivot Point with a test of the 7,847.50 to 7,854.80 band. The low held 17.67 points above that pivot, and the high went 42.70 points through the band's top. The second leg missed. That outlook weighted a return to the 7,775.17 to 7,779.82 pairing of Pivot S1 and one standard deviation support above an extension to Pivot R1 at 7,862.42. The extension came: the high cleared 7,862.42 by 35.08 points, and the low stayed 49.18 points above the pairing.
The macro override did not trigger. It named a yield spike after the 1:00 PM ET auction, a reversal in the large technology names, or a Gulf escalation. The ten-year yield index closed five basis points lower, at 5.26 percent. Provider commentary said most of the largest technology names closed higher. The news feed called the cash close a record. We grade the card as written.
Higher on both ends again. The 7,897.50 high sat 50.00 points above Monday's 7,847.50, and the 7,829.00 low sat 68.75 points above Monday's 7,760.25. Session highs over the last six sessions read 7,770.75, 7,782.00, 7,767.75, 7,810.25, 7,847.50 and 7,897.50. The lows read 7,712.25, 7,705.50, 7,672.75, 7,723.25, 7,760.25 and 7,829.00. The prior week, September 28 through October 2, spanned 7,810.25 to 7,672.75, and Tuesday's high cleared its top by 87.25 points. Four settles added 158.50 points from the 7,715.50 settle of 09/30.
Late prints sit inside the day's range. The chart's 30-minute bars, read after the close, show trade between 7,871.75 and 7,884.00 from the 3:00 PM ET bar through the 4:30 PM ET bar, and the 4:30 PM ET bar closed at 7,880.50. Those quotes are not the settlement. The Wednesday session reopened at 6:00 PM ET Tuesday. The provider's day open, high and low of 7,881.50, 7,883.25 and 7,880.00, shown at the time of writing, belong to that new session and are not used for Tuesday.
The 7,866.83 pivot and the 7,897.50 to 7,905.00 band
The basis does the translating. Tuesday's 7,874.00 settle less the 7,818.93 cash close measures 55.07 points, against 52.30 on Monday. The positioning note uses its own fixed 52.1 offset, and its published futures pairs carry that figure. Its 7,745 modeled volatility threshold carries a source pair of 7,797.10, its 7,670 modeled gamma-flip level 7,722.10, its 7,800 call-side ceiling 7,852.10, its 7,500 put-side base 7,552.10 and its 8,000 gamma concentration 8,052.10.
Support starts close. The late bars' 7,871.75 low sits 2.25 points beneath the settle. The Pivot Point at 7,866.83 (cash 7,811.76) comes next, 7.17 points beneath the settle and 14.73 above the ceiling pair. That pair anchors the setup. The 7,852.10 source pair of the 7,800 ceiling in cash sits 0.10 points above the 7,852 bottom of the entry band, with Monday's 7,847.50 high just beneath it.
Then a dense group. The 14-3 day raw stochastic 80 percent threshold at 7,841.50, Pivot S1 at 7,836.17 (cash 7,781.10), Tuesday's 7,831.75 open, Tuesday's 7,829.00 low (cash 7,773.93) and Monday's 7,826.25 settle (cash 7,771.18) sit close together. From Pivot S1 to Monday's settle is 9.92 points. The 7,826 stop sits beneath all of them, 0.25 points under Monday's settle.
The next band is wider. The 40-day average stall price sits at 7,815.00 and the 70 percent stochastic threshold at 7,813.50. Beneath them, one standard deviation support at 7,806.51 (cash 7,751.44), Pivot S2 at 7,798.33 (cash 7,743.26), the 7,797.10 threshold pair and the 7,796.19 bottom of the one-range frame span 10.32 points. Pivot S2 and the pair sit 1.23 points apart.
Averages come next. The 5-day average sits at 7,783.40. Two standard deviations support at 7,778.55, the 7,777.25 settle of 10/02, the 9-day crossing at 7,774.94, the 38.2 percent retracement from the four-week high at 7,774.30 and the 9-day average at 7,774.06 span 4.49 points. Pivot S3 at 7,767.67 (cash 7,712.60), the 40-day crossing at 7,764.60, Monday's 7,760.25 low and three standard deviations support at 7,757.10 follow.
The tail runs lower. The 18-day crossing sits at 7,752.69, the 50-day average at 7,750.99 and the 20-day at 7,744.85. The 50 percent retracement of the four-week range sits at 7,736.25 and the 7,722.10 gamma-flip pair (cash 7,670) beneath it. The list keeps going. Further down sit the 38.2 percent retracement from the four-week low at 7,698.19, the 100-day average at 7,675.29 and the prior week's 7,672.75 low. The one-month low of 7,575.00 from 09/16, the 7,552.10 put-side base pair (cash 7,500), the 13-week low of 7,386.00 from 07/29 and the 200-day average at 7,368.63 complete the list.
Resistance starts right after the settle. The 4:30 PM ET bar closed at 7,880.50 and the late bars reached 7,884.00. Then the band that matters. Tuesday's 7,897.50 high (cash 7,842.43), the 7,898.00 high of 08/14, the 3-10 day average crossover stall price at 7,904.11, Pivot R1 at 7,904.67 (cash 7,849.60) and the 7,905.00 52-week high from 08/13 (cash 7,849.93) span 7.50 points. Pivot R1 and the 52-week high sit 0.33 points apart. The 52-week high sits 31.00 points above the settle, and the 7,889.25 settle of 08/13 sits beneath the band.
Higher references are extended. The target price published for Wednesday sits at 7,922.44 (cash 7,867.37). Pivot R2 at 7,935.33 (cash 7,880.26) and one standard deviation resistance at 7,941.49 (cash 7,886.42) sit 6.16 points apart, with the one-range frame top at 7,951.81 above them. Two standard deviations resistance at 7,969.45 and Pivot R3 at 7,973.17 (cash 7,918.10) follow, 3.72 points apart. Three standard deviations resistance at 7,990.90 and the 8,052.10 gamma concentration pair (cash 8,000) are the extended references.
Every average sits beneath. The 5-day at 7,783.40 is 90.60 points under the settle, the 9-day at 7,774.06 is 99.94 under, the 20-day at 7,744.85 is 129.15 under and the 50-day at 7,750.99 is 123.01 under. The 100-day sits at 7,675.29, 198.71 points beneath. The 200-day sits at 7,368.63, 505.37 beneath.
The short averages all rose. The 5-day added 28.40 points from Monday's 7,755.00, because the 09/29 settle of 7,732.00 left the window and 7,874.00 replaced it. The 9-day rose 11.28 from 7,762.78 as the 09/23 settle of 7,772.50 left, and the 20-day rose 6.34 from 7,738.51. The 5-day now sits 9.34 points above the 9-day. The 50-day still sits 6.14 points above the 20-day. For Wednesday, the averages would be crossed at 7,774.94 for the 9-day, 7,752.69 for the 18-day and 7,764.60 for the 40-day.
Momentum sits high in its ranges. Relative strength reads 66.90 on the 9-day, 61.30 on the 14-day and 58.48 on the 20-day. The raw stochastic reads 89.54 percent on the 9-day and 91.61 percent on the 14-day, with the 14-day %K at 85.81 percent above %D at 73.06 percent. The published grid places the 14-3 day raw stochastic 80 percent threshold at 7,841.50 and the 70 percent threshold at 7,813.50. Trend strength is weak. On the 9-day, positive direction at 26.99 leads negative at 16.84 with the index at 16.55, and on the 14-day 24.24 leads 18.96 with the index at 12.50. Historic volatility reads 7.21 percent on the 9-day and 9.90 percent on the 14-day. These readings are as published on the provider's technical page dated for the Wednesday session, read after the 6:00 PM ET reopen, so they may carry the live Globex price.
The composite multi-indicator read rose to 88 percent buy from 56 percent buy, with signal strength good and direction strongest. It read 32 percent buy a week ago and 40 percent buy a month ago. Two groups read full buy. The short-horizon group averages 60 percent buy and the medium-horizon and long-horizon groups 100 percent buy each, and the composite trend indicator reads buy.
Ranges ran under their averages. The 14-day average true range stands at 77.81 points and the 14-day average daily range at 79.80; the 9-day figures are 78.64 and 76.92 and the 20-day figures 77.92 and 79.66. One 14-day average true range either side of the settle frames Wednesday between 7,796.19 and 7,951.81. The published deviation bands are narrower. Built from five settlements, one deviation spans 7,806.51 to 7,941.49, two 7,778.55 to 7,969.45 and three 7,757.10 to 7,990.90. They measure how settlements disperse and say nothing about intraday reach.
Zoom out. The settlement sequence from 09/22 reads 7,831.75, 7,772.50, 7,767.00, 7,803.75, 7,746.75, 7,732.00, 7,715.50, 7,724.00, 7,777.25, 7,826.25 and 7,874.00. Tuesday's settle cleared every one of them. Daily ranges for the last seven sessions ran 77.00, 58.50, 76.50, 95.00, 87.00, 87.25 and 68.50 points. Three retracements sit beneath. The grid published for Wednesday places the 38.2 percent line from the four-week high at 7,774.30, the 50 percent line of the four-week range at 7,736.25 and the 38.2 percent line from the four-week low at 7,698.19. No prior-quarter high or low was captured, so the 13-week extremes of 7,905.00 above and 7,386.00 beneath serve as the quarterly reference. No four-hour or intraday series was captured either, so swing structure rests on daily bars only.
A record cash close, a 5.26 percent yield and the minutes ahead
The deficit came first. The trade deficit, released at 8:30 AM ET as the calendar lists it, widened to 105.6 billion dollars against a 102.05 billion forecast, per the news-feed calendar. That is 3.55 billion wider than forecast. No intraday series was preserved for the contract, so no price move is tied to the release.
Yields fell. The ten-year yield index closed at 5.26 percent, down five basis points from Monday's close, and the thirty-year index at 5.64 percent, down two, per the provider's quotes. Provider commentary said Treasuries drew early support from crude's slide to a one-month low and from decent demand at the three-year auction. That auction is listed by the news-feed calendar and remains unconfirmed against the scheduled calendar. Per the same news-feed calendar, and unconfirmed, it stopped at a high yield of 4.932 percent with a bid-to-cover of 2.620. The dollar index fell 0.33 percent to 101.83.
Two policymakers spoke in the afternoon. The news feed carried remarks from the San Francisco Federal Reserve president at 2:00 PM ET that more increases may be needed if shocks persist, and from the Kansas City Federal Reserve president at 2:30 PM ET that the inflation fight has a way to go. Provider commentary said markets price a 19 percent chance of a quarter-point increase at the October 27-28 meeting. It also said the San Francisco remarks and weakness in chipmakers and AI-linked shares limited the gain.
Most large technology names rose. Provider commentary said a large online retailer gained more than 1 percent and a large software maker 0.85 percent, while a large social-media company fell 0.34 percent. It said third-quarter S&P 500 profits are expected to rise 25 percent from a year earlier according to a data compiler, up from a 22 percent estimate in July. The positioning note told a different part of the story. It said the S&P 500 and Nasdaq notched record highs on cooler yields and an advance in AI-related shares, naming gains in three chip designers.
Breadth split by sector. The positioning note said utilities outperformed, with the sector fund up 3 percent, and that photonics shares gained. Provider commentary said cybersecurity shares rallied and airlines and cruise operators rose on lower fuel costs. Chipmakers and data-storage names lagged, with a data-storage maker down more than 9 percent to lead decliners in the S&P 500. The Dow industrials closed up 0.49 percent at a one-week high, per provider commentary, and the Nasdaq-100 cash index closed up 0.48 percent at 31,224.47.
The model has the index on its supportive side. The cash close of 7,818.93 sits 128.93 points above the note's 7,690 reference level, bearish beneath and bullish above, dated 9/22/26. It sits 73.93 points above the 7,745 modeled volatility threshold and 148.93 above the 7,670 modeled gamma-flip level. The ceiling is now beneath. The same close sits 18.93 points above the 7,800 primary call-side ceiling. The gamma index reads 5.526 against 2.272 in Monday's edition, and gamma tilt 1.48 against 1.19. Index notional grew. It reads plus 1.243 billion dollars, and the largest S&P 500 exchange-traded fund's reads plus 337.873 million dollars. The 25-delta risk reversal on the index reads minus 0.031.
In this review's interpretation the close above the 7,800 ceiling in cash, with the gamma index, the gamma tilt and the index gamma notional all higher, places the index deeper inside the supportive, mean-reverting part of its positioning map for Wednesday. In the same reading the 7,800 area in cash acts as first support and the 7,850 to 7,900 band in cash as the next resistance.
Puts still led. Index put volume of 939,056 contracts exceeded call volume of 818,819, and put open interest of 13.10 million exceeds call open interest of 9.415 million. Then the console. A positioning console for the cash index shows call gamma of 11 billion against put gamma of minus 3.8 billion and attributes 7.48 percent of the index's gamma and 0.77 percent of its delta to the nearest expiration. The note's narrative said two of the day's largest same-day positions were dealer-long call blocks of 20,000 contracts at 7,860 and 7,880 in cash. It said the hedging-flow measure printed minus 10 billion dollars of delta, driven mainly by same-day call selling. It also said traders appeared positioned for lower index volatility given a light economic calendar this week. That is the note's reading.
Then the note's own map. It lists resistance at 7,820, 7,850 and 7,900 and support at 7,800, 7,775, 7,750 and 7,700, with key strikes at 8,000, 7,000, 7,800 and 7,700, all in cash. Its highest-conviction combination levels are 7,797 (99.95), 7,828 (99.92), 7,852 (99.89), 7,898 (99.61), 7,813 (99.56), 7,999 (99.51), 8,100 (99.32) and 8,054 (99.26). Scores run from 99.26 to 99.95. The largest gamma concentration sits at 8,000, the primary call-side ceiling at 7,800 and the primary put-side support base at 7,500.
The note's reference column is Monday's close. Its 7,773 cash reference equals Monday's 7,773.95 close, and 7,773 plus the note's stated 0.6 percent gain approximates the 7,819 close it reports, against the provider's 7,818.93. Every futures figure in the note is its cash figure plus 52.1 points, the source's own offset, so cash equivalents here use the 55.07 basis measured Tuesday. The implied one-day move is 0.63 percent and the five-day move 1.55 percent. Applied to the 7,818.93 cash close, the one-day figure spans 7,769.67 to 7,868.19. The note's own pair of 7,762.04 and 7,860.46 is centred on neither close, so it is not used as a range anchor.
Volatility eased. The volatility index closed at 15.01, down 0.51, and the note said its own volatility-of-volatility gauge fell three points to 83. The note also said this week's at-the-money implied volatility of 9 to 10 percent implies a one-day move of roughly 56 to 63 basis points. It put the index's implied-volatility rank at 13 percent against 95 percent for the long-bond fund. On that basis the note said the options market is not pricing a large spillover from rates into equities. The largest S&P 500 exchange-traded fund closed at 779.09, up 0.55 percent. December gold settled at 4,187.1, up 0.73 percent, and November crude settled up one cent at 89.44.
Headlines came late. After the cash close, between 4:04 PM ET and 4:24 PM ET, the news feed carried presidential remarks that the United States still has to finish its campaign against Iran. A remark at 4:20 PM ET said the Russia and Ukraine war is getting closer to ending. At 4:42 PM ET the Treasury Secretary said Iran has not loaded a single barrel of crude onto a vessel since August 25. Provider commentary on crude cited reports of increased Iranian attacks on tankers in the Strait of Hormuz. These are statements carried by the news feed and provider commentary, not events confirmed for this session.
Activity fell. Volume was 1,197,046 contracts on Tuesday's dated row against 1,359,089 on Monday's. Open interest reads 1,889,967 on Tuesday's dated row and 1,907,135 on Monday's. The latest weekly futures positioning report is still the one as of September 29, 2026. It shows asset managers long 1,104,434 contracts against short 200,431, leveraged funds long 125,453 against short 497,942, and dealers long 178,591 against short 785,579. No change in positioning is asserted for Tuesday.
The trade map for Wednesday
The primary setup is a long from 7,852 to 7,860. Tuesday was the fourth consecutive higher settle, and the contract sits above every settlement average from the 5-day to the 200-day. The composite reads 88 percent buy with direction strongest, and the cash close sits above the 7,800 ceiling with larger positive dealer gamma. The band sits on the ceiling pair. The 7,852.10 source pair of that ceiling sits 0.10 points above the band's bottom. The stop sits at 7,826, 10.17 points beneath Pivot S1 at 7,836.17, 3.00 beneath Tuesday's low and 0.25 beneath Monday's settle. The targets step up: 7,886, then 7,916, then an extended 7,946. A weak 14-day directional reading and a 14-day %K of 85.81 percent lead the review to label the setup an analyst judgment that positioning keeps pullbacks shallow, with no measured edge behind it.
From the 7,856 midpoint the risk to the stop is 30 points, 38.6 percent of the 14-day average true range of 77.81. The targets sit 30, 60 and 90 points above that midpoint. Exact multiples of the risk. The settle sits 14.00 points above the top of the band and 22.00 above its bottom, and the review frames the entry as a pullback into it. A one-range frame from the settle spans 7,796.19 to 7,951.81. It holds the band, the stop and all three targets, with the extended 7,946 sitting 5.81 points inside its top. The published one-deviation band runs 7,806.51 to 7,941.49. Its lower edge sits 19.49 points beneath the stop, and the extended target sits 4.51 points above its upper edge.
The scenario ranges are analyst judgment. None carries a calibration. The low-range case runs 7,850 to 7,900, the most likely 7,830 to 7,920 and the high-range case 7,796 to 7,952. Session by session the review expects roughly 7,850 to 7,900 through Globex, with a constructive bias above the 7,866.83 Pivot Point, and 7,845 to 7,905 through London, with the 7,904.67 to 7,905.00 pairing of Pivot R1 and the 52-week high the first test. The morning band is 7,835 to 7,915 and the afternoon 7,825 to 7,935 into the 4:00 PM ET settle.
The night comes first. Globex reopened at 6:00 PM ET Tuesday, after the late Iran and Ukraine headlines, and traded between 7,880.00 and 7,883.25 at the time of writing. A regional Federal Reserve president is listed at 7:00 PM ET Tuesday, per the news-feed calendar and unconfirmed. The managing director of the International Monetary Fund and German industrial production are both listed at 2:00 AM ET Wednesday, per the news-feed calendar and unconfirmed. Both fall just before the London window.
Then the United States morning. The cash open at 9:30 AM ET is the first directional test of the session. The weekly petroleum status report follows at 10:30 AM ET, as the calendar lists it. It reaches the index through crude and yields. A regional inflation-expectations survey and a European Central Bank speaker are listed at 11:00 AM ET, both per the news-feed calendar and unconfirmed.
The minutes are the event. A ten-year note auction is listed at 1:00 PM ET, per the news-feed calendar and unconfirmed. The minutes of the September policy meeting follow at 2:00 PM ET on Wednesday, October 7, 2026, as the calendar lists it, and in the review's judgment they are the single first-order event for the contract. Consumer credit follows at 3:00 PM ET, as the calendar lists it. A Federal Reserve governor speaks on the economic outlook at 4:30 AM ET on Thursday, October 8, 2026, inside the following overnight window, and wholesale inventories follow at 10:00 AM ET that day, both as the calendar lists them. The large banks report from 7:00 AM ET on Tuesday, October 13, 2026, and the consumer price index follows at 8:30 AM ET on Wednesday, October 14, 2026, both as the calendar lists them. The captured calendars carry no mega-capitalisation earnings entry for Wednesday.
One path is weighted. In this review's analyst judgment the most probable path holds the contract above the 7,866.83 Pivot Point into the cash open and offers a test of the 7,904.67 to 7,905.00 pairing of Pivot R1 and the 52-week high before the 2:00 PM ET minutes. A pullback toward the 7,852.10 ceiling pair that holds is weighted above a break beneath Pivot S1 at 7,836.17. The reasons given are four consecutive higher settles, a settle above every average, an 88 percent buy composite with direction strongest, and positive dealer gamma larger than in Monday's edition. No measured frequency backs it. The alternative that would invalidate this reading is a hawkish reading of the minutes that lifts yields back above Monday's closing level and pushes the contract beneath Monday's 7,826.25 settle.
Tuesday's low stopped 2.75 points above Monday's settle, and Wednesday's stop sits 0.25 points beneath it.
The complete data picture
Every number behind Wednesday’s plan, charted first, then the full level lists, then the complete numeric reference underneath.
Full numeric reference, every remaining figure from the session review
1. Executive Summary
The December S&P 500 contract settled at 7,874.00 on Tuesday, up 47.75 points or 0.61 percent from Monday's settle of 7,826.25, after trading between 7,897.50 and 7,829.00, a 68.50 point daily range. The settle finished at 65.7 percent of the range, and the range was 0.86 times the published 14-day average daily range of 79.80 points, the narrowest session since the 58.50 point range of 09/29. Tuesday was the fourth consecutive higher settle and the highest settle since the 7,889.25 settle of 08/13, and the 7,897.50 high was the highest print since the 7,898.00 high of 08/14. The 7,829.00 low sat 2.75 points above Monday's settle, and Tuesday printed a higher high and a higher low against Monday.
The S&P 500 cash index closed at 7,818.93, up 0.58 percent, a record close and the first since August 13, per the news feed at 4:02 PM ET. Provider commentary credited lower Treasury yields, strength in most of the largest technology names, a cybersecurity rally and earnings optimism, and said weakness in chipmakers and AI-linked shares and hawkish remarks from the San Francisco Federal Reserve president limited the gain. The trade deficit, released at 8:30 AM ET as the calendar lists it, widened to 105.6 billion dollars against a 102.05 billion forecast, per the news-feed calendar. No intraday series was preserved for the contract, so no price move in this review is tied to any headline.
The ten-year yield index closed five basis points lower at 5.26 percent and the dollar index fell 0.33 percent to 101.83. The volatility index closed at 15.01, down 0.51, and the positioning note said its own volatility-of-volatility gauge dropped three points to 83. The cash close sits 18.93 points above the primary call side ceiling at 7,800 in cash and above the dealer-positioning reference level at 7,690 in cash, the modeled volatility threshold at 7,745 in cash and the modeled gamma-flip level at 7,670 in cash, with the gamma index and the index gamma notional both higher than in Monday's edition.
The composite multi-indicator read is 88 percent buy with strength good and direction strongest, up from 56 percent buy. The primary setup is a long from the 7,852 to 7,860 zone around the source futures pair of the 7,800 cash ceiling at 7,852.10, stopped at 7,826 beneath Pivot S1 and Monday's settle, with objectives at 7,886, 7,916 and an extended 7,946.
2.1 Intraday and Session Review
The Tuesday session opened at 7,831.75 at the Monday 6:00 PM ET reopen, 5.50 points above Monday's settle, marked a daily high of 7,897.50 and a daily low of 7,829.00, and settled at 7,874.00. No intraday series was preserved for the contract, so this review makes no claim about the order in which the extremes printed or about the path between them; only the daily bar, the settlement and the chart's late-session 30-minute bars are used.
The chart's 30-minute bars read after the close show trade between 7,871.75 and 7,884.00 from the 3:00 PM ET bar through the 4:30 PM ET bar, inside the daily range, with the 4:30 PM ET bar closing at 7,880.50. These quotes are not used as the settlement anywhere in this review. The Wednesday session reopened at 6:00 PM ET Tuesday; the provider's day open, high and low of 7,881.50, 7,883.25 and 7,880.00 shown at the time of writing belong to that new session, not to Tuesday.
The session extremes used here are the completed-session inputs behind the published pivot ladder rather than an independently read bar, back-solved from the outer pivot pairs and verified against every rung. The third resistance point at 7,973.17 minus the third support point at 7,767.67, divided by three, returns 68.50, and the second resistance point at 7,935.33 minus the second support point at 7,798.33, divided by two, returns the same 68.50. Three times the Pivot Point of 7,866.83 less the 7,874.00 settle gives a high plus low sum of 15,726.49, 0.01 from the 15,726.50 of the solved pair because the published pivot is rounded, and the pair of 7,897.50 and 7,829.00 reproduces all seven published rungs. Independent corroboration: the provider's settlement row and the chart's completed Tuesday daily bar carry the same 7,897.50 high and 7,829.00 low, and the provider's one-month high reads 7,897.50 dated 10/06/26.
2.2 Daily Structure
Tuesday printed a higher high and a higher low against Monday: the 7,897.50 high sits 50.00 points above Monday's 7,847.50, and the 7,829.00 low sits 68.75 points above Monday's 7,760.25. The sequence of session highs over the last six sessions reads 7,770.75, 7,782.00, 7,767.75, 7,810.25, 7,847.50 and 7,897.50, and the sequence of session lows reads 7,712.25, 7,705.50, 7,672.75, 7,723.25, 7,760.25 and 7,829.00.
The 52-week and 13-week high of 7,905.00, dated 08/13/26, sits 31.00 points above the settle, and the one-month low of 7,575.00, dated 09/16/26, sits 299.00 points beneath it. Settlements over the last six sessions ran 7,732.00, 7,715.50, 7,724.00, 7,777.25, 7,826.25 and 7,874.00.
No prior-quarter high or low was captured for this session, so the 13-week extremes serve as the available quarterly reference: 7,905.00 above and 7,386.00, dated 07/29/26, beneath.
2.3 4-Hour and Swing Structure
The four-session advance from the 7,715.50 settle of 09/30 to Tuesday's 7,874.00 totals 158.50 points. Daily ranges for the last seven sessions ran 77.00, 58.50, 76.50, 95.00, 87.00, 87.25 and 68.50.
The retracement grid published for Wednesday places the 38.2 percent retracement from the four-week high at 7,774.30, the 50 percent retracement of the four-week range at 7,736.25 and the 38.2 percent retracement from the four-week low at 7,698.19. No four-hour series was captured for this session, and no intraday series was preserved, so swing structure here rests on daily bars only.
2.4 Moving Averages
The averages cited in this subsection were computed from the provider's daily settlement series for the December contract, which holds 259 completed sessions through Tuesday. The 5-day average stands at 7,783.40, the 9-day at 7,774.06, the 20-day at 7,744.85, the 50-day at 7,750.99, the 100-day at 7,675.29 and the 200-day at 7,368.63.
The 7,874.00 settle sits 90.60 points above the 5-day average, 99.94 above the 9-day, 129.15 above the 20-day, 123.01 above the 50-day, 198.71 above the 100-day and 505.37 above the 200-day. The 5-day average rose 28.40 points from Monday's 7,755.00 as the 09/29 settle of 7,732.00 left the window and was replaced by 7,874.00.
The projection grid gives the prices at which each average would be crossed on Wednesday: 7,774.94 for the 9-day, 7,752.69 for the 18-day and 7,764.60 for the 40-day.
2.5 Oscillator and Trend Readings
The oscillator figures below are as published on the provider's technical page dated for the Wednesday session, read after the 6:00 PM ET reopen; the page may carry the live Globex price rather than the settle, so they are quoted as published. The 9-day relative strength reads 66.90, the 14-day relative strength 61.30 and the 20-day relative strength 58.48.
The stochastics sit high in their ranges. The 9-day raw stochastic reads 89.54 percent and the 14-day raw stochastic 91.61 percent, while the 14-day stochastic %K reads 85.81 percent and the 14-day stochastic %D 73.06 percent. The published grid places the 14-3 day raw stochastic 80 percent threshold at 7,841.50 and its 70 percent threshold at 7,813.50.
The directional system favours the upside but with a weak trend reading. The 9-day directional index ADX reads 16.55 with the 9-day +DI at 26.99 and the 9-day -DI at 16.84; the 14-day directional index ADX reads 12.50 with the 14-day +DI at 24.24 and the 14-day -DI at 18.96. The 9-day historic volatility reads 7.21 percent and the 14-day historic volatility 9.90 percent.
The composite multi-indicator read published for the Wednesday session is 88 percent buy, up from 56 percent buy in the prior session's snapshot, with signal strength described as good and direction as strongest. The snapshot history reads 32 percent buy a week ago and 40 percent buy a month ago. The short-horizon group averages 60 percent buy, the medium-horizon group 100 percent buy and the long-horizon group 100 percent buy, and the composite trend indicator reads buy.
2.6 Volatility and Expected Range
The published 14-day average true range stands at 77.81 points and the 14-day average daily range at 79.80 points; the 9-day average true range is 78.64 with a 9-day average daily range of 76.92, and the 20-day average true range is 77.92 with a 20-day average daily range of 79.66. Tuesday's 68.50 point range was 0.86 times the 14-day average daily range.
The 14-day average true range of 77.81 points, added to and subtracted from the 7,874.00 settle, frames Wednesday between 7,796.19 and 7,951.81. The published standard-deviation bands are narrower because they are built from five settlements: one deviation spans 7,806.51 to 7,941.49, two spans 7,778.55 to 7,969.45 and three spans 7,757.10 to 7,990.90. The positioning note's implied one-day move of 0.63 percent, applied to the 7,818.93 cash close, spans 7,769.67 to 7,868.19 in cash.
3.1 Resistance
The settle at 7,874.00 sits 7.17 points above the Pivot Point at 7,866.83. Tuesday's 7,897.50 high comes first, followed by the 3-10 day average crossover stall price at 7,904.11, Pivot R1 at 7,904.67 and the 52-week high of 7,905.00. The published target price of 7,922.44 and Pivot R2 at 7,935.33 follow, then one standard deviation resistance at 7,941.49, two standard deviations resistance at 7,969.45 and Pivot R3 at 7,973.17. Three standard deviations resistance at 7,990.90 and the source futures pair of the 8,000 cash gamma concentration at 8,052.10 are the extended references.
3.2 Support
Beneath the settle, the Pivot Point at 7,866.83 comes first, then the source futures pair of the 7,800 cash primary call side ceiling at 7,852.10, which anchors the setup. The 14-3 day raw stochastic 80 percent threshold at 7,841.50, Pivot S1 at 7,836.17, Tuesday's 7,829.00 low and Monday's 7,826.25 settle follow. The 40-day average stall price at 7,815.00, one standard deviation support at 7,806.51 and Pivot S2 at 7,798.33 form the next band, with the source futures pair of the 7,745 cash modeled volatility threshold at 7,797.10 beside them. The 5-day settlement average at 7,783.40, two standard deviations support at 7,778.55 and Pivot S3 at 7,767.67 sit beneath, with the source futures pair of the 7,670 cash modeled gamma-flip level at 7,722.10 the deeper reference.
4.1 Dollar, Rates, and Fed Policy
The ten-year yield index closed at 5.26 percent, down five basis points from Monday's close, and the thirty-year index at 5.64 percent, down two, per the provider's quotes; provider commentary said Treasuries drew early support from crude's slide to a one-month low and from decent demand at the three-year auction, which the news-feed calendar lists and which remains unconfirmed against the scheduled calendar. That auction, per the news-feed calendar and unconfirmed, stopped at a high yield of 4.932 percent with a bid-to-cover of 2.620. The dollar index fell 0.33 percent to 101.83. The news feed carried remarks from the San Francisco Federal Reserve president at 2:00 PM ET that more increases may be needed if shocks persist, and from the Kansas City Federal Reserve president at 2:30 PM ET that the inflation fight has a way to go. Provider commentary said markets price a 19 percent chance of a quarter-point increase at the October 27-28 meeting. The minutes of the September policy meeting are scheduled for 2:00 PM ET on Wednesday, October 7, 2026, as the calendar lists it.
4.2 Large-Cap Leadership and Earnings
Provider commentary said most of the largest technology names closed higher, with a large online retailer up more than 1 percent and a large software maker up 0.85 percent, while a large social-media company fell 0.34 percent, and that third-quarter S&P 500 profits are expected to rise 25 percent from a year earlier according to a data compiler, up from a 22 percent estimate in July. The large banks report from 7:00 AM ET on Tuesday, October 13, 2026, as the calendar lists it. The positioning note said the S&P 500 and Nasdaq notched record highs on cooler yields and an advance in AI-related shares, naming gains in three chip designers.
4.3 Geopolitical Backdrop
After the cash close, the news feed carried presidential remarks between 4:04 PM ET and 4:24 PM ET that the United States still has to finish its campaign against Iran, a remark at 4:20 PM ET that the Russia and Ukraine war is getting closer to ending, and a statement by the Treasury Secretary at 4:42 PM ET that Iran has not loaded a single barrel of crude onto a vessel since August 25. Provider commentary on crude cited reports of increased Iranian attacks on tankers in the Strait of Hormuz, and November crude settled up one cent at 89.44. These are statements carried by the news feed and provider commentary rather than events confirmed for this session.
4.4 Sector Breadth and Rotation
The positioning note said utilities outperformed, with the sector fund up 3 percent, and that photonics shares gained. Provider commentary said cybersecurity shares rallied, airlines and cruise operators rose on lower fuel costs, and chipmakers and data-storage names lagged, with a data-storage maker down more than 9 percent to lead decliners in the S&P 500. The Dow industrials closed up 0.49 percent at a one-week high, per provider commentary, and the Nasdaq-100 cash index closed up 0.48 percent at 31,224.47.
4.5 Cross-Asset and Volatility
The volatility index closed at 15.01, down 0.51, per the provider's quote. The positioning note said its volatility-of-volatility gauge fell three points to 83, that this week's at-the-money implied volatility of 9 to 10 percent implies a one-day move of roughly 56 to 63 basis points, and that the index's implied-volatility rank sits at 13 percent while the long-bond fund's sits at 95 percent, so the options market is not pricing a large spillover from rates into equities. The largest S&P 500 exchange-traded fund closed at 779.09, up 0.55 percent. December gold settled at 4,187.1, up 0.73 percent.
4.6 Institutional Positioning
The latest positioning report on the provider's overview is still the one as of September 29, 2026: asset managers long 1,104,434 contracts against short 200,431, and leveraged funds long 125,453 against short 497,942, with dealers long 178,591 against short 785,579. The provider overview read for this session shows that September 29 report as its latest, so no change in positioning is asserted for Tuesday.
Open interest on the December contract reads 1,889,967 on Tuesday's dated provider row and 1,907,135 on Monday's dated row, the figure the provider's overview showed at the time of capture; no change in open interest is asserted for Tuesday. Tuesday's volume was 1,197,046 contracts against Monday's 1,359,089.
5. Index Options Flow Context
The positioning note used for this section is the 5:31 PM ET edition for Tuesday. Its reference column holds the prior session's closes, not Tuesday's: its 7,773 cash reference equals Monday's 7,773.95 cash close, and 7,773 plus the note's stated 0.6 percent gain approximates the 7,819 close it reports, against the provider's 7,818.93. The note's futures column equals the cash figure plus 52.1 on every row, the source's offset rather than the 55.07 point basis measured for this session from the December settlement and the cash close.
The note's dealer-positioning reference level is 7,690 in cash, bearish beneath and bullish above, dated 9/22/26, and the cash close sits 128.93 points above it. The modeled volatility threshold is 7,745 in cash (source pair 7,797.10) and the modeled gamma-flip level 7,670 in cash (source pair 7,722.10), so the close sits 73.93 points above the threshold and 148.93 above the flip. The largest gamma concentration is 8,000 in cash (source pair 8,052.10), the primary call side ceiling 7,800 in cash (7,852.10) and the primary put side support base 7,500 in cash (7,552.10). The note lists cash resistance at 7,820, 7,850 and 7,900 and cash support at 7,800, 7,775, 7,750 and 7,700, and key strikes at 8,000, 7,000, 7,800 and 7,700 in cash. Among the combination levels the highest conviction scores sit at 7,797 (99.95), 7,828 (99.92), 7,852 (99.89), 7,898 (99.61), 7,813 (99.56), 7,999 (99.51), 8,100 (99.32) and 8,054 (99.26).
The gamma index reads 5.526 against 2.272 in Monday's edition and gamma tilt 1.48 against 1.19, while the index gamma notional reads plus 1.243 billion dollars and the largest S&P 500 exchange-traded fund's plus 337.873 million dollars. The 25-delta risk reversal on the index reads minus 0.031. Index put volume of 939,056 contracts exceeded call volume of 818,819, and put open interest of 13.10 million exceeds call open interest of 9.415 million. The implied one-day move is 0.63 percent and the implied five-day move 1.55 percent. The note's own implied-move pair of 7,762.04 and 7,860.46 is centred on neither close, so it is not used as a range anchor.
The note's narrative said two of the day's largest same-day positions were dealer-long call blocks of 20,000 contracts at 7,860 and 7,880 in cash, that the hedging-flow measure printed minus 10 billion dollars of delta driven mainly by same-day call selling, and that traders appeared positioned for lower index volatility given a light economic calendar this week. The cash-index console shows call gamma of 11 billion against put gamma of minus 3.8 billion and attributes 7.48 percent of the index's gamma and 0.77 percent of its delta to the nearest expiration; its high and low volatility point fields are excluded as low-confidence.
In this review's interpretation the close above the 7,800 ceiling in cash, with the gamma index, the gamma tilt and the index gamma notional all higher, places the index deeper inside the supportive, mean-reverting part of its positioning map for Wednesday, with the 7,800 area in cash acting as first support and the 7,850 to 7,900 band in cash the next resistance.
6.1 Night Session (6:00 PM ET Tuesday to 3:00 AM ET Wednesday, Globex and Asia)
The contract reopened at 6:00 PM ET Tuesday and traded between 7,880.00 and 7,883.25 at the time of writing. A regional Federal Reserve president is listed at 7:00 PM ET Tuesday and German industrial production at 2:00 AM ET Wednesday, both per the news-feed calendar and unconfirmed. Bias constructive above the 7,866.83 Pivot Point, expected Globex band roughly 7,850 to 7,900.
6.2 London Session (3:00 AM ET to 8:00 AM ET Wednesday)
The managing director of the International Monetary Fund is listed at 2:00 AM ET, per the news-feed calendar and unconfirmed, just before the window. Bias constructive, expected band roughly 7,845 to 7,905, with the 7,904.67 to 7,905.00 pairing of Pivot R1 and the 52-week high the first test.
6.3 Morning Session (9:30 AM ET to 12:00 PM ET Wednesday, regular trading hours open)
The cash open at 9:30 AM ET is the first directional test of the session, and the 10:30 AM ET weekly petroleum report, as the calendar lists it, reaches the index through crude and yields. A regional inflation-expectations survey is listed at 11:00 AM ET, per the news-feed calendar and unconfirmed. Expected band roughly 7,835 to 7,915.
6.4 Afternoon Session (12:00 PM ET to 4:00 PM ET Wednesday)
A ten-year note auction is listed at 1:00 PM ET, per the news-feed calendar and unconfirmed, and the minutes of the September policy meeting follow at 2:00 PM ET on Wednesday, October 7, 2026, as the calendar lists it, the first-order event of the day. Consumer credit follows at 3:00 PM ET on Wednesday, October 7, 2026, as the calendar lists it. Expected band roughly 7,825 to 7,935.
6.5 Night Session Forward (6:00 PM ET Wednesday)
A Federal Reserve governor speaks on the economic outlook at 4:30 AM ET on Thursday, October 8, 2026, as the calendar lists it, inside the following overnight window, and wholesale inventories follow at 10:00 AM ET on Thursday, October 8, 2026, as the calendar lists it.
6.6 Expected Range (Wednesday Full Session)
Low-range scenario: 7,850 to 7,900
Mid-range scenario (most likely): 7,830 to 7,920
High-range scenario: 7,796 to 7,952
6.7 Most Likely Path
In this review's analyst judgment the most probable path holds the contract above the 7,866.83 Pivot Point into the cash open and offers a test of the 7,904.67 to 7,905.00 pairing of Pivot R1 and the 52-week high before the 2:00 PM ET minutes. A pullback toward the 7,852.10 source pair of the 7,800 cash ceiling that holds is weighted above a break beneath Pivot S1 at 7,836.17, because the contract has four consecutive higher settles, sits above every settlement average, the composite read is 88 percent buy with direction strongest, and dealer gamma on the index is positive and larger than in Monday's edition. The alternative that would invalidate this reading is a hawkish reading of the minutes that lifts yields back above Monday's closing level and pushes the contract beneath Monday's 7,826.25 settle.
7. Wednesday Economic Calendar
The Wednesday session reopened at 6:00 PM ET Tuesday. A regional Federal Reserve president is listed at 7:00 PM ET Tuesday, and the managing director of the International Monetary Fund and German industrial production are listed at 2:00 AM ET Wednesday, all per the news-feed calendar and unconfirmed.
The cash open is at 9:30 AM ET. The weekly petroleum status report is scheduled for 10:30 AM ET on Wednesday, October 7, 2026, as the calendar lists it. A regional inflation-expectations survey and a European Central Bank speaker are listed at 11:00 AM ET, and a ten-year note auction at 1:00 PM ET, all per the news-feed calendar and unconfirmed. The minutes of the September policy meeting are scheduled for 2:00 PM ET on Wednesday, October 7, 2026, as the calendar lists it, and consumer credit follows at 3:00 PM ET on Wednesday, October 7, 2026, as the calendar lists it. The captured calendars carry no mega-capitalisation earnings entry for Wednesday.
In this review's judgment the single first-order event for the contract on Wednesday is the 2:00 PM ET release of the minutes, as the calendar lists it. The large banks report from 7:00 AM ET on Tuesday, October 13, 2026, and the consumer price index follows at 8:30 AM ET on Wednesday, October 14, 2026, both as the calendar lists it.
8. Primary Trade Setup
Direction: Long
Rationale: Four consecutive higher settles, a settle above every average from the 5-day to the 200-day, an 88 percent buy composite with direction strongest and a cash close above the 7,800 cash ceiling with larger positive dealer gamma support buying a pullback into the 7,852 to 7,860 zone around the 7,852.10 source pair of that ceiling. A weak 14-day directional index reading and a 14-day stochastic %K of 85.81 percent mean the setup is an analyst judgment that positioning keeps pullbacks shallow rather than a measured edge.
Entry Zone: 7,852 to 7,860
Stop Loss: 7,826 (beneath Pivot S1 at 7,836.17, Tuesday's 7,829.00 low and Monday's 7,826.25 settle)
Target 1 (T1): 7,886 (11.50 beneath the 7,897.50 Tuesday high)
Target 2 (T2): 7,916 (above Pivot R1 at 7,904.67 and the 7,905.00 52-week high)
Target 3 (T3, extended): 7,946 (above Pivot R2 at 7,935.33 and one standard deviation resistance at 7,941.49)
Risk-to-Reward: Approximately 1:1 to T1, 1:2 to T2, 1:3 to T3
Invalidation: A settle beneath Pivot S1 at 7,836.17 negates the thesis. Short of that, the edge is removed by acceptance beneath 7,840 rather than by a touch, defined as two consecutive 30-minute closes beneath 7,840.
Macro override: A hawkish reading of the minutes that lifts the ten-year yield back above Monday's closing level, or a Gulf escalation that lifts crude and yields together, would invalidate the long in real time. In that scenario a gap beneath the 7,826 stop removes the setup before entry, and the 7,797.10 source pair of the 7,745 cash modeled volatility threshold becomes the reference within one 14-day average true range of 77.81 points.
Sources and methodology
This outlook is built from our session review of the December E-mini S&P 500 contract, the December ’26 contract, prepared after Tuesday's close on October 6, 2026 for the Wednesday, October 7, 2026 session. Tuesday's completed extremes are recovered from the published pivot ladder: Pivot R3 at 7,973.17 less Pivot S3 at 7,767.67, divided by three, and Pivot R2 at 7,935.33 less Pivot S2 at 7,798.33, divided by two, both return 68.50, and three times the 7,866.83 Pivot Point less the settle gives a high-plus-low sum of 15,726.49, one hundredth from the 15,726.50 of the solved pair of 7,897.50 and 7,829.00, which reproduces all seven published rungs. The provider's dated row agrees at 7,831.75, 7,897.50, 7,829.00 and 7,874.00, on volume of 1,197,046 contracts and open interest of 1,889,967; the provider's one-month high reads 7,897.50 dated 10/06/26. It is a second surface of the same vendor, so it confirms internal consistency and not the underlying quote. No intraday series was preserved for Tuesday, so that row is the only evidence used to grade Tuesday's card, and no claim is made about the order of the day's prints. Monday's row now reads volume of 1,359,089 and open interest of 1,907,135, revised figures that replace the 1,274,587 and 1,889,967 carried on Tuesday's outlook; that post was not changed.
The contract domain was checked before any level was used: the explicit-month chart's completed Tuesday bar equals the provider's settlement row, the chart's current Wednesday bar opened at 7,881.50, equal to the provider's day open, and the provider's published previous close of 7,874.00 equals the settlement. The Globex session reopened at 6:00 PM ET Tuesday, so the overview page's day high, day low and open belong to the Wednesday session and are not used as Tuesday's range. The moving averages were computed from the 259-row daily settlement series, which excludes the partial Wednesday row; the oscillators are cited as published for the Wednesday session. The positioning note used is the 5:31 PM ET edition for Tuesday, October 6, and its cash levels are quoted as published. Its reference column is the prior session's close and its futures column a fixed 52.1 translation, so any cash equivalent given here uses the 55.07 basis measured this session, settlement against cash close. The cash index extremes and the other cross-asset closes come from the provider's quote read at about 6:22 PM ET. The cash-index console's high and low volatility point fields are excluded as low-confidence, and modeled thresholds are never called strikes. Scenario ranges are analyst judgment. Items marked unconfirmed come from the news-feed calendar or press reports. Every catalyst whose release time had passed at the time of writing is recorded as completed.
Tuesday’s outlook for this contract is here, and the Nasdaq-100 contract's Tuesday outlook covers the index that rose 0.48 percent in cash on Tuesday. Outlooks for ES, NQ, GC and CL are collected on the market outlook page, and our forward trading record is on the performance statement.