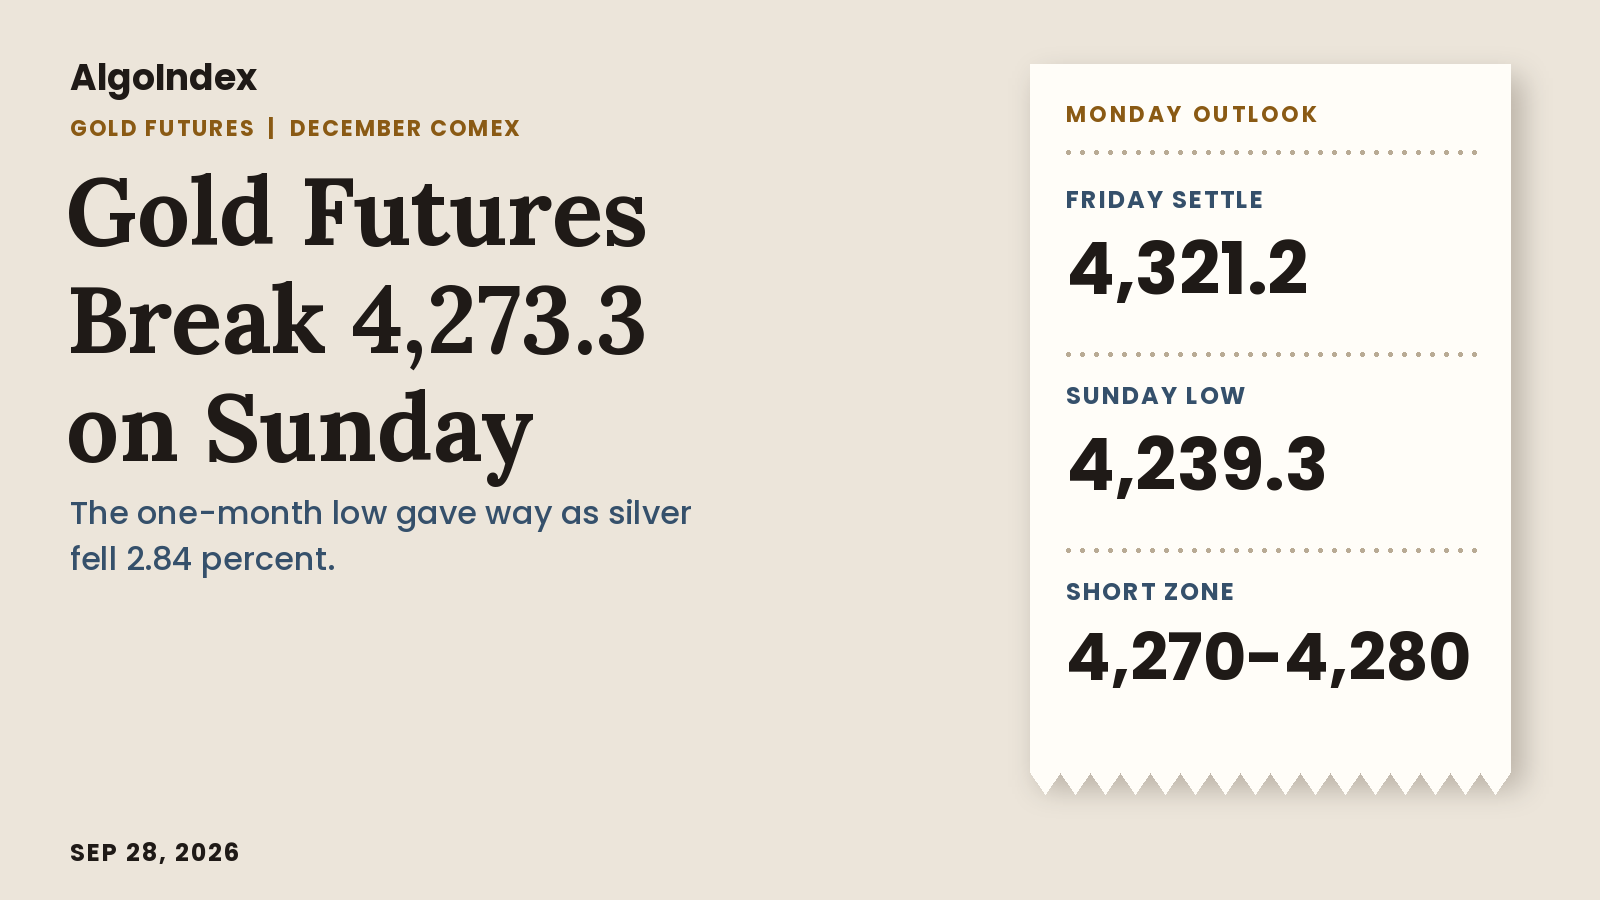
Within three half-hour bars on Sunday evening, December gold went through every support that Friday's session had left behind. The 08:00 PM ET bar closed at 4,283.6, beneath Friday's 4,289.2 low. The 08:30 PM ET bar fell to 4,260.5 on 6,437 contracts, and the 09:00 PM ET bar to 4,246.2 on 8,176. The 09:30 PM ET bar, still open when it was read, reached 4,239.3, the lowest price the contract has traded since the 08/05 session. At 09:51 PM ET the provider quoted gold at 4,244.8, down 76.4 points or 1.77 percent from Friday's settle.
Friday had pointed the other way. The contract settled at 4,321.2, up 23.2 points or 0.54 percent, its first higher settle after four lower ones, after a 62.4 point session between 4,351.6 and 4,289.2. It rose with a weaker dollar while the ten-year yield climbed 2 basis points to 5.18 percent. Then the weekend delivered a rejected Iran plan, a tariff agreement with China and, on Sunday evening, headlines about both renewed talks and more strikes. None of it produced a haven bid.
Monday asks whether the broken 4,273.3 to 4,289.7 band now caps the contract, or whether Asia and Europe buy it back. Silver fell harder than gold on Sunday, 2.84 percent beneath Friday's quote, and copper slid too, while dollar index futures barely moved. The gold review reads that as a metals-wide liquidation. The primary setup does not chase it. It sells a retest of the broken band at 4,270 to 4,280.
Prepared for the Monday, September 28, 2026 session. December gold settled Friday at 4,321.2 after a 4,351.6 to 4,289.2 session, then opened Sunday at 4,315.0 and broke to 4,239.3; the provider quoted it at 4,244.8 at 09:51 PM ET. The first overhead band is the broken support: the 4,273.3 one-month low, the 4,283.0 one-deviation line, Friday's 4,289.2 low and Pivot S1 at 4,289.7. Above it sit 4,298.1, 4,300.6, the 4,303.9 target price, Sunday's 4,315.6 high and the 4,320.7 Pivot Point. Support starts at Sunday's 4,239.3 low, then Pivot S3 at 4,227.3 and the 4,223.4 range projection. The composite refreshed with the live price reads 64% SELL. The primary setup is a short from 4,270 to 4,280, stop 4,302, targets 4,248, 4,221 and 4,194. Monday carries Federal Reserve speakers rather than data, and gold settles at 1:30 PM ET.
Friday's 4,324 short, graded against the bar
Our gold outlook for Friday was a conditional short, built with the ten-year at 5.16 percent on the view that yields were the heavier force. It sold a retracement into 4,324 to 4,336, the band around Thursday's 4,324.4 open and Pivot R1 at 4,331.2, with a 4,368 stop and objectives at 4,292, 4,254 and 4,216. The Friday gold outlook carries the full level map and the conditions that would have voided the setup.
December gold opened Friday at 4,309.5, 14.5 points beneath the band, ran from 4,351.6 to 4,289.2 and settled at 4,321.2. The band traded in full, and the high cleared its top by 15.6 points. The high stopped 16.4 points beneath the stop. The low went 2.8 points through the first objective and held 35.2 above the second. The settle finished 2.8 points beneath the bottom of the band. No intraday series was captured for Friday, so this outlook asserts no fill and no sequence. The card's two-close condition above Thursday's 4,338.0 high cannot be checked from a daily bar either; the high traded 13.6 points above that line.
We also published three range cases. The low-range case, 4,272 to 4,330, held the low and the settle, and the high overran its top by 21.6 points. The most likely band, 4,255 to 4,345, held the settle and missed the high by 6.6. The high-range case, 4,225 to 4,371, contained the whole bar with 19.4 points to spare at the top.
The path call held. It judged a settle inside 4,270 to 4,335 more likely than a break of the 09/16 low, and Friday settled inside it with the low 15.9 points above 4,273.3. The invalidation, a settle above the 4,360 average zone, never came close. The macro override named a sharp decline in yields. The ten-year rose 2 basis points instead, and gold gained anyway. The gold review reads that as a gain that came through the weaker dollar, an interpretation of simultaneous daily changes and not a measured decomposition.
The weekend version of the trade fared worse. A short from 4,346 to 4,356 with a 4,380 stop and targets at 4,322, 4,293 and 4,264 never filled, because Sunday's high of 4,315.6 stayed 30.4 points beneath its band. The contract then traded through every one of its targets without it. It is withdrawn, not managed. Sunday's prints belong to Monday's session, so they sit outside Friday's grade.
A 4,321.2 settle, then a 76.3 point Sunday break
Friday's bar sat above Thursday's on both ends. The session opened at 4,309.5, 11.5 points above Thursday's settle, and the settle finished 11.7 above the open, 32.0 above the low and 30.4 beneath the high, at 51.3 percent of the 62.4 point range. The high stayed 55.9 points beneath Wednesday's 4,407.5 high. The low held 15.9 above the 09/16 low of 4,273.3, which is also the one-month low. No intraday series was captured for Friday, so no Friday path is drawn.
The extremes are back-solved from the published pivot ladder. The third resistance point at 4,414.5 minus the third support point at 4,227.3, divided by three, returns 62.4, and the second pair, 4,383.1 and 4,258.3, divided by two, returns the same. Three times the unrounded 4,320.667 Pivot Point, published as 4,320.7, less the settle gives an 8,640.8 high-plus-low sum, and 4,351.6 with 4,289.2 reproduces all seven rungs. The overview page and the chart's daily bar show the same open, high and low. The chart's last 30-minute bar closed at 4,320.5, a post-settlement print that is not used as the settle.
The week never left the one before it. September 21 through 25 spanned 4,422.1 at Monday's high and 4,278.3 at Thursday's low; the prior week, September 14 through 18, spanned 4,439.8 to 4,273.3. Settles after the 09/18 print of 4,424.9 read 4,383.9, 4,376.4, 4,318.4, 4,298.0 and 4,321.2. Friday's gain recovered 23.2 of the 126.9 points lost across four lower settles. That is 18.3 percent of the decline. Daily ranges ran 61.8 on Monday, 86.5 on Tuesday, 96.8 on Wednesday, 59.7 on Thursday and 62.4 on Friday, so Friday ran 2.7 points wider than Thursday.
Zoom out and the summer high looks distant. No prior-quarter high or low was captured, so the 13-week extremes stand in: 4,755.0, set on 08/25/26, and 4,015.6, set on 06/30/26. Friday's settle sat 433.8 points beneath the high and 305.6 above the low. The retracement grid published for Monday places the 38.2 percent retracement from the 13-week low at 4,298.1, 23.1 points beneath the settle, and the 50 percent retracement of the 13-week range at 4,385.3. The 38.2 percent retracements from the four-week low and the 13-week high sit higher still, at 4,448.1 and 4,472.5.
Every average sits overhead. Computed from 260 completed sessions of the December contract, the 5-day stands at 4,339.58, the 9-day at 4,360.31, the 20-day at 4,407.48, the 50-day at 4,366.31, the 100-day at 4,392.61 and the 200-day at 4,647.73. Friday's settle sat 18.4 points beneath the 5-day, 39.1 beneath the 9-day, 45.1 beneath the 50-day, 71.4 beneath the 100-day, 86.3 beneath the 20-day and 326.5 beneath the 200-day. The 20-day is falling, down 17.14 points from 4,424.62, while the 50-day rose 5.45 points. The 5-day gave up 20.74 points from 4,360.32.
Crossing prices put the averages further away after Sunday. Monday's projection grid puts the 9-day crossing at 4,363.8, the 18-day at 4,396.6 and the 40-day at 4,435.5, and the 9-day stall sits at 4,332.8, 11.6 points above Friday's settle. From the 4,244.8 Sunday quote, even the nearest of those lines needs a recovery of the whole Sunday loss.
Momentum is weak without being stretched. Relative strength reads 38.31 on the 9-day, 42.52 on the 14-day, 45.34 on the 20-day, 47.69 on the 50-day and 49.05 on the 100-day, and the 14-day grid places its 50 percent line at 4,398.3 and its 30 percent line at 4,106.4. Stochastics stay low. The 9-day raw reading is 28.77 percent with %K at 23.30 percent and %D at 32.29 percent, the 14-day 22.23 percent with %K at 15.79 percent and %D at 22.16 percent, and the 20-day 11.55 percent. Friday's settle sat between the 4,316.4 stochastic 20 percent threshold and the 4,337.9 30 percent threshold.
Direction points down on every horizon read. The 9-day index reads 20.23 with positive direction at 11.35 under negative at 18.53; the 14-day reads 15.10 with 13.70 under 18.57, and the 20-day 13.04 with 15.34 under 18.76. The index readings are low. The downtrend is present but not strong. The composite multi-indicator read for Friday was 40% SELL, strength weak and direction weakening, with the short-horizon group at 20% SELL, the medium at 25% SELL and the long at 67% SELL. Refreshed with the live price at about 10:03 PM ET Sunday, it moved to 64% SELL with strength average and direction strengthening. The refreshed page lists 40% SELL for the prior session, hold a week ago and 72% BUY a month ago.
Volatility sets the scale. The 14-day average true range is 97.8 points, 2.26 percent of the settle, and the 14-day average daily range 93.1; the 9-day pair reads 92.8 and 84.4 and the 20-day 100.6 and 104.3. Friday's 62.4 point range was 0.67 times the 14-day average daily range. Historic volatility reads 12.17 percent on the 9-day, 12.31 percent on the 14-day and 19.29 percent on the 20-day. One average true range either side of Friday's settle frames 4,223.4 to 4,419.0. The deviation bands are tighter: 4,283.0 to 4,359.4 at one deviation, 4,267.2 to 4,375.2 at two and 4,255.0 to 4,387.4 at three. Sunday went through the bottom of all three.
Then the reopen. The December contract opened the Sunday session at 4,315.0, 6.2 points beneath Friday's settle. The first four 30-minute bars, from 06:00 PM to 08:00 PM ET, held between 4,315.6 and 4,291.9, above Friday's low, on 2,389, 1,241, 830 and 1,409 contracts. The 08:00 PM ET bar closed at 4,283.6 on 1,900. Volume then jumped. The 08:30 PM ET bar fell to 4,260.5 on 6,437 contracts and the 09:00 PM ET bar to 4,246.2 on 8,176. The partial 09:30 PM ET bar reached 4,239.3 on 3,042 contracts by the time it was read.
That is a 76.3 point range in under four hours, 0.78 times the 14-day average true range. The chart's daily bar read 4,245.7 at 10:02 PM ET, and chart and provider agree on the Sunday open, high and low. The break took out Friday's low, the 4,273.3 one-month low, Pivot S2 at 4,258.3 and three deviations support at 4,255.0. Pivot S3 at 4,227.3 stands 12.0 points beneath the Sunday low.
A 100.97 dollar, a 5.18 percent ten-year and no haven bid
Friday's gain came through the currency. The dollar index closed at 100.97, down 0.32 percent, inside a 100.87 to 101.31 range, after closing at 101.29 on Thursday. Provider commentary tied the dollar's decline to crude's slide, which eased inflation expectations, and to equity strength that curbed demand for liquidity, and said better data and hawkish Federal Reserve remarks limited the losses. The dollar against the yen fell 0.99 percent to 157.287. The news feed carried statements at 08:57 AM and 09:48 AM ET that Japan's finance minister and the United States Treasury Secretary had reaffirmed cooperation and discussed the yen's undervaluation.
Yields rose anyway. The ten-year yield index closed at 5.18 percent, up 2 basis points, after a 5.16 to 5.23 percent session, and the thirty-year closed at 5.50 percent, up 4. No real-yield series was captured, so that channel is not measured. The review reads a higher nominal yield alongside a lower dollar as gold rising through the currency, a reading of simultaneous daily changes.
Federal Reserve voices kept the rate channel tight. The Cleveland Federal Reserve president said between 02:47 PM and 02:58 PM ET, per the news feed, that a good economic outlook is pressuring yields up, that artificial-intelligence investment demand is competing for investors in the bond market and that the United States is on an unsustainable fiscal path. The same remarks called inflation expectations reasonably well anchored. Provider commentary called the New York Federal Reserve president's remarks on returning inflation to target hawkish. The latest captured projection item, stamped 02:00 PM ET on 09/16, recorded 12 of 18 officials seeing one more rate increase this year.
The data leaned firm. Headline durable goods orders were unchanged at 08:30 AM ET against a consensus decline of 0.3 percent, and core orders rose 0.3 percent against 0.6 percent, per the news-feed calendar and unconfirmed. Provider commentary put August nondefense capital goods orders excluding aircraft up 1.6 percent against 0.6 percent expected, with July revised to 0.6 percent. The final University of Michigan sentiment reading printed 48.1 against 47.5. One-year inflation expectations came in at 4.6 percent against a 4.7 percent forecast, per the news-feed calendar and unconfirmed. Friday's outlook had named that expectations figure as the more relevant number for gold, and it printed beneath forecast.
Two weekend headlines pulled in opposite directions, and gold answered neither in the usual way. On trade, the United States and China agreed after President Xi's visit to cut tariffs on 30 billion dollars of non-sensitive goods in each direction and to extend the truce by two months, from November 10 to about mid-January 2027, alongside a new artificial-intelligence dialogue, per press reports. At 09:45 PM ET Sunday China's commerce ministry said the ceasefire would run to January 2027, after most of gold's decline. That is growth relief. In our reading it also removes one reason to hold a hedge.
The war premium went the other way. After Friday's settle, between 04:19 PM and 04:22 PM ET, Iran's foreign minister described a seven-day plan to reopen the Strait of Hormuz. Per press reports, it asked the United States to release frozen funds, lift oil sanctions and end the naval blockade of Iranian ports within four to five days, with final talks by day seven. Press reports carried on the news feed at 08:27 PM and 08:28 PM ET Friday said the President rejected an Iran ceasefire and expects increased bombing after the midterm elections, a report that remains unconfirmed. On Saturday at 09:47 AM ET he said he rejects Iran's proposal.
Security headlines followed. Iranian media reported multiple missiles and drones fired at vessels near Qeshm Island, a report that remains unconfirmed with no verified damage count. The Revolutionary Guards said they had seized a United States underwater drone in the Strait, and Saudi Arabia said it intercepted Houthi drones aimed at the Riyadh area and a ballistic missile aimed at Khamis Mushait. Iran's president told the United Nations General Assembly that Tehran remains open to diplomacy.
Sunday evening added both sides at once. At 06:45 PM ET the President said he expects renewed Iran talks this week, and at 08:30 PM ET that he would not rule out more strikes. The second item coincided with the start of the 08:30 PM ET bar, the one in which gold fell hardest; the series shows timing only and establishes no cause. No haven bid appeared. The review's reading is that the crude and inflation-expectation channel, with firmer yields, outweighed the haven channel at the reopen.
The rest of the metals complex shows how broad the move was. Silver's December contract traded at 62.96 as the latest value in the still-open 09:30 PM ET bar, 2.84 percent beneath Friday's 64.801 quote. On Friday it had closed up 1.25 percent, outpacing gold's 0.54 percent. Copper traded 1.4 percent beneath its own Sunday open. Ten-year note futures traded beneath Friday's final 30-minute close throughout the session, which points to firmer yields, and the dollar against the yen traded at 157.762 against 157.287. Dollar index futures held a narrow 100.79 to 100.92 range. Silver down harder than gold with a flat dollar reads, in the review's interpretation, as liquidation across metals.
Friday's cross-asset pattern had been the reverse of Wednesday's. November crude settled at 92.41, down 2.33 percent, and Brent at 104.32, down 2.14 percent. The S&P 500 cash index closed at 7,743.41, up 0.51 percent, the Nasdaq-100 cash index at 30,608.13, up 0.42 percent, and the volatility index at 14.87, down 0.80 points. Gold moved with the dollar and against crude.
Structural demand stays unmeasured. No central bank purchase figure, Chinese import figure or official reserve series was captured. The gold exchange-traded fund closed at 393.41 on the provider's end-of-day record, up 1.72 or 0.44 percent from 391.69, on 7,695,507 shares; no holdings figure was captured, so fund flows are not asserted. Iran's president welcomed Chinese support for a return to the Islamabad memorandum of understanding at 03:01 PM ET, a diplomatic item and not a demand signal. On Sunday, Chinese industrial profits rose 15.7 percent year to date against 17.6 percent previously at 09:30 PM ET, and Japanese services producer prices printed 3.7 percent against 3.6 percent at 07:52 PM ET, both per the news feed.
Speculators were already cutting. The positioning report as of September 22, 2026 shows managed money long 135,699 contracts, down 6,695 on the week, against short 8,310, down 968, a net long of 127,389 that fell 5,727. Commercials held 57,458 long against 320,361 short, a net short of 262,903, and swap dealers 14,626 long against 250,752 short. Length was cut in the week that printed the 09/16 low while managed-money shorts also fell, which is consistent with long liquidation. That is interpretation, not a measured attribution. Open interest stood at 317,452 on the 09/24 row, up from 314,505 on 09/23, and the 09/25 row carries no figure yet.
The options book behind the gold fund is context only. The fund tracks bullion with a fee drag and has no clean basis to the futures contract, so nothing from it is translated into a futures level. Its console, updated Friday, showed a current price of 392.90 against a previous close of 391.73 on 6,493,831 shares, call gamma of minus 283 million dollars, put gamma of 215 million dollars and next-expiry gamma at 5.62 percent of the total, up from 3.20 percent in the prior review. The book remains concentrated in longer tenors. Short-dated hedging flows are unlikely to dominate Monday's action in the fund.
The trade map for Monday September 28
Overhead, the broken support now does the work. The 09/16 one-month low at 4,273.3, the 4,283.0 one-deviation line, Friday's 4,289.2 low and Pivot S1 at 4,289.7 form a 16.4 point band, and it is the band the setup sells. The 4,298.1 retracement and the 4,300.6 high of the 07:00 PM ET Sunday bar sit together above it, then the 4,303.9 published target price, Sunday's 4,315.6 high and the 4,320.7 Pivot Point. Only a full recovery of the Sunday loss brings the 4,337.9 stochastic threshold, the 4,348.5 oscillator stall and Pivot R1 at 4,352.1 back into view. Every settlement average, from the 5-day at 4,339.58 to the 20-day at 4,407.48, sits above the pivot.
Beneath the quote the map thins out. Two deviations support at 4,267.2, Pivot S2 at 4,258.3 and three deviations support at 4,255.0 were all traded through on Sunday and now serve as references for a bounce. Sunday's 4,239.3 low is the first live support, 5.5 points beneath the 09:51 PM ET quote. Pivot S3 at 4,227.3 and the 4,223.4 range projection sit within 3.9 points of each other beneath it. Beyond the ladder, the 08/05 session low at 4,121.6 is the nearest traded low in the settlement series, with the 4,106.4 relative-strength line and the 4,107.0 40-day stall just under it.
The Monday plan is a short from a rebound into 4,270 to 4,280. Four readings carry it. The contract broke Friday's low, the one-month low and the lower pivot and deviation lines on rising 30-minute volume. Silver fell harder. The composite refreshed with the live price moved to 64% SELL with direction strengthening. And the contract sits beneath every settlement average. The quote at the time of writing sat 25.2 to 35.2 points beneath the band, so the setup needs a rebound to fill and is not a chase of the break. The stop at 4,302 sits above Friday's low, Pivot S1, the 4,298.1 retracement and the 4,300.6 bar high.
The weekend short from 4,346 to 4,356, stop 4,380, targets 4,322, 4,293 and 4,264, is withdrawn. Its band never traded.
The rest of the night decides whether the 4,227.3 to 4,239.3 band holds. China's commerce ministry extended the trade ceasefire at 09:45 PM ET, after most of the decline. Bias is lower beneath the 4,273.3 to 4,289.7 band, with an expected band of roughly 4,220 to 4,280 for the rest of the night.
London works through the dollar, the London price-setting and whether silver steadies. A Bank of England policymaker speaks at 06:00 AM ET, per the news-feed calendar and unconfirmed. Bias lower, expected band roughly 4,215 to 4,285. A loss of Pivot S3 at 4,227.3 opens the 4,223.4 range projection and beyond.
New York brings Federal Reserve voices and no data. Vice Chair for Supervision Bowman speaks at 08:15 AM ET on bank supervision, as reported by the Federal Reserve Board schedule and unconfirmed against the verified forward calendar, and the President of the European Central Bank at 10:00 AM ET, per the news-feed calendar and unconfirmed. The ten-year yield remains the mechanical input; its Friday high was 5.23 percent. A recovery into 4,273.3 to 4,289.7 tests the break. Failure there keeps 4,227.3 to 4,239.3 in play. Expected band roughly 4,215 to 4,290.
Governor Cook speaks at 01:25 PM ET, as reported by the Federal Reserve Board schedule and unconfirmed, and the Richmond Federal Reserve president at 01:30 PM ET, per the news-feed calendar and unconfirmed. Gold settles at 01:30 PM ET, and a settle beneath 4,255.0 would confirm the break on a closing basis. Expected band for the afternoon roughly 4,220 to 4,285. No structural gold expiry falls on Monday; the provider lists the December contract's first notice as 11/30/26 and its expiration as 12/29/26.
The week's anchors come later. The Reserve Bank of Australia decides at 12:30 AM ET Tuesday, per the news-feed calendar and unconfirmed, and job openings print at 10:00 AM ET Tuesday. Governor Barr speaks on the economic outlook at 12:40 PM ET Tuesday, as reported by the Federal Reserve Board schedule and unconfirmed. Personal income and outlays arrive at 08:30 AM ET on September 30, 2026, with the third estimate of second-quarter GDP, and the September employment report at 08:30 AM ET on October 2, 2026, per the verified forward calendar. Press-report previews, unconfirmed, put the payrolls consensus near 100,000 with unemployment seen at 4.2 percent from 4.1 percent.
Three cases frame Monday: 4,225 to 4,275 on the low-range case, 4,205 to 4,290 on the mid-range case, which is the most likely, and 4,160 to 4,320 on the high-range case. In our analyst judgment the contract stays beneath the broken band through Asia and Europe, with at least one test of the 4,227.3 to 4,239.3 support. A rebound toward the band in the United States morning is weighted as more likely to fail than to recover it. The composite strengthened on the sell side, the directional readings point down and silver fell harder than gold. A settle back above Pivot S1 at 4,289.7 would invalidate that reading, turn Sunday into a failed breakdown and put the 4,320.7 Pivot Point back in play.
Friday's gold outlook drew its second target at 4,254, and by 10:01 PM ET Sunday the reopened contract was trading beneath it.
The complete data picture
Every number behind Monday’s plan, charted first, then the full level lists, then the complete numeric reference underneath.
Full numeric reference, the remaining figures from the session review
Carried below in the review’s own words: the Sunday session update, the session review, daily and swing structure, averages, oscillators and volatility from section 2, the macro drivers from section 4, the fund proxy note from section 5 and the Monday calendar from section 7.
Sunday session update
Gold broke down at the Sunday reopen, and this report replaces the weekend update written before it. The December contract opened the Sunday session at 4,315.0, 6.2 points beneath Friday's 4,321.2 settle, and the provider quoted it at 4,244.8, down 76.4 points or 1.77 percent, at 09:51 PM ET; the chart's daily bar read 4,245.7 at 10:02 PM ET. The Sunday session has traded between 4,315.6 and 4,239.3, a 76.3 point range that is already 0.78 times the published 14-day average true range of 97.8 points.
The path is taken from the provider's 30-minute series for the December contract, preserved with this review. The first four 30-minute bars, from 06:00 PM to 08:00 PM ET, held between 4,315.6 and 4,291.9, above Friday's 4,289.2 low. The 08:00 PM ET bar closed at 4,283.6, beneath that low. The 08:30 PM ET bar then fell to 4,260.5 on 6,437 contracts, the 09:00 PM ET bar to 4,246.2 on 8,176 contracts and the 09:30 PM ET bar, still open when it was read, to 4,239.3. The break therefore took out Friday's low, the 09/16 one-month low at 4,273.3, Pivot S2 at 4,258.3 and three standard deviations support at 4,255.0 within the three 30-minute bars from 08:00 PM to 09:30 PM ET, and 4,239.3 is the lowest price the contract has traded since the 08/05 session, whose low was 4,121.6.
The weakness was not confined to gold. Silver's December contract traded at 62.96 as the latest value in the still-open 09:30 PM ET bar, read at 10:01 PM ET, 2.84 percent beneath Friday's 64.801 quote, and copper traded 1.4 percent beneath its own Sunday open. The dollar against the yen traded at 157.762 as the latest value in the still-open 09:30 PM ET bar, read at 10:01 PM ET against 157.287 on Friday's quote list, and ten-year note futures traded beneath Friday's final 30-minute close throughout the Sunday session, which points to firmer yields. The dollar index futures contract stayed in a narrow 100.79 to 100.92 range, so the move did not come through a broad dollar rally. In this review's interpretation the decline reads as a metals-wide liquidation into the Asian open rather than a response to one headline.
The weekend news flow was mixed for gold. After the Friday close, per press reports carried on the news feed at 08:27 PM and 08:28 PM ET, the President rejected an Iran ceasefire and said he expects increased bombing after the midterm elections, a press report that remains unconfirmed; he repeated on Saturday at 09:47 AM ET that he rejects Iran's proposal. On Sunday the news feed carried two press items: at 06:45 PM ET the President said he expects renewed Iran talks this week, and at 08:30 PM ET he said he would not rule out more Iran strikes. The second item coincided with the start of the 08:30 PM ET bar in which gold fell hardest; the series shows the timing only and does not establish a cause. At 09:45 PM ET China's commerce ministry said the trade ceasefire with the United States would be extended to January 2027, after most of the decline. Japanese services producer prices printed 3.7 percent against a 3.6 percent forecast at 07:52 PM ET, and Chinese industrial profits rose 15.7 percent year to date against 17.6 percent previously at 09:30 PM ET, both per the news feed.
2.1 Intraday and session review
The completed Friday session opened at 4,309.5, 11.5 points above Thursday's settle, marked a high of 4,351.6 and a low of 4,289.2, and settled at 4,321.2. No intraday series was captured for the Friday session, so the order in which Friday's extremes were reached is not asserted and no Friday path claim appears in this review; the Sunday path statements rest on the preserved Sunday series described in the Sunday session update. What the daily bar establishes is geometry: the settle finished 11.7 points above the open, 32.0 points above the low and 30.4 points beneath the high, which places it at 51.3 percent of the 62.4 point range.
The session extremes used here are the completed-session inputs behind the published pivot ladder rather than an independently read bar, back-solved from the outer pivot pairs and verified against every rung. The third resistance point at 4,414.5 minus the third support point at 4,227.3, divided by three, returns 62.4, and the second resistance point at 4,383.1 minus the second support point at 4,258.3, divided by two, returns the same 62.4. Three times the unrounded Pivot Point of 4,320.667, published as 4,320.7, less the 4,321.2 settle gives a high plus low sum of 8,640.8, and the resulting pair of 4,351.6 and 4,289.2 reproduces all seven published rungs. Because Globex does not reopen on a Friday evening, the provider's overview page dated for the Friday session shows the same completed-session open, high and low, and the chart's daily bar shows the same values, so the extremes are corroborated by an independent surface. The chart's last 30-minute bar closed at 4,320.5, a post-settlement electronic print that is not used as the settle.
2.2 Daily structure
Friday's bar sits above Thursday's on both ends, its high at 4,351.6 stayed 55.9 points beneath Wednesday's 4,407.5 high, and its low at 4,289.2 held 15.9 points above the 09/16 low of 4,273.3, which is also the one-month low. The week of September 21 through September 25 spanned 4,422.1 at the high on Monday and 4,278.3 at the low on Thursday, and settled at 4,321.2. The prior week, September 14 through September 18, spanned 4,439.8 to 4,273.3, so this week's range sits inside the prior week's range.
For the quarterly reference the review uses the 13-week extremes as the available proxy, because no prior-quarter high or low was captured this run. The 13-week high stands at 4,755.0, set on 08/25/26, and the 13-week low at 4,015.6, set on 06/30/26. The settle sits 433.8 points beneath the 13-week high and 305.6 points above the 13-week low.
2.3 Swing structure
The daily settlement sequence after the 09/18 settle of 4,424.9 reads 4,383.9, 4,376.4, 4,318.4, 4,298.0 and then 4,321.2. Friday's gain recovered 23.2 of the 126.9 points lost across the four lower settles, or 18.3 percent of the decline. Daily ranges ran 61.8 on Monday, 86.5 on Tuesday, 96.8 on Wednesday, 59.7 on Thursday and 62.4 on Friday, so Friday's range was 2.7 points wider than Thursday's.
The retracement grid published for Monday places the 38.2 percent retracement from the 13-week low at 4,298.1, 23.1 points beneath the settle, and the 50 percent retracement of the 13-week range at 4,385.3. The 38.2 percent retracement from the four-week low sits at 4,448.1 and from the 13-week high at 4,472.5. No four-hour series was captured this run, so the four-hour swing sequence is not described.
2.4 Moving averages
The averages cited in this subsection were computed this run from the provider's daily settlement series for the December contract, preserved in the coverage receipt, which holds 260 completed sessions. The 5-day average stands at 4,339.58, the 9-day at 4,360.31, the 20-day at 4,407.48, the 50-day at 4,366.31, the 100-day at 4,392.61 and the 200-day at 4,647.73. The provider's published 5, 20, 50, 100 and 200 day figures reproduce from the same rows.
The 4,321.2 settle sits 18.4 points beneath the 5-day average, 39.1 beneath the 9-day, 45.1 beneath the 50-day, 71.4 beneath the 100-day, 86.3 beneath the 20-day and 326.5 beneath the 200-day. The 20-day average sits above the 100-day and the 50-day because the last 20 settles averaged higher than the last 100 and the last 50; it is falling, down 17.14 points from Thursday's 4,424.62, while the 50-day rose 5.45 points to 4,366.31. The 5-day average fell 20.74 points from 4,360.32.
The projection grid gives the prices at which each average would be crossed on Monday: 4,363.8 for the 9-day, 4,396.6 for the 18-day and 4,435.5 for the 40-day. The 9-day stall at 4,332.8 sits 11.6 points above the settle.
2.5 Oscillator and trend readings
The oscillator figures below are as published on the provider's technical page for the Friday session. Relative strength reads 38.31 on the 9-day, 42.52 on the 14-day, 45.34 on the 20-day, 47.69 on the 50-day and 49.05 on the 100-day. The published 14-day relative-strength grid places the 50 percent line at 4,398.3 and the 30 percent line at 4,106.4, so the 14-day reading sits in the lower half of its band without approaching the lower extreme.
Stochastics remain low. The 9-day raw stochastic reads 28.77 percent with %K at 23.30 percent and %D at 32.29 percent; the 14-day raw stochastic reads 22.23 percent with %K at 15.79 percent and %D at 22.16 percent; the 20-day raw stochastic reads 11.55 percent. The published grid places the 14-3 day raw stochastic 20 percent threshold at 4,316.4 and the 30 percent threshold at 4,337.9, so the settle sits between them.
The directional system still points down on every horizon read. On the 9-day the directional index reads 20.23 with positive direction at 11.35 and negative direction at 18.53; on the 14-day it reads 15.10 with positive direction at 13.70 under negative at 18.57, and on the 20-day 13.04 with positive direction at 15.34 under negative at 18.76. The directional index readings are low, so the downtrend is present but not strong. Historic volatility reads 12.17 percent on the 9-day, 12.31 percent on the 14-day and 19.29 percent on the 20-day.
The composite multi-indicator read, quoted verbatim from the snapshot captured this run, is 40% SELL, with current strength Weak and current direction Weakening. The composite indicator itself reads SELL. The short-horizon group averages 20% SELL, the medium-horizon group 25% SELL and the long-horizon group 67% SELL. The snapshot history published on the same page reads Yesterday 48% SELL, Last Week 32% BUY and Last Month 72% BUY.
2.6 Volatility and expected range
The published 14-day average true range stands at 97.8 points, 2.26 percent of the settle, and the 14-day average daily range at 93.1 points; the 9-day figures are 92.8 and 84.4, and the 20-day figures 100.6 and 104.3. Friday's realised 62.4 point range was 0.67 times the 14-day average daily range.
A one-range projection from the 4,321.2 settle using the 14-day average true range of 97.8 points frames Monday between 4,223.4 and 4,419.0. The published standard-deviation bands are tighter: one deviation spans 4,283.0 to 4,359.4, two spans 4,267.2 to 4,375.2 and three spans 4,255.0 to 4,387.4.
4.1 Dollar and real yields
The dollar index closed at 100.97, down 0.32 points or 0.32 percent, inside a 100.87 to 101.31 range, after closing at 101.29 on Thursday. Provider commentary attributed the dollar's decline to crude's slide, which eased inflation expectations, and to equity strength that curbed liquidity demand, and described the losses as limited by better United States data and by hawkish remarks from the New York Federal Reserve president. The dollar against the yen fell 0.99 percent to 157.287 on the provider's quote list, and the news feed carried statements at 08:57 AM and 09:48 AM ET that the Japanese finance minister and the United States Treasury Secretary had reaffirmed cooperation and discussed the yen's undervaluation.
The ten-year yield index closed at 5.18 percent, up 2 basis points. Its Friday session range ran from 5.16 to 5.23 percent, and the thirty-year closed at 5.50 percent, up 4 basis points. No real-yield series was captured this run, so the real-yield channel is not measured; the nominal rise against a lower dollar is read, as an interpretation of simultaneous daily changes rather than a measured decomposition, as gold's gain coming through the currency rather than through lower rates.
4.2 Fed and monetary policy
The Cleveland Federal Reserve president spoke between 02:47 PM and 02:58 PM ET, per the news feed, saying that rising bond yields reflect a number of factors, that a good economic outlook is pressuring yields up, that artificial-intelligence investment demand is competing for investors in the bond market, that the United States is on an unsustainable fiscal path, and that inflation expectations are reasonably well anchored. Provider commentary described remarks by the New York Federal Reserve president that the Fed needs to return inflation to target as hawkish. The latest captured projection item, stamped 02:00 PM ET on 09/16, recorded 12 of 18 officials seeing one more rate increase this year.
On the data side, the durable goods report released at 08:30 AM ET showed headline orders unchanged against a consensus decline of 0.3 percent and core orders up 0.3 percent against a 0.6 percent consensus, per the news-feed calendar and unconfirmed, while provider commentary put August nondefense capital goods orders excluding aircraft up 1.6 percent against 0.6 percent expected, with July revised to 0.6 percent. The final University of Michigan sentiment reading printed 48.1 against a 47.5 consensus, with one-year inflation expectations at 4.6 percent against a 4.7 percent forecast, per the news-feed calendar and unconfirmed.
4.3 Geopolitical backdrop
Friday's session leaned toward de-escalation: the news feed carried a press report at 11:55 AM ET that the Iran and United States talks had entered a technical stage, and after the settlement but before the 5:00 PM ET end of electronic trading, between 04:19 PM and 04:22 PM ET, Iran's foreign minister described a seven-day plan to reopen the Strait of Hormuz. The weekend reversed that: press reports carried on the news feed at 08:27 PM and 08:28 PM ET Friday said the President rejected an Iran ceasefire and expects increased bombing after the midterm elections, a press report that remains unconfirmed, and on Saturday at 09:47 AM ET he said he rejects Iran's proposal. The weekend update records the unconfirmed report of missile fire near Qeshm Island and the Saudi interceptions. On Sunday the President said at 06:45 PM ET that he expects renewed Iran talks this week and at 08:30 PM ET that he would not rule out more strikes, both per press items on the news feed.
For gold the geopolitical channel did not produce a haven bid on Sunday: the contract fell while the headlines alternated between talks and strikes. In this review's interpretation the crude and inflation-expectation channel, together with firmer yields, outweighed the haven channel at the reopen; that is a reading of simultaneous moves, not a measured decomposition.
4.4 Structural demand
No central bank purchase figure, Chinese import figure or official reserve data was captured this run. The gold exchange-traded fund closed at 393.41 on the provider's end-of-day record, up 1.72 or 0.44 percent from 391.69, on volume of 7,695,507 shares; no holdings figure was captured, so fund flows are not asserted. The news feed carried a statement at 03:01 PM ET by Iran's president welcoming Chinese support for a return to the Islamabad memorandum of understanding, which is a diplomatic item, not a demand signal.
4.5 Energy and cross-asset
The November crude contract settled at 92.41, down 2.33 percent, and Brent's November contract at 104.32, down 2.14 percent, per the news feed. The S&P 500 cash index closed at 7,743.41, up 0.51 percent, the Nasdaq-100 cash index at 30,608.13, up 0.42 percent, and the volatility index at 14.87, down 0.80 points. Silver's December contract closed at 64.801, up 1.25 percent, on the provider's quote list, outpacing gold's 0.54 percent. The cross-asset pattern of lower crude, a lower dollar and higher equities is the reverse of Wednesday's, and gold participated with the dollar rather than with yields.
4.6 Institutional positioning
The positioning report as of September 22, 2026 shows managed money long 135,699 contracts, down 6,695 on the week, against short 8,310, down 968, a net long of 127,389 that fell 5,727 contracts on the week. Commercials held 57,458 long against 320,361 short, a net short of 262,903, and swap dealers held 14,626 long against 250,752 short. Managed-money length was cut in a week in which the contract made the 09/16 low, which is consistent with liquidation of long exposure rather than new short selling, and that reading is interpretation, not a measured attribution.
Open interest on the December contract stood at 317,452 on the latest published row for 09/24, up from 314,505 on 09/23; the 09/25 row carries no open-interest figure yet.
5. Gold fund proxy
The gold exchange-traded fund is used here qualitatively only. It tracks bullion with a fee drag and at a ratio that has no clean basis to the futures contract, so no level from it is translated into a futures price anywhere in this review.
The positioning console for the fund, updated on Friday, showed a current price of 392.90 in its watchlist row against a previous close of 391.73, with share volume of 6,493,831, call gamma of minus 283 million dollars and put gamma of 215 million dollars, and next-expiry gamma at 5.62 percent of the total. The console's summary header on the same page showed a previous close of 392.78 and a daily change of 0.03 percent, which matches Thursday's header value and is treated as stale; the conflict is recorded rather than resolved. The provider's end-of-day record for the fund shows a 393.41 close against 391.69 on Thursday. The console's high-volatility-point and low-volatility-point fields, published as 444 and 319, are excluded as low-confidence per the known defect in that pair of fields.
The qualitative read: next-expiry gamma rose to 5.62 percent of the total from the 3.20 percent recorded in the prior review, but the fund's options book remains concentrated in longer tenors, so short-dated hedging flows are unlikely to dominate Monday's price action in the fund. No gamma-derived level is used for the futures contract, and nothing in section 3 originates from this proxy.
7. Monday calendar
The Sunday session opened at 6:00 PM ET after the weekend closure. Japanese services producer prices printed 3.7 percent against a 3.6 percent forecast at 07:52 PM ET Sunday, and the Bank of Japan published its meeting minutes, per the news feed.
On Monday, Vice Chair for Supervision Bowman speaks at 08:15 AM ET on bank supervision and regulation and Governor Cook at 01:25 PM ET on artificial intelligence and emerging technology, as reported by the Federal Reserve Board schedule and unconfirmed against the verified forward calendar. The European morning carries remarks by a Bank of England policymaker at 06:00 AM ET, and the United States morning carries remarks by the President of the European Central Bank at 10:00 AM ET, both per the news-feed calendar and unconfirmed. In the afternoon a European Central Bank board member speaks at 12:10 PM ET and the Richmond Federal Reserve president at 01:30 PM ET, both per the news-feed calendar and unconfirmed. The verified forward calendar carries no Monday release.
The single first-order event for gold on Monday is not a scheduled release but whether the Sunday break holds through the London and New York sessions, with Vice Chair for Supervision Bowman at 08:15 AM ET the first scheduled Federal Reserve voice, as reported by the Federal Reserve Board schedule and unconfirmed against the verified forward calendar. No structural gold expiry falls on Monday; the provider lists the December contract's expiration as 12/29/26 and first notice as 11/30/26.
Sources and methodology
This outlook is built from our session review of the December COMEX gold contract, GCZ26, tracked on the continuous GC1! chart, prepared after Friday’s close on September 25, 2026 for the Monday, September 28, 2026 session and rewritten after the Sunday reopen, with the Sunday session read at 10:01 PM ET. Friday’s extremes are back-solved from the published pivot ladder, verified against all seven rungs and matched by the overview page and the chart’s daily bar. The six settlement averages were computed from a 260-row daily settlement series. Oscillator readings are cited as published for the Friday session, and the composite read is quoted twice: as published for Friday and as refreshed with the live price at about 10:03 PM ET Sunday.
The Sunday path comes from the provider’s 30-minute series for the December contract, captured at 10:01 PM ET; the 9:30 PM ET bar was still open when it was read. The Sunday open, high and low agree across the provider’s overview page and the chart’s daily bar, and the silver, copper, yen and dollar-index Sunday values are latest values in the still-open bar. The gold fund is used qualitatively and was not re-read on Sunday. Weekend and Sunday headlines are press items carried on the news feed, attributed and time-stamped, and none is independently authenticated. Items marked unconfirmed come from the news-feed calendar or the Federal Reserve Board schedule. The look-back sets the published lines against the completed bar and asserts no fill and no order of events. Scenario ranges are analyst judgment and carry no calibration.
Not captured, and stated nowhere as a figure: any Friday intraday series, a four-hour series, a prior-quarter high or low, a real-yield series, a central bank purchase figure, a Chinese import figure, official reserve data and fund holdings.
Friday’s outlook for this contract is here, and Monday’s crude outlook is here. Outlooks for the equity index, technology index, gold and crude contracts are collected on the market outlook page, and our forward trading record is on the performance statement.