At 8:00 PM ET on Sunday, two hours after the reopen, the December Nasdaq-100 contract climbed to 28,762.50 and traded into the short band we published for Monday. By 10:30 PM ET it had closed two straight 30-minute bars above the band's 28,780 top. Our card defined that as the point where the edge is gone. The stop never traded. Monday's high, 28,891.25 in the 10:00 AM ET bar, stopped 8.75 points beneath it.
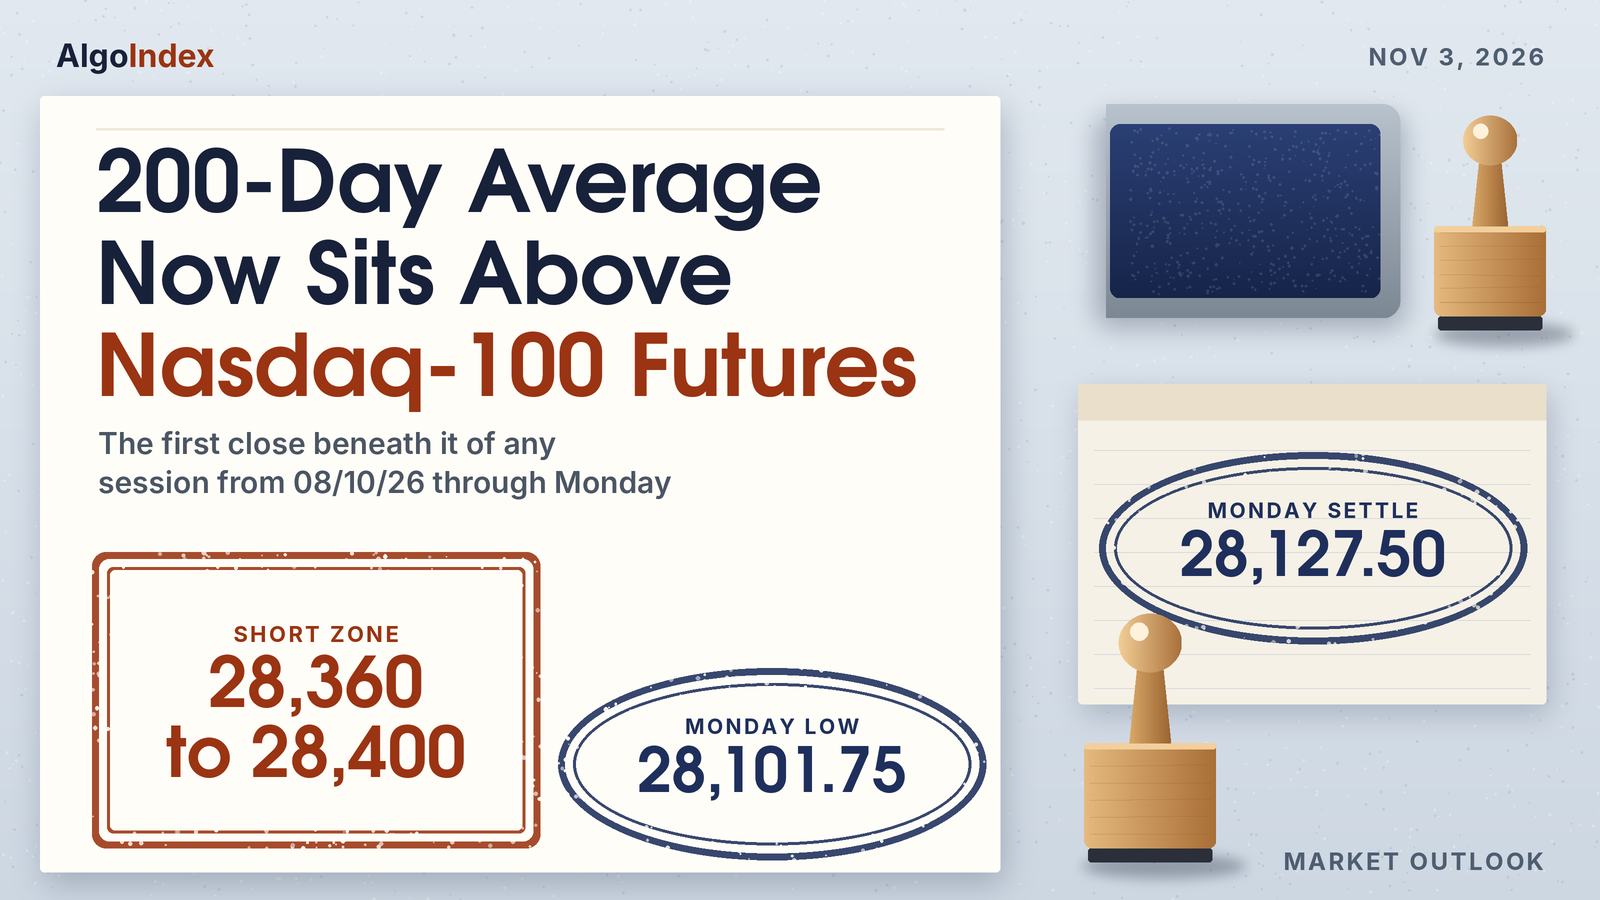
Then the selling came. The contract settled at 28,127.50, down 406.50 points, or 1.42 percent, at 3.3 percent of a 789.50 point range. It was the third straight lower settle and the lowest since 07/29/26. It was also the first settle beneath the 200-day average since 08/10/26, the first date with a full 200-session window in the settlement series. Tuesday's band sits above the settle.
December Nasdaq-100 futures settled at 28,127.50 on Monday, down 406.50 points, with a lower high and a lower low, beneath every settlement average including the 200-day. Monday's published short band at 28,740 to 28,780 traded in the 8:00 PM ET Sunday bar, and two 30-minute closes above 28,780 followed at 10:00 PM ET and 10:30 PM ET, the acceptance the card defined as removing the edge. The 28,900 stop never traded; the high stopped 8.75 points beneath it. All three targets traded later, between the 12:00 PM ET and 2:00 PM ET bars. No fill or result is asserted. The primary setup for Tuesday is a short from 28,360 to 28,400, a band above the settle around the 28,373.50 Pivot Point, stop 28,520, targets 28,240, 28,100 and an extended 27,960. Factory orders and the JOLTS report are scheduled for 10:00 AM ET, as the calendar lists them, and the midterm elections take place on Tuesday, per the news-feed calendar and unconfirmed.
Monday’s card: the band traded on Sunday evening, and the stop stayed 8.75 points out of reach
In Monday’s outlook we set a short from 28,740 to 28,780, stop 28,900. Its targets sat at 28,620, 28,480 and an extended 28,340. Monday's bar, from the review and the provider's 2026-11-02 settlement row, opened at 28,587.75 at the Sunday 6:00 PM ET reopen, made a high of 28,891.25 and a low of 28,101.75, and settled at 28,127.50. The open sat 152.25 points beneath the band.
The band traded early. The 30-minute bar that opened at 8:00 PM ET on Sunday reached 28,762.50, 22.50 points into it. Then came the card's own test. Its invalidation set the rule: a touch alone leaves the edge in place, and acceptance above the band removes it, defined as two consecutive 30-minute closes above 28,780. The 10:00 PM ET bar closed at 28,790.00 and the 10:30 PM ET bar at 28,801.25. Test met. Nine 30-minute closes finished above 28,780 over the session.
The stop held its distance. The high came in the 10:00 AM ET bar, 8.75 points beneath 28,900, and that bar closed at 28,886.50, the highest close of the session. The next bar closed at 28,725.75. The settle invalidation, a settle above Pivot R1 at 29,065.08, was never close. The settle finished 937.58 points beneath it.
The targets came after midday. The 28,587.75 open had sat 32.25 points beneath the 28,620 first target before the band ever traded. After the band, 28,620 next traded in the 12:00 PM ET bar. The 12:30 PM ET bar stopped 5.00 points above the 28,480 second target, which traded in the 1:30 PM ET bar. The 28,340 third target followed in the 2:00 PM ET bar. The low, 238.25 beneath that third target, came in the 3:30 PM ET bar. With the acceptance test met first, no fill and no result are asserted.
The card's macro override named a cash-session recovery in semiconductors or a weekend headline read as de-escalation in the Gulf. Its reference, Pivot R1 at 29,065.08, did not trade; the high stopped 173.83 points beneath it. This article ties no price move to any headline.
The 30-minute series also scores each range over its own window. The most likely case of 28,100 to 28,950 held the whole session, its bottom 1.75 points beneath the low and its top 58.75 above the high. The high-range case of 27,740 to 29,330 held too. The low-range case of 28,250 to 28,800 missed both ends, by 148.25 at the bottom and 91.25 at the top. The night band of 28,250 to 28,800, scored from 6:00 PM ET to 3:00 AM ET, held the night's 28,587.00 low, but the 28,831.50 night high topped it by 31.50.
London's 28,200 to 28,850, from 3:00 AM to 8:00 AM ET, held. So did the morning band of 28,150 to 28,900, with 8.75 to spare at the top. From 12:00 PM to 4:00 PM ET the contract traded between 28,101.75 and 28,686.25, inside the afternoon band of 28,100 to 28,950 by 1.75 at the bottom.
The most probable path, an analyst judgment, kept the contract between two standard deviations support at 27,739.63 and Pivot R1 at 29,065.08. It weighted a rebound toward the Pivot Point at 28,648.92 that failed beneath the 28,934.15 combination-level equivalent. The contract traded through that Pivot Point in the first 30-minute bar. Its high stopped 42.90 points beneath the equivalent, and the low stayed 362.12 above the deviation band. The downside alternative, a reopen beneath Friday's 28,232.75 low, did not occur. The open sat 355.00 above it.
A 137.68 point basis, a band around the Pivot Point and every average overhead
The basis narrowed to 137.68 points, the 28,127.50 settle less the 27,989.82 cash close, from 149.15 on Friday. The review converts five positioning levels at it. The NDX 28,000 put side support base becomes 28,137.68. The NDX 27,959 combination level becomes 28,096.68 and the NDX 28,356 combination level 28,493.68. The modeled volatility threshold at NDX 28,500 becomes 28,637.68, and the modeled gamma-flip level at NDX 28,742 becomes 28,879.68. The conversions are the review's own. Only one sits beneath the settle.
Resistance starts at once. The put-base equivalent sits 10.18 points up, then the 28,223.75 post-settlement print from the 4:30 PM ET bar and Friday's 28,232.75 low. The Pivot Point at 28,373.50 is next, 246.00 up. Three levels sit within 31.68 points: the 200-day average at 28,462.00, the 61.8 percent retracement from the 52-week low at 28,488.88 and the 28,493.68 combination equivalent. Friday's 28,534.00 settle and Monday's 28,587.75 open follow. The 28,637.68 threshold equivalent and Pivot R1 at 28,645.25 sit 7.57 apart.
Higher up sit the one-ATR line at 28,758.29, the 28,879.68 flip equivalent and Monday's 28,891.25 high, 11.57 points apart. One standard deviation resistance at 28,950.14 comes next. Then Pivot R2 at 29,163.00 and Friday's 29,180.00 open and high. The 5-day average at 29,203.00 and the 9-day crossing price at 29,214.00 sit 11.00 apart. Two standard deviations resistance at 29,290.89, the 9-day average at 29,302.00, Pivot R3 at 29,434.75 and three standard deviations resistance at 29,552.36 close the ladder. Beyond it sit the 100-day at 29,926.00, the 20-day at 29,974.50, the 50-day at 30,034.75 and the 30,178.00 high of the week of October 26. The 31,616.50 52-week high of 10/06 caps the list, 3,489.00 points or 11.04 percent up.
Support is thin near the settle. Monday's 28,101.75 low sits 25.75 points down, with the 28,096.68 combination equivalent 5.07 beneath it. Then a gap of 179.17 points. The price at which 14-day relative strength would reach 30, 27,917.51, and Pivot S1 at 27,855.75 come next. The 3-10 day crossover stall level at 27,692.71, the published target price at 27,604.03 and Pivot S2 at 27,584.00 follow. Three references sit within 30.00 points. They are the 50 percent retracement of the 52-week range at 27,522.75, the one-ATR line at 27,496.71 and the 27,492.75 low of 07/30/26. One standard deviation support at 27,304.86, Pivot S3 at 27,066.25, two deviations at 26,964.11 and three at 26,702.64 are the extended references.
Every average sits overhead. The settle sits 334.50 points beneath the 200-day at 28,462.00, 1,075.50 beneath the 5-day at 29,203.00 and 1,174.50 beneath the 9-day at 29,302.00. It sits 1,798.50 beneath the 100-day at 29,926.00, 1,847.00 beneath the 20-day at 29,974.50 and 1,907.25 beneath the 50-day at 30,034.75. The review computed the averages from 259 completed daily settlements and rounded each once to the 0.25 tick. The 5-day fell 262.00 from Friday's 29,465.00 as the 10/26 settle of 29,437.25 left the window. The 20-day fell 159.50 from 30,134.00 as the 10/05 settle of 31,317.75 dropped out.
The order of the longer averages comes from their older settlements. The 30 older ones in the 50-day window averaged 30,075.04, higher than the 20-day, so the 20-day sits beneath the 50-day. The 50 older ones in the 100-day window averaged 29,817.22 and the 100 older ones in the 200-day window 26,997.91. Tuesday's 9-day crossing price is 29,214.00, 1,086.50 points above the settle.
Momentum sits near the bottom of its scale. Relative strength reads 26.51 on the 9-day, 31.40 on the 14-day and 35.51 on the 20-day. The raw stochastics read 1.24 percent on the 9-day and 0.92 percent on the 14-day. The 14-day %K at 12.39 percent sits 11.82 points beneath %D at 24.21 percent. Sellers lead both windows. On the 9-day, negative direction at 35.50 tops positive at 12.22 by 23.28, with the ADX at 36.85; on the 14-day, 33.06 tops 13.66 by 19.40, with the ADX at 27.02. Historic volatility reads 26.68 percent and 24.86 percent. These readings are as published, read at 6:25 PM ET on Monday after the Globex reopen, and may already reflect the reopened session's price.
A composite multi-indicator read published for Tuesday sits at 72 percent sell, with strength described as strong and direction as strongest, against 56 percent sell in the prior session's snapshot. A week ago it read 32 percent sell. A month ago, 88 percent buy. The short-horizon group averages 100 percent sell, the medium 50 percent sell and the long 33 percent sell.
Monday's bar finished near its low. The open at 28,587.75 sat 53.75 points above Friday's settle, and the settle finished 763.75 beneath the high and 25.75 above the low. The high sat 288.75 points beneath Friday's and the low 131.00 beneath Friday's. The 789.50 point range was 1.18 times the 14-day average daily range of 668.79. The 14-day average true range stands at 630.79 points; the 9-day figures are 687.70 and 638.86 and the 20-day figures 595.60 and 589.78. The week of October 26 spanned 30,178.00 to 28,232.75.
One average true range either side of the settle spans 27,496.71 to 28,758.29. The deviation bands, built from five settlements and centred on the settle, run 27,304.86 to 28,950.14, 26,964.11 to 29,290.89 and 26,702.64 to 29,552.36. They describe settlement dispersion only. Ten sessions of daily ranges read 511.75, 385.50, 960.25, 339.00, 548.00, 593.25, 503.75, 683.25, 947.25 and 789.50 points. The settlement changes over those sessions net to minus 1,595.00. Over five sessions the contract is down 1,309.75 points from the 29,437.25 settle of 10/26.
The four-hour bars tell the same story. They closed at 28,776.00, 28,771.00, 28,773.25, 28,696.00, 28,441.50 and 28,223.75. The first gained 188.25 from the open. The one that opened at 10:00 AM ET made the session high and then fell furthest, 251.50 points from 28,693.00. The 2:00 PM ET bar fell a further 217.75.
A 1.39 percent cash decline, a 3.37 percent chip slide and results after Monday’s close
Technology lagged again. The Nasdaq-100 cash index closed at 27,989.82, down 395.03 points or 1.39 percent, after trading between 28,753.39 and 27,967.44. The S&P 500 cash index fell 0.51 percent and the Dow industrials rose 0.41 percent. The semiconductor index fell 3.37 percent to 10,328.33. The news feed's market wrap described the Nasdaq-100 entering a correction amid a chipmaker selloff. The provider's commentary described an early advance that faded through the session, and defensive buying in large consumer and industrial stocks as investors rotated out of technology. In the review's reading, the rotation away from technology that the feeds described last week continued for a third session.
Results came after the bell. A consumer-electronics maker and a data-analytics software group reported after the cash close on Monday, as the calendar lists them. The news feed carried both above estimates. It carried the first at 2.10 dollars a share against an estimate of 2.00, with revenue of 114.48 billion against 113.47 billion. It carried the second's adjusted earnings at 0.44 dollars against 0.41, with revenue of 2.31 billion against 2.17 billion and a raised full-year revenue outlook. These are results carried by the news feed.
Other items ran through the day. The feed carried a press report that a database-software company's 10 billion dollar share sale drew excess demand, and items on bond sales by two large internet-platform companies. The provider's commentary described continued selling in chipmakers and artificial-intelligence infrastructure stocks. This article ties no price move to any of them.
Yields eased. The ten-year yield index closed at 4.89 percent, against 4.92 percent on Friday. Market pricing showed a 74 percent chance of a quarter-point Fed increase at the next meeting, per the provider's commentary and unconfirmed. The US manufacturing survey rose to 55.5, per the provider's commentary and unconfirmed. Construction spending, released at 10:00 AM ET as the calendar lists it, fell 1.9 percent against an expected gain, per the provider's commentary and unconfirmed. In the review's interpretation, Monday's decline was sector-driven rather than rate-driven. No real-yield series was captured, so no real-yield level is asserted.
The news feed carried a state media report at 8:30 AM ET that Iran's Supreme Leader had granted the government authority in negotiations. It also carried the President's afternoon remarks that there was no rush to decide on restarting the war, and reports after the close of explosions heard on Qeshm Island and off Bandar Lengeh. These are reports carried by the feeds, not confirmed events.
Elsewhere, December WTI crude fell 7.36 percent to 96.46 and December gold rose 1.81 percent. The dollar index's daily record eased to 101.75 from 101.88. The volatility index closed at 21.15 against 19.42, after a session high of 21.77. Each move is reported on its own. None is presented here as the cause of another, or of the index's decline.
The cash close sits beneath every positioning line. The dataset's reference prices are Friday's closes: NDX 28,384 corresponds to Friday's 28,384.85 cash close, and QQQ 690 to the fund console's previous close of 690.56. Against Monday's 27,989.82 close, the index sits 10.18 points beneath the 28,000 put side support base. It sits 510.18 beneath the 28,500 modeled volatility threshold and 752.18 beneath the 28,742 modeled gamma-flip level. The largest gamma concentration at 29,000 sits 1,010.18 up, and the call side ceiling at 29,675 sits 1,685.18 up. The index model's gamma tilt reads 0.743 and its gamma notional minus 5.645 million dollars, both model outputs. The dataset lists 29,000, 28,000, 29,675 and 30,000 as key index strikes. Its combination levels are 27,959, 27,533, 27,732 and 28,356.
On the QQQ proxy the put side support base sits at 680, the largest gamma concentration at 700, the modeled gamma-flip level at 721, the modeled volatility threshold at 723 and the call side ceiling at 760. Those are proxy levels. The fund's gamma notional reads minus 958.757 million dollars and its gamma tilt 0.519, proxy model outputs. The console, read at 6:18 PM ET, carried Friday's 690.56 as its previous close and a console price of 683.30, down 1.05 percent. The review treats that as a console reading. Call gamma reads minus 272.42 million against put gamma of minus 1.64 billion. One-month implied volatility reads 25.38 percent against realised volatility of 22.76 percent, 2.62 points apart. The implied-volatility rank reads 71.40 percent and the put-to-call open-interest ratio 1.28.
In the review's interpretation, drawn from the index model and the QQQ fund proxy, both model outputs, a cash close beneath the index's 28,000 put side base with gamma notional negative on both describes an environment in which dealer hedging is more likely to extend moves than to damp them. Gamma stays a damping lens here. It carries no direction. The modeled threshold and flip level are model outputs, not option strikes, and no directional read is drawn from options volume or modeled gamma. Tuesday's band sits beneath the 28,637.68 threshold equivalent and above the 28,137.68 put-base equivalent.
Activity eased. Volume came to 739,966 contracts on the 2026-11-02 row, against Friday's 1,049,656 on the 2026-10-30 row, a figure revised from the 1,023,028 carried in Monday's outlook. Open interest reads 292,941 on that 2026-10-30 row, which Monday's outlook listed as not yet reported. That is 24,864 above the 268,077 on the 2026-10-29 row. Monday's open interest is not yet reported. The weekly positioning report was not captured, so no figure from it is carried.
The trade map for Tuesday
The primary setup is a short from 28,360 to 28,400. The composite moved to 72 percent sell. Negative direction leads on both directional systems, and the settle sits beneath every settlement average, the 200-day included. The whole band sits above the settle. Its bottom sits 232.50 points up and its top 272.50. It brackets the Pivot Point at 28,373.50, 13.50 above its bottom and 26.50 beneath its top.
Then the stop. At 28,520 it sits 120 points above the band top, 31.12 above the 28,488.88 retracement and 26.32 above the 28,493.68 combination-level equivalent. The 200-day average at 28,462.00 sits between the band and the stop. The first target, 28,240, also sits above the settle, 112.50 points up and 16.25 above the post-settlement print. The second, 28,100, sits 1.75 beneath Monday's 28,101.75 low and 27.50 beneath the settle. Then the extended third. At 27,960 it sits 42.49 above the 27,917.51 relative strength projection and 104.25 above Pivot S1 at 27,855.75.
The setup needs a rebound into the band. Readings near the bottom of the stochastic range leave room for a sharper one, so the review calls the setup an analyst judgment that rebounds into the Pivot Point are sold, with no measured edge behind it.
Now the arithmetic. From the 28,380 midpoint the risk to the stop is 140 points, 22.2 percent of the 14-day average true range of 630.79. The targets sit 140, 280 and 420 points beneath the midpoint. Exact multiples. The first target sits 120 points beneath the band bottom and 112.50 above the settle. The second sits 27.50 beneath the settle. The third sits 167.50 beneath it.
The scenario ranges are analyst judgment. The low-range case runs 27,950 to 28,450 and the most likely 27,800 to 28,700. The high-range case runs 27,500 to 28,950, 3.29 points above the one-ATR line at the bottom and 0.14 beneath one standard deviation at the top. Then the sessions. Globex reopened at 6:00 PM ET on Monday, and the review expects roughly 27,950 to 28,450 through the night, with a bias neutral to lower beneath the Pivot Point at 28,373.50. That night top sits 50.00 above the band top and 70.00 beneath the stop.
London follows from 3:00 AM ET at 27,900 to 28,500, with the same bias; Swiss inflation data is listed at 2:30 AM ET by the news-feed calendar, unconfirmed. The morning band runs 27,850 to 28,650, with the setup band in its upper half and the band's top 130.00 above the stop. The afternoon band runs 27,800 to 28,700, its top 180.00 above the stop.
Tuesday's calendar is full. The cash session opens at 9:30 AM ET, and factory orders and the JOLTS report are scheduled for 10:00 AM ET, as the calendar lists them. The calendar lists results from a processor and graphics-chip maker for Tuesday, November 3, for the date only. The midterm elections take place on Tuesday, per the news-feed calendar and unconfirmed. Later in the week the calendar lists a mobile-chip designer's results for Wednesday, November 4, for the date only, the trade report at 8:30 AM ET that day and the employment situation report at 8:30 AM ET on Friday, November 6.
The scenarios are ranked. In the review's analyst judgment the base case holds the contract between Pivot S1 at 27,855.75 and Pivot R1 at 28,645.25. Within it, a rebound toward the Pivot Point at 28,373.50 that stalls beneath the 28,488.88 retracement is weighted above a sustained recovery through Pivot R1. No measured frequency backs it. The 9-day relative strength of 26.51 and the 9-day raw stochastic of 1.24 percent leave room for a rebound.
Second comes a settle above Pivot R1, which could bring the 28,879.68 flip-level equivalent and Monday's 28,891.25 high into play. Third, a move beneath Monday's 28,101.75 low before any rebound could open Pivot S1 and the published target price at 27,604.03 without the rebound the setup needs. The band would stay untraded. In the review's judgment the first-order event on Tuesday is the cash open at 9:30 AM ET, the first cash session after the two after-close results.
Tuesday's band sits between Monday's settle, 232.50 points beneath its bottom, and Pivot R1, 245.25 points above its top.
The complete data picture
Every number behind Tuesday’s plan, charted first, then the full level lists, then the complete numeric reference underneath.
Full numeric reference, every remaining figure from the session review
1. Executive Summary
The December Nasdaq-100 contract settled at 28,127.50 on Monday, down 406.50 or 1.42 percent from Friday's settle of 28,534.00, after trading between 28,891.25 and 28,101.75, a 789.50 point daily range. The settle finished at 3.3 percent of the range, and the range was 1.18 multiples of the published 14-day average daily range of 668.79 points. Monday's high sat 288.75 beneath Friday's 29,180.00 high and its low sat 131.00 beneath Friday's 28,232.75 low, a lower high and a lower low, and Monday was the third consecutive lower settle. The 28,127.50 settle is the lowest since 07/29/26 and stands 11.04 percent beneath the published 52-week high of 31,616.50.
The Nasdaq-100 cash index closed at 27,989.82, down 1.39 percent, while the S&P 500 fell 0.51 percent and the Dow industrials rose 0.41 percent. The semiconductor index fell 3.37 percent. The news feed's market wrap described the Nasdaq-100 entering a correction amid a chipmaker selloff, and the provider's commentary described an early advance that faded through the session. December WTI crude fell 7.36 percent on the day, reported here on its own. A consumer-electronics maker and a data-analytics software group reported after the cash close, and the news feed carried both results above estimates on earnings per share.
The settle sits beneath every settlement average from the 5-day to the 200-day, and Monday's close beneath the 200-day average is the first of any session from 08/10/26, the first date with a full 200-session window in the settlement series, through Monday. Electronic trade after the settle ended at 28,223.75 in the 4:30 PM ET bar, 96.25 above the settle.
The composite multi-indicator read published for Tuesday is "72% SELL" with strength "Strong" and direction "Strongest", from "56% SELL" a session earlier. The Primary Setup below is a short from the 28,360 to 28,400 band around the Pivot Point at 28,373.50, stopped at 28,520, with objectives at 28,240, 28,100 and an extended 27,960.
2. Price Action & Technical Structure
2.1 Intraday and Session Review
The Monday session opened at 28,587.75 at the Sunday 6:00 PM ET reopen, 53.75 above Friday's settle, and the 30-minute series places the high of 28,891.25 in the 10:00 AM ET bar and the low of 28,101.75 in the 3:30 PM ET bar. The 30-minute closes rose from 28,632.00 in the first bar to 28,824.00 in the 12:30 AM ET bar and held between 28,696.00 and 28,824.00 through the 9:30 AM ET bar.
The 10:00 AM ET bar closed at 28,886.50, near the session high, and the next bar closed at 28,725.75. From there the 30-minute closes declined through the afternoon to 28,138.75 in the 3:30 PM ET bar, and the contract settled at 28,127.50. The 4:00 PM ET bar closed at 28,227.00 and the 4:30 PM ET bar at 28,223.75, the post-settlement print.
The open, high and low on the provider's overview page now belong to the Globex session that reopened at 6:00 PM ET for Tuesday, so Monday's completed range is taken from the settlement record and the published pivot ladder. Pivot R3 at 29,434.75 minus Pivot S3 at 27,066.25, divided by three, returns 789.50, and Pivot R2 at 29,163.00 minus Pivot S2 at 27,584.00, divided by two, returns the same 789.50. Three times the Pivot Point of 28,373.50 less the 28,127.50 settle gives a high plus low sum of 56,993.00, which solves to a high of 28,891.25 and a low of 28,101.75; that pair reproduces all seven published rungs. These are the completed-session inputs behind the published pivot ladder rather than an independently read bar, and they are corroborated by the provider's settlement row and the chart's completed daily bar, which carry the same 28,587.75 open, 28,891.25 high, 28,101.75 low and 28,127.50 settle.
2.2 Daily Structure
Monday printed a lower high and a lower low against Friday. Settlements over the last eight sessions read 29,142.00, 29,117.75, 29,437.25, 29,812.00, 29,979.50, 29,562.00, 28,534.00 and 28,127.50, so the last three sessions fell by 417.50, 1,028.00 and 406.50 after three higher settles. Over five sessions the contract is down 1,309.75 from the 29,437.25 settle of 10/26.
The weekly bar for the week of October 26 spanned 30,178.00 to 28,232.75. The provider publishes 28,101.75, Monday's low, as the one-month and 13-week low, and Monday's low is the lowest since the 27,492.75 low of 07/30/26.
2.3 4-Hour and Swing Structure
The four-hour bars for Monday's session, read from the chart, show the 6:00 PM ET bar on Sunday gaining 188.25 to 28,776.00, the next three bars holding near that level, and the 10:00 AM ET bar falling 251.50 from its 28,693.00 open to 28,441.50 after making the session high, the largest decline of the six. The 2:00 PM ET bar fell a further 217.75 to 28,223.75.
Daily ranges for the last ten sessions ran 511.75, 385.50, 960.25, 339.00, 548.00, 593.25, 503.75, 683.25, 947.25 and 789.50. The published grid places the 61.8 percent retracement from the 52-week low at 28,488.88 and the 50 percent retracement of the 52-week range at 27,522.75.
2.4 Moving Averages
The averages cited here were computed from the provider's daily settlement series for the December contract, which holds 259 completed sessions from 10/23/25 through Monday; the partial row of the reopened Tuesday session is excluded, and each average is carried at full precision and rounded once to the quarter point. The 5-day average stands at 29,203.00, the 9-day at 29,302.00, the 20-day at 29,974.50, the 50-day at 30,034.75, the 100-day at 29,926.00 and the 200-day at 28,462.00.
The 28,127.50 settle sits 1,075.50 beneath the 5-day average, 1,174.50 beneath the 9-day, 1,847.00 beneath the 20-day, 1,907.25 beneath the 50-day, 1,798.50 beneath the 100-day and 334.50 beneath the 200-day. The 5-day average fell from Friday's 29,465.00 as Monday's settle replaced the 10/26 settle of 29,437.25, and the 20-day fell from 30,134.00 as the 10/05 settle of 31,317.75 left the window.
The 20-day average sits beneath the 50-day because the 30 older settlements in the 50-day window averaged higher, at 30,075.04. The 50-day sits above the 100-day because the 50 older settlements in the 100-day window averaged lower, at 29,817.22, and the 100-day sits above the 200-day because the 100 older settlements in the 200-day window averaged lower, at 26,997.91. The projection grid gives 29,214.00 as the price at which the 9-day average would be crossed on Tuesday.
2.5 Oscillator and Trend Readings
The oscillator figures below are as published on the provider's technical page, read at 6:25 PM ET on Monday after the Globex reopen; they are the provider's readings and were not computed here, and the page may already reflect the reopened session's price. The 9-day relative strength reads 26.51, the 14-day relative strength 31.40 and the 20-day relative strength 35.51.
The 9-day raw stochastic reads 1.24 percent and the 14-day raw stochastic 0.92 percent, while the 14-day stochastic %K reads 12.39 percent and the 14-day stochastic %D 24.21 percent. The 9-day directional index ADX reads 36.85 with the 9-day +DI at 12.22 and the 9-day -DI at 35.50; the 14-day directional index ADX reads 27.02 with the 14-day +DI at 13.66 and the 14-day -DI at 33.06, so negative direction leads on both. The 9-day historic volatility reads 26.68 percent and the 14-day historic volatility 24.86 percent.
The composite multi-indicator read published for the Tuesday session is "72% SELL", with signal strength "Strong" and direction "Strongest". The snapshot history reads "56% SELL" for the prior session, "32% SELL" a week ago and "88% BUY" a month ago. The short horizon group averages "100% SELL", the medium group "50% SELL" and the long group "33% SELL".
2.6 Volatility and Expected Range
The published 14-day average true range stands at 630.79 points and the 14-day average daily range at 668.79 points; the 9-day average true range is 687.70 with a 9-day average daily range of 638.86, and the 20-day average true range is 595.60 with a 20-day average daily range of 589.78. Monday's 789.50 point range was 1.18 multiples of the 14-day average daily range.
Adding and subtracting the 14-day average true range of 630.79 from the 28,127.50 settle frames Tuesday between 27,496.71 and 28,758.29. The published standard-deviation bands, built from five settlements, span 27,304.86 to 28,950.14 at one deviation, 26,964.11 to 29,290.89 at two and 26,702.64 to 29,552.36 at three. These bands describe dispersion, not intraday reach.
3. Key Levels
3.1 Resistance
Above the 28,127.50 settle, the first references are the 28,137.68 conversion of the index's 28,000 put side support base, the 28,223.75 post-settlement print, Friday's 28,232.75 low and the Pivot Point at 28,373.50. The 200-day average at 28,462.00, the 61.8 percent retracement from the 52-week low at 28,488.88, the 28,493.68 conversion of the index's 28,356 combination level, Friday's 28,534.00 settle, Monday's 28,587.75 open and the 28,637.68 conversion of the index's 28,500 modeled volatility threshold form the next band beside Pivot R1 at 28,645.25. The one-ATR line at 28,758.29, the 28,879.68 conversion of the index's 28,742 modeled gamma-flip level and Monday's 28,891.25 high are the extended references, with one standard deviation resistance at 28,950.14 beyond.
3.2 Support
Beneath the settle sit Monday's 28,101.75 low and the 28,096.68 conversion of the index's 27,959 combination level. The 27,917.51 projection where the 14-day relative strength would reach 30 percent and Pivot S1 at 27,855.75 form the next band, followed by the 3-10 day crossover stall level at 27,692.71, the published target price at 27,604.03 and Pivot S2 at 27,584.00. The 50 percent retracement of the 52-week range at 27,522.75, the one-ATR line at 27,496.71, the 27,492.75 low of 07/30/26 and one standard deviation support at 27,304.86 are the deeper references, with Pivot S3 at 27,066.25, two standard deviations support at 26,964.11 and three standard deviations support at 26,702.64 beneath them.
4. Macro Drivers
4.1 Largest-Company Results and the AI Spending Cycle
A consumer-electronics maker and a data-analytics software group reported after the cash close on Monday, November 2, 2026, as the calendar lists them. The news feed carried the consumer-electronics maker's quarterly earnings at 2.10 dollars a share against an estimate of 2.00, with revenue of 114.48 billion against 113.47 billion, and the data-analytics software group's adjusted earnings at 0.44 dollars against 0.41, with revenue of 2.31 billion against 2.17 billion and a raised full-year revenue outlook. These are results carried by the news feed. The feed also carried a press report that a database-software company's 10 billion dollar share sale drew excess demand and items on bond sales by two large internet-platform companies, in a session in which the provider's commentary described continued selling in chipmakers and artificial-intelligence infrastructure stocks.
4.2 Semiconductor Cycle and Tech Sector Rotation
The semiconductor index closed at 10,328.33, down 3.37 percent, against 1.39 percent for the Nasdaq-100 cash index, 0.51 percent for the S&P 500 and a 0.41 percent gain for the Dow industrials. The provider's commentary described defensive buying in large consumer and industrial stocks as investors rotated out of technology. In the review's reading, the rotation away from technology that the feeds described last week continued for a third session.
4.3 Fed Policy and Real Yields (Duration Sensitivity)
The ten-year yield index closed at 4.89 percent; Friday's close was 4.92 percent. Market pricing showed a 74 percent chance of a quarter-point Fed increase at the next meeting, per the provider's commentary and unconfirmed, and the US manufacturing survey rose to 55.5, per the provider's commentary and unconfirmed. In this review's interpretation the decline was sector-driven rather than rate-driven; the yield move and the index move are reported side by side. No real-yield series was captured.
4.4 Geopolitical Backdrop
The news feed carried a state media report at 8:30 AM ET that Iran's Supreme Leader had granted the government authority in negotiations, the President's afternoon remarks that there was no rush to decide on restarting the war, and reports after the close of explosions heard on Qeshm Island and off Bandar Lengeh. These are reports carried by the feeds, not confirmed events. Separately, December WTI crude fell 7.36 percent to 96.46; no move is attributed to these reports.
4.5 Cross-Asset and Volatility
The volatility index closed at 21.15; Friday's close was 19.42, and its session high was 21.77. The dollar index's daily record eased to 101.75 and gold's December contract rose 1.81 percent. The Nasdaq-100 cash index's session range ran from 28,753.39 to 27,967.44, and the futures settled 137.68 points above the cash close, against 149.15 on Friday, both measured as the December settle less the provider's cash close.
4.6 Institutional Positioning
Open interest on the December contract stood at 292,941 on Friday, the 2026-10-30 row of the provider's settlement record, and Monday's open interest is not yet reported; Monday's December volume was 739,966 contracts against 1,049,656 on Friday's 2026-10-30 row, revised from the 1,023,028 carried in Monday's outlook. The weekly positioning report was not captured.
5. QQQ Options Flow Context (Proxy)
This review uses the QQQ fund and the Nasdaq-100 index columns of the dealer-positioning dataset as the positioning proxy for the December contract; the dataset tracks the index and the fund, and the futures translation below is this review's. The dataset read for this section uses Friday's closes as its reference prices: NDX 28,384 corresponds to Friday's 28,384.85 cash close and QQQ 690 corresponds to the fund console's previous close of 690.56. Friday's 28,384.85 less 395.03 points, a 1.39 percent decline, gives the provider's 27,989.82 close, and every level below is read against that close.
On the index the put side support base sits at NDX 28,000, the modeled volatility threshold at NDX 28,500, the modeled gamma-flip level at NDX 28,742, the largest gamma concentration at NDX 29,000 and the call side ceiling at NDX 29,675. The close sits 10.18 points beneath the put side base, 510.18 beneath the threshold, 752.18 beneath the flip level, 1,010.18 beneath the concentration and 1,685.18 beneath the ceiling. Gamma tilt reads 0.743 and gamma notional minus 5.645 million dollars, both model outputs. The dataset's key index strikes are 29,000, 28,000, 29,675 and 30,000, and its index combination levels are 27,959, 27,533, 27,732 and 28,356. The modeled threshold and flip level are model outputs, not option strikes.
On the fund the put side support base sits at 680, the largest gamma concentration at 700, the modeled gamma-flip level at 721, the modeled volatility threshold at 723 and the call side ceiling at 760. Fund gamma notional reads minus 958.757 million dollars with a gamma tilt of 0.519, proxy model outputs. The QQQ console, read at 6:18 PM ET, carried Friday's 690.56 as its previous close and a console price of 683.30, down 1.05 percent, which is a console reading rather than a cash close. The console shows call gamma of minus 272.42 million against put gamma of minus 1.64 billion, one-month implied volatility of 25.38 percent against realised volatility of 22.76 percent, an implied-volatility rank of 71.40 percent and a put-to-call open-interest ratio of 1.28.
At the measured basis of 137.68 points the NDX 28,000 base converts to 28,137.68, the NDX 27,959 combination level to 28,096.68, the NDX 28,356 combination level to 28,493.68, the NDX 28,500 threshold to 28,637.68 and the NDX 28,742 flip level to 28,879.68. In this review's interpretation, drawn from the index model and the QQQ fund proxy, both model outputs, a cash close beneath the index's 28,000 put side base, with gamma notional negative on both the index and the fund, describes an environment in which dealer hedging is more likely to extend moves than to damp them, and the 28,000 base now sits just above the close as the first dataset reference; gamma is read as a damping lens with no direction.
6. Forecast
6.1 Night Session (6:00 PM ET Monday to 3:00 AM ET Tuesday, Globex and Asia)
Globex reopened at 6:00 PM ET with the after-close results from the consumer-electronics maker and the data-analytics software group already released. Bias neutral to lower beneath the Pivot Point at 28,373.50, expected band roughly 27,950 to 28,450.
6.2 London Session (3:00 AM to 8:00 AM ET Tuesday)
From 3:00 AM ET European trading opens with Swiss inflation data listed at 2:30 AM ET by the news-feed calendar, unconfirmed. Bias neutral to lower beneath the Pivot Point at 28,373.50, expected band roughly 27,900 to 28,500.
6.3 Morning Session (9:30 AM to 12:00 PM ET Tuesday, RTH Open)
The cash open at 9:30 AM ET is the first directional test after Monday's close beneath the index's 28,000 base, and factory orders and the JOLTS report are both scheduled for 10:00 AM ET on Tuesday, November 3, 2026, as the calendar lists it. Expected band roughly 27,850 to 28,650, with the 28,360 to 28,400 setup band in the upper half.
6.4 Afternoon Session (12:00 PM to 4:00 PM ET Tuesday)
The cash close at 4:00 PM ET sets the reference for the midterm elections, per the news-feed calendar and unconfirmed, and for the processor and graphics-chip maker's results due on Tuesday, November 3, 2026, as the calendar lists them, for the date only. Expected band roughly 27,800 to 28,700.
6.5 Night Session Forward (6:00 PM ET Tuesday)
The Tuesday evening session opens at 6:00 PM ET after the processor and graphics-chip maker's results, listed for the date only, and the midterm elections, per the news-feed calendar and unconfirmed. The employment situation report is scheduled for 8:30 AM ET on Friday, November 6, 2026, as the calendar lists it.
6.6 Expected Range (Tuesday Full Session)
Low-range scenario: 27,950 to 28,450; Mid-range scenario (most likely): 27,800 to 28,700; High-range scenario: 27,500 to 28,950.
6.7 Most Likely Path
In this review's analyst judgment the most probable path holds the contract between Pivot S1 at 27,855.75 and Pivot R1 at 28,645.25, with a rebound toward the Pivot Point at 28,373.50 that stalls beneath the 28,488.88 retracement weighted above a sustained recovery through Pivot R1 at 28,645.25. The composite moved to "72% SELL" from "56% SELL", negative direction leads on both directional systems and the settle sits beneath every settlement average, while the 9-day relative strength reading of 26.51 and the 9-day raw stochastic of 1.24 percent leave room for a rebound.
The alternative that would invalidate this reading is a settle above Pivot R1 at 28,645.25, which would bring the 28,879.68 flip-level conversion and Monday's 28,891.25 high into play. On the other side, a move beneath Monday's 28,101.75 low before any rebound would open Pivot S1 at 27,855.75 and the published target price at 27,604.03 without the rebound the setup needs.
7. Tuesday Economic Calendar
Monday's releases are complete. Construction spending, released at 10:00 AM ET on Monday, November 2, 2026, as the calendar lists it, fell 1.9 percent against an expected gain, per the provider's commentary and unconfirmed. The US manufacturing survey rose to 55.5, per the provider's commentary and unconfirmed. Results from the consumer-electronics maker and the data-analytics software group were released after the cash close on Monday, November 2, 2026, as the calendar lists them.
On Tuesday, November 3, 2026, factory orders and the JOLTS report are scheduled for 10:00 AM ET, both as the calendar lists them, and the processor and graphics-chip maker's results are due the same day, as the calendar lists them, for the date only. The midterm elections take place on Tuesday, per the news-feed calendar and unconfirmed.
Later in the week, a mobile-chip designer's results are due on Wednesday, November 4, 2026, as the calendar lists them, for the date only. The trade report is scheduled for 8:30 AM ET on Wednesday, November 4, 2026, and the employment situation report for 8:30 AM ET on Friday, November 6, 2026, both as the calendar lists them. In this review's judgment the first-order event for the Nasdaq-100 on Tuesday is the cash open at 9:30 AM ET, the first cash session after the consumer-electronics maker's and the data-analytics software group's results, following Monday's close beneath the index's 28,000 base, with the processor and graphics-chip maker's results due the same day, listed for the date only.
8. Primary Trade Setup
Direction: Short
Rationale: The settle closed at 3.3 percent of its range for the third consecutive lower settle, beneath every settlement average including the 200-day, and the composite moved to "72% SELL". A rebound into the 28,360 to 28,400 band around the Pivot Point at 28,373.50 offers a short with a defined risk point above the 28,488.88 retracement. Readings near the bottom of the stochastic range leave room for a sharper rebound, so the setup is an analyst judgment that rebounds into the Pivot Point are sold, not a measured edge.
Entry Zone: 28,360 to 28,400
Stop Loss: 28,520 (above the 28,488.88 retracement and the 28,493.68 combination-level conversion)
Target 1 (T1): 28,240 (above the 28,223.75 post-settlement print)
Target 2 (T2): 28,100 (1.75 beneath Monday's 28,101.75 low)
Target 3 (T3, extended): 27,960 (above the 27,917.51 projection and Pivot S1 at 27,855.75)
Risk-to-Reward: Approximately 1:1 to T1, 1:2 to T2, 1:3 to T3
Invalidation: A settle above Pivot R1 at 28,645.25 negates the thesis. Short of that, the edge is removed by acceptance above the entry band and not by a touch, defined as two consecutive 30-minute closes above 28,400.
Macro override: A strong reaction to the results from the consumer-electronics maker, the data-analytics software group or the processor and graphics-chip maker, whose results are listed for the date only, that lifts semiconductors could support the index. In that scenario a move through the 28,520 stop invalidates the short before the targets, and the 28,637.68 threshold conversion becomes the reference, 117.68 beyond the stop and inside one 14-day average true range of 630.79.
Sources and methodology
This outlook is built from our session review of the December E-mini Nasdaq-100 contract, the December ’26 contract, prepared after Monday's close on November 2, 2026 for the Tuesday, November 3, 2026 session. Monday's open, high, low and settle come from the provider's daily settlement record for the December contract, the 2026-11-02 row, and match the chart's completed daily bar; the partial 2026-11-03 row of the reopened Tuesday session is excluded from every count and average. Monday's session opened at the Sunday 6:00 PM ET reopen. The overview's open, high and low already belong to the session that reopened at 6:00 PM ET on Monday, so Monday's range comes from the settlement record and the published pivot ladder: Pivot R3 at 29,434.75 less Pivot S3 at 27,066.25, divided by three, and Pivot R2 at 29,163.00 less Pivot S2 at 27,584.00, divided by two, both return 789.50, and three times the 28,373.50 Pivot Point less the settle gives 56,993.00, the sum of the 28,891.25 high and the 28,101.75 low. Every time of day given for Monday's prices comes from the 30-minute series for Monday's session, which starts at the Sunday 6:00 PM ET reopen, read as Eastern standard-time clock labels; session windows are scored over the bars that open inside each window.
The moving averages are the review's, computed from the provider's daily settlement series for the December contract, 259 completed sessions, and rounded once to the 0.25 tick. The oscillators and the average true and daily ranges are cited as published, read at 6:25 PM ET on Monday after the Globex reopen. Volume and open interest come from the provider's daily record: the 2026-11-02 row reads 739,966 contracts, and Monday's open interest is not yet reported; the 2026-10-30 row now reads 1,049,656 contracts and open interest of 292,941, where Monday's outlook carried 1,023,028 contracts and open interest not yet reported; the 2026-10-29 row reads open interest of 268,077. The weekly positioning report was not captured. The dealer-positioning dataset carries Friday's closes in its reference column; every Nasdaq futures equivalent is the review's conversion at the 137.68 point measured basis, the December settlement less the cash close, against 149.15 on Friday. The QQQ fund is a proxy read alongside the index levels. The reading that dealer hedging is more likely to extend moves than to damp them is the review's interpretation from the index model and that proxy, both model outputs, and gamma is read as a damping lens with no direction; the fund console was read at 6:18 PM ET. Company results are dated by the calendar and described per the news feed; descriptions of the session from the news feed and the provider are attributed commentary. Cross-asset moves are reported side by side, and none is presented as the cause of another. The volume and open-interest changes, the session-window highs and lows and the distances in this article are computed. Scenario ranges are analyst judgment, and items marked unconfirmed come from the news-feed calendar or the provider's commentary.
Monday’s outlook for this contract is here, and the S&P 500 contract’s Monday outlook covers the index that fell 0.51 percent in cash on Monday. Outlooks for ES, NQ, GC and CL are collected on the market outlook page, and our forward trading record is on the performance statement.