At the Monday 6:00 PM ET reopen the December Nasdaq-100 contract opened at 29,745.50, 23.00 points above Monday's settle. The day's high was 29,903.50. It stopped 36.50 points under the bottom of the short band we published for Tuesday, and 80.00 points under Monday's high. The low of 29,391.75 held 165.75 points above Monday's low. An inside day.
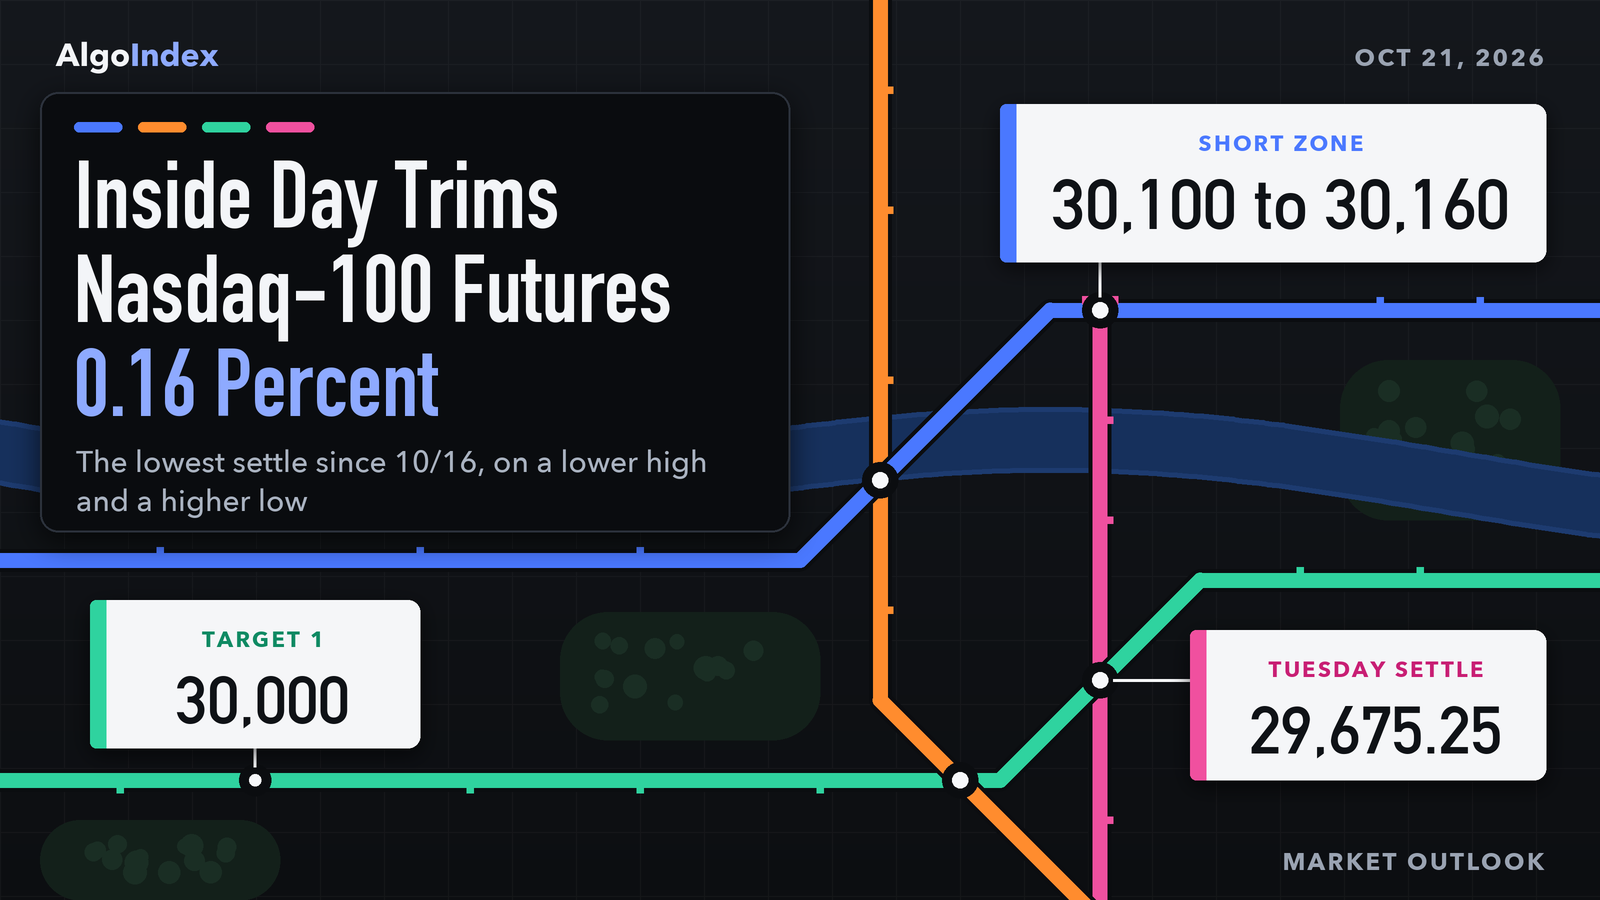
The contract settled at 29,675.25, down 47.25 points, or 0.16 percent, at 55.4 percent of a 511.75 point range. That was the lowest settle since the 29,391.50 of 10/16. The Nasdaq-100 cash index slipped 0.13 percent while the Dow industrials rose 1.02 percent. Results from a streaming company and a server maker came after the close. The reopened Globex session quoted 29,941.25 at 6:23 PM ET, 266.00 points above the settle.
December Nasdaq-100 futures settled at 29,675.25, down 47.25 points, on an inside day with a 511.75 point range. Tuesday's published short band at 29,940 to 30,000 never traded; the high stopped 36.50 points under it. The settle sits beneath every settlement average from the 5-day to the 100-day and 1,341.26 points above the 200-day. The primary setup for Wednesday is a short from 30,100 to 30,160, beneath Pivot R2 at 30,168.58, stop 30,260, targets 30,000, 29,870 and an extended 29,740. All three targets sit above the settle. A social-media group and an electric-vehicle maker report after Wednesday's close, as the calendar lists them.
Tuesday's short band at 29,940 to 30,000 never traded; the high stopped 36.50 points under it
In Tuesday’s outlook we set a short from 29,940 to 30,000, stop 30,100. Its targets sat at 29,840, 29,710 and an extended 29,580. Tuesday's bar, from the review and the provider's 2026-10-20 settlement row, opened at 29,745.50 at the Monday 6:00 PM ET reopen, marked a high of 29,903.50 and a low of 29,391.75, and settled at 29,675.25. The band never traded. The high stopped 36.50 points under its 29,940 bottom and 196.50 under the 30,100 stop. The settle finished 264.75 points beneath the band.
All three targets lie inside the day's range. The low ran 188.25 points through the extended 29,580. Those prices traded, and they score nothing, because the band the card measured from never traded. No intraday series was preserved for Tuesday. So the daily bar cannot show the order in which the high, the low and those prices printed, and none is asserted here. No fill and no result is asserted either.
The card's other lines were never triggered. Its acceptance test needed two consecutive 30-minute closes above 30,000. No close could get there, since the high stopped 96.50 points beneath 30,000. The invalidation needed a settle above Pivot R1 at 30,062.00. The settle finished 386.75 points beneath it.
Its macro override named a continuation of the chip-led rebound, a confirmed de-escalation in the Gulf that pulls crude and yields lower, or a strong reaction to the streaming company's report in the evening session. Chips slipped. The semiconductor index closed down 0.29 percent. December WTI settled 0.73 percent lower at 97.82, and the ten-year yield index closed at 5.12 percent against 5.13 percent on Monday. The review records no confirmed de-escalation: the news feed carried a press report of a mediation proposal and a diplomat's statement that reports of a close deal are wrong, statements carried by the news feed rather than confirmed events. The desk note said the streaming company's shares traded down about 6 percent after its release. The override's references were the 38.2 percent retracement at 30,139.17 and the 40-day crossing price at 30,229.50. The high reached neither. It stopped 235.67 points under the first.
Our ranges are scored against the whole day's extremes, which is all the daily bar allows. The low-range case of 29,500 to 29,990 broke lower by 108.25 points. The most likely case of 29,350 to 30,150 held, the low 41.75 points above its bottom, and the high-range case of 29,190 to 30,400 held. The night band of 29,550 to 29,950 and London's 29,500 to 29,990 contained the high but not the low. The morning band of 29,400 to 30,100 missed the day's low by 8.25 points, and the afternoon band of 29,350 to 30,150 contained the whole day. The bar cannot place the low in any one session. The most probable path, an analyst judgment, kept the contract between Pivot S1 at 29,304.50 and Pivot R1 at 30,062.00. It held. The low stayed 87.25 points above the lower line and the high 158.50 beneath the upper. A rally that fails beneath Pivot R1 was the weighted case, and the high stayed beneath it, short of the band. The alternative, a continuation through Pivot R1 toward the 40-day crossing price at 30,229.50, did not develop.
The 29,860.97 flip conversion, Pivot R1 at 29,921.92 and a band beneath Pivot R2
The basis narrowed to 184.97 points, the 29,675.25 settle less the 29,490.28 cash close, from 193.16 on Monday. Every December equivalent of a positioning level in this article uses it: 29,734.97 for the modeled volatility threshold at NDX 29,550, 29,859.97 for the largest gamma concentration and primary call side ceiling at NDX 29,675, and 29,860.97 for the modeled gamma-flip level at NDX 29,676. The conversions are the review's own. Tuesday's high printed 42.53 points above the flip conversion. The settle sits beneath all three.
Resistance starts 59.72 points up, at the 29,734.97 threshold equivalent. The concentration and flip equivalents sit one point apart at 29,859.97 and 29,860.97. Then come Tuesday's 29,903.50 high, Pivot R1 at 29,921.92 and Monday's 29,983.50 high. One standard deviation resistance at 30,010.82 and the 38.2 percent retracement from the 13-week high at 30,037.12 follow, with the 100-day average at 30,030.97 between them. Then the band. The 38.2 percent retracement from the four-week low at 30,139.17, two standard deviations resistance at 30,149.81 and the 9-40 day crossing price at 30,159.96 all sit inside 30,100 to 30,160. The 50-day average at 30,167.04 and Pivot R2 at 30,168.58 sit just above it, 1.54 points apart. The stop zone is crowded. The 40-day crossing price at 30,232.28, the 9-day crossing price at 30,239.28 and three standard deviations resistance at 30,256.47 all sit beneath the 30,260 stop. Beyond it lie the 9-day average at 30,320.42, the 50 percent retracement of the four-week range at 30,421.25, Pivot R3 at 30,433.67, the 18-day crossing price at 30,634.56 and the 20-day average at 30,660.41. The 31,616.50 one-month, 13-week and 52-week high caps the list.
Support starts 18.42 points down, at the Pivot Point of 29,656.83. The published stall projection at 29,588.76, the published target price at 29,564.97 and the 50 percent retracement of the 13-week range at 29,549.25 sit within 39.51 points of one another. A gap follows. Pivot S1 at 29,410.17, Tuesday's 29,391.75 low, the 29,391.50 settle of 10/16 and one standard deviation support at 29,339.68 come next. The one-month low at 29,226.00, which is also Monday's low, sits 449.25 points beneath the settle, with two standard deviations support at 29,200.69 under it. Pivot S2 at 29,145.08, three standard deviations support at 29,094.03 and Pivot S3 at 28,898.42 form the deeper band. The 200-day average at 28,333.99 and the 27,482.00 13-week low lie far below.
Every average from the 5-day to the 100-day sits overhead. The settle is 147.90 points beneath the 5-day at 29,823.15, 645.17 beneath the 9-day at 30,320.42, 985.16 beneath the 20-day at 30,660.41, 491.79 beneath the 50-day at 30,167.04 and 355.72 beneath the 100-day at 30,030.97. It is 1,341.26 above the 200-day at 28,333.99. The 5-day fell 223.25 points from 30,046.40 as the 10/13 settle of 30,791.50 left the window. The 20-day fell 67.66 from 30,728.08 as the 09/22 settle of 31,028.50 dropped out. The 50-day fell 7.21 from 30,174.25. Older settlements sit lower: the 30 older ones in the 50-day window averaged 29,838.12, the 50 older ones in the 100-day window 29,894.91 and the 100 older ones in the 200-day window 26,637.01. Wednesday's crossing prices are 30,239.28 for the 9-day, 30,634.56 for the 18-day and 30,232.28 for the 40-day.
Momentum stayed weak. Relative strength reads 33.64 on the 9-day, 39.58 on the 14-day and 43.65 on the 20-day. The raw stochastics read 20.06 percent on the 9-day and 18.79 percent on the 14-day, and the 14-day %K at 14.93 percent sits fractionally beneath %D at 15.01 percent, near the bottom of the range. Sellers lead on both windows. On the 9-day, negative direction at 29.53 tops positive at 7.86 by 21.67, with the ADX at 35.78; on the 14-day, 27.51 tops 11.93 by 15.58, with the ADX at 22.38. Historic volatility reads 16.63 percent and 16.67 percent. These readings are as published, read at 6:24 PM ET after the 6:00 PM ET reopen. They may include the first minutes of the Wednesday session.
A composite multi-indicator read published for Wednesday holds at 40 percent sell, unchanged from the prior session, with strength soft and direction weakening. A week ago it read 40 percent buy. A month ago, 72 percent buy. The short-horizon group averages 60 percent sell, the medium 25 percent sell and the long hold, and the trend indicator reads sell.
Its lower shadow is the longer one. The bar's body measures 70.25 points lower from the 29,745.50 open, with an upper shadow of 158.00 points above the open and a lower shadow of 283.50 points beneath the settle. The 14-day average true range stands at 528.37 points and the 14-day average daily range at 543.13; the 9-day figures are 557.70 and 595.61 and the 20-day figures 517.02 and 507.25. One average true range either side of the settle spans 29,146.88 to 30,203.62. The deviation bands, built from five settlements, run 29,339.68 to 30,010.82, 29,200.69 to 30,149.81 and 29,094.03 to 30,256.47, and describe settlement dispersion only. The reopened session already trades above Pivot R1. Eight sessions of daily ranges read 313.50, 445.00, 314.75, 813.50, 574.25, 956.25, 757.50 and 511.75 points, and the session highs since 10/13 read 30,906.00, 30,891.50, 30,196.75, 30,225.00, 29,983.50 and 29,903.50. No prior-quarter extremes were captured, so the 13-week extremes stand in.
A 1.02 percent Dow gain, a 0.13 percent Nasdaq-100 slip and two after-close results
The Dow led. The Dow industrials rose 1.02 percent to 52,495.88 and the S&P 500 cash index 0.28 percent, while the Nasdaq-100 cash index fell 0.13 percent, or 39.06 points, to 29,490.28. The desk note described sector rotation, with the equal-weight S&P 500 fund up 1.0 percent against the Nasdaq-100 fund down 0.1 percent, and rotation toward healthcare and financials, with the healthcare sector fund up 2 percent and the financials sector fund up 1 percent. The NYSE composite rose 0.93 percent, so breadth outside the Nasdaq-100 was firmer than the index itself.
Provider commentary attributed the index gains to earnings optimism, weaker crude and lower yields, and said weakness in chipmakers and artificial-intelligence infrastructure stocks kept the Nasdaq-100 negative. Those accounts are the commentary's. The semiconductor index closed at 11,283.81, down 0.29 percent, after trading as low as 11,043.24. Between 3:32 PM ET and 3:42 PM ET the news feed carried press reports on large multi-year cloud computing commitments disclosed in an artificial-intelligence developer's listing filing, naming a search-engine group, a software maker and the leading graphics-chip maker as counterparties.
Results came after the settlement. The streaming company reported in the calendar's 4:01 PM ET slot, and the news feed carried earnings of 0.87 per share against 0.82 expected, revenue of 12.87 billion in line with expectations, free cash flow of 2.88 billion against 3.22 billion expected and fourth-quarter revenue guidance of 13.44 billion against 13.51 billion expected. The desk note said its shares traded down about 6 percent after the release. At 4:32 PM ET the news feed carried a server maker's preliminary net sales of 18.5 billion to 19.5 billion against a 14.99 billion estimate, citing demand for AI platforms. The desk note said the shares of a newly listed space-launch company traded up about 5 percent after its results. The reopened Globex session quoted 29,941.25 at 6:23 PM ET. The review sets those items beside the quote and assigns no cause.
Wednesday brings more. A social-media group and an analog chip maker are listed at 4:00 PM ET, an information-technology group at 4:10 PM ET and an electric-vehicle maker at 4:15 PM ET, on the news-feed calendar and unconfirmed, and the calendar places them after Wednesday's close without a confirmed time. A search-engine group and a software maker report on October 28, as the calendar lists it.
Yields eased a touch. The ten-year yield index traded between 5.07 and 5.14 percent and closed at 5.12 percent against 5.13 percent on Monday, and the thirty-year index closed at 5.43 percent against 5.47 percent. No inflation-protected yield series was captured, so real yields are not measured here. Housing starts and building permits printed at 8:30 AM ET at 1.221 million and 1.400 million, per the news-feed calendar, and pending home sales printed at 10:00 AM ET at minus 7.3 percent. The next policy statement is scheduled for 2:00 PM ET on October 28, 2026, as the calendar lists it.
The Gulf stayed in the headlines. The news feed carried Iranian media reports of tankers catching fire in the southern corridor of the Strait of Hormuz at 10:36 AM ET and 12:51 PM ET, a press report at 10:11 AM ET that a mediation proposal received US approval and preliminary Iranian agreement, and at 11:12 AM ET a diplomat's statement that reports of a close deal are wrong. These are statements carried by the news feed rather than confirmed events. No causal link to the index is asserted.
Volatility eased. The volatility index closed at 17.31 against 18.44 on Monday, the Nasdaq-100 volatility index at 25.22 against 25.56 and the volatility-of-volatility index at 97.15 against 106.93. The dollar index closed at 101.73, down 0.25.
The cash close sits beneath three model lines. The desk note read is the 5:34 PM ET edition for Tuesday, read at 6:18 PM ET, and its reference prices are the prior session's closes: NDX 29,529 matches Monday's 29,529.34 cash close, and QQQ 718 matches the console's 718.36 previous-close field. Against Tuesday's 29,490.28 close, the index sits 59.72 points beneath the 29,550 modeled volatility threshold, 184.72 beneath the 29,675 largest gamma concentration, which is also the primary call side ceiling, and 185.72 beneath the 29,676 modeled gamma-flip level. The primary put side support base sits at 28,000. The index model's gamma tilt reads 0.943 and its gamma notional minus 4.158 million dollars, both model outputs. The note lists 29,675, 30,000, 29,000 and 31,000 as key index strikes.
On the QQQ proxy the call side ceiling sits at 760, the largest gamma concentration at 720, the put side support base at 700, the threshold at 721 and the flip level at 727. The fund's gamma tilt reads 0.625 and its gamma notional minus 1.034 billion dollars, proxy model outputs. Its console, read at 6:18 PM ET with a page date of 2026-10-20, shows call gamma of minus 1.59 billion against put gamma of minus 2.54 billion. Both gamma fields are negative. One-month implied volatility reads 21.14 percent against realised volatility of 15.80 percent, the implied-volatility rank 42.78 percent and the put-to-call open-interest ratio 1.43. In the review's interpretation, drawn from the index model and the QQQ fund proxy, a cash close beneath the flip level with negative gamma notional on both the index and the fund describes positioning that is less likely to dampen moves, which matters ahead of Wednesday's large earnings releases. That is a damping read. It carries no direction.
The note described the session too. The desk note said tech lagged the broader market and index options flow was dominated by short-dated call selling. Those characterisations are the note's. The console reports volume and modeled gamma without trade side, so no directional read is drawn from them here. The volatility index options expiration at 9:30 AM ET on Wednesday is listed by the desk note, unconfirmed.
Activity picked up. Volume reached 685,959 contracts against Monday's 628,793, a figure revised from the 618,989 carried in Tuesday's outlook. Open interest read 272,277 on Monday's 2026-10-19 row, down from 280,923 on the 2026-10-16 row, and Tuesday's figure is not yet reported. No weekly positioning report was captured, so no managed-money or commercial figure is asserted.
The trade map for Wednesday
The primary setup is a short from 30,100 to 30,160. The settle sits beneath every average from the 5-day to the 100-day, and negative direction leads on both windows. The composite reads 40 percent sell. The cash close sits beneath the modeled gamma-flip level with negative gamma notional on the index and the fund, model outputs read for damping only. The band sits 8.58 points beneath Pivot R2 at 30,168.58 and holds the 38.2 percent retracement at 30,139.17, two standard deviations resistance at 30,149.81 and the 9-40 day crossing price at 30,159.96. Then the stop. The stop at 30,260 sits 3.53 points above three standard deviations resistance at 30,256.47 and 20.72 above the 9-day crossing price at 30,239.28. All of the band sits above the settle, 424.75 to 484.75 points up, and 158.75 to 218.75 points above the reopened session's 29,941.25 quote. The thesis is that rallies stall beneath Pivot R2. The targets sit at 30,000, 10.82 beneath one standard deviation resistance at 30,010.82, 29,870, 10.03 above the 29,859.97 concentration equivalent, and an extended 29,740, 5.03 above the 29,734.97 threshold equivalent. All three sit above the settle, the extended target by 64.75 points. The reopened session already trades above Pivot R1 after the after-close releases, so the review calls the setup an analyst judgment with no measured edge behind it.
Now the arithmetic. From the 30,130 midpoint the risk to the stop is 130 points, 24.6 percent of the 14-day average true range of 528.37. The targets sit 130, 260 and 390 points beneath the midpoint. Exact multiples. The first target, 30,000, sits 100.00 points beneath the band bottom and 324.75 above the settle. The second sits 194.75 above it. The stop sits 584.75 points above it.
The scenario ranges are analyst judgment. The low-range case runs 29,750 to 30,150, the most likely 29,550 to 30,250 and the high-range case 29,150 to 30,430. The settle sits beneath the low-range case. Then the sessions. The review expects roughly 29,750 to 30,150 through the night session, with a bias neutral to higher above Pivot R1 at 29,921.92. The overview's first prints, 29,922.25 to 29,976.00, sit inside that band and 0.33 points or more above Pivot R1. London follows at 29,700 to 30,170, neutral, with two standard deviations resistance at 30,149.81 and Pivot R2 at 30,168.58 the first meaningful resistance band. The morning band runs 29,550 to 30,250. The afternoon band runs 29,450 to 30,260, its top at the stop. The chart showed 29,970.00 at 6:26 PM ET; these reopened-session prints are quotes, not settlements.
Wednesday's calendar starts Tuesday evening. The President is listed to speak at 7:00 PM ET and Japan's trade balance at 7:50 PM ET, both per the news-feed calendar and unconfirmed. Europe follows. UK consumer prices are listed at 2:00 AM ET and the Bank of England governor at 9:00 AM ET, per the news-feed calendar and unconfirmed. Then the open. The volatility index options expiration is listed by the desk note at 9:30 AM ET, unconfirmed, and the cash open at 9:30 AM ET sets the session's first directional test. The official weekly petroleum status report prints at 10:30 AM ET on Wednesday, October 21, 2026, as the calendar lists it. Midday brings two more. The ECB president is listed at 12:00 PM ET and the 20-year Treasury auction at 1:00 PM ET, per the news-feed calendar and unconfirmed. The after-close releases follow. The 6:00 PM ET Globex reopen on Wednesday carries earnings gap risk in both directions.
One path is weighted. In the review's analyst judgment the most probable path holds the contract between Pivot S1 at 29,410.17 and Pivot R2 at 30,168.58, with a rally from the reopened session toward the 30,100 to 30,160 band that fails beneath three standard deviations resistance at 30,256.47 weighted above a sustained break higher. No measured frequency backs it. The alternative is a sustained earnings-driven rally, building on the reopened session's quote above Pivot R1, through Pivot R2 toward the 9-day crossing price at 30,239.28 and Pivot R3 at 30,433.67. The 14-day stochastic sits near the bottom of its range. The settle sits 985.16 points beneath the 20-day average, which leaves room for a reflex rally. In the review's judgment the first-order event for NQ on Wednesday is the after-close pair of results from the social-media group and the electric-vehicle maker, listed on the news-feed calendar and unconfirmed as to time.
Tuesday's 29,903.50 high, the top of an inside day, now sits 196.50 points under Wednesday's short band.
The complete data picture
Every number behind Wednesday’s plan, charted first, then the full level lists, then the complete numeric reference underneath.
Full numeric reference, every remaining figure from the session review
1. Executive Summary
The December Nasdaq-100 contract settled at 29,675.25 on Tuesday, down 47.25 or 0.16 percent from Monday's settle of 29,722.50, after trading between 29,903.50 and 29,391.75, a 511.75 point daily range. The settle finished at 55.4 percent of the range, and the 511.75 point range was 0.94 times the published 14-day average daily range of 543.13 points. Tuesday was an inside day against Monday, with a lower high and a higher low, and the settle was the lowest since the 29,391.50 settle of 10/16.
The Nasdaq-100 cash index closed at 29,490.28, down 39.06 or 0.13 percent, while the S&P 500 cash index closed up 0.28 percent and the Dow industrials closed up 1.02 percent at 52,495.88; the semiconductor index closed down 0.29 percent. The desk note described sector rotation, with the equal-weight S&P 500 fund up 1.0 percent against the Nasdaq-100 fund down 0.1 percent. Provider commentary attributed the index gains to earnings optimism, weaker crude and lower yields, and said weakness in chipmakers and AI-infrastructure stocks kept the Nasdaq-100 negative.
After the close the news feed carried the streaming company's third-quarter results, with earnings of 0.87 per share against 0.82 expected, revenue in line at 12.87 billion and fourth-quarter guidance beneath expectations, and at 4:32 PM ET a server maker's preliminary net sales of 18.5 billion to 19.5 billion against a 14.99 billion estimate. The desk note said the streaming company's shares traded down about 6 percent and the shares of a newly listed space-launch company up about 5 percent after their results. The reopened Globex session quoted the December contract at 29,941.25 at 6:23 PM ET, 266.00 points above the settle; that is a reopened-session quote, not a settlement.
The ten-year yield index closed at 5.12 percent and the dollar index at 101.73. The published 14-day average true range is 528.37 points. The Primary Setup below is a short from the 30,100 to 30,160 band beneath Pivot R2 at 30,168.58, stopped at 30,260 above three standard deviations resistance at 30,256.47, with objectives at 30,000, 29,870 and an extended 29,740.
2. Price Action & Technical Structure
2.1 Intraday and Session Review
The Tuesday session opened at 29,745.50 at the Monday 6:00 PM ET reopen, 23.00 points above Monday's settle, marked a daily high of 29,903.50 and a daily low of 29,391.75, and settled at 29,675.25. No intraday series was preserved for this session, so this review does not describe the order in which the high and the low printed, and no timed price path is asserted; the daily bar alone fixes the open, the extremes and the settle.
The settle sits 283.50 points above the low and 228.25 points beneath the high. The open-to-settle body is 70.25 points lower, with an upper shadow of 158.00 points above the open and a lower shadow of 283.50 points beneath the settle.
Globex reopened at 6:00 PM ET on Tuesday for the Wednesday session, so the open, high and low shown on the provider's overview, 29,925.00, 29,976.00 and 29,922.25, belong to the new Wednesday session and are not Tuesday's range. The provider's last quote at 6:23 PM ET was 29,941.25 and the chart showed 29,970.00 at 6:26 PM ET; these are reopened-session quotes, not settlements, and they sit above Pivot R1 at 29,921.92.
Tuesday's completed-session extremes are taken from the settlement row, and they are also the completed-session inputs behind the published pivot ladder rather than an independently read bar. Pivot R3 at 30,433.67 minus Pivot S3 at 28,898.42, divided by three, returns 511.75, and Pivot R2 at 30,168.58 minus Pivot S2 at 29,145.08, divided by two, returns the same 511.75. Three times the Pivot Point of 29,656.83 less the 29,675.25 settle gives a high plus low sum of 59,295.24, which the pair of 29,903.50 and 29,391.75 reproduces to the published rounding at 59,295.25, and that pair reproduces all seven published rungs.
The provider's settlement row and the chart's completed daily bar carry the same 29,903.50 high and 29,391.75 low.
2.2 Daily Structure
Tuesday was an inside day: the 29,903.50 high sits 80.00 points beneath Monday's 29,983.50, and the 29,391.75 low sits 165.75 points above Monday's 29,226.00.
Settlements over the last eight sessions ran 31,108.75, 30,898.25, 30,791.50, 30,182.75, 30,143.75, 29,391.50, 29,722.50 and 29,675.25. The sequence of session highs over the last six sessions reads 30,906.00, 30,891.50, 30,196.75, 30,225.00, 29,983.50 and 29,903.50, and the sequence of session lows reads 30,591.25, 30,078.00, 29,622.50, 29,268.75, 29,226.00 and 29,391.75.
The one-month low of 29,226.00 sits 449.25 points beneath the settle, and the 13-week low stands at 27,482.00. Above, the one-month, 13-week and 52-week high all stand at 31,616.50. No prior-quarter high or low was captured.
2.3 4-Hour and Swing Structure
Daily ranges for the last eight sessions ran 313.50, 445.00, 314.75, 813.50, 574.25, 956.25, 757.50 and 511.75. The settlement changes over the same eight sessions read plus 139.25, minus 210.50, minus 106.75, minus 608.75, minus 39.00, minus 752.25, plus 331.00 and minus 47.25.
The retracement grid published for Wednesday places the 50 percent retracement of the 13-week range at 29,549.25, the 38.2 percent retracement from the 13-week high at 30,037.12, the 38.2 percent retracement from the four-week low at 30,139.17 and the 50 percent retracement of the four-week range at 30,421.25. No four-hour series was captured, so swing structure here rests on daily bars only.
2.4 Moving Averages
The averages cited in this subsection were computed from the provider's daily settlement series for the December contract, which holds 259 completed sessions through Tuesday; the partial Wednesday row returned after the 6:00 PM ET reopen was dropped before counting. The 5-day average stands at 29,823.15, the 9-day at 30,320.42, the 20-day at 30,660.41, the 50-day at 30,167.04, the 100-day at 30,030.97 and the 200-day at 28,333.99.
The 29,675.25 settle sits 147.90 points beneath the 5-day average, 645.17 points beneath the 9-day, 985.16 points beneath the 20-day, 491.79 points beneath the 50-day and 355.72 points beneath the 100-day, and 1,341.26 points above the 200-day. The 5-day average fell 223.25 from Monday's 30,046.40, because the 10/13 settle of 30,791.50 left the window and was replaced by 29,675.25. The 20-day fell 67.66 from 30,728.08, because the 09/22 settle of 31,028.50 left that window, and the 50-day fell 7.21 from 30,174.25.
The 20-day average sits above the 50-day because the last 20 settlements averaged 30,660.41 against 30,167.04 for the full 50, which means the 30 older settlements in the 50-day window averaged lower, at 29,838.12. The 50-day sits above the 100-day because the 50 older settlements in the 100-day window averaged lower, at 29,894.91, and the 100-day sits above the 200-day because the 100 older settlements in the 200-day window averaged lower, at 26,637.01. The projection grid gives the prices at which each average would be crossed on Wednesday: 30,239.28 for the 9-day, 30,634.56 for the 18-day and 30,232.28 for the 40-day.
2.5 Oscillator and Trend Readings
The oscillator figures below are as published on the provider's technical page, read at 6:24 PM ET after the 6:00 PM ET reopen, so they may include the first minutes of the Wednesday session rather than the settle alone; they are the provider's published readings and were not computed here. The 9-day relative strength reads 33.64, the 14-day relative strength 39.58 and the 20-day relative strength 43.65.
The 9-day raw stochastic reads 20.06 percent and the 14-day raw stochastic 18.79 percent, while the 14-day stochastic %K reads 14.93 percent and the 14-day stochastic %D 15.01 percent, so %K sits fractionally beneath %D near the bottom of the range.
The 9-day directional index ADX reads 35.78 with the 9-day +DI at 7.86 and the 9-day -DI at 29.53; the 14-day directional index ADX reads 22.38 with the 14-day +DI at 11.93 and the 14-day -DI at 27.51, so negative direction leads on both and the 9-day ADX reads above the 14-day. The 9-day historic volatility reads 16.63 percent and the 14-day historic volatility 16.67 percent.
The composite multi-indicator read published for the Wednesday session is 40 percent sell, unchanged from the prior session's snapshot of 40 percent sell, with signal strength described as soft and direction as weakening. The snapshot history reads 40 percent buy a week ago and 72 percent buy a month ago. The short-horizon group averages 60 percent sell, the medium-horizon group 25 percent sell and the long-horizon group hold, and the composite trend indicator reads sell.
2.6 Volatility and Expected Range
The published 14-day average true range stands at 528.37 points and the 14-day average daily range at 543.13 points; the 9-day average true range is 557.70 with a 9-day average daily range of 595.61, and the 20-day average true range is 517.02 with a 20-day average daily range of 507.25. Tuesday's 511.75 point range was 0.94 times the 14-day average daily range.
Adding and subtracting the 14-day average true range of 528.37 points from the 29,675.25 settle frames Wednesday between 29,146.88 and 30,203.62. The published standard-deviation bands are built from five settlements: one deviation spans 29,339.68 to 30,010.82, two spans 29,200.69 to 30,149.81 and three spans 29,094.03 to 30,256.47. These bands describe settlement dispersion, not intraday reach, and the reopened session already trades above Pivot R1.
3. Key Levels
3.1 Resistance
Above the 29,675.25 settle, the first overhead references are the 29,734.97 conversion of the modeled volatility threshold and the 29,859.97 conversion of the largest gamma concentration, followed by Tuesday's 29,903.50 high, Pivot R1 at 29,921.92 and Monday's 29,983.50 high. One standard deviation resistance at 30,010.82 and the 38.2 percent retracement from the 13-week high at 30,037.12 come next, then the 38.2 percent retracement from the four-week low at 30,139.17, two standard deviations resistance at 30,149.81, the 9-40 day crossing price at 30,159.96 and Pivot R2 at 30,168.58. The 40-day crossing price at 30,232.28, the 9-day crossing price at 30,239.28, three standard deviations resistance at 30,256.47 and Pivot R3 at 30,433.67 form the extended band.
3.2 Support
Beneath the settle sits the Pivot Point at 29,656.83, with the published stall projection at 29,588.76, the published target price at 29,564.97 and the 50 percent retracement of the 13-week range at 29,549.25 next. Pivot S1 at 29,410.17, Tuesday's 29,391.75 low and one standard deviation support at 29,339.68 follow, then the one-month low at 29,226.00 and two standard deviations support at 29,200.69. Pivot S2 at 29,145.08, three standard deviations support at 29,094.03 and Pivot S3 at 28,898.42 form the deeper band.
4. Macro Drivers
4.1 Mag7 Earnings and AI Capex Cycle
The streaming company reported after the close: the news feed carried earnings of 0.87 per share against 0.82 expected, revenue of 12.87 billion in line with expectations, free cash flow of 2.88 billion against 3.22 billion expected, and fourth-quarter revenue guidance of 13.44 billion against 13.51 billion expected. The desk note said the streaming company's shares traded down about 6 percent after the release. The news feed also carried press reports between 3:32 PM ET and 3:42 PM ET on large multi-year cloud computing commitments disclosed in an AI developer's listing filing, naming a search-engine group, a software maker and the leading graphics-chip maker as counterparties.
A social-media group is listed at 4:00 PM ET and an electric-vehicle maker at 4:15 PM ET on Wednesday on the news-feed calendar and unconfirmed, with the calendar placing both after the close without a confirmed time, and a search-engine group and a software maker report on October 28, as the calendar lists it.
4.2 Semiconductor Cycle and Tech Sector Rotation
The semiconductor index closed at 11,283.81, down 0.29 percent, after trading as low as 11,043.24, and provider commentary said chipmakers and AI-infrastructure stocks weighed on the Nasdaq-100. At 4:32 PM ET the news feed carried a server maker's preliminary net sales of 18.5 billion to 19.5 billion against a 14.99 billion estimate, citing demand for AI platforms. The desk note described rotation toward healthcare and financials, with the healthcare sector fund up 2 percent and the financials sector fund up 1 percent.
4.3 Fed Policy and Real Yields (Duration Sensitivity)
The ten-year yield index traded between 5.07 and 5.14 percent and closed at 5.12 percent against 5.13 percent on Monday, and the thirty-year index closed at 5.43 percent against 5.47 percent. No inflation-protected yield series was captured. The next policy statement is scheduled for 2:00 PM ET on October 28, 2026, as the calendar lists it, and the 20-year Treasury auction is listed at 1:00 PM ET on Wednesday, per the news-feed calendar and unconfirmed.
4.4 Geopolitical Backdrop
The news feed carried Iranian media reports of tankers catching fire in the southern corridor of the Strait of Hormuz at 10:36 AM ET and 12:51 PM ET, a press report at 10:11 AM ET that a mediation proposal received US approval and preliminary Iranian agreement, and at 11:12 AM ET a diplomat's statement that reports of a close deal are wrong. December WTI settled 0.73 percent lower at 97.82. These are statements carried by the news feed rather than confirmed events.
4.5 Cross-Asset and Volatility
The volatility index closed at 17.31 against 18.44 on Monday, the Nasdaq-100 volatility index at 25.22 against 25.56, and the volatility-of-volatility index at 97.15 against 106.93. The dollar index closed at 101.73, down 0.25. The NYSE composite rose 0.93 percent, so breadth outside the Nasdaq-100 was firmer than the index itself.
4.6 Institutional Positioning
No weekly positioning report was captured. Open interest on the December contract stood at 272,277 for Monday, on the 2026-10-19 row of the provider's settlement record, and Tuesday's volume was 685,959 contracts against 628,793 on Monday, the 2026-10-19 row, revised from the 618,989 carried in Tuesday's outlook; Tuesday's open interest is not yet reported. The measured closing basis was 184.97 points, the December settlement of 29,675.25 less the 29,490.28 cash close from the same provider's daily record, against 193.16 on Monday.
5. QQQ Options Flow Context (Proxy)
This review uses the QQQ fund as the proxy for the positioning data available, alongside the index levels published in the same desk note. The desk note read for this section is the 5:34 PM ET edition for Tuesday, read at 6:18 PM ET. Its reference prices are the prior session's closes, not Tuesday's: NDX 29,529 matches Monday's 29,529.34 cash close and QQQ 718 matches the console's 718.36 previous-close field. Every index level below is read against Tuesday's 29,490.28 cash close.
On the Nasdaq-100 index the modeled volatility threshold sits at NDX 29,550, the largest gamma concentration and the primary call side ceiling both at NDX 29,675, the modeled gamma-flip level at NDX 29,676 and the primary put side support base at NDX 28,000. The cash close sits 59.72 points beneath the threshold, 184.72 points beneath the concentration and 185.72 points beneath the flip level. Gamma tilt reads 0.943 and gamma notional minus 4.158 million dollars, both model outputs. The note's key index strikes are 29,675, 30,000, 29,000 and 31,000.
On the QQQ proxy the primary call side ceiling sits at 760, the largest gamma concentration at 720, the primary put side support base at 700, the modeled volatility threshold at 721 and the modeled gamma-flip level at 727. The fund's gamma tilt reads 0.625 and gamma notional minus 1.034 billion dollars, proxy model outputs. The QQQ console, read at 6:18 PM ET with a page date of 2026-10-20, shows call gamma of minus 1.59 billion against put gamma of minus 2.54 billion, one-month implied volatility of 21.14 percent against realised volatility of 15.80 percent, an implied-volatility rank of 42.78 percent and a put-to-call open-interest ratio of 1.43.
At the measured closing basis of 184.97 points the modeled volatility threshold at NDX 29,550 corresponds to 29,734.97 on the December contract, the concentration and call side ceiling at NDX 29,675 to 29,859.97 and the modeled gamma-flip level at NDX 29,676 to 29,860.97. These conversions are this review's, not the source's. Tuesday's 29,903.50 high printed 42.53 points above the 29,860.97 conversion of the flip level, and the settle sits beneath all three conversions.
The desk note described tech lagging the broader market and index options flow dominated by short-dated call selling; those characterisations are the note's, and the console reports volume and modeled gamma without trade side, so no directional read is drawn from them here. The volatility index options expiration at 9:30 AM ET on Wednesday is listed by the desk note, unconfirmed. In this review's interpretation, drawn from the index model and the QQQ fund proxy, both model outputs, a cash close beneath the flip level with negative gamma notional on both the index and the fund describes positioning that is less likely to dampen moves, a damping read with no direction, which matters ahead of Wednesday's large earnings releases.
6. Forecast
6.1 Night Session (6:00 PM ET Tuesday to 3:00 AM ET Wednesday, Globex and Asia)
Globex reopened at 6:00 PM ET on Tuesday and quoted the December contract at 29,941.25 at 6:23 PM ET, above Pivot R1 at 29,921.92, after the streaming company's and the server maker's releases. The President is listed to speak at 7:00 PM ET and Japan's trade balance at 7:50 PM ET, both per the news-feed calendar and unconfirmed. Bias neutral to higher above Pivot R1, expected Globex band roughly 29,750 to 30,150.
6.2 London Session (3:00 AM to 8:00 AM ET Wednesday)
UK consumer prices are listed at 2:00 AM ET, per the news-feed calendar and unconfirmed. Bias neutral, expected band roughly 29,700 to 30,170, with two standard deviations resistance at 30,149.81 and Pivot R2 at 30,168.58 the first meaningful resistance band.
6.3 Morning Session (9:30 AM to 12:00 PM ET Wednesday, RTH Open)
The volatility index options expiration is listed by the desk note at 9:30 AM ET, unconfirmed, and the cash open at 9:30 AM ET sets the session's first directional test. The official weekly petroleum status report prints at 10:30 AM ET on Wednesday, October 21, 2026, as the calendar lists it. Expected band roughly 29,550 to 30,250.
6.4 Afternoon Session (12:00 PM to 4:00 PM ET Wednesday)
The ECB president is listed at 12:00 PM ET and the 20-year Treasury auction at 1:00 PM ET, both per the news-feed calendar and unconfirmed. Expected band roughly 29,450 to 30,260, with positioning into the after-close earnings releases the main afternoon influence in this review's judgment.
6.5 Night Session Forward (6:00 PM ET Wednesday)
A social-media group and an analog chip maker are listed at 4:00 PM ET, an information-technology group at 4:10 PM ET and an electric-vehicle maker at 4:15 PM ET on the news-feed calendar and unconfirmed, with the calendar placing them after Wednesday's close without a confirmed time, so the 6:00 PM ET Globex reopen on Wednesday carries earnings gap risk in both directions.
6.6 Expected Range (Wednesday Full Session)
Low-range scenario: 29,750 to 30,150; Mid-range scenario (most likely): 29,550 to 30,250; High-range scenario: 29,150 to 30,430.
6.7 Most Likely Path
In this review's analyst judgment the most probable path holds the contract between Pivot S1 at 29,410.17 and Pivot R2 at 30,168.58, with a rally from the reopened session toward the 30,100 to 30,160 band that fails beneath three standard deviations resistance at 30,256.47 weighted above a sustained break higher. The settle sits beneath the 5-day, 9-day, 20-day, 50-day and 100-day settlement averages, negative direction leads on both directional systems, the composite reads 40 percent sell and the cash close sits beneath the modeled gamma-flip level (a model output, read as a damping lens with no direction).
The alternative that would invalidate this reading is a sustained earnings-driven rally, building on the reopened session's quote above Pivot R1, that carries the contract through Pivot R2 at 30,168.58 toward the 9-day crossing price at 30,239.28 and Pivot R3 at 30,433.67. The 14-day stochastic sits near the bottom of its range. The settle also sits 985.16 points beneath the 20-day average, which leaves room for a reflex rally.
7. Wednesday Economic Calendar
Tuesday's releases are complete. Housing starts and building permits printed at 8:30 AM ET on Tuesday at 1.221 million and 1.400 million, per the news-feed calendar, and pending home sales printed at 10:00 AM ET at minus 7.3 percent. The streaming company reported after the close, in the calendar's 4:01 PM ET slot, and the news feed carried a server maker's preliminary results at 4:32 PM ET.
On Tuesday evening the President is listed to speak at 7:00 PM ET and Japan's trade balance at 7:50 PM ET, both per the news-feed calendar and unconfirmed. On Wednesday UK consumer prices are listed at 2:00 AM ET and the Bank of England governor at 9:00 AM ET, per the news-feed calendar and unconfirmed. The volatility index options expiration is listed by the desk note at 9:30 AM ET, unconfirmed. The official weekly petroleum status report prints at 10:30 AM ET on Wednesday, October 21, 2026, as the calendar lists it. The ECB president is listed at 12:00 PM ET and the 20-year Treasury auction at 1:00 PM ET, per the news-feed calendar and unconfirmed.
After the close, A social-media group and an analog chip maker are listed at 4:00 PM ET, an information-technology group at 4:10 PM ET and an electric-vehicle maker at 4:15 PM ET on the news-feed calendar and unconfirmed, with the calendar placing them after Wednesday's close without a confirmed time. The FOMC statement is scheduled for 2:00 PM ET on Wednesday, October 28, 2026, as the calendar lists it, the same day a search-engine group and a software maker report. In this review's judgment the first-order event for NQ on Wednesday is the after-close releases from the social-media group and the electric-vehicle maker, with the morning volatility-index expiration (listed by the desk note) and the 1:00 PM ET auction (per the news-feed calendar) the scheduled intraday events, both unconfirmed.
8. Primary Trade Setup
Direction: Short
Rationale: The settle sits beneath the 5-day, 9-day, 20-day, 50-day and 100-day settlement averages, negative direction leads on the 9-day and 14-day directional systems, the composite reads 40 percent sell, and the cash close sits beneath the modeled gamma-flip level with negative gamma notional on both the index model and the QQQ fund proxy (model outputs, read as a damping lens with no direction). A rally into two standard deviations resistance at 30,149.81 and Pivot R2 at 30,168.58 offers a short with a defined risk point above three standard deviations resistance at 30,256.47. The reopened session already trades above Pivot R1 at 29,921.92 after the after-close releases, so the setup is an analyst judgment that rallies stall beneath Pivot R2, not a measured edge.
Entry Zone: 30,100 to 30,160
Stop Loss: 30,260 (above three standard deviations resistance at 30,256.47 and the 9-day crossing price at 30,239.28)
Target 1 (T1): 30,000 (10.82 beneath one standard deviation resistance at 30,010.82)
Target 2 (T2): 29,870 (10.03 above the 29,859.97 conversion of the largest gamma concentration)
Target 3 (T3, extended): 29,740 (5.03 above the 29,734.97 conversion of the modeled volatility threshold)
Risk-to-Reward: Approximately 1:1 to T1, 1:2 to T2, 1:3 to T3
Invalidation: A settle above three standard deviations resistance at 30,256.47 negates the thesis. Short of that, the edge is removed by acceptance above the entry band and not by a touch, defined as two consecutive 30-minute closes above 30,160.
Macro override: A strong earnings-driven rally in the largest technology names, or a confirmed de-escalation in the Gulf that pulls crude and yields lower, would support a further advance. In that scenario a move through the 30,260 stop removes the setup, and Pivot R3 at 30,433.67 becomes the reference within one 14-day average true range of 528.37 points of the 30,260 stop (173.67 points beyond it).
Sources and methodology
This outlook is built from our session review of the December E-mini Nasdaq-100 contract, the December ’26 contract, prepared after Tuesday's close on October 20, 2026 for the Wednesday, October 21, 2026 session. Tuesday's open, high, low and settle come from the provider's daily settlement record for the December contract, the 2026-10-20 row, and match the chart's completed daily bar. Tuesday's completed extremes are also the inputs behind the published pivot ladder: Pivot R3 at 30,433.67 less Pivot S3 at 28,898.42, divided by three, and Pivot R2 at 30,168.58 less Pivot S2 at 29,145.08, divided by two, both return 511.75, and three times the 29,656.83 Pivot Point less the settle gives 59,295.24, which the pair of 29,903.50 and 29,391.75 reproduces to the published rounding at 59,295.25. No intraday series was preserved for Tuesday, so no statement in this article places a print at a time of day, and Tuesday's card is graded against the daily bar alone. Tuesday's session opened at the Monday 6:00 PM ET reopen. Globex reopened at 6:00 PM ET Tuesday, so the open, high and low on the provider's overview belong to the Wednesday session and are not Tuesday's range.
The moving averages were computed from the provider's 259-session daily settlement series for the December contract, with the partial Wednesday row dropped; the oscillators are cited as published, read at 6:24 PM ET after the reopen. Volume and open interest come from the provider's daily record: the 2026-10-20 row reads 685,959 contracts with open interest not yet reported, the 2026-10-19 row now reads 628,793 contracts and open interest of 272,277, where Tuesday's outlook carried 618,989 for Monday, and the 2026-10-16 row reads open interest of 280,923. The desk note used is the 5:34 PM ET Tuesday edition, read at 6:18 PM ET, with Monday's closes in its reference column; every Nasdaq futures equivalent is the review's conversion at the 184.97 point measured basis, the December settlement less the cash close from the same provider's daily record, and Monday's 193.16 basis is the figure carried in Tuesday's outlook. The QQQ fund is a proxy read alongside the index levels. The reading that positioning is less likely to dampen moves is the review's interpretation from the index model and that proxy, both model outputs, and it is a damping read with no direction; the fund console, dated 2026-10-20, was read at 6:18 PM ET. The dollar index percentage, the volatility index change, the eight-session net change and the volume and open-interest changes are computed. Scenario ranges are analyst judgment, and items marked unconfirmed come from the news-feed calendar or the desk note.
Tuesday’s outlook for this contract is here, and the S&P 500 contract’s Tuesday outlook covers the index that rose 0.28 percent in cash on Tuesday. Outlooks for ES, NQ, GC and CL are collected on the market outlook page, and our forward trading record is on the performance statement.