At the Tuesday 6:00 PM ET reopen the December Nasdaq-100 contract opened at 29,925.00, 249.75 points above Tuesday's settle. The day's high was 30,113.00. It reached 13.00 points into the short band we published for Wednesday and stopped 147.00 points under that card's stop. The low of 29,727.50 held 335.75 points above Tuesday's low. A higher high and a higher low.
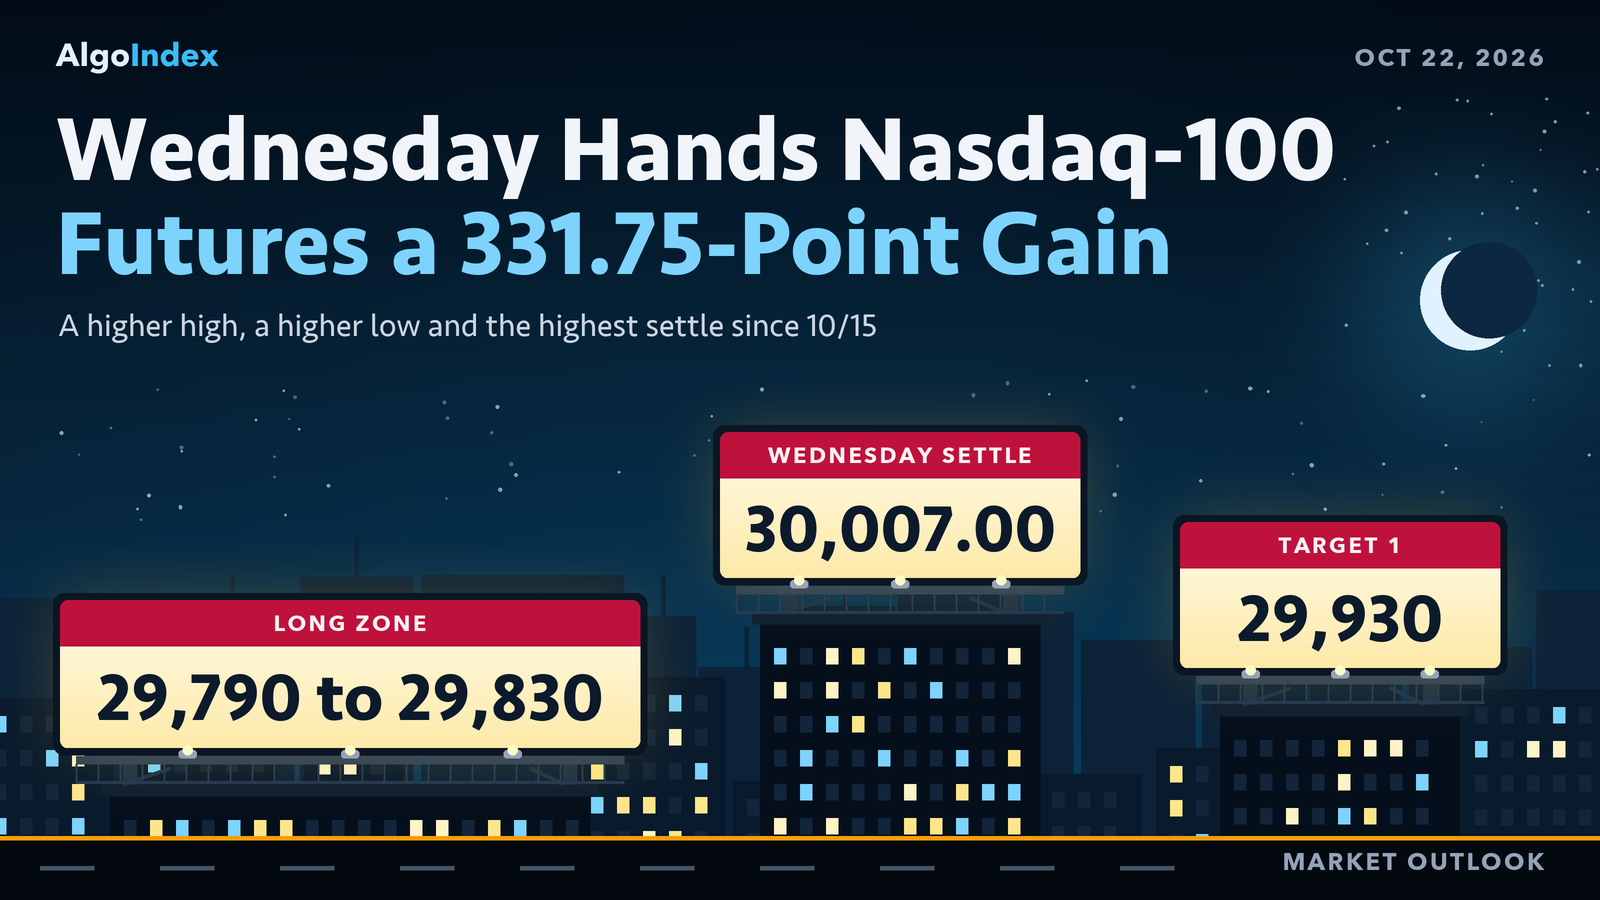
The contract settled at 30,007.00, up 331.75 points, or 1.12 percent, at 72.5 percent of a 385.50 point range. That was the highest settle since the 30,143.75 of 10/15. The Nasdaq-100 cash index rose 1.13 percent and the semiconductor index 1.97 percent. Results from a social-media group and an electric-vehicle maker came after the close. The reopened Globex session quoted 29,901.25 at 6:23 PM ET, 105.75 points beneath the settle.
December Nasdaq-100 futures settled at 30,007.00, up 331.75 points, with a higher high and a higher low on a 385.50 point range. Wednesday's published short band at 30,100 to 30,160 traded, the high reaching 13.00 points into it, and the 30,260 stop did not; the daily bar cannot show the order of the prints. The settle sits above the 5-day and 200-day averages and beneath the 9-day through the 100-day. The primary setup for Thursday is a long from 29,790 to 29,830, just above Pivot S1 at 29,785.33, stop 29,690, targets 29,930, 30,050 and an extended 30,170. The band and the first target sit beneath the settle. Weekly jobless claims are listed at 8:30 AM ET, per the news-feed calendar and unconfirmed.
Wednesday's short band at 30,100 to 30,160 traded; the 30,260 stop did not
In Wednesday’s outlook we set a short from 30,100 to 30,160, stop 30,260. Its targets sat at 30,000, 29,870 and an extended 29,740. Wednesday's bar, from the review and the provider's 2026-10-21 settlement row, opened at 29,925.00 at the Tuesday 6:00 PM ET reopen, marked a high of 30,113.00 and a low of 29,727.50, and settled at 30,007.00. The band traded. The high reached 13.00 points above its 30,100 bottom and stopped 47.00 points under its 30,160 top. The stop sat 147.00 points higher still. The settle finished 93.00 points beneath the band and 7.00 points above the first target.
All three target prices lie inside the day's range. The low ran 12.50 points through the extended 29,740. No intraday series was preserved for Wednesday, and the open sat 175.00 points beneath the band. So the low may have printed before the band traded or after it. The daily bar cannot show which, and no order is asserted here. No fill and no result is asserted either.
The card's other lines were never triggered. Its acceptance test needed two consecutive 30-minute closes above 30,160. No close could get there, since the high stopped 47.00 points beneath 30,160. The invalidation needed a settle above three standard deviations resistance at 30,256.47. The settle finished 249.47 points beneath it.
Its macro override named a strong earnings-driven rally in the largest technology names, or a confirmed de-escalation in the Gulf that pulls crude and yields lower, with a move through the 30,260 stop removing the setup. The desk note described Wednesday as a rally led by technology and earnings, with the largest technology names up about 1 percent. The review records no confirmed de-escalation. The news feed carried a report of ordered departures from US embassies across the Gulf and press reports of US troop and diplomatic moves, statements carried by the news feed rather than confirmed events. December WTI settled 0.68 percent lower at 97.15, and the ten-year yield index closed at 5.15 percent against 5.11 percent. The stop never traded. Pivot R3 at 30,433.67, the override's reference, sat 320.67 points above the high.
Our ranges are scored against the whole day's extremes, which is all the daily bar allows. The low-range case of 29,750 to 30,150 broke lower by 22.50 points. The most likely case of 29,550 to 30,250 held, the low 177.50 points above its bottom and the high 137.00 beneath its top, and the high-range case of 29,150 to 30,430 held. The night band of 29,750 to 30,150 contained the high but not the low. London's 29,700 to 30,170 contained the whole day, the low 27.50 points inside it. The morning band of 29,550 to 30,250 and the afternoon band of 29,450 to 30,260 contained it too. The bar cannot place the extremes in any one session.
The most probable path, an analyst judgment, kept the contract between Pivot S1 at 29,410.17 and Pivot R2 at 30,168.58. It held. The low stayed 317.33 points above the lower line and the high 55.58 beneath the upper. The weighted case was a rally toward the band that fails beneath three standard deviations resistance at 30,256.47. The high reached the band, and the settle finished 93.00 points beneath it. The alternative, a break through Pivot R2 toward the 9-day crossing price at 30,239.28 and Pivot R3 at 30,433.67, did not develop.
A 184.48 point basis, a crowded zone near Pivot S1 and a lid at 30,037.12
The basis narrowed to 184.48 points, the 30,007.00 settle less the 29,822.52 cash close, from 184.97 on Tuesday. Every December equivalent of a positioning level in this article uses it: 30,184.48 for the NDX 30,000 key strike, 29,859.48 for the call side and largest gamma concentration at NDX 29,675, 29,694.48 for the modeled volatility threshold at NDX 29,510, 29,599.48 for the modeled gamma-flip level at NDX 29,415 and 28,184.48 for the primary put side support base at NDX 28,000. The conversions are the review's own. The settle sits above all of them except the key-strike equivalent.
Resistance starts 30.12 points up, at the 38.2 percent retracement from the 13-week high at 30,037.12. The 9-day crossing price at 30,101.56, Wednesday's 30,113.00 high and the published target price at 30,113.92 follow, within 12.36 points of one another. Then come the 38.2 percent retracement from the four-week low at 30,139.17, the 30,143.75 settle of 10/15, the 50-day average at 30,168.74 and Pivot R1 at 30,170.83. The 10/14 settle of 30,182.75 and the 30,184.48 key-strike equivalent sit 1.73 points apart. The 9-day average at 30,213.47, the 40-day crossing price at 30,243.24 and one standard deviation resistance at 30,302.27 follow. Pivot R2 at 30,334.67, the 50 percent retracement of the four-week range at 30,421.25, two standard deviations resistance at 30,424.57, three standard deviations resistance at 30,518.42 and Pivot R3 at 30,556.33 form the extended band. The 18-day crossing price at 30,601.66 and the 20-day average at 30,622.53 sit beyond it. The 31,616.50 one-month, 13-week and 52-week high caps the list, 1,609.50 points up.
Support starts 57.83 points down, at the Pivot Point of 29,949.17. Wednesday's 29,925.00 open and Tuesday's 29,903.50 high sit beneath it, then the 29,859.48 call side equivalent. The zone gets crowded here. The 5-day average at 29,788.00 and Pivot S1 at 29,785.33 sit 2.67 points apart, just beneath the long band. Wednesday's 29,727.50 low, one standard deviation support at 29,711.73 and the 29,694.48 threshold equivalent come next, within 33.02 points, with Tuesday's 29,675.25 settle under them. The 29,599.48 flip equivalent, two standard deviations support at 29,589.43, Pivot S2 at 29,563.67 and the 50 percent retracement of the 13-week range at 29,549.25 form the next group. Three standard deviations support at 29,495.58, Pivot S3 at 29,399.83 and Tuesday's 29,391.75 low form the deeper band. The 29,226.00 one-month low sits 781.00 points beneath the settle. The 200-day average at 28,351.51, the 28,184.48 put side equivalent, the 27,482.00 13-week low and the 23,429.00 52-week low lie far below.
The averages split. The settle sits 219.00 points above the 5-day at 29,788.00 and 1,655.49 above the 200-day at 28,351.51. It sits 14.08 beneath the 100-day at 30,021.08, 161.74 beneath the 50-day at 30,168.74, 206.47 beneath the 9-day at 30,213.47 and 615.53 beneath the 20-day at 30,622.53. The 5-day fell 35.15 points from 29,823.15 even though the settle rose, because the 10/14 settle of 30,182.75 left the window. The 20-day fell 37.89 from 30,660.41 as the 09/23 settle of 30,764.75 dropped out. The 50-day was little changed from 30,167.04. Older settlements sit lower: the 30 older ones in the 50-day window averaged near 29,866, the 50 older ones in the 100-day window near 29,873 and the 100 older ones in the 200-day window near 26,682. Thursday's crossing prices are 30,101.56 for the 9-day, 30,601.66 for the 18-day and 30,243.24 for the 40-day.
Momentum sits below the midline. Relative strength reads 42.81 on the 9-day, 45.20 on the 14-day and 47.35 on the 20-day. The raw stochastics read 37.85 percent on the 9-day and 32.67 percent on the 14-day, and the 14-day %K at 24.08 percent sits 5.28 points above %D at 18.80 percent, in the lower part of the range. Sellers still lead on both windows. On the 9-day, negative direction at 26.89 tops positive at 11.43 by 15.46, with the ADX at 36.29; on the 14-day, 25.87 tops 14.08 by 11.79, with the ADX at 22.89. Historic volatility reads 18.55 percent and 17.53 percent. These readings are as published, read at 6:23 PM ET after the 6:00 PM ET reopen. They may include the first minutes of the Thursday session.
A composite multi-indicator read published for Thursday sits at 32 percent sell, against 40 percent sell for the prior session, with strength at its minimum and direction weakest. A week ago it read 8 percent sell. A month ago, 72 percent buy. The short-horizon group averages 40 percent sell, the medium 25 percent sell and the long hold, and the trend indicator reads sell.
Its lower shadow is the longer one. The bar's body measures 82.00 points higher from the 29,925.00 open, with an upper shadow of 106.00 points above the settle and a lower shadow of 197.50 points beneath the open. The 14-day average true range stands at 521.89 points and the 14-day average daily range at 526.21; the 9-day figures are 544.37 and 563.56 and the 20-day figures 513.05 and 503.92. One average true range either side of the settle spans 29,485.11 to 30,528.89. The deviation bands, built from five settlements, run 29,711.73 to 30,302.27, 29,589.43 to 30,424.57 and 29,495.58 to 30,518.42, and describe settlement dispersion only. Nine sessions of daily ranges read 313.50, 445.00, 314.75, 813.50, 574.25, 956.25, 757.50, 511.75 and 385.50 points. The session highs since 10/14 read 30,891.50, 30,196.75, 30,225.00, 29,983.50, 29,903.50 and 30,113.00, and the lows 30,078.00, 29,622.50, 29,268.75, 29,226.00, 29,391.75 and 29,727.50. No prior-quarter extremes were captured, so the 13-week extremes stand in.
A 1.13 percent Nasdaq-100 gain, a 1.97 percent chip rally and four after-close results
Technology led. The Nasdaq-100 cash index rose 1.13 percent, or 332.24 points, to 29,822.52, the semiconductor index 1.97 percent to 11,505.56 and the S&P 500 cash index 0.58 percent. The desk note described the session as a rally led by technology and earnings, with semiconductor and software funds each up about 2 percent and the largest technology names up about 1 percent. The desk note also said a space-launch company's shares rose 7.8 percent after earnings. Those characterisations are the note's.
Results came after the settlement. The news feed carried the social-media group's third-quarter earnings of 3.83 dollars a share against 3.57 expected and revenue of 64.60 billion against 63.33 billion, with operating income of 12.99 billion against a 20.85 billion estimate. The feed also carried a 2026 loss outlook of 18 billion to 19 billion for its virtual-reality unit, no revenue outlook for 2027 and plans for non-voting shares to fund artificial intelligence investment. The desk note said the shares traded about 4 percent higher after hours, near 724 dollars.
Three more followed. The news feed carried the electric-vehicle maker's adjusted earnings of 0.48 dollars a share against 0.44 expected, revenue of 28.05 billion against 28.13 billion and a gross margin of 19.6 percent against 17.8 percent. Its shares traded roughly flat near 386 dollars, the desk note said. Two more beat estimates on the feed. The feed carried the analog chip maker's earnings of 2.62 dollars a share against 2.42 expected, revenue of 6.06 billion against 5.93 billion and data center revenue up 95 percent from a year earlier. Then the information-technology group. Its operating earnings of 2.95 dollars a share against 2.86 expected came on revenue of 17.10 billion against 16.83 billion, on the feed. At 4:51 PM ET the feed carried a press report that a search-engine group stopped using nondisclosure agreements for data centers.
The reopened session quoted lower. The provider's last quote at 6:23 PM ET was 29,901.25 and the chart showed 29,839.00 at 6:26 PM ET, both beneath the settle and both quotes rather than settlements. The overview's Thursday-session open, high and low read 29,984.00, 29,993.25 and 29,888.00. The review sets these quotes beside the after-close releases and the Gulf headlines and assigns no cause.
Yields rose. The ten-year yield index closed at 5.15 percent against 5.11 percent on Tuesday and the thirty-year at 5.44 percent against 5.42 percent, and the Nasdaq-100 rose despite the higher yields. No inflation-protected yield series was captured, so the real-yield move is not measured here. The 20-year Treasury auction drew a high yield of 5.469 percent against 5.420 percent previously, per the news-feed calendar and unconfirmed. The next policy statement is scheduled for 2:00 PM ET on October 28, 2026, as the calendar lists it. Provider commentary said markets price a 15 percent chance of a quarter-point increase at that meeting.
The Gulf stayed in the headlines. At 2:47 PM ET the news feed carried a report that the State Department was preparing ordered departures from US embassies across the Gulf. From 4:52 PM ET to 4:58 PM ET it carried press reports, citing two US officials, that US troops and diplomats were moving out of posts in the Middle East. These are statements carried by the news feed rather than confirmed events. No causal link to the index is asserted.
Volatility eased. The Nasdaq volatility index closed at 24.42 against 25.22 on Tuesday, the volatility index at 16.68 against 17.31 and the volatility-of-volatility index at 94.55 against 97.15. The desk note said the volatility index fell about 4 percent after Wednesday's volatility-index options expiration, and that fixed-strike implied volatility declined during the session before partly reversing after the close. The dollar index closed at 101.78 against 101.70, and December gold settled 0.18 percent higher at 4,150.0.
The cash close sits above three positioning lines. The desk note read is the 5:42 PM ET edition for Wednesday, read at 6:19 PM ET, and its reference prices are the prior session's closes: NDX 29,490 equals Tuesday's 29,490.28 cash close, and QQQ 717 sits beside the fund's Tuesday close of 717.63. Against Wednesday's 29,822.52 close, the index sits 147.52 points above the 29,675 call side, which is also the largest gamma concentration, 312.52 above the 29,510 modeled volatility threshold and 407.52 above the 29,415 modeled gamma-flip level. The primary put side support base sits at NDX 28,000. The index model's gamma tilt reads 0.901, its gamma notional minus 3.247 million dollars and its 25-delta risk reversal minus 0.062, all model outputs. The note lists 29,675, 30,000, 29,000 and 29,200 as key index strikes.
On the QQQ proxy the call side sits at 760, the largest gamma concentration at 720, the modeled volatility threshold at 720, the flip level at 727 and the put side support base at 700. Those are proxy levels. The fund closed at 725.20 in the provider's daily record, 5.20 above the threshold and 1.80 beneath the flip level. Its gamma tilt reads 0.582 and its gamma notional minus 997.292 million dollars, proxy model outputs. The note's key fund strikes are 720, 700, 710 and 725. The console, read at 6:19 PM ET with a page date of 2026-10-21, shows call gamma of minus 1.52 billion against put gamma of minus 2.61 billion. Both gamma fields are negative. The put-to-call open-interest ratio reads 1.44, one-month implied volatility 21.59 percent against realised volatility of 15.40 percent, and the implied-volatility rank 45.86 percent.
In the review's interpretation, drawn from the index model and the QQQ fund proxy, a cash close above the index threshold and the call side, with negative gamma notional on the fund and on the index, leaves the contract in an environment where moves are less likely to be dampened. That is a damping read. It carries no direction. The modeled threshold and flip level are model outputs, not option strikes, and the console reports volume and modeled gamma without trade side, so no directional read is drawn from it.
Activity eased. Volume reached 654,208 contracts against Tuesday's 690,870, a figure revised from the 685,959 carried in Wednesday's outlook. Open interest reads 271,460 on Tuesday's 2026-10-20 row, which Wednesday's outlook listed as not yet reported, down 817 from 272,277 on the 2026-10-19 row. Wednesday's figure is not yet reported. No weekly positioning report was captured, so no managed-money or commercial figure is asserted.
The trade map for Thursday
The primary setup is a long from 29,790 to 29,830. Wednesday printed a higher high and a higher low, and the settle sits above the 5-day average at the highest level since 10/15. The cash close sits above the index's modeled volatility threshold and above the call side, model outputs read for damping only, and the desk note said the social-media group's results drew an after-hours gain. The band sits 4.67 points above Pivot S1 at 29,785.33, with the 5-day average at 29,788.00 just beneath it. Then the stop. The stop at 29,690 sits 21.73 points beneath one standard deviation support at 29,711.73, 4.48 beneath the 29,694.48 threshold equivalent and 37.50 beneath Wednesday's low. All of the band sits beneath the settle, 177.00 to 217.00 points down. The thesis, an analyst judgment, is that dips are bought after the earnings releases.
The targets sit at 29,930, 19.17 beneath the Pivot Point at 29,949.17 and still 77.00 beneath the settle; 30,050, 43.00 above the settle and 12.88 above the 30,037.12 retracement; and an extended 30,170, 0.83 beneath Pivot R1 at 30,170.83. The settle sits beneath the 9-day, 20-day, 50-day and 100-day averages and the composite reads 32 percent sell. So the review calls the setup an analyst judgment with no measured edge behind it.
Now the arithmetic. From the 29,810 midpoint the risk to the stop is 120 points, 23.0 percent of the 14-day average true range of 521.89. The targets sit 120, 240 and 360 points above the midpoint. Exact multiples. The first target, 29,930, sits 100.00 points above the band top and 77.00 beneath the settle. The second sits 43.00 above it. The stop sits 317.00 points beneath it.
The scenario ranges are analyst judgment. The low-range case runs 29,700 to 30,170, the most likely 29,560 to 30,330 and the high-range case 29,485 to 30,530. Then the sessions. The review expects roughly 29,700 to 30,100 through the night session, with a bias neutral above Pivot S1 at 29,785.33. The reopened session's 29,901.25 and 29,839.00 quotes sit inside that band, 201.25 and 139.00 points above its bottom. London follows at 29,650 to 30,150, neutral, with Pivot R1 at 30,170.83 the first meaningful resistance above. The morning band runs 29,560 to 30,330. The afternoon band runs 29,500 to 30,420, with Gulf headlines the main afternoon influence in the review's judgment.
Thursday's calendar starts Wednesday evening. The President is listed to speak at 7:00 PM ET and the Bank of Korea rate decision at 9:00 PM ET, both per the news-feed calendar and unconfirmed. Europe follows. The Swiss central bank's meeting minutes are listed at 3:30 AM ET and the UK industrial orders survey at 6:00 AM ET, per the news-feed calendar and unconfirmed. Weekly jobless claims are listed at 8:30 AM ET with a forecast of 200,000, per the news-feed calendar and unconfirmed. Then the open. The cash open at 9:30 AM ET sets the session's first directional test after the overnight earnings reaction. Euro-area consumer confidence is listed at 10:00 AM ET and a 5-year inflation-protected Treasury auction at 1:00 PM ET, per the news-feed calendar and unconfirmed. The scheduled calendar lists no Thursday entry. Globex reopens at 6:00 PM ET Thursday, with Australian flash purchasing managers' surveys at 6:00 PM ET and Japan's consumer prices at 7:30 PM ET, per the news-feed calendar and unconfirmed, ahead of Friday's flash surveys in Europe and the US.
One path is weighted. In the review's analyst judgment the most probable path holds the contract between Pivot S2 at 29,563.67 and Pivot R2 at 30,334.67, with a dip toward the 29,790 to 29,830 band that holds above one standard deviation support at 29,711.73 weighted slightly above a break lower. No measured frequency backs it. The alternative is a risk-off move on Gulf headlines, or a fading of the earnings reaction, that carries the contract beneath Pivot S2 toward three standard deviations support at 29,495.58. Negative direction leads on both directional systems and the composite reads 32 percent sell, so a break lower is a live alternative. Then the calendar. In the review's judgment the first-order influence for NQ on Thursday is the cash-session reaction to the social-media group's results, with the 8:30 AM ET jobless claims, listed by the news-feed calendar and unconfirmed, the scheduled macro release.
Wednesday's 29,727.50 low, the bottom of a higher-low day, now sits 62.50 points under Thursday's long band.
The complete data picture
Every number behind Thursday’s plan, charted first, then the full level lists, then the complete numeric reference underneath.
Full numeric reference, every remaining figure from the session review
1. Executive Summary
The December Nasdaq-100 contract settled at 30,007.00 on Wednesday, up 331.75 or 1.12 percent from Tuesday's settle of 29,675.25, after trading between 30,113.00 and 29,727.50, a 385.50 point daily range. The settle finished at 72.5 percent of the range, and the 385.50 point range was 0.73 times the published 14-day average daily range of 526.21 points. Wednesday printed a higher high and a higher low against Tuesday, and the settle was the highest since the 30,143.75 settle of 10/15.
The cash index closed at 29,822.52, up 332.24 or 1.13 percent, and the semiconductor index rose 1.97 percent, while the S&P 500 cash index gained 0.58 percent. The desk note described the session as a rally led by technology and earnings, with semiconductor and software funds each up about 2 percent and the largest technology names up about 1 percent, and said a space-launch company's shares rose 7.8 percent after earnings. The measured closing basis was 184.48 points, the December settlement less the cash close from the same provider's daily record.
After the close the news feed carried the social-media group's third-quarter results, with earnings of 3.83 dollars a share against 3.57 expected and revenue of 64.60 billion against 63.33 billion, operating income of 12.99 billion against a 20.85 billion estimate and no revenue outlook for 2027; the desk note said the social-media group's shares rose about 4 percent after hours while the electric-vehicle maker, which beat on adjusted earnings, traded roughly flat. An analog chip maker and an information-technology group also reported results above estimates on the feed. The reopened session quoted the contract at 29,901.25 at 6:23 PM ET and the chart showed 29,839.00 at 6:26 PM ET, beneath the settle, as the feed carried press reports of US troop and diplomatic moves in the Middle East.
The settle sits above the 5-day and 200-day settlement averages but beneath the 9-day, 20-day, 50-day and 100-day, negative direction leads on both directional systems, and the composite multi-indicator read is 32 percent sell with strength at its minimum. The published 14-day average true range is 521.89 points. The Primary Setup below is a long from the 29,790 to 29,830 band just above Pivot S1 at 29,785.33, stopped at 29,690 beneath one standard deviation support at 29,711.73, with objectives at 29,930, 30,050 and an extended 30,170.
2. Price Action & Technical Structure
2.1 Intraday and Session Review
The Wednesday session opened at 29,925.00 at the Tuesday 6:00 PM ET reopen, 249.75 points above Tuesday's settle, marked a daily high of 30,113.00 and a daily low of 29,727.50, and settled at 30,007.00. No intraday series was preserved for this session, so this review does not describe the order in which the high and the low printed, and no timed price path is asserted; the daily bar alone fixes the open, the extremes and the settle.
This review records only that the 30,113.00 high and the 29,727.50 low both belong to Wednesday's completed session and that the settle sits 279.50 points above the low and 106.00 points beneath the high.
Globex reopened at 6:00 PM ET on Wednesday for the Thursday session, so the open, high and low shown on the provider's overview, 29,984.00, 29,993.25 and 29,888.00, belong to the new Thursday session and are not Wednesday's range. The provider's last quote at 6:23 PM ET was 29,901.25 and the chart showed 29,839.00 at 6:26 PM ET; these are reopened-session quotes, not settlements.
Wednesday's completed-session extremes are taken from the settlement row, and they are also the completed-session inputs behind the published pivot ladder rather than an independently read bar. Pivot R3 at 30,556.33 minus Pivot S3 at 29,399.83, divided by three, returns 385.50, and Pivot R2 at 30,334.67 minus Pivot S2 at 29,563.67, divided by two, returns the same 385.50. Three times the Pivot Point of 29,949.17 less the 30,007.00 settle gives a high plus low sum of 59,840.51, which the pair of 30,113.00 and 29,727.50 reproduces to the published rounding at 59,840.50, and that pair reproduces all seven published rungs.
The provider's settlement row and the chart's completed daily bar carry the same 29,925.00 open, 30,113.00 high, 29,727.50 low and 30,007.00 settle.
2.2 Daily Structure
Wednesday printed a higher high and a higher low: the 30,113.00 high sits 209.50 points above Tuesday's 29,903.50, and the 29,727.50 low sits 335.75 points above Tuesday's 29,391.75. The settle above the 29,925.00 open leaves a body of 82.00 points, an upper shadow of 106.00 points above the settle and a lower shadow of 197.50 points beneath the open.
Settlements over the last nine sessions ran 31,108.75, 30,898.25, 30,791.50, 30,182.75, 30,143.75, 29,391.50, 29,722.50 and 29,675.25 before Wednesday's 30,007.00, so Wednesday's settle was the highest since the 30,143.75 settle of 10/15. The sequence of session highs over the last six sessions reads 30,891.50, 30,196.75, 30,225.00, 29,983.50, 29,903.50 and 30,113.00, and the sequence of session lows reads 30,078.00, 29,622.50, 29,268.75, 29,226.00, 29,391.75 and 29,727.50.
The one-month, 13-week and 52-week high all sit at 31,616.50, 1,609.50 points above the settle, and the one-month low of 29,226.00 sits 781.00 points beneath it. The 13-week low of 27,482.00 and the 52-week low of 23,429.00 frame the lower side. No prior-quarter high or low was captured, so the 13-week extremes serve as the available quarterly reference.
2.3 4-Hour and Swing Structure
Daily ranges for the last nine sessions ran 313.50, 445.00, 314.75, 813.50, 574.25, 956.25, 757.50, 511.75 and 385.50, so Wednesday's range was the narrowest since the 314.75 point range of 10/13. The settlement changes over the same nine sessions read plus 139.25, minus 210.50, minus 106.75, minus 608.75, minus 39.00, minus 752.25, plus 331.00, minus 47.25 and plus 331.75.
The retracement grid published for Thursday places the 38.2 percent retracement from the 13-week high at 30,037.12, 30.12 points above the settle, the 38.2 percent retracement from the four-week low at 30,139.17 and the 50 percent retracement of the four-week range at 30,421.25. Beneath the settle, the 50 percent retracement of the 13-week range sits at 29,549.25. No four-hour series was captured, so swing structure here rests on daily bars only.
2.4 Moving Averages
The averages cited in this subsection were computed from the provider's daily settlement series for the December contract, which holds 259 completed sessions through Wednesday; the partial Thursday row returned after the 6:00 PM ET reopen was dropped before counting. The 5-day average stands at 29,788.00, the 9-day at 30,213.47, the 20-day at 30,622.53, the 50-day at 30,168.74, the 100-day at 30,021.08 and the 200-day at 28,351.51.
The 30,007.00 settle sits 219.00 points above the 5-day average, 206.47 points beneath the 9-day, more than 600 points beneath the 20-day, 161.74 points beneath the 50-day, 14.08 points beneath the 100-day and 1,655.49 points above the 200-day. The 5-day average fell 35.15 points from Tuesday's 29,823.15 even though the settle rose, because the 10/14 settle of 30,182.75 left the window and was replaced by 30,007.00. The 20-day fell 37.89 points from 30,660.41, because the 09/23 settle of 30,764.75 left that window, and the 50-day was little changed from 30,167.04.
The 20-day average sits above the 50-day because the last 20 settlements averaged 30,622.53 against 30,168.74 for the full 50, which means the 30 older settlements in the 50-day window averaged lower, near 29,866. The 50-day sits above the 100-day because the 50 older settlements in the 100-day window averaged lower, near 29,873, and the 100-day sits above the 200-day because the 100 older settlements in the 200-day window averaged lower, near 26,682. The projection grid gives the prices at which each average would be crossed on Thursday: 30,101.56 for the 9-day, 30,601.66 for the 18-day and 30,243.24 for the 40-day.
2.5 Oscillator and Trend Readings
The oscillator figures below are as published on the provider's technical page, read at 6:23 PM ET after the 6:00 PM ET reopen, so they may include the first minutes of the Thursday session rather than the settle alone; they are the provider's published readings and were not computed here. The 9-day relative strength reads 42.81, the 14-day relative strength 45.20 and the 20-day relative strength 47.35.
The 9-day raw stochastic reads 37.85 percent and the 14-day raw stochastic 32.67 percent, while the 14-day stochastic %K reads 24.08 percent and the 14-day stochastic %D 18.80 percent, so %K sits above %D in the lower part of the range.
The 9-day directional index ADX reads 36.29 with the 9-day +DI at 11.43 and the 9-day -DI at 26.89; the 14-day directional index ADX reads 22.89 with the 14-day +DI at 14.08 and the 14-day -DI at 25.87, so negative direction leads on both. The 9-day historic volatility reads 18.55 percent and the 14-day historic volatility 17.53 percent.
The composite multi-indicator read published for the Thursday session is 32 percent sell, against the prior session's snapshot of 40 percent sell, with signal strength described as minimum and direction as weakest. The snapshot history reads 8 percent sell a week ago and 72 percent buy a month ago. The short-horizon group averages 40 percent sell, the medium-horizon group 25 percent sell and the long-horizon group hold, and the composite trend indicator reads sell.
2.6 Volatility and Expected Range
The published 14-day average true range stands at 521.89 points and the 14-day average daily range at 526.21 points; the 9-day average true range is 544.37 with a 9-day average daily range of 563.56, and the 20-day average true range is 513.05 with a 20-day average daily range of 503.92. Wednesday's 385.50 point range was 0.73 times the 14-day average daily range.
Adding and subtracting the 14-day average true range of 521.89 points from the 30,007.00 settle frames Thursday between 29,485.11 and 30,528.89. The published standard-deviation bands are built from five settlements: one deviation spans 29,711.73 to 30,302.27, two spans 29,589.43 to 30,424.57 and three spans 29,495.58 to 30,518.42. These bands describe settlement dispersion, not intraday reach, and an earnings or headline gap can open outside any of them.
3. Key Levels
3.1 Resistance
Above the 30,007.00 settle, the first overhead reference is the 38.2 percent retracement from the 13-week high at 30,037.12, followed by the 9-day average crossing price at 30,101.56, Wednesday's 30,113.00 high and the published target price at 30,113.92. The 38.2 percent retracement from the four-week low at 30,139.17 and Pivot R1 at 30,170.83 come next, then the 30,184.48 conversion of the NDX 30,000 key strike, the 40-day average crossing price at 30,243.24 and one standard deviation resistance at 30,302.27. Pivot R2 at 30,334.67, two standard deviations resistance at 30,424.57 and Pivot R3 at 30,556.33 form the extended band.
3.2 Support
Beneath the settle sits the Pivot Point at 29,949.17, then the 29,859.48 conversion of the NDX 29,675 call side and largest gamma concentration, Pivot S1 at 29,785.33 and Wednesday's 29,727.50 low. One standard deviation support at 29,711.73 and the 29,694.48 conversion of the modeled volatility threshold at NDX 29,510 follow, then Tuesday's 29,675.25 settle, the 29,599.48 conversion of the modeled gamma-flip level at NDX 29,415, two standard deviations support at 29,589.43 and Pivot S2 at 29,563.67. Three standard deviations support at 29,495.58 and Pivot S3 at 29,399.83 form the deeper band.
4. Macro Drivers
4.1 Mag7 Earnings and AI Capex Cycle
After the close the news feed carried the social-media group's third-quarter results: earnings of 3.83 dollars a share against 3.57 expected, revenue of 64.60 billion against 63.33 billion, operating income of 12.99 billion against a 20.85 billion estimate, a 2026 loss outlook for its virtual-reality unit of 18 billion to 19 billion and no revenue outlook for 2027, alongside plans for non-voting shares to fund artificial intelligence investment. On the feed, the electric-vehicle maker reported adjusted earnings of 0.48 dollars a share against 0.44 expected, revenue of 28.05 billion against 28.13 billion and a gross margin of 19.6 percent against 17.8 percent. The desk note said the social-media group traded about 4 percent higher after hours, near 724 dollars, and the electric-vehicle maker roughly flat near 386 dollars.
A search-engine group and a software maker report on Wednesday, October 28, 2026, as the calendar lists it, without a confirmed time. At 4:51 PM ET the feed carried a press report that a search-engine group stopped using nondisclosure agreements for data centers.
4.2 Semiconductor Cycle and Tech Sector Rotation
The semiconductor index closed at 11,505.56, up 1.97 percent, and the desk note put the semiconductor and software funds each up about 2 percent. After the close the news feed carried an analog chip maker's results, with earnings of 2.62 dollars a share against 2.42 expected, revenue of 6.06 billion against 5.93 billion and data center revenue up 95 percent from a year earlier, and an information-technology group's operating earnings of 2.95 dollars a share against 2.86 expected on revenue of 17.10 billion against 16.83 billion.
4.3 Fed Policy and Real Yields (Duration Sensitivity)
The ten-year yield index closed at 5.15 percent against 5.11 percent on Tuesday and the thirty-year at 5.44 percent against 5.42 percent. The 20-year Treasury auction drew a high yield of 5.469 percent against 5.420 percent previously, per the news-feed calendar and unconfirmed against the scheduled calendar. The next policy statement is scheduled for 2:00 PM ET on October 28, 2026, as the calendar lists it, and provider commentary said markets price a 15 percent chance of a quarter-point increase at that meeting. The Nasdaq-100 rose despite the higher yields; no inflation-protected yield series was captured, so the real-yield move is not measured here.
4.4 Geopolitical Backdrop
The news feed carried at 2:47 PM ET a report that the State Department was preparing ordered departures from US embassies across the Gulf, and at 4:52 PM ET to 4:58 PM ET the news feed carried press reports, citing two US officials, that US troops and diplomats were moving out of posts in the Middle East. December WTI settled 0.68 percent lower at 97.15. These are statements carried by the news feed rather than confirmed events.
4.5 Cross-Asset and Volatility
The Nasdaq volatility index closed at 24.42 against 25.22 on Tuesday, the volatility index at 16.68 against 17.31 and the volatility-of-volatility index at 94.55 against 97.15. The desk note said the volatility index fell about 4 percent after Wednesday's volatility-index options expiration and that fixed-strike implied volatility declined during the session before partly reversing after the close. The dollar index closed at 101.78 against 101.70, and December gold settled 0.18 percent higher at 4,150.0.
4.6 Institutional Positioning
No weekly positioning report was captured. Open interest on the December contract stood at 271,460 for Tuesday, on the 2026-10-20 row of the provider's settlement record, a figure Wednesday's outlook listed as not yet reported; Wednesday's open interest is not yet reported, and Wednesday's volume was 654,208 contracts against 690,870 on Tuesday, the 2026-10-20 row, revised from the 685,959 carried in Wednesday's outlook. The measured closing basis was 184.48 points, the December settlement of 30,007.00 less the 29,822.52 cash close from the same provider's daily record, against 184.97 on Tuesday.
5. QQQ Options Flow Context (Proxy)
This review uses the QQQ fund as the proxy for the positioning data available, alongside the index column of the same desk note. The desk note read for this section is the 5:42 PM ET edition for Wednesday, read at 6:19 PM ET. Its reference prices are the prior session's closes, not Wednesday's: NDX 29,490 equals Tuesday's 29,490.28 cash close and QQQ 717 sits beside the fund's Tuesday close of 717.63. Every level below is read against Wednesday's 29,822.52 cash close.
On the index the call side and the largest gamma concentration both sit at NDX 29,675, the modeled volatility threshold at NDX 29,510, the modeled gamma-flip level at NDX 29,415 and the primary put side support base at NDX 28,000. The cash close sits 147.52 points above the call side, 312.52 points above the threshold and 407.52 points above the flip level. Gamma tilt reads 0.901, gamma notional minus 3.247 million dollars and the 25-delta risk reversal minus 0.062, all model outputs. The note's key index strikes are NDX 29,675, 30,000, 29,000 and 29,200.
On the fund the call side sits at QQQ 760, the largest concentration at 720, the modeled volatility threshold at 720, the modeled gamma-flip level at 727 and the put side support base at 700; the fund closed at 725.20 in the provider's daily record, above the threshold and beneath the flip level. Fund gamma tilt reads 0.582 and gamma notional minus 997.292 million dollars, proxy model outputs, and the note's key fund strikes are 720, 700, 710 and 725. The fund's positioning console, read at 6:19 PM ET with a page date of 2026-10-21, shows call gamma of minus 1.52 billion against put gamma of minus 2.61 billion, a put-to-call open-interest ratio of 1.44, one-month implied volatility of 21.59 percent against realised volatility of 15.40 percent and an implied-volatility rank of 45.86 percent.
Index levels are converted to December futures at's measured 184.48 point basis: NDX 30,000 converts to 30,184.48, the call side at 29,675 to 29,859.48, the threshold at 29,510 to 29,694.48, the flip level at 29,415 to 29,599.48 and the put side base at 28,000 to 28,184.48. These conversions are this review's, not the source's. The modeled threshold and flip level are model outputs, not option strikes, and the console's current-price fields and high and low volatility point fields were not used.
In this review's interpretation, drawn from the index model and the QQQ fund proxy, both model outputs, a cash close above the index threshold and above the call side, with negative gamma notional on the fund and on the index, leaves the contract in an environment where moves are less likely to be dampened, a damping read with no direction; the setup in section 8 buys the 29,790 to 29,830 band, above the 29,694.48 conversion of the threshold, with the stop at 29,690.
6. Forecast
6.1 Night Session (6:00 PM ET Wednesday to 3:00 AM ET Thursday, Globex and Asia)
Globex reopened at 6:00 PM ET on Wednesday after the releases from the social-media group, the electric-vehicle maker, the information-technology group and the analog chip maker, and the chart showed the December contract at 29,839.00 at 6:26 PM ET. The President is listed to speak at 7:00 PM ET and the Bank of Korea rate decision at 9:00 PM ET, both per the news-feed calendar and unconfirmed. Bias neutral above Pivot S1 at 29,785.33, expected Globex band roughly 29,700 to 30,100.
6.2 London Session (3:00 AM to 8:00 AM ET Thursday)
The Swiss central bank's meeting minutes are listed at 3:30 AM ET and the UK industrial orders survey at 6:00 AM ET, both per the news-feed calendar and unconfirmed. Bias neutral, expected band roughly 29,650 to 30,150, with Pivot R1 at 30,170.83 the first meaningful resistance above.
6.3 Morning Session (9:30 AM to 12:00 PM ET Thursday, RTH Open)
Weekly jobless claims are listed at 8:30 AM ET, per the news-feed calendar and unconfirmed, and the cash open at 9:30 AM ET sets the session's first directional test after the overnight earnings reaction. Euro-area consumer confidence is listed at 10:00 AM ET, per the news-feed calendar and unconfirmed. Expected band roughly 29,560 to 30,330.
6.4 Afternoon Session (12:00 PM to 4:00 PM ET Thursday)
A 5-year inflation-protected Treasury auction is listed at 1:00 PM ET, per the news-feed calendar and unconfirmed. Expected band roughly 29,500 to 30,420, with Gulf headlines the main afternoon influence in this review's judgment.
6.5 Night Session Forward (6:00 PM ET Thursday)
Globex reopens at 6:00 PM ET on Thursday. Australian flash purchasing managers' surveys are listed at 6:00 PM ET and Japan's consumer prices at 7:30 PM ET, both per the news-feed calendar and unconfirmed, ahead of Friday's flash surveys in Europe and the US.
6.6 Expected Range (Thursday Full Session)
Low-range scenario: 29,700 to 30,170; Mid-range scenario (most likely): 29,560 to 30,330; High-range scenario: 29,485 to 30,530.
6.7 Most Likely Path
In this review's analyst judgment the most probable path holds the contract between Pivot S2 at 29,563.67 and Pivot R2 at 30,334.67, with a dip toward the 29,790 to 29,830 band that holds above one standard deviation support at 29,711.73 weighted slightly above a break lower. Wednesday printed a higher high and a higher low, the settle sits above the 5-day average, the cash close sits above the index threshold and the call side (model outputs, read as a damping lens with no direction), and the social-media group's results drew an after-hours gain on the desk note's account.
The alternative that would invalidate this reading is a risk-off move on Gulf headlines or a fading of the earnings reaction that carries the contract beneath Pivot S2 at 29,563.67 toward three standard deviations support at 29,495.58. The settle sits beneath the 9-day, 20-day, 50-day and 100-day averages, negative direction leads on both directional systems and the composite reads 32 percent sell, so a break lower is a live alternative.
7. Thursday Economic Calendar
Wednesday's releases are complete. UK consumer prices printed at 2:00 AM ET at 3.5 percent, per the news-feed calendar and unconfirmed against the scheduled calendar. Usual weekly earnings for the third quarter were scheduled for 10:00 AM ET and the official weekly petroleum status report for 10:30 AM ET on Wednesday, October 21, 2026, both as the calendar lists them. The 20-year Treasury auction drew a high yield of 5.469 percent at 1:00 PM ET, per the news-feed calendar and unconfirmed against the scheduled calendar. The social-media group, the electric-vehicle maker, the information-technology group and the analog chip maker reported after the close.
On Wednesday evening the President is listed to speak at 7:00 PM ET and the Bank of Korea rate decision at 9:00 PM ET, both per the news-feed calendar and unconfirmed. On Thursday the Swiss central bank's meeting minutes are listed at 3:30 AM ET and the UK industrial orders survey at 6:00 AM ET, per the news-feed calendar and unconfirmed. Weekly jobless claims are listed at 8:30 AM ET, with a forecast of 200,000 on the news-feed calendar and unconfirmed, euro-area consumer confidence at 10:00 AM ET and a 5-year inflation-protected Treasury auction at 1:00 PM ET, both per the news-feed calendar and unconfirmed.
Later in the window, the FOMC statement is scheduled for 2:00 PM ET on Wednesday, October 28, 2026, as the calendar lists it, and A search-engine group and a software maker report on Wednesday, October 28, 2026, as the calendar lists it, without a confirmed time. The scheduled calendar contains no Thursday, October 22, 2026 entry. In this review's judgment the first-order influence for NQ on Thursday is the cash-session reaction to the social-media group's results, with the 8:30 AM ET jobless claims, listed by the news-feed calendar and unconfirmed, the scheduled macro release.
8. Primary Trade Setup
Direction: Long
Rationale: Wednesday printed a higher high and a higher low, the settle sits above the 5-day average and at the highest level since 10/15, the cash close sits above the index's modeled volatility threshold and above the call side (model outputs, read as a damping lens with no direction), and the social-media group's results drew an after-hours gain on the desk note's account. A dip toward Pivot S1 at 29,785.33, into the band just above it, offers a long with a defined risk point beneath one standard deviation support at 29,711.73 and the 29,694.48 conversion of the threshold. The settle sits beneath the 9-day, 20-day, 50-day and 100-day averages and the composite reads 32 percent sell, so the setup is an analyst judgment that dips are bought after the earnings releases, not a measured edge.
Entry Zone: 29,790 to 29,830
Stop Loss: 29,690 (beneath one standard deviation support at 29,711.73 and the 29,694.48 conversion of the modeled volatility threshold)
Target 1 (T1): 29,930 (beneath the Pivot Point at 29,949.17)
Target 2 (T2): 30,050 (above Wednesday's 30,007.00 settle and the 30,037.12 retracement)
Target 3 (T3, extended): 30,170 (beneath Pivot R1 at 30,170.83)
Risk-to-Reward: Approximately 1:1 to T1, 1:2 to T2, 1:3 to T3
Invalidation: A settle beneath one standard deviation support at 29,711.73 negates the thesis. Short of that, the edge is removed by acceptance beneath the entry band and not by a touch, defined as two consecutive 30-minute closes beneath 29,790.
Macro override: A risk-off move on a confirmed Gulf escalation, or a reversal of the after-hours earnings reaction in the largest technology names, would pressure the contract. In that scenario a move through the 29,690 stop invalidates the long, and Pivot S2 at 29,563.67 and three standard deviations support at 29,495.58 become the references within one 14-day average true range of 521.89 points of the 29,690 stop (126.33 and 194.42 points beyond it).
Sources and methodology
This outlook is built from our session review of the December E-mini Nasdaq-100 contract, the December ’26 contract, prepared after Wednesday's close on October 21, 2026 for the Thursday, October 22, 2026 session. Wednesday's open, high, low and settle come from the provider's daily settlement record for the December contract, the 2026-10-21 row, and match the chart's completed daily bar. Wednesday's completed extremes are also the inputs behind the published pivot ladder: Pivot R3 at 30,556.33 less Pivot S3 at 29,399.83, divided by three, and Pivot R2 at 30,334.67 less Pivot S2 at 29,563.67, divided by two, both return 385.50, and three times the 29,949.17 Pivot Point less the settle gives 59,840.51, which the pair of 30,113.00 and 29,727.50 reproduces to the published rounding at 59,840.50. No intraday series was preserved for Wednesday, so no statement in this article places a Wednesday print at a time of day, and Wednesday's card is graded against the daily bar alone. Wednesday's session opened at the Tuesday 6:00 PM ET reopen. Globex reopened at 6:00 PM ET Wednesday, so the open, high and low on the provider's overview belong to the Thursday session and are not Wednesday's range.
The moving averages were computed from the provider's 259-session daily settlement series for the December contract, with the partial Thursday row dropped; the oscillators are cited as published, read at 6:23 PM ET after the reopen. Volume and open interest come from the provider's daily record: the 2026-10-21 row reads 654,208 contracts with open interest not yet reported, the 2026-10-20 row now reads 690,870 contracts and open interest of 271,460, where Wednesday's outlook carried 685,959 contracts and open interest not yet reported, and the 2026-10-19 row reads open interest of 272,277. The desk note used is the 5:42 PM ET Wednesday edition, read at 6:19 PM ET, with Tuesday's closes in its reference column; every Nasdaq futures equivalent is the review's conversion at the 184.48 point measured basis, the December settlement less the cash close from the same provider's daily record, against 184.97 on Tuesday. The QQQ fund is a proxy read alongside the index levels. The reading that moves are less likely to be dampened is the review's interpretation from the index model and that proxy, both model outputs, and it is a damping read with no direction; the fund console, dated 2026-10-21, was read at 6:19 PM ET. The dollar index percentage, the nine-session net change and the volume and open-interest changes are computed. Scenario ranges are analyst judgment, and items marked unconfirmed come from the news-feed calendar.
Wednesday’s outlook for this contract is here, and the S&P 500 contract’s Wednesday outlook covers the index that rose 0.58 percent in cash on Wednesday. Outlooks for ES, NQ, GC and CL are collected on the market outlook page, and our forward trading record is on the performance statement.