At the Wednesday 6:00 PM ET reopen the December Nasdaq-100 contract opened at 29,984.00, 23.00 points beneath Wednesday's settle. The day's low was 29,033.00. It ran 757.00 points beneath the long band we published for Thursday and 657.00 points beneath that card's stop. The high of 29,993.25 stopped 56.75 points short of the card's second target. A lower high and a lower low.
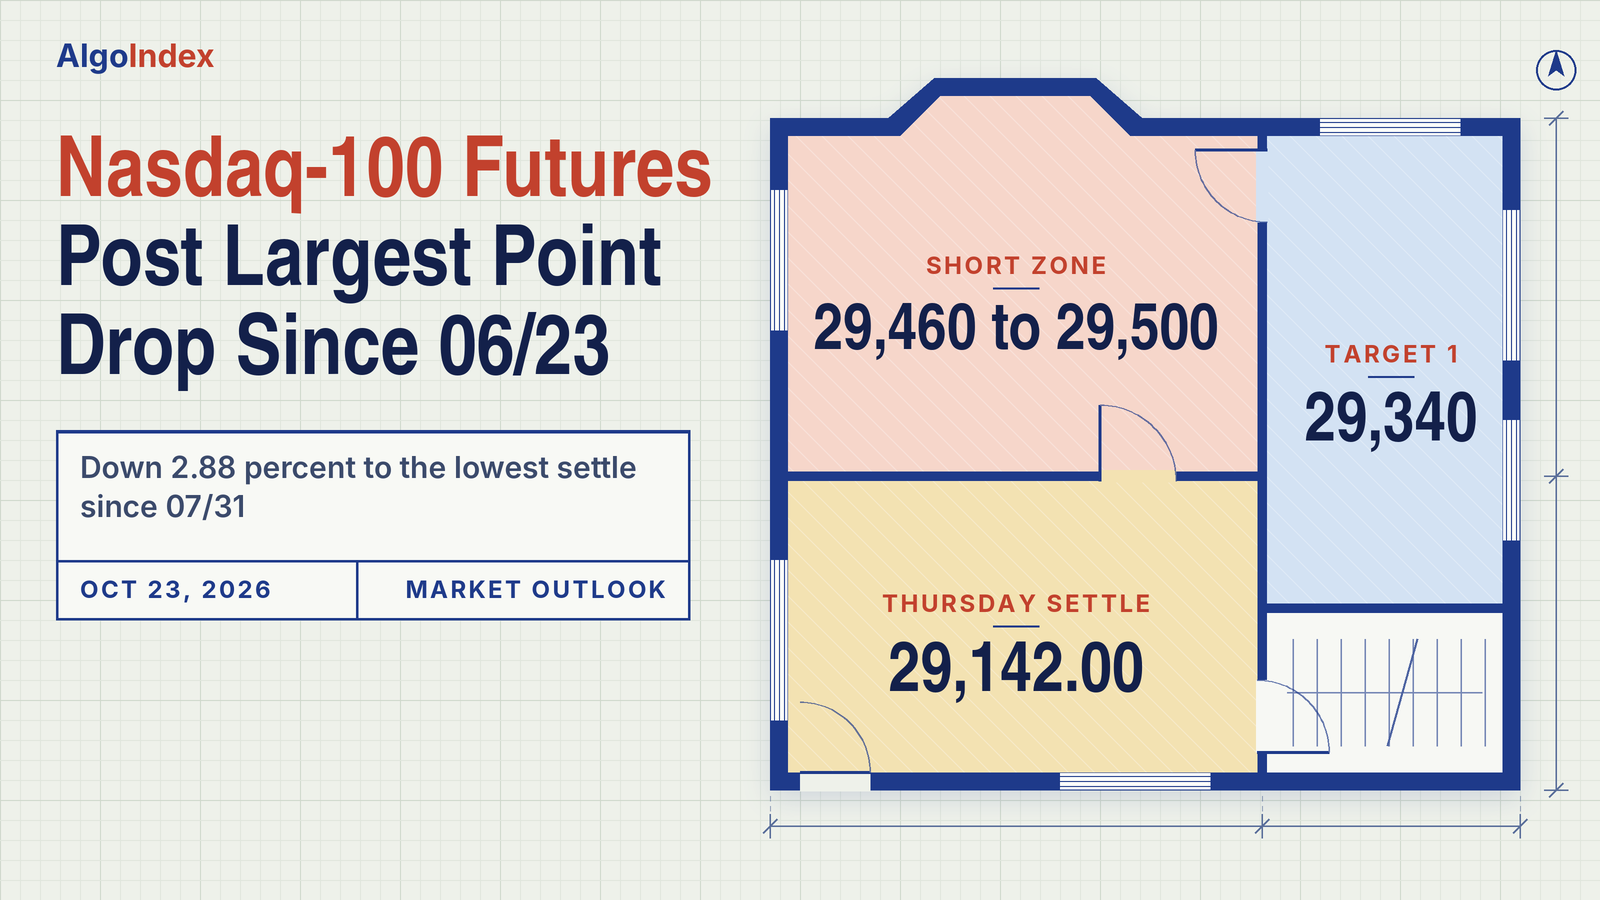
The contract settled at 29,142.00, down 865.00 points, or 2.88 percent, at 11.4 percent of a 960.25 point range. That was the largest one-day point decline since the 999.00 of 06/23 and the lowest settle since the 28,688.50 of 07/31. The Nasdaq-100 cash index fell 2.90 percent and the semiconductor index 6.72 percent. The Dow industrials and the NYSE composite closed slightly higher. The reopened Globex session quoted 29,124.75 at about 6:30 PM ET, 17.25 points beneath the settle.
December Nasdaq-100 futures settled at 29,142.00, down 865.00 points, with a lower high and a lower low on a 960.25 point range. Thursday's published long band at 29,790 to 29,830 traded, and so did the 29,690 stop, the low running 657.00 points beneath it; the daily bar cannot show the order of the prints. The settle sits beneath every settlement average from the 5-day to the 100-day and above the 200-day. The primary setup for Friday is a short from 29,460 to 29,500, around one standard deviation resistance at 29,473.21, stop 29,620, targets 29,340, 29,200 and an extended 29,060. The band and the first two targets sit above the settle. The US flash purchasing managers' surveys are listed at 9:45 AM ET, per the news-feed calendar and unconfirmed.
Thursday's long band at 29,790 to 29,830 traded, and so did the 29,690 stop
In Thursday’s outlook we set a long from 29,790 to 29,830, stop 29,690. Its targets sat at 29,930, 30,050 and an extended 30,170. Thursday's bar, from the review and the provider's 2026-10-22 settlement row, opened at 29,984.00 at the Wednesday 6:00 PM ET reopen, marked a high of 29,993.25 and a low of 29,033.00, and settled at 29,142.00. The band traded. So did the stop. The low ran 757.00 points beneath the band's 29,790 bottom and 657.00 beneath the 29,690 stop. The settle finished 548.00 points beneath the stop.
The open sat 154.00 points above the band and 54.00 above the first target. The 29,930 first target lies inside the day's range. The other two did not print. The high stopped 56.75 points short of 30,050. No intraday series was preserved for Thursday, so the daily bar cannot show whether 29,930 traded after the band did, or when the stop traded. No order is asserted here. No fill and no result are asserted either.
The card's other lines broke too. Its invalidation needed a settle beneath one standard deviation support at 29,711.73. The settle finished 569.73 points beneath it. Its acceptance test needed two consecutive 30-minute closes beneath 29,790. Without a 30-minute series that test cannot be checked, though the settle sits 648.00 points beneath 29,790.
Its macro override named a risk-off move on a confirmed Gulf escalation, or a reversal of the after-hours earnings reaction in the largest technology names. The evening positioning note said the Nasdaq fell 3 percent, led by megacap shares and semiconductors. The news feed carried Houthi claims of attacks on Saudi targets, statements carried by the news feed rather than confirmed events. The review ties the decline to no single headline. Both of the override's references traded. The low sat 530.67 points beneath Pivot S2 at 29,563.67 and 462.58 beneath three standard deviations support at 29,495.58.
Our ranges are scored against the whole day's extremes, which is all the daily bar allows. All three analyst-judgment scenario ranges broke lower. The low-range case of 29,700 to 30,170 broke by 667.00 points, the most likely case of 29,560 to 30,330 by 527.00 and the high-range case of 29,485 to 30,530 by 452.00. The high stayed inside all three. The session bands fared the same. The night band of 29,700 to 30,100, London's 29,650 to 30,150, the morning band of 29,560 to 30,330 and the afternoon band of 29,500 to 30,420 each contained the high but not the low. The bar cannot place the extremes in any one session.
The most probable path, an analyst judgment, kept the contract between Pivot S2 at 29,563.67 and Pivot R2 at 30,334.67. It did not hold. The low broke the lower line by 530.67 points, while the high stayed 341.42 beneath the upper. The weighted case was a dip toward the band that holds above 29,711.73. The low and the settle both finished beneath that line. The alternative named a break beneath Pivot S2 toward three standard deviations support at 29,495.58. Its levels printed.
A 183.31 point basis, a crowded zone near 29,033.00 and a first lid at 29,389.42
The basis narrowed to 183.31 points, the 29,142.00 settle less the 28,958.69 cash close, from 184.48 on Wednesday. The review converts four positioning levels at it. The modeled gamma-flip level at NDX 29,523 becomes 29,706.31, the modeled volatility threshold at NDX 29,590 becomes 29,773.31, the NDX 29,000 key strike 29,183.31 and the put side support base at NDX 28,000 28,183.31. The conversions are the review's own. The settle sits beneath all of them except the put side equivalent.
Resistance starts 41.31 points up, at the 29,183.31 key-strike equivalent. The Pivot Point follows at 29,389.42, 247.42 points up. Then come one standard deviation resistance at 29,473.21, the 50 percent retracement of the 13-week range at 29,549.25 and the 5-day average near 29,588. A tight band follows. Two standard deviations resistance at 29,610.40, the one-ATR line at 29,696.19, the 29,706.31 flip equivalent, three standard deviations resistance at 29,715.67 and Pivot R1 at 29,745.83 sit within 135.43 points. The 29,773.31 threshold equivalent and the 9-day crossing price at 29,882.03 come next.
Above them sits Thursday's own start. The 29,984.00 open, the 29,993.25 high, the 9-day average near 29,995, the 100-day near 30,001, Wednesday's 30,007.00 settle and the 38.2 percent retracement from the four-week low at 30,019.90 sit within 35.90 points. Wednesday's 30,113.00 high, the 50-day near 30,149, the 40-day crossing price at 30,221.51 and Pivot R2 at 30,349.67 follow. The 18-day crossing price at 30,515.12, the 20-day near 30,541 and Pivot R3 at 30,706.08 form the extended band. The 31,616.50 one-month, 13-week and 52-week high caps the list, 2,474.50 points up.
Support starts 80.62 points down, at the 38.2 percent retracement from the 13-week low at 29,061.38. The published target price at 29,057.14 and Thursday's 29,033.00 low, now the one-month low, sit within 28.38 points of it. That is the crowded zone. Beneath it, one standard deviation support at 28,810.79 and Pivot S1 at 28,785.58 sit 25.21 points apart. The 07/31 settle of 28,688.50 and two standard deviations support at 28,673.60 follow. Then come the 08/03 low of 28,599.50, the one-ATR line at 28,587.81 and three standard deviations support at 28,568.33. The 61.8 percent retracement from the 52-week low at 28,488.88 and Pivot S2 at 28,429.17 form the deeper band. The 200-day average near 28,365, the 28,183.31 put side equivalent, Pivot S3 at 27,825.33, the 27,482.00 13-week low and the 23,429.00 52-week low lie far below.
Only one average sits beneath the settle. The settle sits about 446 points beneath the 5-day near 29,588, about 853 beneath the 9-day near 29,995, about 859 beneath the 100-day near 30,001, about 1,007 beneath the 50-day near 30,149 and about 1,399 beneath the 20-day near 30,541. It sits about 777 above the 200-day near 28,365. The averages are the review's, computed from the daily settlements and stated to whole points. The 5-day fell about 200 points as the 10/15 settle of 30,143.75 left the window. The 20-day fell about 81 as the 09/24 settle of 30,766.75 dropped out, and the 50-day about 20. Older settlements sit lower. The 30 older ones in the 50-day window averaged near 29,887, the 50 older ones in the 100-day window near 29,853 and the 100 older ones in the 200-day window near 26,729. Friday's crossing prices are 29,882.03 for the 9-day, 30,515.12 for the 18-day and 30,221.51 for the 40-day.
Momentum sits near the bottom. Relative strength reads 30.46 on the 9-day, 35.85 on the 14-day and 40.12 on the 20-day. The raw stochastics read 4.83 percent on the 9-day and 4.22 percent on the 14-day. The 14-day %K at 18.56 percent sits 0.63 points beneath %D at 19.19 percent. Sellers lead on both windows. On the 9-day, negative direction at 35.01 tops positive at 9.34 by 25.67, with the ADX at 38.69; on the 14-day, 31.57 tops 12.31 by 19.26, with the ADX at 24.39. Historic volatility reads 21.20 percent and 19.82 percent. These readings are as published, read at about 6:30 PM ET after the 6:00 PM ET reopen. They may include the first minutes of the Friday session.
A composite multi-indicator read published for Friday sits at 40 percent sell, against 32 percent sell in the prior session's snapshot, with strength described as average and direction as strengthening. A week ago it read 8 percent sell. A month ago, 72 percent buy. The short-horizon group averages 60 percent sell, the medium 25 percent sell and the long hold, and the trend indicator reads sell.
Most of the bar is body. It measures 842.00 points lower from the 29,984.00 open, with an upper shadow of 9.25 points above the open and a lower shadow of 109.00 points beneath the settle. The 14-day average true range stands at 554.19 points and the 14-day average daily range at 557.50; the 9-day figures are 592.11 and 635.42 and the 20-day figures 536.10 and 529.06. One average true range either side of the settle spans 28,587.81 to 29,696.19. The deviation bands, built from five settlements, run 28,810.79 to 29,473.21, 28,673.60 to 29,610.40 and 28,568.33 to 29,715.67. They describe settlement dispersion only. The range was the widest since the 1,132.50 of 08/04, and the low the lowest since the 28,599.50 of 08/03. Ten sessions of daily ranges read 313.50, 445.00, 314.75, 813.50, 574.25, 956.25, 757.50, 511.75, 385.50 and 960.25 points. The session highs since 10/15 read 30,196.75, 30,225.00, 29,983.50, 29,903.50, 30,113.00 and 29,993.25, and the lows 29,622.50, 29,268.75, 29,226.00, 29,391.75, 29,727.50 and 29,033.00. No prior-quarter extremes were captured, so the 13-week extremes stand in.
A 2.90 percent Nasdaq-100 drop, a 6.72 percent chip slide and a flat Dow
Technology fell alone. The Nasdaq-100 cash index fell 2.90 percent, or 863.83 points, to 28,958.69. The semiconductor index fell 6.72 percent, or 773.58 points, to 10,731.98, and the S&P 500 cash index 1.21 percent to 7,663.43. The Dow industrials closed at 52,867.98, up 0.02 percent, and the NYSE composite at 24,275.53, up 0.09 percent. In the review's interpretation that pattern describes rotation out of artificial-intelligence-linked shares rather than a broad liquidation; no sector flow data was captured to measure it.
The social-media group reported after Wednesday's close. On Thursday the news feed carried items that its future spending commitments had risen to 825 billion dollars and that a gauge of its credit risk had reached a fresh high on its artificial-intelligence spending plans. The feed's European market wrap described stocks falling globally as disappointing technology earnings fuelled doubts over whether heavy artificial-intelligence investment can deliver sufficient returns. Its US wrap described heavy losses among major technology companies alongside escalating conflict in the Middle East. Those descriptions are the feed's.
After the close the news feed carried talks on additional computing capacity for a leading artificial-intelligence developer at 4:20 PM ET. At 4:12 PM ET it carried a press report that a space company's lower-rated debt would price at about 8.3 percent. The captured news feed carried no mega-cap result released after Thursday's close.
The reopened session quoted beneath the settle. The provider's latest quote at about 6:30 PM ET was 29,124.75 and the chart showed 29,122.75 at about 6:33 PM ET, both quotes rather than settlements. The overview's Friday-session open, high and low read 29,116.50, 29,149.25 and 29,090.00. They are not Thursday's range.
Yields fell. The ten-year yield index closed at 4.95 percent against 5.14 percent and the thirty-year at 5.29 percent against 5.43 percent. Lower yields would ordinarily favour long-duration technology shares; on Thursday the index fell regardless. Weekly jobless claims printed at 194,000 against a 200,000 forecast at 8:30 AM ET, per the news-feed calendar and unconfirmed. The 5-year inflation-protected Treasury auction at 1:00 PM ET drew a high yield of 2.367 percent, per the news-feed calendar and unconfirmed. The news feed carried an item that traders no longer fully price a Fed rate increase before year-end. The next policy statement is scheduled for 2:00 PM ET on October 28, 2026, as the calendar lists it.
The Gulf stayed in the headlines. At 3:09 AM ET the news feed carried a warning from Iran's Revolutionary Guards navy of confrontation against US regional bases. From 8:01 AM ET to 8:02 AM ET it carried Houthi claims of attacks on Saudi targets. The claimed targets included the Defence Ministry in Riyadh and the state oil company's facility at Yanbu. At 4:43 PM ET, after the close, the news feed carried the President's invocation of the Defense Production Act for petroleum capacity. These are statements carried by the news feed rather than confirmed events. No causal link to the index is asserted.
Volatility rose. The Nasdaq volatility index closed at 28.72 against 24.42, the volatility index at 19.03 against 16.68 and the volatility-of-volatility index at 107.94 against 94.55. December Brent rose 4.0 percent to 113.17 on Gulf headlines, as the review puts it. December gold fell 2.16 percent and the dollar index eased to 101.61. These items coincided with the session, and with no intraday series preserved, no move in the index is attributed to any one of them.
The cash close sits beneath three positioning lines. The evening positioning note used is the 5:22 PM ET edition for Thursday, read at 8:58 PM ET. Its reference prices are the prior session's closes: NDX 29,822 equals Wednesday's 29,822.52 cash close, and QQQ 725 matches the fund's Wednesday close of 725.21. Against Thursday's 28,958.69 close, the index sits 564.31 points beneath the 29,523 modeled gamma-flip level, 631.31 beneath the 29,590 modeled volatility threshold and 716.31 beneath the 29,675 call side ceiling. It sits 958.69 above the put side support base at 28,000. The largest gamma concentration sits at NDX 30,000. The index model's gamma tilt reads 1.078 and its gamma notional plus 1.999 million dollars, both model outputs. The note lists 30,000, 29,675, 29,000 and 31,000 as key index strikes.
On the QQQ proxy the call side ceiling sits at 731, the modeled gamma-flip level at 729, the modeled volatility threshold at 725, the largest gamma concentration at 720 and the put side support base at 700. Those are proxy levels. The fund's gamma tilt reads 0.760 and its gamma notional minus 518.953 million dollars, proxy model outputs. The note's key fund strikes are 720, 700, 730 and 740. The console, read at about 9:00 PM ET with a page date of 2026-10-22, shows call gamma of minus 1.87 billion against put gamma of minus 2.46 billion. One-month implied volatility reads 21.39 percent against realised volatility of 15.58 percent. The implied-volatility rank reads 44.49 percent, the skew rank 57.60 percent and the put-to-call open-interest ratio 1.44.
The note's commentary said a block of fund puts expiring October 30 at the 700 strike, highlighted the prior Friday, had gained 193 percent. It also said the fund's implied volatility term structure shifted into backwardation and higher than the prior session. In the review's interpretation, drawn from the index model and the QQQ fund proxy, an index close beneath the flip level and the threshold, with fund gamma notional negative, describes an environment where dealer hedging is more likely to amplify than to dampen moves. That is a damping read. It carries no direction. The modeled threshold and flip level are model outputs, not option strikes, and no directional read is drawn from options volume or modeled gamma.
Activity rose. Volume reached 822,661 contracts against Wednesday's 666,845, a figure revised from the 654,208 carried in Thursday's outlook, so the decline came on higher volume. Open interest reads 270,896 on Wednesday's 2026-10-21 row, which Thursday's outlook listed as not yet reported, down 564 from 271,460 on the 2026-10-20 row. Thursday's figure is not yet reported. No weekly positioning report was captured, so no change in speculative length is asserted.
The trade map for Friday
The primary setup is a short from 29,460 to 29,500. Thursday printed a lower high and a lower low, and the settle sits beneath every settlement average from the 5-day to the 100-day. Negative direction leads on both directional systems. The composite reads 40 percent sell with direction described as strengthening. The band sits around one standard deviation resistance at 29,473.21 and above the Pivot Point at 29,389.42. Then the stop. The stop at 29,620 sits 9.60 points above two standard deviations resistance at 29,610.40 and 95.67 beneath three standard deviations resistance at 29,715.67. It also sits 86.31 beneath the 29,706.31 flip equivalent. All of the band sits above the settle, 318.00 to 358.00 points up. The thesis, an analyst judgment, is that rallies are sold while technology leadership is under pressure.
The first target sits at 29,340, 49.42 beneath the Pivot Point and still 198.00 above the settle. The second, 29,200, sits 58.00 above the settle and 16.69 above the 29,183.31 key-strike equivalent. Then the extended third. At 29,060 it sits 1.38 beneath the 29,061.38 retracement, 2.86 above the 29,057.14 target price and 82.00 beneath the settle. The 14-day raw stochastic at 4.22 percent sits near the bottom of its range and leaves room for a sharp rebound. So the review calls the setup an analyst judgment with no measured edge behind it.
Now the arithmetic. From the 29,480 midpoint the risk to the stop is 140 points, 25.3 percent of the 14-day average true range of 554.19. The targets sit 140, 280 and 420 points beneath the midpoint. Exact multiples. The first target, 29,340, sits 120.00 points beneath the band bottom and 198.00 above the settle. The second sits 58.00 above the settle. The third sits 82.00 beneath it.
The scenario ranges are analyst judgment. The low-range case runs 28,800 to 29,470, the most likely 28,670 to 29,610 and the high-range case 28,430 to 29,750. Then the sessions. The review expects roughly 28,800 to 29,470 through the night session, with a bias lower beneath the Pivot Point at 29,389.42. The reopened session's 29,124.75 and 29,122.75 quotes sit inside that band, 324.75 and 322.75 points above its bottom. London follows at 28,780 to 29,480, with a bias lower. There, one standard deviation support at 28,810.79 and Pivot S1 at 28,785.58 are the first meaningful supports beneath the 29,033.00 low. The morning band runs 28,670 to 29,610, between two standard deviations support at 28,673.60 and two standard deviations resistance at 29,610.40. The afternoon band runs 28,570 to 29,720. A Friday close carries weekend headline exposure, which in the review's judgment can keep positioning light into the close.
Friday's calendar starts Thursday evening. Japan's consumer prices are listed at 7:30 PM ET and Japan's flash purchasing managers' surveys at 8:30 PM ET, per the news-feed calendar and unconfirmed. Europe follows. The French, German, euro-area and UK flash surveys are listed between 3:15 AM ET and 4:30 AM ET, per the news-feed calendar and unconfirmed. Canadian retail sales are listed at 8:30 AM ET, per the news-feed calendar and unconfirmed. Then the open. The US flash purchasing managers' surveys are listed at 9:45 AM ET, with a composite forecast of 57.4 against 58.4 previously, per the news-feed calendar and unconfirmed. The final University of Michigan sentiment survey is listed at 10:00 AM ET, per the news-feed calendar and unconfirmed. The captured calendars list no scheduled US release between noon and the 4:00 PM ET cash close. A rating decision on France is listed as tentative at 4:00 PM ET, per the news-feed calendar and unconfirmed. The scheduled calendar lists no Friday entry. The market then closes for the weekend, and Globex reopens at 6:00 PM ET on Sunday.
One path is weighted. In the review's analyst judgment the most probable path holds the contract between Pivot S2 at 28,429.17 and Pivot R1 at 29,745.83. Within it, a rebound toward the 29,460 to 29,500 band that fails beneath two standard deviations resistance at 29,610.40 is weighted slightly above a recovery. No measured frequency backs it. The alternative is a reversal of Thursday's technology selling that carries the contract above Pivot R1 toward Thursday's 29,993.25 high. The 14-day raw stochastic sits at 4.22 percent, the settle sits about 777 points above the 200-day average and the broad market held near flat. So a rebound before any extension is a live alternative. In the review's judgment the first-order influence for NQ on Friday is whether Thursday's technology selling extends, with the 9:45 AM ET US flash purchasing managers' surveys, listed by the news-feed calendar and unconfirmed, the main scheduled release.
Thursday's 29,033.00 low, the bottom of the widest range since 08/04, now sits 427.00 points under Friday's short band.
The complete data picture
Every number behind Friday’s plan, charted first, then the full level lists, then the complete numeric reference underneath.
Full numeric reference, every remaining figure from the session review
1. Executive Summary
The December Nasdaq-100 contract settled at 29,142.00 on Thursday, down 865.00 or 2.88 percent from Wednesday's settle of 30,007.00, after trading between 29,993.25 and 29,033.00, a 960.25 point daily range. The settle finished at 11.4 percent of the range, and the 960.25 point range was 1.72 times the published 14-day average daily range of 557.50 points. Thursday printed a lower high and a lower low against Wednesday. The 865.00 point decline was the largest one-day point decline since the 999.00 point decline of 06/23, the range was the widest since the 1,132.50 point range of 08/04, the settle was the lowest since the 28,688.50 settle of 07/31, and the low was the lowest since the 28,599.50 low of 08/03.
The Nasdaq-100 cash index closed at 28,958.69, down 863.83 or 2.90 percent, and the semiconductor index fell 6.72 percent to 10,731.98, while the Dow industrials closed up 0.02 percent and the NYSE composite up 0.09 percent, so the decline was concentrated in technology. The news feed carried items on the social-media group's future spending commitments rising to 825 billion dollars and on its credit risk gauge reaching a fresh high on artificial-intelligence spending plans, following Wednesday's after-close results, and its market wraps described stocks falling on doubts over whether heavy artificial-intelligence investment can deliver sufficient returns while Middle East tensions escalated.
The ten-year yield index fell to 4.95 percent from 5.14 percent and the dollar index eased to 101.61. The Nasdaq volatility index rose to 28.72 from 24.42 and the S&P 500 volatility index to 19.03 from 16.68. Brent's December contract rose 4.0 percent to 113.17 on Gulf headlines. These items coincided with the session; no intraday series was preserved, so no move is attributed to any one of them.
The settle sits beneath every settlement average from the 5-day to the 100-day and above the 200-day, negative direction leads on both directional systems, and the composite multi-indicator read is 40 percent sell with direction described as strengthening. The published 14-day average true range is 554.19 points. The index cash close sits 564.31 points beneath the modeled gamma-flip level at NDX 29,523, per the evening positioning note, a model output read as a damping lens with no direction. The Primary Setup below is a short from the 29,460 to 29,500 band around one standard deviation resistance at 29,473.21, stopped at 29,620 above two standard deviations resistance at 29,610.40, with objectives at 29,340, 29,200 and an extended 29,060.
2. Price Action & Technical Structure
2.1 Intraday and Session Review
The Thursday session opened at 29,984.00 at the Wednesday 6:00 PM ET reopen, 23.00 points beneath Wednesday's settle, marked a daily high of 29,993.25 and a daily low of 29,033.00, and settled at 29,142.00. No intraday series was preserved for this session, so this review does not describe the order in which the high and the low printed, and no timed price path is asserted; the daily bar alone fixes the open, the extremes and the settle.
This review records only that the 29,993.25 high and the 29,033.00 low both belong to Thursday's completed session and that the settle sits 109.00 points above the low and 851.25 points beneath the high.
Globex reopened at 6:00 PM ET on Thursday for the Friday session, so the open, high and low shown on the provider's overview, 29,116.50, 29,149.25 and 29,090.00, belong to the new Friday session and are not Thursday's range. The provider's latest quote at about 6:30 PM ET was 29,124.75, 17.25 points beneath the settle, and the chart showed 29,122.75 at about 6:33 PM ET; these are reopened-session quotes, not settlements.
Thursday's completed-session extremes are taken from the settlement row, and they are also the completed-session inputs behind the published pivot ladder rather than an independently read bar. Pivot R3 at 30,706.08 minus Pivot S3 at 27,825.33, divided by three, returns 960.25, and Pivot R2 at 30,349.67 minus Pivot S2 at 28,429.17, divided by two, returns the same 960.25. Three times the Pivot Point of 29,389.42 less the 29,142.00 settle gives a high plus low sum of 59,026.26, which the pair of 29,993.25 and 29,033.00 reproduces to the published rounding at 59,026.25, and that pair reproduces all seven published rungs.
The provider's settlement row and the chart's completed daily bar carry the same 29,984.00 open, 29,993.25 high, 29,033.00 low and 29,142.00 settle, and the provider's one-month low reads 29,033.00, equal to Thursday's low.
2.2 Daily Structure
Thursday printed a lower high and a lower low: the 29,993.25 high sits 119.75 points beneath Wednesday's 30,113.00, and the 29,033.00 low sits 694.50 points beneath Wednesday's 29,727.50. The settle beneath the 29,984.00 open leaves a body of 842.00 points, an upper shadow of 9.25 points above the open and a lower shadow of 109.00 points beneath the settle.
Settlements over the last ten sessions ran 31,108.75, 30,898.25, 30,791.50, 30,182.75, 30,143.75, 29,391.50, 29,722.50, 29,675.25 and 30,007.00 before Thursday's 29,142.00, so Thursday's settle was the lowest since the 28,688.50 settle of 07/31. The sequence of session highs over the last six sessions reads 30,196.75, 30,225.00, 29,983.50, 29,903.50, 30,113.00 and 29,993.25, and the sequence of session lows reads 29,622.50, 29,268.75, 29,226.00, 29,391.75, 29,727.50 and 29,033.00.
The one-month high, 13-week high and 52-week high all sit at 31,616.50, and the one-month low now sits at Thursday's 29,033.00. The 13-week low of 27,482.00 and the 52-week low of 23,429.00 frame the lower side. No prior-quarter high or low was captured, so the 13-week extremes serve as the available quarterly reference.
2.3 4-Hour and Swing Structure
Daily ranges for the last ten sessions ran 313.50, 445.00, 314.75, 813.50, 574.25, 956.25, 757.50, 511.75, 385.50 and 960.25. The settlement changes over the same ten sessions read plus 139.25, minus 210.50, minus 106.75, minus 608.75, minus 39.00, minus 752.25, plus 331.00, minus 47.25, plus 331.75 and minus 865.00.
The retracement grid published for Friday places the 38.2 percent retracement from the 13-week low at 29,061.38, 80.62 points beneath the settle, and the 50 percent retracement of the 13-week range at 29,549.25 above it. Further beneath, the 61.8 percent retracement from the 52-week low sits at 28,488.88, and above, the 38.2 percent retracement from the four-week low sits at 30,019.90. No four-hour series was captured, so swing structure here rests on daily bars only.
2.4 Moving Averages
The averages cited in this subsection were computed from the provider's daily settlement series for the December contract, which holds 259 completed sessions through Thursday; the partial Friday row returned after the 6:00 PM ET reopen was dropped before counting. To whole points, the 5-day average stands at about 29,588, the 9-day at about 29,995, the 20-day at about 30,541, the 50-day at about 30,149, the 100-day at about 30,001 and the 200-day at about 28,365.
The 29,142.00 settle sits about 446 points beneath the 5-day average, about 853 points beneath the 9-day, about 1,399 points beneath the 20-day, about 1,007 points beneath the 50-day and about 859 points beneath the 100-day, and about 777 points above the 200-day. The 5-day average fell about 200 points, because the 10/15 settle of 30,143.75 left the window and was replaced by 29,142.00. The 20-day fell about 81 points, because the 09/24 settle of 30,766.75 left that window, and the 50-day fell about 20 points.
The 20-day average sits above the 50-day because the last 20 settlements averaged more than the full 50, which means the 30 older settlements in the 50-day window averaged lower, at about 29,887. The 50-day sits above the 100-day because the 50 older settlements in the 100-day window averaged lower, at about 29,853, and the 100-day sits above the 200-day because the 100 older settlements in the 200-day window averaged lower, at about 26,729. The projection grid gives the prices at which each average would be crossed on Friday: 29,882.03 for the 9-day, 30,515.12 for the 18-day and 30,221.51 for the 40-day.
2.5 Oscillator and Trend Readings
The oscillator figures below are as published on the provider's technical page, read at about 6:30 PM ET after the 6:00 PM ET reopen, so they may include the first minutes of the Friday session rather than the settle alone; they are the provider's published readings and were not computed here. The 9-day relative strength reads 30.46, the 14-day relative strength 35.85 and the 20-day relative strength 40.12.
The 9-day raw stochastic reads 4.83 percent and the 14-day raw stochastic 4.22 percent, while the 14-day stochastic %K reads 18.56 percent and the 14-day stochastic %D 19.19 percent, so %K sits just beneath %D near the bottom of the range.
The 9-day directional index ADX reads 38.69 with the 9-day +DI at 9.34 and the 9-day -DI at 35.01; the 14-day directional index ADX reads 24.39 with the 14-day +DI at 12.31 and the 14-day -DI at 31.57, so negative direction leads on both and the 9-day ADX reads above the 14-day. The 9-day historic volatility reads 21.20 percent and the 14-day historic volatility 19.82 percent.
The composite multi-indicator read published for the Friday session is 40 percent sell, against 32 percent sell in the prior session's snapshot, with signal strength described as average and direction as strengthening. The snapshot history reads 8 percent sell a week ago and 72 percent buy a month ago. The short-horizon group averages 60 percent sell, the medium-horizon group 25 percent sell and the long-horizon group hold, and the composite trend indicator reads sell.
2.6 Volatility and Expected Range
The published 14-day average true range stands at 554.19 points and the 14-day average daily range at 557.50 points; the 9-day average true range is 592.11 with a 9-day average daily range of 635.42, and the 20-day average true range is 536.10 with a 20-day average daily range of 529.06. Thursday's 960.25 point range was 1.72 times the 14-day average daily range.
Adding and subtracting the 14-day average true range of 554.19 points from the 29,142.00 settle frames Friday between 28,587.81 and 29,696.19. The published standard-deviation bands are built from five settlements: one deviation spans 28,810.79 to 29,473.21, two spans 28,673.60 to 29,610.40 and three spans 28,568.33 to 29,715.67. These bands describe settlement dispersion, not intraday reach, and a headline gap can open outside any of them.
3. Key Levels
3.1 Resistance
Above the 29,142.00 settle, the first listed overhead reference is the Pivot Point at 29,389.42, followed by one standard deviation resistance at 29,473.21 and the 50 percent retracement of the 13-week range at 29,549.25. Two standard deviations resistance at 29,610.40, three standard deviations resistance at 29,715.67 and Pivot R1 at 29,745.83 come next, then the 9-day average crossing price at 29,882.03, Thursday's 29,993.25 high and Wednesday's 30,007.00 settle. Wednesday's 30,113.00 high precedes Pivot R2 at 30,349.67, with Pivot R3 at 30,706.08 the extended reference.
3.2 Support
Beneath the settle sits the 38.2 percent retracement from the 13-week low at 29,061.38, then the published target price at 29,057.14 and Thursday's 29,033.00 low, which is also the one-month low. One standard deviation support at 28,810.79 and Pivot S1 at 28,785.58 form the next band, with the 07/31 settle of 28,688.50 and two standard deviations support at 28,673.60 beneath. Three standard deviations support at 28,568.33, the 61.8 percent retracement from the 52-week low at 28,488.88 and Pivot S2 at 28,429.17 form the deeper band, with Pivot S3 at 27,825.33 the extended reference.
4. Macro Drivers
4.1 Mag7 Earnings and AI Capex Cycle
The social-media group reported after Wednesday's close, and on Thursday the news feed carried items that its future spending commitments had risen to 825 billion dollars and that a gauge of its credit risk had reached a fresh high on its artificial-intelligence spending plans. The news feed's European market wrap described stocks falling globally as disappointing technology earnings fuelled doubts over whether heavy artificial-intelligence investment can deliver sufficient returns, and its US wrap described heavy losses among major technology companies alongside escalating conflict in the Middle East.
Other items carried by the news feed included talks on additional computing capacity for a leading artificial-intelligence developer at 4:20 PM ET, after the close, and a press report at 4:12 PM ET that a space company's lower-rated debt would price at about 8.3 percent. The captured news feed carried no mega-cap result released after Thursday's close.
4.2 Semiconductor Cycle and Tech Sector Rotation
The semiconductor index fell 773.58 points or 6.72 percent to 10,731.98, against a 2.90 percent decline in the Nasdaq-100 cash index. The Dow industrials closed at 52,867.98, up 0.02 percent, and the NYSE composite at 24,275.53, up 0.09 percent, so the broad market held near flat while technology and semiconductors fell. In this review's interpretation that pattern describes rotation out of artificial-intelligence-linked shares rather than a broad liquidation; no sector flow data was captured to measure it.
4.3 Fed Policy and Real Yields (Duration Sensitivity)
The ten-year yield index fell to 4.95 percent from 5.14 percent and the thirty-year to 5.29 percent from 5.43 percent. Weekly jobless claims printed at 194,000 against a 200,000 forecast at 8:30 AM ET, per the news-feed calendar and unconfirmed against the scheduled calendar, and the 5-year inflation-protected Treasury auction at 1:00 PM ET drew a high yield of 2.367 percent, per the news-feed calendar and unconfirmed against the scheduled calendar. The news feed carried an item that traders no longer fully price a Fed rate increase before year-end. Lower yields would ordinarily favour long-duration technology shares; on Thursday the index fell regardless.
4.4 Geopolitical Backdrop
The news feed carried at 8:01 AM ET to 8:02 AM ET Houthi claims of attacks on Saudi targets, including the Defence Ministry in Riyadh and the state oil company's facility at Yanbu, after a 3:09 AM ET warning from Iran's Revolutionary Guards navy of confrontation against US regional bases. At 4:43 PM ET, after the close, the news feed carried the President's invocation of the Defense Production Act for petroleum capacity. These are statements carried by the news feed rather than confirmed events.
4.5 Cross-Asset and Volatility
The Nasdaq volatility index closed at 28.72 against 24.42, the S&P 500 volatility index at 19.03 against 16.68 and the volatility-of-volatility index at 107.94 against 94.55. The S&P 500 cash index fell 1.21 percent to 7,663.43. Brent's December contract rose 4.0 percent to 113.17, gold's December contract fell 2.16 percent and the dollar index eased to 101.61.
The measured basis between the December contract's 29,142.00 settle and the 28,958.69 cash close is 183.31 points, against 184.48 on Wednesday, both measured from the same provider daily record.
4.6 Institutional Positioning
No weekly positioning report was captured, so no change in speculative length is asserted. Open interest on the December contract is shown at 270,896 for Wednesday, on the 2026-10-21 row of the provider's record, a figure Thursday's outlook listed as not yet reported, and Thursday's open interest is not yet reported; Thursday's December volume was 822,661 contracts against 666,845 on Wednesday, the 2026-10-21 row, revised from the 654,208 carried in Thursday's outlook, so the decline came on higher volume.
5. QQQ Options Flow Context (Proxy)
This review uses the QQQ fund and the evening positioning note's index columns as the proxy for the positioning data available. The positioning note is the 5:22 PM ET edition for Thursday, read at 8:58 PM ET. Its reference prices are the prior session's closes: NDX 29,822 equals Wednesday's 29,822.52 cash close and QQQ 725 matches the fund's Wednesday close of 725.21 shown on the console.
On the index the modeled volatility threshold sits at NDX 29,590, the call side ceiling at NDX 29,675, the largest gamma concentration at NDX 30,000, the modeled gamma-flip level at NDX 29,523 and the put side support base at NDX 28,000. Against Thursday's 28,958.69 cash close, the close sits 564.31 points beneath the flip level, 631.31 points beneath the threshold, 716.31 points beneath the call side ceiling and 958.69 points above the put side base. Index gamma tilt reads 1.078 and gamma notional plus 1.999 million dollars, both model outputs, and the key index strikes are NDX 30,000, 29,675, 29,000 and 31,000.
On the fund the modeled volatility threshold sits at 725, the call side ceiling at 731, the largest gamma concentration at 720, the modeled gamma-flip level at 729 and the put side support base at 700. Fund gamma tilt reads 0.760 and gamma notional minus 518.953 million dollars, proxy model outputs, and the key fund strikes are 720, 700, 730 and 740. The modeled threshold and flip level are model outputs, not option strikes.
At the measured 183.31 point basis, this review converts the index flip level to 29,706.31, the threshold to 29,773.31, the 29,000 strike to 29,183.31 and the put side base to 28,183.31 in December futures terms. These conversions are this review's, not the source's.
The QQQ console, read at about 9:00 PM ET with a page date of 2026-10-22, shows call gamma of minus 1.87 billion against put gamma of minus 2.46 billion, one-month implied volatility of 21.39 percent against realised volatility of 15.58 percent, an implied-volatility rank of 44.49 percent, a skew rank of 57.60 percent and a put-to-call open-interest ratio of 1.44. The console's live price field and its high and low volatility point fields are excluded.
The positioning note's commentary said the Nasdaq fell 3 percent, led by megacap shares and semiconductors, that a block of fund puts expiring October 30 at the 700 strike, highlighted the prior Friday, had gained 193 percent, and that the fund's implied volatility term structure shifted into backwardation and higher than the prior session. In this review's interpretation, drawn from the index model and the QQQ fund proxy, both model outputs, an index close beneath the flip level and the threshold, with fund gamma notional negative, describes an environment where dealer hedging is more likely to amplify than to dampen moves, a damping read with no direction. The setup in section 8 sells the 29,460 to 29,500 band, beneath the 29,706.31 conversion of the flip level, with the 29,620 stop also beneath that conversion.
6. Forecast
6.1 Night Session (6:00 PM ET Thursday to 3:00 AM ET Friday, Globex and Asia)
Globex reopened at 6:00 PM ET on Thursday and quoted the December contract at 29,124.75 at about 6:30 PM ET, 17.25 points beneath the settle. Japan's consumer prices are listed at 7:30 PM ET and Japan's flash purchasing managers' surveys at 8:30 PM ET, both per the news-feed calendar and unconfirmed. Bias lower beneath the Pivot Point at 29,389.42, expected Globex band roughly 28,800 to 29,470.
6.2 London Session (3:00 AM to 8:00 AM ET Friday)
The euro-area flash purchasing managers' surveys are listed at 4:00 AM ET and the UK flash surveys at 4:30 AM ET, both per the news-feed calendar and unconfirmed. Bias lower, expected band roughly 28,780 to 29,480, with one standard deviation support at 28,810.79 and Pivot S1 at 28,785.58 the first meaningful supports beneath the 29,033.00 low and one standard deviation resistance at 29,473.21 the first meaningful resistance above the 29,389.42 pivot level.
6.3 Morning Session (9:30 AM to 12:00 PM ET Friday, RTH Open)
The US flash purchasing managers' surveys are listed at 9:45 AM ET and the final University of Michigan sentiment survey at 10:00 AM ET, both per the news-feed calendar and unconfirmed. Expected band roughly 28,670 to 29,610, with two standard deviations support at 28,673.60 beneath and two standard deviations resistance at 29,610.40 above.
6.4 Afternoon Session (12:00 PM to 4:00 PM ET Friday)
The captured calendars list no scheduled US release between noon and the 4:00 PM ET cash close. A Friday close carries weekend headline exposure, which in this review's judgment can keep positioning light into the close. Expected band roughly 28,570 to 29,720.
6.5 Night Session Forward (6:00 PM ET Friday)
The market closes for the weekend after Friday's session, and Globex reopens at 6:00 PM ET on Sunday. A rating decision on France is listed as tentative at 4:00 PM ET on Friday, per the news-feed calendar and unconfirmed, and two days of headline exposure separate Friday's close from the Sunday reopen.
6.6 Expected Range (Friday Full Session)
Low-range scenario: 28,800 to 29,470; Mid-range scenario (most likely): 28,670 to 29,610; High-range scenario: 28,430 to 29,750.
6.7 Most Likely Path
In this review's analyst judgment the most probable path holds the contract between Pivot S2 at 28,429.17 and Pivot R1 at 29,745.83, with a rebound toward the 29,460 to 29,500 band that fails beneath two standard deviations resistance at 29,610.40 weighted slightly above a recovery. The settle sits beneath every settlement average from the 5-day to the 100-day, negative direction leads on both directional systems, the composite reads 40 percent sell with direction described as strengthening, and the semiconductor index fell 6.72 percent.
The alternative that would invalidate this reading is a reversal of Thursday's technology selling, which could carry the contract above Pivot R1 at 29,745.83 toward Thursday's 29,993.25 high. The 14-day raw stochastic at 4.22 percent sits near the bottom of its range, the settle sits about 777 points above the 200-day average, and the broad market held near flat, so a rebound before any extension is a live alternative.
7. Friday Economic Calendar
Thursday's releases are complete. Weekly jobless claims printed at 194,000 at 8:30 AM ET, per the news-feed calendar and unconfirmed against the scheduled calendar, the 5-year inflation-protected Treasury auction drew a high yield of 2.367 percent at 1:00 PM ET, per the news-feed calendar and unconfirmed against the scheduled calendar, and Australia's flash composite purchasing managers' index printed at 6:00 PM ET at 47.7 against 51.3 previously, per the news-feed calendar and unconfirmed against the scheduled calendar.
On Thursday evening Japan's consumer prices are listed at 7:30 PM ET, per the news-feed calendar and unconfirmed. On Friday the French, German, euro-area and UK flash purchasing managers' surveys are listed between 3:15 AM ET and 4:30 AM ET, all per the news-feed calendar and unconfirmed. Canadian retail sales are listed at 8:30 AM ET, the US flash purchasing managers' surveys at 9:45 AM ET, with a composite forecast of 57.4 against 58.4 previously, and the final University of Michigan sentiment survey at 10:00 AM ET, all per the news-feed calendar and unconfirmed. The captured calendars carry no mega-cap earnings entry for Friday.
Later in the window, the FOMC statement is scheduled for 2:00 PM ET on Wednesday, October 28, 2026, as the calendar lists it, and the advance estimate of third-quarter GDP and the September personal income and outlays report for 8:30 AM ET on Thursday, October 29, 2026, as the calendar lists it. A search-engine group and a software maker are listed to report on Wednesday, October 28, 2026, as the calendar lists it. The scheduled calendar contains no Friday, October 23, 2026 entry. In this review's judgment the first-order influence for the Nasdaq-100 on Friday is whether Thursday's technology selling extends, with the 9:45 AM ET US flash purchasing managers' surveys listed by the news-feed calendar, unconfirmed, the main scheduled release.
8. Primary Trade Setup
Direction: Short
Rationale: The settle sits beneath every settlement average from the 5-day to the 100-day, negative direction leads on the 9-day and 14-day directional systems, the composite reads 40 percent sell with direction strengthening, and Thursday's decline settled in the lower eighth of a range 1.72 times the 14-day average daily range. A rebound toward one standard deviation resistance at 29,473.21, into the band around it above the Pivot Point at 29,389.42, offers a short with a defined risk point above two standard deviations resistance at 29,610.40. The 14-day raw stochastic near the bottom of its range leaves room for a sharp rebound, so the setup is an analyst judgment that rallies are sold while technology leadership is under pressure, not a measured edge.
Entry Zone: 29,460 to 29,500
Stop Loss: 29,620 (above two standard deviations resistance at 29,610.40 and beneath three standard deviations resistance at 29,715.67)
Target 1 (T1): 29,340 (beneath the Pivot Point at 29,389.42)
Target 2 (T2): 29,200 (above Thursday's 29,142.00 settle)
Target 3 (T3, extended): 29,060 (just beneath the 38.2 percent retracement at 29,061.38 and above the published target price at 29,057.14)
Risk-to-Reward: Approximately 1:1 to T1, 1:2 to T2, 1:3 to T3
Invalidation: A settle above two standard deviations resistance at 29,610.40 negates the thesis. Short of that, the edge is removed by acceptance above the entry band and not by a touch, defined as two consecutive 30-minute closes above 29,500.
Macro override: A broad reversal in technology shares, or a de-escalation in the Gulf that lifts risk appetite, would undercut the short. In that scenario a move through the 29,620 stop invalidates the setup before the targets, and three standard deviations resistance at 29,715.67 and Pivot R1 at 29,745.83 become the references, 95.67 and 125.83 points beyond the stop and inside one 14-day average true range of 554.19 points.
Sources and methodology
This outlook is built from our session review of the December E-mini Nasdaq-100 contract, the December ’26 contract, prepared after Thursday's close on October 22, 2026 for the Friday, October 23, 2026 session. Thursday's open, high, low and settle come from the provider's daily settlement record for the December contract, the 2026-10-22 row, and match the chart's completed daily bar. Thursday's completed extremes are also the inputs behind the published pivot ladder: Pivot R3 at 30,706.08 less Pivot S3 at 27,825.33, divided by three, and Pivot R2 at 30,349.67 less Pivot S2 at 28,429.17, divided by two, both return 960.25, and three times the 29,389.42 Pivot Point less the settle gives 59,026.26, which the pair of 29,993.25 and 29,033.00 reproduces to the published rounding at 59,026.25. No intraday series was preserved for Thursday, so no statement in this article places a Thursday print at a time of day, and Thursday's card is graded against the daily bar alone. Thursday's session opened at the Wednesday 6:00 PM ET reopen. Globex reopened at 6:00 PM ET Thursday, so the open, high and low on the provider's overview belong to the Friday session and are not Thursday's range.
The moving averages are the review's, computed from the provider's 259-session daily settlement series for the December contract, with the partial Friday row dropped, and stated to whole points; the oscillators are cited as published, read at about 6:30 PM ET after the reopen. Volume and open interest come from the provider's daily record: the 2026-10-22 row reads 822,661 contracts with open interest not yet reported, the 2026-10-21 row now reads 666,845 contracts and open interest of 270,896, where Thursday's outlook carried 654,208 contracts and open interest not yet reported, and the 2026-10-20 row reads open interest of 271,460. The evening positioning note used is the 5:22 PM ET Thursday edition, read at 8:58 PM ET, with Wednesday's closes in its reference column; every Nasdaq futures equivalent is the review's conversion at the 183.31 point measured basis, the December settlement less the cash close from the same provider's daily record, against 184.48 on Wednesday. The QQQ fund is a proxy read alongside the index levels. The reading that dealer hedging is more likely to amplify than to dampen moves is the review's interpretation from the index model and that proxy, both model outputs, and it is a damping read with no direction; the fund console, dated 2026-10-22, was read at about 9:00 PM ET. The volume and open-interest changes, the ten-session net change and the distances in this article are computed. Scenario ranges are analyst judgment, and items marked unconfirmed come from the news-feed calendar.
Thursday’s outlook for this contract is here, and the S&P 500 contract’s Thursday outlook covers the index that fell 1.21 percent in cash on Thursday. Outlooks for ES, NQ, GC and CL are collected on the market outlook page, and our forward trading record is on the performance statement.