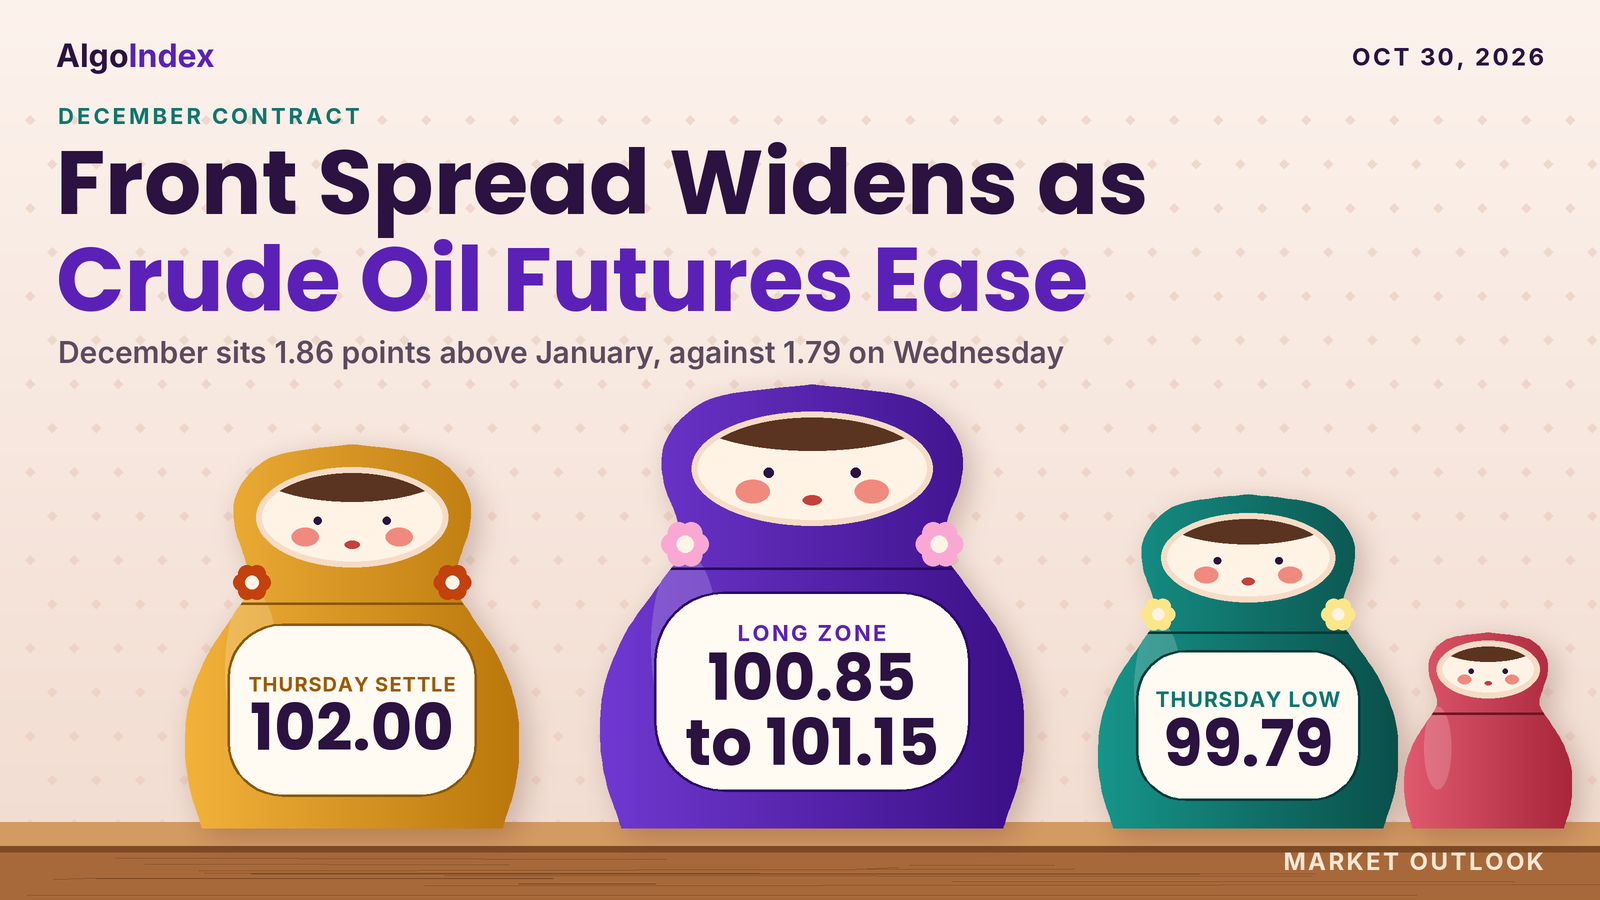
December crude settled at 102.00 on Thursday, down 78 cents or 0.76 percent, after a 3.21 point session between 99.79 and 103.00. The settle finished at 68.8 percent of that range. It was an inside session. The 103.00 high sat 55 cents beneath Wednesday's 103.55, and the 99.79 low sat 4 cents above Wednesday's 99.75. The range was 0.87 times the 14-day average daily range of 3.71 points. Over five sessions the contract is up 2.53 from the 99.47 settle of 10/22.
Thursday's range ran through our band and our stop. The Thursday card was a long from 101.10 to 101.40 with a 100.30 stop. The 99.79 low traded 1.31 beneath the band's bottom and 51 cents beneath that stop. The 103.00 high cleared the 102.20 first target by 80 cents and stopped 15 cents short of the 103.15 second target. No intraday series was preserved. The daily bar cannot show whether the stop or the first target printed first, so no fill and no result is asserted.
Brent eased by less. Its December contract settled at 114.88, down 44 cents or 0.38 percent, per the news feed at 2:50 PM ET and the provider's daily record. Its premium over December WTI widened to 12.88 from 12.54. December now sits 1.86 above January's 100.14, against 1.79 on Wednesday. That front-of-curve backwardation widened after easing in each of the three prior sessions.
The news flow ran in both directions. At 4:55 AM ET the news feed carried a press report of ongoing talks on a temporary peace arrangement. At 1:54 PM ET and 1:55 PM ET the news feed carried maritime security reports that a tanker had been struck by an unknown projectile in the Strait of Hormuz. At 3:13 PM ET the news feed carried a press report that the top US regional commander had briefed the President on military options for Iran. All three were reports. These items coincided with the session; no intraday series was preserved for any path claim, so the review does not attribute the move to any one of them.
December crude settled at 102.00, down 78 cents. That is 68.8 percent of a 99.79 to 103.00 range that sat entirely inside Wednesday's. The settle sits above all six settlement averages, 6 cents above the 5-day at 101.94. The first reference above is Wednesday's 102.78 settle, then Thursday's 103.00 high, one standard deviation resistance at 103.29 and Pivot R1 at 103.40. Support starts at the 101.95 target price, then the 5-day, the 101.83 stall level and the 101.60 Pivot Point. The setup is a long on the December contract. It runs from 100.85 to 101.15, stop 99.70, targets 102.30, 103.60 and an extended 104.75. The whole band sits beneath the settle, its top 85 cents under it, and the 102.30 first target sits 30 cents above the settle. Globex reopened at 6:00 PM ET on Thursday.
Thursday's 99.79 low ran 51 cents through the 100.30 stop
First, the grading. In Thursday's outlook we set a long on the December contract from 101.10 to 101.40, stop 100.30, with targets at 102.20, 103.15 and an extended 104.10. A settle beneath Pivot S1 at 100.50 would negate it. Two consecutive 30-minute closes beneath 101.10 would remove the edge. The card is graded on December's Thursday bar.
Then December traded. Its bar, from the provider's settlement row, opened at 101.96 at the Wednesday 6:00 PM ET reopen. That was 56 cents above the band's top and 82 cents beneath Wednesday's settle. It marked a high of 103.00 and a low of 99.79, and settled at 102.00. The range spanned the whole band. The low printed 1.31 beneath its 101.10 bottom. It also printed 51 cents beneath the 100.30 stop. The stop traded.
So did the first target. The high cleared 102.20 by 80 cents. It stopped 15 cents short of the 103.15 second target and 1.10 short of the extended 104.10. The settle finished 20 cents beneath the first target. The daily bar fixes the open, the extremes and the settle only. It cannot show whether the stop or the first target printed first. So no fill and no result is asserted. No invalidation settle printed; the 102.00 settle sat 1.50 above the 100.50 line.
Our ranges gave way mostly at the bottom. The low-range case of 101.20 to 103.60 broke at the bottom by 1.41 and held at the top by 60 cents. The most likely case of 100.40 to 104.30 gave way at the bottom by 61 cents and held at the top by 1.30. The high-range case of 99.10 to 105.80 held, with 69 cents to spare at the bottom. One deviation, 101.08 to 104.48, gave way by 1.29 at the bottom. Two deviations, 100.38 to 105.18, gave way by 59 cents. Three deviations, 99.84 to 105.72, gave way by 5 cents. One average true range around Wednesday's settle, 99.11 to 106.45, held by 68 cents at the bottom and 3.45 at the top. The session bands for Globex, London, the morning and the afternoon need an intraday series, so they are not graded.
The weighted path expected a hold between Pivot S1 at 100.50 and Pivot R1 at 104.30. It pictured a dip toward 101.08 that held above 100.30. The low printed 71 cents beneath that S1 and 51 cents beneath 100.30. The dip went deeper than pictured. No extension through Wednesday's 103.55 high printed; Thursday's high stopped 55 cents short. The alternative named a sustained move beneath 100.50 after the 8:30 AM ET GDP release, opening 100.38 and Tuesday's 99.90 settle. Both of those levels traded. The settle still finished 1.50 above 100.50, and the daily bar cannot show how long price stayed beneath it. The card's macro override named a confirmed step toward a deal that reopens the strait. The review records no confirmed step.
The December band at 100.85 to 101.15, just above one standard deviation support
The map moved down 25 cents, the gap between the two midpoints. Every price here is the December contract. The new band, 100.85 to 101.15, sits just above one standard deviation support at 100.71, its bottom 14 cents over that line. The Pivot Point at 101.60 sits 45 cents above its top. The 80 percent stochastic projection at 100.92 sits inside it. The settle sits 85 cents above the band's top and 1.15 above its bottom. The stop at 99.70 sits 9 cents beneath Thursday's 99.79 low and 5 cents beneath Wednesday's 99.75 low. It sits 6 cents beneath three standard deviations support at 99.76.
Globex reopened at 6:00 PM ET on Thursday. So the provider's overview already showed the Friday session, with an open of 102.80, a high of 102.88 and a low of 102.61. Those prints belong to the new session. All three sit above Thursday's settle, the low by 61 cents. The provider's previous close of 102.00 is Thursday's settle. Quotes after the reopen are not settlements and do not form a preserved intraday series.
Thursday ran narrower than Wednesday. Its 3.21 range was 0.87 times the 14-day average daily range. The bar carries a small body with a long lower shadow. The settle sits 4 cents above the 101.96 open. The upper shadow runs 1.00 above the settle and the lower shadow 2.17 beneath the open. Settlements over seven sessions read 97.15, 99.47, 103.27, 101.76, 99.90, 102.78 and 102.00. The last three sessions alternated between gains and declines. The high stopped 92 cents beneath the 103.92 of 10/23, still the one-month, 13-week and 52-week high. The one-month low is 86.00 and the 13-week low 71.00. January fell 85 cents, more than December's 78. That is why the spread widened while the outright price eased.
Wednesday's 102.78 settle is the first reference above, 78 cents up. Thursday's 103.00 high and one standard deviation resistance at 103.29 follow. Pivot R1 at 103.40 and Wednesday's 103.55 high come next. The 103.79 crossover stall level, two standard deviations resistance at 103.83 and the 103.92 high of 10/23 sit within 13 cents of one another. Three standard deviations resistance at 104.24, Pivot R2 at 104.81 and the 70 percent relative strength projection at 104.98 are the extended references. The 105.63 top of one average true range and Pivot R3 at 106.61 sit beyond.
Support starts 5 cents down, at the 101.95 published target price. The 5-day average at 101.94 sits a cent beneath it, then the 101.83 stall level. The Pivot Point at 101.60 sits 40 cents beneath the settle. The 80 percent projection at 100.92 and one standard deviation support at 100.71 follow. Then come the 9-day crossing price at 100.52 and the 9-day average at 100.30. Pivot S1 at 100.19 is the first published pivot support. Two standard deviations support at 100.17 sits 2 cents under it. Then a run of three levels within 4 cents. Thursday's 99.79 low, three standard deviations support at 99.76 and Wednesday's 99.75 low make it up. The 99.41 projection, Pivot S2 at 98.39 and the 98.37 bottom of one average true range follow. The 38.2 percent retracement from the four-week high sits at 97.07, 4.93 beneath the settle, with Pivot S3 at 96.98 under it. The long tail starts with the 18-day crossing at 96.91 and the 20-day at 95.68. It runs through the 94.96 retracement, the 40-day crossing at 93.03 and the 92.85 and 91.34 retracements. Further down sit the 50-day at 90.62, the 86.00 one-month low, the 100-day at 82.72, the 200-day at 77.39 and the 71.00 13-week low. No four-hour series was captured, so swing structure rests on daily bars only.
Every average still sits beneath price. The settle is 6 cents above the 5-day at 101.94 and 1.70 above the 9-day at 100.30. It sits 6.32 above the 20-day at 95.68 and 11.38 above the 50-day at 90.62. The gaps to the 100-day at 82.72 and the 200-day at 77.39 are 19.28 and 24.61. The 5-day rose 51 cents from 101.44. The 10/22 settle of 99.47 left the window and 102.00 replaced it. The 20-day rose 56 cents from 95.12 as the 10/01 settle of 90.84 left, and the 50-day rose 42 cents from 90.20. The stack stays in order. The 30 older settlements in the 50-day window averaged 87.24, the 50 older ones in the 100-day window 74.82 and the 100 older ones in the 200-day window 72.07. Friday's crossing prices are 100.52 for the 9-day, 96.91 for the 18-day and 93.03 for the 40-day.
Momentum readings stay high. Relative strength reads 65.92 on the 9-day, 65.76 on the 14-day and 64.90 on the 20-day. The raw stochastics read 77.85 percent on the 9-day and 87.22 percent on the 14-day. The 14-day %K at 84.85 percent remains marginally beneath %D at 85.26 percent, in the upper part of the range. Positive direction leads on both windows. It reads 22.27 against 4.12 on the 9-day with the ADX at 60.35, and 23.35 against 5.51 on the 14-day with the ADX at 46.87. Historic volatility reads 30.79 percent and 27.89 percent. The composite multi-indicator read for Friday is 100 percent buy, unchanged from the prior session. Its signal strength is described as strong and its direction as strengthening. It read 100 percent buy a week ago and 40 percent a month ago. The short, medium and long horizon groups each average 100 percent buy. The trend indicator reads buy. These are the provider's published readings, read at 6:20 PM ET on Thursday after the 6:00 PM ET reopen, so the provider may already be blending the reopened session's quote into them.
Average ranges sit near 3.6 points. The 14-day average true range stands at 3.63 points and the 14-day average daily range at 3.71. The 9-day figures are 3.68 and 3.77 and the 20-day 3.55 and 3.57. These were read after the reopen and carry the same caveat. One average true range either side of the settle spans 98.37 to 105.63. The deviation bands, built from five settlements and centred on the settle, run 100.71 to 103.29, 100.17 to 103.83 and 99.76 to 104.24. They describe settlement dispersion only. With Gulf headlines active after the settle, a single report can carry the contract outside any of them. Ten sessions of daily ranges read 4.05, 2.99, 6.12, 4.14, 2.45, 5.08, 2.80, 3.38, 3.80 and 3.21.
Tanker reports, a reserve loan and a 12.88 Brent premium
Headlines ran in both directions. At 4:55 AM ET the news feed carried a press report that the administration is in ongoing talks on a temporary peace arrangement. At 1:32 PM ET the feed carried a report that two large US oil companies cancelled executive travel to a Gulf energy conference next week on security grounds. At 1:33 PM ET it carried Iran's parliament speaker saying progress depends on agreement to Iran's seven conditions. At 1:47 PM ET it carried the President repeating that the Iran conflict will be over very soon.
Then the security reports. At 1:54 PM ET and 1:55 PM ET the news feed carried maritime security reports of a tanker struck by an unknown projectile while transiting outbound through the Strait of Hormuz. At 3:13 PM ET the news feed carried a press report that the top US regional commander briefed the President in person on military options for Iran. They coincided with the session. These are reports and statements carried by the feeds rather than events confirmed for this review, and none is treated as the measured cause of Thursday's move. No move is attributed to any one of them.
More came after the settle. At 3:51 PM ET to 3:53 PM ET the news feed carried statements from Yemen's Houthis claiming attacks on Saudi Arabia's Ras Tanura refinery, the Abqaiq facility and the Rabigh refinery. These are claims carried by the feed, and no damage or output effect was confirmed for this review. At 3:58 PM ET the news feed carried an Energy Department statement that five companies are to borrow 16.75 million barrels of crude from the Strategic Petroleum Reserve, out of 17 million barrels offered. It is a statement carried by the feed rather than a change in supply measured for this review. No producer-group statement was carried on the feeds read, so no quota or compliance change is asserted. The calendar lists the seven-country producer meeting deciding December production for Sunday, November 1, 2026.
No crude inventory report was released on Thursday in the calendars captured. The calendar lists the last weekly petroleum status report at 10:30 AM ET on Wednesday, October 28, 2026. It showed a crude draw of 1.892 million barrels, per the news-feed calendar and unconfirmed. The reserve loan, a statement carried by the news feed, is the only reserve item on the feeds. The calendar lists the next report for 10:30 AM ET on Wednesday, November 4, 2026.
Products split around crude. In the provider's daily record, December heating oil settled at 4.5875 dollars a gallon, down 1.64 percent from 4.6639, and December gasoline at 3.0881, down 0.66 percent from 3.1087. Heating oil fell by more than crude in percentage terms and gasoline by less. The heating oil margin is 42 gallons times the heating oil settle less the WTI settle. Against December WTI it stands at 90.68 dollars a barrel against 93.10 on Wednesday. The gasoline margin stands at 27.70 against 27.79. Both narrowed. No national refinery utilisation figure and no seasonal demand series were captured, so neither is asserted.
Rates and the dollar eased. The dollar index closed at 102.04 in the provider's daily record, down 0.15 from Wednesday's 102.19. The provider's ten-year yield record closed at 4.99 percent against 5.04 percent. The calendar lists the advance GDP estimate and the personal income and outlays report at 8:30 AM ET. GDP grew 3.4 percent against a 3.2 percent forecast and the PCE price index rose 3.6 percent from a year earlier, in line with the forecast, both per the news-feed calendar and unconfirmed. The European Central Bank held the main rate at 2.65 percent at 9:15 AM ET, per the news-feed calendar and unconfirmed. The seven-year note auction at 1:00 PM ET stopped at 4.894 percent, per the news-feed calendar and unconfirmed.
All four markets the reviews cover fell. Gold's December contract settled at 4,031.4, down 0.50 percent, and silver's December contract fell 2.40 percent. The S&P 500 cash index closed at 7,720.39, down 0.30 percent, and the Nasdaq-100 cash index fell 1.38 percent. The volatility index closed at 17.20 against 16.91. Crude's 0.76 percent decline was smaller than those of the Nasdaq-100 and silver, and larger than those of gold and the S&P 500. In the review's interpretation, equities and technology earnings set Thursday's lead across markets.
Money managers held a net long as of October 20. The weekly positioning report dated that day puts managed-money long positions at 163,413 contracts and short positions at 127,226, for a net long of 36,187. Commercial long positions stand at 890,913 and commercial short positions at 1,007,071. The report predates the moves of the last seven sessions, and the next report is due after the Friday close. December open interest stood at 268,720 for Wednesday in the provider's record, down from 278,341 on Tuesday. Thursday's open interest had not been reported at the time of capture. Thursday's December volume was 241,204 contracts against a revised 294,149 on Wednesday. No dealer-positioning dataset was read for crude.
The trade map for Friday
The review's setup is a long on the December contract. It runs from 100.85 to 101.15. The settle sits above every settlement average from the 5-day to the 200-day. Thursday held inside Wednesday's range with a long lower shadow. The composite stands at 100 percent buy with strong signal strength. That is the trend case. The band sits just above one standard deviation support at 100.71 and beneath the Pivot Point at 101.60. The stop at 99.70 sits beneath both session lows. The first target, 102.30, sits 30 cents above Thursday's settle and beneath its 103.00 high. The second, 103.60, sits above Pivot R1 at 103.40 and beneath the 103.79 stall level. The extended 104.75 sits beneath Pivot R2 at 104.81. In the review's reading, reported diplomacy can unwind part of the supply premium quickly. The review calls the setup an analyst judgment that dips are bought while the trend averages hold, not a measured edge.
Now the arithmetic. From the 101.00 midpoint the risk to the stop is 1.30, 35.8 percent of the 14-day average true range of 3.63. The targets sit 1.30, 2.60 and 3.75 above the midpoint. That is 1, 2 and 2.88 times the risk. The review rounds the last to 1:2.9. The whole band sits beneath the settle, its top 85 cents and its bottom 1.15 under it. The 102.30 first target sits 30 cents above the settle and 70 cents beneath Thursday's high. The 103.60 second target sits 5 cents above Wednesday's 103.55 high and 19 cents beneath the 103.79 stall level. The extended 104.75 sits 51 cents above three standard deviations resistance at 104.24 and 6 cents beneath Pivot R2.
Scenario ranges in the review are analyst judgment. The low-range case runs 101.20 to 103.40, the most likely 100.60 to 103.90 and the high-range case 99.40 to 105.60. Then by session. Globex reopened at 6:00 PM ET on Thursday. The provider's overview then showed the new session trading between 102.61 and 102.88, above the settle, at the time of capture. The review's bias is constructive while the contract holds above Pivot S1 at 100.19, with an expected band of roughly 101.20 to 103.60 absent a further Gulf headline. Two Asian items follow. Tokyo consumer prices are listed at 7:30 PM ET and the Bank of Japan decision at 11:30 PM ET on Thursday, both per the news-feed calendar and unconfirmed.
London runs roughly 101.00 to 103.80 with a constructive bias. German flash GDP is listed at 5:00 AM ET and euro-area flash GDP at 6:00 AM ET, both per the news-feed calendar and unconfirmed. The calendar lists results from an integrated oil company at 6:30 AM ET. The review names the Pivot Point at 101.60 as the first meaningful support. Three levels sit between the settle and that line: 101.95, 101.94 and 101.83. It names Pivot R1 at 103.40 as the first published resistance beyond Thursday's 103.00 high. The numbers differ. One standard deviation resistance at 103.29 sits between the two, 11 cents beneath R1.
The morning band runs roughly 100.60 to 104.00. The calendar lists the employment cost index at 8:30 AM ET. Canadian monthly GDP is listed at the same 8:30 AM ET, per the news-feed calendar and unconfirmed. The calendar lists results from a second integrated oil company for the date only. The entry band sits beneath the settle, inside that morning band. Two standard deviations resistance at 103.83 sits 17 cents beneath its top. The afternoon runs roughly 100.20 to 104.30. Federal Reserve speakers are listed at 12:00 PM ET and 12:30 PM ET, per the news-feed calendar and unconfirmed, and crude settles at 2:30 PM ET. The review puts the outer edges near two standard deviations support at 100.17 and three standard deviations resistance at 104.24. The first sits 3 cents beneath the band's bottom, outside it. The second sits 6 cents inside its top.
Then the weekend. Globex halts at 5:00 PM ET on Friday and reopens at 6:00 PM ET on Sunday, November 1. The calendar lists the seven-country producer meeting for that Sunday, for the date only. US daylight saving time ends at 2:00 AM ET the same day, as the calendar lists it. Two days of headline exposure separate Friday's settle from the next reopen. Chinese official manufacturing data is listed at 9:30 PM ET on Friday, per the news-feed calendar and unconfirmed.
The review also weighs the path. In the review's analyst judgment the most probable path holds the contract between Pivot S1 at 100.19 and two standard deviations resistance at 103.83, with a dip toward one standard deviation support at 100.71 that holds above 99.70 weighted slightly above a direct extension through Wednesday's 103.55 high. In the review's reading the inside session and the settle sitting only 6 cents above the 5-day average argue for a test lower before any extension. It names an alternative. A sustained move beneath Pivot S1 at 100.19 after the 8:30 AM ET employment cost index would invalidate that reading. It would open Thursday's 99.79 low and Pivot S2 at 98.39. The upside case is named too. A reopened session that holds above Thursday's 103.00 high would put Pivot R1 at 103.40 and the 103.92 high of 10/23 in play without the dip the setup needs. In the review's judgment the first-order scheduled event for crude on Friday is the 8:30 AM ET employment cost index. It names the Sunday producer meeting and unscheduled Gulf headlines as the larger sources of risk.
The reopen low of 102.61 sat 1.46 above Friday's band.
The complete data picture
Every number behind Friday’s plan, charted first, then the full level lists, then the complete numeric reference underneath. Every price is the December contract unless January is named.
Full numeric reference, every remaining figure from the session review
1. Executive Summary
The December crude contract settled at 102.00 on Thursday, down 78 cents or 0.76 percent from Wednesday's settle of 102.78, after trading between 103.00 and 99.79, a 3.21 point daily range. The settle finished at 68.8 percent of the range, and the 3.21 point range was 0.87 multiples of the published 14-day average daily range of 3.71 points. Thursday's 103.00 high sat 55 cents beneath Wednesday's 103.55 high and Thursday's 99.79 low sat 4 cents above Wednesday's 99.75 low, so the session traded entirely inside Wednesday's range. Over five sessions the contract is up 2.53 points from the 99.47 settle of 10/22.
Brent's December contract settled at 114.88, down 44 cents or 0.38 percent, per the news feed at 2:50 PM ET and the provider's daily record, so its premium over December WTI widened to 12.88 from 12.54 on Wednesday. The January WTI contract settled at 100.14 in the provider's daily record, which leaves December 1.86 points above January against 1.79 on Wednesday, so the front-of-curve backwardation widened after easing in each of the three prior sessions.
The news flow ran in both directions. The news feed carried at 1:54 PM ET and 1:55 PM ET maritime security reports that a tanker had been struck by an unknown projectile while transiting outbound through the Strait of Hormuz, and at 3:13 PM ET a press report that the top US regional commander had briefed the President on military options for Iran. On the other side, the news feed carried at 4:55 AM ET a press report of ongoing talks on a temporary peace arrangement and at 1:33 PM ET Iran's parliament speaker saying progress depends on agreement to Iran's seven conditions. These items coincided with the session; no intraday series was preserved for any path claim, so this review does not attribute the move to any one of them.
After the settle, the news feed carried at 3:51 PM ET to 3:53 PM ET statements from Yemen's Houthis claiming attacks on the Ras Tanura refinery, the Abqaiq facility and the Rabigh refinery in Saudi Arabia, and at 3:58 PM ET an Energy Department statement that companies are to borrow 16.75 million barrels from the Strategic Petroleum Reserve. The provider's overview showed the reopened Friday session trading above Thursday's settle at the time of capture. The published 14-day average true range is 3.63 points. The Primary Setup below is a long from the 100.85 to 101.15 band just above one standard deviation support at 100.71, stopped at 99.70 beneath both session lows, with objectives at 102.30, 103.60 and an extended 104.75.
2. Price Action & Technical Structure
2.1 Intraday and Session Review
The Thursday session opened at 101.96 at the Wednesday 6:00 PM ET reopen, 82 cents beneath Wednesday's settle, marked a daily high of 103.00 and a daily low of 99.79, and settled at 102.00 at 2:30 PM ET. This review makes no claim about the order in which the high and the low printed; the daily bar fixes the open, the extremes and the settle, and that is the evidence used here.
The settle sits 2.21 points above the low and 1.00 point beneath the high. The body of the daily bar measures 4 cents from the 101.96 open to the 102.00 settle, with an upper shadow of 1.00 point above the settle and a lower shadow of 2.17 points beneath the open, so the bar carries a small body with a long lower shadow.
Globex reopened at 6:00 PM ET, so the open, high and low shown on the provider's overview page, 102.80, 102.88 and 102.61, belong to the new Friday session and not to Thursday's completed session. The provider's previous close of 102.00 is Thursday's settle.
Thursday's completed-session extremes are the completed-session inputs behind the published pivot ladder rather than an independently read bar. Pivot R3 at 106.61 minus Pivot S3 at 96.98, divided by three, returns 3.21, and Pivot R2 at 104.81 minus Pivot S2 at 98.39, divided by two, returns the same 3.21. Three times the Pivot Point of 101.60 less the 102.00 settle gives a high plus low sum of 202.80, which the pair of 103.00 and 99.79 reproduces to within the published rounding at 202.79, and that pair reproduces all seven published rungs.
Independent corroboration: the provider's settlement row and the chart's completed daily bar on the continuous symbol carry the same 101.96 open, 103.00 high, 99.79 low and 102.00 settle, and the news feed reported the December settle at 102.00, down 78 cents, at 2:31 PM ET.
2.2 Daily Structure
Thursday's 103.00 high sits 55 cents beneath Wednesday's 103.55, and the 99.79 low sits 4 cents above Wednesday's 99.75, so Thursday was an inside session. The high stopped 92 cents beneath the 103.92 high of 10/23, which the provider still publishes as the 52-week, 13-week and one-month high.
Settlements over the last seven sessions read 97.15, 99.47, 103.27, 101.76, 99.90, 102.78 and 102.00, so the contract has alternated between gains and declines for the last three sessions. The one-month low published by the provider is 86.00 and the 13-week low is 71.00.
The forward curve remains in backwardation at the front: December settled 1.86 points above January's 100.14, against 1.79 points on Wednesday. January fell 85 cents on the day, more than December's 78 cent decline, which is why the spread widened while the outright price eased.
2.3 4-Hour and Swing Structure
Daily ranges for the last ten sessions ran 4.05, 2.99, 6.12, 4.14, 2.45, 5.08, 2.80, 3.38, 3.80 and 3.21, and the settlement changes over the same ten sessions read plus 2.52, minus 0.48, minus 0.72, minus 0.67, plus 2.32, plus 3.80, minus 1.51, minus 1.86, plus 2.88 and minus 0.78.
The retracement grid published for Friday places the 38.2 percent retracement from the four-week high at 97.07, 4.93 points beneath the settle, and the 50 percent retracement of the four-week range at 94.96. Further beneath, the 38.2 percent retracement from the four-week low sits at 92.85 and the 38.2 percent retracement from the 13-week high at 91.34. No four-hour series was captured for this review, so swing structure here rests on daily bars only.
2.4 Moving Averages
The averages cited in this subsection were computed for this review from the provider's daily settlement series for the December contract, which holds 259 completed sessions through Thursday; the partial Friday row of the reopened Globex session was dropped before counting. The 5-day average stands at 101.94, the 9-day at 100.30, the 20-day at 95.68, the 50-day at 90.62, the 100-day at 82.72 and the 200-day at 77.39.
The 102.00 settle sits 6 cents above the 5-day average, 1.70 points above the 9-day, 6.32 points above the 20-day, 11.38 points above the 50-day, 19.28 points above the 100-day and 24.61 points above the 200-day. The 5-day average rose 51 cents from Wednesday's 101.44, because the 10/22 settle of 99.47 left the window and was replaced by 102.00. The 20-day rose 56 cents from 95.12, because the 10/01 settle of 90.84 left that window, and the 50-day rose 42 cents from 90.20.
The 20-day average sits above the 50-day because the last 20 settlements averaged 95.68 against 90.62 for the full 50, which means the 30 older settlements in the 50-day window averaged lower, at 87.24. The 50-day sits above the 100-day because the 50 older settlements in the 100-day window averaged lower, at 74.82, and the 100-day sits above the 200-day because the 100 older settlements in the 200-day window averaged lower, at 72.07. The projection grid gives the prices at which each average would be crossed on Friday: 100.52 for the 9-day, 96.91 for the 18-day and 93.03 for the 40-day.
2.5 Oscillator and Trend Readings
The oscillator figures below are as published on the provider's technical page, read at 6:20 PM ET on Thursday after the 6:00 PM ET reopen, so the provider may already be blending the reopened session's quote into them; they are the provider's published readings, not this review's computations. The 9-day relative strength reads 65.92, the 14-day relative strength 65.76 and the 20-day relative strength 64.90.
The 9-day raw stochastic reads 77.85 percent and the 14-day raw stochastic 87.22 percent, while the 14-day stochastic %K reads 84.85 percent and the 14-day stochastic %D 85.26 percent, so %K remains marginally beneath %D in the upper part of the range.
The 9-day directional index ADX reads 60.35 with the 9-day +DI at 22.27 and the 9-day -DI at 4.12; the 14-day directional index ADX reads 46.87 with the 14-day +DI at 23.35 and the 14-day -DI at 5.51, so positive direction leads on both. The 9-day historic volatility reads 30.79 percent and the 14-day historic volatility 27.89 percent.
The composite multi-indicator read published for the Friday session is "100% BUY", unchanged from the prior session's snapshot of "100% BUY", with signal strength described as "Strong" and direction as "Strengthening". The snapshot history reads "100% BUY" a week ago and "40% BUY" a month ago. The short-horizon, medium-horizon and long-horizon groups each average "100% BUY", and the composite trend indicator reads buy.
2.6 Volatility and Expected Range
The published 14-day average true range stands at 3.63 points and the 14-day average daily range at 3.71 points; the 9-day average true range is 3.68 with a 9-day average daily range of 3.77, and the 20-day average true range is 3.55 with a 20-day average daily range of 3.57. These were read after the reopen and carry the same caveat as the oscillators. Thursday's 3.21 point range was 0.87 multiples of the 14-day average daily range.
Adding and subtracting the 14-day average true range of 3.63 points from the 102.00 settle frames Friday between 98.37 and 105.63. The published standard-deviation bands are built from five settlements: one deviation spans 100.71 to 103.29, two spans 100.17 to 103.83 and three spans 99.76 to 104.24. These bands describe settlement dispersion, not intraday reach, and with Gulf headlines active after the settle a single report can carry the contract outside any of them.
3. Key Levels
3.1 Resistance
Above the 102.00 settle, the first overhead references are Thursday's 103.00 high and one standard deviation resistance at 103.29, followed by Pivot R1 at 103.40 and Wednesday's 103.55 high. The 3-10 day crossover stall level at 103.79, two standard deviations resistance at 103.83 and the 103.92 high of 10/23, which is also the published 52-week, 13-week and one-month high, form the next band. Three standard deviations resistance at 104.24, Pivot R2 at 104.81 and the 70 percent relative strength projection at 104.98 are the extended references, with Pivot R3 at 106.61 beyond.
3.2 Support
Beneath the settle sits the published target price at 101.95 and the 14-day %K stochastic stall level at 101.83, then the Pivot Point at 101.60 and the 80 percent raw stochastic projection at 100.92. One standard deviation support at 100.71 and the 9-day average crossing price at 100.52 sit above Pivot S1 at 100.19 and two standard deviations support at 100.17. Thursday's 99.79 low, three standard deviations support at 99.76, Wednesday's 99.75 low, the 70 percent raw stochastic projection at 99.41, Pivot S2 at 98.39, the 38.2 percent retracement from the four-week high at 97.07 and Pivot S3 at 96.98 are the extended references.
4. Macro Drivers
4.1 OPEC and Supply Policy (Quotas, Compliance, Saudi/Russia Signals)
No producer-group statement was carried on the feeds read for this review, so no quota or compliance change is asserted. The calendar lists the seven-country producer meeting deciding December production for Sunday, November 1, 2026. After the settle, the news feed carried at 3:51 PM ET to 3:53 PM ET statements from Yemen's Houthis claiming attacks on Saudi Arabia's Ras Tanura refinery, the Abqaiq facility and the Rabigh refinery; these are claims carried by the feed, and no damage or output effect was confirmed for this review.
The feed also carried at 3:58 PM ET an Energy Department statement that five companies are to borrow 16.75 million barrels of crude from the Strategic Petroleum Reserve out of 17 million barrels offered. It is a statement carried by the feed rather than a change in supply measured for this review.
4.2 EIA and API Inventory (Crude Stocks, Gasoline, Distillates, Cushing, SPR)
No crude inventory report was released on Thursday in the calendars captured for this review. The last weekly petroleum status report, released at 10:30 AM ET on Wednesday, October 28, 2026, as the calendar lists it, showed a crude draw of 1.892 million barrels, per the news-feed calendar and unconfirmed. The Strategic Petroleum Reserve loan described in section 4.1 is the only reserve item carried on the feeds for this review.
The next weekly petroleum status report is scheduled for 10:30 AM ET on Wednesday, November 4, 2026, as the calendar lists it, which is the next inventory release the captured calendar lists for crude.
4.3 Geopolitical Backdrop (Middle East, Iran, Russia/Ukraine, Venezuela)
The news feed carried at 4:55 AM ET a press report that the administration is in ongoing talks on a temporary peace arrangement, at 1:33 PM ET Iran's parliament speaker saying progress depends on agreement to Iran's seven conditions, and at 1:47 PM ET the President repeating that the Iran conflict will be over very soon. At 1:54 PM ET and 1:55 PM ET the feed carried maritime security reports of a tanker struck by an unknown projectile while transiting outbound through the Strait of Hormuz, and at 3:13 PM ET a press report that the top US regional commander briefed the President in person on military options for Iran.
The news feed also carried at 1:32 PM ET a report that two large US oil companies cancelled executive travel to a Gulf energy conference next week on security grounds. These are reports and statements carried by the feeds rather than events confirmed for this review, and none is treated as the measured cause of Thursday's move.
4.4 Demand and Refining (Refinery Utilization, Crack Spreads, Seasonal Pattern)
On the December contracts in the provider's daily record, December heating oil settled at 4.5875 dollars a gallon, down 1.64 percent from 4.6639 on Wednesday, and December gasoline at 3.0881, down 0.66 percent from 3.1087. Heating oil fell by more than crude in percentage terms and gasoline by less.
Against the December WTI settle, the heating oil margin, 42 gallons times the heating oil settle less the WTI settle, stands at 90.68 dollars a barrel against 93.10 on Wednesday, and the gasoline margin at 27.70 against 27.79. Both margins narrowed. No national refinery utilisation figure and no seasonal demand series were captured, so neither is asserted.
4.5 Dollar and Cross-Asset (DXY, Commodities Complex, Equity Risk-On/Off)
The dollar index closed at 102.04 in the provider's daily record, down 0.15 from Wednesday's 102.19, and the provider's ten-year yield record closed at 4.99 percent; Wednesday's close was 5.04 percent. The advance GDP estimate released at 8:30 AM ET on Thursday, October 29, 2026, as the calendar lists it, showed, per the news-feed calendar and unconfirmed, growth of 3.4 percent against a forecast of 3.2 percent, and the personal income and outlays report at the same time showed the PCE price index up 3.6 percent from a year earlier, in line with the forecast, both per the news-feed calendar and unconfirmed.
Gold's December contract settled at 4,031.4, down 0.50 percent, and silver's December contract fell 2.40 percent. The S&P 500 cash index closed at 7,720.39, down 0.30 percent, and the Nasdaq-100 cash index fell 1.38 percent, with the volatility index at 17.20; Wednesday's close was 16.91. Crude fell by less than the Nasdaq-100 and silver in percentage terms, and in this review's interpretation Thursday's lead came from equities and technology earnings rather than from crude.
4.6 Institutional Positioning (COT, Money Manager and Commercial Hedger, Speculator Length)
The weekly positioning report dated October 20, shown on the provider's overview, puts managed-money long positions at 163,413 contracts and managed-money short positions at 127,226, for a net long of 36,187. Commercial long positions stand at 890,913 and commercial short positions at 1,007,071. The report predates the moves of the last seven sessions, and the next report is due after the Friday close.
Open interest on the December contract is shown at 268,720 for Wednesday in the provider's record, down from 278,341 on Tuesday, and Thursday's open interest had not been reported at the time of capture; Thursday's December volume was 241,204 contracts. Brent's December premium over December WTI widened to 12.88 from 12.54, and the December-January WTI spread widened to 1.86 from 1.79.
5. No Liquid Options Proxy
This review covers crude without a positioning dataset. There is no dealer-positioning surface read for this instrument in this review, no gamma map, no options concentration levels and no flow attribution, and none is inferred from any other instrument. Every level in section 3 originates in published pivot arithmetic, published standard-deviation bands, published retracement and moving-average projections, settlement averages computed from the provider's daily record, or the completed-session extremes described in section 2.1.
This is a statement about coverage, not about the existence of listed crude options. No such dataset was read for this review, so no claim resting on one appears anywhere in this review or in this outlook. The positioning inputs used for crude are the weekly positioning report, the Brent spread, the front calendar spread, the product margins and the open-interest and volume record.
6. Forecast
6.1 Night Session (6:00 PM ET Thursday to 3:00 AM ET Friday, Globex/Asia)
Globex reopened at 6:00 PM ET on Thursday, October 29, 2026, and the provider's overview showed the new session trading between 102.61 and 102.88 at the time of capture, above Thursday's settle, after the claimed attacks on Saudi facilities. Tokyo consumer prices are listed at 7:30 PM ET and the Bank of Japan decision at 11:30 PM ET on Thursday, October 29, 2026, both per the news-feed calendar and unconfirmed. Bias constructive while the contract holds above Pivot S1 at 100.19, expected band roughly 101.20 to 103.60 absent a further Gulf headline.
6.2 London Session (3:00 AM ET to 8:00 AM ET Friday)
German flash GDP is listed at 5:00 AM ET and euro-area flash GDP at 6:00 AM ET on Friday, October 30, 2026, both per the news-feed calendar and unconfirmed, and results from an integrated oil company are scheduled for 6:30 AM ET on Friday, October 30, 2026, as the calendar lists them. Bias constructive, expected band roughly 101.00 to 103.80, with the Pivot Point at 101.60 the first meaningful support and Pivot R1 at 103.40 the first pivot resistance beyond Thursday's 103.00 high, with one standard deviation resistance at 103.29 between the two.
6.3 Morning Session (9:00 AM ET to 12:00 PM ET Friday, US Open / Pit Session)
The employment cost index is scheduled for 8:30 AM ET on Friday, October 30, 2026, as the calendar lists it, and Canadian monthly GDP is listed at the same 8:30 AM ET, per the news-feed calendar and unconfirmed. Results from a second integrated oil company are due on Friday, October 30, 2026, as the calendar lists them for the date only. Expected band roughly 100.60 to 104.00, with the 100.85 to 101.15 entry band beneath and two standard deviations resistance at 103.83 above.
6.4 Afternoon Session (12:00 PM ET to 2:30 PM ET Friday, NYMEX Pit Close)
Federal Reserve speakers are listed at 12:00 PM ET and 12:30 PM ET on Friday, October 30, 2026, per the news-feed calendar and unconfirmed, and crude settles at 2:30 PM ET. Expected band roughly 100.20 to 104.30, with the outer edges near two standard deviations support at 100.17 and three standard deviations resistance at 104.24. The weekend carries the producer meeting described in section 4.1, so the Friday settle may carry that risk into the weekend.
6.5 Night Session Forward (6:00 PM ET Friday)
Globex halts at 5:00 PM ET on Friday and does not reopen until 6:00 PM ET on Sunday, November 1, 2026. US daylight saving time ends at 2:00 AM ET on Sunday, November 1, 2026, as the calendar lists it, and the seven-country producer meeting is listed for the same Sunday, as the calendar lists it, for the date only. Two days of headline exposure therefore separate Friday's settle from the next reopen, and Chinese official manufacturing data is listed at 9:30 PM ET on Friday, October 30, 2026, per the news-feed calendar and unconfirmed.
6.6 Expected Range (Friday Full Session)
Low-range scenario: 101.20 to 103.40
Mid-range scenario (most likely): 100.60 to 103.90
High-range scenario: 99.40 to 105.60
6.7 Most Likely Path
In this review's analyst judgment the most probable path holds the contract between Pivot S1 at 100.19 and two standard deviations resistance at 103.83, with a dip toward one standard deviation support at 100.71 that holds above 99.70 weighted slightly above a direct extension through Wednesday's 103.55 high. The settle sits above every settlement average from the 5-day to the 200-day, positive direction leads on both directional systems and the composite reads "100% BUY", while the inside session and the settle sitting only 6 cents above the 5-day average argue for a test lower before any extension.
The alternative that would invalidate this reading is a sustained move beneath Pivot S1 at 100.19 after the 8:30 AM ET employment cost index on Friday, October 30, 2026, as the calendar lists it, which would open Thursday's 99.79 low and Pivot S2 at 98.39. On the other side, a reopened session that holds above Thursday's 103.00 high on further Gulf reports would put Pivot R1 at 103.40 and the 103.92 high of 10/23 in play without the dip the setup needs.
7. Friday Economic Calendar
Thursday's releases are complete. The advance GDP estimate and the personal income and outlays report were released at 8:30 AM ET on Thursday, October 29, 2026, as the calendar lists them; per the news-feed calendar and unconfirmed, GDP grew 3.4 percent against a 3.2 percent forecast and the PCE price index rose 3.6 percent from a year earlier, in line with the forecast. The European Central Bank decision released at 9:15 AM ET on Thursday, October 29, 2026, per the news-feed calendar and unconfirmed, held the main rate at 2.65 percent. The seven-year note auction at 1:00 PM ET on Thursday, October 29, 2026, per the news-feed calendar and unconfirmed, stopped at 4.894 percent. Crude settled at 2:30 PM ET, and results from an online retailer and a chipmaker were released after the close on Thursday, October 29, 2026, as the calendar lists them.
On Friday, October 30, 2026 German flash GDP is listed at 5:00 AM ET and euro-area flash GDP at 6:00 AM ET, both per the news-feed calendar and unconfirmed. Results from an integrated oil company are scheduled for 6:30 AM ET and the employment cost index for 8:30 AM ET on Friday, October 30, 2026, both as the calendar lists them, and results from a second integrated oil company are due the same day, as the calendar lists them for the date only. Federal Reserve speakers are listed at 12:00 PM ET and 12:30 PM ET on Friday, October 30, 2026, per the news-feed calendar and unconfirmed.
Later in the cycle, the seven-country producer meeting is listed for Sunday, November 1, 2026, as the calendar lists it, the day US daylight saving time ends at 2:00 AM ET, as the calendar lists it. The next weekly petroleum status report is scheduled for 10:30 AM ET on Wednesday, November 4, 2026, and the employment situation report for 8:30 AM ET on Friday, November 6, 2026, both as the calendar lists them. In this review's judgment the first-order scheduled event for crude on Friday is the 8:30 AM ET employment cost index, with the Sunday producer meeting and unscheduled Gulf headlines the larger sources of risk.
8. Primary Trade Setup
Direction: Long
Rationale: The settle sits above every settlement average from the 5-day to the 200-day, Thursday held inside Wednesday's range with a long lower shadow, and the composite stands at "100% BUY" with strong signal strength. A dip into the 100.85 to 101.15 band, just above one standard deviation support at 100.71 and beneath the Pivot Point at 101.60, offers a long with a defined risk point beneath both session lows. Reported diplomacy can unwind part of the supply premium quickly, so the setup is an analyst judgment that dips are bought while the trend averages hold, not a measured edge.
Entry Zone: 100.85 to 101.15
Stop Loss: 99.70 (9 cents beneath Thursday's 99.79 low and 5 cents beneath Wednesday's 99.75 low)
Target 1 (T1): 102.30 (above Thursday's 102.00 settle and beneath Thursday's 103.00 high)
Target 2 (T2): 103.60 (above Pivot R1 at 103.40 and beneath the 103.79 crossover stall level)
Target 3 (T3, extended): 104.75 (beneath Pivot R2 at 104.81)
Risk-to-Reward: Approximately 1:1 to T1, 1:2 to T2, 1:2.9 to T3
Invalidation: A settle beneath Pivot S1 at 100.19 negates the thesis. Short of that, the edge is removed by acceptance beneath the entry band rather than by a touch, defined as two consecutive 30-minute closes beneath 100.85.
Macro override: A confirmed step toward a temporary peace arrangement with Iran would remove part of the supply premium. In that scenario a move through the 99.70 stop invalidates the long before the targets, and Pivot S2 at 98.39 becomes the reference, 1.31 points beyond the stop and inside one 14-day average true range of 3.63 points.
Sources and methodology
This outlook is built from our session review of the December WTI crude contract (CLZ26), prepared after Thursday's close on October 29, 2026 for the Friday, October 30, 2026 session. December, which the chart's continuous symbol tracks, is the front month. Thursday's completed extremes are the inputs behind the published pivot ladder: Pivot R3 at 106.61 less Pivot S3 at 96.98, divided by three, and Pivot R2 at 104.81 less Pivot S2 at 98.39, divided by two, both return 3.21. Three times the 101.60 Pivot Point less the 102.00 settle gives 202.80, which the 103.00 high and 99.79 low reproduce at 202.79, within the published rounding. The provider's settlement row and the chart's completed Thursday bar carry the same open, extremes and settle, and the news feed reported the December settle at 102.00, down 78 cents, at 2:31 PM ET. No intraday series was preserved for Thursday, so no timed price path is asserted, and no price move is tied to a headline or to the inventory report.
Thursday's card was written on the December contract and is graded only on the provider's December settlement row for 10/29 (open 101.96, high 103.00, low 99.79, settle 102.00, volume 241,204). The daily bar fixes the open, the extremes and the settle, so the order of events within Thursday cannot be shown, and the card's session bands are not graded.
The moving averages were computed from the provider's daily settlement series for December, 259 completed sessions through Thursday; the partial Friday row of the reopened Globex session was dropped before counting. The oscillators and range averages are cited as published, read at 6:20 PM ET after the reopen. Thursday's volume and the open-interest figures equal the provider's dated rows. Wednesday's 10/28 row has been revised: December volume now reads 294,149 against the 274,349 cited in Thursday's outlook, and open interest, not reported then, reads 268,720. Thursday's open interest had not been reported. The close position in the range is 2.21 over 3.21, or 68.8 percent. The weekly positioning report is dated October 20. No dealer-positioning dataset was read for crude; the positioning inputs are the weekly positioning report, the Brent spread, the front calendar spread, the product margins and the open-interest and volume record. Scenario ranges are analyst judgment, and items marked unconfirmed come from the news feed or its calendar.
Thursday’s outlook for this contract is here, and the gold contract’s Thursday outlook covers the metal whose December contract settled at 4,031.4 on Thursday, down 0.50 percent. Outlooks for ES, NQ, GC and CL are collected on the market outlook page, and our forward trading record is on the performance statement.