At the Wednesday 6:00 PM ET reopen the December Nasdaq-100 contract opened at 29,793.50, 146.50 points beneath the short band we published for Thursday. The day's high added just 0.75 points. It stopped 145.75 short of the band. The low, meanwhile, reached beneath all three of the card's target prices. With the band untouched, the card never came into play.
The contract settled at 29,562.00, down 417.50 points, or 1.39 percent, at 66.0 percent of a 683.25 point range. It was the largest decline since 10/22. The Nasdaq-100 cash index fell 1.38 percent to 29,402.51, while the S&P 500 cash index lost 0.30 percent. Results from an online retailer and a processor maker followed the close, as the calendar lists them. Friday's map starts beneath the settle.
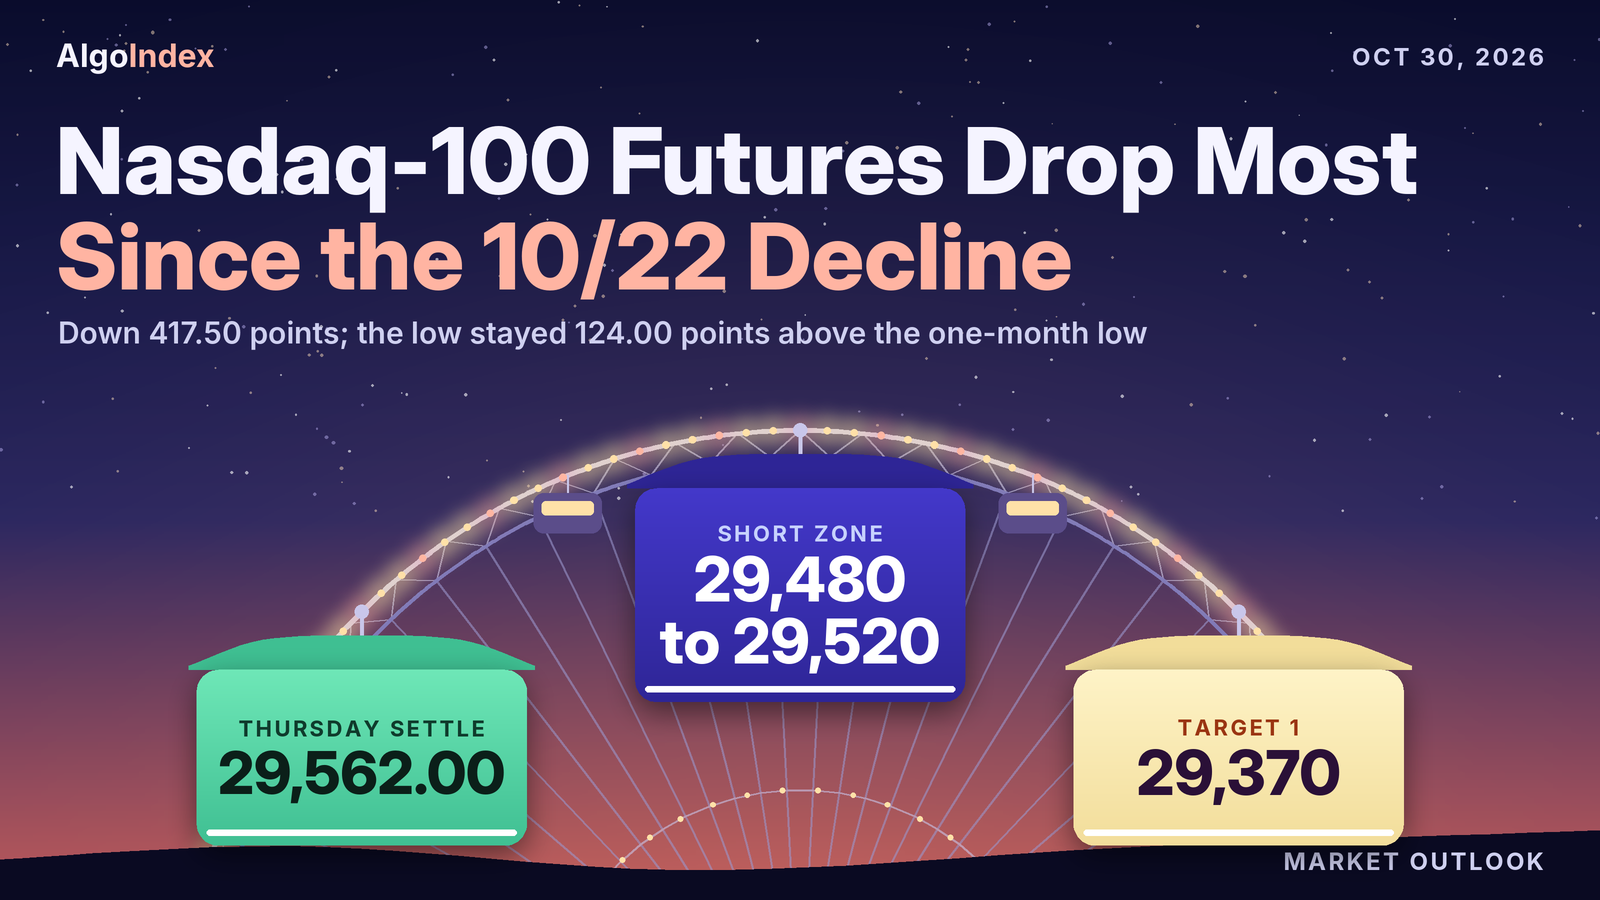
December Nasdaq-100 futures settled at 29,562.00, down 417.50 points, with a lower high and a lower low that ended a run of three higher settles. Thursday's published short band at 29,940 to 29,980 never traded, and neither did the 30,080 stop; the session sat wholly beneath the 29,840 first target while the 29,720 and 29,600 target prices traded, the daily bar cannot show the order, and with the band untouched the card never came into play. The settle sits beneath every settlement average from the 5-day to the 100-day and above the 200-day. The primary setup for Friday is a short from 29,480 to 29,520, a band beneath the settle that holds the Pivot Point at 29,489.08, stop 29,630, targets 29,370, 29,240 and an extended 29,110. The employment cost index is scheduled for 8:30 AM ET, as the calendar lists it.
Thursday’s card: the band stayed 145.75 points out of reach and the stop never traded
In Thursday’s outlook we set a short from 29,940 to 29,980, stop 30,080. Its targets sat at 29,840, 29,720 and an extended 29,600. Thursday's bar, from the review and the provider's 2026-10-29 settlement row, opened at 29,793.50 at the Wednesday 6:00 PM ET reopen, marked a high of 29,794.25 and a low of 29,111.00, and settled at 29,562.00. The band was never reached. The high stopped 145.75 points beneath its bottom.
The stop sat further off still, 285.75 points above the high. The first target's price never traded either. The whole session sat beneath it, 45.75 points under 29,840 at the high. The low cut 609.00 points beneath the second target and 489.00 beneath the extended third. The settle finished 38.00 beneath that third target. None of it made the card active. A short from the band needed the band to trade, so no fill and no result are asserted. No intraday series was preserved for Thursday, and the daily bar cannot show the order of any of these prints.
The card's other tests were never close. Its invalidation needed a settle above Pivot R1 at 30,213.58. The settle finished 651.58 points beneath that line. Its acceptance test needed two consecutive 30-minute closes above 29,980. Without a 30-minute series that test cannot be read bar by bar. It could not have fired, though. The high stayed 185.75 points beneath 29,980.
Its macro override named a cash-session reversal of the after-hours decline in a search-engine group, or GDP and inflation data read as easing pressure on rates. Its reference, Wednesday's 30,178.00 high, did not trade. The high stopped 383.75 points beneath it. The news feed carried at 9:33 AM ET an item that the group's shares fell 13 percent after its results. Advance GDP and the personal income and outlays report came at 8:30 AM ET, as the calendar lists them. Per the news-feed calendar and unconfirmed, GDP grew 3.4 percent against a 3.2 percent forecast and the PCE price index rose 3.6 percent from a year earlier. The review ties no price move to either item.
Our ranges are scored against the whole day's extremes, which is all the daily bar allows. None held. All seven of Thursday's range bands contained the high and missed the low. The most likely case of 29,430 to 30,080 held the high with 285.75 points to spare. Its bottom sat 319.00 above the low. The high-range case of 29,206 to 30,368 came closest, 95.00 points short at the bottom. The low-range case and the night band, both 29,550 to 29,950, missed by 439.00. London's 29,500 to 29,950 missed by 389.00. The morning band of 29,430 to 30,040 and the afternoon band of 29,430 to 30,080 missed by 319.00. The bar cannot place the low in any one session.
The most probable path, an analyst judgment, kept the contract between Pivot S2 at 29,440.17 and the 30,080.24 relative strength projection. It weighted a failed rebound toward the Pivot Point at 29,943.92. The path did not hold. The low went 329.17 points beneath S2, though the settle finished 121.83 above it. The high stopped 149.67 beneath that Pivot Point, and the bar cannot say whether any rebound came first. The downside alternative was a fall through two standard deviations support at 29,429.29 that would bring Pivot S3 at 29,206.08 into play. The low went through both, by 318.29 and 95.08 points. The upside alternative, a settle above Pivot R1, never came close.
A 159.49 point basis, a band beneath the settle and five averages overhead
The basis narrowed to 159.49 points, the 29,562.00 settle less the 29,402.51 cash close, from 166.34 on Wednesday. The review converts five positioning levels at it. The modeled gamma-flip level at NDX 29,514 becomes 29,673.49, the modeled volatility threshold at NDX 29,590 becomes 29,749.49 and the call side ceiling at NDX 29,675 becomes 29,834.49. The NDX 30,000 strike, home of the largest gamma concentration, becomes 30,159.49. The 29,000 strike becomes 29,159.49. The conversions are the review's own. Only the last sits beneath the settle.
Resistance starts 19.75 points up, at the 5-day average at 29,581.75. Then a tight knot. The 9-day crossing price at 29,591.59, the 9-day average at 29,606.25, the published target price at 29,610.22 and the 3-10-16 day MACD stall level at 29,614.93 sit within 23.34 points. Friday's 29,630 stop sits 15.07 above the last of them.
Higher up, the 29,673.49 flip equivalent and Wednesday's 29,674.25 low sit 0.76 apart. The 9-day average stall level at 29,722.50 and the 29,749.49 threshold equivalent follow. Thursday's 29,793.50 open and 29,794.25 high sit 0.75 apart. Then come the 29,834.49 ceiling equivalent, Pivot R1 at 29,867.17 and one standard deviation resistance at 29,896.58. The 100-day average at 29,947.50, Wednesday's 29,979.50 settle, the 38.2 percent retracement from the four-week low at 29,991.47 and two standard deviations resistance at 30,035.17 come next. Seven more sit between 30,079.03 and 30,178.00. They are the 18-day crossing price at 30,079.03, the 50-day average at 30,087.00, the one-ATR line at 30,125.92, three standard deviations resistance at 30,141.52, the 30,159.49 strike equivalent, Pivot R2 at 30,172.33 and Wednesday's 30,178.00 high. The 40-day crossing price at 30,211.24, the 20-day average at 30,260.25 and Pivot R3 at 30,550.42 form the extended band. The 31,616.50 52-week, 13-week and one-month high caps the list, 2,054.50 points up.
Support starts 7.37 points down, at the 50 percent retracement of the 13-week range at 29,554.63. The 3-10 day crossover stall level at 29,513.46 and the Pivot Point at 29,489.08 follow. Both lie inside Friday's short band. Beneath it come the 14-day %K stochastic stall level at 29,361.60, one standard deviation support at 29,227.42 and Pivot S1 at 29,183.92. The 29,159.49 strike equivalent sits 24.43 beneath S1 and 48.49 above Thursday's 29,111.00 low. Two standard deviations support at 29,088.83 and the 38.2 percent retracement from the 13-week low at 29,068.02 follow.
Lower still, the one-ATR line at 28,998.08, the 28,987.00 one-month low of 10/23 and three standard deviations support at 28,982.48 sit within 15.60 points. Pivot S2 at 28,805.83 and Pivot S3 at 28,500.67 follow. The 200-day average at 28,442.25 lies beneath them all.
Five averages sit overhead. The settle sits 19.75 points beneath the 5-day at 29,581.75, 44.25 beneath the 9-day at 29,606.25, 385.50 beneath the 100-day at 29,947.50, 525.00 beneath the 50-day at 30,087.00 and 698.25 beneath the 20-day at 30,260.25. Only the 200-day, at 28,442.25, sits beneath it, by 1,119.75. The review computed the averages from 259 completed daily settlements, with the partial Friday row dropped, and rounded each once to the 0.25 tick. The 5-day rose 84.00 from Wednesday's 29,497.75 as the 10/22 settle of 29,142.00 left the window. The 20-day fell 60.00 from 30,320.25 as the 10/01 settle of 30,760.50 dropped out. The 50-day fell 4.75 from 30,091.75. Older settlements sit lower. The 30 older ones in the 50-day window averaged 29,971.30, the 50 older ones in the 100-day window 29,807.95 and the 100 older ones in the 200-day window 26,937.07. Friday's crossing prices are 29,591.59 for the 9-day, 30,079.03 for the 18-day and 30,211.24 for the 40-day.
Momentum slipped beneath the middle. Relative strength reads 42.52 on the 9-day, 43.61 on the 14-day and 45.24 on the 20-day. The raw stochastics read 48.28 percent on the 9-day and 24.98 percent on the 14-day. The 14-day %K at 33.79 percent sits 5.84 points above %D at 27.95 percent. Sellers lead both windows. On the 9-day, negative direction at 30.48 tops positive at 17.93 by 12.55, with the ADX at 33.97; on the 14-day, 28.99 tops 17.72 by 11.27, with the ADX at 24.85. Historic volatility reads 21.23 percent and 21.20 percent. These readings are as published, read at 6:21 PM ET on Thursday after the 6:00 PM ET reopen. They may already blend in the reopened session's quote.
A composite multi-indicator read published for Friday sits at 16 percent sell, with strength described as minimum and direction as average, against 24 percent buy in the prior session's snapshot. A week ago it read 40 percent sell. A month ago, 80 percent buy. The short-horizon group averages 40 percent sell, the medium 25 percent buy, and the long group reads hold. The trend indicator reads sell.
Thursday's bar closed beneath its open. The settle finished 231.50 points beneath the 29,793.50 open, with an upper shadow of only 0.75 points above the open and a lower shadow of 451.00 points beneath the settle. The high sat 383.75 points beneath Wednesday's and the low 563.25 beneath Wednesday's. The 683.25 point range was 1.14 times the 14-day average daily range of 599.00. The 14-day average true range stands at 563.92 points; the 9-day figures are 593.19 and 586.92 and the 20-day figures 546.25 and 549.72, all read after the reopen with the same caveat as the oscillators.
One average true range either side of the settle spans 28,998.08 to 30,125.92. The deviation bands, built from five settlements and centred on the settle, run 29,227.42 to 29,896.58, 29,088.83 to 30,035.17 and 28,982.48 to 30,141.52. They describe settlement dispersion only. The provider's overview showed the reopened session between 29,112.50 and 29,180.00 at the time of capture, wholly beneath the lower one-deviation line; its high sat 47.42 beneath it. Ten sessions of daily ranges read 956.25, 757.50, 511.75, 385.50, 960.25, 339.00, 548.00, 593.25, 503.75 and 683.25 points. The settlement changes over those sessions net to minus 581.75. Over five sessions the contract is still up 420.00 points from the 29,142.00 settle of 10/22. No four-hour series was captured, so the swing read rests on daily bars.
A 1.38 percent cash decline, a 1.42 percent chip slide and results after the close
Technology led the decline. The Nasdaq-100 cash index closed at 29,402.51, down 410.65 points or 1.38 percent. The S&P 500 cash index fell 0.30 percent and the Dow industrials 0.25 percent. On unrounded closes, technology underperformed the broad market by 1.07 percentage points. The semiconductor index fell 165.80 points, or 1.42 percent, to 11,518.20, after trading between 11,620.79 and 11,363.81.
One large company drew the headlines. The news feed carried at 9:33 AM ET an item that a search-engine group's shares fell 13 percent after its results. Those results came after Wednesday's close, as the calendar lists them. The provider's commentary attributed the decline in stocks to the group's disappointing sales, a fall in a large Korean chipmaker's shares and a drop in a machinery maker after its guidance. All of that is attributed and not verified independently. The same commentary said the Korean chipmaker's fall of nearly 4 percent weighed on US chip stocks. That is the provider's framing. The review measured no such relationship. The news feed's market wrap described a rotation out of large technology shares into the broader market as bonds rallied.
Debt ran through the day too. The news feed carried at 7:31 AM ET and 12:21 PM ET items that a software maker launched a high-grade bond offering expected to raise about 25 billion dollars. At 10:13 AM ET it carried the European Central Bank President saying debt issuance by large cloud providers plays a role in the rise in yields. At 11:23 AM ET the news feed carried a regulatory vote on Chinese testing laboratories. At 2:51 PM ET it carried a statement from the largest US chip designer's chief executive addressing a press report about a customer.
Then the results. An online retailer and a processor maker reported after the cash close, as the calendar lists them. Per the news feed, the online retailer reported earnings per share of 1.89 dollars against an estimate of 1.97 and net sales of 201.9 billion dollars against 202.26 billion. Its cloud sales of 45.98 billion beat the 45.68 billion estimate, per the news feed. The processor maker reported adjusted earnings per share of 0.52 dollars against 0.41, per the news feed, with revenue of 16.51 billion against 16.54 billion. The feed headlined both as disappointing at 4:14 PM ET. Both fell sharply in extended trading, as described in market commentary from the provider. Those moves came after the cash close. So they are not part of Thursday's settlement.
The data came first. Advance GDP and the personal income and outlays report were released at 8:30 AM ET, as the calendar lists them. Per the news-feed calendar and unconfirmed, GDP grew 3.4 percent against a 3.2 percent forecast and the PCE price index rose 3.6 percent from a year earlier, in line with the forecast. Two more items followed. The European Central Bank decision at 9:15 AM ET, per the news-feed calendar and unconfirmed, held the main rate at 2.65 percent. The seven-year note auction at 1:00 PM ET stopped at 4.894 percent, per the news-feed calendar and unconfirmed. The provider's ten-year yield record closed at 4.99 percent against 5.04 percent on Wednesday. Rate pricing is attributed. The provider's commentary reported that markets price a 78 percent chance of a rate increase at the December FOMC meeting, a figure attributed and not verified independently. No real-yield series was captured, so no real-yield level is asserted.
Geopolitical items ran through the afternoon. At 1:54 PM ET and 1:55 PM ET the news feed carried maritime security reports of a tanker struck in the Strait of Hormuz. At 3:13 PM ET it carried a press report that the top US regional commander briefed the President on military options for Iran. After the close the news feed carried claims by Yemen's Houthis of attacks on three Saudi oil facilities. These are reports carried by the feeds rather than events confirmed. No causal link to the index is asserted.
Crude eased. December WTI settled at 102.00, down 0.76 percent. The dollar index closed at 102.04 against 102.19. December gold settled at 4,031.4, down 0.50 percent. The volatility index rose to 17.20 from 16.91.
The cash close sits beneath four positioning lines. The dealer-positioning dataset's reference prices are the prior session's closes: NDX 29,813 corresponds to Wednesday's 29,813.16 cash close, and QQQ 725 to the fund's previous close of 725.61. Against Thursday's 29,402.51 close, the index sits 111.49 points beneath the 29,514 modeled gamma-flip level, 187.49 beneath the 29,590 modeled volatility threshold and 272.49 beneath the 29,675 call side ceiling. It sits 597.49 points beneath 30,000, the strike with the largest gamma concentration. The put side support base at 28,000 lies 1,402.51 points beneath the close. The index model's gamma tilt reads 1.199 and its gamma notional 6.632 million dollars, both model outputs. The dataset lists 30,000, 29,675, 29,000 and 31,000 as key index strikes.
On the QQQ proxy the call side ceiling sits at 760, the modeled gamma-flip level at 729, the modeled volatility threshold at 725, the largest gamma concentration at 720 and the put side support base at 700. Those are proxy levels. The fund's gamma tilt reads 0.772 and its gamma notional minus 306.448 million dollars, proxy model outputs. The console, read at 6:23 PM ET with a page date of 2026-10-29, shows the hedge level at 725. On the console, call gamma reads minus 1.77 billion against put gamma of minus 2.3 billion. One-month implied volatility reads 20.59 percent against realised volatility of 18.69 percent. That puts implied 1.90 points above realised, with the consumer-electronics maker's results still ahead. The implied-volatility rank reads 39.01 percent, the skew rank 72.40 percent and the put-to-call open-interest ratio 1.39.
In the review's interpretation, drawn from the index model and the QQQ fund proxy, an index close beneath the flip level, the threshold and the call side ceiling, with index gamma notional only marginally positive and the fund's negative, describes an environment in which dealer hedging gives little damping and can extend moves. Gamma stays a damping lens here. It carries no direction. The modeled threshold and flip level are model outputs, not option strikes, and no directional read is drawn from options volume or modeled gamma. Friday's band sits beneath the 29,673.49 flip equivalent and above the 29,159.49 equivalent of the 29,000 strike.
Activity jumped. Volume reached 794,700 contracts, against Wednesday's 609,592 on the 2026-10-28 row, a figure revised from the 600,583 carried in Thursday's outlook. Open interest reads 267,642 on that 2026-10-28 row, which Thursday's outlook listed as not yet reported. That is 494 above the 267,148 on the 2026-10-27 row. Thursday's figure is not yet reported. The weekly positioning report dated October 20 puts leveraged-fund longs at 51,749 contracts and shorts at 50,799, a net long of 950. Asset-manager longs stand at 109,985 and shorts at 32,195. The report predates the moves of the last seven sessions, and the next one is due after the Friday close.
The trade map for Friday
The primary setup is a short from 29,480 to 29,520. The composite reads 16 percent sell, and its trend indicator reads sell. Negative direction leads on both directional systems. The settle sits beneath every settlement average from the 5-day to the 100-day after a lower high and a lower low, and the cash index closed beneath the dataset's modeled flip level. The whole band sits beneath the settle. Its top sits 42.00 points down and its bottom 82.00. It holds two references. The Pivot Point at 29,489.08 sits 9.08 above its bottom, and the 3-10 day crossover stall level at 29,513.46 sits 6.54 beneath its top.
Then the stop. At 29,630 it sits 19.78 points above the 29,610.22 published target price and 43.49 beneath the 29,673.49 flip equivalent. All three targets sit beneath the settle. The first, 29,370, sits 8.40 above the 14-day %K stochastic stall level at 29,361.60. The second, 29,240, sits 12.58 above one standard deviation support at 29,227.42. Then the extended third. At 29,110 it sits 1.00 beneath Thursday's 29,111.00 low and 21.17 above two standard deviations support at 29,088.83. The reopened session traded well beneath the band at the time of capture; its 29,180.00 high sat 300.00 points beneath the band bottom. So the review calls the setup an analyst judgment that rebounds into the Pivot Point are sold, with no measured edge behind it.
Now the arithmetic. From the 29,500 midpoint the risk to the stop is 130 points, 23.1 percent of the 14-day average true range of 563.92. The targets sit 130, 260 and 390 points beneath the midpoint. Exact multiples. The first target sits 110.00 points beneath the band bottom and 192.00 beneath the settle. The second sits 322.00 beneath the settle. The third sits 452.00 beneath it.
The scenario ranges are analyst judgment. The low-range case runs 29,050 to 29,500, its top 62.00 beneath the settle, and the most likely 28,900 to 29,620. The high-range case runs 28,500 to 29,870. Pivot S3 sits 0.67 inside its bottom, and Pivot R1 2.83 inside its top. Then the sessions. Globex reopened at 6:00 PM ET on Thursday, and the review expects roughly 28,980 to 29,500 through the night, with a lower bias beneath the Pivot Point. London follows at 28,950 to 29,520, bias lower, with Pivot S1 at 29,183.92 the pivot of the session. The morning band runs 28,900 to 29,620. The setup band's top sits 100.00 points beneath its top. The afternoon band runs 28,800 to 29,650. Pivot S2 sits 5.83 above its bottom and the 29,630 stop 20.00 beneath its top.
Friday's calendar starts overnight. Tokyo consumer prices are listed at 7:30 PM ET on Thursday and the Bank of Japan decision at 11:30 PM ET, both per the news-feed calendar and unconfirmed. German flash GDP is listed at 5:00 AM ET and euro-area flash GDP at 6:00 AM ET, both per the news-feed calendar and unconfirmed. An oil major reports at 6:30 AM ET, as the calendar lists it. Then the data. The employment cost index is scheduled for 8:30 AM ET, as the calendar lists it. The cash session opens at 9:30 AM ET. Federal Reserve speakers are listed at 12:00 PM ET and 12:30 PM ET, per the news-feed calendar and unconfirmed. Globex halts at 5:00 PM ET. It does not reopen until 6:00 PM ET on Sunday, November 1, the day US daylight saving time ends at 2:00 AM ET, as the calendar lists it. Two days of headline exposure separate Friday's settle from the next reopen. A consumer-electronics maker reports on Monday, November 2, as the calendar lists it, for the date only.
One path is weighted. In the review's analyst judgment the most probable path holds the contract between Pivot S2 at 28,805.83 and the published target price at 29,610.22. Within it, a rebound toward the Pivot Point that fails is weighted slightly above a sustained recovery of Thursday's settle. No measured frequency backs it. The alternative is a settle above the 29,610.22 target price after the 8:30 AM ET employment cost index, as the calendar lists it. That would open the 29,673.49 flip-level equivalent and the 29,722.50 stall level. On the other side sits two standard deviations support at 29,088.83. A fall through it at the cash open would bring the 28,987.00 one-month low and Pivot S2 into play without the rebound the setup needs. In the review's judgment the first-order event on Friday is the cash-session reaction at the 9:30 AM ET open to Thursday's after-hours results.
Friday's band sits between Thursday's settle, 42.00 points above it, and the reopened session's high, 300.00 points beneath it.
The complete data picture
Every number behind Friday’s plan, charted first, then the full level lists, then the complete numeric reference underneath.
Full numeric reference, every remaining figure from the session review
1. Executive Summary
The December Nasdaq-100 contract settled at 29,562.00 on Thursday, down 417.50 or 1.39 percent from Wednesday's settle of 29,979.50, after trading between 29,794.25 and 29,111.00, a 683.25 point daily range. The settle finished at 66.0 percent of the range, and the 683.25 point range was 1.14 multiples of the published 14-day average daily range of 599.00 points. Thursday's high sat 383.75 points beneath Wednesday's 30,178.00 high and Thursday's low sat 563.25 points beneath Wednesday's 29,674.25 low, so the session printed a lower high and a lower low and ended a run of three higher settles. The 417.50 point decline was the largest one-day decline since the 865.00 point decline of 10/22, and the 683.25 point range was the widest since the 960.25 point range of 10/22.
The cash index closed at 29,402.51, down 410.65 or 1.38 percent, while the S&P 500 cash index fell 0.30 percent and the Dow industrials 0.25 percent, so, on unrounded closes, technology underperformed the broad market by 1.07 percentage points. The semiconductor index fell 1.42 percent to 11,518.20. The news feed carried at 9:33 AM ET an item that a search-engine group's shares fell 13 percent after its results, and the provider's commentary attributed the decline in stocks to that group's disappointing sales, a fall in a large Korean chipmaker's shares and a drop in a machinery maker after its guidance, all attributed and not verified independently.
After the close, results from an online retailer and a processor maker were released on Thursday, October 29, 2026, as the calendar lists them. Per the news feed, the online retailer reported earnings per share of 1.89 dollars against an estimate of 1.97 and net sales of 201.9 billion dollars against 202.26 billion, with cloud sales of 45.98 billion against 45.68 billion, and the processor maker reported adjusted earnings per share of 0.52 dollars against 0.41 with revenue of 16.51 billion against 16.54 billion. Both fell sharply in extended trading, as described in market commentary from the provider, and the provider's overview showed the reopened Friday session trading near 29,172 at the time of capture, beneath Pivot S1 at 29,183.92.
The composite multi-indicator read is "16% SELL", against "24% BUY" in the prior session's snapshot, with negative direction leading on both directional systems and the settle beneath every settlement average from the 5-day to the 100-day. The published 14-day average true range is 563.92 points. The Primary Setup below is a short from the 29,480 to 29,520 band around the Pivot Point at 29,489.08, stopped at 29,630 above the published target price at 29,610.22, with objectives at 29,370, 29,240 and an extended 29,110.
2. Price Action & Technical Structure
2.1 Intraday and Session Review
The Thursday session opened at 29,793.50 at the Wednesday 6:00 PM ET reopen, 186.00 points beneath Wednesday's settle, marked a daily high of 29,794.25 and a daily low of 29,111.00, and settled at 29,562.00 at 4:00 PM ET. This review makes no claim about the order in which the high and the low printed; the daily bar fixes the open, the extremes and the settle, and that is the evidence used here.
The settle sits 451.00 points above the low and 232.25 points beneath the high. The body of the daily bar measures 231.50 points from the 29,793.50 open down to the 29,562.00 settle, with an upper shadow of 0.75 points above the open and a lower shadow of 451.00 points beneath the settle.
Globex reopened at 6:00 PM ET, so the open, high and low shown on the provider's overview page, 29,180.00, 29,180.00 and 29,112.50, belong to the new Friday session and not to Thursday's completed session. The provider's previous close of 29,562.00 is Thursday's settle.
Thursday's completed-session extremes are the completed-session inputs behind the published pivot ladder rather than an independently read bar. Pivot R3 at 30,550.42 minus Pivot S3 at 28,500.67, divided by three, returns 683.25, and Pivot R2 at 30,172.33 minus Pivot S2 at 28,805.83, divided by two, returns the same 683.25. Three times the Pivot Point of 29,489.08 less the 29,562.00 settle gives a high plus low sum of 58,905.24, which the pair of 29,794.25 and 29,111.00 reproduces to within the published rounding at 58,905.25, and that pair reproduces all seven published rungs.
The provider's settlement row and the chart's completed daily bar carry the same 29,793.50 open, 29,794.25 high, 29,111.00 low and 29,562.00 settle.
2.2 Daily Structure
Thursday's 29,794.25 high sits 383.75 points beneath Wednesday's 30,178.00, and the 29,111.00 low sits 563.25 points beneath Wednesday's 29,674.25, so the session printed a lower high and a lower low after three sessions of higher highs and higher lows. The low stayed 124.00 points above the one-month low of 28,987.00 set on 10/23.
Settlements over the last seven sessions read 30,007.00, 29,142.00, 29,117.75, 29,437.25, 29,812.00, 29,979.50 and 29,562.00. The provider publishes 31,616.50 as the 52-week, 13-week and one-month high and 28,987.00 as the one-month low. Over five sessions the contract is up 420.00 points from the 29,142.00 settle of 10/22.
The December settle stood 159.49 points above the 29,402.51 cash close, against 166.34 points on Wednesday, both measured as the settle less the provider's cash close from the same completed-session daily records.
2.3 4-Hour and Swing Structure
Daily ranges for the last ten sessions ran 956.25, 757.50, 511.75, 385.50, 960.25, 339.00, 548.00, 593.25, 503.75 and 683.25, and the settlement changes over the same ten sessions read minus 752.25, plus 331.00, minus 47.25, plus 331.75, minus 865.00, minus 24.25, plus 319.50, plus 374.75, plus 167.50 and minus 417.50.
The retracement grid published for Friday places the 50 percent retracement of the 13-week range at 29,554.63, the 38.2 percent retracement from the 13-week low at 29,068.02 and the 38.2 percent retracement from the four-week low at 29,991.47. No four-hour series was captured, so swing structure here rests on daily bars only.
2.4 Moving Averages
The averages cited in this subsection were computed from the provider's daily settlement series for the December contract, which holds 259 completed sessions through Thursday; the partial Friday row of the reopened Globex session was dropped before counting. Each average is carried at full precision and rounded once to the 0.25 tick. The 5-day average stands at 29,581.75, the 9-day at 29,606.25, the 20-day at 30,260.25, the 50-day at 30,087.00, the 100-day at 29,947.50 and the 200-day at 28,442.25.
The 29,562.00 settle sits 19.75 points beneath the 5-day average, 44.25 points beneath the 9-day, 698.25 points beneath the 20-day, 525.00 points beneath the 50-day and 385.50 points beneath the 100-day, and 1,119.75 points above the 200-day. The 5-day average rose from Wednesday's 29,497.75, because the 10/22 settle of 29,142.00 left the window and was replaced by 29,562.00. The 20-day fell from 30,320.25 as the 10/01 settle of 30,760.50 left that window, and the 50-day fell from 30,091.75.
The 20-day average sits above the 50-day because the 30 older settlements in the 50-day window averaged lower, at 29,971.30. The 50-day sits above the 100-day because the 50 older settlements in the 100-day window averaged lower, at 29,807.95, and the 100-day sits above the 200-day because the 100 older settlements in the 200-day window averaged lower, at 26,937.07. The projection grid gives the prices at which each average would be crossed on Friday: 29,591.59 for the 9-day, 30,079.03 for the 18-day and 30,211.24 for the 40-day.
2.5 Oscillator and Trend Readings
The oscillator figures below are as published on the provider's technical page, read at 6:21 PM ET on Thursday after the 6:00 PM ET reopen, so the provider may already be blending the reopened session's quote into them; they are the provider's published readings and were not computed here. The 9-day relative strength reads 42.52, the 14-day relative strength 43.61 and the 20-day relative strength 45.24.
The 9-day raw stochastic reads 48.28 percent and the 14-day raw stochastic 24.98 percent, while the 14-day stochastic %K reads 33.79 percent and the 14-day stochastic %D 27.95 percent.
The 9-day directional index ADX reads 33.97 with the 9-day +DI at 17.93 and the 9-day -DI at 30.48; the 14-day directional index ADX reads 24.85 with the 14-day +DI at 17.72 and the 14-day -DI at 28.99, so negative direction leads on both. The 9-day historic volatility reads 21.23 percent and the 14-day historic volatility 21.20 percent.
The composite multi-indicator read published for the Friday session is "16% SELL", against the prior session's snapshot of "24% BUY", with signal strength described as "Minimum" and direction as "Average". The snapshot history reads "40% SELL" a week ago and "80% BUY" a month ago. The short-horizon group averages "40% SELL", the medium-horizon group "25% BUY" and the long-horizon group "HOLD", and the composite trend indicator reads sell.
2.6 Volatility and Expected Range
The published 14-day average true range stands at 563.92 points and the 14-day average daily range at 599.00 points; the 9-day average true range is 593.19 with a 9-day average daily range of 586.92, and the 20-day average true range is 546.25 with a 20-day average daily range of 549.72. These were read after the reopen and carry the same caveat as the oscillators. Thursday's 683.25 point range was 1.14 multiples of the 14-day average daily range.
Adding and subtracting the 14-day average true range of 563.92 points from the 29,562.00 settle frames Friday between 28,998.08 and 30,125.92. The published standard-deviation bands are built from five settlements: one deviation spans 29,227.42 to 29,896.58, two spans 29,088.83 to 30,035.17 and three spans 28,982.48 to 30,141.52. These bands describe settlement dispersion, not intraday reach, and the reopened session already traded beneath the lower one-deviation band at the time of capture, its 29,180.00 high 47.42 points beneath 29,227.42.
3. Key Levels
3.1 Resistance
Above the 29,562.00 settle, the first overhead reference is the 5-day average at 29,581.75, then the 9-day average crossing price at 29,591.59, the 9-day average at 29,606.25, the published target price at 29,610.22 and the 3-10-16 day MACD stall level at 29,614.93, followed by the 29,673.49 conversion of the flip level, Wednesday's 29,674.25 low, the 9-day average stall level at 29,722.50, the 29,749.49 conversion of the threshold, Thursday's 29,793.50 open and Thursday's 29,794.25 high. The 29,834.49 conversion of the call side ceiling, Pivot R1 at 29,867.17, one standard deviation resistance at 29,896.58, the 100-day average at 29,947.50, Wednesday's 29,979.50 settle, the 38.2 percent retracement from the four-week low at 29,991.47 and two standard deviations resistance at 30,035.17 form the next band. The 18-day crossing price at 30,079.03, the 50-day average at 30,087.00, the one-ATR line at 30,125.92, three standard deviations resistance at 30,141.52, the 30,159.49 conversion of the 30,000 strike, Pivot R2 at 30,172.33 and Wednesday's 30,178.00 high are the extended references, with the 40-day crossing price at 30,211.24, the 20-day average at 30,260.25 and Pivot R3 at 30,550.42 beyond.
3.2 Support
Beneath the settle sits the 50 percent retracement of the 13-week range at 29,554.63, the 3-10 day crossover stall level at 29,513.46 and the Pivot Point at 29,489.08, then 29,361.60, the 14-day %K stochastic stall level. One standard deviation support at 29,227.42, Pivot S1 at 29,183.92 and the 29,159.49 conversion of the 29,000 strike sit above Thursday's 29,111.00 low and two standard deviations support at 29,088.83. The 38.2 percent retracement from the 13-week low at 29,068.02, the one-ATR line at 28,998.08, the one-month low at 28,987.00, three standard deviations support at 28,982.48, Pivot S2 at 28,805.83 and Pivot S3 at 28,500.67 are the extended references, with the 200-day average at 28,442.25 beneath them.
4. Macro Drivers
4.1 Largest-Company Results and the AI Spending Cycle
A search-engine group's results, released after the close on Wednesday, October 28, 2026, as the calendar lists them, dominated Thursday's cash session in the review's reading: the news feed carried at 9:33 AM ET an item that the shares fell 13 percent, and the provider's commentary attributed the index decline partly to the group's disappointing sales. The news feed also carried at 7:31 AM ET and 12:21 PM ET items that a software maker launched a high-grade bond offering expected to raise about 25 billion dollars, and at 10:13 AM ET the European Central Bank President saying debt issuance by large cloud providers plays a role in the rise in yields.
Results from the online retailer and the processor maker were released after the close on Thursday, October 29, 2026, as the calendar lists them. Per the news feed, the online retailer's earnings per share of 1.89 dollars missed the 1.97 estimate and net sales of 201.9 billion dollars missed the 202.26 billion estimate, while cloud sales of 45.98 billion beat the 45.68 billion estimate; the processor maker's adjusted earnings per share of 0.52 dollars beat the 0.41 estimate while revenue of 16.51 billion missed the 16.54 billion estimate. The feed headlined both as disappointing at 4:14 PM ET, and both fell sharply in extended trading, as described in market commentary from the provider. A consumer-electronics maker's results are due on Monday, November 2, 2026, as the calendar lists them, for the date only.
4.2 Semiconductor Cycle and Tech Sector Rotation
The semiconductor index closed at 11,518.20, down 165.80 or 1.42 percent, after trading between 11,620.79 and 11,363.81. The provider's commentary said a fall of nearly 4 percent in a large Korean chipmaker's shares after its results weighed on US chip stocks; that is the provider's framing, not a relationship measured. The news feed carried at 2:51 PM ET a statement from the largest US chip designer's chief executive addressing a press report about a customer, and at 11:23 AM ET a regulatory vote on Chinese testing laboratories.
The Nasdaq-100 cash index's 1.38 percent decline compared with 0.30 percent for the S&P 500 cash index and 0.25 percent for the Dow industrials. The news feed's market wrap described a rotation out of large technology shares into the broader market as bonds rallied.
4.3 Fed Policy and Real Yields (Duration Sensitivity)
The advance GDP estimate and the personal income and outlays report were released at 8:30 AM ET on Thursday, October 29, 2026, as the calendar lists it. Per the news-feed calendar and unconfirmed, GDP grew 3.4 percent against a 3.2 percent forecast and the PCE price index rose 3.6 percent from a year earlier, in line with the forecast. The provider's ten-year yield record closed at 4.99 percent; Wednesday's close was 5.04 percent. The provider's commentary reported that markets price a 78 percent chance of a rate increase at the December FOMC meeting, a figure attributed and not verified independently. No real-yield series was captured, so no real-yield level is asserted.
4.4 Geopolitical Backdrop
The news feed carried at 1:54 PM ET and 1:55 PM ET maritime security reports of a tanker struck in the Strait of Hormuz, at 3:13 PM ET a press report that the top US regional commander briefed the President on military options for Iran, and after the close claims by Yemen's Houthis of attacks on three Saudi oil facilities. December WTI crude settled at 102.00, down 0.76 percent. These are reports carried by the feeds rather than events confirmed.
4.5 Cross-Asset and Volatility
The volatility index closed at 17.20; Wednesday's close was 16.91. The dollar index closed at 102.04 against 102.19. Gold's December contract fell 0.50 percent to 4,031.4. The fund's one-month implied volatility of 20.59 percent against realised volatility of 18.69 percent, read on the QQQ console at 6:23 PM ET, puts implied 1.90 points above realised with the consumer-electronics maker's results still ahead.
4.6 Institutional Positioning
The weekly positioning report dated October 20, shown on the provider's overview, puts leveraged-fund long positions at 51,749 contracts and short positions at 50,799, and asset-manager long positions at 109,985 against short positions of 32,195. The report predates the moves of the last seven sessions, and the next report is due after the Friday close.
Open interest on the December contract is shown at 267,642 for Wednesday, on the 2026-10-28 row of the provider's record, against 267,148 for Tuesday on the 2026-10-27 row, and Thursday's open interest is not yet reported; Thursday's December volume was 794,700 contracts, against 609,592 on Wednesday's 2026-10-28 row, revised from the 600,583 carried in Thursday's outlook.
5. QQQ Options Flow Context (Proxy)
This review uses the QQQ fund and the index columns of the dealer-positioning dataset as the proxy for the positioning data available. The dataset's reference prices are the prior session's closes: NDX 29,813 corresponds to Wednesday's 29,813.16 cash close and QQQ 725 corresponds to the fund's previous close of 725.61 shown on the console.
On the index the modeled volatility threshold sits at NDX 29,590, the call side ceiling at NDX 29,675, the largest gamma concentration at NDX 30,000, the modeled gamma-flip level at NDX 29,514 and the put side support base at NDX 28,000. Against Thursday's 29,402.51 cash close, the close sits 187.49 points beneath the threshold, 111.49 points beneath the flip level, 272.49 points beneath the call side ceiling and 597.49 points beneath the 30,000 strike, and 1,402.51 points above the put side base. Index gamma tilt reads 1.199 and gamma notional 6.632 million dollars, both model outputs, and the key index strikes are NDX 30,000, 29,675, 29,000 and 31,000.
On the fund the modeled volatility threshold sits at 725, the largest gamma concentration at 720, the call side ceiling at 760, the modeled gamma-flip level at 729 and the put side support base at 700. Fund gamma tilt reads 0.772 and gamma notional minus 306.448 million dollars, proxy model outputs. The modeled threshold and flip level are model outputs, not option strikes.
At the measured 159.49 point basis, the December settle of 29,562.00 less the 29,402.51 cash close, this review converts the index flip level to 29,673.49, the threshold to 29,749.49, the call side ceiling to 29,834.49, the 30,000 strike to 30,159.49 and the 29,000 strike to 29,159.49 in December futures terms. These conversions are this review's, not the dataset's.
The QQQ console, read at 6:23 PM ET with a page date of 2026-10-29, shows the hedge level at 725, call gamma of minus 1.77 billion against put gamma of minus 2.3 billion, one-month implied volatility of 20.59 percent against realised volatility of 18.69 percent, an implied-volatility rank of 39.01 percent, a skew rank of 72.40 percent and a put-to-call open-interest ratio of 1.39. The console's high and low volatility point fields are not carried.
In this review's interpretation, drawn from the index model and the QQQ fund proxy, both model outputs, an index close beneath the flip level, the threshold and the call side ceiling, with index gamma notional only marginally positive and the fund's negative, describes an environment in which dealer hedging gives little damping and can extend moves; gamma is read as a damping lens with no direction. The setup in section 8 sells the 29,480 to 29,520 band, beneath the 29,673.49 conversion of the flip level and above the 29,159.49 conversion of the 29,000 strike.
6. Forecast
6.1 Night Session (6:00 PM ET Thursday to 3:00 AM ET Friday, Globex and Asia)
Globex reopened at 6:00 PM ET on Thursday, October 29, 2026, and the provider's overview showed the new session trading between 29,112.50 and 29,180.00 at the time of capture, beneath Thursday's settle after the online retailer's and the processor maker's results. Tokyo consumer prices are listed at 7:30 PM ET and the Bank of Japan decision at 11:30 PM ET on Thursday, October 29, 2026, both per the news-feed calendar and unconfirmed. Bias lower beneath the Pivot Point at 29,489.08, expected band roughly 28,980 to 29,500.
6.2 London Session (3:00 AM to 8:00 AM ET Friday)
German flash GDP is listed at 5:00 AM ET and euro-area flash GDP at 6:00 AM ET on Friday, October 30, 2026, both per the news-feed calendar and unconfirmed. Bias lower beneath the Pivot Point at 29,489.08, expected band roughly 28,950 to 29,520, with Pivot S1 at 29,183.92 the pivot of the session.
6.3 Morning Session (9:30 AM to 12:00 PM ET Friday, RTH Open)
The employment cost index is scheduled for 8:30 AM ET on Friday, October 30, 2026, as the calendar lists it, and the cash open at 9:30 AM ET is the first directional test of the after-hours reaction to Thursday's results. Expected band roughly 28,900 to 29,620, with the top of the 29,480 to 29,520 setup band 100.00 points beneath the top of that range.
6.4 Afternoon Session (12:00 PM to 4:00 PM ET Friday)
Federal Reserve speakers are listed at 12:00 PM ET and 12:30 PM ET on Friday, October 30, 2026, per the news-feed calendar and unconfirmed. Expected band roughly 28,800 to 29,650, with Pivot S2 at 28,805.83 5.83 points above the bottom and the 29,630 stop 20.00 points beneath the top.
6.5 Night Session Forward (6:00 PM ET Friday)
Globex halts at 5:00 PM ET on Friday and does not reopen until 6:00 PM ET on Sunday, November 1, 2026, the day US daylight saving time ends at 2:00 AM ET, as the calendar lists it. Two days of headline exposure therefore separate Friday's settle from the next reopen, and A consumer-electronics maker's results follow on Monday, November 2, 2026, as the calendar lists them, for the date only.
6.6 Expected Range (Friday Full Session)
Low-range scenario: 29,050 to 29,500; Mid-range scenario (most likely): 28,900 to 29,620; High-range scenario: 28,500 to 29,870.
6.7 Most Likely Path
In this review's analyst judgment the most probable path holds the contract between Pivot S2 at 28,805.83 and the published target price at 29,610.22, with a rebound toward the Pivot Point at 29,489.08 that fails weighted slightly above a sustained recovery of Thursday's settle. The composite reads "16% SELL" with negative direction leading on both directional systems, the settle sits beneath every average from the 5-day to the 100-day, and the cash index closed beneath the dataset's modeled flip level, while the reopened session already trading beneath the lower one-deviation band leaves room for a rebound first.
The alternative that would invalidate this reading is a settle above the 29,610.22 target price after the 8:30 AM ET employment cost index on Friday, October 30, 2026, as the calendar lists it, which would open the 29,673.49 flip-level conversion and the 29,722.50 stall level. On the other side, a fall through two standard deviations support at 29,088.83 at the cash open would bring the one-month low at 28,987.00 and Pivot S2 at 28,805.83 into play without the rebound the setup needs.
7. Friday Economic Calendar
Thursday's releases are complete. The advance GDP estimate and the personal income and outlays report were released at 8:30 AM ET on Thursday, October 29, 2026, as the calendar lists it; per the news-feed calendar and unconfirmed, GDP grew 3.4 percent and the PCE price index rose 3.6 percent from a year earlier. The European Central Bank decision released at 9:15 AM ET on Thursday, October 29, 2026, per the news-feed calendar and unconfirmed, held the main rate at 2.65 percent, and the seven-year note auction at 1:00 PM ET, per the news-feed calendar and unconfirmed, stopped at 4.894 percent. Results from the online retailer and the processor maker were released after the close on Thursday, October 29, 2026, as the calendar lists them.
On Friday, October 30, 2026 German flash GDP is listed at 5:00 AM ET and euro-area flash GDP at 6:00 AM ET, both per the news-feed calendar and unconfirmed. Results from an oil major are scheduled for 6:30 AM ET and the employment cost index for 8:30 AM ET on Friday, October 30, 2026, both as the calendar lists them. Federal Reserve speakers are listed at 12:00 PM ET and 12:30 PM ET on Friday, October 30, 2026, per the news-feed calendar and unconfirmed.
Later in the cycle, US daylight saving time ends at 2:00 AM ET on Sunday, November 1, 2026, as the calendar lists it. Results from a consumer-electronics maker and a data-analytics software group are due on Monday, November 2, 2026, and from a processor and graphics-chip maker on Tuesday, November 3, 2026, as the calendar lists them, for the date only, and the employment situation report is scheduled for 8:30 AM ET on Friday, November 6, 2026, as the calendar lists it. In this review's judgment the first-order event for the Nasdaq-100 on Friday is the cash-session reaction at the 9:30 AM ET open to Thursday's after-hours results, with the 8:30 AM ET employment cost index the first scheduled release.
8. Primary Trade Setup
Direction: Short
Rationale: The composite reads "16% SELL" with the composite trend indicator on sell, negative direction leads on the 9-day and 14-day directional systems, and the settle sits beneath every settlement average from the 5-day to the 100-day after a lower high and a lower low. The cash index closed beneath the dataset's modeled flip level, and a rebound into the 29,480 to 29,520 band around the Pivot Point at 29,489.08 offers a short with a defined risk point above the published target price. The reopened session already trades well beneath the band, so the setup is an analyst judgment that rebounds into the Pivot Point are sold, not a measured edge.
Entry Zone: 29,480 to 29,520
Stop Loss: 29,630 (above the published target price at 29,610.22 and beneath the 29,673.49 conversion of the modeled flip level)
Target 1 (T1): 29,370 (above 29,361.60, the 14-day %K stochastic stall level)
Target 2 (T2): 29,240 (above one standard deviation support at 29,227.42)
Target 3 (T3, extended): 29,110 (beneath Thursday's 29,111.00 low and above two standard deviations support at 29,088.83)
Risk-to-Reward: Approximately 1:1 to T1, 1:2 to T2, 1:3 to T3
Invalidation: A settle above the published target price at 29,610.22 negates the thesis. Short of that, the edge is removed by acceptance above the entry band and not by a touch, defined as two consecutive 30-minute closes above 29,520.
Macro override: A cash-session reversal of the after-hours declines in the online retailer and the processor maker, described in market commentary, or a labour-cost reading taken as easing pressure on rates, would support the index. In that scenario a move through the 29,630 stop invalidates the short before the targets, and the 29,673.49 flip-level conversion becomes the reference, 43.49 points beyond the stop and inside one 14-day average true range of 563.92 points.
Sources and methodology
This outlook is built from our session review of the December E-mini Nasdaq-100 contract, the December ’26 contract, prepared after Thursday's close on October 29, 2026 for the Friday, October 30, 2026 session. Thursday's open, high, low and settle come from the provider's daily settlement record for the December contract, the 2026-10-29 row, and match the chart's completed daily bar. Thursday's completed extremes are also the inputs behind the published pivot ladder: Pivot R3 at 30,550.42 less Pivot S3 at 28,500.67, divided by three, and Pivot R2 at 30,172.33 less Pivot S2 at 28,805.83, divided by two, both return 683.25, and three times the 29,489.08 Pivot Point less the settle gives 58,905.24, against 58,905.25 for the pair of 29,794.25 and 29,111.00, a difference within the published rounding. No intraday series was preserved for Thursday, so no statement in this article places a Thursday print at a time of day, and Thursday's card is graded against the daily bar alone. Thursday's session opened at the Wednesday 6:00 PM ET reopen, and Friday's session opened at the Thursday 6:00 PM ET reopen. The open, high and low on the provider's overview page, 29,180.00, 29,180.00 and 29,112.50, belong to that new Friday session and are not used as Thursday's range; the provider's previous close of 29,562.00 is Thursday's settle.
The moving averages are the review's, computed from the provider's daily settlement series for the December contract, 259 completed sessions with the partial Friday row dropped, and rounded once to the 0.25 tick. The oscillators and the average true and daily ranges are cited as published, read at 6:21 PM ET on Thursday after the 6:00 PM ET reopen, so the provider may already blend the reopened session's quote into them. Volume and open interest come from the provider's daily record: the 2026-10-29 row reads 794,700 contracts with open interest not yet reported, and the 2026-10-28 row now reads 609,592 contracts and open interest of 267,642, where Thursday's outlook carried 600,583 contracts and open interest not yet reported; the 2026-10-27 row reads open interest of 267,148. The weekly positioning report is dated October 20. The provider's ten-year yield record now reads 5.04 percent for Wednesday. The dealer-positioning dataset carries Wednesday's closes in its reference column; every Nasdaq futures equivalent is the review's conversion at the 159.49 point measured basis, the December settlement less the cash close, against 166.34 on Wednesday. The QQQ fund is a proxy read alongside the index levels. The reading that dealer hedging gives little damping and can extend moves is the review's interpretation from the index model and that proxy, both model outputs, and gamma is read as a damping lens with no direction; the fund console, dated 2026-10-29, was read at 6:23 PM ET. After-hours share moves for the two large companies that reported after the close are described in market commentary from the provider, and the reported results are per the news feed. The 1.07 point gap between the Nasdaq-100 and the S&P 500 is measured on unrounded closes. The volume and open-interest changes, the ten-session net change and the distances in this article are computed. Scenario ranges are analyst judgment, and items marked unconfirmed come from the news-feed calendar.
Thursday’s outlook for this contract is here, and the S&P 500 contract’s Thursday outlook covers the index that fell 0.30 percent in cash on Thursday. Outlooks for ES, NQ, GC and CL are collected on the market outlook page, and our forward trading record is on the performance statement.