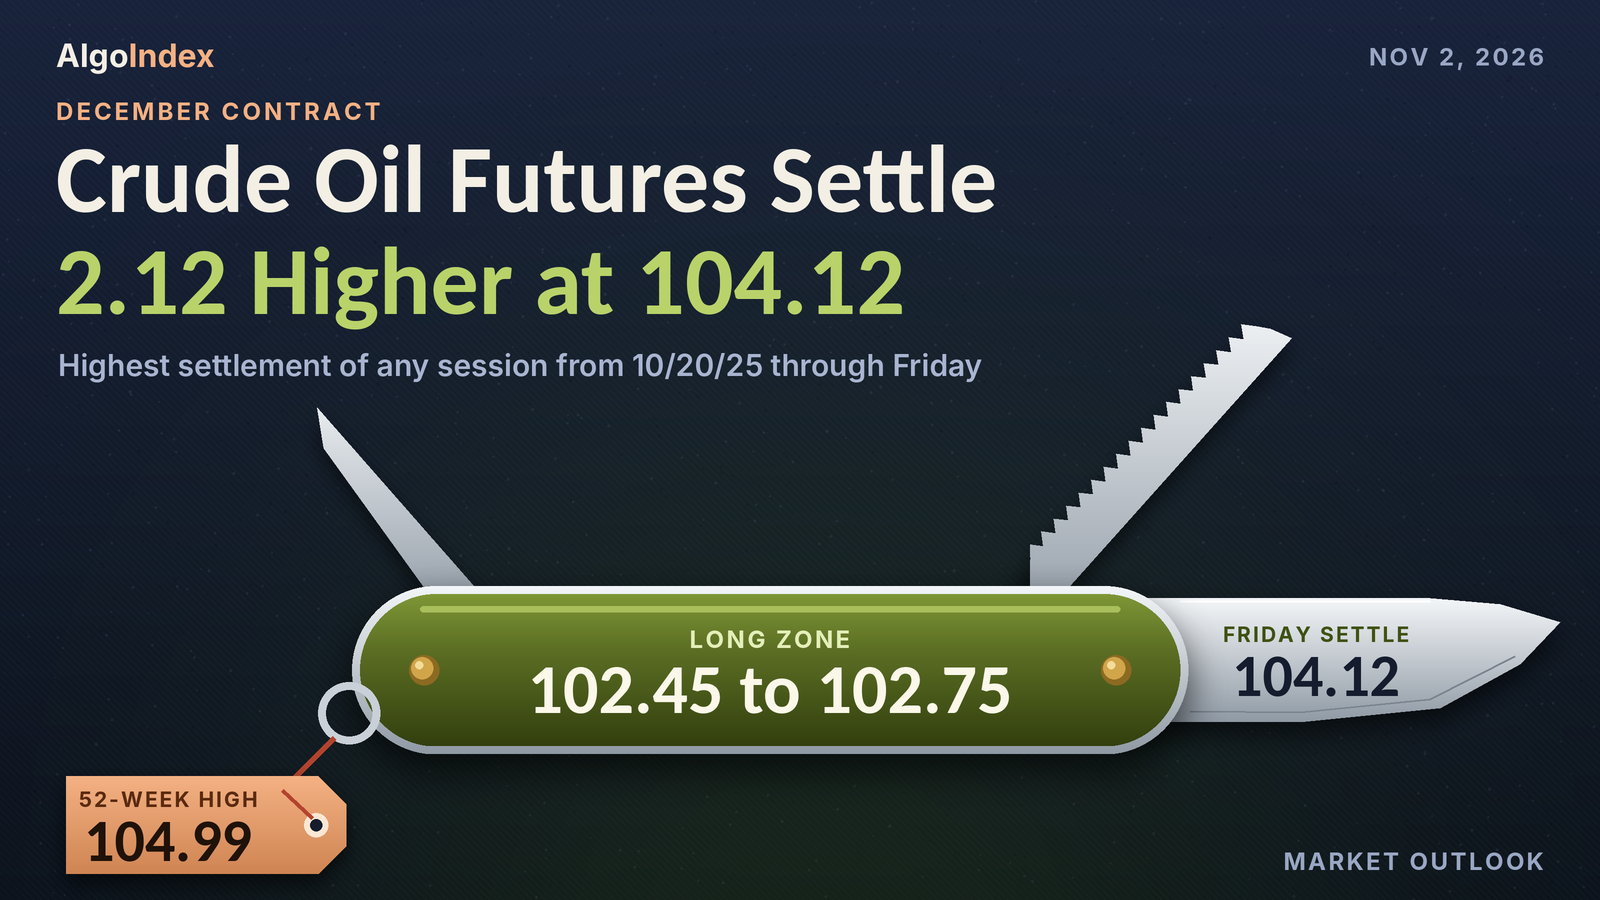
December crude settled at 104.12 on Friday, up 2.12 or 2.08 percent, after a 2.56 point session between 102.43 and 104.99. The settle finished at 66.0 percent of that range. It was a higher high and a higher low. The 104.99 high sat 1.99 above Thursday's 103.00, and the 102.43 low sat 2.64 above Thursday's 99.79. The range was 0.72 times the 14-day average daily range of 3.56 points. The settle is the highest of any session in the provider's record from 10/20/25 through Friday. The 104.99 high is the published 52-week, 13-week and one-month high.
Friday never came down to our band. The Friday card was a long from 100.85 to 101.15 with a 99.70 stop. The 102.43 low held 1.28 above the band's top, and the stop sat 2.73 beneath that low. The 30-minute bars put the low in the 9:00 PM ET bar on Thursday evening and the high in the 9:30 PM ET bar. That second bar carried price through the 103.60 and 104.75 target prices. With the band untouched, the card never came into play. No fill and no result are asserted.
Brent rose by more. Its December contract settled at 117.64, up 2.76 or 2.40 percent, and its premium over December WTI widened to 13.52 from 12.88. December now sits 1.91 above January, against 1.86 on Thursday. Heating oil rose 1.93 percent and gasoline 2.21 percent, so both product margins over crude widened. Crude rose while the S&P 500 cash index fell 1.82 percent and gold 3.29 percent.
Electronic trade after the 2:30 PM ET settle turned lower. The 3:00 PM ET and 3:30 PM ET bars took the contract from 104.16 to a 103.14 close. The 4:00 PM ET bar marked the post-settlement low of 102.64, and the 4:30 PM ET bar closed at 102.95, 1.17 beneath the settle, before the 5:00 PM ET halt. That move coincided with the news feed's reports of tanker incidents in the Strait of Hormuz and the President's remarks on talks with Iran; the series does not establish that either headline caused it. The 102.95 print is a post-settlement quote.
December crude settled at 104.12, up 2.12, at 66.0 percent of a 102.43 to 104.99 range. That settle is the highest in the provider's record from 10/20/25. It sits above all six settlement averages, 2.01 above the 5-day at 102.11. Resistance starts at the 104.92 projection and Friday's 104.99 high, then the 105.16 target price and Pivot R1 at 105.26. Support starts at the Pivot Point at 103.85, then Thursday's 103.00 high and the 102.95 post-settlement print. The setup is a long on the December contract from 102.45 to 102.75, around Pivot S1 at 102.70. The stop is 101.85, with targets at 103.35, 104.10 and an extended 104.85. The whole band sits beneath the settle. So do the first two targets, the second by 2 cents; only the extended target sits above it. Globex reopens at 6:00 PM ET on Sunday, November 1.
Friday's 102.43 low stayed 1.28 above the long band
First, the grading. In Friday's outlook we set a long on the December contract from 100.85 to 101.15, stop 99.70, with targets at 102.30, 103.60 and an extended 104.75. A settle beneath Pivot S1 at 100.19 would negate it. Two consecutive 30-minute closes beneath 100.85 would remove the edge. The card is graded on December's Friday bar, with the order of events taken from the preserved 30-minute bars.
December never came down. Its bar, from the provider's settlement row, opened at 102.80 at the Thursday 6:00 PM ET reopen. That was 1.65 above the band's top. It marked a high of 104.99 and a low of 102.43, and settled at 104.12. The band never traded. The low stopped 1.28 above its 101.15 top. The stop sat 2.73 beneath the low and never traded either.
Two target prices traded anyway. The whole session sat above the 102.30 first target, the low by 13 cents. The 103.60 second target and the extended 104.75 both printed, first in the 9:30 PM ET bar on Thursday evening. That bar ran from 102.73 to the 104.99 high. A long from the band needed the band to trade. With the band untouched, the card never came into play, so no fill and no result are asserted. No invalidation settle printed; the 104.12 settle sat 3.93 above the 100.19 line.
Our ranges gave way at the top. The low-range case of 101.20 to 103.40 broke at the top by 1.59. The most likely case of 100.60 to 103.90 broke at the top by 1.09. The high-range case of 99.40 to 105.60 held, with 61 cents to spare. One deviation, 100.71 to 103.29, gave way at the top by 1.70. Two deviations gave way at 103.83 by 1.16. Three deviations gave way at 104.24 by 75 cents. One average true range around Thursday's settle, 98.37 to 105.63, held by 64 cents at the top.
The session bands can be graded this time. Every one broke at its top. Globex, 6:00 PM ET to 3:00 AM ET, traded 102.43 to 104.99 against a 101.20 to 103.60 band, 1.39 over. London traded 102.84 to 104.54 against 101.00 to 103.80, 74 cents over. The morning traded 103.28 to 104.65 against 100.60 to 104.00, 65 cents over. The afternoon traded 103.99 to 104.98 against 100.20 to 104.30, 68 cents over. No session came within 1.23 of a band's bottom.
The weighted path expected a hold between Pivot S1 at 100.19 and two standard deviations resistance at 103.83. It pictured a dip toward 100.71. No dip came; the low stopped 1.72 above 100.71. The card's upside case came closest. It said a reopened session holding above Thursday's 103.00 high would put Pivot R1 at 103.40 and the 103.92 high of 10/23 in play without the dip. Nothing before the 9:30 PM ET bar reached 103.00. That bar traded through 103.00, 103.40, Wednesday's 103.55 high and 103.92. From the 3:30 AM ET bar to the settle, every 30-minute low held above 103.00, the lowest at 103.28. The alternative, a sustained move beneath 100.19, never developed. The macro override named a confirmed step toward a temporary peace arrangement with Iran. The review records no confirmed step.
The December band at 102.45 to 102.75, around Pivot S1 and beneath the settle
The map moved up 1.60, the gap between the two midpoints. Every price here is the December contract. The new band, 102.45 to 102.75, holds Pivot S1 at 102.70 and one standard deviation support at 102.58. Its bottom sits 2 cents above Friday's 102.43 low. The settle sits 1.37 above the band's top and 1.67 above its bottom. The 102.95 close of the last 30-minute bar sits 20 cents above the top. The stop at 101.85 sits 58 cents beneath Friday's low and 9 cents beneath two standard deviations support at 101.94.
Both of Friday's extremes came on Thursday evening. The session opened at 102.80 at the 6:00 PM ET reopen, 80 cents above Thursday's settle. The low printed in the 9:00 PM ET bar and the high in the 9:30 PM ET bar. From the 8:00 AM ET bar to the settle, the 30-minute bars held between 103.28 and 104.98. That 104.98 came in the 12:30 PM ET and 1:00 PM ET bars, a cent beneath the overnight high. Settlement came at 2:30 PM ET.
Friday printed a higher high and a higher low after Thursday's inside session. Settlements over seven sessions read 99.47, 103.27, 101.76, 99.90, 102.78, 102.00 and 104.12. The last four daily changes alternated: minus 1.86, plus 2.88, minus 0.78 and plus 2.12. Over five sessions the contract is up 85 cents from the 103.27 settle of 10/23. The weekly bar opened at 102.61, ran from 99.44 to 104.99 and closed at 104.12. The prior week ran from 95.25 to 103.92. So the week, too, printed a higher high and a higher low. The one-month low is 86.00, from 10/06. Friday's 2.56 range was the narrowest since 2.45 on 10/22.
The four-hour bars tell the late story. The 2:00 PM ET bar opened at 104.30 and closed at 102.95 after a 102.64 low. It was the widest decline of the session's six four-hour bars and the only one to close beneath 103.00. The hourly and 15-minute series carry the same post-settlement decline from the 3:00 PM ET hour.
Resistance starts 80 cents up, at the 104.92 relative strength projection, with Friday's 104.99 high 7 cents above it. The 105.16 target price, Pivot R1 at 105.26 and one standard deviation resistance at 105.66 form the next band. Two standard deviations resistance at 106.30 and Pivot R2 at 106.41 follow. Three standard deviations resistance at 106.79 and the 107.11 crossover stall level come next. The 107.71 top of one average true range sits between that stall level and Pivot R3 at 107.82. The review's list leaves it out.
Support starts 27 cents down, at the Pivot Point at 103.85. Thursday's 103.00 high and the 102.95 post-settlement print sit a nickel apart. Friday's 102.80 open and Wednesday's 102.78 settle follow. Then come Pivot S1 at 102.70, one standard deviation support at 102.58 and Friday's 102.43 low. The 102.16 projection, the 5-day average at 102.11 and Thursday's 102.00 settle come next; the review's list skips the 5-day. The 101.95 stall level and two standard deviations support at 101.94 sit a cent apart, above the stop. Beneath it sit three standard deviations support at 101.45, the 9-day crossing price at 101.31 and Pivot S2 at 101.29. The review's list also skips the 9-day average at 100.92 and the 100.53 bottom of one average true range. Pivot S3 at 100.14, Thursday's 99.79 low and the 99.44 weekly low follow. The long tail starts with the 18-day crossing at 97.88 and the 97.74 retracement. It runs through the 20-day at 96.41, the 95.49 retracement, the prior week's 95.25 low and the 93.25 and 92.01 retracements. Further down sit the 50-day at 91.04, the 86.00 one-month low, the 100-day at 82.96 and the 200-day at 77.61.
Every average sits beneath price. The settle is 2.01 above the 5-day at 102.11 and 3.20 above the 9-day at 100.92. It sits 7.71 above the 20-day at 96.41 and 13.08 above the 50-day at 91.04. The gaps to the 100-day at 82.96 and the 200-day at 77.61 are 21.16 and 26.51. The 5-day rose 17 cents from 101.94 as the 10/23 settle of 103.27 left the window. The 20-day rose 73 cents from 95.68 as the 10/02 settle of 89.43 left. The stack stays in order. The 30 older settlements in the 50-day window averaged 87.47, the 50 older ones in the 100-day window 74.87 and the 100 older ones in the 200-day window 72.27. Monday's crossing prices are 101.31 for the 9-day and 97.88 for the 18-day.
Momentum readings sit high on their scales. Relative strength reads 70.55 on the 9-day, 68.89 on the 14-day and 67.22 on the 20-day. The raw stochastics read 91.07 percent on the 9-day and 93.85 percent on the 14-day. The 14-day %K at 91.16 percent sits above %D at 86.94 percent. Positive direction leads on both windows. It reads 26.36 against 3.74 on the 9-day with the ADX at 61.99, and 25.92 against 5.18 on the 14-day with the ADX at 48.28. Historic volatility reads 31.23 percent and 27.92 percent. The composite multi-indicator read for Monday is 100 percent buy. Its signal strength is described as maximum and its direction as strongest. It read 100 percent buy for the prior session and a week ago, and 56 percent a month ago. The short, medium and long horizon groups each average 100 percent buy. These are the provider's published readings, read at 6:21 PM ET on Friday with Globex closed for the weekend.
Average ranges sit near 3.6 points. The 14-day average true range stands at 3.59 points and the 14-day average daily range at 3.56. The 9-day figures are 3.60 and 3.73 and the 20-day 3.52 and 3.45. One average true range either side of the settle spans 100.53 to 107.71. The deviation bands, built from five settlements and centred on the settle, run 102.58 to 105.66, 101.94 to 106.30 and 101.45 to 106.79. They describe dispersion only. The 102.95 post-settlement print already sits inside the one-deviation band, 37 cents above its lower edge. Ten sessions of daily ranges read 2.99, 6.12, 4.14, 2.45, 5.08, 2.80, 3.38, 3.80, 3.21 and 2.56.
Gulf reports, a 13.52 Brent premium and wider product margins
The news flow came late in the day. At 2:34 PM ET the news feed carried a press report that a Qatari delegation arrived in Tehran for talks. Two more items followed. At 2:47 PM ET the news feed carried a report from Yemen's government that the Houthis attacked Aden airport and the presidential palace complex. At 3:07 PM ET the news feed carried a maritime security report of a vessel hit by an unknown projectile 40 nautical miles south of Lavan Island.
More came after the settle. At 4:01 PM ET the news feed carried the President's remarks that "there are talks" with Iran and "we have time". Tanker reports followed. At 4:03 PM ET the news feed carried an Iranian state media report that a fourth tanker exploded after striking a mine in the Strait of Hormuz. At 4:18 PM ET the news feed carried a maritime security report of a crude tanker hit by a projectile in the strait. These are reports carried by the feeds rather than events confirmed for this review. They coincided with the post-settlement decline, and the series does not establish that any of them caused it.
The provider's commentary cited a reported Ukrainian strike on a refinery in Russia's Samara region. These are reports carried by the feeds and attributed commentary, not events confirmed for this review.
One scheduled supply event falls on the weekend. The calendar lists the seven participating producers' monthly meeting on December output for Sunday, November 1, 2026, for the date only. Whether any decision is published before the 6:00 PM ET Sunday reopen is not known. The review does not anticipate its outcome.
No inventory report came on Friday. The calendar lists the last weekly petroleum status report at 10:30 AM ET on Wednesday, October 28, 2026. It showed a crude draw of 1.892 million barrels, per the news-feed calendar and unconfirmed, a figure the provider's commentary also cited. The calendar lists the next report for 10:30 AM ET on Wednesday, November 4, 2026. Thursday's Energy Department statement on a 16.75 million barrel reserve loan, carried by the news feed, was covered in Friday's outlook.
Products rose with crude. In the provider's daily record December heating oil settled at 4.6761 dollars a gallon, up 1.93 percent, and December gasoline at 3.1565, up 2.21 percent. The heating oil margin is 42 gallons times the heating oil settle less the WTI settle. Against December WTI it stands at 92.28 dollars a barrel, against 90.68 on Thursday. The gasoline margin stands at 28.45 against 27.70. Both widened. The news feed carried a release that an integrated oil company's third-quarter profit nearly tripled to 9.9 billion dollars, with refining described as the main contributor. The news feed also carried a remark from a second integrated oil company's chief executive that global refining capacity could begin to recover next year. The calendar lists both companies' results for Friday, October 30, 2026.
Crude moved against a broad retreat. The S&P 500 cash index fell 1.82 percent to 7,580.07 and the Nasdaq-100 cash index 3.46 percent. Gold's December contract fell 3.29 percent to 3,898.9 and silver's 5.93 percent. The dollar index closed at 101.88 in the provider's daily record, against 102.04. The ten-year yield record closed at 4.93 percent against 4.98 percent. The calendar lists the employment cost index at 8:30 AM ET on Friday. It rose 0.8 percent, in line with the forecast, per the news-feed calendar and unconfirmed.
Money managers trimmed both sides as of October 27. The weekly positioning report dated that day puts managed-money long positions at 157,433 contracts, down 5,980, and short positions at 126,305, down 921. That leaves a net long of 31,128. Commercial long positions stand at 906,437 and commercial short positions at 1,009,405. December open interest stood at 261,778 on Thursday, against 268,720 on Wednesday. Friday's open interest had not been reported at the time of capture. Friday's December volume was 248,668 contracts. The contract's last trading day is November 20, 2026, per the provider's specifications, so open interest is migrating toward January. No dealer-positioning dataset was read for crude.
The trade map for Monday
The review's setup is a long on the December contract from 102.45 to 102.75. The settle is the highest in the provider's record from 10/20/25 through Friday. The composite reads 100 percent buy, with signal strength described as maximum. Positive direction leads on both windows, and the settle sits above every settlement average. That is the trend case. The band holds Pivot S1 at 102.70 and one standard deviation support at 102.58, and its bottom sits 2 cents above Friday's low. The stop at 101.85 sits beneath that low and beneath two standard deviations support at 101.94. The first target, 103.35, sits beneath the Pivot Point at 103.85. The second, 104.10, sits 2 cents beneath Friday's settle. The extended 104.85 sits 14 cents beneath Friday's high. In the review's reading, a de-escalation headline can carry price through the band. The review calls the setup an analyst judgment that dips are bought while the trend averages hold, not a measured edge.
Now the arithmetic. From the 102.60 midpoint the risk to the stop is 75 cents, 20.9 percent of the 14-day average true range of 3.59. The targets sit 75 cents, 1.50 and 2.25 above the midpoint. That is exactly 1, 2 and 3 times the risk. The whole band sits beneath the settle, its top 1.37 and its bottom 1.67 under it. The 103.35 first target sits 77 cents beneath the settle and 35 cents above Thursday's 103.00 high. The 104.10 second target sits 25 cents above the Pivot Point and 2 cents beneath the settle. Only the extended 104.85 sits above the settle, 73 cents over it and 7 cents beneath the 104.92 projection.
Scenario ranges in the review are analyst judgment. The low-range case runs 102.40 to 104.40, the most likely 101.90 to 105.30 and the high-range case 100.50 to 106.80. Then the weekend. Globex halted at 5:00 PM ET on Friday. It reopens at 6:00 PM ET on Sunday, November 1, after US daylight saving time ends at 2:00 AM ET that morning, as the calendar lists it. Two days of headline exposure separate Friday's settle from the reopen. The calendar lists the producer meeting for that Sunday, for the date only. Whether any decision is published before the reopen is not known.
The review's Globex bias is neutral to firm above Pivot S1 at 102.70. Its expected band runs roughly 102.00 to 105.00. Gap references run both ways. Above sit the 104.12 settle, the 104.99 high and Pivot R1 at 105.26. Beneath sit the 102.95 print, Pivot S1, Friday's 102.43 low and two standard deviations support at 101.94.
London runs roughly 102.40 to 105.30, with a firm bias while the contract holds above the Pivot Point at 103.85. The 102.95 post-settlement print sits 90 cents beneath that line. European manufacturing surveys are listed for Monday morning, per the news-feed calendar and unconfirmed. The morning band runs roughly 102.30 to 105.40. The calendar lists construction spending at 10:00 AM ET. The US manufacturing survey is listed for Monday morning, per the news-feed calendar and unconfirmed. The review puts the setup band at the lower edge of that range; its bottom sits 15 cents above it. The afternoon runs roughly 102.20 to 105.60. The calendar lists the senior loan officer survey at 2:00 PM ET, and crude settles at 2:30 PM ET.
Then the week. The Monday evening session carries into Tuesday's midterm elections, per the news-feed calendar and unconfirmed. The calendar lists the JOLTS report at 10:00 AM ET on Tuesday, November 3. It lists the next weekly petroleum status report at 10:30 AM ET on Wednesday, November 4, and the employment situation report at 8:30 AM ET on Friday, November 6.
The review also weighs the path. In the review's analyst judgment the most probable path holds the contract between two standard deviations support at 101.94 and Pivot R1 at 105.26. It pictures a reopen near the 102.95 print and a test of the 102.43 to 102.70 area before any recovery toward the 104.12 settle. That path is weighted above an immediate break through Friday's 104.99 high. The alternative that would invalidate this reading is a reopen beneath 101.94 after the weekend. It would bring Pivot S2 at 101.29 and Pivot S3 at 100.14 into play without the dip-buying the setup needs. On the other side, a confirmed escalation over the weekend could open Friday's 104.99 high and Pivot R1 at 105.26 at the reopen without a test of the band. In the review's judgment the first-order event for crude on Monday is the 6:00 PM ET Sunday reopen. It prices the weekend's Gulf headlines and any producer decision published by then.
The 102.95 print sits 20 cents above Monday's band.
The complete data picture
Every number behind Monday’s plan, charted first, then the full level lists, then the complete numeric reference underneath. Every price is the December contract unless January is named.
Full numeric reference, every remaining figure from the session review
1. Executive Summary
The December WTI contract settled at 104.12 on Friday, up 2.12 or 2.08 percent from Thursday's settle of 102.00, after trading between 104.99 and 102.43, a 2.56 point daily range. The settle finished at 66.0 percent of the range, and the range was 0.72 multiples of the published 14-day average daily range of 3.56 points. Friday's high sat 1.99 above Thursday's 103.00 high and Friday's low sat 2.64 above Thursday's 99.79 low, so the session printed a higher high and a higher low. The 104.12 settle is the highest settlement of any session from 10/20/25 through Friday, and the 104.99 high is the provider's published 52-week, 13-week and one-month high.
Brent's December contract settled at 117.64, up 2.76 or 2.40 percent, so its premium over December WTI widened to 13.52 from 12.88. December stands 1.91 above January against 1.86 on Thursday. Heating oil rose 1.93 percent and gasoline 2.21 percent, and the product margins over crude widened. The news feed carried at 2:47 PM ET a report that Yemen's Houthis struck Aden airport, at 3:07 PM ET a maritime security report of a vessel hit by a projectile south of Lavan Island, and after the settle reports of a fourth tanker striking a mine in the Strait of Hormuz alongside the President's remark at 4:01 PM ET that "there are talks" with Iran. These are reports carried by the feeds rather than events confirmed for this review.
Electronic trade after the 2:30 PM ET settlement ended the week at 102.95 in the final 30-minute bar, 1.17 beneath the settle, so the Sunday reopen starts from a reference beneath Friday's settlement. The S&P 500 cash index fell 1.82 percent and gold 3.29 percent, while crude rose, so crude moved against the broad risk retreat.
The settle sits above every settlement average from the 5-day to the 200-day, positive direction leads on both directional systems, and the composite multi-indicator read is "100% BUY" with strength "Maximum" and direction "Strongest". The Primary Setup below is a long from the 102.45 to 102.75 band around Pivot S1 at 102.70, stopped at 101.85 beneath Friday's low, with objectives at 103.35, 104.10 and an extended 104.85.
2. Price Action & Technical Structure
2.1 Intraday and Session Review
The Friday session opened at 102.80 at the Thursday 6:00 PM ET reopen, 80 cents above Thursday's settle, marked a daily high of 104.99 and a daily low of 102.43, and settled at 104.12 at 2:30 PM ET. The preserved 30-minute series on the continuous symbol places both extremes in the Thursday evening hours: the low in the 9:00 PM ET bar and the high in the 9:30 PM ET bar. Through the US morning the contract held between 103.28 and 104.98 in the 30-minute bars from 8:00 AM ET to the settle.
After the settle the 30-minute bars from 3:00 PM ET carried the contract lower, to a 102.95 close in the 4:30 PM ET bar before the 5:00 PM ET halt. That move coincided with the news feed's reports of tanker incidents in the Strait of Hormuz and the President's remarks on talks with Iran; the series does not establish that either headline caused it. The 102.95 electronic print is a post-settlement quote and is labelled as such everywhere it appears.
Because Globex does not reopen until Sunday, the open, high and low on the provider's overview page belong to Friday's completed session. The published pivot ladder for the next session was computed from those same inputs. Pivot R3 at 107.82 minus Pivot S3 at 100.14, divided by three, returns 2.56, and Pivot R2 at 106.41 minus Pivot S2 at 101.29, divided by two, returns the same 2.56. Three times the Pivot Point of 103.85 less the 104.12 settle gives a high plus low sum of 207.43, which the pair of 104.99 and 102.43 reproduces to within the published rounding at 207.42, and that pair reproduces all seven published rungs. Independent corroboration: the provider's settlement row and the chart's completed daily bar carry the same 102.80 open, 104.99 high, 102.43 low and 104.12 settle.
2.2 Daily Structure
Friday's 104.99 high sits 1.99 above Thursday's 103.00 high and the 102.43 low sits 2.64 above Thursday's 99.79 low, a higher high and a higher low after Thursday's inside session. Settlements over the last seven sessions read 99.47, 103.27, 101.76, 99.90, 102.78, 102.00 and 104.12, and the daily changes have alternated between gains and declines for the last four sessions: minus 1.86, plus 2.88, minus 0.78 and plus 2.12. Over five sessions the contract is up 85 cents from the 103.27 settle of 10/23.
The weekly bar on the chart opened at 102.61 and closed at 104.12, with a high of 104.99 and a low of 99.44, against the prior week's 103.92 high and 95.25 low, so the week printed a higher high and a higher low. The provider publishes 104.99 as the 52-week, 13-week and one-month high and 86.00 as the one-month low of 10/06.
2.3 4-Hour and Swing Structure
The four-hour bars for Friday's session, read from the chart, show the 2:00 PM ET bar opening at 104.30 and closing at 102.95 after a low of 102.64, the widest decline of the session's six four-hour bars and the only one that closed beneath 103.00. The 1-hour and 15-minute series carry the same post-settlement decline from the 3:00 PM ET hour.
Daily ranges for the last ten sessions ran 2.99, 6.12, 4.14, 2.45, 5.08, 2.80, 3.38, 3.80, 3.21 and 2.56, so Friday's range was the narrowest since 2.45 on 10/22. The retracement grid published for Monday places the 38.2 percent retracement from the four-week high at 97.74, the 50 percent retracement of the four-week range at 95.49, the 38.2 percent retracement from the four-week low at 93.25 and the 38.2 percent retracement from the 13-week high at 92.01.
2.4 Moving Averages
The averages cited here were computed for this review from the provider's daily settlement series for the December contract, which holds 260 completed sessions from 10/20/25 through Friday; each is carried at full precision and rounded once to the cent. The 5-day average stands at 102.11, the 9-day at 100.92, the 20-day at 96.41, the 50-day at 91.04, the 100-day at 82.96 and the 200-day at 77.61.
The 104.12 settle sits 2.01 above the 5-day average, 3.20 above the 9-day, 7.71 above the 20-day, 13.08 above the 50-day, 21.16 above the 100-day and 26.51 above the 200-day. The 5-day average rose from Thursday's 101.94 as the 10/23 settle of 103.27 left the window, and the 20-day rose from 95.68 as the 10/02 settle of 89.43 left that window.
The 20-day average sits above the 50-day because the 30 older settlements in the 50-day window averaged lower, at 87.47. The 50-day sits above the 100-day because the 50 older settlements in the 100-day window averaged lower, at 74.87, and the 100-day sits above the 200-day because the 100 older settlements in the 200-day window averaged lower, at 72.27. The projection grid gives 101.31 as the price at which the 9-day average would be crossed on Monday and 97.88 for the 18-day.
2.5 Oscillator and Trend Readings
The oscillator figures below are as published on the provider's technical page, read at 6:21 PM ET on Friday with Globex closed for the weekend; they are the provider's readings, not this review's computations. The 9-day relative strength reads 70.55, the 14-day relative strength 68.89 and the 20-day relative strength 67.22.
The 9-day raw stochastic reads 91.07 percent and the 14-day raw stochastic 93.85 percent, while the 14-day stochastic %K reads 91.16 percent and the 14-day stochastic %D 86.94 percent. The 9-day directional index ADX reads 61.99 with the 9-day +DI at 26.36 and the 9-day -DI at 3.74; the 14-day directional index ADX reads 48.28 with the 14-day +DI at 25.92 and the 14-day -DI at 5.18, so positive direction leads on both. The 9-day historic volatility reads 31.23 percent and the 14-day historic volatility 27.92 percent.
The composite multi-indicator read published for the Monday session is "100% BUY", with signal strength "Maximum" and direction "Strongest". The snapshot history reads "100% BUY" for the prior session, "100% BUY" a week ago and "56% BUY" a month ago. The short, medium and long horizon groups each average "100% BUY".
2.6 Volatility and Expected Range
The published 14-day average true range stands at 3.59 points and the 14-day average daily range at 3.56 points; the 9-day average true range is 3.60 with a 9-day average daily range of 3.73, and the 20-day average true range is 3.52 with a 20-day average daily range of 3.45. Friday's 2.56 point range was 0.72 multiples of the 14-day average daily range.
Adding and subtracting the 14-day average true range of 3.59 from the 104.12 settle frames Monday between 100.53 and 107.71. The published standard-deviation bands, built from five settlements, span 102.58 to 105.66 at one deviation, 101.94 to 106.30 at two and 101.45 to 106.79 at three. The 102.95 post-settlement print already sits inside the one-deviation band, 37 cents above its lower edge. These bands describe dispersion, not intraday reach.
3. Key Levels
3.1 Resistance
Above the 104.12 settle, the first references are the 14-day relative strength projection at 70 percent at 104.92 and Friday's 104.99 high, which is also the published 52-week high. The published target price at 105.16, Pivot R1 at 105.26 and one standard deviation resistance at 105.66 form the next band, followed by two standard deviations resistance at 106.30 and Pivot R2 at 106.41. Three standard deviations resistance at 106.79, the 3-10 day crossover stall level at 107.11 and Pivot R3 at 107.82 are the extended references.
3.2 Support
Beneath the settle sit the Pivot Point at 103.85 and the 103.00 to 102.95 area of Thursday's high and the post-settlement print. Pivot S1 at 102.70, one standard deviation support at 102.58 and Friday's 102.43 low form the next band, with the 14-3 day raw stochastic projection at 80 percent at 102.16 and Thursday's 102.00 settle beneath. The 14-day stochastic stall level at 101.95, two standard deviations support at 101.94, three standard deviations support at 101.45, the 9-day average crossing price at 101.31 and Pivot S2 at 101.29 are the deeper references, with Pivot S3 at 100.14 beyond.
4. Macro Drivers
4.1 OPEC and Supply Policy (Quotas, Compliance, Saudi/Russia Signals)
The seven participating producers' monthly meeting on December output is scheduled for Sunday, November 1, 2026, as the calendar lists it, for the date only. Whether any decision is published before the 6:00 PM ET Sunday reopen is not known; the meeting is the scheduled supply event between Friday's settle and Monday's session. This review does not anticipate its outcome.
4.2 EIA and API Inventory (Crude Stocks, Gasoline, Distillates, Cushing, SPR)
The weekly petroleum status report released at 10:30 AM ET on Wednesday, October 28, 2026, as the calendar lists it, showed a crude draw of 1.892 million barrels, per the news-feed calendar and unconfirmed, a figure the provider's commentary also cited. The next weekly report is scheduled for 10:30 AM ET on Wednesday, November 4, 2026, as the calendar lists it. Thursday's Energy Department statement on a 16.75 million barrel reserve loan, carried by the news feed, was recorded in the prior review.
4.3 Geopolitical Backdrop (Middle East, Iran, Russia/Ukraine, Venezuela)
The news feed carried at 2:34 PM ET a press report that a Qatari delegation arrived in Tehran for talks, at 2:47 PM ET a report from Yemen's government that the Houthis attacked Aden airport and the presidential palace complex, and at 3:07 PM ET a maritime security report of a vessel hit by an unknown projectile 40 nautical miles south of Lavan Island. After the settle it carried at 4:01 PM ET the President's remarks that "there are talks" with Iran and "we have time", at 4:03 PM ET an Iranian state media report that a fourth tanker exploded after striking a mine in the Strait of Hormuz, and at 4:18 PM ET a maritime security report of a crude tanker hit by a projectile in the strait.
The provider's commentary cited a reported Ukrainian strike on a refinery in Russia's Samara region. These are reports carried by the feeds and attributed commentary, not events confirmed for this review.
4.4 Demand and Refining (Refinery Utilization, Crack Spreads, Seasonal Pattern)
The December heating oil contract settled at 4.6761 and December gasoline at 3.1565, up 1.93 percent and 2.21 percent. At 42 gallons to the barrel the heating oil margin over December WTI stands at 92.28 against 90.68 on Thursday and the gasoline margin at 28.45 against 27.70, so both product margins widened. The news feed carried a release that an integrated oil company's third-quarter profit nearly tripled to 9.9 billion dollars, with refining described as the main contributor, and a remark from a second integrated oil company's chief executive that global refining capacity could begin to recover next year. Both companies reported on Friday, October 30, 2026, as the calendar lists it.
4.5 Dollar and Cross-Asset (DXY, Commodities Complex, Equity Risk-On/Off)
The dollar index's daily record closed at 101.88 against 102.04 and the ten-year yield index at 4.93 percent; Thursday's close was 4.98 percent. The S&P 500 cash index fell 1.82 percent and the Nasdaq-100 cash index 3.46 percent, while gold's December contract fell 3.29 percent and silver's 5.93 percent. Crude's 2.08 percent gain, with Brent and the products also higher, came against declines in equities and metals, so the energy complex moved against Friday's broad risk retreat.
4.6 Institutional Positioning (COT, Money Manager vs Commercial Hedger, Speculator Length)
The weekly positioning report as of October 27, shown on the provider's overview, puts managed-money long positions at 157,433 contracts, down 5,980, against short positions of 126,305, down 921, and commercial long positions at 906,437 against short positions of 1,009,405. Open interest on the December contract stood at 261,778 on Thursday against 268,720 on Wednesday, and Friday's December volume was 248,668 contracts. The contract's last trading day is November 20, 2026, per the provider's specifications, so open interest is migrating toward January.
5. No Liquid Options Proxy
This review covers crude without a positioning dataset. There is no dealer-positioning surface read for this instrument in this review, no gamma map, no options concentration levels and no flow attribution, and none is inferred from any other instrument. Every level in section 3 originates in published pivot arithmetic, published standard-deviation bands, published retracement and moving-average projections, settlement averages computed from the provider's daily record, or the completed-session extremes described in section 2.1.
This is a statement about coverage, not about the existence of listed crude options. No such dataset was read for this review, so no claim resting on one appears anywhere in this review or in this outlook. The positioning inputs used for crude are the weekly positioning report, the Brent spread, the front calendar spread, the product margins and the open-interest and volume record.
6. Forecast
6.1 Night Session (6:00 PM ET Sunday to 3:00 AM ET Monday, Globex/Asia)
Globex halted at 5:00 PM ET on Friday and reopens at 6:00 PM ET on Sunday, November 1, 2026, after US daylight saving time ends at 2:00 AM ET that morning, as the calendar lists it. Two days of headline exposure therefore separate Friday's settle from the reopen, and the producer meeting of Sunday, November 1, 2026, as the calendar lists it, falls inside that window. Gap references run both ways: above, Friday's 104.12 settle, the 104.99 high and Pivot R1 at 105.26; beneath, the 102.95 post-settlement print, Pivot S1 at 102.70, Friday's 102.43 low and two standard deviations support at 101.94. Bias neutral to firm above Pivot S1, expected band roughly 102.00 to 105.00.
6.2 London Session (3:00 AM ET to 8:00 AM ET Monday)
From 3:00 AM ET European trading digests the weekend's Gulf headlines and any producer decision published by then. European manufacturing surveys are listed for Monday morning by the news-feed calendar, unconfirmed. Bias firm while the contract holds above the Pivot Point at 103.85, expected band roughly 102.40 to 105.30.
6.3 Morning Session (9:00 AM ET to 12:00 PM ET Monday, US Open / Pit Session)
Construction spending is scheduled for 10:00 AM ET on Monday, November 2, 2026, as the calendar lists it, and the US manufacturing survey is listed for Monday morning by the news-feed calendar, unconfirmed. Expected band roughly 102.30 to 105.40, with the 102.45 to 102.75 setup band at the lower edge.
6.4 Afternoon Session (12:00 PM ET to 2:30 PM ET Monday, NYMEX Pit Close)
The senior loan officer survey is scheduled for 2:00 PM ET on Monday, November 2, 2026, as the calendar lists it, with little direct bearing on crude. The settlement at 2:30 PM ET is the reference for the midweek inventory cycle. Expected band roughly 102.20 to 105.60.
6.5 Night Session Forward (6:00 PM ET Monday)
The Monday evening session carries into Tuesday's midterm elections, per the news-feed calendar and unconfirmed. The next weekly petroleum status report is scheduled for 10:30 AM ET on Wednesday, November 4, 2026, as the calendar lists it.
6.6 Expected Range (Monday Full Session)
Low-range scenario: 102.40 to 104.40
Mid-range scenario (most likely): 101.90 to 105.30
High-range scenario: 100.50 to 106.80
6.7 Most Likely Path
In this review's analyst judgment the most probable path holds the contract between two standard deviations support at 101.94 and Pivot R1 at 105.26, with the reopen near the 102.95 post-settlement print and a test of the 102.43 to 102.70 area before any recovery toward the 104.12 settle weighted above an immediate break through Friday's 104.99 high. Positive direction leads on both directional systems, the composite reads "100% BUY" and the settle sits above every settlement average.
The alternative that would invalidate this reading is a reopen beneath two standard deviations support at 101.94 after the weekend, which would bring Pivot S2 at 101.29 and Pivot S3 at 100.14 into play without the dip-buying the setup needs. On the other side, a confirmed escalation over the weekend could open Friday's 104.99 high and Pivot R1 at 105.26 at the reopen without a test of the setup band.
7. Monday Economic Calendar
Friday's releases are complete. The employment cost index released at 8:30 AM ET on Friday, October 30, 2026, as the calendar lists it, rose 0.8 percent, in line with the forecast, per the news-feed calendar and unconfirmed. An integrated oil company reported at 6:30 AM ET and a second during the day on Friday, October 30, 2026, both as the calendar lists them. December WTI settled at 2:30 PM ET and Brent at 2:48 PM ET, per the news feed's settlement items.
Over the weekend the producer meeting is scheduled for Sunday, November 1, 2026, as the calendar lists it, for the date only, and US daylight saving time ends at 2:00 AM ET that day, as the calendar lists it, so Monday's clock times are in standard time. On Monday, November 2, 2026, construction spending is scheduled for 10:00 AM ET and the senior loan officer survey for 2:00 PM ET, both as the calendar lists them; the US and European manufacturing surveys are listed for Monday by the news-feed calendar, unconfirmed.
Later in the week, the midterm elections fall on Tuesday, per the news-feed calendar and unconfirmed, the JOLTS report is scheduled for 10:00 AM ET on Tuesday, November 3, 2026, the weekly petroleum status report for 10:30 AM ET on Wednesday, November 4, 2026, and the employment situation report for 8:30 AM ET on Friday, November 6, 2026, all as the calendar lists them. In this review's judgment the first-order event for crude on Monday is the Sunday reopen at 6:00 PM ET, which prices the weekend's Gulf headlines together with any producer decision published by then.
8. Primary Trade Setup
Direction: Long
Rationale: The settle is the highest of any session from 10/20/25 through Friday, the composite reads "100% BUY" with strength "Maximum", and positive direction leads on both directional systems with the settle above every settlement average. A dip into the 102.45 to 102.75 band around Pivot S1 at 102.70 offers a long with a defined risk point beneath Friday's low. A de-escalation headline can carry price through the band, so the setup is an analyst judgment that dips are bought while the trend averages hold, not a measured edge.
Entry Zone: 102.45 to 102.75
Stop Loss: 101.85 (beneath Friday's 102.43 low and two standard deviations support at 101.94)
Target 1 (T1): 103.35 (beneath the Pivot Point at 103.85)
Target 2 (T2): 104.10 (beneath Friday's 104.12 settle)
Target 3 (T3, extended): 104.85 (beneath Friday's 104.99 high)
Risk-to-Reward: Approximately 1:1 to T1, 1:2 to T2, 1:3 to T3
Invalidation: A settle beneath two standard deviations support at 101.94 negates the thesis. Short of that, the edge is removed by acceptance beneath the entry band rather than by a touch, defined as two consecutive 30-minute closes beneath 102.45.
Macro override: A confirmed step toward a US and Iran arrangement, or a producer decision read as adding supply, would weigh on crude. In that scenario a move through the 101.85 stop invalidates the long before the targets, and Pivot S2 at 101.29 becomes the reference, 56 cents beyond the stop and inside one 14-day average true range of 3.59.
Sources and methodology
This outlook is built from our session review of the December WTI crude contract (CLZ26), prepared after Friday's close on October 30, 2026 for the Monday, November 2, 2026 session. December, which the chart's continuous symbol tracks, is the front month; its last trading day is November 20, 2026. Friday's completed extremes are the inputs behind the published pivot ladder: Pivot R3 at 107.82 less Pivot S3 at 100.14, divided by three, and Pivot R2 at 106.41 less Pivot S2 at 101.29, divided by two, both return 2.56. Three times the 103.85 Pivot Point less the 104.12 settle gives 207.43, which the 104.99 high and 102.43 low reproduce at 207.42, within the published rounding. The provider's settlement row and the chart's completed Friday bar carry the same open, extremes and settle.
Friday's card was written on the December contract and is graded on the provider's December settlement row for 10/30 (open 102.80, high 104.99, low 102.43, settle 104.12, volume 248,668). The order of events within Friday comes from the preserved 30-minute bars on the continuous symbol, 46 bars from the Thursday 6:00 PM ET reopen to the 4:30 PM ET bar, labelled in Eastern time. No price move is tied to a headline; headlines are reported with their clock times and their sources.
The moving averages were computed from the provider's daily settlement series for December, 260 completed sessions from 10/20/25 through Friday. The oscillators and range averages are cited as published, read at 6:21 PM ET on Friday. Friday's volume and the open-interest figures equal the provider's dated rows. Thursday's 10/29 row has been revised: December volume now reads 262,537 against the 241,204 cited in Friday's outlook, and open interest, not reported then, reads 261,778. Friday's open interest had not been reported. The gasoline change is 0.0684 over 3.0881, or 2.21 percent. The weekly positioning report is dated October 27. No dealer-positioning dataset was read for crude; the positioning inputs are the weekly positioning report, the Brent spread, the front calendar spread, the product margins and the open-interest and volume record. Scenario ranges are analyst judgment, and items marked unconfirmed come from the news feed or its calendar. Monday's clock times are as the review and the calendar state them, after daylight saving time ends on Sunday.
Friday’s outlook for this contract is here, and the gold contract’s Friday outlook covers the metal whose December contract settled at 3,898.9 on Friday, down 3.29 percent. Outlooks for ES, NQ, GC and CL are collected on the market outlook page, and our forward trading record is on the performance statement.