Last night's outlook set a short from 87.30 to 87.60, stopped at 88.20. The 5:30 AM ET bar reached 87.39 and activated it. Thirty minutes later the 6:00 AM ET bar traded down to 86.61, through the first target at 86.70, a gain of 0.60 from the bottom of the band and 0.90 from the top. The rest did not survive the morning. The 10:00 AM ET bar ran to 88.74 and took the 88.20 stop, a loss of 0.90 from the bottom of the band and 0.60 from the top on whatever was still open. The second target at 85.95 never traded; the lowest print after activation was 86.05, in the 2:30 PM ET bar.
Wednesday came in two halves. The contract made its 85.81 low in the 4:00 AM ET bar, climbed through the European morning and topped at 88.74 in the 10:00 AM ET bar. Then sellers took back almost all of it. The 12:00 PM ET bar fell 0.88 and the 2:00 PM ET bar fell 0.87 to 86.40 ahead of the settle.
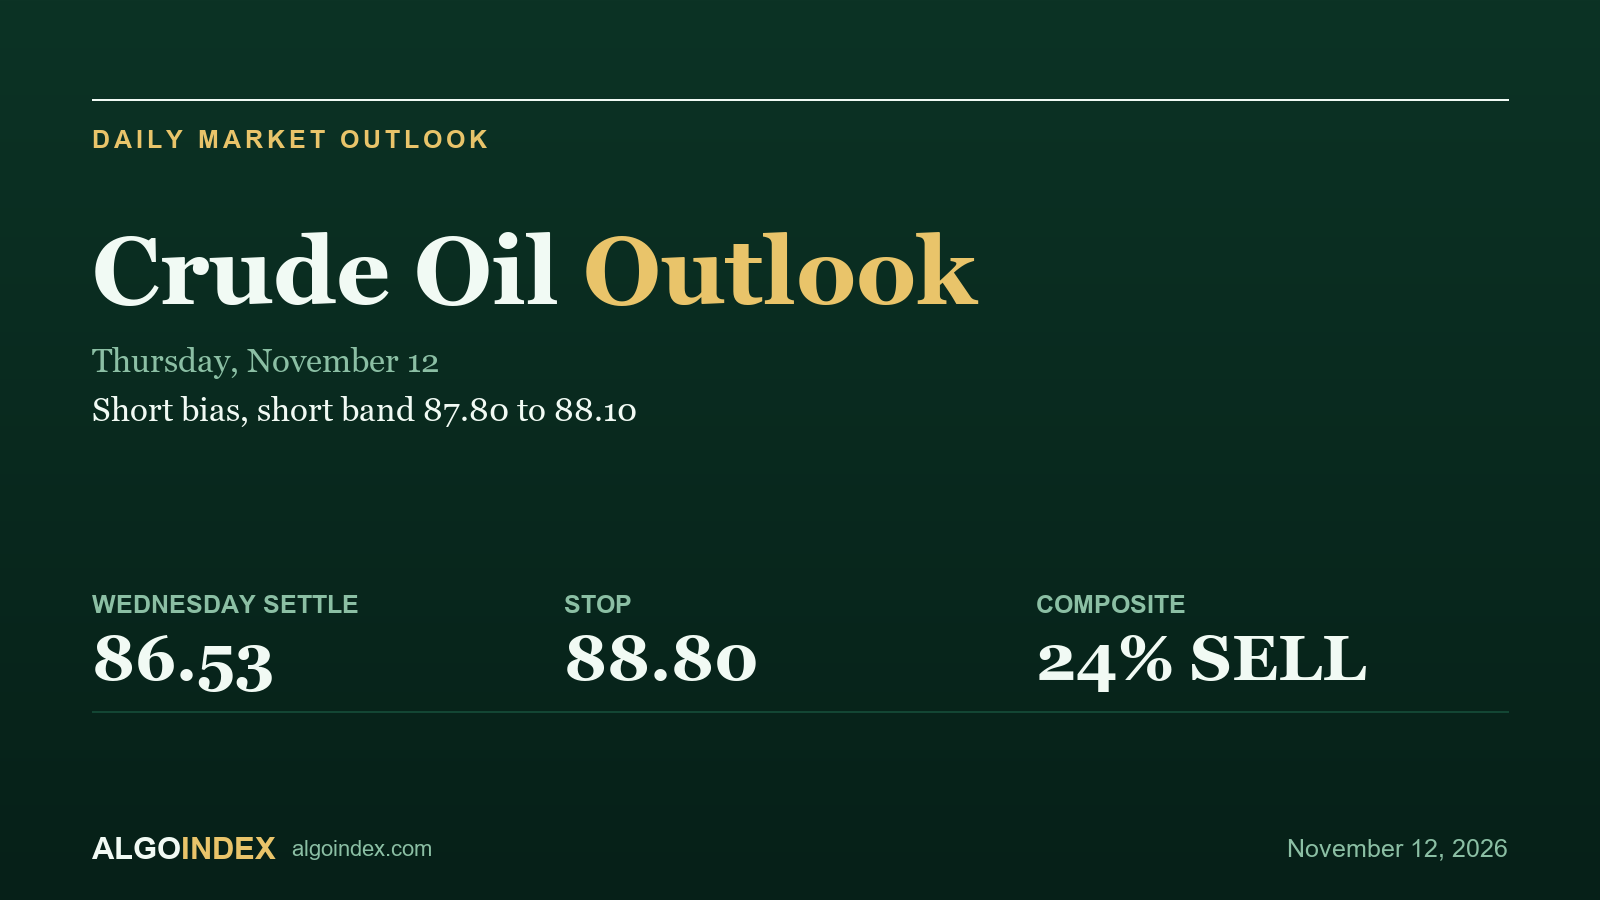
December crude settled at 86.53, up 0.49 or 0.57 percent, its first higher settle after two lower ones. The 2.93 dollar range was the narrowest since 10/30/26, and the settle finished at 24.6 percent of it, 2.21 beneath the high. Over five sessions the contract is down 1.59, or 1.80 percent, from the 88.12 settle of 11/04/26.
- Settle 86.53: beneath the 5-day, 9-day, 20-day and 50-day averages, above the 100-day at 84.15 and the 200-day at 78.86.
- Thursday's setup: short 87.80 to 88.10, stop 88.80, targets 87.10, 86.25 and an extended 85.40.
- Thesis negated on a settle above Wednesday's 88.74 high; acceptance above the band means two consecutive 30-minute closes above 88.10.
- The weekly government petroleum report, delayed by Veterans Day, is scheduled for 12:00 PM ET on Thursday, November 12.
- Wednesday's card activated, reached its first target at 86.70, then hit its 88.20 stop in the 10:00 AM ET bar.
How Wednesday traded: a morning rebound sold back
The night was quiet. From the 86.43 reopen, 0.39 above Tuesday's settle, the bars held between 86.04 and 86.81 until 3:00 AM ET and closed that window at 86.24. For a contract with a 14-day average daily range of 4.59, that is a narrow window.
Europe brought the move. The 4:00 AM ET bar printed the 85.81 session low and then rose 0.92 from open to close, the largest gain of any half-hour bar. The window to the 9:30 AM ET equity cash open traded between 85.81 and 87.53 and closed at 87.23. The 9:30 AM ET bar added 0.48 to 87.71, and the 10:00 AM ET bar rose 0.82 to 88.53 after touching 88.74; its 1.33 dollar span was the widest of the session.
The high did not hold. The 12:00 PM ET bar fell 0.88, from 87.83 to 86.95, the largest decline of any bar. The 2:00 PM ET bar fell 0.87 from 87.27 to 86.40, the settle was fixed at 2:30 PM ET at 86.53, and the 2:30 PM ET bar traded down to 86.05. The 4:30 PM ET bar closed at 86.42, 0.11 beneath the settle.
The provider's market commentary said crude rose on short covering and fell from its best level after the dollar index rallied to a 1.5-year high; that is attributed commentary. Brent's January contract settled at 92.76, up 1.27 dollars or 1.39 percent. The dollar index closed at 102.91, up 0.67 percent.
Momentum still leans down. The composite reads "24% SELL" with strength "Minimum" and direction "Weakening", against "32% SELL" a session earlier and "88% BUY" a month ago. Negative direction leads both systems, 30.76 against 14.70 on the 9-day with an ADX of 46.25, and all three raw stochastics read 12.55 percent. The settle is the eighth straight beneath the 20-day average and the sixth beneath the 50-day.
Inventory report, products and the dollar
Veterans Day pushed the weekly government petroleum report to 12:00 PM ET on Thursday. The news-feed calendar lists a forecast crude change of minus 1.483 million barrels against a prior minus 0.865 million, unconfirmed. Tuesday's after-close industry estimate showed a 9.8 million barrel draw with a 5.1 million barrel build at Cushing, also a news-feed item and unconfirmed until the government figures print.
Distillates led the complex. Heating oil's December contract settled at 4.2113 dollars a gallon, up 1.95 percent, while gasoline's December contract slipped 0.05 percent to 2.6075. The heating oil margin over December WTI widened to 90.34 dollars a barrel from 87.46, and the gasoline margin narrowed to 22.99 from 23.53. In our reading that points to middle-distillate demand rather than broad product strength, which keeps the crude bid narrow.
The cash Treasury market was closed for the holiday. Gold's December contract fell 0.74 percent and the S&P 500 cash index rose 1.31 percent. December's premium over January narrowed to 1.10 from 1.18, Brent's January premium over January WTI widened to 7.33 from 6.63, and December volume fell to 208,390 contracts from 288,756.
The trade map for Thursday
The setup sells a rebound into 87.80 to 88.10, between the Pivot Point at 87.03 and Pivot R1 at 88.24, just under the 5-day average at 88.15. The stop at 88.80 sits above Wednesday's 88.74 high and beneath one standard deviation resistance at 88.85.
The first target, 87.10, sits above the Pivot Point. The second, 86.25, sits beneath the 86.53 settle and above the 86.13 retracement from the 52-week low. The extended 85.40 sits above Pivot S1 at 85.31. Measured from the 87.95 midpoint of the band, reward runs 1:1, 1:2 and 1:3.
A settle above the 88.74 high negates the thesis and would bring Pivot R2 at 89.96 into play, 1.16 beyond the stop. Before that, two consecutive 30-minute closes above 88.10 remove the edge. A large government draw or further Gulf supply reports could lift crude through the stop before any target trades.
Our base case holds crude between Pivot S1 at 85.31 and Pivot R1 at 88.24 into the 12:00 PM ET report, with a rebound that stalls beneath 88.74. The mid-range scenario runs 84.90 to 88.30, the low-range one 85.60 to 87.60 and the high-range one 83.80 to 89.90. Reports of diplomatic progress in the Gulf could instead carry the contract through the 85.81 low toward Pivot S2 at 84.10 with no rebound at all. The setup is an analyst judgment, not a measured edge.
The complete data picture
Every figure behind Thursday's plan, charted first; the full numeric reference follows underneath.
- Brent January 92.76 up 1.27, 1.39%
- Heating oil December 4.2113 up 1.95%
- Gasoline December 2.6075 down 0.05%
- Dollar index 102.91 up 0.68, 0.67%
- December-January spread 1.10 from 1.18
- Brent-WTI January spread 7.33 from 6.63
- Heating oil margin 90.34 from 87.46
- Gasoline margin 22.99 from 23.53
- Thu, Nov 12, 12:00 PM ET Weekly government petroleum report scheduled, moved for the holiday
- Fri, Nov 13, 4:00 AM ET Energy agency monthly report listed by the news-feed calendar, unconfirmed
- Fri, Nov 13, 8:30 AM ET Producer price index scheduled
Full numeric reference, every figure from the review
Executive Summary
The December crude contract settled at 86.53 on Wednesday, up 0.49 or 0.57 percent from Tuesday's settle of 86.04, after trading between 88.74 and 85.81, a 2.93 point daily range. The settle finished at 24.6 percent of the range, 2.21 beneath the high, and the range was 0.64 multiples of the published 14-day average daily range of 4.59 points. Wednesday printed a higher high, 1.81 above Tuesday's 86.93, and a higher low, 1.93 above Tuesday's 83.88, and ended a run of two lower settles.
The 88.74 high is the highest since the 91.42 high of 11/09/26, and the 2.93 point range is the narrowest since the 2.56 point range of 10/30/26. Over five sessions the contract is down 1.59 from the 88.12 settle of 11/04/26, a decline of 1.80 percent. The settle remains beneath the 5-day, 9-day, 20-day and 50-day settlement averages and above the 100-day and 200-day.
The session divided into two halves. The contract made its 85.81 low in the 4:00 AM ET bar, rose through the European morning and made the 88.74 high in the 10:00 AM ET bar, then gave back most of that gain: the 12:00 PM ET bar fell 0.88 and the 2:00 PM ET bar fell 0.87 to 86.40 ahead of the 2:30 PM ET settle.
The provider's market commentary said crude rose on short covering and fell from its best level after the dollar index rallied to a 1.5-year high, which is attributed commentary. Brent's January contract settled at 92.76, up 1.27 dollars or 1.39 percent, per a news-feed settlement item and the settlement record, and the dollar index's daily record closed at 102.91, up 0.67 percent.
The composite multi-indicator read published on Wednesday evening is "24% SELL" with strength "Minimum" and direction "Weakening", against "32% SELL" a session earlier. The Primary Setup in section 8 is a short from the 87.80 to 88.10 band, between the Pivot Point at 87.03 and Pivot R1 at 88.24, stopped at 88.80 above Wednesday's 88.74 high, with objectives at 87.10, 86.25 and an extended 85.40. The weekly government petroleum report, delayed by the Veterans Day holiday, is scheduled for 12:00 PM ET on Thursday, November 12, 2026, per the verified forward calendar, and in this review's judgment it is the first-order scheduled input for crude on Thursday.
Price Action & Technical Structure
2.1 Intraday and Session Review
The Wednesday session opened at 86.43 at the Tuesday 6:00 PM ET reopen, 0.39 above Tuesday's settle, and the 30-minute series places the low of 85.81 in the 4:00 AM ET bar on Wednesday and the high of 88.74 in the 10:00 AM ET bar. Between the 6:00 PM ET reopen and 3:00 AM ET the bars held between 86.04 and 86.81 and closed that window at 86.24, a quiet overnight window for a contract whose published 14-day average daily range is 4.59 points.
From 3:00 AM ET to the 9:30 AM ET equity cash open the contract traded between 85.81 and 87.53. The 4:00 AM ET bar made the session low of 85.81 and then rose 0.92 from open to close, the largest gain of any 30-minute bar in the session, and the window closed at 87.23. The 9:30 AM ET bar rose 0.48 to 87.71, and the 10:00 AM ET bar rose 0.82 to 88.53 after reaching 88.74; its 1.33 point span from high to low was the widest of any bar in the session.
Across the cash hours, from 9:30 AM ET to 4:00 PM ET, the bars held between 86.05 and 88.74. The 12:00 PM ET bar fell 0.88 from 87.83 to 86.95, the largest decline of any bar, and the 2:00 PM ET bar fell 0.87 from 87.27 to 86.40, with the settle fixed at 2:30 PM ET at 86.53. The 2:30 PM ET bar traded down to 86.05, and the 4:30 PM ET bar closed at 86.42, 0.11 beneath the settle.
The provider's overview page, read at 6:19 PM ET, carries an open of 86.50, a high of 86.53 and a low of 86.27 that belong to the Globex session that reopened at 6:00 PM ET on Wednesday, not to Wednesday's completed session; its previous close field reads 86.53. Wednesday's completed range is instead recovered from the published pivot ladder. Pivot R3 at 91.17 minus Pivot S3 at 82.38, divided by three, returns 2.93, and Pivot R2 at 89.96 minus Pivot S2 at 84.10, divided by two, returns the same 2.93. The published Pivot Point is 87.03. Three times that value, less the 86.53 settle, gives a high plus low sum of 174.56, within the rounding of the published value, which with the 2.93 range solves to a high of 88.7425 and a low of 85.8125, or 88.74 and 85.81 at the published two-decimal rounding.
That pair, with the 86.53 settle, reproduces all seven published rungs. These are the completed-session inputs behind the published pivot ladder rather than an independently read bar, and they are corroborated by the provider's settlement row, the chart's completed daily bar and the 30-minute series, which carry the same 86.43 open, 88.74 high, 85.81 low and 86.53 settle.
2.2 Daily Structure
Wednesday printed a higher high and a higher low against Tuesday and settled 0.49 higher, the first higher settle after two lower settles. Settlements over the last six sessions read 88.12, 90.52, 90.83, 86.85, 86.04 and 86.53, so the contract has recovered 0.49 of the 4.79 points lost on Monday and Tuesday and settles 1.59 beneath the 88.12 settle of 11/04/26.
The 88.74 high is the highest since the 91.42 high of 11/09/26. The provider publishes 104.99 as the 52-week, 13-week and one-month high, 83.88 as the one-month low and 76.67 as the 13-week low. The settle sits 0.40 above the 86.13 level published as the 61.8 percent retracement from the 52-week low and 0.96 beneath the 87.49 level published as the 38.2 percent retracement from the 13-week low; the session high reached above both levels and the settle returned beneath the second.
The settle finished at 24.6 percent of the day's range, 0.72 above the 85.81 low and 2.21 beneath the 88.74 high. In this review's interpretation a settle in the lower quarter of a range that had reached a higher high describes a rejected rebound rather than a completed recovery, because the contract gave back 2.21 of the 2.93 point range after the 10:00 AM ET high.
2.3 4-Hour and Swing Structure
The 2.93 point range was the narrowest since the 2.56 point range of 10/30/26, after ranges of 6.40 on Monday and 3.05 on Tuesday. In the 30-minute series no bar moved more than 0.92 from open to close, and two bars, at 4:00 AM ET and 10:00 AM ET, spanned more than 1.20 from high to low.
The swing sequence since the 104.99 high of 10/30/26 shows highs of 102.75 on 11/02, 98.82 on 11/03, 97.15 on 11/04 and 91.32 on 11/05, a higher high at 92.53 on 11/06, lower highs at 91.42 on Monday and 86.93 on Tuesday, and a higher high at 88.74 on Wednesday that remains beneath Monday's 91.42. The lows read 89.07 on 11/06, 85.02 on Monday, 83.88 on Tuesday and 85.81 on Wednesday, the first higher low since 11/06/26.
Daily ranges over the last eight sessions, from 10/30/26, ran 2.56, 7.60, 5.23, 10.02, 4.67, 3.46, 6.40 and 2.93, so Wednesday's range sits at the low end of that set after the 10.02 point range of 11/04/26. The published grid places the 61.8 percent retracement from the 52-week low at 86.13, the 38.2 percent retracement from the 13-week low at 87.49, the 50 percent retracement of the 13-week range at 90.83 and the 50 percent retracement of the 52-week range at 80.31.
2.4 Moving Averages
The averages cited here were computed in this analysis from the provider's daily settlement series for the December contract, which holds 259 completed sessions from 10/31/25 through Wednesday; the partial row dated Thursday, opened by the 6:00 PM ET Globex reopen, was excluded before counting, and each average is carried at full precision and rounded once to the cent. The 5-day average stands at 88.15, the 9-day at 91.73, the 20-day at 96.19, the 50-day at 92.47, the 100-day at 84.15 and the 200-day at 78.86.
The 86.53 settle sits 1.62 beneath the 5-day average, 5.20 beneath the 9-day, 9.66 beneath the 20-day and 5.94 beneath the 50-day, and 2.38 above the 100-day and 7.67 above the 200-day. It is the eighth consecutive settle beneath the 20-day average, the last settle above it on 10/30/26, and the sixth consecutive settle beneath the 50-day, the last settle above it on 11/03/26. The 5-day average fell from Tuesday's 88.47 as Wednesday's settle replaced the 11/04 settle of 88.12, and the 9-day fell from 93.45 as the 102.00 settle of 10/29/26 left the window.
The 20-day average sits above the 50-day because the 30 older settlements in the 50-day window averaged lower, at 90.00. The 50-day sits above the 100-day because the 50 older settlements in the 100-day window averaged lower, at 75.82, and the 100-day sits above the 200-day because the 100 older settlements in the 200-day window averaged lower, at 73.56. The projection grid gives 82.27 as the level at which the 3-day and 10-day averages would stall their crossover.
2.5 Oscillator and Trend Readings
The oscillator figures below are as published on the provider's technical page, read at 6:19 PM ET on Wednesday after the Globex reopen, so they may include the live price of the reopened session; they are the provider's readings, not the computations. The 9-day relative strength reads 32.28, the 14-day relative strength 38.06 and the 20-day relative strength 42.39.
The 9-day, 14-day and 20-day raw stochastic all read 12.55 percent, while the 14-day stochastic %K reads 10.65 percent and the 14-day stochastic %D 14.13 percent. The 9-day directional index ADX reads 46.25 with the 9-day +DI at 14.70 and the 9-day -DI at 30.76, and the 14-day directional index ADX reads 36.30 with the 14-day +DI at 16.38 and the 14-day -DI at 26.51, so negative direction leads on both systems. The 9-day historic volatility reads 59.94 percent and the 14-day historic volatility 56.69 percent.
The composite multi-indicator read published on Wednesday evening, on a page titled for Thursday, November 12, 2026, is "24% SELL", with signal strength "Minimum" and direction "Weakening". The snapshot history reads "32% SELL" for the prior session, "24% SELL" a week ago and "88% BUY" a month ago. The short horizon group averages "60% SELL", the medium group "25% SELL" and the long group "67% BUY", and the trend composite reads "SELL".
2.6 Volatility and Expected Range
The published 14-day average true range stands at 4.35 points and the 14-day average daily range at 4.59 points; the 9-day average true range is 4.53 with a 9-day average daily range of 5.10, and the 20-day average true range is 4.15 with a 20-day average daily range of 4.41. Wednesday's 2.93 point range was 0.64 multiples of the 14-day average daily range.
Adding and subtracting the 14-day average true range of 4.35 from the 86.53 settle frames Thursday between 82.18 and 90.88. The published standard-deviation bands, built from five settlements, span 84.21 to 88.85 at one deviation, 83.25 to 89.81 at two and 82.51 to 90.55 at three. These bands describe dispersion, not intraday reach, and Thursday carries the delayed government inventory report inside the session, which in this review's judgment makes a range near the 14-day average more likely than Wednesday's contraction.
Key Levels
3.1 Resistance
Above the 86.53 settle, the first reference is the Pivot Point at 87.03, followed by the 87.49 retracement from the 13-week low and the 87.53 high of the 3:00 AM to 9:30 AM ET window. The 5-day average at 88.15, Pivot R1 at 88.24 and the 88.33 stall of the 14-day %K line form the next band, with Wednesday's 88.74 high and one standard deviation resistance at 88.85 just above it. Pivot R2 at 89.96 and the 90.83 midpoint of the 13-week range are the deeper references, with the 50-day average at 92.47 beyond them.
3.2 Support
Beneath the settle sit the 86.42 close of the 4:30 PM ET bar and the 86.13 retracement from the 52-week low. Wednesday's 85.81 low, Pivot S1 at 85.31 and the 85.27 published target price form the next band, followed by one standard deviation support at 84.21 and Pivot S2 at 84.10. Tuesday's 83.88 low, now the one-month low, the 83.25 two-deviation band and Pivot S3 at 82.38 are the deeper references.
Macro Drivers
4.1 OPEC and Supply Policy
The producer group's monthly report was listed for 8:00 AM ET on Wednesday, November 11, 2026 by the news-feed calendar, unconfirmed, and its contents were not captured in this analysis. The supply items carried by the feeds were reports rather than figures: at 2:16 PM ET the commodities feed reported that Mexico's state oil company raised crude processing to the highest level since 2013, and the supply references that bore on price were the Gulf transit reports in section 4.3. The international energy agency's monthly report is listed for 4:00 AM ET on Friday, November 13, 2026 by the news-feed calendar, unconfirmed.
4.2 EIA and API Inventory (Crude Stocks, Gasoline, Distillates, Cushing, SPR)
The weekly government petroleum report did not publish on Wednesday because of the Veterans Day holiday and is scheduled for 12:00 PM ET on Thursday, November 12, 2026, per the verified forward calendar. The news-feed calendar lists a forecast crude change of minus 1.483 million barrels against a prior minus 0.865 million barrels, a news-feed item that is unconfirmed. Tuesday's after-close industry estimate, a 9.8 million barrel draw with a 5.1 million barrel build at Cushing, was a news-feed item carried in Tuesday's review and remains unconfirmed until the government figures print.
4.3 Geopolitical Backdrop
The news feed carried geopolitical reports through the session, including items on Gulf transit. These are reports carried by the feeds, and the settlement series does not establish that any single item caused a particular move.
4.4 Demand and Refining (Refinery Utilization, Crack Spreads, Seasonal Pattern)
Heating oil's December contract settled at 4.2113 dollars a gallon, up 1.95 percent, and gasoline's December contract at 2.6075, down 0.05 percent, against crude's 0.57 percent gain. Measured on the December contracts, the heating oil margin over December WTI widened to 90.34 dollars a barrel from 87.46, while the gasoline margin narrowed to 22.99 from 23.53. Distillate strength against gasoline weakness points, in this review's interpretation, to demand for middle distillates rather than broad refined-product demand, which leaves the crude bid narrow.
4.5 Dollar and Cross-Asset (DXY, Commodities Complex, Equity Risk-On/Off)
The dollar index's daily record closed at 102.91, up 0.68 points or 0.67 percent, and the provider's commentary described the dollar at a 1.5-year high and tied the move to firmer Fed hike expectations after Tuesday's consumer price index, which is attributed commentary. The cash Treasury market was closed for Veterans Day, so the ten-year yield index printed no session. Gold's December contract fell 0.74 percent, silver's December contract rose 1.52 percent and the S&P 500 cash index rose 1.31 percent. Crude's afternoon decline from the 10:00 AM ET high came while the dollar firmed; these moves coincided, and no captured series separates their effects.
At 8:54 AM ET the news feed carried a sentiment note that markets continue to price a more hawkish Fed, and investment-bank commentary in the same feed expected a second quarter-point hike in December. For crude, these items bear on demand expectations through the dollar and rates rather than on supply.
4.6 Institutional Positioning (COT, Money Manager vs Commercial Hedger, Speculator Length)
The latest weekly positioning report on the provider's overview, for the week to Tuesday, November 3, 2026, shows managed money at 147,382 long, down 10,051, against 125,654 short, down 651, as listed and not recomputed. Wednesday's December volume was 208,390 contracts against 288,756 on Tuesday, per the settlement record. December's premium over January narrowed to 1.10 from 1.18, and Brent's January premium over January WTI widened to 7.33 from 6.63 as Brent's January contract rose 1.39 percent against 0.67 percent for January WTI.
Options positioning
This analysis covers crude without a positioning dataset; listed crude options trade, but no dealer-positioning dataset for them was read in this analysis. There is no gamma map, no options concentration levels and no flow attribution, and none is inferred from any other instrument. Every level in section 3 originates in published pivot arithmetic, published standard-deviation bands, published retracement and moving-average projections, settlement averages computed from the provider's daily record, or the completed-session extremes described in section 2.1.
This is a statement about the scope of this analysis, not about the existence or liquidity of listed crude options. No claim resting on such a dataset appears in this review. The positioning inputs used for crude are the Brent spread, the front calendar spread, the product margins, the volume record and the weekly positioning figures in section 4.6.
Forecast
Night Session (6:00 PM ET Wednesday to 3:00 AM ET Thursday, Globex/Asia)
Globex reopened at 6:00 PM ET on Wednesday with the overview showing an 86.50 open, beneath the 86.53 settle. Japanese producer prices are listed for 6:50 PM ET on Wednesday, November 11, 2026 by the news-feed calendar, unconfirmed. Bias neutral to lower beneath the Pivot Point at 87.03, expected band roughly 85.70 to 87.30.
London Session (3:00 AM to 8:00 AM ET Thursday)
UK growth data are listed for 2:00 AM ET on Thursday, November 12, 2026 by the news-feed calendar, unconfirmed, ahead of the London session. Bias neutral beneath Pivot R1 at 88.24, expected band roughly 85.50 to 87.60.
Morning Session (9:00 AM to 12:00 PM ET Thursday, US Open / Pit Session)
Weekly jobless claims are listed for 8:30 AM ET on Thursday, November 12, 2026 by the news-feed calendar, unconfirmed, and remarks by a Fed governor are listed for 10:00 AM ET on Thursday by the same calendar, also unconfirmed. Expected band roughly 85.30 to 88.20, with the 87.80 to 88.10 setup band near the top.
Afternoon Session (12:00 PM to 2:30 PM ET Thursday, NYMEX Pit Close)
The weekly government petroleum report is scheduled for 12:00 PM ET on Thursday, November 12, 2026, per the verified forward calendar, and the settlement at 2:30 PM ET fixes the reference. Expected band roughly 84.80 to 88.60, the widest of the day's windows because of the report.
Night Session Forward (6:00 PM ET Thursday)
The Thursday evening session carries into the producer price index at 8:30 AM ET on Friday, November 13, 2026, per the verified forward calendar. The international energy agency's monthly report is listed for 4:00 AM ET on Friday, November 13, 2026 by the news-feed calendar, unconfirmed.
Expected Range (Thursday Full Session)
Low-range scenario: 85.60 to 87.60
Mid-range scenario (most likely): 84.90 to 88.30
High-range scenario: 83.80 to 89.90
Most Likely Path
In this review's analyst judgment, the most probable path holds the contract between Pivot S1 at 85.31 and Pivot R1 at 88.24 into the 12:00 PM ET government report, with a rebound toward the 87.80 to 88.10 band that stalls beneath Wednesday's 88.74 high weighted above a settle through it. The composite reads "24% SELL" with strength "Minimum", negative direction leads on both directional systems and the settle sits beneath the 5-day, 9-day, 20-day and 50-day averages after a rejected rebound, which in this review's interpretation favours selling a rebound rather than chasing a decline from the reopen.
The alternative that would invalidate this reading is a settle above Wednesday's 88.74 high and one standard deviation resistance at 88.85, which would bring Pivot R2 at 89.96 into play; a government draw that confirms Tuesday's industry estimate, or further Gulf supply reports, are the inputs most likely to drive that alternative. On the other side, reports of diplomatic progress in the Gulf could carry the contract through Wednesday's 85.81 low toward Pivot S2 at 84.10 without the rebound the setup needs.
Calendar
Wednesday's releases are complete. Wednesday, November 11, 2026 was the Veterans Day holiday, with CME Globex on normal hours and normal settlement times and banks closed, per the verified forward calendar, and the cash Treasury market closed. December WTI settled at 2:30 PM ET at 86.53, and the producer group's monthly report listed for 8:00 AM ET on Wednesday by the news-feed calendar, unconfirmed, was not captured in this analysis.
Thursday opens with UK growth data listed for 2:00 AM ET by the news-feed calendar, unconfirmed, and weekly jobless claims listed for 8:30 AM ET on Thursday, November 12, 2026 by the news-feed calendar, unconfirmed. Remarks by a Fed governor are listed for 10:00 AM ET on Thursday, November 12, 2026 by the news-feed calendar, unconfirmed. The weekly government petroleum report is scheduled for 12:00 PM ET on Thursday, November 12, 2026, per the verified forward calendar. A 30-year bond auction is listed for 1:00 PM ET on Thursday by the news-feed calendar, unconfirmed, and several Fed officials are listed through the day by the news-feed calendar, unconfirmed.
Later in the week, the producer price index is scheduled for 8:30 AM ET on Friday, November 13, 2026, per the verified forward calendar. In this review's judgment the first-order input for crude on Thursday is the weekly government petroleum report at 12:00 PM ET, per the verified forward calendar, with Gulf headline flow as the unscheduled input.
Primary setup
Direction: Short
Rationale: The contract settled at 24.6 percent of a range that reached a higher high, beneath the 5-day, 9-day, 20-day and 50-day averages, the composite reads "24% SELL" and negative direction leads on both directional systems. A rebound into the 87.80 to 88.10 band, between the Pivot Point at 87.03 and Pivot R1 at 88.24, offers a short with a defined risk point above Wednesday's 88.74 high. The government report at 12:00 PM ET and the Gulf headlines can carry price through the band, so the setup is an analyst judgment that rebounds toward Pivot R1 are sold, not a measured edge.
Entry Zone: 87.80 to 88.10
Stop Loss: 88.80 (above Wednesday's 88.74 high and beneath one standard deviation resistance at 88.85)
Target 1 (T1): 87.10 (above the Pivot Point at 87.03)
Target 2 (T2): 86.25 (beneath the 86.53 settle, above the 86.13 retracement from the 52-week low)
Target 3 (T3, extended): 85.40 (above Pivot S1 at 85.31)
Risk-to-Reward: Approximately 1:1 to T1, 1:2 to T2, 1:3 to T3
Invalidation: A settle above Wednesday's 88.74 high negates the thesis. Short of that, the edge is removed by acceptance above the entry band rather than by a touch, defined as two consecutive 30-minute closes above 88.10.
Macro override: A government report showing a large crude draw or further Gulf supply disruption reports would lift the contract. In that scenario a move through the 88.80 stop invalidates the short before the targets, and Pivot R2 at 89.96 becomes the reference, 1.16 beyond the stop and well inside one 14-day average true range of 4.35.
Sources and methodology
Prices, settlements and volume come from the exchange settlement record and the provider's daily series for the December contract (CLZ26). Session timing comes from the 30-minute bar series of Wednesday's Globex session, from the 6:00 PM ET reopen on Tuesday. Moving averages were computed from 259 completed daily settlements; oscillators, the composite read and the pivot ladder are quoted as published, and the pivot ladder was checked against Wednesday's high, low and settle. Weekly positioning figures are as listed for the week to Tuesday, November 3, 2026. Economic-calendar times come from the verified forward calendar unless marked as listed and unconfirmed.
The prior card is graded only on its own levels, with the full Wednesday session from the reopen; no fill is assumed. Listed crude options trade, but no dealer-positioning dataset for them was read, so no options-based level appears here.
Crude sold off 2.21 dollars from its high on Wednesday, and Thursday's delayed inventory count may decide whether that rebound gets a second attempt.