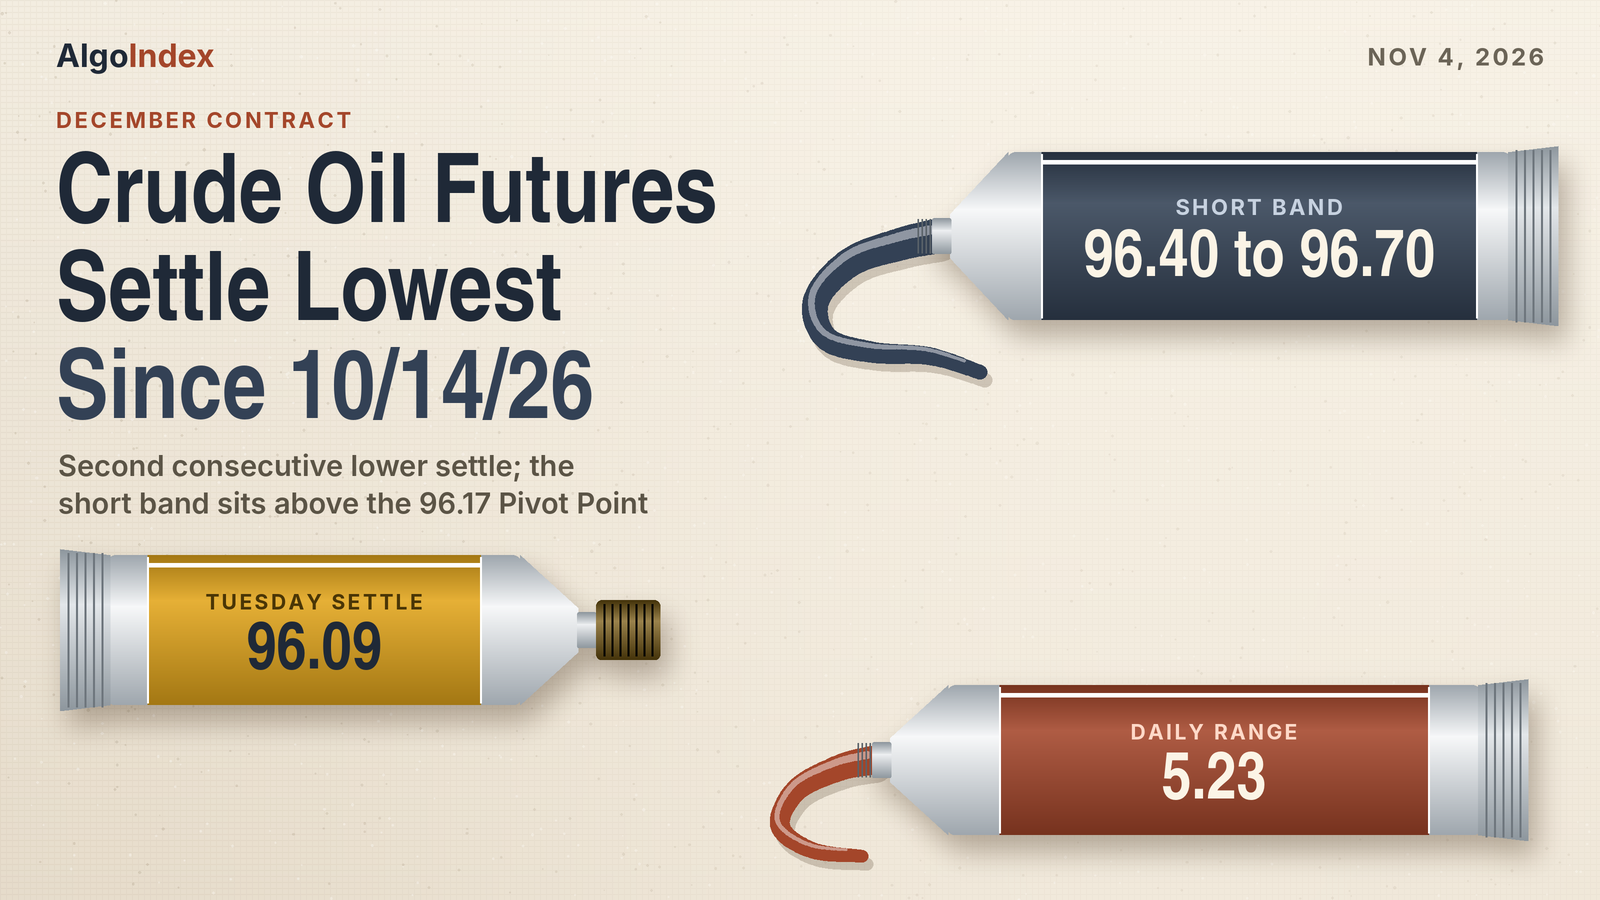
December crude settled at 96.09 on Tuesday, down 0.37 or 0.38 percent from Monday's 96.46. The session ran between 98.82 and 93.59, a 5.23 point range. The settle finished at 47.8 percent of it. That range was 1.27 times the 14-day average daily range of 4.12 points. Tuesday printed a lower high and a lower low, and a second lower settle in a row. The settle is the lowest since 10/14/26, when the contract settled at 93.90. The low is the lowest since the 92.46 low of 10/15/26.
Tuesday's short card traded early. The card was a short from 97.95 to 98.25 with a 98.85 stop. The session opened at 96.30, beneath the band, and the 1:30 AM ET bar first reached into it, at 98.14. Two 30-minute closes above the band's top followed at 6:00 AM ET and 6:30 AM ET, the condition the card set for removing the edge. The 7:00 AM ET bar then made the 98.82 high, 3 cents beneath the stop. The stop never traded. All three targets traded later in the morning. No fill and no result are asserted.
Wednesday's session reopened at 6:00 PM ET on Tuesday. As of 10:15 PM ET it had traded from a 97.15 high in the 8:00 PM ET bar to a 94.90 low in the 9:30 PM ET bar. The contract traded at 95.36 at that time, 0.73 or 0.76 percent beneath Tuesday's settle, in a 10:00 PM ET bar that was still forming. The review then moved its setup to a short from 96.40 to 96.70. That band sits above both the 96.09 settle and the 95.36 print. It asks for a rebound first.
Products went the other way. Brent's January contract settled at 103.60, down 1.17 or 1.12 percent, while gasoline rose 1.22 percent and heating oil 2.47 percent. The 4:30 PM ET bar closed at 96.76, 0.67 above the settle; that is a post-settlement quote. At 4:54 PM ET the news feed carried an industry estimate of a 5.267 million barrel crude draw against a forecast build of 2.1 million. The calendar lists the government petroleum status report for 10:30 AM ET on Wednesday.
December crude settled at 96.09, down 0.37 or 0.38 percent, at 47.8 percent of a 93.59 to 98.82 range. The settle sits beneath the 5-day and 20-day averages and above the 50-day, 100-day and 200-day. As of 10:15 PM ET the reopened session had traded from 97.15 to 94.90 and stood at 95.36. Resistance starts at the Pivot Point at 96.17, then the 96.76 post-settlement print, the 97.15 overnight high and the 20-day average at 97.21. Support starts at the 95.49 retracement, then Monday's 95.15 low and the 94.97 projection. The setup stays short, now from 96.40 to 96.70, with a 97.30 stop and targets at 95.80, 95.05 and an extended 94.30. The whole band sits above both the settle and the 95.36 print.
Tuesday's short band traded overnight, and the high stopped 3 cents short of the 98.85 stop
First, the grading. In Tuesday's outlook we set a short on the December contract from 97.95 to 98.25, stop 98.85, with targets at 97.35, 96.60 and an extended 95.85. A settle above one standard deviation resistance at 99.45 would negate it. Two consecutive 30-minute closes above 98.25 would remove the edge. The card is graded on December's Tuesday bar, with the order of events taken from the preserved 30-minute bars.
The open came in low. December's bar, from the provider's settlement row, opened at 96.30 at the Monday 6:00 PM ET reopen. That was 1.65 beneath the band's bottom. It was also beneath the first two targets, 1.05 under 97.35 and 30 cents under 96.60, so those two prices had already traded before the band did. The overnight hours then climbed. The 1:30 AM ET bar reached 98.14, the first trade inside the band, and the 2:00 AM ET bar ran to 98.69, above its 98.25 top.
The first target came next. After the band traded, the 4:30 AM ET bar was the first to trade back at 97.35, with a low of 97.29. Then the acceptance line printed. The 6:00 AM ET bar closed at 98.43 and the 6:30 AM ET bar at 98.57. Those were two consecutive closes above 98.25, the condition the card set for removing the edge. The 7:00 AM ET bar made the session's 98.82 high. That sat 3 cents beneath the 98.85 stop, which never traded.
The decline followed. The 7:00 AM ET bar closed at 96.93. The 8:00 AM ET bar ran from 97.59 down to 95.44, through the 96.60 second target and the 95.85 extended target. The 8:30 AM ET bar made the 93.59 low, 2.26 beneath the third target. The 96.09 settle sat 51 cents beneath the second target and 24 cents above the third. It sat 3.36 beneath the 99.45 line, so no invalidation settle printed. No fill and no result are asserted.
The ranges mostly held. The low-range case of 95.10 to 98.20 gave way at both ends, at the top by 62 cents and at the bottom by 1.51. The most likely case of 94.30 to 99.00 broke at the bottom by 71 cents; its top sat 18 cents above the high. The high-range case of 92.50 to 100.50 held. One deviation, 93.47 to 99.45, held with the low 12 cents above its bottom. Two and three deviations held, and so did one average true range around Monday's settle, 92.49 to 100.43.
The session bands split. Globex, 6:00 PM ET to 3:00 AM ET, traded 96.12 to 98.69 against a 95.10 to 98.20 band. Its high sat 49 cents over the top. London traded 96.77 to 98.82 against 94.90 to 98.40, its high 42 cents over. The 8:00 AM ET and 8:30 AM ET bars fall between the London and morning windows. They traded 93.59 to 97.59 and carried the low. The morning then traded 94.57 to 96.96 inside a 94.50 to 98.80 band. The afternoon traded 95.55 to 96.30 inside 94.30 to 99.00.
The weighted path held the contract between Pivot S1 at 93.49 and one standard deviation resistance at 99.45. It did, and the low sat 10 cents above 93.49. The path pictured a rebound toward the Pivot Point at 98.12 that stalls beneath the 98.72 projection. The rebound came first, through the night, and reached 98.82, 10 cents above that projection. The alternative, a settle above 99.45, did not print. The other side named a move beneath Monday's 95.15 low before any rebound. The rebound came first; the 95.15 low gave way in the 8:30 AM ET bar. The macro override named a confirmed breakdown of US and Iran talks. The review records reports on diplomacy carried by the feeds, not a confirmed breakdown.
The overnight session as of 10:15 PM ET, and a new band at 96.40 to 96.70 above the 95.36 print
Globex reopened for Wednesday at 6:00 PM ET on Tuesday. The first five bars all traded across the 96.40 to 96.70 area that later became the band: the 6:00 PM ET bar ran 96.64 to 96.82 and the 6:30 PM ET bar 95.73 to 96.80. The 8:00 PM ET bar reached 97.15, the overnight high as of 10:15 PM ET. It closed at 95.97, 1.18 beneath that high. The 30-minute closes eased to 95.16 by the 9:30 PM ET bar, which made the 94.90 low. No bar after the 8:00 PM ET bar reached the band. As of 10:15 PM ET the contract traded at 95.36, in a 10:00 PM ET bar that was still forming.
Two references gave way overnight. The trade moved beneath the 50 percent retracement of the four-week range at 95.49. At the low it also moved beneath the 94.97 stochastic projection. Between 8:16 PM ET and 9:11 PM ET the news feed carried projections of US election results; the series does not establish that any headline caused a particular move. The review notes that equity index futures fell more than 1 percent over the same hours.
The original band was never reached. That band ran 97.70 to 98.00, and the 97.15 overnight high sat 55 cents beneath it. With the market 2.34 beneath it as of 10:15 PM ET, the review moved the setup to a band nearer the market. Every Tuesday measurement is unchanged. The map moved down 1.55, the gap between the old and new midpoints.
The new band, 96.40 to 96.70, sits between the Pivot Point at 96.17 and the 96.76 post-settlement print. It sits above both reference prices. Its bottom is 31 cents over the 96.09 settle and 1.04 over the 95.36 print as of 10:15 PM ET. The stop at 97.30 sits 15 cents above the 97.15 overnight high. Target 1, 95.80, sits 29 cents beneath the settle but 44 cents above the print. Target 2, 95.05, sits beneath the print and 15 cents above the 94.90 overnight low. Target 3, 94.30, sits beneath both, 2 cents above the 94.28 published target price. So the short asks for a rebound into the band before any decline.
Tuesday's high came before its low. Through the overnight hours the 30-minute closes ranged between 96.27 and 98.57, the close of the 6:30 AM ET bar. The 7:00 AM ET bar made the high and closed at 96.93, 1.89 beneath it. The 8:00 AM ET bar closed at 95.68 and the 8:30 AM ET bar at 94.58. The 9:00 AM ET bar recovered to 96.14. From the 9:30 AM ET bar through the 3:30 PM ET bar the bars stayed between 95.54 and 96.80. Settlement came at 2:30 PM ET.
Tuesday printed a lower high and a lower low. Its 98.82 high sat 3.93 beneath Monday's 102.75, and its 93.59 low sat 1.56 beneath Monday's 95.15. Settlements over eight sessions read 103.27, 101.76, 99.90, 102.78, 102.00, 104.12, 96.46 and 96.09. The contract fell on Monday and Tuesday after Friday's 2.12 gain. Over five sessions it is down 3.81 from the 99.90 settle of 10/27. The weekly bar for the week of October 26 spanned 104.99 to 99.44. The provider publishes 104.99 as the 52-week, 13-week and one-month high and 86.00 as the one-month low.
The four-hour bars show the turn. The 6:00 PM ET bar closed at 96.61 and the 10:00 PM ET bar at 97.96. The 6:00 AM ET bar made both the session high and low. It fell 1.68 from its 97.54 open to 95.86, the largest decline of the six. The 10:00 AM ET bar closed at 95.89, near its open. Ten sessions of daily ranges read 4.14, 2.45, 5.08, 2.80, 3.38, 3.80, 3.21, 2.56, 7.60 and 5.23, so Tuesday's was the second widest after Monday's.
Resistance starts 8 cents up, at the Pivot Point at 96.17. Tuesday's 96.30 open, Monday's 96.46 settle and the 96.76 post-settlement print follow. The 97.15 overnight high comes next, then the 20-day average at 97.21, which the review's list leaves out. The 97.74 retracement, the 98.52 crossing price, the 98.72 projection, Pivot R1 at 98.74 and Tuesday's 98.82 high form the next band. One standard deviation resistance at 99.84 follows. The 100.15 top of one average true range comes next, also missing from the review's list. The 5-day at 100.29, the 100.80 crossing price, two standard deviations resistance at 101.39 and Pivot R2 at 101.40 come after.
Support starts 60 cents down, at the 95.49 retracement. Monday's 95.15 low, which the review's list skips, sits beneath it. The 94.97 projection follows. The 94.28 target price, the 93.92 crossing price, Tuesday's 93.59 low and Pivot S1 at 93.51 form the next band. The 93.25 retracement and one standard deviation support at 92.34 come next. The list then skips the 92.03 bottom of one average true range and the 50-day at 91.61, which sit above Pivot S2 at 90.94. As of 10:15 PM ET the nearest references above the 95.36 print are the 95.49 retracement, 13 cents up, then the settle and the Pivot Point. Beneath it sit Monday's 95.15 low, 21 cents down, the 94.97 projection and the 94.90 overnight low.
The averages split around price. The settle sits 4.20 beneath the 5-day at 100.29 and 1.12 beneath the 20-day at 97.21. It sits 4.48 above the 50-day at 91.61, 12.83 above the 100-day at 83.26 and 18.10 above the 200-day at 77.99. The 5-day fell 76 cents from 101.05 as the 10/27 settle of 99.90 left the window. The 20-day rose 38 cents from 96.82 as the 10/06 settle of 88.43 left it. The stack beneath stays in order. The 30 older settlements in the 50-day window averaged 87.88, the 50 older ones in the 100-day window 74.92 and the 100 older ones in the 200-day window 72.73. Wednesday's crossing prices are 100.80 for the 9-day, 98.52 for the 18-day and 93.92 for the 40-day.
Momentum stayed soft. Relative strength reads 44.57 on the 9-day, 50.12 on the 14-day and 53.17 on the 20-day. The raw stochastics read 21.93 percent on the 9-day and 28.97 percent on the 14-day. The 14-day %K at 51.58 percent sits beneath %D at 71.24 percent. Negative direction leads on the 9-day, 23.16 against 17.39, with the ADX at 51.04. Positive direction holds a narrow lead on the 14-day, 19.74 against 18.58, with the ADX at 42.58. Historic volatility reads 51.97 percent and 44.81 percent.
The composite multi-indicator read for Wednesday is 8 percent buy, unchanged from the prior session. It read 96 percent buy a week ago and 40 percent a month ago. Its signal strength is described as soft and its direction as weakest. The short horizon group averages 40 percent sell, the medium 25 percent buy and the long 67 percent buy, and the trend composite reads hold. These are the provider's published readings, read at 6:26 PM ET on Tuesday after the Globex reopen; the page may already reflect the reopened session's price.
Average ranges sit near 4 points. The 14-day average true range stands at 4.06 points, about 4.2 percent of the settle, and the 14-day average daily range at 4.12. The 9-day figures are 4.31 and 4.01 and the 20-day 3.86 and 3.82. One average true range either side of the settle spans 92.03 to 100.15. The deviation bands, built from five settlements and centred on the settle, run 92.34 to 99.84, 90.79 to 101.39 and 89.60 to 102.58. They describe dispersion only.
Diplomacy reports, an industry draw estimate and wider product margins
Diplomacy reports ran all day. At 1:40 AM ET the news feed carried a senior Iranian official saying the two sides were far from a deal. At 8:26 AM ET it carried a regional press report of concessions on the nuclear programme and frozen funds. At 10:14 AM ET and 10:16 AM ET it carried Iranian state media saying no new development had been reached and rejecting reports that a deal was close. At 11:04 AM ET it carried an Iranian official saying there was no deadline for exchanging messages through mediators. These are reports carried by the feeds, not confirmed events.
The review places the 8:26 AM ET press report on concessions inside the 8:00 AM ET bar, which coincided with it; the series does not establish that any headline caused a particular move. A press report at 1:19 PM ET said the administration was negotiating an agreement with Venezuela, as carried by the feeds.
Supply drew comment only. The commodity feed carried commentary on the state oil company of the largest Gulf producer and on reduced investment by the largest oil companies; these are commentary items, not supply decisions. The producer group's monthly report is listed for Wednesday, November 11, 2026 at 8:00 AM ET by the news-feed calendar, unconfirmed.
Inventories came after the settle. The 4:30 PM ET bar closed at 96.76. At 4:54 PM ET the news feed carried the industry estimate of a 5.267 million barrel crude draw against a forecast build of 2.1 million and a prior draw of 2.031 million. The same estimate put gasoline up 1.427 million barrels, distillates down 1.192 million and Cushing up 0.511 million. The calendar lists the government petroleum status report for 10:30 AM ET on Wednesday, November 4, 2026.
Products rose while crude fell. In the provider's daily record December heating oil settled at 4.5306 dollars a gallon, up 2.47 percent, and December gasoline at 2.9355, up 1.22 percent. The heating oil margin is 42 gallons times the heating oil settle less the WTI settle. Against December WTI it widened to 94.20 dollars a barrel from 89.25. The gasoline margin widened to 27.20 from 25.34.
Other markets moved on the same day. The dollar index's daily record closed at 101.87 against 101.75. The ten-year yield index closed at 4.95 percent against 4.89 percent. Gold's December contract fell 0.74 percent and silver 2.23 percent. The S&P 500 cash index rose 0.36 percent and the Nasdaq-100 0.68 percent. The provider's commentary attributed the dollar's firmness to stronger JOLTS and factory orders figures, per the provider's commentary and unconfirmed. Those reports came at 10:00 AM ET on Tuesday, as the calendar lists them: 7.523 million openings against a forecast of 7.164 million, and a 1.8 percent rise in orders against 1.2 percent, per the news feed.
December open interest stood at 236,239 on Monday, against 257,459 on Friday. Tuesday's open interest had not been reported in final form. Tuesday's December volume was 348,750 contracts against 390,924 on Monday. December's premium over January narrowed to 1.32 from 1.66. Brent's January premium over January WTI narrowed to 8.83 from 9.97. No dealer-positioning dataset was read for crude.
The trade map for Wednesday
The review's setup stays short on the December contract, now from 96.40 to 96.70, set at 10:15 PM ET from the overnight trade. The overnight session traded beneath the 95.49 retracement after failing at 97.15. The composite holds at 8 percent buy with direction described as weakest. Negative direction leads on the 9-day directional system. In the review's reading, a rebound into the band, between the Pivot Point at 96.17 and the 96.76 post-settlement print, offers a short with a defined risk point above the 97.15 overnight high. In the review's reading, the 10:30 AM ET inventory report could carry price through the band. The review calls the setup an analyst judgment that rebounds toward the post-settlement print are sold, not a measured edge. It replaces the 97.70 to 98.00 band, which the overnight session did not reach.
Now the arithmetic. From the 96.55 midpoint the risk to the stop is 75 cents, 18.5 percent of the 14-day average true range of 4.06. The targets sit 75 cents, 1.50 and 2.25 beneath the midpoint. That is exactly 1, 2 and 3 times the risk. The whole band sits above the settle, its bottom 31 cents and its top 61 cents over it. Against the 95.36 print as of 10:15 PM ET, the bottom sits 1.04 higher and the top 1.34. Target 1 sits 29 cents beneath the settle and 44 cents above the print. Target 2 sits 1.04 beneath the settle and 31 cents beneath the print. Target 3 sits 1.79 beneath the settle and 60 cents beneath the 94.90 overnight low.
Scenario ranges in the review are analyst judgment. The low-range case runs 94.60 to 96.20, the most likely 93.80 to 96.80 and the high-range case 93.00 to 97.80. For the rest of the night session the review's bias is lower beneath the Pivot Point at 96.17. Its expected band runs roughly 94.70 to 95.90. That bottom sits 20 cents beneath the 94.90 overnight low.
London starts at 3:00 AM ET and runs roughly 94.50 to 96.30. Its bias is neutral to lower beneath the Pivot Point at 96.17, and the band's top sits 13 cents above that pivot. European services surveys are listed between 3:50 AM ET and 4:30 AM ET by the news-feed calendar, unconfirmed. The morning band runs roughly 93.80 to 96.80, with the setup band near the top; its 96.70 top sits 10 cents beneath 96.80. The calendar lists the trade report at 8:30 AM ET, before that window opens. The private payrolls estimate is listed for 8:15 AM ET and the services purchasing managers' survey for 10:00 AM ET, per the news-feed calendar and unconfirmed.
Then comes the report. The review treats the government petroleum status report at 10:30 AM ET, as the calendar lists it, as the first scheduled test of the industry estimate. The afternoon runs roughly 93.80 to 96.80, and crude settles at 2:30 PM ET. In the review's judgment the first-order event for crude on Wednesday is that report, with US and Iran diplomacy headlines the main unscheduled source of volatility. The calendar lists preliminary productivity and costs at 8:30 AM ET on Thursday, November 5, and the employment situation report at 8:30 AM ET on Friday, November 6.
The review also weighs the path. In the review's analyst judgment, revised at 10:15 PM ET, the most probable path holds the contract between Pivot S1 at 93.51 and the 97.15 overnight high. It pictures a rebound toward the Pivot Point at 96.17 and the 96.76 print that stalls beneath the overnight high. That path is weighted above a recovery through the 97.74 retracement. In the review's reading, the industry draw and the 2.47 percent gain in heating oil point to support beneath the market. The alternative that would invalidate this reading is a settle above 97.74. That could bring Pivot R1 at 98.74 into play. On the other side, a move beneath the 94.28 target price before any rebound could bring Pivot S1 and one standard deviation support at 92.34 into play without the rebound the setup needs.
The 95.36 print sits 1.04 beneath the band. The setup needs that gap closed first.
The complete data picture
Every number behind Wednesday’s plan, charted first, then the full level lists, then the complete numeric reference underneath. Every price is the December contract unless January is named.
Full numeric reference, every remaining figure from the session review
1. Executive Summary
The December crude contract settled at 96.09 on Tuesday, down 0.37 or 0.38 percent from Monday's settle of 96.46, after trading between 98.82 and 93.59, a 5.23 point daily range. The settle finished at 47.8 percent of the range, and the range was 1.27 multiples of the 14-day average daily range of 4.12 points. Tuesday printed a lower high, 3.93 beneath Monday's 102.75, and a lower low, 1.56 beneath Monday's 95.15, and it was the second consecutive lower settle. The 96.09 settle is the lowest since 10/14/26, when the contract settled at 93.90, and the 93.59 low is the lowest since the 92.46 low of 10/15/26.
The session carried two directions. The overnight hours rose to the 98.82 high in the 7:00 AM ET bar, and the morning then fell to the 93.59 low in the 8:30 AM ET bar before the cash-hours trade held between 95.54 and 96.80. The news feed carried at 8:26 AM ET a regional press report that Washington and Tehran had made concessions on the nuclear programme and frozen funds, and at 10:14 AM ET and 10:16 AM ET Iranian state media saying no new development had been reached and rejecting reports that a deal was close; these are reports carried by the feeds, not confirmed events.
Brent's January contract settled at 103.60, down 1.17 or 1.12 percent, while gasoline rose 1.22 percent and heating oil 2.47 percent. After the settle the news feed carried an industry estimate of a 5.267 million barrel crude draw against a forecast build of 2.1 million; the contract traded at 96.76 in the 4:30 PM ET bar, 0.67 above the settle.
The composite multi-indicator read published for Wednesday is "8% BUY" with strength "Soft" and direction "Weakest", unchanged from "8% BUY" a session earlier. The Primary Setup in section 8, revised at 10:15 PM ET after the overnight session, is a short from the 96.40 to 96.70 band between the Pivot Point at 96.17 and the 96.76 post-settlement print, stopped at 97.30, with objectives at 95.80, 95.05 and an extended 94.30.
Overnight update, 10:15 PM ET Tuesday. The reopened Globex session for Wednesday traded from a 97.15 high in the 8:00 PM ET bar to a 94.90 low in the 9:30 PM ET bar, and the contract traded at 95.36 as of 10:15 PM ET, 0.73 or 0.76 percent beneath Tuesday's settle. The 8:00 PM ET bar closed at 95.97, 1.18 beneath its high, and the 30-minute closes eased to 95.16 by the 9:30 PM ET bar, taking the contract beneath the 50 percent retracement of the four-week range at 95.49 and, at the low, beneath the 94.97 stochastic projection. Between 8:16 PM ET and 9:11 PM ET the news feed carried projections of US election results; these are items carried by the news feed, not confirmed events, and the series does not establish that any headline caused a particular move. Equity index futures fell more than 1 percent over the same hours.
The original Primary Setup band of 97.70 to 98.00 was not reached overnight; the session high of 97.15 sat 0.55 beneath it. With the market 2.34 beneath the band as of 10:15 PM ET, the setup in section 8 is moved to a band nearer the market. Every Tuesday measurement in this review is unchanged.
2. Price Action & Technical Structure
2.1 Intraday and Session Review
The Tuesday session opened at 96.30 at the Monday 6:00 PM ET reopen, 0.16 beneath Monday's settle, and the preserved 30-minute series on the continuous symbol places the high of 98.82 in the 7:00 AM ET bar and the low of 93.59 in the 8:30 AM ET bar. Through the overnight hours the 30-minute closes ranged between 96.27 and 98.57, the close of the 6:30 AM ET bar.
The 7:00 AM ET bar made the session high and closed at 96.93, 1.89 beneath the high. The 8:00 AM ET bar closed at 95.68 and the 8:30 AM ET bar made the low and closed at 94.58; the 8:26 AM ET press report on concessions coincided with the 8:00 AM ET bar. The 9:00 AM ET bar recovered to 96.14, and from the 9:30 AM ET bar through the 3:30 PM ET bar the 30-minute bars stayed between 95.54 and 96.80, with the settle fixed at 2:30 PM ET. The 4:30 PM ET bar closed at 96.76, the post-settlement print. The series does not establish that any headline caused a particular move.
The open, high and low on the provider's overview page now belong to the Globex session that reopened at 6:00 PM ET for Wednesday, so Tuesday's completed range is taken from the settlement record and the published pivot ladder. Pivot R3 at 103.97 minus Pivot S3 at 88.28, divided by three, returns 5.23, and Pivot R2 at 101.40 minus Pivot S2 at 90.94, divided by two, returns the same 5.23. Three times the Pivot Point of 96.17 less the 96.09 settle gives a high plus low sum of 192.42, which solves to a high of 98.82 and a low of 93.59 within published rounding; that pair reproduces all seven published rungs. These are the completed-session inputs behind the published pivot ladder rather than an independently read bar, and they are corroborated by the provider's settlement row and the chart's completed daily bar, which carry the same 96.30 open, 98.82 high, 93.59 low and 96.09 settle.
2.2 Daily Structure
Tuesday printed a lower high and a lower low against Monday. Settlements over the last eight sessions read 103.27, 101.76, 99.90, 102.78, 102.00, 104.12, 96.46 and 96.09, so the contract has fallen on Monday and Tuesday after Friday's 2.12 gain. Over five sessions the contract is down 3.81 from the 99.90 settle of 10/27.
The weekly bar for the week of October 26 spanned 104.99 to 99.44. The provider publishes 104.99 as the 52-week, 13-week and one-month high and 86.00 as the one-month low.
2.3 4-Hour and Swing Structure
The four-hour bars for Tuesday's session, read from the chart, show the 6:00 PM ET bar closing at 96.61 and the 10:00 PM ET bar at 97.96. The 6:00 AM ET bar made both the session high and low and fell 1.68 from its 97.54 open to 95.86, the largest decline of the six, and the 10:00 AM ET bar closed at 95.89, near its open.
Daily ranges for the last ten sessions, from 10/21, ran 4.14, 2.45, 5.08, 2.80, 3.38, 3.80, 3.21, 2.56, 7.60 and 5.23, so Tuesday's range was the second widest of the ten after Monday's 7.60. The published grid places the 38.2 percent retracement from the four-week high at 97.74 and the 50 percent retracement of the four-week range at 95.49.
2.4 Moving Averages
The averages cited here were computed for this review from the provider's daily settlement series for the December contract, which holds 259 completed sessions from 10/23/25 through Tuesday; the partial row of the reopened Wednesday session is excluded, and each average is carried at full precision and rounded once to the cent. The 5-day average stands at 100.29, the 20-day at 97.21, the 50-day at 91.61, the 100-day at 83.26 and the 200-day at 77.99.
The 96.09 settle sits 4.20 beneath the 5-day average and 1.12 beneath the 20-day, and 4.48 above the 50-day, 12.83 above the 100-day and 18.10 above the 200-day. The 5-day average fell from Monday's 101.05 as Tuesday's settle replaced the 10/27 settle of 99.90, and the 20-day rose from 96.82 as the 10/06 settle of 88.43 left the window.
The 20-day average sits above the 50-day because the 30 older settlements in the 50-day window averaged lower, at 87.88. The 50-day sits above the 100-day because the 50 older settlements in the 100-day window averaged lower, at 74.92, and the 100-day sits above the 200-day because the 100 older settlements in the 200-day window averaged lower, at 72.73. The projection grid gives 100.80 as the price at which the 9-day average would be crossed on Wednesday.
2.5 Oscillator and Trend Readings
The oscillator figures below are as published on the provider's technical page, read at 6:26 PM ET on Tuesday after the Globex reopen; they are the provider's readings, not this review's computations, and the page may already reflect the reopened session's price. The 9-day relative strength reads 44.57, the 14-day relative strength 50.12 and the 20-day relative strength 53.17.
The 9-day raw stochastic reads 21.93 percent and the 14-day raw stochastic 28.97 percent, while the 14-day stochastic %K reads 51.58 percent and the 14-day stochastic %D 71.24 percent. The 9-day directional index ADX reads 51.04 with the 9-day +DI at 17.39 and the 9-day -DI at 23.16, so negative direction leads on the 9-day system; the 14-day directional index ADX reads 42.58 with the 14-day +DI at 19.74 and the 14-day -DI at 18.58, a narrow positive lead. The 9-day historic volatility reads 51.97 percent and the 14-day historic volatility 44.81 percent.
The composite multi-indicator read published for the Wednesday session is "8% BUY", with signal strength "Soft" and direction "Weakest". The snapshot history reads "8% BUY" for the prior session, "96% BUY" a week ago and "40% BUY" a month ago. The short horizon group averages "40% SELL", the medium group "25% BUY" and the long group "67% BUY", and the trend composite reads "HOLD".
2.6 Volatility and Expected Range
The published 14-day average true range stands at 4.06 points and the 14-day average daily range at 4.12 points; the 9-day average true range is 4.31 with a 9-day average daily range of 4.01, and the 20-day average true range is 3.86 with a 20-day average daily range of 3.82. Tuesday's 5.23 point range was 1.27 multiples of the 14-day average daily range.
Adding and subtracting the 14-day average true range of 4.06 from the 96.09 settle frames Wednesday between 92.03 and 100.15. The published standard-deviation bands, built from five settlements, span 92.34 to 99.84 at one deviation, 90.79 to 101.39 at two and 89.60 to 102.58 at three. These bands describe dispersion, not intraday reach.
3. Key Levels
3.1 Resistance
Above the 96.09 settle, the first references are the Pivot Point at 96.17 and the 96.76 post-settlement print. The 97.74 retracement from the four-week high, the 98.52 price that would cross the 18-day average, the 98.72 projection for a 50 percent raw stochastic, Pivot R1 at 98.74 and Tuesday's 98.82 high form the next band. One standard deviation resistance at 99.84, the 100.29 5-day average and the 100.80 9-day crossing price are the extended references, with Pivot R2 at 101.40 beyond. As of 10:15 PM ET, with the contract at 95.36, the nearest reference above the reopened market is the 95.49 retracement, 0.13 above, followed by the 96.09 settle, the Pivot Point at 96.17, the 96.76 post-settlement print and the 97.15 overnight high.
3.2 Support
Beneath the settle sit the 50 percent retracement of the four-week range at 95.49 and the 94.97 projection for a 20 percent raw stochastic. The published target price at 94.28, the 93.92 price that would cross the 40-day average, Tuesday's 93.59 low and Pivot S1 at 93.51 form the next band. The 38.2 percent retracement from the four-week low at 93.25 and one standard deviation support at 92.34 are the deeper references, with Pivot S2 at 90.94 beyond. As of 10:15 PM ET the overnight session had traded to 94.90, beneath the 95.49 retracement and the 94.97 projection, and with the contract at 95.36 Monday's 95.15 low, the 94.97 projection and the 94.90 overnight low sit nearest beneath the market, with the 94.28 target price and Pivot S1 at 93.51 further down.
4. Macro Drivers
4.1 OPEC and Supply Policy (Quotas, Compliance, Saudi/Russia Signals)
The feeds for Tuesday contain commentary rather than producer-group decisions, per the news feed and unconfirmed. The producer group's monthly report is listed for Wednesday, November 11, 2026 at 8:00 AM ET by the news-feed calendar, unconfirmed. The commodity feed carried commentary on the state oil company of the largest Gulf producer and on reduced investment by the largest oil companies; these are commentary items, not supply decisions.
4.2 EIA and API Inventory (Crude Stocks, Gasoline, Distillates, Cushing, SPR)
After the settle, at 4:54 PM ET, the news feed carried the industry estimate of a 5.267 million barrel crude draw against a forecast build of 2.1 million and a prior draw of 2.031 million, with gasoline up 1.427 million, distillates down 1.192 million and Cushing up 0.511 million. The 4:30 PM ET bar closed at 96.76. The government petroleum status report is scheduled for 10:30 AM ET on Wednesday, November 4, 2026, as the calendar lists it.
4.3 Geopolitical Backdrop (Middle East, Iran, Russia/Ukraine, Venezuela)
The news feed carried at 1:40 AM ET a senior Iranian official saying the two sides were far from a deal, at 8:26 AM ET a regional press report of concessions on the nuclear programme and frozen funds, and at 10:14 AM ET and 10:16 AM ET Iranian state media rejecting reports that a deal was close. At 11:04 AM ET it carried an Iranian official saying there was no deadline for exchanging messages through mediators. A press report at 1:19 PM ET said the administration was negotiating an agreement with Venezuela. These are reports carried by the feeds, not events confirmed for this review.
4.4 Demand and Refining (Refinery Utilization, Crack Spreads, Seasonal Pattern)
Heating oil's December contract settled at 4.5306 dollars a gallon, up 2.47 percent, and gasoline's December contract at 2.9355, up 1.22 percent, while crude fell. Measured on the December contracts, the heating oil margin over December WTI widened to 94.20 dollars a barrel from 89.25 and the gasoline margin to 27.20 from 25.34.
4.5 Dollar and Cross-Asset (DXY, Commodities Complex, Equity Risk-On/Off)
The dollar index's daily record closed at 101.87 against 101.75. The ten-year yield index closed at 4.95 percent; Monday's close was 4.89 percent. Gold's December contract fell 0.74 percent and silver 2.23 percent, while the S&P 500 cash index rose 0.36 percent and the Nasdaq-100 0.68 percent. The provider's commentary attributed the dollar's firmness to stronger JOLTS and factory orders figures, per the provider's commentary and unconfirmed.
4.6 Institutional Positioning (COT, Money Manager vs Commercial Hedger, Speculator Length)
Open interest on the December contract stood at 236,239 on Monday per the settlement record; Tuesday's figure had not been reported in final form, and Tuesday's December volume was 348,750 contracts against 390,924 on Monday. December's premium over January narrowed to 1.32 from 1.66, and Brent's January premium over January WTI narrowed to 8.83 from 9.97.
5. No Liquid Options Proxy
This review covers crude without a positioning dataset. There is no dealer-positioning surface read for this instrument in this review, no gamma map, no options concentration levels and no flow attribution, and none is inferred from any other instrument. Every level in section 3 originates in published pivot arithmetic, published standard-deviation bands, published retracement and moving-average projections, settlement averages computed from the provider's daily record, or the completed-session extremes described in section 2.1.
This is a statement about coverage, not about the existence of listed crude options. No such dataset was read for this review, so no claim resting on one appears anywhere in this review or in this outlook. The positioning inputs used for crude are the Brent spread, the front calendar spread, the product margins and the open-interest and volume record.
6. Forecast
6.1 Night Session (6:00 PM ET Tuesday to 3:00 AM ET Wednesday, Globex/Asia)
Globex reopened at 6:00 PM ET after the 4:54 PM ET industry inventory estimate and, as of 10:15 PM ET, had traded from the 97.15 high in the 8:00 PM ET bar to the 94.90 low in the 9:30 PM ET bar. Bias lower beneath the Pivot Point at 96.17, expected band for the rest of the session roughly 94.70 to 95.90.
6.2 London Session (3:00 AM ET to 8:00 AM ET Wednesday)
From 3:00 AM ET European trading opens with European services surveys listed between 3:50 AM ET and 4:30 AM ET by the news-feed calendar, unconfirmed. Bias neutral to lower beneath the Pivot Point at 96.17, expected band roughly 94.50 to 96.30.
6.3 Morning Session (9:00 AM ET to 12:00 PM ET Wednesday, US Open / Pit Session)
The government petroleum status report at 10:30 AM ET on Wednesday, November 4, 2026, as the calendar lists it, is the first scheduled test of the industry estimate. The trade report is scheduled for 8:30 AM ET the same day, as the calendar lists it. Expected band roughly 93.80 to 96.80, with the 96.40 to 96.70 setup band near the top.
6.4 Afternoon Session (12:00 PM ET to 2:30 PM ET Wednesday, NYMEX Pit Close)
The settlement at 2:30 PM ET fixes the reference after the inventory report, with US and Iran diplomacy headlines the main unscheduled source of movement, in this review's judgment. Expected band roughly 93.80 to 96.80.
6.5 Night Session Forward (6:00 PM ET Wednesday)
The Wednesday evening session at 6:00 PM ET carries the settle into Thursday. The employment situation report is scheduled for 8:30 AM ET on Friday, November 6, 2026, as the calendar lists it.
6.6 Expected Range (Wednesday Full Session)
Low-range scenario: 94.60 to 96.20
Mid-range scenario (most likely): 93.80 to 96.80
High-range scenario: 93.00 to 97.80
6.7 Most Likely Path
In this review's analyst judgment, revised at 10:15 PM ET, the most probable path holds the contract between Pivot S1 at 93.51 and the 97.15 overnight high, with a rebound toward the Pivot Point at 96.17 and the 96.76 post-settlement print that stalls beneath the overnight high weighted above a recovery through the 97.74 retracement. The composite holds at "8% BUY" with direction "Weakest", the settle sits beneath the 5-day and 20-day averages and negative direction leads on the 9-day system, while the industry inventory draw and the 2.47 percent gain in heating oil point to support beneath the market.
The alternative that would invalidate this reading is a settle above the 97.74 retracement from the four-week high, which would bring Pivot R1 at 98.74 into play. On the other side, a move beneath the 94.28 target price before any rebound would bring Pivot S1 at 93.51 and one standard deviation support at 92.34 into play without the rebound the setup needs.
7. Wednesday Economic Calendar
Tuesday's releases are complete. The JOLTS report and factory orders, both released at 10:00 AM ET on Tuesday, November 3, 2026, as the calendar lists it, came in at 7.523 million openings against a forecast of 7.164 million and a 1.8 percent rise in orders against 1.2 percent, per the news feed. The midterm elections took place on Tuesday, per the news-feed calendar and unconfirmed, and the industry inventory estimate was released after the settle.
On Wednesday, November 4, 2026, the trade report is scheduled for 8:30 AM ET and the government petroleum status report for 10:30 AM ET, both as the calendar lists them. The private payrolls estimate is listed for 8:15 AM ET and the services purchasing managers' survey for 10:00 AM ET, per the news-feed calendar and unconfirmed.
Later in the week, preliminary productivity and costs are scheduled for 8:30 AM ET on Thursday, November 5, 2026 and the employment situation report for 8:30 AM ET on Friday, November 6, 2026, both as the calendar lists them. In this review's judgment the first-order event for crude on Wednesday is the government petroleum status report at 10:30 AM ET, which tests the industry draw estimate, with US and Iran diplomacy headlines the main unscheduled source of volatility.
8. Primary Trade Setup
Direction: Short
Rationale: The overnight session traded beneath the 95.49 retracement after failing at 97.15, the composite holds at "8% BUY" with direction "Weakest" and negative direction leads on the 9-day directional system. A rebound into the 96.40 to 96.70 band, between the Pivot Point at 96.17 and the 96.76 post-settlement print, offers a short with a defined risk point above the 97.15 overnight high. The 10:30 AM ET inventory report can carry price through the band, so the setup is an analyst judgment that rebounds toward the post-settlement print are sold, not a measured edge. This setup replaces the 97.70 to 98.00 band, which the overnight session did not reach.
Entry Zone: 96.40 to 96.70
Stop Loss: 97.30 (above the 97.15 overnight high)
Target 1 (T1): 95.80 (beneath the 96.17 Pivot Point and above the 95.49 retracement)
Target 2 (T2): 95.05 (above the 94.97 stochastic projection)
Target 3 (T3, extended): 94.30 (above the 94.28 published target price)
Risk-to-Reward: Approximately 1:1 to T1, 1:2 to T2, 1:3 to T3
Invalidation: A settle above the 97.74 retracement from the four-week high negates the thesis. Short of that, the edge is removed by acceptance above the entry band rather than by a touch, defined as two consecutive 30-minute closes above 96.70.
Macro override: A government report confirming a large draw, or a confirmed breakdown of US and Iran talks, would lift the contract. In that scenario a move through the 97.30 stop invalidates the short before the targets, and the 97.74 retracement becomes the reference, 0.44 beyond the stop and inside one 14-day average true range of 4.06.
Sources and methodology
This outlook is built from our session review of the December WTI crude contract (CLZ26), prepared after Tuesday's close on November 3, 2026 for the Wednesday, November 4, 2026 session, and updated at 10:15 PM ET on Tuesday from the reopened session's trade. December is the contract the chart's continuous symbol tracks. Tuesday's completed extremes are the inputs behind the published pivot ladder: Pivot R3 at 103.97 less Pivot S3 at 88.28, divided by three, and Pivot R2 at 101.40 less Pivot S2 at 90.94, divided by two, both return 5.23. Three times the 96.17 Pivot Point less the 96.09 settle gives 192.42, which the 98.82 high and 93.59 low reproduce within published rounding. The provider's settlement row and the chart's completed Tuesday bar carry the same 96.30 open, extremes and settle.
Tuesday's card was written on the December contract and is graded on the provider's December settlement row for 11/03 (open 96.30, high 98.82, low 93.59, settle 96.09, volume 348,750). The order of events within Tuesday comes from the preserved 30-minute bars on the continuous symbol, 46 bars from the Monday 6:00 PM ET reopen to the 4:30 PM ET bar, labelled in Eastern standard time. Wednesday's overnight prices come from the same 30-minute series for the session that reopened at 6:00 PM ET, nine bars to 10:15 PM ET with the 10:00 PM ET bar still forming; they are live-session prices, not settlements. No price move is tied to a headline by this outlook.
The moving averages were computed from the provider's daily settlement series for December, 259 completed sessions from 10/23/25 through Tuesday; the partial row of the reopened Wednesday session is excluded. The oscillators and range averages are cited as published, read at 6:26 PM ET on Tuesday. Tuesday's volume equals the provider's dated row. Monday's 11/02 row has been revised: December volume now reads 390,924 against the 357,697 cited in Tuesday's outlook, and open interest, not reported then, reads 236,239. Tuesday's open interest had not been reported in final form. The S&P 500 percentage is computed from the dated closes of 7,541.40 and 7,568.92. No dealer-positioning dataset was read for crude; the positioning inputs are the Brent spread, the front calendar spread, the product margins and the open-interest and volume record. Scenario ranges are analyst judgment, and items marked unconfirmed come from the news feed or its calendar. Clock times are Eastern standard time, as the review and the calendar state them.
Tuesday’s outlook for this contract is here, and the gold contract’s Tuesday outlook covers the metal whose December contract settled at 3,940.4 on Tuesday, down 0.74 percent. Outlooks for ES, NQ, GC and CL are collected on the market outlook page, and our forward trading record is on the performance statement.