Our Thursday outlook set a long from 7,680 to 7,688 at Wednesday’s settle. Thursday opened at 7,737.25, 49.25 points above that band. Every print before the cash open held at or above 7,691.00. Then the 9:30 AM ET bar fell from 7,707.50 to 7,580.50, through the band and the 7,662 stop in the same bar. No target traded after it. No fill and no result is asserted.
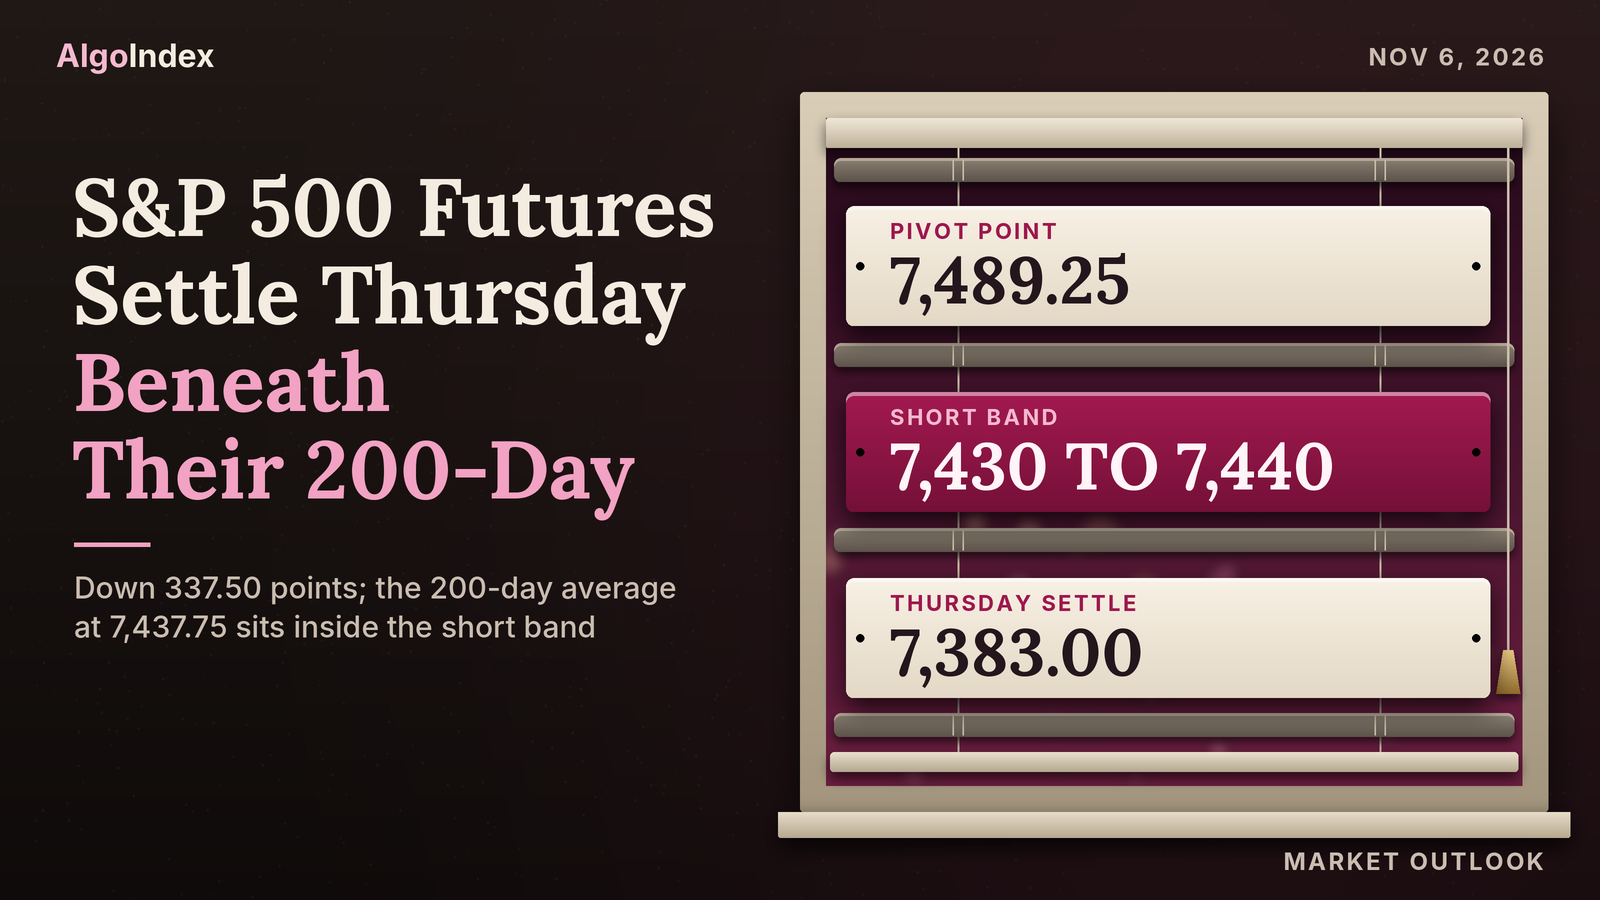
The decline came after the cash open. December E-mini futures settled at 7,383.00 on Thursday, down 337.50 points or 4.37 percent, after a 392.75 point range from 7,738.75 to 7,346.00. The decline is the largest one-session point decline, and the range the widest, of the 259 completed sessions in the series. The high came in the 7:00 AM ET bar and the low in the 4:30 PM ET bar. The settle finished at 9.4 percent of the range.
December S&P 500 futures settled at 7,383.00 on Thursday, beneath every settlement average from the 5-day to the 200-day. Friday’s setup is a short from 7,430 to 7,440. The whole band sits above the settle, its bottom 47.00 points up and 0.73 above the 7,429.27 conversion of the 7,400 support, with the 200-day average at 7,437.75 inside it. The stop is 7,462, 4.25 above the 7,457.75 high of the 2:30 PM ET bar. The first target, 7,408, sits 25.00 above the settle; the second, 7,381, and an extended 7,354 sit beneath it. Per the dataset’s levels, the 7,353.73 cash close sits 46.27 points beneath its 7,400 support, the nearest level in its summary. The employment situation report is scheduled for 8:30 AM ET on Friday, as the calendar lists it.
Thursday’s long met its stop in the bar that reached its band
In Thursday’s outlook we set a long from 7,680 to 7,688 at Wednesday’s settle. Its stop sat at 7,662. The targets were 7,706, 7,728 and an extended 7,750. The card covers the whole Thursday session, from the Wednesday 6:00 PM ET reopen. Thursday’s completed bar, from the review and the dated 2026-11-05 row, opened at 7,737.25. It ranged from 7,738.75 to 7,346.00 and settled at 7,383.00.
The night held above the band. The open sat 9.25 points above the second target. From the reopen through the 9:00 AM ET bar the lowest print was 7,691.00, in the 12:30 AM ET bar, 3.00 above the band top. The 7,706 and 7,728 targets printed in those hours, before any entry. For a long, a target print ahead of the band does not count.
Then the cash open. The 9:30 AM ET bar opened at 7,707.50, 19.50 above the band top. It fell to 7,580.50 and closed at 7,593.75. That one bar reached through the band and through the 7,662 stop, to 81.50 beneath it. Its internal order is not established beyond its open above both. The 10:00 AM ET bar closed at 7,524.25. That pair of closes met the acceptance test the card named, two consecutive 30-minute closes beneath 7,680.
Nothing came back. From the 10:00 AM ET bar on, the highest print was 7,602.75, 59.25 beneath the stop and 103.25 beneath the first target. The extended 7,750 never traded; the 7,738.75 high sat 11.25 beneath it. No fill and no result is asserted.
The thesis line went too. The card negated its thesis on a settle beneath the Pivot Point at 7,652.25. Thursday settled 269.25 points beneath it. Of the card’s ranked paths, this was the second: a settle beneath the Pivot Point that brings the 7,631.88 pivot conversion and the 7,612.88 flip-level conversion into play. Both traded in the 9:30 AM ET bar.
Our ranges held overnight and missed in the cash session. The night session, 6:00 PM to 3:00 AM ET, traded from 7,691.00 to 7,737.25, inside its 7,690 to 7,760 band, its low 1.00 above the bottom. London, 3:00 AM to 8:00 AM ET, traded from 7,704.75 to 7,738.75, inside its 7,685 to 7,760 band. The morning session reached 7,421.00, 249.00 beneath its 7,670 band bottom. The afternoon high of 7,472.00 sat 198.00 beneath the same bottom. Thursday’s 7,346.00 low sat 274.00 beneath even the high-range case, 7,620 to 7,820. We grade the card as written: band and stop in one bar, then the acceptance closes, with no result claimed.
Down 337.50 to 7,383.00 on a 392.75 point range
December E-mini futures settled at 7,383.00 on Thursday, down 337.50 points or 4.37 percent from Wednesday’s 7,720.50. The range ran 392.75 points. That is the widest of the 259 completed sessions in the series, ahead of Wednesday’s 256.25. The range was 3.18 times the 14-day average daily range of 123.64 points. The prior largest one-session decline in the series was 203.25 points, on 06/05/26.
It printed a lower high and a lower low. The 7,738.75 high sat 7.50 beneath Wednesday’s 7,746.25, and the 7,346.00 low sat 144.00 beneath Wednesday’s 7,490.00. The settle came in 107.00 beneath that Wednesday low. It is the lowest settle since the 7,343.00 settle of 05/04/26, and the low is the lowest since the 7,339.25 low of 05/05/26. The decline more than reversed the 146.00 points gained on Tuesday and Wednesday.
The decline came in the cash session. From the reopen to 3:00 AM ET the bars held between 7,691.00 and 7,737.25 and closed that window at 7,709.50. From 3:00 AM ET to the 9:30 AM ET cash open they held between 7,704.75 and 7,738.75, closing at 7,707.50. The 7:00 AM ET bar made the high.
Then three bars carried the largest declines. The 9:30 AM ET bar fell 113.75, from 7,707.50 to 7,593.75, with a low of 7,580.50. No 30-minute bar in the session fell further. The 10:00 AM ET bar fell 69.50 to 7,524.25, with a low of 7,498.00. The 10:30 AM ET bar fell 54.50 to 7,469.75, with a low of 7,421.00. Across those three bars the contract fell 237.75 points, open to close.
Rebounds faded. The 11:00 AM ET bar rose 38.75 to 7,508.50 and the 11:30 AM ET bar reached 7,515.25. From 12:00 PM ET to 2:00 PM ET the bars held between 7,388.00 and 7,472.00. The 2:30 PM ET bar rose 43.50 to 7,447.25, with a high of 7,457.75. No bar gained more. The 3:00 PM ET bar fell 46.50 to 7,400.75.
The close came near the low. The 3:30 PM ET bar closed at 7,381.25, 1.75 beneath the 7,383.00 settle. After the cash close the 4:00 PM ET bar closed at 7,370.75. The 4:30 PM ET bar made the 7,346.00 low and closed at 7,353.00, 30.00 beneath the settle.
The basis narrowed. Thursday’s settle less the 7,353.73 cash close measures 29.27 points, against 31.88 on Wednesday. Every cash equivalent here uses the new figure. The dataset keeps its own 30.43 point offset, 1.16 wider. Its published futures pairs are 8,130.43 for the 8,100 call-side ceiling, 8,030.43 for the 8,000 gamma concentration, 7,715.43 for the 7,685 modeled volatility threshold, 7,674.43 for the 7,644 modeled gamma-flip level and 7,530.43 for the 7,500 put-side support base.
Resistance comes first. It starts 23.28 points above the settle, at the 7,406.28 oscillator stall price. The 7,421.00 low of the 10:30 AM ET bar, the 7,429.27 conversion of the dataset’s 7,400 support and the 200-day average at 7,437.75 follow. Those four span 31.47 points. Then a second band. The 7,457.75 high of the 2:30 PM ET bar (cash 7,428.48), the 7,472.00 top of the midday window, the Pivot Point at 7,489.25 (cash 7,459.98) and Wednesday’s 7,490.00 low sit within 32.25. One standard deviation resistance at 7,505.46 and the one-range frame top at 7,505.59 sit 0.13 apart, with the 7,515.25 high of the 11:30 AM ET bar above them.
Higher up sit the 7,529.27 conversion of the 7,500 put-side base and its 7,530.43 pair. Two deviations at 7,556.19, the 7,556.67 retracement from the four-week low, the 5-day average at 7,577.75 and three deviations at 7,595.12 follow. Pivot R1 at 7,632.50 (cash 7,603.23) and the 7,629.27 conversion of the 7,600 support are the extended references. Beyond them sit the 7,648.06 price that would cross the 9-day average on Friday, the 9-day at 7,655.50 and the flip-level conversion and pair at 7,673.27 and 7,674.43.
The upper references are far off. The 100-day at 7,701.25, the threshold conversion at 7,714.27 and its 7,715.43 pair, the 20-day at 7,719.50 and Wednesday’s 7,720.50 settle come next. Thursday’s 7,737.25 open and 7,738.75 high (cash 7,709.48), the 50-day at 7,742.75 and Wednesday’s 7,746.25 high follow. Pivot R2 at 7,882.00, the 7,897.50 one-month high and the 7,905.00 52-week and 13-week high from 08/13 (cash 7,875.73) sit higher. Pivot R3 at 8,025.25, the 8,030.43 concentration pair and the 8,130.43 ceiling pair complete the list.
Support starts 1.75 points down, at the 7,381.25 close of the 3:30 PM ET bar (cash 7,351.98). The 7,370.75 close of the 4:00 PM ET bar follows. Then a tight group. The 7,355.30 retracement from the 52-week low, the 7,353.00 post-close print, Thursday’s 7,346.00 low (cash 7,316.73), the 7,343.00 settle of 05/04/26, the 7,341.75 published target price and the 7,339.25 low of 05/05/26 sit within 16.05. The settle sits 27.70 above the retracement and 41.25 above the target price.
Beneath that the next band opens. One standard deviation support at 7,260.54 and the one-range frame bottom at 7,260.41 sit 0.13 apart. Pivot S1 at 7,239.75 (cash 7,210.48), the 7,222.18 crossover stall and two deviations at 7,209.81 follow. The 7,185.50 retracement of the 52-week range and three deviations at 7,170.88 come next. Pivot S2 at 7,096.50 (cash 7,067.23), the 7,029.27 conversion of the 7,000 key strike, Pivot S3 at 6,847.00 and the 6,466.00 52-week low are the deeper references.
Every average sits above the settle. It sits 194.75 points beneath the 5-day at 7,577.75, 272.50 beneath the 9-day at 7,655.50 and 336.50 beneath the 20-day at 7,719.50. The longer averages sit further off. It sits 359.75 beneath the 50-day at 7,742.75, 318.25 beneath the 100-day at 7,701.25 and 54.75 beneath the 200-day at 7,437.75. It is the first settle beneath the 200-day among the 60 sessions, from 08/13/26, for which the series supports that average. Each average was rounded once to the 0.25 tick from the 259-session settlement series.
The averages kept their order. The 5-day fell 74.25 from Wednesday’s 7,652.00 as Thursday’s settle replaced the 10/29 settle of 7,754.25. The 200-day rose 1.25 from 7,436.50. The 30 older settlements in the 50-day window averaged 7,758.13, which keeps the 20-day beneath the 50-day. The 50 older settlements in the 100-day window averaged 7,659.99 and the 100 older settlements in the 200-day window 7,174.28. The 200-day window holds 28 rows with no recorded volume from the contract’s thinly traded early months, so that average rests on thin history.
Momentum readings sit low. On the provider’s published readings, taken at 6:26 PM ET on Thursday after the Globex reopen, relative strength reads 29.19 on the 9-day, 32.85 on the 14-day and 36.06 on the 20-day. Those readings may already reflect the reopened session’s price. The raw stochastic reads 7.81 percent on the 9-day and 14-day and 6.84 percent on the 20-day. The smoothed 14-day %K at 32.11 percent sits 6.46 above %D at 25.65 percent.
Direction leads negative. The 9-day ADX reads 26.93, with +DI at 14.23 and -DI at 27.38. The 14-day ADX reads 20.53, with +DI at 14.75 and -DI at 26.85. Negative direction leads on both, by 13.15 and 12.10. Historic volatility reads 26.69 percent on the 9-day and 22.56 percent on the 14-day.
The composite multi-indicator read published for Friday is 72 percent sell, against 48 percent sell a session earlier. Its strength is described as maximum and its direction as strongest, and the trend composite reads sell. A week ago the snapshot read 16 percent buy, and a month ago 80 percent buy. The short-horizon group averages 100 percent sell, the medium-horizon group 50 percent sell and the long-horizon group 33 percent sell.
Thursday’s range ran far past the averages. The 14-day average true range stands at 122.59 points and the 14-day average daily range at 123.64. The 9-day figures are 143.71 and 144.31, the 20-day figures 110.21 and 110.57. One average true range either side of the settle frames Friday between 7,260.41 and 7,505.59. The deviation bands run 7,260.54 to 7,505.46 at one deviation, 7,209.81 to 7,556.19 at two and 7,170.88 to 7,595.12 at three. Built from five settlements, they describe dispersion and say nothing of intraday reach. They are wide after a decline of this size.
Zoom out. Daily ranges over the last ten sessions, from 10/23, ran 65.75, 87.75, 73.00, 69.25, 64.25, 154.75, 123.00, 77.75, 256.25 and 392.75 points. Thursday’s exceeded Wednesday’s by 136.50. Settlements over the last six sessions read 7,754.25, 7,614.00, 7,574.50, 7,596.75, 7,720.50 and 7,383.00. Over five sessions the contract is down 371.25 points from the 7,754.25 settle of 10/29, which the provider publishes as a 4.79 percent five-day change. Thursday’s high sat 166.25 beneath the 7,905.00 52-week high.
The semiconductor index fell 12.25 percent as the volatility index rose to 28.18
News items keep their own times here. None is tied to a price move. The 30-minute bars place Thursday’s high in the 7:00 AM ET bar and the low in the 4:30 PM ET bar, and the bars carry no cause.
The declines were deepest in chips. The S&P 500 cash index closed at 7,353.73, down 334.89 points or 4.36 percent. The Dow industrials fell 3.44 percent and the Nasdaq-100 cash index 6.36 percent. The semiconductor index fell 12.25 percent. Commentary carried by the news feed on the post-election policy outlook, attributed and unconfirmed, described a broad selloff led by technology shares on concerns about artificial-intelligence and data-centre spending. The series does not establish that any single report caused a particular move.
Other markets moved at the same time. The volatility index closed at 28.18, up 69.66 percent from 16.61. The ten-year yield index eased five basis points to 4.84 percent. The dollar index’s daily record held at 101.55 against 101.57. December crude rose 2.72 percent to 90.52 and December gold 0.99 percent to 4,113.5. Yields fell while the contract fell, and nothing in the data separates the effects.
Thursday’s releases are complete. Preliminary productivity was released at 8:30 AM ET on Thursday, November 5, as the calendar lists it. Per the news-feed calendar it came in at 3.6 percent against a forecast of 2.7 percent, with unit labour costs at minus 0.7 percent against a forecast of 0.4 percent. Weekly jobless claims of 189 thousand against a forecast of 196 thousand were listed by the news-feed calendar, unconfirmed. At 9:24 AM ET the news feed carried a Federal Reserve Bank official saying productivity gains reflected adaptation to labour shortages rather than artificial intelligence. The UK central bank raised its rate to 4.00 percent from 3.75 percent, per the news-feed calendar, unconfirmed.
Spending items ran through the session. At 9:27 AM ET the news feed carried a ratings agency saying a major share of planned data-centre capacity may face regulatory hurdles. At 12:01 PM ET it carried a 17 billion dollar data-centre investment by a search company. At 1:39 PM ET it carried 31 billion dollars of orders for a consumer-hardware company’s bond sale. At 2:52 PM ET it carried a request from lawmakers for a briefing from a chip designer’s chief executive on links to China. These are reports carried by the feed.
Two items stay attributed. The news feed carried a report on US and Iran diplomacy, a nuclear proposal sent through an intermediary. It remains a report, unconfirmed, and no move is tied to it. Commentary carried by the news feed on the post-election policy outlook described a continuing rotation, and an investment-bank note described recent breadth as positioning-driven. Both are attributed commentary.
Activity rose. Thursday’s December volume was 3,349,999 contracts on the 2026-11-05 row, against 2,412,784 on Wednesday’s revised 2026-11-04 row, a rise of 937,215 or 38.8 percent. Our Thursday outlook carried the preliminary 2,329,405 for Wednesday. Wednesday’s open interest now reads 1,968,406 on the revised 2026-11-04 row, 9,784 above Tuesday’s 1,958,622. Thursday’s final open interest was not yet reported.
The dealer-positioning dataset used here, the edition timed 5:12 PM ET on Thursday, takes Wednesday’s closes as its reference prices. Its 7,688 index reference sits 0.62 beneath Wednesday’s 7,688.62 cash close. Its 28,437 Nasdaq-100 reference sits 0.17 beneath Wednesday’s 28,437.17. Wednesday’s 7,688.62 less 334.89 points, a 4.36 percent decline, gives the 7,353.73 close. Every level below is read against that close.
The close now sits beneath every model level. It sits 290.27 points beneath the 7,644 modeled gamma-flip level (ES 7,673.27 at the measured basis, dataset pair 7,674.43). It sits 331.27 beneath the 7,685 modeled volatility threshold (ES 7,714.27, pair 7,715.43) and 146.27 beneath the 7,500 put-side support base (ES 7,529.27, pair 7,530.43). The 8,000 gamma concentration sits 646.27 points above the close and the 8,100 call-side ceiling 746.27. In the dataset’s model, gamma tilt reads 1.102, gamma notional 242.076 million dollars and the gamma index 1.443. Its implied moves are 0.60 percent for one day, about 44.12 points on the close, and 1.48 percent for five. Its 25-delta risk reversal reads minus 0.045. The modeled threshold and flip level are model outputs; neither is an option strike.
The dataset draws its own map. Its summary lists resistance at 7,735, 7,760 and 7,800, a dealer-positioning pivot at 7,690 and support at 7,700, 7,600, 7,500 and 7,400. Its key strikes are 8,000, 7,000, 7,700 and 7,800, all in cash. These levels were computed from Wednesday’s closes, and the dataset does not state how they shifted during Thursday’s decline. At the measured basis the 7,400 support converts to 7,429.27, the 7,600 support to 7,629.27 and the 7,000 key strike to 7,029.27. Statements in the dataset about the order of intraday moves are not used; the session path here comes from the futures bars.
The console adds detail. The S&P 500 positioning console, read at 6:18 PM ET, still carried Wednesday’s 7,688.62 as its last close. Its 7,324.65 console price is a console reading and differs from Thursday’s cash close. It shows model call gamma of minus 4.07 billion against put gamma of minus 3.69 billion. One-month implied volatility reads 13.02 percent against realised volatility of 12.47 percent, 0.55 points apart. The implied-volatility rank reads 17.05 percent, the skew rank 62.40 percent and the put-to-call open-interest ratio 1.43. The dataset’s gamma figures and the console’s come from different models and timestamps, and neither is summed with the other.
The nearest key strike sits far below. In the review’s interpretation, a cash close beneath every support level in the dataset’s summary leaves the 7,000 key strike as the nearest key strike beneath the price, 353.73 points lower. In that interpretation the support levels for Friday rest mainly on pivot arithmetic, deviation bands and retracements. Gamma is a damping lens. It carries no direction of its own.
The trade map for Friday
The primary setup for Friday, November 6, is a short from 7,430 to 7,440. It reverses Thursday’s direction, with the band bottom 250.00 points lower. The contract settled at 9.4 percent of the widest range in the series, beneath every settlement average including the 200-day. The composite moved to 72 percent sell with direction strongest. Now the geometry. The whole band sits above Thursday’s settle, its bottom 47.00 points up and its top 57.00 up. So the short asks for a rebound first. The band bottom sits 0.73 above the 7,429.27 conversion of the 7,400 support, and the 200-day average at 7,437.75 sits inside the band. The stop at 7,462 sits 22.00 above the band, 4.25 above the 7,457.75 high of the 2:30 PM ET bar and 27.25 beneath the Pivot Point at 7,489.25. Targets step down from the band. The first, 7,408, sits 1.72 above the 7,406.28 oscillator stall and 25.00 above the settle. The second, 7,381, sits 2.00 beneath the settle. The extended 7,354 sits 8.00 above the 7,346.00 session low and 29.00 beneath the settle. The evidence against is plain. In the review’s words, oscillators are stretched after a 337.50 point decline, and a rebound could run through the band after the 8:30 AM ET report. The review calls the setup an analyst judgment that rebounds into the 200-day average are sold. No measured edge stands behind it.
Now the arithmetic. From the 7,435 midpoint the risk to the stop is 27 points, 22.0 percent of the 14-day average true range of 122.59. The targets sit 27, 54 and 81 points beneath the midpoint. Exact multiples. From the settle the midpoint sits 52.00 points higher, the rebound the setup needs. The invalidation line, the Pivot Point at 7,489.25, sits 27.25 above the stop.
The session bands are the review’s analyst judgment. For the night session, 6:00 PM ET Thursday to 3:00 AM ET Friday, the bias is lower beneath the 7,429.27 conversion, with a band of roughly 7,300 to 7,420. That band tops out 10.00 beneath the setup band. A Federal Reserve Bank official’s remarks at 7:00 PM ET on Thursday are listed by the news-feed calendar, unconfirmed. London, 3:00 AM to 8:00 AM ET, carries a bias lower to neutral beneath the 200-day average at 7,437.75 and runs roughly 7,310 to 7,430, topping out at the band bottom. Remarks by a regional Federal Reserve official at 4:30 AM ET and European retail sales at 5:00 AM ET are listed by the news-feed calendar, unconfirmed.
The employment situation report is scheduled for 8:30 AM ET on Friday, November 6, as the calendar lists it. In the review’s judgment the 9:30 AM ET cash open is the first directional test of the 7,400 support conversion. Two listings follow. The University of Michigan preliminary survey at 10:00 AM ET and a regional Federal Reserve official’s remarks at 9:10 AM ET are listed by the news-feed calendar, unconfirmed. The morning band, 9:30 AM to 12:00 PM ET, runs roughly 7,280 to 7,470, with the setup band near its top. The afternoon band, 12:00 PM to 4:00 PM ET, runs roughly 7,300 to 7,450 into the weekend. Remarks by the Federal Reserve’s Vice Chair for Supervision are scheduled for 12:15 PM ET and consumer credit for 3:00 PM ET, as the calendar lists them.
The scenario ranges, also analyst judgment, run 7,310 to 7,430 for the low-range case, 7,270 to 7,470 for the mid-range case, the most likely, and 7,220 to 7,510 for the high-range case. The low-range case tops out at the band bottom. Globex reopens at 6:00 PM ET on Sunday, after two days of weekend headline risk on diplomacy. Chinese inflation data at 8:30 PM ET on Sunday is listed by the news-feed calendar, unconfirmed. Next week the consumer price index is scheduled for 8:30 AM ET on Tuesday, November 10, and the producer price index for 8:30 AM ET on Friday, November 13, as the calendar lists them.
Three paths, ranked. In the review’s analyst judgment the most probable path holds the contract between Pivot S1 at 7,239.75 and the Pivot Point at 7,489.25. In the same judgment, a rebound toward the 7,429.27 conversion and the 200-day average at 7,437.75 that stalls there is weighted above a recovery through the Pivot Point. That is our base case. The review weighs it that way because the composite moved to 72 percent sell with direction strongest. Negative direction leads on both directional systems, and the settle sits beneath every settlement average. Against that, in the review’s interpretation, the 9-day relative strength at 29.19 and raw stochastics at 7.81 percent describe a stretched contract, which favours a rebound attempt that is sold over an immediate extension. The second scenario is a settle above the Pivot Point. It would invalidate the reading and could bring one standard deviation resistance at 7,505.46 and the 7,529.27 base conversion into play. The third runs lower first. A move beneath the 7,341.75 target price before any rebound could bring one standard deviation support at 7,260.54 and Pivot S1 at 7,239.75 into play without the rebound the setup needs. A deeper correction toward Pivot S2 at 7,096.50 is the worst-case scenario in the review’s judgment.
Thursday’s long met its stop in the same bar that reached its band; Friday’s short sits 52.00 points above the settle at its midpoint, so the rebound has to come first.
The complete data picture
Every number behind Friday’s plan, charted first, then the full level lists, then the complete numeric reference underneath.
Full numeric reference, every remaining figure from the session review
1. Executive Summary
The December S&P 500 contract settled at 7,383.00 on Thursday, down 337.50 or 4.37 percent from Wednesday's settle of 7,720.50, after trading between 7,738.75 and 7,346.00, a 392.75 point daily range. The settle finished at 9.4 percent of the range, and the range was 3.18 multiples of the 14-day average daily range of 123.64 points. Thursday printed a lower high, 7.50 beneath Wednesday's 7,746.25, and a lower low, 144.00 beneath Wednesday's 7,490.00. The 337.50 point decline is the largest one-session point decline and the 392.75 point range the widest in the 259 completed settlements in the series, which run from 10/28/25 and include thinly traded early rows. The 7,383.00 settle is the lowest since the 7,343.00 settle of 05/04/26, and the 7,346.00 low the lowest since the 7,339.25 low of 05/05/26.
The decline came in the cash session. The overnight hours held between 7,691.00 and 7,737.25 and the 7:00 AM ET bar made the 7,738.75 high; the 9:30 AM ET bar then fell 113.75, from 7,707.50 to 7,593.75, the largest decline of any 30-minute bar in the session, and the 10:00 AM ET and 10:30 AM ET bars fell a further 69.50 and 54.50. The S&P 500 cash index closed at 7,353.73, down 4.36 percent, the Nasdaq-100 fell 6.36 percent and the semiconductor index 12.25 percent. Commentary carried by the news feed on the post-election policy outlook, attributed and unconfirmed, described a broad selloff led by technology shares on concerns about artificial-intelligence and data-centre spending, and the series does not establish that any single report caused a particular move.
The volatility index closed at 28.18, up 69.66 percent, the ten-year yield eased to 4.84 percent, down five basis points, and the dollar index held at 101.55, while December crude rose 2.72 percent. The settle sits beneath every settlement average from the 5-day to the 200-day, and it is the first settle beneath the 200-day average among the 60 sessions, from 08/13/26, for which the series supports that average.
The composite multi-indicator read published for Friday is "72% SELL" with strength "Maximum" and direction "Strongest", against "48% SELL" a session earlier. The primary setup is a short from the 7,430 to 7,440 band around the 7,429.27 conversion of the dealer-positioning SPX 7,400 support and the 200-day average, stopped at 7,462, with objectives at 7,408, 7,381 and an extended 7,354.
2. Price Action & Technical Structure
2.1 Intraday and Session Review
The Thursday session opened at 7,737.25 at the Wednesday 6:00 PM ET reopen, 16.75 above Wednesday's settle, and the 30-minute series of the December contract places the high of 7,738.75 in the 7:00 AM ET bar and the low of 7,346.00 in the 4:30 PM ET bar. Between the 6:00 PM ET reopen and 3:00 AM ET the bars held between 7,691.00 and 7,737.25 and closed that window at 7,709.50, and from 3:00 AM ET to the 9:30 AM ET cash open they held between 7,704.75 and 7,738.75, closing that window at 7,707.50.
The 9:30 AM ET bar fell 113.75 to 7,593.75 with a low of 7,580.50, the 10:00 AM ET bar fell 69.50 to 7,524.25 with a low of 7,498.00 and the 10:30 AM ET bar fell 54.50 to 7,469.75 with a low of 7,421.00. The 11:00 AM ET bar rose 38.75 to 7,508.50 and the 11:30 AM ET bar reached 7,515.25. From 12:00 PM ET to 2:00 PM ET the bars held between 7,388.00 and 7,472.00; the 2:30 PM ET bar rose 43.50 to 7,447.25 with a high of 7,457.75, the largest gain of any 30-minute bar in the session, and the 3:00 PM ET bar fell 46.50 to 7,400.75. The 3:30 PM ET bar closed at 7,381.25, 1.75 beneath the 7,383.00 settle. After the cash close the 4:00 PM ET bar closed at 7,370.75, and the 4:30 PM ET bar made the 7,346.00 low and closed at 7,353.00.
Thursday's completed range is taken from the settlement record and the published pivot ladder. Pivot R3 at 8,025.25 minus Pivot S3 at 6,847.00, divided by three, returns 392.75, and Pivot R2 at 7,882.00 minus Pivot S2 at 7,096.50, divided by two, returns the same 392.75. Three times the Pivot Point of 7,489.25 less the 7,383.00 settle gives a high plus low sum of 15,084.75, which solves to a high of 7,738.75 and a low of 7,346.00; that pair reproduces all seven published rungs. These are the completed-session inputs behind the published pivot ladder rather than an independently read bar, and they are corroborated by the provider's settlement row and the chart's completed daily bar, which carry the same 7,737.25 open, 7,738.75 high, 7,346.00 low and 7,383.00 settle.
2.2 Daily Structure
Thursday printed a lower high and a lower low against Wednesday and settled 337.50 lower, beneath Wednesday's 7,490.00 low. Settlements over the last six sessions read 7,754.25, 7,614.00, 7,574.50, 7,596.75, 7,720.50 and 7,383.00, so Thursday's decline more than reversed the 146.00 points gained over Tuesday and Wednesday. Over five sessions the contract is down 371.25 from the 7,754.25 settle of 10/29, which the provider also publishes as a 4.79 percent five-day change.
The provider publishes 7,905.00 as the 52-week and 13-week high and 7,897.50 as the one-month high, and Thursday's 7,346.00 low now stands as the one-month and 13-week low; the 52-week low is 6,466.00. The Thursday settle sits 27.70 above the 7,355.30 level published as the 61.8 percent retracement from the 52-week low and 41.25 above the 7,341.75 published target price.
2.3 4-Hour and Swing Structure
Daily ranges for the last ten sessions, from 10/23, ran 65.75, 87.75, 73.00, 69.25, 64.25, 154.75, 123.00, 77.75, 256.25 and 392.75, so Thursday's range was the widest of the ten and exceeded Wednesday's by 136.50. In the 30-minute series the three largest declines came in the 9:30 AM ET bar, 113.75, the 10:00 AM ET bar, 69.50, and the 10:30 AM ET bar, 54.50, and the largest gains in the 2:30 PM ET bar, 43.50, and the 11:00 AM ET bar, 38.75.
Thursday's 7,738.75 high sits 7.50 beneath Wednesday's 7,746.25 and 166.25 beneath the 7,905.00 52-week high. The published grid places the 38.2 percent retracement from the four-week low at 7,556.67, the 50 percent retracement of the 52-week range at 7,185.50 and the 3-10 day average crossover stall at 7,222.18.
2.4 Moving Averages
The averages cited here were computed from the provider's daily settlement series for the December contract, which holds 259 completed sessions from 10/28/25 through Thursday; the partial row of the reopened Friday session is excluded, and each average is carried at full precision and rounded once to the quarter point. The 200-day window includes 28 zero-volume rows from the contract's thinly traded early months, which carry quoted settlement prices; the 200-day figure is computed as published and carries that limitation. The 5-day average stands at 7,577.75, the 9-day at 7,655.50, the 20-day at 7,719.50, the 50-day at 7,742.75, the 100-day at 7,701.25 and the 200-day at 7,437.75.
The 7,383.00 settle sits 194.75 beneath the 5-day average, 272.50 beneath the 9-day, 336.50 beneath the 20-day, 359.75 beneath the 50-day, 318.25 beneath the 100-day and 54.75 beneath the 200-day. The 5-day average fell from Wednesday's 7,652.00 as Thursday's settle replaced the 10/29 settle of 7,754.25, and the 200-day average rose from 7,436.50.
The 20-day average sits beneath the 50-day because the 30 older settlements in the 50-day window averaged higher, at 7,758.13. The 50-day sits above the 100-day because the 50 older settlements in the 100-day window averaged lower, at 7,659.99, and the 100-day sits above the 200-day because the 100 older settlements in the 200-day window averaged lower, at 7,174.28. The projection grid gives 7,648.06 as the price at which the 9-day average would be crossed on Friday.
2.5 Oscillator and Trend Readings
The oscillator figures below are as published on the provider's technical page, read at 6:26 PM ET on Thursday after the Globex reopen; they are the provider's readings, none was computed for this review, and the page may already reflect the reopened session's price. The 9-day relative strength reads 29.19, the 14-day relative strength 32.85 and the 20-day relative strength 36.06.
The 9-day and 14-day raw stochastic both read 7.81 percent and the 20-day raw stochastic 6.84 percent, while the 14-day stochastic %K reads 32.11 percent and the 14-day stochastic %D 25.65 percent. The 9-day directional index ADX reads 26.93 with the 9-day +DI at 14.23 and the 9-day -DI at 27.38, and the 14-day directional index ADX reads 20.53 with the 14-day +DI at 14.75 and the 14-day -DI at 26.85, so negative direction leads on both systems. The 9-day historic volatility reads 26.69 percent and the 14-day historic volatility 22.56 percent.
The composite multi-indicator read published for the Friday session is "72% SELL", with signal strength "Maximum" and direction "Strongest". The snapshot history reads "48% SELL" for the prior session, "16% BUY" a week ago and "80% BUY" a month ago. The short horizon group averages "100% SELL", the medium group "50% SELL" and the long group "33% SELL", and the trend composite reads "SELL".
2.6 Volatility and Expected Range
The published 14-day average true range stands at 122.59 points and the 14-day average daily range at 123.64 points; the 9-day average true range is 143.71 with a 9-day average daily range of 144.31, and the 20-day average true range is 110.21 with a 20-day average daily range of 110.57. Thursday's 392.75 point range was 3.18 multiples of the 14-day average daily range.
Adding and subtracting the 14-day average true range of 122.59 from the 7,383.00 settle frames Friday between 7,260.41 and 7,505.59. The published standard-deviation bands, built from five settlements, span 7,260.54 to 7,505.46 at one deviation, 7,209.81 to 7,556.19 at two and 7,170.88 to 7,595.12 at three. These bands describe dispersion, not intraday reach, and after a decline of this size they are wide.
3. Key Levels
3.1 Resistance
Above the 7,383.00 settle, the first references are the 7,406.28 oscillator stall price and the 7,429.27 conversion of the dealer-positioning SPX 7,400 support, with the 200-day average at 7,437.75 beside it. The 7,457.75 high of the 2:30 PM ET bar, the Pivot Point at 7,489.25 and one standard deviation resistance at 7,505.46 form the next band, with the 7,529.27 conversion of the SPX 7,500 put side support base above them. Pivot R1 at 7,632.50 and the 7,629.27 conversion of the SPX 7,600 support are the extended references.
3.2 Support
Beneath the settle sit the 7,355.30 retracement from the 52-week low, Thursday's 7,346.00 low and the 7,341.75 published target price. One standard deviation support at 7,260.54 and Pivot S1 at 7,239.75 form the next band, with the 7,222.18 crossover stall and two standard deviation support at 7,209.81 beneath them. Pivot S2 at 7,096.50 and the 7,029.27 conversion of the SPX 7,000 dealer-positioning key strike are the deeper references.
4. Macro Drivers
4.1 Dollar, Rates, and Fed Policy
The ten-year yield index closed at 4.84 percent, down five basis points, and the dollar index's daily record at 101.55, little changed. Preliminary productivity was released at 8:30 AM ET on Thursday, November 5, 2026, as the calendar lists it, at 3.6 percent against a forecast of 2.7 percent, with unit labour costs at minus 0.7 percent against a forecast of 0.4 percent, per the news-feed calendar. The news feed carried at 9:24 AM ET a Federal Reserve Bank official saying productivity gains reflected adaptation to labour shortages rather than artificial intelligence. The UK central bank raised its rate to 4.00 percent from 3.75 percent, per the news-feed calendar, unconfirmed. Yields fell while the contract fell, and no series in the review separates the effects.
4.2 Large-Cap Leadership and Earnings
The news feed carried items on artificial-intelligence spending through the session: at 9:27 AM ET a ratings agency saying a major share of planned data-centre capacity may face regulatory hurdles, at 12:01 PM ET a 17 billion dollar data-centre investment by a search company, at 1:39 PM ET 31 billion dollars of orders for a consumer-hardware company's bond sale, and at 2:52 PM ET a request from lawmakers for a briefing from a chip designer's chief executive on links to China. These are reports carried by the feed. The calendars carry no mega-cap earnings entry for Friday.
4.3 Geopolitical Backdrop
The news feed carried a report on US and Iran diplomacy, a nuclear proposal sent through an intermediary. It is a report carried by the feed, not an event confirmed here, and no move is tied to it.
4.4 Sector Breadth and Rotation
The semiconductor index fell 12.25 percent and the Nasdaq-100 cash index 6.36 percent, against the S&P 500's 4.36 percent and the Dow Jones Industrial Average's 3.44 percent. Commentary carried by the news feed on the post-election policy outlook described a continuing rotation, and an investment-bank note described recent breadth as positioning-driven rather than a fundamental rotation; both are attributed commentary. Sector-level returns are not part of the review's primary series.
4.5 Cross-Asset and Volatility
The volatility index closed at 28.18, up 69.66 percent on the session. December crude rose 2.72 percent and gold 0.99 percent. The cash basis, the settle less the S&P 500 cash close of 7,353.73, is 29.27 points, against 31.88 on Wednesday; both legs are completed-session daily records from the provider, read between 6:21 PM ET and 6:23 PM ET.
4.6 Institutional Positioning
Thursday's December volume was 3,349,999 contracts against 2,412,784 on Wednesday, per the settlement record; the record's open-interest column for Thursday was not yet reported.
5. SPX Options Flow Context
The dealer-positioning dataset read for this section, the edition timed 5:12 PM ET on Thursday, uses Wednesday's closes as its reference prices, not Thursday's: SPX 7,688 sits 0.62 beneath Wednesday's 7,688.62 cash close and NDX 28,437 sits 0.17 beneath Wednesday's 28,437.17. Wednesday's 7,688.62 less 334.89 points, a 4.36 percent decline, gives the provider's 7,353.73 Thursday close, and every level below is read against that close.
On the index the primary call side ceiling sits at SPX 8,100, the largest gamma concentration at SPX 8,000, the modeled volatility threshold at SPX 7,685, the modeled gamma-flip level at SPX 7,644 and the primary put side support base at SPX 7,500. The close sits 746.27 points beneath the ceiling, 646.27 beneath the largest concentration, 331.27 beneath the threshold, 290.27 beneath the flip level and 146.27 beneath the put side base. Gamma tilt reads 1.102, gamma notional 242.076 million dollars and the dataset's gamma index 1.443, with an implied one-day move of 0.60 percent, an implied five-day move of 1.48 percent and a 25-delta risk reversal of minus 0.045. The dataset's summary lists resistance at 7,735, 7,760 and 7,800, its dealer-positioning pivot at 7,690 and support at 7,700, 7,600, 7,500 and 7,400, and its key strikes are SPX 8,000, 7,000, 7,700 and 7,800. These levels were computed from Wednesday's closes, and the dataset does not state how they shifted during Thursday's decline.
The dataset publishes its own December futures pair for each level, carrying the source's 30.43 point offset and not the measured 29.27 point basis: the ceiling at 8,130.43, the largest concentration at 8,030.43, the modeled volatility threshold at 7,715.43, the modeled gamma-flip level at 7,674.43 and the put side support base at 7,530.43. These are quoted as the source's pairs. The modeled threshold and flip level are model outputs, not option strikes. At the measured basis the SPX 7,000 key strike converts to 7,029.27, the SPX 7,400 support to 7,429.27, the SPX 7,500 base to 7,529.27, the SPX 7,600 support to 7,629.27, the SPX 7,644 flip level to 7,673.27 and the SPX 7,685 threshold to 7,714.27.
The S&P 500 positioning console, read at 6:18 PM ET, carried Wednesday's 7,688.62 as its last close and a console price of 7,324.65, which is a console reading rather than Thursday's cash close. It shows call gamma of minus 4.07 billion against put gamma of minus 3.69 billion, one-month implied volatility of 13.02 percent against realised volatility of 12.47 percent, an implied-volatility rank of 17.05 percent, a skew rank of 62.40 percent and a put-to-call open-interest ratio of 1.43.
In this review's interpretation a cash close beneath every support level in the dataset's summary, the nearest being SPX 7,400 at 46.27 points above the close, leaves the SPX 7,000 key strike as the nearest key strike beneath the price, 353.73 points lower, so the levels in section 3.2 rest mainly on published pivot arithmetic, standard-deviation bands and retracements. The primary setup sells a rebound into the 7,429.27 conversion of the SPX 7,400 support. Statements in the dataset about the order of intraday moves are not used; the session path in section 2.1 comes from the 30-minute futures series.
6. Forecast
6.1 Night Session (6:00 PM ET Thursday to 3:00 AM ET Friday, Globex/Asia)
Globex reopened at 6:00 PM ET. A Federal Reserve Bank official's remarks at 7:00 PM ET on Thursday are listed by the news-feed calendar, unconfirmed. Bias lower beneath the 7,429.27 conversion, expected band roughly 7,300 to 7,420, its top 10.00 beneath the 7,430 bottom of the setup band.
6.2 London Session (3:00 AM to 8:00 AM ET Friday)
Remarks by a regional Federal Reserve official at 4:30 AM ET and European retail sales at 5:00 AM ET are listed by the news-feed calendar, unconfirmed. Bias lower to neutral beneath the 200-day average at 7,437.75, expected band roughly 7,310 to 7,430.
6.3 Morning Session (9:30 AM to 12:00 PM ET Friday, RTH Open)
The employment situation report is scheduled for 8:30 AM ET on Friday, November 6, 2026, as the calendar lists it, and the cash open at 9:30 AM ET is the first directional test of the SPX 7,400 support conversion. The University of Michigan preliminary survey at 10:00 AM ET is listed by the news-feed calendar, unconfirmed. Expected band roughly 7,280 to 7,470, with the 7,430 to 7,440 setup band near the top.
6.4 Afternoon Session (12:00 PM to 4:00 PM ET Friday)
Remarks by the Fed Vice Chair for Supervision are scheduled for 12:15 PM ET and consumer credit for 3:00 PM ET on Friday, November 6, 2026, as the calendar lists them. Expected band roughly 7,300 to 7,450 into the weekend.
6.5 Night Session Forward (6:00 PM ET Sunday reopen)
Globex reopens at 6:00 PM ET on Sunday, after two days of weekend headline risk on diplomacy. Chinese inflation data at 8:30 PM ET on Sunday is listed by the news-feed calendar, unconfirmed.
6.6 Expected Range (Friday Full Session)
Low-range scenario: 7,310 to 7,430 (its top at the setup band bottom)
Mid-range scenario (most likely): 7,270 to 7,470
High-range scenario: 7,220 to 7,510
6.7 Most Likely Path
In this review's analyst judgment, the most probable path holds the contract between Pivot S1 at 7,239.75 and the Pivot Point at 7,489.25, with a rebound toward the 7,429.27 conversion and the 200-day average at 7,437.75 that stalls there weighted above a recovery through the Pivot Point at 7,489.25. The composite moved to "72% SELL" from "48% SELL" with direction "Strongest", negative direction leads on both directional systems and the settle sits beneath every settlement average, while the 9-day relative strength at 29.19 and raw stochastics at 7.81 percent describe a contract that is stretched after a 337.50 point decline, which in this review's interpretation favours a rebound attempt that is sold rather than an immediate extension.
The alternative that would invalidate this reading is a settle above the Pivot Point at 7,489.25, which would bring one standard deviation resistance at 7,505.46 and the 7,529.27 base conversion into play. On the other side, a move beneath the 7,341.75 target price before any rebound would bring one standard deviation support at 7,260.54 and Pivot S1 at 7,239.75 into play without the rebound the setup needs; a deeper correction toward Pivot S2 at 7,096.50 is the worst-case scenario in this review's judgment.
7. Friday Economic Calendar
Thursday's releases are complete. Preliminary productivity and costs were released at 8:30 AM ET on Thursday, November 5, 2026, as the calendar lists it, with productivity at 3.6 percent against a forecast of 2.7 percent and unit labour costs at minus 0.7 percent against a forecast of 0.4 percent, per the news-feed calendar. Weekly jobless claims of 189 thousand against a forecast of 196 thousand were listed by the news-feed calendar, unconfirmed against the calendar.
On Friday, November 6, 2026, the employment situation report is scheduled for 8:30 AM ET, remarks by the Fed Vice Chair for Supervision for 12:15 PM ET and consumer credit for 3:00 PM ET, as the calendar lists them. The University of Michigan preliminary survey at 10:00 AM ET and remarks by a regional Federal Reserve official at 9:10 AM ET are listed by the news-feed calendar, unconfirmed.
Next week, the consumer price index is scheduled for 8:30 AM ET on Tuesday, November 10, 2026 and the producer price index for 8:30 AM ET on Friday, November 13, 2026, as the calendar lists them. In this review's judgment the first-order influence on the contract for Friday is the 8:30 AM ET employment report and the reaction at the 9:30 AM ET cash open against the SPX 7,400 support conversion.
8. Primary Trade Setup
Direction: Short
Rationale: The contract settled at 9.4 percent of the widest range in the series, beneath every settlement average including the 200-day, the composite moved to "72% SELL" with direction "Strongest" and the cash index closed beneath every support level in the dealer-positioning summary. A rebound into the 7,430 to 7,440 band, around the 7,429.27 conversion of the SPX 7,400 support and the 200-day average at 7,437.75, offers a short with a defined risk point above the 7,457.75 high of the 2:30 PM ET bar. Oscillators are stretched after a 337.50 point decline and a rebound can run through the band after the 8:30 AM ET report, so the setup is an analyst judgment that rebounds into the 200-day average are sold, not a measured edge.
Entry Zone: 7,430 to 7,440
Stop Loss: 7,462 (above the 7,457.75 high of the 2:30 PM ET bar)
Target 1 (T1): 7,408 (above the 7,406.28 oscillator stall)
Target 2 (T2): 7,381 (beneath the 7,383.00 settle)
Target 3 (T3, extended): 7,354 (above the 7,346.00 session low)
Risk-to-Reward: Approximately 1:1 to T1, 1:2 to T2, 1:3 to T3
Invalidation: A settle above the Pivot Point at 7,489.25 negates the thesis. Short of that, the edge is removed by acceptance above the entry band, defined as two consecutive 30-minute closes above 7,440; a touch alone does not remove it.
Macro override: A softer employment report that pulls yields lower, or a rebound in semiconductors, would lift the contract. In that scenario a move through the 7,462 stop invalidates the short before the targets, and the Pivot Point at 7,489.25 becomes the reference, 27.25 beyond the stop and well inside one 14-day average true range of 122.59.
Sources and methodology
This outlook is built from our session review of the December E-mini S&P 500 contract, the December ’26 contract, prepared after Thursday’s close on November 5, 2026 for the Friday, November 6, 2026 session. Thursday’s completed extremes are the inputs behind the published pivot ladder: Pivot R3 at 8,025.25 less Pivot S3 at 6,847.00, divided by three, and Pivot R2 at 7,882.00 less Pivot S2 at 7,096.50, divided by two, both return 392.75, and three times the 7,489.25 Pivot Point less the settle gives a high-plus-low sum of 15,084.75, which the pair of 7,738.75 and 7,346.00 reproduces. The provider’s settlement row and the chart’s completed Thursday daily bar carry the same 7,737.25 open, 7,738.75 high, 7,346.00 low and 7,383.00 settle. Those figures, the 30-minute bars of the December contract from the Wednesday 6:00 PM ET reopen and the review’s own statements are the only evidence used to grade Thursday’s card, which was set at Wednesday’s settle and covers the whole session. Times of day come from the bars and are Eastern time. The partial row of the reopened Friday session is excluded from every count and average and is not quoted. Wednesday’s volume now reads 2,412,784 contracts on the revised 2026-11-04 row, which replaces the preliminary 2,329,405 carried in Thursday’s outlook, and that row’s open interest reads 1,968,406; that post was not changed. Thursday’s final open interest was not yet reported.
The moving averages were computed from the provider’s 259-session daily settlement series through Thursday and rounded once to the 0.25 tick. The oscillators, directional readings, historic volatility and range averages are cited as published, read at 6:26 PM ET on Thursday after the Globex reopen. The dealer-positioning dataset uses Wednesday’s closes as its reference prices and a fixed 30.43 point translation for its futures column, so cash equivalents here use the 29.27 point basis measured on Thursday, settlement against cash close. The dataset’s statements about the order of intraday moves are not used. The dataset’s gamma figures and the console’s call and put gamma are separate model measures from different timestamps; they are shown side by side, each with its source, and never combined. Company items are described generically. Scenario ranges are analyst judgment. Items marked unconfirmed come from the news-feed calendar or the news feed, and every catalyst whose release time had passed at the time of writing is recorded as completed.
Thursday’s outlook for this contract is here, and the Nasdaq-100 contract’s Thursday outlook set the levels for the index whose cash close fell 6.36 percent on Thursday. Outlooks for ES, NQ, GC and CL are collected on the market outlook page, and our forward trading record is on the performance statement.
Monday’s follow-up outlook for S&P 500, written after Friday’s close, is here.