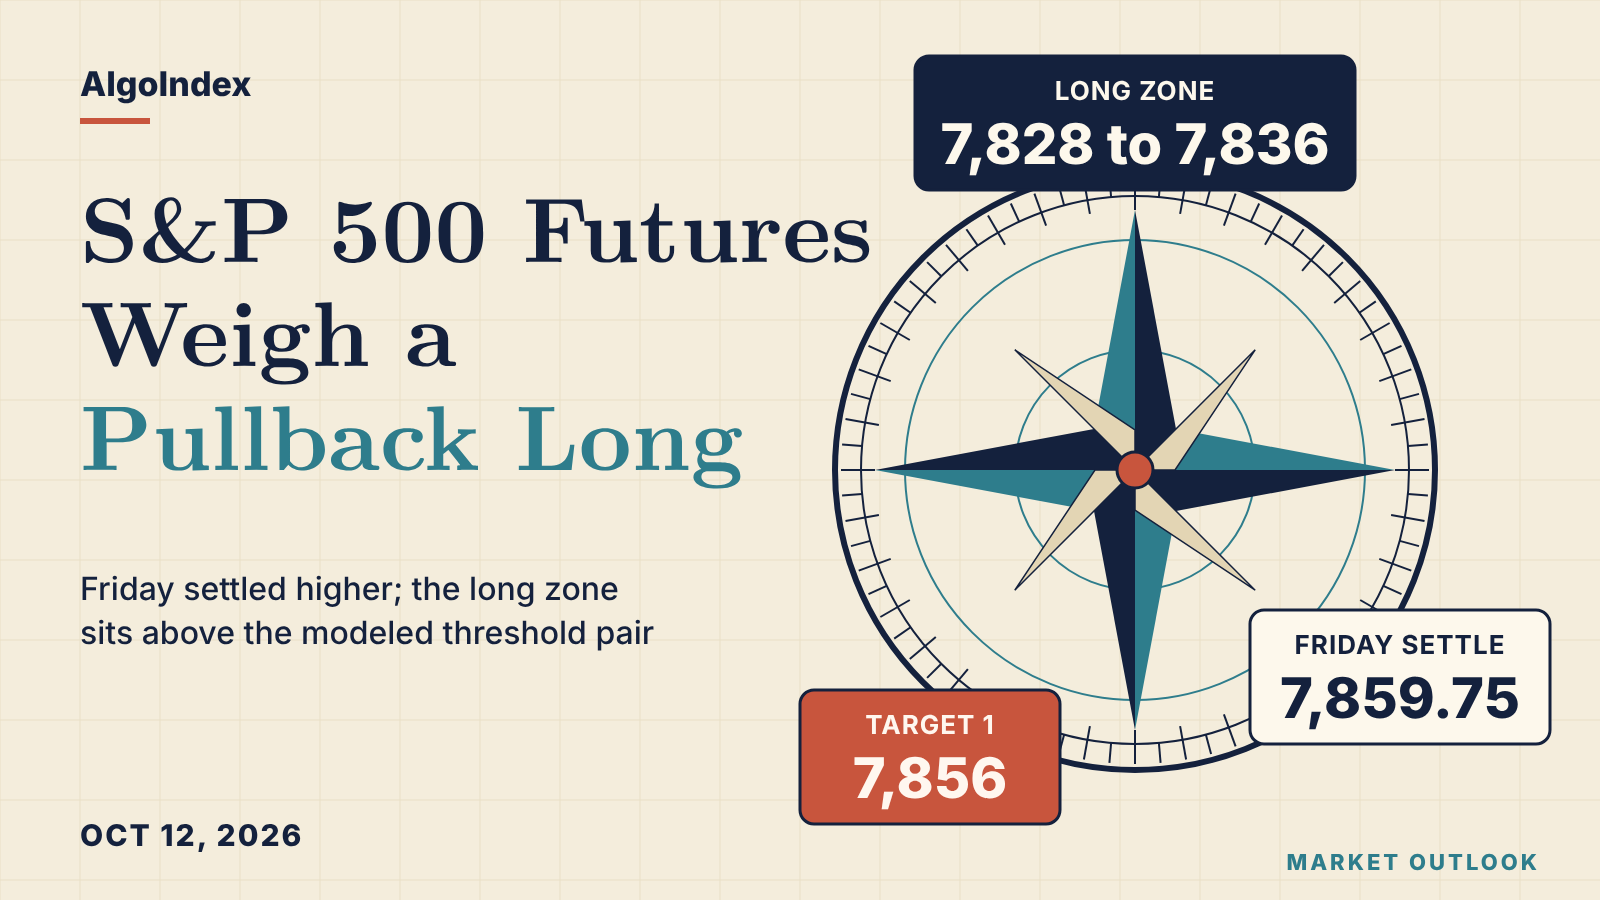
At 9:48 PM ET on Sunday the December S&P 500 contract traded near 7,881.00. Globex had reopened at 6:00 PM ET and carried it to 7,882.50, 1.33 points above Pivot R1 at 7,881.17 and 12.00 above Friday's 7,870.50 high. The overnight low held at 7,861.25, just 1.50 above the settle. That puts Monday's long zone, 7,828 to 7,836, 45.00 points beneath the market.
Friday did the groundwork. December E-mini futures settled at 7,859.75, up 43.50 points or 0.56 percent, after a 7,817.00 to 7,870.50 session. The 53.50 point range was the narrowest since the 38.00 point range of 09/22. A higher high and a higher low. The settle finished at 79.9 percent of the range, and the week closed 82.50 points higher, a 1.06 percent gain from the 7,777.25 settle of 10/02. The cash index closed at 7,811.54, up 0.59 percent, as provider commentary pointed to earnings optimism and eased worry about artificial-intelligence infrastructure demand.
December S&P 500 futures settled at 7,859.75, 10.67 points above the 7,849.08 Pivot Point and above every settlement average from the 5-day at 7,845.80 to the 200-day at 7,380.17. The primary setup is a long from 7,828 to 7,836 around Pivot S1 at 7,827.67 and one standard deviation support at 7,835.80, stop 7,808 beneath 7,816.07, the source's futures pair for the modeled volatility threshold, targets 7,856, 7,880 and an extended 7,904. The band sits beneath the market. Sunday's reopen traded near 7,881.00 at 9:48 PM ET, 45.00 points above the band top, so the setup needs a pullback to engage. The cash close sits 46.54 points above the 7,765 modeled volatility threshold with gamma tilt at 1.187. Monday is Columbus Day: the cash Treasury market is closed while equities and futures trade normal hours, and the September consumer price index on Wednesday is the week's key scheduled event.
Friday's 7,870.50 high ran through the short band and stopped 7.50 points under the stop
In Friday’s outlook we set a short from 7,846 to 7,854. Its stop sat at 7,878, with targets at 7,822, 7,794 and an extended 7,766. Friday's completed bar, from the review, opened at 7,820.50 at the Thursday 6:00 PM ET reopen, marked a high of 7,870.50 and a low of 7,817.00, and settled at 7,859.75. The open sat 25.50 points beneath the band's 7,846 bottom. The whole band traded at some point, since the high cleared its 7,854 top by 16.50 points. The stop held. The high stopped 7.50 points beneath 7,878.
The first target is a question of order. The 7,817.00 low sits 5.00 points beneath 7,822, and the 7,820.50 open already sat 1.50 beneath it, before price had reached the band. No complete intraday series was preserved for Friday, so the record cannot say whether price came back to 7,822 after it entered the band. The 7,794 and 7,766 targets never printed; the low held 23.00 and 51.00 points above them. No fill and no result is asserted.
The settle came close to the card's hard line. The card named a settle above two standard deviations resistance at 7,868.39 as the invalidation, and the 7,859.75 settle finished 8.64 points beneath it. It did finish 4.42 points above Pivot R1 at 7,855.33, the acceptance line, and 5.75 above the band top. Acceptance needed two consecutive 30-minute closes above 7,855.33. The record holds no 30-minute closes from the body of the session, so a qualifying pair is neither confirmed nor ruled out.
Our ranges sat a little low. The most likely band of 7,770 to 7,860 held the settle, 0.25 points under its top, yet the high broke that top by 10.50 points. The low-range case of 7,790 to 7,845 missed the high by 25.50 and the settle by 14.75. The high-range case of 7,739 to 7,893 contained the whole session, with the high 22.50 points beneath its top.
The weighted path missed at the top. Friday's outlook expected a hold between Pivot S1 at 7,780.08 and Pivot R1 at 7,855.33. The low stayed 36.92 points above that Pivot S1, while the high went 15.17 points through Pivot R1. The named alternative was a chip recovery, or a fall in yields after the inflation-expectations survey, that lifts the contract through 7,868.39 toward Wednesday's 7,884.50 high. Its price leg went part of the way: the high cleared 7,868.39 by 2.11 points and stopped 14.00 short of 7,884.50. Neither trigger showed in the closes. The ten-year yield index closed one basis point higher at 5.24 percent, and the semiconductor index fell 0.41 percent. We grade the card as written.
Pivot S1 at 7,827.67, the 7,828 to 7,836 band and the 7,816.07 line
The basis narrowed. Friday's 7,859.75 settle less the 7,811.54 cash close measures 48.21 points, and every cash equivalent in this article uses that offset. The positioning note keeps its own fixed 51.07 point offset, so its published futures pairs differ: 8,051.07 for the 8,000 gamma concentration, 7,951.07 for the 7,900 call-side ceiling, 7,816.07 for the 7,765 modeled volatility threshold, 7,771.07 for the 7,720 modeled gamma-flip level and 7,551.07 for the 7,500 put-side base.
Resistance starts close. Friday's 7,870.50 high (cash 7,822.29) sits 10.75 points above the settle. Pivot R1 at 7,881.17 (cash 7,832.96) and one standard deviation resistance at 7,883.70 (cash 7,835.49) sit 2.53 points apart, and Sunday's 7,882.50 overnight high landed between them. Above that, two standard deviations resistance at 7,893.61 (cash 7,845.40), the 7,897.50 one-month high, Pivot R2 at 7,902.58 (cash 7,854.37) and the 7,905.00 52-week and 13-week high (cash 7,856.79) stack within 11.39 points. Pivot R3 at 7,934.67 (cash 7,886.46) is the last pivot; the 7,951.07 and 8,051.07 pairs sit beyond it.
Support begins with three references inside 8.03 points: the published target price at 7,853.83 (cash 7,805.62), the Pivot Point at 7,849.08 (cash 7,800.87) and the 5-day settlement average at 7,845.80 (cash 7,797.59). Then comes the band that anchors the setup. One standard deviation support at 7,835.80 (cash 7,787.59), Pivot S1 at 7,827.67 (cash 7,779.46) and two standard deviations support at 7,825.89 span 9.91 points. The 7,828 to 7,836 entry band wraps the first two, its bottom 0.33 above the pivot.
The stop's group sits next. Three standard deviations support at 7,818.28, Friday's 7,817.00 low (cash 7,768.79) and 7,816.07, the source pair of the 7,765 threshold, sit 2.21 points apart, and the 7,808 stop sits 8.07 beneath that pair. Lower down come the 9-day average crossing price at 7,805.72, the 9-day average at 7,797.53, Pivot S2 at 7,795.58 (cash 7,747.37), the 18-day crossing at 7,785.46, the 38.2 percent retracement from the four-week high at 7,774.30 and Pivot S3 at 7,774.17 (cash 7,725.96). The averages crowd in next. The 50-day average at 7,771.88, the 7,771.07 flip pair (cash 7,720), the 20-day average at 7,766.23, the 40-day crossing at 7,762.83 and the 50 percent retracement of the four-week range at 7,736.25 follow. The deep references are the 100-day average at 7,683.14, the 7,575.00 one-month low, the 7,551.07 put-side pair (cash 7,500) and the 200-day average at 7,380.17.
Every average sits beneath the settle. The 5-day stands 13.95 points under it, the 9-day 62.22, the 20-day 93.53 and the 50-day 87.88; the 100-day sits 176.62 beneath and the 200-day 479.58. The 5-day rose 16.50 points from Thursday's 7,829.30 as the 10/02 settle of 7,777.25 left the window. The 20-day rose 6.63 from 7,759.60 and the 50-day 6.45 from 7,765.43. One quirk persists. The 50-day still sits above the 20-day, so the 30 older settlements in its window averaged 7,775.64, more than the latest 20. For Monday the averages would be crossed at 7,805.72 for the 9-day, 7,785.46 for the 18-day and 7,762.83 for the 40-day.
Momentum firmed. Relative strength reads 61.40 on the 9-day and 58.47 on the 14-day. The raw stochastic reads 83.20 percent on both windows, while the smoothed 14-day %K at 75.71 percent sits beneath %D at 80.69 percent. Trend strength stays thin. Positive direction leads on the 9-day, 21.77 against 18.33 with the ADX at 14.53, and on the 14-day, 21.19 against 19.63 with the ADX at 10.90. Historic volatility reads 6.76 percent on the 9-day and 7.66 percent on the 14-day.
The composite multi-indicator read jumped to 80 percent buy from 64 percent buy, with strength soft and direction strengthening. It read 16 percent buy a week ago and 16 percent sell a month ago. The short-horizon group averages 60 percent buy, the medium-horizon group 100 percent buy and the long-horizon group 67 percent buy, and the composite trend indicator reads buy.
Ranges compressed. The 14-day average true range stands at 75.40 points and the 14-day average daily range at 72.30; the 9-day figures are 74.72 and 74.47 and the 20-day figures 76.20 and 77.74. Friday's 53.50 point range was 0.74 times the 14-day average daily range. One average true range either side of the settle frames Monday between 7,784.35 and 7,935.15. The published deviation bands are tighter: 7,835.80 to 7,883.70 at one deviation, 7,825.89 to 7,893.61 at two and 7,818.28 to 7,901.22 at three. Built from five settlements, they describe settlement dispersion only.
Zoom out. Daily ranges over the last eight sessions ran 76.50, 95.00, 87.00, 87.25, 68.50, 68.75, 75.25 and 53.50 points. The prior week, September 28 through October 2, spanned 7,672.75 to 7,810.25; this week spanned 7,760.25 to 7,897.50. The 52-week high of 7,905.00 sits 45.25 points above the settle and the 7,575.00 one-month low 284.75 beneath it. The retracement grid for Monday places the 38.2 percent line from the four-week high at 7,774.30 and the 50 percent line at 7,736.25. No four-hour series and no prior-quarter extremes were captured, so swing structure rests on daily bars.
Earnings hopes, sinking implied volatility and a weekend of Gulf headlines
Earnings carried Friday. Provider commentary cited an estimate of 25 percent year-on-year growth in third-quarter S&P 500 profits, up from 22 percent in July. It said concerns about artificial-intelligence infrastructure demand eased after people familiar with the matter said a leading artificial-intelligence developer expects at least 70 billion dollars of annualised revenue by year end, refuting Thursday's press report. The positioning note said the seven largest companies rose about 1 percent as a group.
Breadth leaned away from chips. The positioning note said software rose about 3 percent and financials about 1 percent, while semiconductors lagged with the chip fund down about 1 percent, and that the financial sector fund reclaimed a key positioning level. The semiconductor index closed at 12,572.42, down 0.41 percent. The Dow Jones industrial average closed at 51,654.95, up 0.83 percent, which provider commentary called a 1.5-week high, ahead of the S&P 500's 0.59 percent and the Nasdaq-100's 0.51 percent. Per the note, its one-month implied correlation measure fell to 6.93 as a dispersion theme continued.
Rates barely moved. The ten-year yield index closed at 5.24 percent, up one basis point, the thirty-year unchanged at 5.60 percent and the dollar index at 102.21, up 0.07 percent. The University of Michigan preliminary sentiment index printed 46.3 against a 47.6 forecast at 10:00 AM ET, with one-year inflation expectations at 4.7 percent and five-year expectations at 3.5 percent, per the news feed and unconfirmed against a primary release. Then the rate odds. Provider commentary said markets price a 19 percent chance of a quarter-point rate increase at the October 27 to 28 meeting. November WTI crude settled at 91.85, up 0.39 percent, and December gold at 4,216.3, up 1.43 percent.
Implied volatility sank. The volatility index closed at 14.84, down 0.57, and the Nasdaq-100 implied-volatility gauge at 20.55. The positioning note put the volatility-of-volatility index at 84.88 and said the volatility complex fell to its August lows, with near-term fixed-strike implied volatility down one to two points, next week's at-the-money implied volatility below 10 percent and Monday's near 5.6 percent. The note read that as leaving the market fragile to headline risk ahead of the consumer price index at 8:30 AM ET on Wednesday, October 14, 2026. It also cited monthly options expiration on Friday, October 16, 2026, per the note and unconfirmed. Its implied one-day move is 0.52 percent, about 40.62 points on the 7,811.54 close, and its implied five-day move 1.55 percent, about 121.08 points.
The cash close sits clear of the model lines. The note used is the 5:38 PM ET Friday edition, and its reference column carries Thursday's closes: its 7,765 reference equals Thursday's 7,765.36 cash close. Against Friday's 7,811.54 close, the index sits 46.54 points above the 7,765 modeled volatility threshold, 91.54 above the 7,720 modeled gamma-flip level and 88.46 beneath the 7,900 call-side ceiling. Gamma tilt reads 1.187 and gamma notional plus 736.963 million dollars, so dealer gamma stays positive. The modeled threshold and flip level are model outputs; neither is an option strike.
A positioning console for the cash index, dated 2026-10-09 and read at about 6:34 PM ET, shows call gamma of 8.17 billion against put gamma of minus 2.91 billion, with 10.86 percent of gamma in the nearest expiration, against 8.5 billion, minus 2.7 billion and 7.59 percent in Thursday's read. Call gamma still dominates. One-month implied volatility of 12.43 percent sits above one-month realised volatility of 10.12 percent, with an implied-volatility rank of 13.45 percent. In the review's interpretation a close above the threshold, with positive gamma tilt and very low near-term implied volatility, favours contained dips toward the 7,816.07 to 7,835.80 zone over a trend day lower.
The note draws its own map. It lists resistance at 7,800, 7,830, 7,850 and 7,900, support at 7,750 and 7,700, a desk pivot at 7,690 and key strikes at 8,000, 7,800, 7,000 and 7,700, all in cash. It said same-day iron-condor positions of about 10 thousand contracts at the 7,745 to 7,740 and 7,835 to 7,840 strikes sat in a zone of positive gamma. Then the flow. The S&P 500 hedging-flow measure finished at about minus 8 billion dollars of delta, driven mainly by about minus 6 billion of same-day call selling, which the note read as caution about adding longer-dated risk before the weekend.
Positioning in futures thinned. Non-commercial net positioning in S&P 500 futures moved to minus 154.1 thousand from minus 142.5 thousand in the week to Tuesday, October 6, per the news feed at 4:15 PM ET. Friday's volume on the December contract was 1,077,892 contracts against 1,700,014 on Thursday. The open-interest column lags one session, so no change is asserted.
Headlines ran all day. The news feed carried at 8:33 AM ET Iranian state-affiliated media reports that a large liquefied petroleum gas tanker was hit and caught fire. At 11:36 AM ET the President said the Iran matter would be over soon, one way or the other. At 2:46 PM ET he said he had concluded a call with Russia's president, with Russia to supply diesel, and a temporary Treasury license for Russian-origin diesel followed at 2:50 PM ET. At 4:57 PM ET, after the cash close, the Saudi-led coalition said it is carrying out a wide-ranging operation against Houthi capabilities in Yemen. All of these are statements carried by the news feed; none was confirmed for this review.
The weekend added more, per the news feed. A missile struck the domestic terminals at Riyadh's airport on Saturday, October 10, a second strike was reported Sunday, airport operations were suspended, and the President said Saturday that the United States may join Saudi strikes on the Houthis. A drone hit a tanker near Oman's Sohar anchorage just outside the Strait of Hormuz. The Energy Department approved an emergency exchange of up to 4 million barrels from the strategic reserve for the hurricane disruption, and Russia lifted its diesel export restrictions after Friday's supply arrangement. The contract still reopened higher. By 9:48 PM ET it traded near 7,881.00, up 21.25 points, inside a 7,861.25 to 7,882.50 overnight range.
The trade map for Monday
The primary setup is a long from 7,828 to 7,836. The cash close sits 46.54 points above the 7,765 modeled volatility threshold with positive dealer gamma, the settle sits above every settlement average from the 5-day to the 200-day, and the composite rose to 80 percent buy with direction strengthening. The band holds one standard deviation support at 7,835.80 and sits 0.33 points above Pivot S1 at 7,827.67. The stop sits at 7,808, beneath 7,816.07 and Friday's 7,817.00 low. Targets step up. The first, 7,856, sits 2.17 above the 7,853.83 published target price; the second, 7,880, sits 1.17 beneath Pivot R1 at 7,881.17; and the extended 7,904 sits 1.42 above Pivot R2 at 7,902.58 and 1.00 beneath the 7,905.00 52-week high. Low ADX readings and unusually low near-term implied volatility into a data-heavy week lead the review to call the setup an analyst judgment that dips stay contained above the threshold pair, with no measured edge behind it.
Now the arithmetic. From the 7,832 midpoint the risk to the stop is 24 points, 31.8 percent of the 14-day average true range of 75.40. The targets sit 24, 48 and 72 points above the midpoint. Exact multiples. Friday's settle sat 23.75 points above the band top, and Sunday's 7,881.00 quote sits 45.00 above it, so the setup needs a pullback to engage. The overnight low of 7,861.25 stayed 25.25 points above the band. A one-range frame from the settle, 7,784.35 to 7,935.15, holds the band, the stop and all three targets.
The Sunday update frames Monday's first test as whether Pivot R1 at 7,881.17 holds as support or caps the move. At 9:48 PM ET the contract traded 0.17 points beneath it. A gap above Pivot R1 or beneath Pivot S1, in the review's words, would reset the level map.
The scenario ranges are analyst judgment, with no calibration. The low-range case runs 7,828 to 7,881, the most likely 7,817 to 7,894 and the high-range case 7,784 to 7,935. Session by session the review expects roughly 7,830 to 7,880 through Globex, with a neutral to higher bias above the 7,849.08 Pivot Point, 7,826 to 7,884 through London, 7,820 to 7,890 in the morning and 7,820 to 7,895 in the afternoon. Sunday's 7,882.50 high already sits 2.50 points above the Globex band's top.
Monday's calendar is thin. Columbus Day keeps the cash Treasury market closed while equities and all futures trade normal hours, per the Sunday update, and the Federal Reserve is closed, with its daily statistical releases moving to Tuesday. Bank of England policymakers are listed at 5:30 AM ET and 8:50 AM ET and a regional Federal Reserve president at 12:10 PM ET, all per the news-feed calendar and unconfirmed. The cash session runs from 9:30 AM ET to 4:00 PM ET. Japanese producer prices at 7:50 PM ET, the Australian central bank's minutes at 8:30 PM ET and the International Monetary Fund's World Economic Outlook at 10:00 PM ET follow, also per the news-feed calendar and unconfirmed.
The week fills fast. Bank earnings begin on Tuesday, October 13, 2026, with the largest bank's results at about 7:00 AM ET. The September consumer price index lands at 8:30 AM ET on Wednesday, October 14, 2026, retail sales and producer prices follow at 8:30 AM ET on Thursday, October 15, 2026, and the Fed chair speaks on Friday, October 16, 2026, as the calendar lists them. In the review's judgment the first-order influences on Monday are weekend headlines and the start of bank earnings, with the consumer price index the week's key scheduled event.
One path is weighted. In this review's analyst judgment the most probable path holds the contract between Pivot S1 at 7,827.67 and Pivot R2 at 7,902.58, with a dip toward the 7,828 to 7,836 band that holds above the 7,816.07 threshold pair weighted above a break lower. No measured frequency backs it. The alternative that would invalidate the reading is a weekend escalation that lifts yields and the dollar, or a renewed slide in chip shares, carrying the contract through 7,816.07 toward Pivot S3 at 7,774.17 and the 7,771.07 flip pair.
Friday's settle sat 21.42 points beneath Pivot R1; by 9:48 PM ET on Sunday the contract sat 0.17 beneath it.
The complete data picture
Every number behind Monday’s plan, charted first, then the full level lists, then the complete numeric reference underneath.
Full numeric reference, every remaining figure from the session review
1. Executive Summary
The December S&P 500 contract settled at 7,859.75 on Friday, up 43.50 points or 0.56 percent from Thursday's settle of 7,816.25, after trading between 7,870.50 and 7,817.00, a 53.50 point daily range. The settle finished at 79.9 percent of the range, and the range was 0.74 times the published 14-day average daily range of 72.30 points. Friday printed a higher high and a higher low against Thursday, and its 53.50 point range was the narrowest since the 38.00 point range of 09/22. Over the week the contract rose 82.50 points, or 1.06 percent, from the 7,777.25 settle of 10/02.
The S&P 500 cash index closed at 7,811.54, up 46.18 points or 0.59 percent. Its Friday session ran from 7,779.34 to 7,820.57. Provider commentary said stocks settled higher on earnings optimism, citing an estimate of 25 percent year-on-year growth in third-quarter S&P 500 profits, up from 22 percent in July, and on eased concerns about artificial-intelligence infrastructure demand after people familiar with the matter said a leading artificial-intelligence developer expects at least 70 billion dollars of annualised revenue by year end. The Dow Jones Industrial Average closed at 51,654.95, up 0.83 percent, which provider commentary called a 1.5-week high.
The ten-year yield index closed at 5.24 percent, up one basis point. The volatility index closed at 14.84, down 0.57. The University of Michigan preliminary sentiment index printed 46.3 against a forecast of 47.6 at 10:00 AM ET, per the news feed and unconfirmed against a primary release. The cash close sits 46.54 points above the modeled volatility threshold at SPX 7,765 published in the positioning note, with gamma tilt at 1.187 and positive gamma notional.
The Monday session follows a weekend of Iran, Gulf and Russian supply headlines, and Monday is the Columbus Day holiday with Globex on normal hours, as the calendar lists it. The Primary Setup below is a long from the 7,828 to 7,836 band, around Pivot S1 at 7,827.67 and one standard deviation support at 7,835.80, stopped at 7,808 beneath the 7,816.07 source futures pair of the modeled volatility threshold, with objectives at 7,856, 7,880 and an extended 7,904.
2. Price Action & Technical Structure
2.1 Intraday and Session Review
The Friday session opened at 7,820.50 at the Thursday 6:00 PM ET reopen, 4.25 points above Thursday's settle, marked a daily high of 7,870.50 and a daily low of 7,817.00, and settled at 7,859.75. No complete intraday series was preserved for this session, so this review makes no claim about when the high or the low printed or about the path between them.
After the settle, the chart's 4:30 PM ET bar closed at 7,866.00; that post-settlement quote is not used as the settlement anywhere in this review. Globex is closed for the weekend, so the provider's day open, high and low of 7,820.50, 7,870.50 and 7,817.00 belong to the completed Friday session, and the pivot ladder published for Monday is built from that session.
The session extremes used here are the completed-session inputs behind the published pivot ladder rather than an independently read bar, back-solved from the outer pivot pairs and verified against every rung. Pivot R3 at 7,934.67 minus Pivot S3 at 7,774.17, divided by three, returns 53.50, and Pivot R2 at 7,902.58 minus Pivot S2 at 7,795.58, divided by two, returns the same 53.50. Three times the Pivot Point of 7,849.08 less the 7,859.75 settle gives a high plus low sum of 15,687.49, one hundredth from the 15,687.50 of the solved pair because the published pivot is rounded, and the pair of 7,870.50 and 7,817.00 reproduces all seven published rungs. Independent corroboration: the provider's overview, the provider's settlement row and the chart's completed Friday daily bar carry the same 7,870.50 high and 7,817.00 low.
2.2 Daily Structure
Friday printed a higher high and a higher low against Thursday: the 7,870.50 high sits 12.25 points above Thursday's 7,858.25, and the 7,817.00 low sits 34.00 points above Thursday's 7,783.00. The settle at 79.9 percent of the range leaves an upper shadow of 10.75 points on the daily bar. The sequence of session highs over the last six sessions reads 7,810.25, 7,847.50, 7,897.50, 7,884.50, 7,858.25 and 7,870.50, and the sequence of session lows reads 7,723.25, 7,760.25, 7,829.00, 7,815.75, 7,783.00 and 7,817.00. Settlements over the same six sessions ran 7,777.25, 7,826.25, 7,874.00, 7,852.75, 7,816.25 and 7,859.75.
The prior week, September 28 through October 2, spanned 7,810.25 to 7,672.75. This week, October 5 through October 9, spanned 7,897.50 to 7,760.25 and closed 82.50 points higher. The 52-week and 13-week high of 7,905.00 sits 45.25 points above the settle, and the one-month low of 7,575.00 sits 284.75 points beneath it.
No prior-quarter high or low was captured for this review, so the 13-week extremes serve as the available quarterly reference.
2.3 4-Hour and Swing Structure
Daily ranges for the last eight sessions ran 76.50, 95.00, 87.00, 87.25, 68.50, 68.75, 75.25 and 53.50. The settlement changes over the same eight sessions read minus 16.50, plus 8.50, plus 53.25, plus 49.00, plus 47.75, minus 21.25, minus 36.50 and plus 43.50.
The retracement grid published for Monday places the 38.2 percent retracement from the four-week high at 7,774.30 and the 50 percent retracement of the four-week range at 7,736.25. No four-hour series was captured for this review, so swing structure here rests on daily bars only.
2.4 Moving Averages
The averages cited in this subsection were computed for this review from the provider's daily settlement series for the December contract, which holds 260 completed sessions through Friday. The 5-day average stands at 7,845.80, the 9-day at 7,797.53, the 20-day at 7,766.23, the 50-day at 7,771.88, the 100-day at 7,683.14 and the 200-day at 7,380.17.
The 7,859.75 settle sits 13.95 points above the 5-day average, 62.22 points above the 9-day, 93.53 points above the 20-day, 87.88 points above the 50-day, 176.62 points above the 100-day and 479.58 points above the 200-day. The 5-day average rose 16.50 points from Thursday's 7,829.30, because the 10/02 settle of 7,777.25 left the window and was replaced by 7,859.75. The 20-day rose 6.63 points from 7,759.60 and the 50-day 6.45 points from 7,765.43.
The 50-day average sits above the 20-day because the last 20 settlements averaged 7,766.23 against 7,771.88 for the full 50, which means the 30 older settlements in the 50-day window averaged higher, at 7,775.64. The projection grid gives the prices at which each average would be crossed on Monday: 7,805.72 for the 9-day, 7,785.46 for the 18-day and 7,762.83 for the 40-day.
2.5 Oscillator and Trend Readings
The oscillator figures below are as published on the provider's technical page dated for the Friday session and read after the settle; Globex is closed for the weekend, so the page reflects the completed session. The 9-day relative strength reads 61.40 and the 14-day relative strength 58.47.
The 9-day raw stochastic reads 83.20 percent and the 14-day raw stochastic 83.20 percent, while the 14-day stochastic %K reads 75.71 percent and the 14-day stochastic %D 80.69 percent, so the smoothed lines sit in the upper quarter of their range with %K beneath %D.
The 9-day directional index ADX reads 14.53 with the 9-day +DI at 21.77 and the 9-day -DI at 18.33; the 14-day directional index ADX reads 10.90 with the 14-day +DI at 21.19 and the 14-day -DI at 19.63, so positive direction leads on both while the ADX readings stay low. The 9-day historic volatility reads 6.76 percent and the 14-day historic volatility 7.66 percent.
The composite multi-indicator read published for the Friday session is 80 percent buy, up from 64 percent buy in the prior session's snapshot, with signal strength described as soft and direction as strengthening. The snapshot history reads 16 percent buy a week ago and 16 percent sell a month ago. The short-horizon group averages 60 percent buy, the medium-horizon group 100 percent buy and the long-horizon group 67 percent buy, and the composite trend indicator reads buy.
2.6 Volatility and Expected Range
The published 14-day average true range stands at 75.40 points and the 14-day average daily range at 72.30 points; the 9-day average true range is 74.72 with a 9-day average daily range of 74.47, and the 20-day average true range is 76.20 with a 20-day average daily range of 77.74. Friday's 53.50 point range was 0.74 times the 14-day average daily range.
Adding and subtracting the 14-day average true range of 75.40 points from the 7,859.75 settle frames Monday between 7,784.35 and 7,935.15. The published standard-deviation bands are narrower because they are built from five settlements: one deviation spans 7,835.80 to 7,883.70, two spans 7,825.89 to 7,893.61 and three spans 7,818.28 to 7,901.22. These bands describe settlement dispersion, not intraday reach.
3. Key Levels
3.1 Resistance
The settle at 7,859.75 sits 10.75 points beneath Friday's 7,870.50 high, the first resistance. Pivot R1 at 7,881.17 and one standard deviation resistance at 7,883.70 form the next band, followed by two standard deviations resistance at 7,893.61, the 7,897.50 one-month high, Pivot R2 at 7,902.58 and the 7,905.00 52-week high. Pivot R3 at 7,934.67 and the 7,951.07 source futures pair of the primary call side ceiling at SPX 7,900 are the extended references, with the 8,051.07 source pair of the largest gamma concentration at SPX 8,000 beyond.
3.2 Support
Beneath the settle, the published target price at 7,853.83, the Pivot Point at 7,849.08 and the 5-day settlement average at 7,845.80 come first. One standard deviation support at 7,835.80, Pivot S1 at 7,827.67 and two standard deviations support at 7,825.89 form the band that anchors the setup. Three standard deviations support at 7,818.28, Friday's 7,817.00 low and the 7,816.07 source futures pair of the modeled volatility threshold at SPX 7,765 form the next grouping, with the 9-day average crossing price at 7,805.72 beneath. Pivot S2 at 7,795.58, the 18-day average crossing price at 7,785.46, Pivot S3 at 7,774.17 and the 7,771.07 source pair of the modeled gamma-flip level at SPX 7,720 follow, with the 7,551.07 source pair of the primary put side support base at SPX 7,500 beyond.
4. Macro Drivers
4.1 Dollar, Rates, and Fed Policy
The ten-year yield index closed at 5.24 percent, up one basis point. The thirty-year yield index closed unchanged at 5.60 percent. The dollar index closed at 102.21, up 0.07 percent. The University of Michigan preliminary sentiment index printed 46.3 against a forecast of 47.6 at 10:00 AM ET, with one-year inflation expectations at 4.7 percent and five-year expectations at 3.5 percent, per the news feed and unconfirmed against a primary release. Provider commentary said markets price a 19 percent chance of a quarter-point rate increase at the October 27 to 28 meeting. The consumer price index for September is scheduled for 8:30 AM ET on Wednesday, October 14, 2026, as the calendar lists it.
4.2 Large-Cap Leadership and Earnings
Provider commentary said earnings optimism underpinned stocks, citing an estimate of 25 percent year-on-year growth in third-quarter S&P 500 profits, and that concerns about artificial-intelligence infrastructure demand eased after people familiar with the matter said a leading artificial-intelligence developer expects at least 70 billion dollars of annualised revenue by year end, refuting Thursday's press report. The positioning note said the seven largest companies rose about 1 percent as a group. Bank earnings begin on Tuesday, October 13, 2026, with the largest bank's results at about 7:00 AM ET, as the calendar lists it, and the positioning note described bullish options positioning in two of the large banks ahead of their reports.
4.3 Geopolitical Backdrop
The news feed carried at 8:33 AM ET Iranian state-affiliated media reports that a large liquefied petroleum gas tanker was hit and caught fire, and at 11:36 AM ET the President said the Iran matter would be over soon, one way or the other. At 2:46 PM ET he said he had concluded a call with Russia's president, with Russia to supply diesel to the market, and a temporary Treasury license for Russian-origin diesel followed at 2:50 PM ET. After the cash close, at 4:57 PM ET, the Saudi-led coalition said it is carrying out a wide-ranging operation against Houthi capabilities in Yemen. These are statements carried by the news feed rather than events confirmed for this review.
4.4 Sector Breadth and Rotation
The positioning note said software rose about 3 percent and financials about 1 percent while semiconductors lagged, with the chip fund down about 1 percent, and that the financial sector fund reclaimed a key positioning level. The semiconductor index closed at 12,572.42, down 0.41 percent. The Dow Jones Industrial Average rose 0.83 percent, outpacing the S&P 500's 0.59 percent and the Nasdaq-100's 0.51 percent. The positioning note said its one-month implied correlation measure fell to 6.93 as a dispersion theme continued.
4.5 Cross-Asset and Volatility
The volatility index closed at 14.84, down 0.57. The Nasdaq-100 implied-volatility gauge closed at 20.55. The positioning note put the volatility-of-volatility index at 84.88 and said the volatility complex fell to its August lows ahead of the weekend, with near-term fixed-strike implied volatility down one to two points and next week's at-the-money implied volatility below 10 percent, Monday's near 5.6 percent. The positioning note read that extreme low implied volatility as leaving the market fragile to headline risk ahead of the consumer price index at 8:30 AM ET on Wednesday, October 14, 2026, as the calendar lists it. The note also cited monthly options expiration on Friday, October 16, 2026, per the positioning note and unconfirmed. November WTI crude settled at 91.85, up 0.39 percent, and gold at 4,216.3, up 1.43 percent.
4.6 Institutional Positioning
Friday's volume on the December contract was 1,077,892 contracts against 1,700,014 on Thursday. The open-interest column on the provider's settlement series lags one session, so no open-interest change is asserted for Friday. The news feed carried at 4:15 PM ET that non-commercial net positioning in S&P 500 futures moved to minus 154.1 thousand from minus 142.5 thousand in the week to Tuesday, October 6. The positioning note said the S&P 500 hedging-flow measure finished at about minus 8 billion dollars of delta, driven mainly by about minus 6 billion of same-day call selling, and read the short tenor of the flow as caution about adding longer-dated risk ahead of the weekend.
5. SPX Options Flow Context
The positioning note read for this section is the 5:38 PM ET edition for Friday. Its reference prices are the prior session's closes, not Friday's: SPX 7,765 equals Thursday's 7,765.36 cash close, and 7,765.36 plus 0.59 percent gives 7,811.2, consistent with the note's stated 7,812 close and the provider's 7,811.54. Every level below is read against Friday's 7,811.54 cash close.
On the index the primary call side ceiling sits at SPX 7,900, the largest gamma concentration at SPX 8,000, the modeled volatility threshold at SPX 7,765, the modeled gamma-flip level at SPX 7,720 and the primary put side support base at SPX 7,500. The close sits 88.46 points beneath the 7,900 ceiling, 46.54 points above the threshold and 91.54 points above the flip level. Gamma tilt reads 1.187 and gamma notional plus 736.963 million dollars, so dealer gamma remains positive. The note's summary lists resistance at 7,800, 7,830, 7,850 and 7,900, support at 7,750 and 7,700 and its desk pivot at 7,690, and its key strikes are SPX 8,000, 7,800, 7,000 and 7,700.
The note publishes its own December futures pair for each level, carrying the source's 51.07 point offset rather than this review's measured 48.21 point basis: the ceiling at 7,951.07, the largest concentration at 8,051.07, the modeled volatility threshold at 7,816.07, the modeled gamma-flip level at 7,771.07 and the put side support base at 7,551.07. These are quoted as the source's pairs. The modeled threshold and flip level are model outputs, not option strikes.
The narrative said the S&P 500 traded a 53 basis point range and that same-day iron-condor positions of about 10 thousand contracts at the 7,745 to 7,740 and 7,835 to 7,840 strikes sat in a zone of positive gamma. The note's implied one-day move is 0.52 percent, or about 40.62 points on the 7,811.54 close, and its implied five-day move 1.55 percent, or about 121.08 points. Its published implied one-day high and low do not reconcile with either the reference or the close, so that pair is excluded.
The S&P 500 positioning console, Date Updated 2026-10-09, read at about 6:34 PM ET, shows call gamma of 8.17 billion against put gamma of minus 2.91 billion, with 10.86 percent of gamma attributed to the nearest expiration, against 8.5 billion, minus 2.7 billion and 7.59 percent in Thursday's read. One-month implied volatility of 12.43 percent sits above one-month realised volatility of 10.12 percent, with an implied-volatility rank of 13.45 percent. Its current-price field of 7,817.05 is a post-close indicative quote, not the close, and its high and low volatility point fields are treated as low-confidence and excluded.
In this review's interpretation a cash close above the modeled volatility threshold, with positive gamma tilt and very low near-term implied volatility, favours contained dips toward the 7,816.07 to 7,835.80 zone rather than a trend day lower, and the setup in section 8 buys the band above that threshold pair.
6. Forecast
6.1 Night Session (6:00 PM ET Sunday to 3:00 AM ET Monday, Globex/Asia)
Globex reopens at 6:00 PM ET on Sunday, October 11, after two days of weekend headline exposure, with the 4:57 PM ET Friday coalition statement on Yemen, the Hormuz tanker reports and the Russian diesel arrangement unresolved at the close. A gap above Pivot R1 at 7,881.17 or beneath Pivot S1 at 7,827.67 would reset the level map. Bias neutral to higher above the Pivot Point at 7,849.08, expected Globex band roughly 7,830 to 7,880.
6.2 London Session (3:00 AM to 8:00 AM ET Monday)
A Bank of England policymaker is listed at 5:30 AM ET, per the news-feed calendar and unconfirmed. Bias neutral to higher, expected band roughly 7,826 to 7,884, with the 7,828 to 7,836 band the first meaningful support beneath the 5-day average.
6.3 Morning Session (9:30 AM to 12:00 PM ET Monday, RTH Open)
A second Bank of England policymaker is listed at 8:50 AM ET, per the news-feed calendar and unconfirmed. The cash open at 9:30 AM ET sets the session's first directional test on the Columbus Day holiday, with Globex on normal hours, as the calendar lists it. Expected band roughly 7,820 to 7,890.
6.4 Afternoon Session (12:00 PM to 4:00 PM ET Monday)
A regional Federal Reserve president is listed at 12:10 PM ET, per the news-feed calendar and unconfirmed. The cash close follows at 4:00 PM ET. Expected band roughly 7,820 to 7,895.
6.5 Night Session Forward (6:00 PM ET Monday)
The Tuesday session opens at 6:00 PM ET Monday. Japanese producer prices are listed at 7:50 PM ET and the International Monetary Fund's World Economic Outlook at 10:00 PM ET, both per the news-feed calendar and unconfirmed. Bank earnings begin on Tuesday, October 13, 2026, with the largest bank's results at about 7:00 AM ET, as the calendar lists it.
6.6 Expected Range (Monday Full Session)
Low-range scenario: 7,828 to 7,881
Mid-range scenario (most likely): 7,817 to 7,894
High-range scenario: 7,784 to 7,935
6.7 Most Likely Path
In this review's analyst judgment the most probable path holds the contract between Pivot S1 at 7,827.67 and Pivot R2 at 7,902.58, with a dip toward the 7,828 to 7,836 band that holds above the 7,816.07 threshold pair weighted above a break lower, because the cash close sits above the modeled volatility threshold with positive dealer gamma, the settle sits above every settlement average from the 5-day to the 200-day, and the composite rose to 80 percent buy with direction strengthening. The alternative that would invalidate this reading is a weekend escalation that lifts yields and the dollar, or a renewed slide in chip shares, carrying the contract through 7,816.07 toward Pivot S3 at 7,774.17 and the 7,771.07 flip pair.
7. Monday Economic Calendar
Globex reopens at 6:00 PM ET on Sunday, October 11. Monday, October 12, is the Columbus Day holiday, with Globex on normal hours and products settling at normal times, as the calendar lists it; the Federal Reserve is closed and its daily statistical releases move to Tuesday, as the same calendar lists it.
A Bank of England policymaker is listed at 5:30 AM ET and a second at 8:50 AM ET, and a regional Federal Reserve president at 12:10 PM ET, all per the news-feed calendar and unconfirmed. The cash session runs from 9:30 AM ET to 4:00 PM ET. Japanese producer prices are listed at 7:50 PM ET, the Australian central bank's minutes at 8:30 PM ET and the International Monetary Fund's World Economic Outlook at 10:00 PM ET, all per the news-feed calendar and unconfirmed. The captured calendars carry no mega-capitalisation earnings entry for Monday.
Later in the week, bank earnings begin on Tuesday, October 13, 2026, with the largest bank's results at about 7:00 AM ET, as the calendar lists it. The consumer price index for September is scheduled for 8:30 AM ET on Wednesday, October 14, 2026, as the calendar lists it, and retail sales and producer prices for 8:30 AM ET on Thursday, October 15, 2026, as the calendar lists it. In this review's judgment the captured calendars carry only central-bank speakers for Monday, so the first-order influences on the S&P 500 are weekend headlines and the start of bank earnings on Tuesday, with the September consumer price index on Wednesday the week's key scheduled event.
8. Primary Trade Setup
Direction: Long
Rationale: The cash close sits 46.54 points above the modeled volatility threshold at SPX 7,765 with positive dealer gamma, the settle sits above every settlement average from the 5-day to the 200-day, and the composite rose to 80 percent buy with direction strengthening; a dip into one standard deviation support at 7,835.80 and Pivot S1 at 7,827.67 offers a long with a defined risk point beneath the 7,816.07 source futures pair of that threshold. The directional systems show positive direction with low ADX readings and near-term implied volatility is unusually low into a week with the consumer price index, so the setup is an analyst judgment that dips stay contained above the threshold pair, not a measured edge.
Entry Zone: 7,828 to 7,836
Stop Loss: 7,808 (beneath the 7,816.07 source pair of the modeled volatility threshold and Friday's 7,817.00 low)
Target 1 (T1): 7,856 (2.17 above the 7,853.83 published target price)
Target 2 (T2): 7,880 (1.17 beneath Pivot R1 at 7,881.17)
Target 3 (T3, extended): 7,904 (1.42 above Pivot R2 at 7,902.58 and 1.00 beneath the 7,905.00 52-week high)
Risk-to-Reward: Approximately 1:1 to T1, 1:2 to T2, 1:3 to T3
Invalidation: A settle beneath the 7,816.07 source pair of the modeled volatility threshold negates the thesis. Short of that, the edge is removed by acceptance beneath two standard deviations support at 7,825.89 rather than by a touch, defined as two consecutive 30-minute closes beneath 7,825.89.
Macro override: A weekend escalation in the Gulf that lifts yields and the dollar, or a renewed slide in chip shares, would invalidate the long in real time. In that scenario a gap beneath the 7,808 stop removes the setup before entry, and Pivot S3 at 7,774.17 and the 7,771.07 gamma-flip pair become the references within one 14-day average true range of 75.40 points.
Sources and methodology
This outlook is built from our session review of the December E-mini S&P 500 contract, the December ’26 contract, prepared after Friday's close on October 9, 2026 for the Monday, October 12, 2026 session, and from the Sunday evening update written at 9:48 PM ET on October 11, 2026, which carries the overnight quotes and the weekend headlines. Friday's completed extremes are the inputs behind the published pivot ladder: Pivot R3 at 7,934.67 less Pivot S3 at 7,774.17, divided by three, and Pivot R2 at 7,902.58 less Pivot S2 at 7,795.58, divided by two, both return 53.50, and three times the 7,849.08 Pivot Point less the settle gives a high-plus-low sum of 15,687.49, 0.01 from the 15,687.50 of the solved pair of 7,870.50 and 7,817.00 because the published pivot is rounded. The provider's overview, its settlement row and the chart's completed Friday bar carry the same extremes. Those figures and the review's own statements are the only evidence used to grade Friday's card. No complete intraday series was preserved, so no claim is made about when the high or the low printed. Thursday's volume now reads 1,700,014 contracts, a revised figure that replaces the 1,637,654 carried in Friday's outlook; that post was not changed.
The moving averages were computed from the provider's 260-session daily settlement series through Friday; the oscillators are cited as published for the Friday session, read after the settle with Globex closed for the weekend. The positioning note used is the 5:38 PM ET edition for Friday, October 9; its reference column carries Thursday's closes and its futures column a fixed 51.07 point translation, so cash equivalents here use the 48.21 point basis measured on Friday, settlement against cash close. The note's implied one-day high and low pair does not reconcile with either the reference or the close and is excluded. The console's 7,817.05 current-price field is a post-close indicative quote, and its high and low volatility point fields are excluded as low-confidence. Sunday quotes are those in the 9:48 PM ET update, with the session still open. Scenario ranges are analyst judgment. Items marked unconfirmed come from the news-feed calendar or press reports, and every catalyst whose release time had passed at the time of writing is recorded as completed.
Friday’s outlook for this contract is here, and the Nasdaq-100 contract’s Friday outlook covers the index that rose 0.51 percent in cash on Friday. Outlooks for ES, NQ, GC and CL are collected on the market outlook page, and our forward trading record is on the performance statement.