In the 30-minute bar that began at 10:00 AM ET on Tuesday, December gold reached 4,207.2, the high of the settlement window. That bar held the job openings report, 7.079 million against a 7.2275 million forecast, and a consumer confidence reading of 81.9 against a forecast of 89. Both came in beneath forecast, and the move and the releases coincided in the same bar. The 11:00 AM ET bar traded back to 4,180.0. The contract settled at 4,179.7 at 1:30 PM ET, up 11.3 points or 0.27 percent from Monday's 4,168.4, at 47.3 percent of a 72.9 point range.
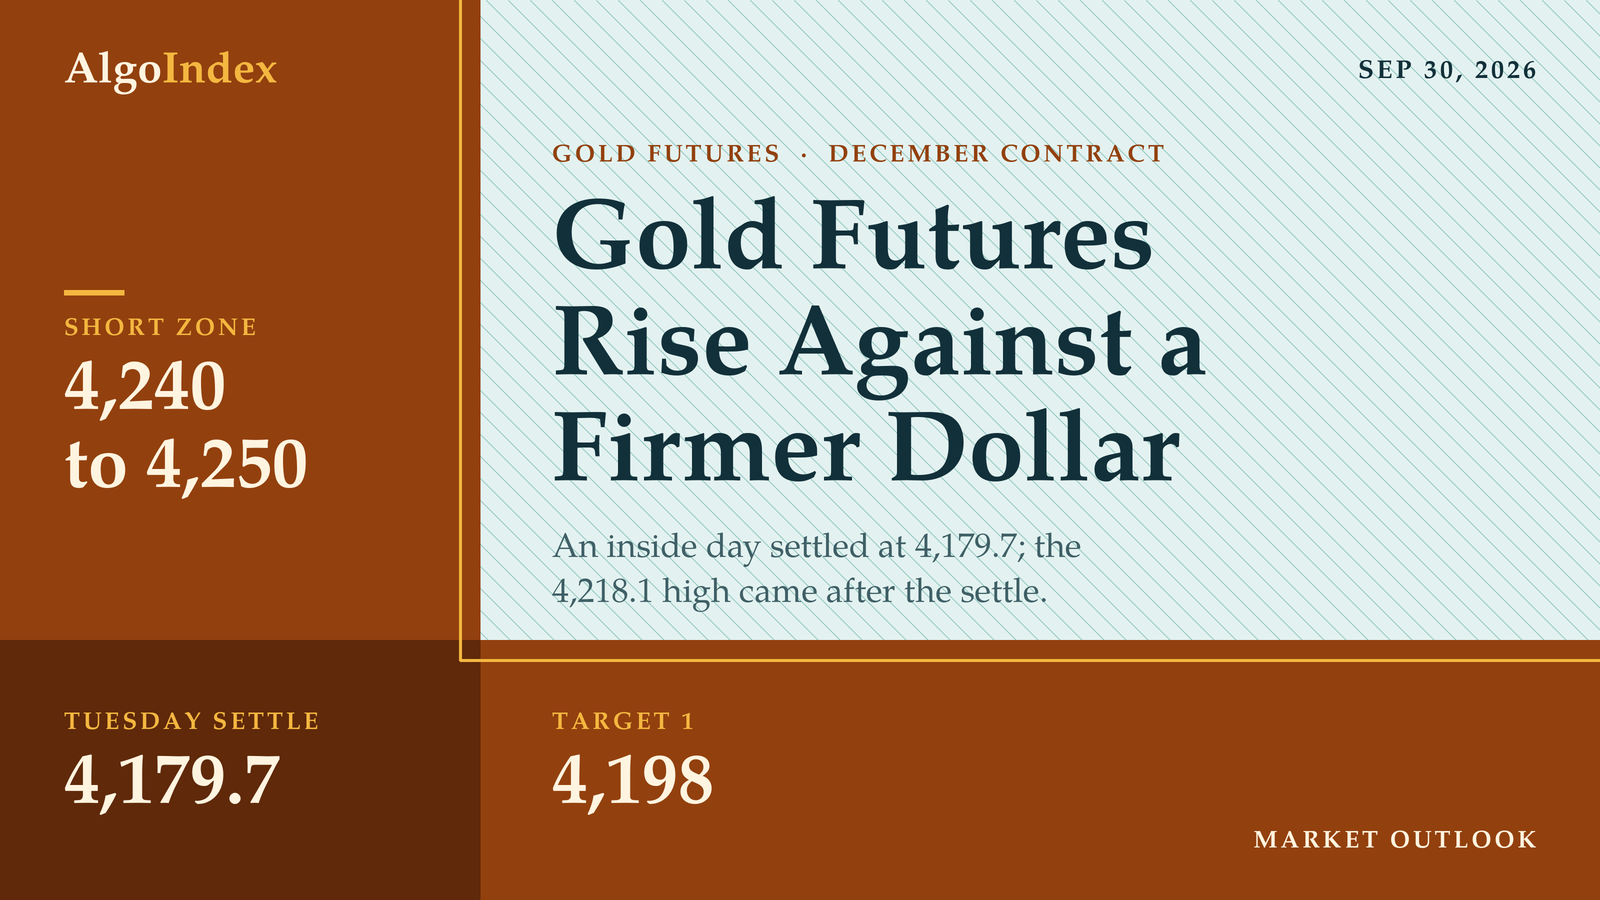
The ends of the day sat outside that window. The 4,145.2 low printed in the 9:00 PM ET bar on Monday evening, soon after the reopen. The 4,218.1 daily high came after the settle, in the 4:30 PM ET bar, and the Wednesday session reopened at 4,216.2. Gold's gain came against a firmer dollar and higher yields. The dollar index closed at 101.37, which provider commentary called a two-month high, and the ten-year yield index printed a 5.29 percent session high before closing at 5.26 percent. Tuesday was an inside day against Monday's 172.7 point row. Wednesday's primary setup is a short from 4,240 to 4,250, beneath Pivot R2 at 4,253.9.
December gold settled at 4,179.7, 34.5 points above Tuesday's 4,145.2 low and 38.4 points beneath the 4,218.1 post-settlement high. The Wednesday session reopened at 4,216.2, 36.5 points above the settle and 0.6 points beneath Pivot R1 at 4,216.8. The settle sits beneath all six settlement averages, from the 5-day at 4,257.1 to the 200-day at 4,645.7. The composite reads "80% SELL", with Current Direction "Strengthening". The 14-day raw stochastic reads 10.87 percent. The primary setup is a short from 4,240 to 4,250, stop 4,292, targets 4,198, 4,151 and 4,104. Wednesday's first-order event is the personal income and outlays report, which the calendar lists at 8:30 AM ET.
Tuesday's short, scored against the bar
Our Tuesday outlook set a short from 4,205 to 4,215, stop 4,265, with targets at 4,155, 4,100 and 4,045. Tuesday's completed bar ran from 4,145.2 to 4,218.1. That range covered the whole entry band. The high cleared the top of the band by 3.1 points, and the low sat 59.8 points beneath its bottom. The session opened at 4,150.1, 54.9 points beneath the band. The 4,265 stop stayed 46.9 points above the high. It was never reached.
This time the series shows the order. The preserved 30-minute provider series places the first trade inside the band in the 10:00 AM ET bar, which reached 4,207.2. No earlier bar traded above the 4,196.8 of the 9:30 AM ET bar. The 4,145.2 session low, 9.8 points through the 4,155 first target, had printed in the 9:00 PM ET bar on Monday evening, 13 hours before that. So that print carries no result for the card. From the 10:00 AM ET bar through the 4:30 PM ET bar, the lowest print was 4,174.4, in the 1:30 PM ET bar, 19.4 points above the first target. The second target at 4,100 stayed 45.2 points beneath the session low, and the third, at 4,045, stayed 100.2 points beneath it.
The card's two exit lines held as well. Tuesday settled at 4,179.7, 95.3 points beneath Pivot R1 at 4,275.0, the settle line the card named as its invalidation, and 25.3 points beneath the bottom of the band. The second test was two consecutive 30-minute closes above the 4,221.2 stall point for the 14-day %k, with the 4,244.1 threshold also cleared. The highest 30-minute close in the series was 4,215.0, in the 4:30 PM ET bar. The 4,218.1 daily high stayed 3.1 points beneath 4,221.2. Neither line was crossed.
The scoring uses the dated 2026-09-29 row of the provider's daily record. It reads 4,150.1, 4,218.1, 4,145.2 and 4,179.7, on 146,181 contracts, with no open-interest figure yet. Tonight's review states the same open, high, low and settle. Monday's row now carries 229,031 contracts, against the preliminary 221,267 our Tuesday outlook carried, and open interest of 324,659, up 2,159 from Friday's 322,500.
Tuesday began near its low. The contract opened at 4,150.1 at the Monday 6:00 PM ET reopen, 18.3 points beneath Monday's settle. The 4,145.2 low printed in the 9:00 PM ET bar. The evening and Asian bars held between 4,145.2 and 4,171.8 through the 11:30 PM ET bar. Then the advance came in steps. The 2:00 AM ET bar reached 4,179.5, the 7:00 AM ET bar 4,193.3 and the 9:30 AM ET bar 4,196.8.
The 10:00 AM ET bar opened at 4,189.5 and reached 4,207.2 before closing at 4,204.1. It contained the job openings and consumer confidence releases, both beneath forecast, and the move and the releases coincided in the same bar. The 11:00 AM ET bar opened at 4,202.2 and traded down to 4,180.0. The 12:30 PM ET bar reached 4,176.7 before the 1:30 PM ET settlement at 4,179.7. The settle-window range was therefore 4,207.2 to 4,145.2, or 62.0 points.
After the settle the contract rose. The 2:00 PM ET bar opened at 4,176.5 and reached 4,203.1. That move coincided with a 2:00 PM ET news-feed item in which the New York Fed president said one further rate increase is likely this year if the economy meets expectations. Provider commentary described those remarks as dovish. The bars through the close extended to 4,218.1 in the 4:30 PM ET bar, 38.4 points above the settle, and that bar closed at 4,215.0. The series shows the moves and the headlines in the same bars. It does not establish causation. The preserved series holds 46 bars, from the reopen through that 4:30 PM ET bar.
Those extremes carry a provenance note. They are the completed-session inputs behind the published pivot ladder, back-solved from its outer pairs. The third resistance point at 4,289.7 less the third support point at 4,071.0, divided by three, returns 72.9. The second pair, 4,253.9 less 4,108.1, divided by two, returns the same 72.9. Three times the 4,181.0 Pivot Point less the 4,179.7 settle gives a high-plus-low sum of 8,363.3. The pair of 4,218.1 and 4,145.2 then reproduces all seven published rungs. The chart's completed Tuesday daily bar reads 4,150.1, 4,218.1, 4,145.2 and 4,179.7. The reopened session's open of 4,216.2, high of 4,217.3 and low of 4,212.8 belong to Wednesday and are not used as Tuesday's range anywhere here.
Tuesday traded entirely inside Monday's range. Its 4,218.1 high sits 97.7 points beneath Monday's 4,315.8 high, and its 4,145.2 low sits 2.1 points above Monday's 4,143.1 low, which remains the one-month low. The range was 0.76 times the published 14-day average daily range of 96.2 points, a contraction after Monday's expansion. Our Tuesday outlook gave Monday's range as 172.5 points from a 4,315.6 high. The provider's revised row shows 4,315.8, so the range is now 172.7. Apart from Monday's 4,168.4, the settle is the lowest since the 4,152.6 settle of 08/04.
An inside day beneath all six averages
The prior week, September 21 through September 25, spanned 4,422.1 to 4,278.3. Tuesday's whole range sits beneath that week's low. Across five sessions the contract lost 196.7 points, or 4.49 percent, from the 4,376.4 settle of 09/22. The one-month high of 4,558.5, set on 09/03/26, sits 378.8 points above the settle. The 13-week low of 4,015.6, set on 06/30/26, sits 164.1 points beneath it. The settle sits 27.7 percent beneath the 52-week high of 5,781.8, set on 01/29/26. No prior-quarter high or low is available tonight, so the 13-week extremes serve as the quarterly reference. The provider's overview lists the 13-week high at 4,755.0, set on 08/25/26, and the 52-week low at 3,978.7, set on 09/30/25.
Read the settlements in order. From 09/14 they run 4,351.9, 4,332.8, 4,387.5, 4,399.7, 4,424.9, 4,383.9, 4,376.4, 4,318.4, 4,298.0, 4,321.2, 4,168.4 and 4,179.7. The swing high remains the 4,424.9 settle of 09/18. Lower settles since then carried the contract to Monday's 4,143.1 low. Tuesday is the first session since that low. It held above it. Daily ranges for the last seven sessions ran 61.8, 86.5, 96.8, 59.7, 62.4, 172.7 and 72.9.
Four retracement references sit overhead. The grid published for Wednesday places the 38.2 percent retracement from the 13-week low at 4,298.1 and from the four-week low at 4,301.8. The 50 percent retracement of the four-week range sits at 4,350.8, and the 38.2 percent retracement from the 13-week high at 4,472.5. No four-hour series is available. The 30-minute series is the only intraday evidence used.
Every average is still overhead. The figures come from the provider's daily settlement series for the December contract, 259 completed sessions through Tuesday. The 5-day average stands at 4,257.1, the 9-day at 4,319.0, the 20-day at 4,374.3, the 50-day at 4,370.3, the 100-day at 4,381.4 and the 200-day at 4,645.7. The settle sits 77.4 points beneath the 5-day, 194.6 beneath the 20-day, 190.6 beneath the 50-day and 466.0 beneath the 200-day.
Two averages moved in opposite directions. The 20-day fell 15.1 points from Monday's 4,389.4, because the 08/31 settle of 4,481.5 left its window and was replaced by 4,179.7. The 50-day rose 2.1 points from 4,368.2, because the 07/20 settle of 4,073.0 left its window. The 20-day now sits only 4.0 points above the 50-day. So the 30 settles from 07/21 through 08/31, the older part of the 50-day window, averaged lower than the latest 20. The projection grid gives Wednesday's crossing prices at 4,308.9 for the 9-day, 4,360.9 for the 18-day and 4,438.2 for the 40-day, with the 40-day stall at 4,152.6.
The oscillators sit low. They are published figures from the provider's technical page dated for the Wednesday session. That page was read after the 6:00 PM ET reopen, so the most recent value in each may include live Globex trade in place of the settle. Relative strength reads 27.08 on the 9-day, 33.99 on the 14-day and 38.88 on the 20-day. The grid places the 14-day relative-strength 30 percent line at 4,101.7 and its 50 percent line at 4,367.4. Stochastics sit at the bottom of their range. The 9-day raw stochastic reads 12.34 percent and the 14-day 10.87 percent. The 14-day %K sits at 13.54 percent and %D at 14.12 percent. The grid places the 14-3 day raw stochastic 20 percent threshold at 4,210.5 and its 30 percent threshold at 4,244.1.
The directional system points down. On the 9-day the directional index reads 27.36, with negative direction at 28.30 against positive direction at 8.41. The 14-day reads 18.17, negative 25.01 over positive 11.40. The composite multi-indicator snapshot, quoted verbatim, reads overall "80% SELL", Current Strength "Good", Current Direction "Strengthening" and Composite Indicator "SELL". The short-term group reads "60% SELL", the medium-term group "100% SELL" and the long-term group "67% SELL". Yesterday it read "64% SELL". Last week, "HOLD". Last month, "16% BUY". The sell reading deepened from the prior session and has moved from a buy reading a month ago.
Tuesday's range ran under the averages. The published 14-day average true range stands at 101.4 points, 2.43 percent of the settle, and the 14-day average daily range at 96.2 points. The 9-day average true range is 99.0 and the 20-day 102.9. Historic volatility reads 19.31 percent on the 9-day and 18.02 percent on the 14-day. Applied either side of the 4,179.7 settle, the 14-day average true range frames Wednesday between 4,078.3 and 4,281.1. The published standard-deviation bands are built from five settlements. One deviation spans 4,103.2 to 4,256.2, two span 4,071.5 to 4,287.9 and three span 4,047.2 to 4,312.2. The 4,216.2 reopen already sits inside the upper half of the one-deviation band.
Higher yields, a firmer dollar, and gold still up
Start with the rate channel. The ten-year yield index printed a 5.29 percent session high, which provider commentary called a new 19-year high, before closing at 5.26 percent, up 2 basis points. The thirty-year closed at 5.59 percent after a 5.62 percent high, and the desk note said thirty-year yields reached their highest level since 2002. The dollar index closed at 101.37, up 0.17 points, after a 101.61 high. Provider commentary described that close as a two-month high supported by rising Treasury yields. No real-yield series is available, so only nominal yields are cited.
Gold rose against both. In our review's interpretation that reflects the offset from lower crude and softer data rather than a change in the rate backdrop.
Crude did most of the offsetting. The November contract settled at 89.38, down 3.48 percent, and Brent's November contract at 102.59, down 2.56 percent. Provider commentary said the energy decline eased inflation expectations. The job openings report showed 7.079 million openings against a 7.2275 million forecast, and consumer confidence printed 81.9 against 89, per the news-feed calendar. Provider commentary described the confidence reading as a 12-year low.
Policy pricing moved after the New York Fed president spoke. In a 2:00 PM ET news-feed item he said one further rate increase is likely this year if the economy meets expectations. In a 4:05 PM ET item he said rising bond yields show tighter financial conditions at the margin. He also said he does not believe they signal shifting longer-run inflation views. The desk note reported that the priced probability of an October increase fell to 45 percent from 70 percent after his remarks. Provider commentary gave a figure of 52 percent. The two sources disagree. Neither figure is used as a level input. The next rate decision is listed for October 28, 2026 at 2:00 PM ET on the news-feed calendar, unconfirmed.
The Iran talks stayed unresolved in the reporting on hand. A press report on the news feed at 2:31 PM ET said mediators are pushing to break the deadlock. An energy-news item at 3:01 PM ET described Iranian threats against regional energy infrastructure. The Iranian president's office said at 3:24 PM ET that Iran will not compromise on nuclear rights, and the President said at 3:56 PM ET that Iran is doing very poorly. All of these items arrived after gold's 1:30 PM ET settle.
Structural demand is the blind spot again. No central-bank purchase figure and no Chinese import or premium data are available, so none is asserted. Chinese manufacturing survey data are listed at 9:30 PM ET on September 29, 2026, per the news-feed calendar and unconfirmed. The gold exchange-traded fund closed at 382.89, up 4.98 or 1.32 percent, per the provider's end-of-day record. No holdings figure is available.
Elsewhere the moves were small. Silver's December contract settled at 61.153, down 0.92 percent. The S&P 500 cash index closed at 7,670.84, down 0.17 percent, and the Nasdaq-100 at 30,339.33, up 0.21 percent. The volatility index closed at 16.04.
Then positioning. The report as of September 22, 2026, unchanged since Monday's review, shows managed money long 135,699 contracts against short 8,310. That is a net long of 127,389, with long positions down 6,695 on the week. Swap dealers held 14,626 long against 250,752 short. The report predates the 196.7 point decline of the past five sessions, so the current speculative length is not known. The next report covers positions as of Tuesday, September 29.
The bullion fund is read qualitatively only. It tracks bullion with a fee drag and at a ratio that has no clean basis to the futures contract, so no level from it becomes a futures price. The positioning console for the fund, dated as updated on 2026-09-29, showed a current price of 383.28 against a previous close of 377.91, a daily change of 1.42 percent, on 14,038,684 shares. Call gamma read minus 268 million dollars and put gamma 171 million dollars. The console's current price includes trade after the provider's 382.89 end-of-day close. That conflict is recorded and left unresolved. The high-volatility-point and low-volatility-point fields are excluded as low-confidence. Next-expiry gamma fell to 2.31 percent of the total, from 5.20 percent in the prior review. In our review's interpretation, the fund's near-dated options book carries less weight into Wednesday.
The trade map for Wednesday
The setup leans on the sell readings. The composite deepened to "80% SELL" with Current Direction "Strengthening". The directional system points down, and the settle sits beneath all six settlement averages. Tuesday's post-settlement advance still carried the contract to Pivot R1. A further rebound into the band between the stochastic 30 percent threshold at 4,244.1 and Pivot R2 at 4,253.9 offers a short with a defined risk point above Pivot R3. The entry zone runs 4,240 to 4,250, 60.3 to 70.3 points above the settle and 23.8 to 33.8 points above the 4,216.2 reopen. The stop at 4,292 sits above Pivot R3 at 4,289.7 and two standard deviations resistance at 4,287.9. From the 4,245 entry midpoint the stop sits 47 points away. The 14-day average true range is 101.4 points. Gold rose against a firmer dollar and higher yields on Tuesday, so the setup is an analyst judgment against evident underlying demand.
The reopen came in higher. The Wednesday session reopened at 4,216.2 at 6:00 PM ET, 36.5 points above the settle and 0.6 points beneath Pivot R1 at 4,216.8, after the post-settlement advance. Chinese manufacturing survey data and Australian consumer prices are listed at 9:30 PM ET, per the news-feed calendar and unconfirmed. The first test is whether the post-settlement gain holds above the 4,207.2 settle-window high. The night session, 6:00 PM ET Tuesday to 3:00 AM ET Wednesday, carries a neutral bias beneath the 4,244.1 to 4,256.2 band. Expected Globex band roughly 4,190 to 4,245.
London runs from 3:00 AM to 8:00 AM ET. United Kingdom output data are listed at 2:00 AM ET and French consumer prices at 2:45 AM ET, just before it. German unemployment follows at 3:55 AM ET and German consumer prices at 8:00 AM ET, forecast 3.1 percent year on year, all per the news-feed calendar and unconfirmed. Tuesday's advance built through this window. A stall beneath Pivot R2 at 4,253.9 here would be the first sign that the post-settlement move is fading. Bias neutral. Expected band roughly 4,185 to 4,255.
Then the United States morning, 9:30 AM to 12:00 PM ET. The private payroll survey comes first, at 8:15 AM ET, forecast 74,000 against 38,000, per the news-feed calendar and unconfirmed. The calendar lists the personal income and outlays report at 8:30 AM ET. The third estimate of second-quarter output comes with it. The news-feed calendar lists core price-index forecasts of 3.3 percent year on year, against 3.3 percent, and 0.3 percent month on month. Yields are the channel. A firm price-index print that lifts yields again would press the contract back toward the 4,181.0 Pivot Point and the 4,152.6 average stall. A soft print that eases yields keeps the 4,244.1 to 4,256.2 band in play. The weekly petroleum status report follows at 10:30 AM ET. Expected band roughly 4,150 to 4,265.
The afternoon, 12:00 PM to 4:00 PM ET, holds the 1:30 PM ET gold settlement. A regional Federal Reserve president is listed at 1:30 PM ET, per the news-feed calendar and unconfirmed. Wednesday is also the last session of the quarter, and the desk note flagged quarter-end pension rebalancing. The calendar lists a Federal Reserve governor at 3:25 PM ET. Expected band roughly 4,160 to 4,250.
Wednesday evening's Globex session opens at 6:00 PM ET. Micron's quarterly results follow the equity close, and the calendar lists the call at 4:30 PM ET. Further Federal Reserve speakers are listed at 5:10 PM ET and 6:00 PM ET, per the news-feed calendar and unconfirmed. The calendar lists the employment report at 8:30 AM ET on October 2, 2026.
The single first-order event for gold on Wednesday is the personal income and outlays report at 8:30 AM ET, through its effect on the ten-year yield and the dollar. Three scenario bands frame the full session. The low-range case runs 4,180 to 4,245. The mid-range case, the most likely, runs 4,150 to 4,260, and the high-range case 4,100 to 4,290.
In our review's analyst judgment, the most probable path holds the Globex session between the 4,194.6 stall and the 4,244.1 stochastic threshold. In the same judgment, the 8:30 AM ET report on September 30, 2026 decides the direction of the United States morning, and a settle between 4,152.6 and 4,256.2 is weighted above a settle outside that band. Why? The composite read deepened to "80% SELL" and the directional system points down. Tuesday, though, held above Monday's low, and the post-settlement advance reached Pivot R1. The alternative that would invalidate this reading is a soft price-index print with a sharp fall in yields, which would put the 4,287.9 to 4,312.2 band in play.
Tuesday's whole range fit inside Monday's, and Wednesday reopened at 4,216.2, beside Pivot R1, with the 4,240 to 4,250 band still 23.8 points overhead.
The complete data picture
Every number behind Wednesday’s plan, charted first, then the full level lists, then the complete numeric reference underneath.
Full numeric reference, every remaining figure from the session review
Carried below in the review's own order: the level notes behind sections 3.1 and 3.2, the executive summary from section 1, sections 2.1 to 2.6, sections 4.1 to 4.6, the fund options context from section 5, the session-by-session forecast from section 6, the Wednesday calendar from section 7 and the primary setup from section 8.
Level notes (3.1 Resistance and 3.2 Support)
The reopened session trades near Pivot R1 at 4,216.8, with the 4,218.1 post-settlement high 1.3 points above it and the stochastic 20 percent threshold at 4,210.5 beneath it. The next band runs from the stochastic 30 percent threshold at 4,244.1 through Pivot R2 at 4,253.9 to one standard deviation resistance at 4,256.2.
Above that, the 5-day settlement average at 4,257.1, two standard deviations resistance at 4,287.9 and Pivot R3 at 4,289.7 form the upper group, with the 38.2 percent retracements at 4,298.1 and 4,301.8 and the 9-day average crossing at 4,308.9 just beyond. Three standard deviations resistance at 4,312.2 and Monday's 4,315.8 high are the extended references.
The settle-window high of 4,207.2 and the 4,194.6 stall level for the 14-day %k line are the first references beneath the reopened price, followed by the Pivot Point at 4,181.0 and the 4,179.7 settle. The 40-day average stall at 4,152.6, the 4,145.2 Tuesday low, Pivot S1 at 4,143.9 and Monday's 4,143.1 one-month low sit within 9.5 points of each other.
Beneath that, the published target price at 4,138.4, Pivot S2 at 4,108.1, one standard deviation support at 4,103.2 and the relative-strength 30 percent line at 4,101.7 form the next group, with the three-and-ten day crossover stall at 4,074.6, two standard deviations support at 4,071.5 and Pivot S3 at 4,071.0 as the deeper references.
1. Executive Summary
The December gold contract settled at 4,179.7 on Tuesday, up 11.3 points or 0.27 percent from Monday's 4,168.4 settle. The daily row spans 4,218.1 to 4,145.2, a 72.9 point range, and the settle finished at 47.3 percent of it. Tuesday was an inside day against Monday's 172.7 point row, and the range was 0.76 times the published 14-day average daily range of 96.2 points, a contraction after Monday's expansion. Apart from Monday's 4,168.4, the settle is the lowest since the 4,152.6 settle of 08/04.
The preserved 30-minute series shows that the two ends of the daily row belong to different windows. The 4,145.2 low printed in the 9:00 PM ET bar on Monday evening, soon after the reopen. The contract then climbed through the Asian and European hours, and the 10:00 AM ET bar, which contained a job openings report of 7.079 million against a 7.2275 million forecast and a consumer confidence reading of 81.9 against a forecast of 89, reached the 4,207.2 settle-window high. The 11:00 AM ET bar traded back to 4,180.0, and the contract settled at 4,179.7 at 1:30 PM ET. The 4,218.1 daily high came after the settle, in the 4:30 PM ET bar, and the Wednesday session reopened at 4,216.2.
Gold's gain came against a firmer dollar and higher yields: the dollar index closed at 101.37, which provider commentary called a two-month high, and the ten-year yield index printed a 5.29 percent session high (provider record read at 06:46 PM ET), a new 19-year high in that commentary, before closing at 5.26 percent. Crude's 3.48 percent decline and the weaker labour and confidence data were the offsets, and provider commentary described the New York Fed president's remarks as dovish. The composite multi-indicator snapshot nonetheless deepened to "80% SELL" from "Yesterday 64% SELL".
The primary setup is a short from the 4,240 to 4,250 band between the stochastic 30 percent threshold and Pivot R2 at 4,253.9, stopped above Pivot R3 at 4,289.7, with objectives at 4,198, 4,151 and an extended 4,104.
2.1 Intraday and Session Review
The Tuesday session opened at 4,150.1 at the Monday 6:00 PM ET reopen, 18.3 points beneath Monday's settle, marked a daily high of 4,218.1 and a daily low of 4,145.2, and settled at 4,179.7 at 1:30 PM ET. The preserved 30-minute provider series, 46 bars from the reopen through the 4:30 PM ET bar, places the low in the 9:00 PM ET Monday bar and the daily high in the 4:30 PM ET Tuesday bar, so the session made its low first and its high more than 19 hours later, after the settle.
The evening and Asian bars held between 4,145.2 and 4,171.8 through the 11:30 PM ET bar. The advance came in steps: the 2:00 AM ET bar reached 4,179.5, the 7:00 AM ET bar 4,193.3 and the 9:30 AM ET bar 4,196.8. The 10:00 AM ET bar opened at 4,189.5 and reached 4,207.2 before closing at 4,204.1; it contained the job openings and consumer confidence releases, both beneath forecast, and the move and the releases coincided in the same bar. The 11:00 AM ET bar opened at 4,202.2 and traded down to 4,180.0, and the 12:30 PM ET bar reached 4,176.7 before the 1:30 PM ET settlement at 4,179.7. The settle-window range was therefore 4,207.2 to 4,145.2, or 62.0 points.
After the settle the contract rose. The 2:00 PM ET bar opened at 4,176.5 and reached 4,203.1, a move that coincided with a 2:00 PM ET news-feed item in which the New York Fed president said one further rate increase is likely this year if the economy meets expectations, and which provider commentary described as dovish. The bars through the close extended to 4,218.1 in the 4:30 PM ET bar, 38.4 points above the settle, and that bar closed at 4,215.0. The series shows the moves and the headlines in the same bars; it does not establish causation.
The session extremes used here are the completed-session inputs behind the published pivot ladder, back-solved from the outer pivot pairs and verified against every rung. The third resistance point at 4,289.7 minus the third support point at 4,071.0, divided by three, returns 72.9, and the second resistance point at 4,253.9 minus the second support point at 4,108.1, divided by two, returns the same 72.9. Three times the Pivot Point of 4,181.0 less the 4,179.7 settle gives a high plus low sum of 8,363.3, and the resulting pair of 4,218.1 and 4,145.2 reproduces all seven published rungs. The chart's completed Tuesday daily bar reads 4,150.1, 4,218.1, 4,145.2 and 4,179.7, an independent confirmation, and the intraday series shows that the ladder's high belongs to the post-settlement window.
Because Globex reopened at 6:00 PM ET, the provider's overview page now shows the Wednesday session: its open of 4,216.2, high of 4,217.3 and low of 4,212.8 belong to the new session and are not used as Tuesday's range anywhere in this outlook.
2.2 Daily Structure
Tuesday traded entirely inside Monday's range: the 4,218.1 high sits beneath Monday's high and the 4,145.2 low sits 2.1 points above Monday's 4,143.1 low, which remains the one-month low. The prior week, September 21 through September 25, spanned 4,422.1 to 4,278.3, so Tuesday's whole range sits beneath that week's low.
Across five sessions the contract lost 196.7 points or 4.49 percent from the 4,376.4 settle of 09/22. The one-month high of 4,558.5, set on 09/03/26, sits 378.8 points above the settle, and the 13-week low of 4,015.6, set on 06/30/26, sits 164.1 points beneath it. The settle sits 27.7 percent beneath the 52-week high of 5,781.8, set on 01/29/26.
No prior-quarter high or low is available, so the 13-week extremes serve as the available quarterly reference.
2.3 4-Hour and Swing Structure
The daily settlement sequence from 09/14 reads 4,351.9, 4,332.8, 4,387.5, 4,399.7, 4,424.9, 4,383.9, 4,376.4, 4,318.4, 4,298.0, 4,321.2, 4,168.4 and 4,179.7. The swing high remains the 4,424.9 settle of 09/18, and the lower settles since then carried the contract to Monday's 4,143.1 low; Tuesday is the first session since that low and it held above it. Daily ranges for the last seven sessions ran 61.8, 86.5, 96.8, 59.7, 62.4, 172.7 and 72.9.
The retracement grid published for Wednesday places the 38.2 percent retracement from the 13-week low at 4,298.1 and from the four-week low at 4,301.8, the 50 percent retracement of the four-week range at 4,350.8 and the 38.2 percent retracement from the 13-week high at 4,472.5. No four-hour series is available; the 30-minute series in section 2.1 is the only intraday evidence used.
2.4 Moving Averages
The averages cited here were computed from the provider's daily settlement series for the December contract, which holds 259 completed sessions through Tuesday. The 5-day average stands at 4,257.1, the 9-day at 4,319.0, the 20-day at 4,374.3, the 50-day at 4,370.3, the 100-day at 4,381.4 and the 200-day at 4,645.7.
The 4,179.7 settle sits beneath every one of them: 77.4 points beneath the 5-day, 194.6 beneath the 20-day, 190.6 beneath the 50-day and 466.0 beneath the 200-day. The 20-day average fell 15.1 points from Monday's 4,389.4, because the 08/31 settle of 4,481.5 left its window and was replaced by 4,179.7, while the 50-day rose 2.1 points from 4,368.2, because the 07/20 settle of 4,073.0 left its window. The 20-day average sits 4.0 points above the 50-day, which means the 30 settles from 07/21 through 08/31 that make up the older part of the 50-day window averaged lower than the latest 20.
The projection grid gives the prices at which each average would be crossed on Wednesday: 4,308.9 for the 9-day, 4,360.9 for the 18-day and 4,438.2 for the 40-day, with the 40-day stall at 4,152.6.
2.5 Oscillator and Trend Readings
The oscillator figures below are as published on the provider's technical page dated for the Wednesday session, which was read after the 6:00 PM ET reopen, so the most recent value in each may include live Globex trade rather than the settle. Relative strength reads 27.08 on the 9-day, 33.99 on the 14-day and 38.88 on the 20-day. The published grid places the 14-day relative-strength 30 percent line at 4,101.7 and its 50 percent line at 4,367.4.
Stochastics sit at the bottom of their range. The 9-day raw stochastic reads 12.34 percent and the 14-day 10.87 percent, with the 14-day %K at 13.54 percent and %D at 14.12 percent. The published grid places the 14-3 day raw stochastic 20 percent threshold at 4,210.5 and its 30 percent threshold at 4,244.1.
The directional system points down. On the 9-day the directional index reads 27.36 with positive direction at 8.41 and negative direction at 28.30; on the 14-day it reads 18.17 with positive direction at 11.40 against negative at 25.01. Historic volatility reads 19.31 percent on the 9-day and 18.02 percent on the 14-day.
The composite multi-indicator snapshot reads, verbatim: overall "80% SELL", Current Strength "Good", Current Direction "Strengthening", Composite Indicator "SELL"; short-term group "60% SELL", medium-term group "100% SELL", long-term group "67% SELL"; snapshot "Yesterday 64% SELL", "Last Week HOLD", "Last Month 16% BUY". The sell reading deepened from the prior session and has moved from a buy reading a month ago.
2.6 Volatility and Expected Range
The published 14-day average true range stands at 101.4 points, 2.43 percent of the settle, and the 14-day average daily range at 96.2 points; the 9-day average true range is 99.0 and the 20-day is 102.9. Tuesday's 72.9 point range was 0.76 times the 14-day average daily range.
The 14-day average true range of 101.4 points, applied either side of the 4,179.7 settle, frames Wednesday between 4,078.3 and 4,281.1. The published standard-deviation bands are built from five settlements: one deviation spans 4,103.2 to 4,256.2, two spans 4,071.5 to 4,287.9 and three spans 4,047.2 to 4,312.2. The Wednesday session reopened at 4,216.2, which already sits inside the upper half of the one-deviation band.
4.1 Dollar and Real Yields
The dollar index closed at 101.37, up 0.17 points, after a 101.61 high, and provider commentary described the close as a two-month high supported by rising Treasury yields. The ten-year yield index closed at 5.26 percent, up 2 basis points, after a 5.29 percent session high (provider record read at 06:46 PM ET) that provider commentary called a new 19-year high, and the thirty-year closed at 5.59 percent after a 5.62 percent high; the desk note said thirty-year yields reached their highest level since 2002. No real-yield series is available, so only nominal yields are cited. Gold rose against both, which in the review's interpretation reflects the offset from lower crude and softer data rather than a change in the rate backdrop.
4.2 Fed and Monetary Policy
In a 2:00 PM ET news-feed item the New York Fed president said one further rate increase is likely this year if the economy meets expectations, and in a 4:05 PM ET item he said rising bond yields show tighter financial conditions at the margin and that he does not believe they signal shifting longer-run inflation views. The desk note reported that the priced probability of an October increase fell to 45 percent from 70 percent after his remarks; provider commentary gave a figure of 52 percent. The two sources disagree, and neither figure is used as a level input. The next rate decision is listed for October 28, 2026 at 2:00 PM ET on the news-feed calendar, unconfirmed.
4.3 Geopolitical Backdrop
The United States and Iran negotiations remained unresolved in the reporting on hand. A press report on the news feed at 2:31 PM ET said mediators are pushing to break the deadlock; the Iranian president's office said at 3:24 PM ET that Iran will not compromise on nuclear rights; an energy-news item at 3:01 PM ET described Iranian threats against regional energy infrastructure; and the President said at 3:56 PM ET that Iran is doing very poorly. All of these items arrived after gold's 1:30 PM ET settle.
4.4 China and Structural Demand (Central Bank Buying, Reserve Data, Fund Flows)
No central-bank purchase figure and no Chinese import or premium data are available, so none is asserted. Chinese manufacturing survey data are listed at 9:30 PM ET on September 29, 2026, per the news-feed calendar and unconfirmed. The gold exchange-traded fund closed at 382.89, up 4.98 or 1.32 percent, per the provider's end-of-day record; no holdings figure is available.
4.5 Energy and Cross-Asset
Crude's November contract settled at 89.38, down 3.48 percent, and Brent's November contract at 102.59, down 2.56 percent, which provider commentary said eased inflation expectations. Silver's December contract settled at 61.153, down 0.92 percent. The S&P 500 cash index closed at 7,670.84, down 0.17 percent, and the Nasdaq-100 at 30,339.33, up 0.21 percent; the volatility index closed at 16.04. The job openings report showed 7.079 million openings against a 7.2275 million forecast and consumer confidence printed 81.9 against 89, per the news-feed calendar, and provider commentary described the confidence reading as a 12-year low.
4.6 Institutional Positioning (Futures Report, Fund Holdings, Speculator Length)
The positioning report as of September 22, 2026, unchanged since Monday's review, shows managed money long 135,699 contracts against short 8,310, a net long of 127,389, with long positions down 6,695 on the week. Swap dealers held 14,626 long against 250,752 short. The report predates the 196.7 point decline of the past five sessions, so the current speculative length is not known. The next report covers positions as of Tuesday, September 29.
On the provider's dated daily rows, the December contract traded 146,181 contracts on 09/29, whose open interest is not yet published, and 229,031 contracts on 09/28 with open interest of 324,659, up 2,159 from 322,500 on 09/25.
5. Bullion Fund Options Flow Context (Proxy)
The gold exchange-traded fund is used here qualitatively only. It tracks bullion with a fee drag and at a ratio that has no clean basis to the futures contract, so no level from it is translated into a futures price anywhere in this outlook.
The positioning console for the fund, dated as updated on 2026-09-29, showed a current price of 383.28 against a previous close of 377.91, a daily change of 1.42 percent, with share volume of 14,038,684, call gamma of minus 268 million dollars and put gamma of 171 million dollars, and next-expiry gamma at 2.31 percent of the total. The console's current price includes trade after the provider's 382.89 end-of-day close, and the conflict is recorded rather than resolved. The console's high-volatility-point and low-volatility-point fields are excluded as low-confidence per the known defect in that pair of fields.
The qualitative read: call gamma remains negative and put gamma positive, and next-expiry gamma fell to 2.31 percent of the total from 5.20 percent in the prior review, so in the review's interpretation the fund's near-dated options book carries less weight into Wednesday. No gamma-derived level is used for the futures contract, and nothing in the resistance and support lists originates from this proxy.
6. Forecast, session by session
Night Session (6:00 PM ET Tuesday to 3:00 AM ET Wednesday, Globex and Asia). The Wednesday session reopened at 4,216.2 at 6:00 PM ET, 36.5 points above the settle and at Pivot R1 at 4,216.8, after the post-settlement advance. Chinese manufacturing survey data and Australian consumer prices are listed at 9:30 PM ET, per the news-feed calendar and unconfirmed. The first test is whether the post-settlement gain holds above the 4,207.2 settle-window high. Bias neutral beneath the 4,244.1 to 4,256.2 band, expected Globex band roughly 4,190 to 4,245.
London Session (3:00 AM to 8:00 AM ET Wednesday). The European morning carries German unemployment at 3:55 AM ET and German consumer prices at 8:00 AM ET, forecast 3.1 percent year on year, both per the news-feed calendar and unconfirmed. Tuesday's advance built through this window, so a stall beneath Pivot R2 at 4,253.9 here would be the first sign that the post-settlement move is fading. Bias neutral, expected band roughly 4,185 to 4,255.
Morning Session (9:30 AM to 12:00 PM ET Wednesday, US Open). The calendar lists the personal income and outlays report at 8:30 AM ET, with the news-feed calendar listing a core year-on-year forecast of 3.3 percent against 3.3 percent. The private payroll survey precedes it at 8:15 AM ET, forecast 74,000, per the news-feed calendar and unconfirmed. A firm price-index print that lifts yields again would press the contract back toward the 4,181.0 Pivot Point and the 4,152.6 average stall; a soft print that eases yields keeps the 4,244.1 to 4,256.2 band in play. Expected band roughly 4,150 to 4,265.
Afternoon Session (12:00 PM to 4:00 PM ET Wednesday). Gold settles at 1:30 PM ET, and a regional Federal Reserve president is listed at 1:30 PM ET, per the news-feed calendar and unconfirmed. Wednesday is also the last session of the quarter, and the desk note flagged quarter-end pension rebalancing. The calendar lists a Federal Reserve governor at 3:25 PM ET. Expected band roughly 4,160 to 4,250.
Night Session Forward (6:00 PM ET Wednesday). Micron's quarterly results follow the equity close, and the calendar lists the call at 4:30 PM ET; further Federal Reserve speakers are listed at 5:10 PM ET and 6:00 PM ET, per the news-feed calendar and unconfirmed. The calendar lists the employment report at 8:30 AM ET on October 2, 2026.
Expected Range (Wednesday full session). Low-range scenario 4,180 to 4,245. Mid-range scenario, the most likely, 4,150 to 4,260. High-range scenario 4,100 to 4,290.
Most Likely Path. In the review's analyst judgment the most probable path holds the Globex session between the 4,194.6 stall and the 4,244.1 stochastic threshold, and the personal income and outlays report at 8:30 AM ET on September 30, 2026, which the calendar lists, decides the direction of the United States morning. A settle between 4,152.6 and 4,256.2 is weighted above a settle outside that band, because the composite read deepened to "80% SELL" and the directional system points down, while Tuesday held above Monday's low and the post-settlement advance reached Pivot R1. The alternative that would invalidate this reading is a soft price-index print with a sharp fall in yields, which would put the 4,287.9 to 4,312.2 band in play.
7. Wednesday Economic Calendar
The Wednesday session reopened at 6:00 PM ET Tuesday. Chinese manufacturing survey data and Australian consumer prices are listed at 9:30 PM ET, per the news-feed calendar and unconfirmed. The European morning lists United Kingdom output data at 2:00 AM ET, French consumer prices at 2:45 AM ET, German unemployment at 3:55 AM ET and German consumer prices at 8:00 AM ET, all per the news-feed calendar and unconfirmed.
The United States morning carries the private payroll survey at 8:15 AM ET, forecast 74,000 against 38,000, per the news-feed calendar and unconfirmed, then the personal income and outlays report and the third estimate of second-quarter output at 8:30 AM ET, both listed on the calendar; the news-feed calendar lists core price-index forecasts of 3.3 percent year on year and 0.3 percent month on month. The calendar lists the weekly petroleum status report at 10:30 AM ET. Gold settles at 1:30 PM ET, a regional Federal Reserve president is listed at 1:30 PM ET, per the news-feed calendar and unconfirmed, and the calendar lists a Federal Reserve governor at 3:25 PM ET. Micron's results follow the equity close, with the call listed at 4:30 PM ET.
The single first-order event for gold on Wednesday is the personal income and outlays report at 8:30 AM ET, through its effect on the ten-year yield and the dollar.
8. Primary Trade Setup
Direction: Short
Rationale: The composite snapshot deepened to "80% SELL" with Current Direction "Strengthening", the directional system points down and the settle sits beneath all six settlement averages, while Tuesday's post-settlement advance carried the contract to Pivot R1; a further rebound into the band between the stochastic 30 percent threshold at 4,244.1 and Pivot R2 at 4,253.9 offers a short with a defined risk point above Pivot R3. Gold rose against a firmer dollar and higher yields on Tuesday, so the setup is an analyst judgment against evident underlying demand.
Entry Zone: 4,240 to 4,250
Stop Loss: 4,292 (above Pivot R3 at 4,289.7 and two standard deviations resistance at 4,287.9)
Target 1: 4,198 (above the 4,194.6 stall level for the 14-day %k line)
Target 2: 4,151 (beneath the 40-day average stall at 4,152.6 and above Pivot S1 at 4,143.9)
Target 3 (extended): 4,104 (above one standard deviation support at 4,103.2 and beneath Pivot S2 at 4,108.1)
Risk-to-Reward: Approximately 1:1 to T1, 1:2 to T2, 1:3 to T3, measured from the 4,245 entry midpoint.
Invalidation: A settle above Pivot R3 at 4,289.7 negates the thesis. Short of that, the edge is removed by acceptance above one standard deviation resistance at 4,256.2, defined as two consecutive 30-minute closes above 4,256.2.
Macro override: A soft personal income and outlays print that drives the ten-year yield back beneath 5.2 percent and the dollar index lower would remove the rate pressure behind the sell reading. In that scenario the short is wrong immediately, and the 4,298.1 to 4,312.2 band becomes the reference within one 14-day average true range of 101.4 points.
Sources and methodology
This outlook is built from our session review of the December COMEX gold contract, GCZ26, the December '26 contract, prepared after Tuesday's close on September 29, 2026 for the Wednesday, September 30 session. The contract domain was checked before any level was used: the daily chart title read 4,213.6 with a stated change of plus 0.81 percent, which returns 4,179.7, equal to the provider's published previous close, and the chart's completed Tuesday bar equals the provider's settlement row, so chart and data sit on the same December contract. Because Globex reopened at 6:00 PM ET, the day high, day low and open on the provider's overview belong to the Wednesday session and are not presented anywhere here as Tuesday's range. Every catalyst whose release time had passed by 6:20 PM ET is recorded as completed.
Tuesday's extremes are the completed-session inputs behind the published pivot ladder, back-solved from its outer pairs, verified against all seven published rungs and reproduced by the chart's daily bar; the 30-minute series shows the 4,218.1 high printed after the settle. Every intraday ordering claim rests on the preserved 30-minute provider series, and Tuesday's short was scored only against the dated 09/29 row and that series. Volume and open interest are taken from the provider's dated daily rows: 146,181 contracts on the 09/29 row, whose open interest is not yet published; 229,031 contracts and 324,659 of open interest on 09/28, a row our Tuesday outlook carried as a preliminary 221,267 contracts with no open interest. The provider's revised Monday row shows a 4,315.8 high where the chart and Monday's reading showed 4,315.6, so Monday's range is cited as 172.7 points from the revised row. The settlement averages were computed from the 259 completed settlement rows, all oscillator readings are cited as published, and the composite read and its snapshot history are quoted verbatim. The 9-day %K and %D, the 20-day directional index, the 20-day average daily range, the 20-day historic volatility, the 14-3 day stochastic 50 percent threshold, the 13-week high and the 52-week low come from the same published pages. The bullion exchange-traded fund is used qualitatively only; no level in this outlook originates in it, and its two volatility-point fields are excluded. Scenario ranges and path weightings are analyst judgment. Items marked per the news-feed calendar and unconfirmed carry that qualification exactly as the review states it. A real-yield series, a four-hour series, central bank purchase data, Chinese import data, fund holdings and a prior-quarter high and low were not available, and no figure is stated for any of them.
Tuesday’s outlook for this contract is here, and Tuesday’s crude read is here. Outlooks for ES, NQ, GC and CL are collected on the market outlook page, and our forward trading record is on the performance statement.