At the Sunday 6:00 PM ET reopen the December Nasdaq-100 contract opened at 29,268.00, 150.25 points above Friday's settle and 12.00 points beneath the short band we published for Monday. The day then ran through nearly every line on that card. The band traded, the stop price traded, and the first two targets printed. The extended target did not. A daily bar cannot say in what order.
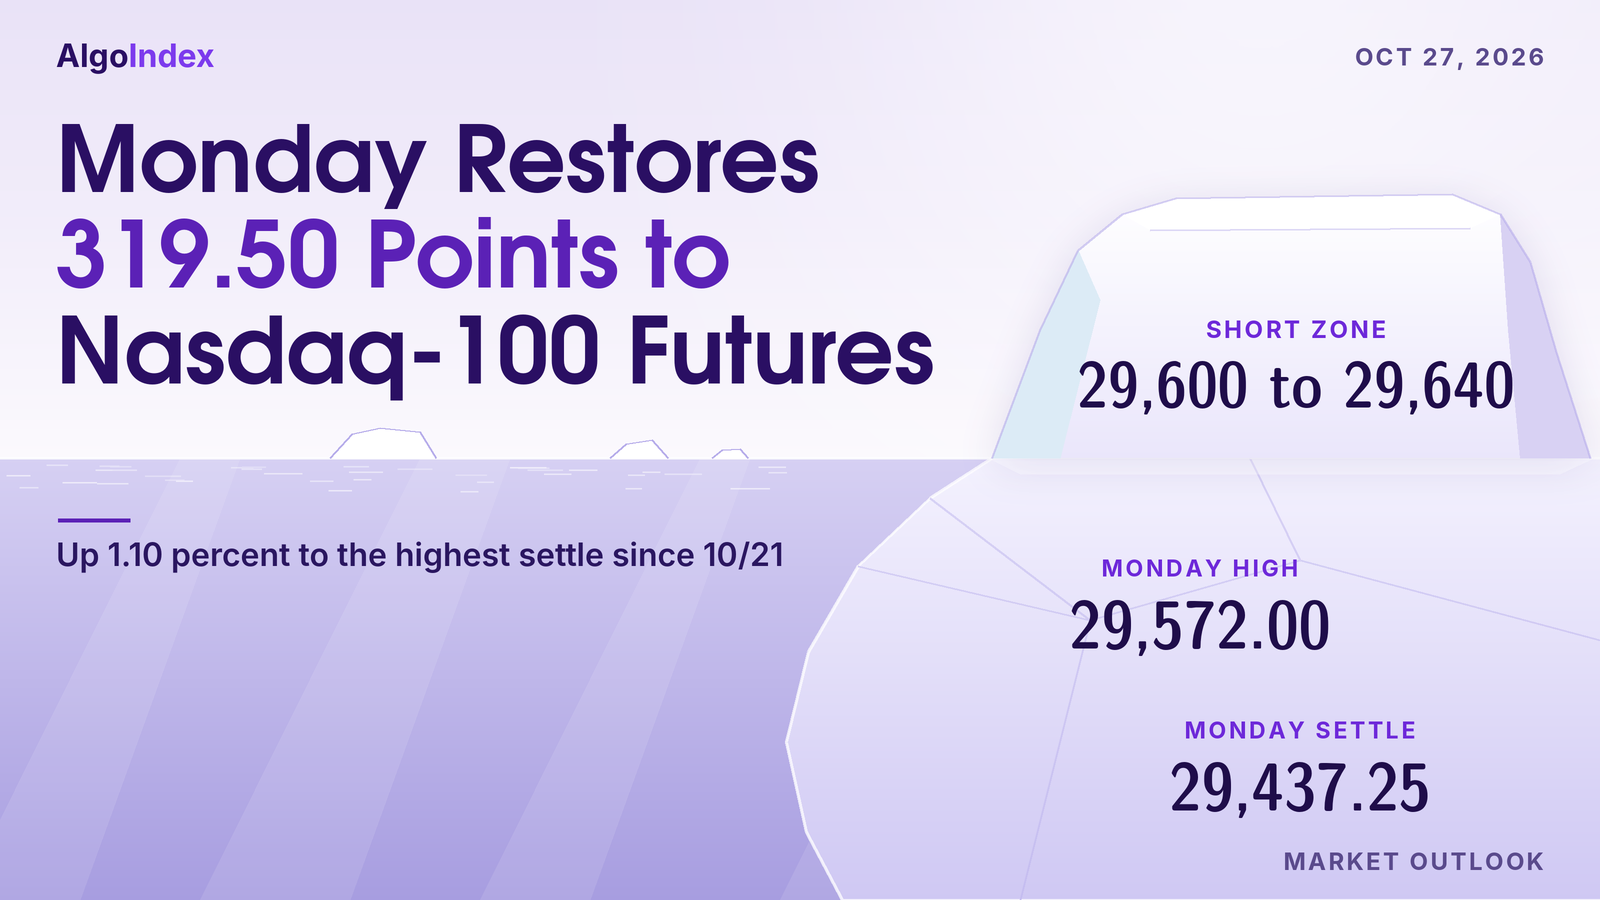
The contract settled at 29,437.25, up 319.50 points, or 1.10 percent, at 75.4 percent of a 547.75 point range. That was the largest one-day gain since the 331.75 of 10/21 and the highest settle since the 30,007.00 of 10/21. It ended a run of two lower settles. The Nasdaq-100 cash index rose 1.09 percent to 29,273.40, and the semiconductor index jumped 2.82 percent. Technology led.
December Nasdaq-100 futures settled at 29,437.25, up 319.50 points, with a higher high and a higher low on a 547.75 point range, the widest since 10/22. Monday's published short band at 29,280 to 29,320 traded, the 29,420 stop price traded, and the 29,180 and 29,060 targets printed, while the 28,940 extended target did not; the daily bar cannot show the order. The settle sits beneath the 5-day, 9-day, 20-day, 50-day and 100-day settlement averages and above the 200-day. The primary setup for Tuesday is a short from 29,600 to 29,640, beneath Pivot R1 at 29,664.75, stop 29,740, targets 29,500, 29,380 and an extended 29,260. The band and the first target sit above the settle; the second and third targets sit beneath it. The durable goods report is scheduled for 8:30 AM ET, as the calendar lists it, and the policy statement for 2:00 PM ET on Wednesday.
Monday's card traded from its band to its stop, with two targets printed
In Monday’s outlook we set a short from 29,280 to 29,320, stop 29,420. Its targets sat at 29,180, 29,060 and an extended 28,940. Monday's bar, from the review and the provider's 2026-10-26 settlement row, opened at 29,268.00 at the Sunday 6:00 PM ET reopen, marked a high of 29,572.00 and a low of 29,024.25, and settled at 29,437.25. The range spanned the whole band. The open sat 12.00 points beneath its bottom. The high cleared its top by 252.00.
The stop price traded too. The high stood 152.00 points above 29,420, and the settle finished 17.25 above it. On the other side, the low sat 155.75 points beneath the first target and 35.75 beneath the second, so both prices printed. The extended 28,940 did not print; the low stopped 84.25 points above it. No intraday series was preserved for Monday. So the daily bar cannot show whether the band, the stop or the targets traded first, and no order is asserted here. No fill and no result are asserted either.
The card's settle test held. Its invalidation needed a settle above Pivot R2 at 29,482.58, and the settle finished 45.33 points beneath it. Its acceptance test needed two consecutive 30-minute closes above 29,320. Without a 30-minute series that test cannot be read bar by bar. The settle itself sat 117.25 points above 29,320.
Its macro override named a broad recovery in technology shares, or a de-escalation in the Gulf that pulls crude and yields lower. Technology did climb. The Nasdaq-100 cash index rose 1.09 percent and the semiconductor index 2.82 percent. December WTI settled down 1.46 percent. The ten-year yield index closed at 4.99 percent against 4.98, so yields did not fall. Both of the override's references traded: the high cleared Pivot R2 at 29,482.58 by 89.42 points and the 29,483.22 flip equivalent by 88.78. The review ties no move to any single headline.
Our ranges are scored against the whole day's extremes, which is all the daily bar allows. One held. The high-range case of 28,580 to 29,660 contained the day, with 444.25 points to spare beneath the low and 88.00 above the high. The low-range case of 28,940 to 29,330 and the most likely case of 28,800 to 29,480 did not. The high cleared their tops by 242.00 and 92.00 points. Each session band topped out beneath the 29,572.00 high: the night's 29,330 by 242.00, London's 29,350 by 222.00, the morning's 29,480 by 92.00 and the afternoon's 29,510 by 62.00. The bar cannot place the high in any one session.
The most probable path, an analyst judgment, kept the contract between Pivot S2 at 28,804.58 and Pivot R2 at 29,482.58. It did not hold. The low stayed 219.67 points above S2, but the high cleared R2 by 89.42. The weighted case was a rebound toward the band that fails beneath Friday's 29,326.00 high, and the bar does not show it: the high traded 246.00 points above Friday's high and the settle 111.25 above it. The alternative named a technology recovery above the 29,483.22 flip equivalent toward one standard deviation resistance at 29,507.02. The high cleared 29,507.02 by 64.98 points. The settle finished 45.97 beneath the flip equivalent.
A 163.85 point basis, a crowded band from 29,572.00 to 29,664.75 and five averages overhead
The basis widened to 163.85 points, the 29,437.25 settle less the 29,273.40 cash close, from 160.22 on Friday. The review converts four positioning levels at it. The modeled volatility threshold at NDX 29,300 becomes 29,463.85, the modeled gamma-flip level at NDX 29,102 becomes 29,265.85, the call side ceiling at NDX 29,675 becomes 29,838.85 and the NDX 29,000 key strike 29,163.85. The conversions are the review's own. The settle sits 26.60 points beneath the threshold equivalent and 171.40 above the flip equivalent.
Resistance starts 26.60 points up, at the 29,463.85 threshold equivalent, with the 5-day average at 29,475.75 just 11.90 above it. The 50 percent retracement of the 13-week range follows at 29,549.25. Then the crowd. Monday's 29,572.00 high, the 9-day crossing price at 29,579.63 and the 29,583.21 stall level of the 14-day %K stochastic sit within 11.21 points. The 3-10-16 day MACD stall level at 29,622.61, the 9-day average at 29,646.75 and Pivot R1 at 29,664.75 sit within 42.14 points above them. Tuesday's short band takes in the first.
Higher up, one standard deviation resistance at 29,812.44 and the 29,838.85 ceiling equivalent sit 26.41 points apart. Pivot R2 follows at 29,892.25. The 100-day average at 29,961.25, two standard deviations resistance at 29,967.85, the one-ATR line at 29,976.71 and the 38.2 percent retracement from the four-week low at 29,991.47 sit within 30.22 points. Then come the 10/21 settle of 30,007.00, three standard deviations resistance at 30,087.09, the 50-day at 30,101.25, the 40-day crossing price at 30,194.81 and Pivot R3 at 30,212.50. The 18-day crossing price at 30,344.28 and the 20-day at 30,396.25 form the extended band. The 31,616.50 one-month, 13-week and 52-week high from 10/06 caps the list, 2,179.25 points up.
Support starts 92.75 points down, at the Pivot Point at 29,344.50. Monday's 29,268.00 open, the 29,265.85 flip equivalent and Tuesday's 29,260 extended target sit within 8.00 points, with the published target price at 29,235.70 beneath. Next comes the 29,163.85 key-strike equivalent. The 3-10 day crossover stall level at 29,134.46, Friday's 29,117.75 settle and Pivot S1 at 29,117.00 follow, the last of them 46.85 points beneath it. One standard deviation support at 29,062.06 and the 38.2 percent retracement from the 13-week low at 29,061.38 sit 0.68 apart, with Monday's 29,024.25 low beneath. Friday's 28,987.00 low remains the one-month low.
Lower still, two standard deviations support at 28,906.65 and the one-ATR line at 28,897.79 sit 8.86 points apart. Pivot S2 at 28,796.75 and three standard deviations support at 28,787.41 sit 9.34 apart, and Pivot S3 at 28,569.25 follows. The 200-day average at 28,392.75 and the 27,482.00 13-week low from 07/29 lie far below.
Five averages sit overhead. The settle sits 38.50 points beneath the 5-day at 29,475.75, 209.50 beneath the 9-day at 29,646.75, 524.00 beneath the 100-day at 29,961.25, 664.00 beneath the 50-day at 30,101.25 and 959.00 beneath the 20-day at 30,396.25. It sits 1,044.50 above the 200-day at 28,392.75. The review computed the averages from 259 completed daily settlements, with the partial Tuesday row dropped, and rounded each once to the 0.25 tick. The 5-day fell 57.00 points at the tick, 57.05 before rounding, from Friday's 29,533.00 as the 10/19 settle of 29,722.50 left the window. The 20-day fell 56.50 as the 09/28 settle of 30,566.25 dropped out, and the 50-day 20.00. Older settlements sit lower. The 30 older ones in the 50-day window averaged 29,904.50, the 50 older ones in the 100-day window 29,821.00 and the 100 older ones in the 200-day window 26,824.50. Tuesday's crossing prices are 29,579.63 for the 9-day, 30,344.28 for the 18-day and 30,194.81 for the 40-day.
Momentum stays low. Relative strength reads 38.41 on the 9-day, 40.83 on the 14-day and 43.46 on the 20-day. The raw stochastics read 23.64 percent on the 9-day and 17.77 percent on the 14-day, and the 14-day %K at 8.99 percent sits 4.84 points beneath %D at 13.83 percent. Sellers still lead both windows. On the 9-day, negative direction at 29.94 tops positive at 12.64 by 17.30, with the ADX at 40.89; on the 14-day, 28.53 tops 14.17 by 14.36, with the ADX at 26.39. Historic volatility reads 23.55 percent and 19.76 percent. These readings are as published, read at about 6:23 PM ET on Monday after the 6:00 PM ET reopen. They may already blend in the reopened session's quote.
A composite multi-indicator read published for Tuesday sits at 32 percent sell, with strength described as weak and direction as weakest, against 56 percent sell in the prior session's snapshot. A week ago it read 40 percent sell. A month ago, 88 percent buy. The short-horizon group averages 40 percent sell, the medium 25 percent sell and the long a hold, and the trend indicator reads sell.
This bar had a body. The settle finished 169.25 points above the 29,268.00 open, with an upper shadow of 134.75 points above the settle and a lower shadow of 243.75 points beneath the open. Monday's high topped Friday's by 246.00 points and its low by 37.25. The 547.75 point range was 0.96 times the 14-day average daily range of 569.36 and the widest since the 960.25 of 10/22. The 14-day average true range stands at 539.46 points; the 9-day figures are 562.18 and 649.53 and the 20-day figures 527.32 and 529.17, all read after the reopen with the same caveat as the oscillators.
One average true range either side of the settle spans 28,897.79 to 29,976.71. The deviation bands, built from five settlements and centred on the settle, run 29,062.06 to 29,812.44, 28,906.65 to 29,967.85 and 28,787.41 to 30,087.09. They describe settlement dispersion only. Ten sessions of daily ranges read 314.75, 813.50, 574.25, 956.25, 757.50, 511.75, 385.50, 960.25, 339.00 and 547.75 points, and the settlement changes over those sessions net to minus 1,461.00. No four-hour series was captured, so the swing read rests on daily bars.
A 2.82 percent chip rally, a 1.09 percent Nasdaq-100 gain and a week of results
Chips carried the day. The Nasdaq-100 cash index closed at 29,273.40, up 315.87 points or 1.09 percent. The semiconductor index rose 304.01 points, or 2.82 percent, to 11,083.47, after trading between 11,182.46 and 10,823.85. The broad market lagged. The S&P 500 cash index rose 0.70 percent, the Dow industrials 0.28 percent and the NYSE composite 0.29 percent, so the Nasdaq-100 outperformed the broad market. The evening positioning note cited semiconductor shares as the leaders of Monday's advance. It also noted the social-media group's shares declining after the reported stock offering.
At 9:03 AM ET the news feed carried a leading artificial-intelligence developer's application to list class A common stock on the Nasdaq. Its first-half figures followed from 9:05 AM ET to 9:06 AM ET, as the news feed carried them. Revenue read 16.3 billion dollars and the net loss 80.7 billion dollars, per the news feed. At 9:21 AM ET a press report carried by the news feed said it targets the week of November 16 for the offering. Another stock sale was reported. A press report carried before the open said the social-media group is seeking to raise as much as 95 billion dollars from stock sales to fund AI expansion.
Late in the day the news feed carried more. From 4:22 PM ET to 4:24 PM ET it carried a 63 billion dollar AI financing arranged by a group of banks and an asset manager with a chipmaker. It also carried the chipmaker's agreement to supply AI accelerators, via a special-purpose vehicle, for lease to that developer. The provider's commentary linked the gain to lower crude after no US or Israeli strike on Iran over the weekend. That link is the commentary's. These items coincided with the session, and with no intraday series preserved, no move is attributed to any one of them.
Results crowd the week. A payments network reports after the close on Tuesday, October 27, as the calendar lists it. A search-engine group and a software maker report after the close on Wednesday, October 28, and an online retailer after the close on Thursday, October 29, as the calendar lists them. The evening positioning note published after the close described traders as cautious about adding new risk ahead of the Fed decision and results from three of the largest technology companies.
Yields barely moved. The ten-year yield index closed at 4.99 percent against 4.98 and the thirty-year at 5.30 percent against 5.31. The Chicago Fed national activity index printed 0.07 at 8:30 AM ET and the Dallas Fed manufacturing index 13.40 at 10:31 AM ET, per the news-feed calendar and unconfirmed. The US two-year note auction stopped at a 4.708 percent high yield with a 2.590 bid-to-cover, per the news-feed calendar and unconfirmed. The policy meeting begins on Tuesday, October 27, as the calendar lists it. Its statement is scheduled for 2:00 PM ET on Wednesday, October 28, as the calendar lists it.
Talks ran in Tehran. At 9:10 AM ET the news feed carried the start of a meeting there between Iran and senior Saudi, Pakistani and Turkish officials. At 11:47 AM ET it carried an agreement to continue those talks. At 3:36 PM ET it carried Iranian state television saying Iran is open to a shorter US proposal timeline if conditions are met. Trade headlines ran too. At 3:27 PM ET a press report said the US and Canada are working on a deal to ease tariffs on Canadian steel and autos. From 4:34 PM ET to 4:40 PM ET the news feed carried remarks by Canada's prime minister rejecting the US trade terms offered in August. These are statements carried by the news feed rather than confirmed events. No causal link to the index is asserted.
Crude fell. December WTI settled at 101.76, down 1.46 percent, and the dollar index closed at 101.96 against 101.81. December gold settled at 4,038.4, up 0.76 percent. The Nasdaq-100 volatility index eased to 26.40 from 28.30, the S&P 500 volatility index to 18.39 from 19.45 and the volatility-of-volatility index to 101.43 from 109.70. The evening positioning note reported fixed-strike implied volatility on the S&P 500 up about one volatility point for this week's expirations, with the October 29 and October 30 expirations at 16.1 and 16.5 percent.
The cash close sits between two positioning lines. The evening positioning note used is the 5:51 PM ET edition for Monday, read at 6:17 PM ET. Its reference prices are the prior session's closes: NDX 28,957 corresponds to Friday's 28,957.53 cash close, and QQQ 704 to the fund's Friday close of 704.39. Against Monday's 29,273.40 close, the index sits 26.60 points beneath the 29,300 modeled volatility threshold and 171.40 above the 29,102 modeled gamma-flip level. The 29,675 call side ceiling sits 401.60 points higher. It sits 273.40 above the largest gamma concentration at 29,000 and 1,273.40 above the put side support base at 28,000. The index model's gamma tilt reads 0.839 and its gamma notional minus 4.341 million dollars, both model outputs. The note lists 29,000, 28,000, 29,675 and 30,000 as key index strikes.
On the QQQ proxy the call side ceiling sits at 760, the modeled gamma-flip level at 730, the modeled volatility threshold at 725, and the largest gamma concentration and the put side support base both at 700. Those are proxy levels. The fund's gamma tilt reads 0.526 and its gamma notional minus 1.073 billion dollars, proxy model outputs. The note's key fund strikes are 700, 690, 720 and 710. The console, read at about 6:18 PM ET with a page date of 2026-10-26, shows call gamma of minus 1.27 billion against put gamma of minus 2.41 billion. One-month implied volatility reads 24.62 percent against realised volatility of 17.74 percent. The implied-volatility rank reads 66.60 percent, the skew rank 31.20 percent and the put-to-call open-interest ratio 1.41.
In the review's interpretation, drawn from the index model and the QQQ fund proxy, an index close above the flip level but beneath the threshold, with negative gamma notional on the index and the fund, describes an environment where dealer hedging can still amplify moves. That is a damping read. It carries no direction. In the same interpretation, a fund implied volatility well above realised shows the options market pricing more movement than the index has recently delivered ahead of the week's results. The modeled threshold and flip level are model outputs, not option strikes, and no directional read is drawn from options volume or modeled gamma.
Activity eased. Volume reached 671,673 contracts against Friday's 677,678, a figure revised from the 672,105 carried in Monday's outlook. Open interest reads 285,953 on Friday's 2026-10-23 row, which Monday's outlook listed as not yet reported, down 3,000 from 288,953 on the 2026-10-22 row. Monday's figure is not yet reported. The weekly positioning report dated October 20 puts leveraged-fund longs at 51,749 contracts and shorts at 50,799. That is a net long of 950 against a net short of 11,593 a week earlier. Asset-manager longs stand at 109,985 and shorts at 32,195. The report predates the 10/22 decline and Monday's gain.
The trade map for Tuesday
The primary setup is a short from 29,600 to 29,640. The settle sits beneath every settlement average from the 5-day to the 100-day. Negative direction leads on both directional systems, and the composite reads 32 percent sell. The cash index closed beneath the modeled volatility threshold with negative gamma notional, a model output. The band sits 28.00 points above Monday's 29,572.00 high and 20.37 above the 9-day crossing price at 29,579.63. It holds the 29,622.61 MACD stall level. Its top sits 24.75 beneath Pivot R1 at 29,664.75. Then the stop. At 29,740 it sits 75.25 points above R1 and 72.44 beneath one standard deviation resistance at 29,812.44. All of the band sits above the settle, 162.75 to 202.75 points up. The thesis, an analyst judgment, is that rallies are sold beneath Pivot R1 ahead of Wednesday's results.
The first target sits at 29,500, 36.15 above the 29,463.85 threshold equivalent and 62.75 above the settle. The second, 29,380, sits 35.50 above the Pivot Point and 57.25 beneath the settle. Then the extended third. At 29,260 it sits 5.85 beneath the 29,265.85 flip equivalent and 24.30 above the 29,235.70 target price. Monday printed a higher high and a higher low, and the cash close sits above the flip level, which leaves room for a further advance. So the review calls the setup an analyst judgment with no measured edge behind it.
Now the arithmetic. From the 29,620 midpoint the risk to the stop is 120 points, 22.2 percent of the 14-day average true range of 539.46. The targets sit 120, 240 and 360 points beneath the midpoint. Exact multiples. The first target, 29,500, sits 100.00 points beneath the band bottom and 62.75 above the settle. The second sits 57.25 beneath the settle. The third sits 177.25 beneath it.
The scenario ranges are analyst judgment. The low-range case runs 29,250 to 29,660, the most likely 29,060 to 29,810 and the high-range case 28,900 to 29,970. Then the sessions. Globex reopened at 6:00 PM ET on Monday above the settle, and the review expects roughly 29,300 to 29,620 through the night, with a neutral bias beneath Pivot R1. London follows at 29,250 to 29,660, bias neutral. There the Pivot Point is the first support beneath the settle. Pivot R1 is the first pivot resistance above it, with the 29,463.85 threshold equivalent, Monday's 29,572.00 high and six other references between them, and R1 sits 4.75 points above London's top. The morning band runs 29,120 to 29,810. Pivot S1 sits 3.00 points beneath its bottom and one standard deviation resistance 2.44 above its top. The afternoon band runs 29,060 to 29,890. One standard deviation support sits 2.06 points inside its bottom and Pivot R2 2.25 above its top.
Tuesday's calendar is fuller. Australian consumer prices are listed at 8:30 PM ET and the New Zealand rate decision at 9:00 PM ET on Monday, per the news-feed calendar and unconfirmed. French consumer confidence is listed at 3:45 AM ET and eurozone money supply at 5:00 AM ET, per the news-feed calendar and unconfirmed. The advance durable goods report is scheduled for 8:30 AM ET, as the calendar lists it. Its news-feed consensus reads 1.9 percent against minus 0.1 percent previously, per the news-feed calendar and unconfirmed. Then the open. The cash session opens at 9:30 AM ET, and new home sales are scheduled for 10:00 AM ET, as the calendar lists it. The consumer confidence survey is listed at 10:00 AM ET and the five-year note auction at 1:00 PM ET, per the news-feed calendar and unconfirmed. The cash close follows at 4:00 PM ET. Globex halts at 5:00 PM ET and reopens at 6:00 PM ET. Thursday brings the advance estimate of third-quarter GDP and the September personal income and outlays report at 8:30 AM ET, as the calendar lists them.
One path is weighted. In the review's analyst judgment the most probable path holds the contract between Pivot S1 at 29,117.00 and Pivot R2 at 29,892.25. Within it, a rebound toward the 29,600 to 29,640 band that stalls beneath Pivot R1 at 29,664.75 is weighted slightly above an extension. No measured frequency backs it. The alternative is continued technology leadership ahead of Wednesday's results. That could carry the contract above R1 toward one standard deviation resistance at 29,812.44 and Pivot R2. Monday's higher high and higher low, the cash close above the flip level and the weakest direction reading behind the composite's sell keep a further advance a live alternative. In the review's judgment the first-order scheduled item on Tuesday is the 8:30 AM ET durable goods report. In the same judgment, the week's first-order events are the policy statement and the search-engine group's and software maker's results on Wednesday, as the calendar lists them.
Monday's 29,572.00 high, the top of the widest range since 10/22, now sits 28.00 points beneath Tuesday's short band.
The complete data picture
Every number behind Tuesday’s plan, charted first, then the full level lists, then the complete numeric reference underneath.
Full numeric reference, every remaining figure from the session review
1. Executive Summary
The December Nasdaq-100 contract settled at 29,437.25 on Monday, up 319.50 or 1.10 percent from Friday's settle of 29,117.75, after trading between 29,572.00 and 29,024.25, a 547.75 point daily range. The settle finished at 75.4 percent of the range, and the 547.75 point range was 0.96 times the published 14-day average daily range of 569.36 points. Monday printed a higher high and a higher low against Friday, the 319.50 point gain was the largest one-day gain since the 331.75 point gain of 10/21, and the settle was the highest since the 30,007.00 settle of 10/21. The gain ended a run of two consecutive lower settles.
The Nasdaq-100 cash index closed at 29,273.40, up 315.87 or 1.09 percent, and the semiconductor index rose 2.82 percent to 11,083.47. The broad S&P 500 cash index rose 0.70 percent and the Dow industrials 0.28 percent, so technology led the advance. The news feed carried at 9:03 AM ET a leading artificial-intelligence developer's filing for an initial public offering of class A shares on the Nasdaq, and later items on AI financing and supply agreements involving a chipmaker; the provider's commentary also linked the gain to lower crude after no US or Israeli strike on Iran over the weekend. These items coincided with the session; no intraday series was preserved for any path claim, so no move is attributed to any one of them.
The cash index closed 26.60 points beneath the modeled volatility threshold at NDX 29,300 and 171.40 points above the modeled gamma-flip level at NDX 29,102 in the evening positioning note, with negative gamma notional, a model output, on both the index and the fund. The composite multi-indicator read is "32% SELL", with strength "Weak" and direction "Weakest", and the settle sits beneath every settlement average from the 5-day to the 100-day.
The ten-year yield index closed at 4.99 percent and the Nasdaq-100 volatility index fell to 26.40 from 28.30. The published 14-day average true range is 539.46 points. The Primary Setup below is a short from the 29,600 to 29,640 band beneath Pivot R1 at 29,664.75, stopped at 29,740, with objectives at 29,500, 29,380 and an extended 29,260.
2. Price Action & Technical Structure
2.1 Intraday and Session Review
The Monday session opened at 29,268.00 at the Sunday 6:00 PM ET reopen, 150.25 points above Friday's settle, marked a daily high of 29,572.00 and a daily low of 29,024.25, and settled at 29,437.25. This review makes no claim about the order in which the high and the low printed; the daily bar fixes the open, the extremes and the settle, and that is the evidence used here.
The settle sits 413.00 points above the low and 134.75 points beneath the high, in the upper part of the session's range.
Globex reopened at 6:00 PM ET, so the open, high and low shown on the provider's overview page, 29,480.50, 29,501.25 and 29,471.00, belong to the new Tuesday session and not to Monday's completed session. The provider's previous close of 29,437.25 is Monday's settle.
Monday's completed-session extremes are the completed-session inputs behind the published pivot ladder rather than an independently read bar. Pivot R3 at 30,212.50 minus Pivot S3 at 28,569.25, divided by three, returns 547.75, and Pivot R2 at 29,892.25 minus Pivot S2 at 28,796.75, divided by two, returns the same 547.75. Three times the Pivot Point of 29,344.50 less the 29,437.25 settle gives a high plus low sum of 58,596.25, which the pair of 29,572.00 and 29,024.25 reproduces exactly, and that pair reproduces all seven published rungs.
The provider's settlement row and the chart's completed daily bar carry the same 29,268.00 open, 29,572.00 high, 29,024.25 low and 29,437.25 settle.
2.2 Daily Structure
Monday's 29,572.00 high sits 246.00 points above Friday's 29,326.00, and the 29,024.25 low sits 37.25 points above Friday's 28,987.00, so the session printed a higher high and a higher low. The settle above the 29,268.00 open leaves a body of 169.25 points, an upper shadow of 134.75 points above the settle and a lower shadow of 243.75 points beneath the open.
Settlements over the last ten sessions ran 30,791.50, 30,182.75, 30,143.75, 29,391.50, 29,722.50, 29,675.25, 30,007.00, 29,142.00 and 29,117.75 before Monday's 29,437.25. Friday's 28,987.00 low remains the provider's published one-month low, the one-month, 13-week and 52-week high is 31,616.50 from 10/06, and the 13-week low is 27,482.00 from 07/29.
2.3 4-Hour and Swing Structure
Daily ranges for the last ten sessions ran 314.75, 813.50, 574.25, 956.25, 757.50, 511.75, 385.50, 960.25, 339.00 and 547.75, so Monday's range was the widest since the 960.25 range of 10/22. The settlement changes over the same ten sessions read minus 106.75, minus 608.75, minus 39.00, minus 752.25, plus 331.00, minus 47.25, plus 331.75, minus 865.00, minus 24.25 and plus 319.50.
The retracement grid published for Tuesday places the 50 percent retracement of the 13-week range at 29,549.25, 112.00 points above the settle, and the 38.2 percent retracement from the four-week low at 29,991.47. Beneath, the 38.2 percent retracement from the 13-week low sits at 29,061.38. No four-hour series was captured, so swing structure here rests on daily bars only.
2.4 Moving Averages
The averages cited in this subsection were computed from the provider's daily settlement series for the December contract, which holds 259 completed sessions through Monday; the partial Tuesday row of the reopened Globex session was dropped before counting, and each figure was rounded once to the 0.25 tick. The 5-day average stands at 29,475.75, the 9-day at 29,646.75, the 20-day at 30,396.25, the 50-day at 30,101.25, the 100-day at 29,961.25 and the 200-day at 28,392.75.
The 29,437.25 settle sits 38.50 points beneath the 5-day average, 209.50 points beneath the 9-day, 959.00 points beneath the 20-day, 664.00 points beneath the 50-day and 524.00 points beneath the 100-day, and 1,044.50 points above the 200-day. The 5-day average fell 57.00 points at the tick, 57.05 before rounding, from Friday's 29,533.00, because the 10/19 settle of 29,722.50 left the window and was replaced by 29,437.25. The 20-day fell 56.50 points, because the 09/28 settle of 30,566.25 left that window, and the 50-day fell 20.00 points.
The 20-day average sits above the 50-day because the 30 older settlements in the 50-day window averaged lower, at 29,904.50, than the last 20. The 50-day sits above the 100-day because the 50 older settlements in the 100-day window averaged lower, at 29,821.00, and the 100-day sits above the 200-day because the 100 older settlements in the 200-day window averaged lower, at 26,824.50. The projection grid gives the prices at which each average would be crossed on Tuesday: 29,579.63 for the 9-day, 30,344.28 for the 18-day and 30,194.81 for the 40-day.
2.5 Oscillator and Trend Readings
The oscillator figures below are as published on the provider's technical page, read at about 6:23 PM ET on Monday after the 6:00 PM ET reopen, so the provider may already be blending the reopened session's quote into them; they are the provider's published readings and were not computed here. The 9-day relative strength reads 38.41, the 14-day relative strength 40.83 and the 20-day relative strength 43.46.
The 9-day raw stochastic reads 23.64 percent and the 14-day raw stochastic 17.77 percent, while the 14-day stochastic %K reads 8.99 percent and the 14-day stochastic %D 13.83 percent, so %K sits beneath %D in the lower part of the range.
The 9-day directional index ADX reads 40.89 with the 9-day +DI at 12.64 and the 9-day -DI at 29.94; the 14-day directional index ADX reads 26.39 with the 14-day +DI at 14.17 and the 14-day -DI at 28.53, so negative direction leads on both. The 9-day historic volatility reads 23.55 percent and the 14-day historic volatility 19.76 percent.
The composite multi-indicator read published for the Tuesday session is "32% SELL", with strength "Weak" and direction "Weakest", and the composite trend indicator reads sell. The short-term group reads "Average: 40% SELL", the medium-term group "Average: 25% SELL" and the long-term group "Average: HOLD". The snapshot comparisons read "56% SELL" for yesterday, "40% SELL" for last week and "88% BUY" for last month.
2.6 Volatility and Expected Range
The published 14-day average true range stands at 539.46 points and the 14-day average daily range at 569.36 points; the 9-day average true range is 562.18 with a 9-day average daily range of 649.53, and the 20-day average true range is 527.32 with a 20-day average daily range of 529.17. These were read after the reopen and carry the same caveat as the oscillators. Monday's 547.75 point range was 0.96 times the 14-day average daily range.
Adding and subtracting the 14-day average true range of 539.46 points from the 29,437.25 settle frames Tuesday between 28,897.79 and 29,976.71. The published standard-deviation bands are built from five settlements and centre on the settle: one deviation spans 29,062.06 to 29,812.44, two spans 28,906.65 to 29,967.85 and three spans 28,787.41 to 30,087.09. These bands describe settlement dispersion, not intraday reach.
3. Key Levels
3.1 Resistance
Above the 29,437.25 settle, the first overhead reference is the 29,463.85 conversion of the modeled volatility threshold at the measured basis, followed by the 5-day average at 29,475.75, the 50 percent retracement of the 13-week range at 29,549.25, Monday's 29,572.00 high, the 9-day average crossing price at 29,579.63, the 29,583.21 stall level of the 14-day %K stochastic, and the 3-10-16 day MACD stall level at 29,622.61, with the 9-day average at 29,646.75 above it. Pivot R1 at 29,664.75 precedes one standard deviation resistance at 29,812.44, the 29,838.85 conversion of the call side ceiling and Pivot R2 at 29,892.25. Two standard deviations resistance at 29,967.85, the 38.2 percent retracement from the four-week low at 29,991.47 and Pivot R3 at 30,212.50 are the extended references.
3.2 Support
Beneath the settle sits the Pivot Point at 29,344.50, then the 29,265.85 conversion of the modeled gamma-flip level and the published target price at 29,235.70. The 29,163.85 conversion of the NDX 29,000 key strike, the 3-10 day crossover stall level at 29,134.46 and Pivot S1 at 29,117.00 form the next band, with one standard deviation support at 29,062.06, the 38.2 percent retracement from the 13-week low at 29,061.38 and Monday's 29,024.25 low beneath. Friday's 28,987.00 low, two standard deviations support at 28,906.65, Pivot S2 at 28,796.75 and Pivot S3 at 28,569.25 are the extended references.
4. Macro Drivers
4.1 Largest-Company Results and the AI Spending Cycle
The news feed carried at 9:03 AM ET a leading artificial-intelligence developer's application to list class A common stock on the Nasdaq, with first-half revenue of 16.3 billion dollars and a first-half net loss of 80.7 billion dollars carried at 9:05 AM ET to 9:06 AM ET, and a press report at 9:21 AM ET that it targets the week of November 16 for the offering. A press report carried before the open said the social-media group is seeking to raise as much as 95 billion dollars from stock sales to fund AI expansion. The news feed carried at 4:22 PM ET to 4:24 PM ET a 63 billion dollar AI financing arranged by a group of banks and an asset manager with a chipmaker, and that chipmaker's agreement to supply AI accelerators through a special-purpose vehicle for lease to the same developer.
Results from a payments network are scheduled after the close on Tuesday, October 27, 2026, as the calendar lists it. Results from a search-engine group and a software maker are scheduled after the close on Wednesday, October 28, 2026, as the calendar lists them. Results from an online retailer are scheduled after the close on Thursday, October 29, 2026, as the calendar lists it. The evening positioning note published after the close described traders as cautious about adding new risk ahead of the Fed decision and results from three of the largest technology companies.
4.2 Semiconductor Cycle and Tech Sector Rotation
The semiconductor index closed at 11,083.47, up 304.01 or 2.82 percent, after trading between 11,182.46 and 10,823.85. The evening positioning note cited semiconductor shares as the leaders of Monday's advance and noted the social-media group's shares declining after the reported stock offering. The Nasdaq-100 cash index's 1.09 percent gain outpaced the S&P 500 cash index's 0.70 percent and the Dow industrials' 0.28 percent.
4.3 Fed Policy and Real Yields (Duration Sensitivity)
The ten-year yield index closed at 4.99 percent against 4.98 percent and the thirty-year at 5.30 percent against 5.31 percent. The Chicago Fed national activity index printed 0.07 at 8:30 AM ET and the Dallas Fed manufacturing index printed 13.40 at 10:31 AM ET, and the US two-year note auction stopped at a 4.708 percent high yield, all per the news-feed calendar and unconfirmed. The FOMC meeting begins on Tuesday, October 27, 2026, as the calendar lists it, and the FOMC statement is scheduled for 2:00 PM ET on Wednesday, October 28, 2026, as the calendar lists it.
4.4 Geopolitical Backdrop
The news feed carried at 9:10 AM ET the start of a meeting in Tehran between Iran and senior Saudi, Pakistani and Turkish officials, at 11:47 AM ET the agreement to continue those talks, and at 3:36 PM ET Iranian state television saying Iran is open to a shorter US proposal timeline if conditions are met. The news feed also carried at 4:34 PM ET to 4:40 PM ET remarks by Canada's prime minister rejecting the US trade terms offered in August, after a 3:27 PM ET press report that the two countries are working on a deal to ease tariffs on Canadian steel and autos. These are statements carried by the news feed rather than confirmed events.
4.5 Cross-Asset and Volatility
December WTI settled at 101.76, down 1.46 percent, and the dollar index closed at 101.96 against 101.81. The Nasdaq-100 volatility index closed at 26.40 against 28.30 on Friday, the S&P 500 volatility index at 18.39 against 19.45 and the volatility-of-volatility index at 101.43 against 109.70. The evening positioning note reported fixed-strike implied volatility on the S&P 500 up about one volatility point for this week's expirations, with the October 29 and October 30 expirations at 16.1 and 16.5 percent.
December gold settled at 4,038.4, up 0.76 percent. The NYSE composite rose 0.29 percent, so the Nasdaq-100 cash index outperformed the broad market on Monday.
4.6 Institutional Positioning
The weekly positioning report dated October 20, shown on the provider's overview, puts leveraged-fund long positions at 51,749 contracts and leveraged-fund short positions at 50,799, for a net long of 950 against a net short of 11,593 a week earlier. Asset-manager long positions stand at 109,985 and asset-manager short positions at 32,195. The report predates the 10/22 decline and Monday's gain.
Open interest on the December contract is shown at 285,953 for Friday, on the 2026-10-23 row of the provider's record, a figure Monday's outlook listed as not yet reported, and Monday's open interest is not yet reported; Monday's December volume was 671,673 contracts against 677,678 on Friday, the 2026-10-23 row, revised from the 672,105 carried in Monday's outlook.
5. QQQ Options Flow Context (Proxy)
This review uses the QQQ fund and the evening positioning note's index columns as the proxy for the positioning data available. The positioning note is the 5:51 PM ET edition for Monday, read at 6:17 PM ET. Its reference prices are the prior session's closes: NDX 28,957 corresponds to Friday's 28,957.53 cash close and QQQ 704 matches the fund's Friday close of 704.39 shown on the console.
On the index the modeled volatility threshold sits at NDX 29,300, the call side ceiling at NDX 29,675, the modeled gamma-flip level at NDX 29,102, the largest gamma concentration at NDX 29,000 and the put side support base at NDX 28,000. Against Monday's 29,273.40 cash close, the close sits 26.60 points beneath the threshold, 401.60 points beneath the call side ceiling, 171.40 points above the flip level, 273.40 points above the largest gamma concentration and 1,273.40 points above the put side base. Index gamma tilt reads 0.839 and gamma notional minus 4.341 million dollars, both model outputs, and the key index strikes are NDX 29,000, 28,000, 29,675 and 30,000.
On the fund the modeled volatility threshold sits at 725, the call side ceiling at 760, the modeled gamma-flip level at 730, and the largest gamma concentration and the put side support base both at 700. Fund gamma tilt reads 0.526 and gamma notional minus 1.073 billion dollars, proxy model outputs, and the key fund strikes are 700, 690, 720 and 710. The modeled threshold and flip level are model outputs, not option strikes.
At the measured 163.85 point basis, the December settle of 29,437.25 less the 29,273.40 cash close, this review converts the index threshold to 29,463.85, the flip level to 29,265.85, the call side ceiling to 29,838.85 and the 29,000 strike to 29,163.85 in December futures terms. These conversions are this review's, not the positioning note's.
The QQQ console, read at about 6:18 PM ET with a page date of 2026-10-26, shows call gamma of minus 1.27 billion against put gamma of minus 2.41 billion, one-month implied volatility of 24.62 percent against realised volatility of 17.74 percent, an implied-volatility rank of 66.60 percent, a skew rank of 31.20 percent and a put-to-call open-interest ratio of 1.41. The console's live price field and its high and low volatility point fields are excluded.
In this review's interpretation, drawn from the index model and the QQQ fund proxy, both model outputs, an index close above the flip level but beneath the threshold, with negative gamma notional on the index and the fund, describes an environment where dealer hedging can still amplify moves, a damping read with no direction, and a fund implied volatility well above realised shows the options market pricing more movement than the index has recently delivered ahead of the week's results. The setup in section 8 sells the 29,600 to 29,640 band, above the 29,463.85 conversion of the threshold and beneath Pivot R1 at 29,664.75, with the 29,260 extended objective just beneath the 29,265.85 conversion of the flip level.
6. Forecast
6.1 Night Session (6:00 PM ET Monday to 3:00 AM ET Tuesday, Globex and Asia)
Globex reopened at 6:00 PM ET on Monday, October 26, 2026 above the settle. Australian consumer prices are listed at 8:30 PM ET and the New Zealand rate decision at 9:00 PM ET on Monday, October 26, 2026, both per the news-feed calendar and unconfirmed. Bias neutral beneath Pivot R1 at 29,664.75, expected band roughly 29,300 to 29,620.
6.2 London Session (3:00 AM to 8:00 AM ET Tuesday)
French consumer confidence is listed at 3:45 AM ET and eurozone money supply at 5:00 AM ET on Tuesday, October 27, 2026, both per the news-feed calendar and unconfirmed. Bias neutral, expected band roughly 29,250 to 29,660, with the Pivot Point at 29,344.50 the first meaningful support beneath the settle and Pivot R1 at 29,664.75 the first pivot resistance above it, with the 29,463.85 threshold conversion, Monday's 29,572.00 high and six other references between the settle and R1.
6.3 Morning Session (9:30 AM to 12:00 PM ET Tuesday, RTH Open)
The advance durable goods report is scheduled for 8:30 AM ET on Tuesday, October 27, 2026, as the calendar lists it, the cash open at 9:30 AM ET sets the session's first directional test, and new home sales are scheduled for 10:00 AM ET on Tuesday, October 27, 2026, as the calendar lists it. The consumer confidence survey is listed at 10:00 AM ET on Tuesday, October 27, 2026, per the news-feed calendar and unconfirmed. Expected band roughly 29,120 to 29,810, with Pivot S1 at 29,117.00 beneath and one standard deviation resistance at 29,812.44 above.
6.4 Afternoon Session (12:00 PM to 4:00 PM ET Tuesday)
The US five-year note auction is listed at 1:00 PM ET on Tuesday, October 27, 2026, per the news-feed calendar and unconfirmed, and the cash session closes at 4:00 PM ET. Expected band roughly 29,060 to 29,890, with the outer edges near one standard deviation support at 29,062.06, which sits 2.06 points inside the bottom, and Pivot R2 at 29,892.25, 2.25 points above the top.
6.5 Night Session Forward (6:00 PM ET Tuesday)
Globex reopens at 6:00 PM ET on Tuesday after the 5:00 PM ET halt, with a payments network's results after the close on Tuesday, October 27, 2026, as the calendar lists it. The FOMC statement is scheduled for 2:00 PM ET on Wednesday, October 28, 2026, as the calendar lists it, with results from a search-engine group and a software maker after the close the same day, as the calendar lists it, so in this review's judgment the forward window carries the week's first-order events.
6.6 Expected Range (Tuesday Full Session)
Low-range scenario: 29,250 to 29,660; Mid-range scenario (most likely): 29,060 to 29,810; High-range scenario: 28,900 to 29,970.
6.7 Most Likely Path
In this review's analyst judgment the most probable path holds the contract between Pivot S1 at 29,117.00 and Pivot R2 at 29,892.25, with a rebound toward the 29,600 to 29,640 band that stalls beneath Pivot R1 at 29,664.75 weighted slightly above an extension. The settle sits beneath every settlement average from the 5-day to the 100-day, negative direction leads on both directional systems, the composite reads "32% SELL", and the cash close sits beneath the modeled volatility threshold with negative gamma notional, a model output.
The alternative that would invalidate this reading is continued technology leadership ahead of Wednesday's results, which could carry the contract above Pivot R1 at 29,664.75 toward one standard deviation resistance at 29,812.44 and Pivot R2 at 29,892.25. Monday printed a higher high and a higher low, the cash close sits above the flip level, and the composite's direction reads "Weakest" for the sell signal, so a further advance before any reversal is a live alternative.
7. Tuesday Economic Calendar
Monday's releases are complete. The Chicago Fed national activity index printed 0.07, the Dallas Fed manufacturing index printed 13.40 and the US two-year note auction stopped at a 4.708 percent high yield with a 2.590 bid-to-cover, all per the news-feed calendar and unconfirmed. The cash session closed at 4:00 PM ET.
On Tuesday, October 27, 2026 French consumer confidence is listed at 3:45 AM ET and eurozone money supply at 5:00 AM ET, both per the news-feed calendar and unconfirmed. The advance durable goods report is scheduled for 8:30 AM ET on Tuesday, October 27, 2026, as the calendar lists it, with a news-feed consensus of 1.9 percent against minus 0.1 percent previously, per the news-feed calendar and unconfirmed. New home sales are scheduled for 10:00 AM ET on Tuesday, October 27, 2026, as the calendar lists it, and the consumer confidence survey is listed at 10:00 AM ET, per the news-feed calendar and unconfirmed. The five-year note auction is listed at 1:00 PM ET, per the news-feed calendar and unconfirmed, the FOMC meeting begins on Tuesday, October 27, 2026, as the calendar lists it, and a payments network's results follow the close on Tuesday, October 27, 2026, as the calendar lists it.
Later in the week, the FOMC statement is scheduled for 2:00 PM ET on Wednesday, October 28, 2026, as the calendar lists it, results from a search-engine group and a software maker after the close on Wednesday, October 28, 2026, as the calendar lists it, the advance estimate of third-quarter GDP and the September personal income and outlays report for 8:30 AM ET on Thursday, October 29, 2026, as the calendar lists it, and an online retailer's results after the close on Thursday, October 29, 2026, as the calendar lists it. In this review's judgment the first-order scheduled item on Tuesday is the 8:30 AM ET durable goods report, with the week's first-order events the FOMC statement and the search-engine group's and software maker's results on Wednesday.
8. Primary Trade Setup
Direction: Short
Rationale: The settle sits beneath every settlement average from the 5-day to the 100-day, negative direction leads on the 9-day and 14-day directional systems, the composite reads "32% SELL", and the cash index closed beneath the modeled volatility threshold with negative gamma notional, a model output. A rebound into the 29,600 to 29,640 band, 20.37 points above the 9-day average crossing price at 29,579.63, holding the 29,622.61 MACD stall level and beneath Pivot R1 at 29,664.75, offers a short with a defined risk point above Pivot R1. Monday's higher high and higher low and the cash close above the flip level leave room for a further advance, so the setup is an analyst judgment that rallies are sold beneath Pivot R1 ahead of Wednesday's results, not a measured edge.
Entry Zone: 29,600 to 29,640
Stop Loss: 29,740 (above Pivot R1 at 29,664.75 and beneath one standard deviation resistance at 29,812.44)
Target 1 (T1): 29,500 (above the 29,463.85 conversion of the modeled volatility threshold)
Target 2 (T2): 29,380 (above the Pivot Point at 29,344.50)
Target 3 (T3, extended): 29,260 (just beneath the 29,265.85 conversion of the modeled gamma-flip level and above the published target price at 29,235.70)
Risk-to-Reward: Approximately 1:1 to T1, 1:2 to T2, 1:3 to T3
Invalidation: A settle above one standard deviation resistance at 29,812.44 negates the thesis. Short of that, the edge is removed by acceptance above the entry band and not by a touch, defined as two consecutive 30-minute closes above 29,640.
Macro override: Continued technology leadership ahead of Wednesday's results, or a decisive drop in yields, would undercut the short. In that scenario a move through the 29,740 stop invalidates the setup before the targets, and one standard deviation resistance at 29,812.44 becomes the reference, 72.44 points beyond the stop and inside one 14-day average true range of 539.46 points.
Sources and methodology
This outlook is built from our session review of the December E-mini Nasdaq-100 contract, the December ’26 contract, prepared after Monday's close on October 26, 2026 for the Tuesday, October 27, 2026 session. Monday's open, high, low and settle come from the provider's daily settlement record for the December contract, the 2026-10-26 row, and match the chart's completed daily bar. Monday's completed extremes are also the inputs behind the published pivot ladder: Pivot R3 at 30,212.50 less Pivot S3 at 28,569.25, divided by three, and Pivot R2 at 29,892.25 less Pivot S2 at 28,796.75, divided by two, both return 547.75, and three times the 29,344.50 Pivot Point less the settle gives 58,596.25, which the pair of 29,572.00 and 29,024.25 reproduces exactly. No intraday series was preserved for Monday, so no statement in this article places a Monday print at a time of day, and Monday's card is graded against the daily bar alone. Monday's session opened at the Sunday 6:00 PM ET reopen, and Tuesday's session opened at the Monday 6:00 PM ET reopen. The open, high and low on the provider's overview page, 29,480.50, 29,501.25 and 29,471.00, belong to that new Tuesday session and are not used as Monday's range; the provider's previous close of 29,437.25 is Monday's settle.
The moving averages are the review's, computed from the provider's daily settlement series for the December contract, 259 completed sessions with the partial Tuesday row dropped, and rounded once to the 0.25 tick. The oscillators and the average true and daily ranges are cited as published, read at about 6:23 PM ET on Monday after the 6:00 PM ET reopen, so the provider may already blend the reopened session's quote into them. Volume and open interest come from the provider's daily record: the 2026-10-26 row reads 671,673 contracts with open interest not yet reported, and the 2026-10-23 row now reads 677,678 contracts and open interest of 285,953, where Monday's outlook carried 672,105 contracts and open interest not yet reported; the 2026-10-22 row reads open interest of 288,953. The weekly positioning report is dated October 20. The evening positioning note used is the 5:51 PM ET Monday edition, read at 6:17 PM ET, with Friday's closes in its reference column; every Nasdaq futures equivalent is the review's conversion at the 163.85 point measured basis, the December settlement less the cash close, against 160.22 on Friday. The QQQ fund is a proxy read alongside the index levels. The reading that dealer hedging can still amplify moves is the review's interpretation from the index model and that proxy, both model outputs, and it is a damping read with no direction; the fund console, dated 2026-10-26, was read at about 6:18 PM ET. The volume and open-interest changes, the ten-session net change and the distances in this article are computed. Scenario ranges are analyst judgment, and items marked unconfirmed come from the news-feed calendar.
Monday’s outlook for this contract is here, and the S&P 500 contract’s Monday outlook covers the index that rose 0.70 percent in cash on Monday. Outlooks for ES, NQ, GC and CL are collected on the market outlook page, and our forward trading record is on the performance statement.