At the Tuesday 6:00 PM ET reopen the December Nasdaq-100 contract printed 31,521.00, inside the first 30-minute bar of Wednesday's session. Nothing traded higher all day. The low of 31,143.00 came inside the 9:30 AM ET bar, the cash-open bar, according to the chart's 30-minute bars. Provider commentary said stocks settled lower on higher Treasury yields and the prospect of further rate increases, with the ten-year yield touching a 24-year high of 5.36 percent.
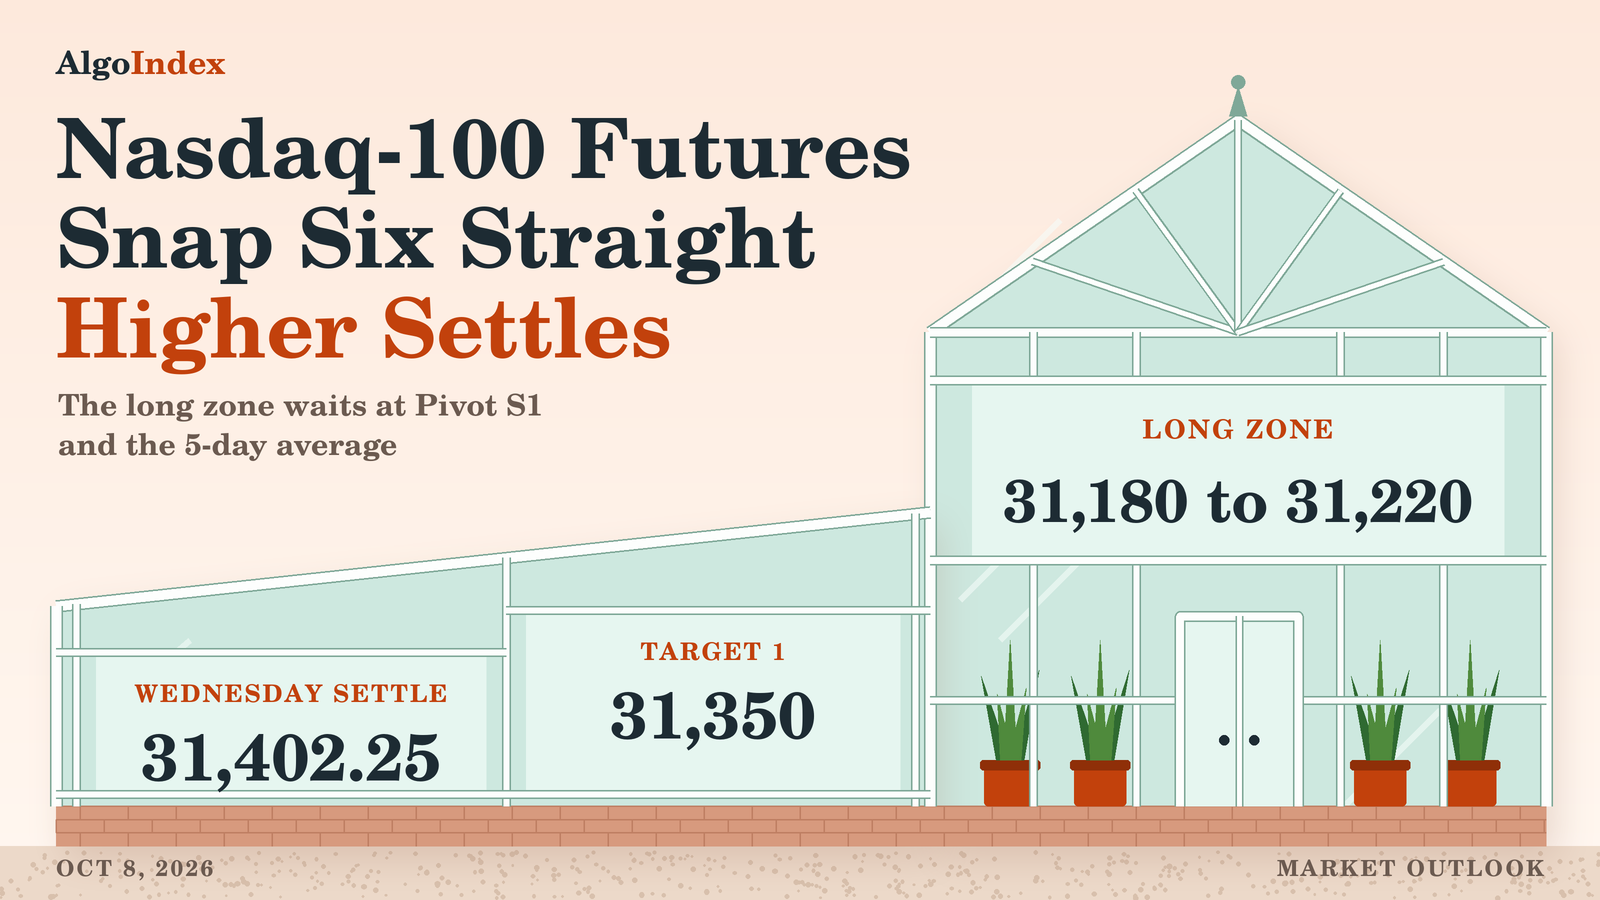
Settlement came at 31,402.25, down 81.00 points or 0.26 percent from Tuesday's 31,483.25. That ended a run of six consecutive higher settles. The 378.00 point range ran 0.82 times the published 14-day average daily range of 463.14 points, and the settle finished at 68.6 percent of it. Both ends stepped down. The high sat 95.50 points beneath Tuesday's 31,616.50, the 52-week high, and the low 166.25 points beneath Tuesday's 31,309.25. The Thursday session reopened at 6:00 PM ET Wednesday. Next up is a thirty-year bond auction at 1:00 PM ET Thursday, on the news-feed calendar and unconfirmed.
December Nasdaq-100 futures settled at 31,402.25, down 81.00 points, at 68.6 percent of a 378.00 point range and 46.83 points above the Pivot Point at 31,355.42. Six higher settles ended. The high of 31,521.00 printed inside the 6:00 PM ET bar of Tuesday evening and the 31,143.00 low inside the 9:30 AM ET bar. Wednesday's row on the provider's daily record shows volume of 500,010 contracts and open interest of 281,627, a column that appears lagged one session; Tuesday's revised row reads 478,622 and 282,834. The composite multi-indicator read holds at 88 percent buy, strength and direction average. Every settlement average sits beneath the settle. Dealer positioning puts the cash-index call-side ceiling and largest gamma concentration at 31,500, or 31,742.17 in futures at the 242.17 point basis. The modeled volatility threshold sits at 30,990, or 31,232.17, and the modeled gamma flip at 30,449, or 30,691.17. Overhead: the 31,420.64 %K stall price, the 31,509.11 target price, Wednesday's 31,521.00 high, Pivot R1 at 31,567.83 and the 31,616.50 52-week high. Beneath: the Pivot Point, the 31,205.10 to 31,189.83 band of the 5-day average and Pivot S1, the 31,143.00 low and one standard deviation support at 31,107.66. The primary setup is a long from 31,180 to 31,220, stop 31,050, targets 31,350, 31,500 and 31,650. Yields lead. The first-order event, in the review's judgment, is the 1:00 PM ET thirty-year bond auction, unconfirmed.
Wednesday traded through the 31,400 to 31,440 band and its 31,280 stop
Our Wednesday outlook set a long from 31,400 to 31,440 with a stop at 31,280 and targets at 31,560, 31,700 and 31,840. Wednesday's completed bar, on the provider's daily record, opened at 31,510.00 at the Tuesday 6:00 PM ET reopen, marked a high of 31,521.00 and a low of 31,143.00, and settled at 31,402.25. Tonight's review states the same four prints. The band traded. So did the stop. The low ran 257.00 points beneath the band's lower edge and 137.00 beneath 31,280. No target traded. The 31,521.00 high stopped 39.00 points short of 31,560, and 31,700 and 31,840 stayed further out.
Two prints carry a time. The chart's 30-minute bars place the 31,521.00 high inside the 6:00 PM ET bar of Tuesday evening and the 31,143.00 low inside the 9:30 AM ET bar, which traded from 31,143.00 to 31,275.50. The open sat 70.00 points above the band's upper edge. Between those two bars the record is selective. It cannot show when the band first traded or when 31,280 first traded. The record holds prints only. It shows no fills. Settlement landed inside the band, 2.25 points above its lower edge and 37.75 beneath its upper edge.
The exit lines can be scored. The card named a settle beneath Pivot S1 at 31,322.83 as its invalidation. Wednesday settled 79.42 points above it, though the low traded 179.83 points beneath it. Its second test was acceptance beneath 31,340, defined as two consecutive 30-minute closes. That test was met. The 9:30 AM ET bar traded wholly beneath 31,340, its 31,275.50 top 64.50 points under the line, and closed at 31,238.00. The 10:00 AM ET bar closed at 31,254.75, also beneath it. By that bar at the latest, the card's edge was gone by its own definition.
The weighted path missed. We had the contract holding above the 31,469.67 Pivot Point into the cash open and retesting the 31,616.50 high to 31,630.08 Pivot R1 area before the 2:00 PM ET minutes. The 9:30 AM ET bar topped at 31,275.50, 194.17 points beneath that Pivot Point. Wednesday's high fell 95.50 points short of 31,616.50. We also weighted a pullback toward Pivot S1 at 31,322.83 and the 31,358.78 conversion that holds above a break beneath Tuesday's 31,309.25 low. The break came. The low undercut 31,309.25 by 166.25 points and the 31,358.78 conversion by 215.78. Settlement came back above both, 67.42 points beneath the old Pivot Point.
Two session bands can be checked against a timed print. The Globex band of 31,380 to 31,600 held the 31,521.00 high, which printed in the 6:00 PM ET bar, 79.00 points beneath its top. The morning band of 31,300 to 31,700 did not hold. The 9:30 AM ET bar reached 31,143.00, 157.00 points beneath its bottom. The European and afternoon bands need a fuller intraday record, so they go unscored. Across the full session the low broke the 31,380 bottom of the low-range case by 237.00 points and the 31,280 bottom of the mid-range case by 137.00. The high-range case of 31,030 to 31,940 held the whole day, with 113.00 points to spare at the bottom. The settle finished inside all three.
The macro override named three risks. They were a hawkish reading of the minutes that lifts the ten-year yield back above Monday's 5.31 percent close, a renewed slide in semiconductor shares, or a Gulf escalation that lifts crude and yields together. The ten-year yield index touched 5.36 percent during the session and closed at 5.27, per the provider's quotes. The record does not show when that high printed. Provider commentary said the minutes showed most policymakers judged another increase by year-end appropriate. The semiconductor index fell 1.15 percent. At 3:41 PM ET the news feed carried a maritime security notice of a tanker struck near Qatar, and November crude settled down 1.16. No record here ties any of these to a price move. We grade the card as written.
A 31,521.00 high, a 31,143.00 low and the end of six higher settles
Wednesday opened at 31,510.00 at the Tuesday 6:00 PM ET reopen, 26.75 points above Tuesday's settle. Its 31,521.00 high came inside that first 6:00 PM ET bar. Its 31,143.00 low came inside the 9:30 AM ET bar, which traded from 31,143.00 to 31,275.50. Settlement came at 31,402.25, 118.75 points beneath the high and 259.25 above the low. Only selected 30-minute bars were preserved. Nothing here describes the path between them.
Late trade sat near the settle. The chart's 3:30 PM ET bar traded between 31,359.25 and 31,422.25, and the 4:30 PM ET bar between 31,380.00 and 31,416.50. Those quotes are not used as the settlement. The Thursday session reopened at 6:00 PM ET Wednesday. The provider's day open, high and low of 31,403.00, 31,438.50 and 31,403.00, shown at the time of writing, belong to that new session, not to Wednesday.
Those extremes also come from the ladder. Wednesday's high and low are the completed-session inputs behind the published pivot ladder, back-solved from the outer pivot pairs and checked against every rung. The third resistance point at 31,945.83 minus the third support point at 30,811.83, divided by three, returns 378.00. The second pair, 31,733.42 and 30,977.42, divided by two, returns the same 378.00. Three times the 31,355.42 Pivot Point less the settle gives 62,664.01. That is one hundredth from the 62,664.00 sum of the solved pair, because the published pivot is rounded, and the pair reproduces all seven published rungs. The provider's settlement row and the chart's completed Wednesday daily bar carry the same high and low.
Against Tuesday the bar stepped down at both ends. The high sits 95.50 points beneath Tuesday's 31,616.50, the 52-week high, and the low 166.25 beneath Tuesday's 31,309.25. The settle sits 214.25 points beneath that 52-week high. Activity rose. Wednesday's 2026-10-07 row on the provider's daily record shows volume of 500,010 contracts, against 478,622 on Tuesday's revised row. Open interest reads 281,627 on Wednesday's row. That is the figure Tuesday's row carried before its revision, so the column appears lagged one session and no open-interest change is asserted. Tuesday's row now reads 282,834. Our Wednesday outlook carried 470,004 contracts and 281,627 for Tuesday.
The prior week still frames the move. That week, September 28 through October 2, spanned 30,356.75 to 31,282.50. Wednesday's low traded 139.50 points beneath its 31,282.50 top, and the settle finished 119.75 points above it. No weekly positioning report figure was captured for the Nasdaq contract, so no positioning change is asserted.
Six higher settles ended. Settlements over the last seven sessions ran 30,613.25, 30,698.75, 30,760.50, 31,061.75, 31,317.75, 31,483.25 and 31,402.25. The run that ended on Tuesday added 917.00 points from the 30,566.25 settle of 09/28, and Wednesday gave back 81.00 of them. Session highs over the last six sessions read 30,906.00, 31,151.50, 31,282.50, 31,371.00, 31,616.50 and 31,521.00. Lows read 30,512.25, 30,529.25, 30,760.25, 30,957.50, 31,309.25 and 31,143.00. Wednesday broke both sequences. Daily ranges for the last eight sessions ran 564.00, 353.50, 393.75, 622.25, 522.25, 413.50, 307.25 and 378.00.
The retracement grid published for Thursday places the 38.2 percent retracement from the four-week high at 30,637.24 and the 50 percent retracement of the four-week range at 30,334.75, both beneath the settle. The 38.2 percent retracement from the 13-week high sits at 30,037.12. No four-hour series was captured. Swing structure here rests on daily bars only.
Every average still sits beneath the settle. Computed from the provider's daily settlement series for the December contract, 259 completed sessions through Wednesday, the 5-day stands at 31,205.10, the 9-day at 30,977.00, the 20-day at 30,443.05, the 50-day at 29,990.15, the 100-day at 30,013.14 and the 200-day at 28,156.16. The settle sits 197.15 points above the 5-day, 425.25 above the 9-day and 959.20 above the 20-day. It is 1,412.11 above the 50-day, 1,389.11 above the 100-day and 3,246.10 above the 200-day.
Window arithmetic lifted the short averages. The 5-day rose 140.70 points from Tuesday's 31,064.40, because the 09/30 settle of 30,698.75 left the window and was replaced by 31,402.25. The 9-day rose 70.61 points as the 09/24 settle of 30,766.75 left its window, and the 20-day rose 83.03 points as the 09/09 settle of 29,741.75 left. The 100-day sits 23.00 points above the 50-day. Its older 50 settles averaged 30,036.14, higher than the latest 50. The projection grid gives the prices at which each average would be crossed on Thursday: 30,987.97 for the 9-day, 30,605.97 for the 18-day and 30,138.44 for the 40-day.
Momentum stays high. The oscillator figures are as published on the provider's technical page dated for the Thursday session, read after the 6:00 PM ET reopen, so the page may carry the live Globex price in place of the settle. Relative strength reads 72.25 on the 9-day, 67.34 on the 14-day and 63.23 on the 20-day. The 9-day raw stochastic reads 82.99 percent and the 14-day 89.12 percent. The 14-day %K sits at 93.73 percent, above %D at 92.50 percent.
Positive direction still leads. On the 9-day the directional index reads 30.21, with positive direction at 28.72 and negative at 14.09; on the 14-day it reads 20.00, with positive direction at 27.31 against negative at 15.66. Historic volatility reads 8.83 percent on the 9-day and 13.94 percent on the 14-day. The composite multi-indicator read published for the Thursday session is 88 percent buy, the same as the prior session's snapshot, with strength and direction both described as average. A week ago it read 80 percent buy. A month ago, 56 percent. The short-horizon and medium-horizon groups each average 100 percent buy, the long-horizon group 33 percent buy, and the composite trend indicator reads buy.
Volatility frames Thursday. The published 14-day average true range stands at 449.67 points, 1.43 percent of the settle, and the 14-day average daily range at 463.14; the 9-day figures are 440.41 and 430.56, and the 20-day figures 464.44 and 462.09. One 14-day average true range either side of the settle spans 30,952.58 to 31,851.92. The published standard-deviation bands are narrower, built from five settlements. One deviation spans 31,107.66 to 31,696.84, two span 30,985.63 to 31,818.87 and three span 30,892.00 to 31,912.50. Those bands describe settlement dispersion only.
A 5.36 percent yield high, a 1.15 percent chip drop and the minutes
Yields set the tone. The ten-year yield index closed at 5.27 percent, up one basis point, after a session high of 5.36 percent, per the provider's quotes, and provider commentary called that high a 24-year high. The minutes of the September policy meeting were released at 2:00 PM ET on Wednesday, October 7, 2026, as the calendar lists them. Provider commentary said most policymakers judged another rate increase by year-end appropriate. No priced policy probability was captured.
One auction set a marker. A ten-year note auction stopped at 5.300 percent, per the news-feed calendar and unconfirmed, the highest auction yield since November 2000 per the news feed. At 11:00 AM ET a regional survey of one-year inflation expectations printed 3.9 percent, also per the news-feed calendar and unconfirmed.
Chips fell harder than the index. The semiconductor index closed at 13,066.15, down 151.67 points or 1.15 percent, after a session range of 12,864.94 to 13,082.11, per the provider's quote. The Nasdaq-100 cash index lost 0.21 percent. No single-stock breadth series was captured, so no rotation claim beyond that comparison is made.
Product news ran through the afternoon. Between 1:15 PM ET and 1:57 PM ET the equities feed carried a software maker's product event. It included execution containers for software agents, a coding model that runs on laptops, and personal computers built on a chipmaker's processors that begin reaching customers next week. At 2:03 PM ET the feed carried an artificial-intelligence developer's release of a new model. These are statements carried by the news feed and not measured effects. The captured calendars carry no mega-capitalisation earnings entry for Thursday, and the large banks begin reporting on Tuesday, October 13, 2026, as the calendar lists it.
Gulf headlines arrived late. At 3:08 PM ET the news feed carried a press report that the White House is seeking strike options against Iran, and at 3:41 PM ET a maritime security notice of a tanker struck near Qatar. Between 4:35 PM ET and 4:37 PM ET, after the 4:00 PM ET settlement, it carried a statement that Iran and Oman agreed coordinates for safe transit routes through the Strait of Hormuz. A post-close wrap on the feed said the record-setting rally halted as high oil prices raised inflation concerns. These are statements carried by the news feed and were not confirmed.
Elsewhere the dollar index rose 0.40 percent to 102.24. November crude settled at 88.28, down 1.16, and December gold at 4,140.7, down 46.4. Provider commentary said stocks recovered from their worst levels after crude gave up an early advance. The S&P 500 cash index closed at 7,801.77, down 0.22 percent. The Nasdaq-100 cash index closed at 31,160.08, down 64.39 points or 0.21 percent, after a 30,904.46 to 31,170.12 session range, so it closed 10.04 points beneath its session high. The volatility index closed at 15.08, up 0.07, and the Nasdaq-100 volatility gauge at 21.00, down 0.15, per the provider's quotes.
The basis narrowed. The measured closing basis, the December settlement of 31,402.25 less the 31,160.08 cash close, both from the provider for the completed session, is 242.17 points. On Tuesday it was 258.78, so it narrowed by 16.61 points.
The desk note comes next. The edition used is the 6:21 PM ET note for Wednesday, read at about 8:38 PM ET, and its reference prices are the prior session's closes. The NDX reference of 31,224 equals Tuesday's 31,224.47 cash close, and the QQQ reference of 759 equals Tuesday's 759.66 fund close. Every level is therefore read against Wednesday's 31,160.08 cash close.
On the cash index the primary call-side ceiling and the largest gamma concentration both sit at 31,500. The modeled volatility threshold sits at 30,990, the modeled gamma-flip level at 30,449 and the primary put-side support base at 30,200. The 31,160.08 close sits 339.92 points beneath the ceiling, 170.08 above the threshold and 711.08 above the flip level. The note lists 31,500, 31,000, 30,000 and 32,000 as key strikes. Gamma tilt reads 1.893 for the index and 1.174 for the fund. Gamma notional reads plus 17.11 million dollars for the index and plus 387.989 million for the fund.
The fund proxy sits just under its threshold. Its primary call-side ceiling and largest gamma concentration sit at 760, the modeled volatility threshold at 759, the modeled gamma-flip level at 752 and the primary put-side support base at 700. The fund's positioning console, marked as updated 2026-10-07, showed a 758.18 quote, beneath the 759 threshold and above the 752 flip level. That is a thin margin. It shows call gamma of minus 723 million against put gamma of minus 2.5 billion and attributes 12.59 percent of gamma to the nearest expiration. Its high and low volatility point fields are treated as low-confidence and excluded.
Conversions carry four cash levels into futures. At the measured closing basis of 242.17 points, cash 31,500 corresponds to 31,742.17 on the December contract, the 30,990 threshold to 31,232.17, the 30,449 flip level to 30,691.17 and 30,200 to 30,442.17. These are conversions made by this review. The source publishes no Nasdaq futures pair. The threshold and the flip level are model outputs with no listed strike behind them.
The note's narrative said the S&P 500 and the Nasdaq pulled back from all-time highs, that semiconductors fell about 1 percent and software about 1 percent while memory shares rose about 1 percent, and that the S&P 500 hedging-flow measure finished at plus 12 billion dollars of delta, mostly from same-day put selling. In this review's interpretation positive index gamma above the flip level argues for contained ranges, while a December price beneath the 31,232.17 threshold equivalent leaves the contract in the less dampened zone. Wednesday's low traded 89.17 points beneath that equivalent. The settle finished 170.08 above it.
The trade map for Thursday
The primary setup is a long from 31,180 to 31,220, around Pivot S1 at 31,189.83 and the 5-day settlement average at 31,205.10. The case rests on structure. The settle sits above every average from the 5-day to the 200-day, positive direction leads on the 9-day and 14-day directional systems, and the composite reads 88 percent buy. The stop at 31,050 sits beneath one standard deviation support at 31,107.66 and Wednesday's 31,143.00 low. Two readings cut the other way. The six-session advance ended on Wednesday, and the 14-day %K reads 93.73 percent. So the setup is an analyst judgment that pullbacks stay shallow while yields stabilise. It is not a measured edge. The band sits just beneath 31,232.17, the December equivalent of the 30,990 modeled volatility threshold, 12.17 points above its top, so a reclaim of that level after entry is part of the thesis. The 14-day average true range of 449.67 points compares with a 150 point stop distance from the 31,200 midpoint. The band is the one our Tuesday outlook carried; Tuesday's low stopped 89.25 points above it.
Overhead the references start 18.39 points above the settle, at the 31,420.64 stall price for the 14-day %K. The 3:30 PM ET bar topped at 31,422.25, and the new Thursday session had printed 31,438.50 by the time of writing. Tuesday's 31,483.25 settle comes next. The published target price of 31,509.11 and Wednesday's 31,521.00 high follow. Pivot R1 at 31,567.83 and the 52-week high at 31,616.50 sit above them, then the 14-day relative-strength 70 percent line at 31,637.96 and one standard deviation resistance at 31,696.84. Pivot R2 at 31,733.42, the 31,742.17 conversion of the cash 31,500 ceiling, the 3-10 day average crossover stall price at 31,760.54 and two standard deviations resistance at 31,818.87 come after that. Three standard deviations resistance at 31,912.50 and Pivot R3 at 31,945.83 are the extended references.
Support starts 46.83 points beneath the settle, at the 31,355.42 Pivot Point, with the 31,359.25 low of the 3:30 PM ET bar 3.83 points over it. Tuesday's 31,309.25 low, the 31,282.50 prior-week high and the 31,275.50 top of the 9:30 AM ET bar sit beneath. Then the zone. The 31,232.17 conversion of the cash 30,990 threshold sits 12.17 points above it. The 5-day settlement average at 31,205.10 and Pivot S1 at 31,189.83 frame it, with Wednesday's 31,143.00 low 46.83 points beneath Pivot S1. One standard deviation support at 31,107.66 follows, 57.66 points above the stop. The 9-day average crossing price at 30,987.97, two standard deviations support at 30,985.63, Pivot S2 at 30,977.42 and the 9-day settlement average at 30,977.00 form a tight grouping 10.97 points deep. Three standard deviations support at 30,892.00, Pivot S3 at 30,811.83, the 30,691.17 conversion of the cash 30,449 flip level, the 38.2 percent retracement from the four-week high at 30,637.24 and the 30,442.17 conversion of the cash 30,200 put-side base are the deeper references.
The night comes first. Globex reopened at 6:00 PM ET Wednesday with the minutes and the 4:37 PM ET Hormuz transit statement already released, and it had traded between 31,403.00 and 31,438.50 by the time of writing. Japanese current account data are listed at 7:50 PM ET, on the news-feed calendar and unconfirmed. Bias reads neutral above the 31,355.42 Pivot Point, with an expected Globex band of roughly 31,250 to 31,520 absent a headline shock.
Europe follows. German trade data are listed at 2:00 AM ET Thursday, on the news-feed calendar and unconfirmed. The calendar lists a Federal Reserve governor on the economic outlook at 4:30 AM ET on Thursday, October 8, 2026. The European Central Bank's meeting account is listed at 7:30 AM ET and the Bank of England governor at 8:15 AM ET, both on the news-feed calendar and unconfirmed. The expected band runs roughly 31,190 to 31,570.
Then the data. Weekly initial jobless claims are listed at 8:30 AM ET with a forecast of 200 thousand against 197 thousand, on the news-feed calendar and unconfirmed, before the cash open at 9:30 AM ET. The calendar lists wholesale inventories at 10:00 AM ET. A regional Federal Reserve president is listed at 10:40 AM ET, on the news-feed calendar and unconfirmed. The morning band runs roughly 31,100 to 31,600, with Pivot S1 at 31,189.83 the first meaningful support.
The afternoon carries the auction. A thirty-year bond auction is listed at 1:00 PM ET and the same regional Federal Reserve president again at 1:40 PM ET, both on the news-feed calendar and unconfirmed. The afternoon band runs roughly 31,100 to 31,600 into the 4:00 PM ET settlement. That is the hinge. In this review's judgment the single first-order event for the Nasdaq-100 on Thursday is the 1:00 PM ET thirty-year bond auction, on the news-feed calendar and unconfirmed, because yields set the tone on Wednesday. More follows. Japanese household spending is listed at 7:30 PM ET Thursday and the preliminary University of Michigan survey at 10:00 AM ET on Friday, both on the news-feed calendar and unconfirmed. Further out, the calendar lists the large banks before the open on Tuesday, October 13, 2026, and the consumer price index for September at 8:30 AM ET on Wednesday, October 14, 2026.
Three scenarios frame the day. Across the full session the low-range case runs 31,250 to 31,520, the mid-range and most likely case 31,100 to 31,620 and the high-range case 30,950 to 31,850. All three nest. In this review's analyst judgment the most probable path holds the contract above Pivot S1 at 31,189.83, with a pullback into the 31,189.83 to 31,205.10 band of Pivot S1 and the 5-day settlement average weighted as a buying area. Three grounds carry that weight. A settle above every computed average. Positive direction leading on the 9-day and 14-day systems. The 88 percent buy composite. A 14-day stochastic %K of 93.73 percent and a 9-day relative strength of 72.25 argue that upside extension beyond the 31,616.50 high needs a catalyst. One risk stands out. The alternative that would invalidate this reading is a further rise in yields after the 1:00 PM ET thirty-year auction, on the news-feed calendar and unconfirmed, that takes the contract beneath one standard deviation support at 31,107.66 and toward Pivot S2 at 30,977.42.
Yields set the tone on Wednesday, and the news-feed calendar puts the thirty-year auction at 1:00 PM ET Thursday, unconfirmed.
The complete data picture
Every number behind Thursday’s plan, charted first, then the full level map, then the complete numeric reference underneath.
Cash-index levels at the measured 242.17 point basis: the 31,500 call-side ceiling translates to 31,742.17 in futures, the 30,990 modeled volatility threshold to 31,232.17, the 30,449 modeled gamma flip to 30,691.17 and the 30,200 put-side base to 30,442.17. No other cash level is translated.
Full numeric reference, every remaining figure from the session review
3.1 Resistance, level by level
The first published resistance, 18.39 points above the settle, is 31,420.64, the stall price for the 14-day %K, followed by the published target price of 31,509.11 and Wednesday's 31,521.00 high. Pivot R1 at 31,567.83 and the 52-week high at 31,616.50 come next, then the 14-day relative-strength 70 percent line at 31,637.96 and one standard deviation resistance at 31,696.84. Pivot R2 at 31,733.42, the 3-10 day average crossover stall price at 31,760.54 and two standard deviations resistance at 31,818.87 follow, with three standard deviations resistance at 31,912.50 and Pivot R3 at 31,945.83 the extended references.
3.2 Support, level by level
Beneath the settle, the Pivot Point at 31,355.42 comes first, then the 5-day settlement average at 31,205.10 and Pivot S1 at 31,189.83, the band that anchors the setup, with Wednesday's 31,143.00 low beneath it. One standard deviation support at 31,107.66 follows, then the 9-day average crossing price at 30,987.97, two standard deviations support at 30,985.63, Pivot S2 at 30,977.42 and the 9-day settlement average at 30,977.00 in a tight grouping. Three standard deviations support at 30,892.00, Pivot S3 at 30,811.83 and the 38.2 percent retracement from the four-week high at 30,637.24 are the deeper references.
1. Executive Summary
The December Nasdaq-100 contract settled at 31,402.25 on Wednesday, down 81.00 points or 0.26 percent from Tuesday's settle of 31,483.25, after trading between 31,521.00 and 31,143.00, a 378.00 point daily range. The settle finished at 68.6 percent of the range, and the 378.00 point range was 0.82 times the published 14-day average daily range of 463.14 points. Wednesday printed a lower high and a lower low against Tuesday, and the 81.00 point decline ended a run of six consecutive higher settles.
The Nasdaq-100 cash index closed at 31,160.08, down 64.39 points or 0.21 percent, after a session range of 30,904.46 to 31,170.12, per the provider's quote, so the cash index closed 10.04 points beneath its session high. Provider commentary said stocks settled lower on higher Treasury yields and the prospect of further rate increases, with the ten-year yield touching a 24-year high of 5.36 percent and the minutes of the September policy meeting showing most policymakers judged another increase by year-end appropriate, and that stocks recovered from their worst levels after crude gave up an early advance. The semiconductor index fell 1.15 percent to 13,066.15.
The composite multi-indicator read published for the Thursday session is 88 percent buy, unchanged from the prior session's snapshot, with signal strength and direction both described as average. The evening desk note places the Nasdaq-100 primary call side ceiling and the largest gamma concentration at NDX 31,500, the modeled volatility threshold at NDX 30,990 and the modeled gamma-flip level at NDX 30,449, so the 31,160.08 cash close sits between the threshold and the ceiling; section 5 carries the detail.
The Primary Setup below is a long from the 31,180 to 31,220 band, around Pivot S1 at 31,189.83, stopped at 31,050 beneath one standard deviation support at 31,107.66 and Wednesday's 31,143.00 low, with objectives at 31,350, 31,500 and an extended 31,650.
2.1 Intraday and Session Review
The Wednesday session opened at 31,510.00 at the Tuesday 6:00 PM ET reopen, 26.75 points above Tuesday's settle, marked a daily high of 31,521.00 and a daily low of 31,143.00, and settled at 31,402.25. The chart's 30-minute bars place the 31,521.00 high inside the 6:00 PM ET bar of Tuesday evening and the 31,143.00 low inside the 9:30 AM ET bar, which traded from 31,143.00 to 31,275.50. Only selected 30-minute bars were preserved, not a complete intraday series, so this review makes no claim about the path between those bars.
The chart's 3:30 PM ET bar traded between 31,359.25 and 31,422.25 and the 4:30 PM ET bar between 31,380.00 and 31,416.50. The Thursday session reopened at 6:00 PM ET Wednesday; the provider's day open, high and low of 31,403.00, 31,438.50 and 31,403.00 shown at the time of writing belong to that new session, not to Wednesday.
The session extremes used here are the completed-session inputs behind the published pivot ladder and were not read independently from a bar, back-solved from the outer pivot pairs and verified against every rung. The third resistance point at 31,945.83 minus the third support point at 30,811.83, divided by three, returns 378.00, and the second resistance point at 31,733.42 minus the second support point at 30,977.42, divided by two, returns the same 378.00. Three times the Pivot Point of 31,355.42 less the 31,402.25 settle gives a high plus low sum of 62,664.01, 0.01 from the 62,664.00 of the solved pair because the published pivot is rounded, and the pair of 31,521.00 and 31,143.00 reproduces all seven published rungs. Independent corroboration: the provider's settlement row and the chart's completed Wednesday daily bar carry the same 31,521.00 high and 31,143.00 low.
2.2 Daily Structure
Wednesday printed a lower high and a lower low against Tuesday: the 31,521.00 high sits 95.50 points beneath Tuesday's 31,616.50, the 52-week high, and the 31,143.00 low sits 166.25 points beneath Tuesday's 31,309.25. The settle sits 214.25 points beneath the 52-week high. The sequence of session highs over the last six sessions reads 30,906.00, 31,151.50, 31,282.50, 31,371.00, 31,616.50 and 31,521.00, and the sequence of session lows reads 30,512.25, 30,529.25, 30,760.25, 30,957.50, 31,309.25 and 31,143.00.
The prior week, September 28 through October 2, spanned 30,356.75 to 31,282.50, Wednesday's 31,143.00 low traded 139.50 points beneath the 31,282.50 prior-week high, while the settle sits 119.75 points above it. Settlements over the last seven sessions ran 30,613.25, 30,698.75, 30,760.50, 31,061.75, 31,317.75, 31,483.25 and 31,402.25.
2.3 4-Hour and Swing Structure
Daily ranges for the last eight sessions ran 564.00, 353.50, 393.75, 622.25, 522.25, 413.50, 307.25 and 378.00. The six higher settles that ended on Tuesday added 917.00 points from the 30,566.25 settle of 09/28 to 31,483.25, and Wednesday gave back 81.00 of them.
The retracement grid published for Thursday places the 38.2 percent retracement from the four-week high at 30,637.24 and the 50 percent retracement of the four-week range at 30,334.75, both beneath the settle, with the 38.2 percent retracement from the 13-week high at 30,037.12. No four-hour series was captured, so swing structure here rests on daily bars only.
2.4 Moving Averages
The averages cited in this subsection were computed from the provider's daily settlement series for the December contract, which holds 259 completed sessions through Wednesday. The 5-day average stands at 31,205.10, the 9-day at 30,977.00, the 20-day at 30,443.05, the 50-day at 29,990.15, the 100-day at 30,013.14 and the 200-day at 28,156.16.
The 31,402.25 settle sits above every one of them: 197.15 points above the 5-day, 425.25 above the 9-day, 959.20 above the 20-day, 1,412.11 above the 50-day, 1,389.11 above the 100-day and 3,246.10 above the 200-day. The 5-day average rose 140.70 points from Tuesday's 31,064.40, because the 09/30 settle of 30,698.75 left the window and was replaced by 31,402.25. The 9-day rose 70.61 points as the 09/24 settle of 30,766.75 left its window, and the 20-day rose 83.03 points as the 09/09 settle of 29,741.75 left.
The 100-day average sits 23.00 points above the 50-day, which means the older 50 settlements inside the 100-day window averaged higher than the most recent 50, at 30,036.14. The projection grid gives the prices at which each average would be crossed on Thursday: 30,987.97 for the 9-day, 30,605.97 for the 18-day and 30,138.44 for the 40-day.
2.5 Oscillator and Trend Readings
The oscillator figures below are as published on the provider's technical page dated for the Thursday session, read after the 6:00 PM ET reopen; the page may carry the live Globex price in place of the settle, so they are quoted as published. The 9-day relative strength reads 72.25, the 14-day relative strength 67.34 and the 20-day relative strength 63.23.
The stochastics sit high in their ranges. The 9-day raw stochastic reads 82.99 percent and the 14-day raw stochastic 89.12 percent, while the 14-day stochastic %K reads 93.73 percent and the 14-day stochastic %D 92.50 percent.
The 9-day directional index ADX reads 30.21 with the 9-day +DI at 28.72 and the 9-day -DI at 14.09, and the 14-day directional index ADX reads 20.00 with the 14-day +DI at 27.31 and the 14-day -DI at 15.66, so positive direction leads on both. The 9-day historic volatility reads 8.83 percent and the 14-day historic volatility 13.94 percent.
The composite multi-indicator read published for the Thursday session is 88 percent buy, the same as the prior session's snapshot, against 80 percent buy a week ago and 56 percent buy a month ago, with strength and direction both described as average. The short-horizon and medium-horizon groups each average 100 percent buy, the long-horizon group 33 percent buy, and the composite trend indicator reads buy.
2.6 Volatility and Expected Range
The published 14-day average true range stands at 449.67 points and the 14-day average daily range at 463.14 points; the 9-day average true range is 440.41 with a 9-day average daily range of 430.56, and the 20-day average true range is 464.44 with a 20-day average daily range of 462.09. Wednesday's 378.00 point range was 0.82 times the 14-day average daily range.
Adding and subtracting the 14-day average true range of 449.67 points from the 31,402.25 settle frames Thursday between 30,952.58 and 31,851.92. The published standard-deviation bands are narrower because they are built from five settlements: one deviation spans 31,107.66 to 31,696.84, two spans 30,985.63 to 31,818.87 and three spans 30,892.00 to 31,912.50. These bands describe settlement dispersion, not intraday reach.
The Nasdaq volatility index closed at 21.00, down 0.15, and the broad volatility index at 15.08, up 0.07, per the provider's quotes.
4.1 Mag7 Earnings and AI Capex Cycle
The equities feed carried a software maker's product event between 1:15 PM ET and 1:57 PM ET, including execution containers for software agents, a coding model that runs on laptops and personal computers built on a chipmaker's processors that begin reaching customers next week, and an artificial-intelligence developer's release of a new model at 2:03 PM ET. These are statements carried by the news feed and not measured effects. The captured calendars carry no mega-capitalisation earnings entry for Thursday; large bank earnings begin on Tuesday, October 13, 2026, as the calendar lists it.
4.2 Semiconductor Cycle and Tech Sector Rotation
The semiconductor index closed at 13,066.15, down 151.67 points or 1.15 percent, after a session range of 12,864.94 to 13,082.11, per the provider's quote, so chipmakers lagged the Nasdaq-100 cash index's 0.21 percent decline. No single-stock breadth series was captured, so no rotation claim beyond the index comparison is made.
4.3 Fed Policy and Real Yields (Duration Sensitivity)
The minutes of the September policy meeting were released at 2:00 PM ET on Wednesday, October 7, 2026, as the calendar lists it, and provider commentary said most policymakers judged another rate increase by year-end appropriate. The ten-year yield index closed at 5.27 percent, up one basis point, after a session high of 5.36 percent, and a ten-year note auction stopped at 5.300 percent, per the news-feed calendar and unconfirmed, the highest auction yield since November 2000 per the news feed. A regional survey of one-year inflation expectations printed 3.9 percent at 11:00 AM ET, per the news-feed calendar and unconfirmed. No priced policy probability was captured.
4.4 Geopolitical Backdrop
The news feed carried at 3:08 PM ET a press report that the White House is seeking strike options against Iran, at 3:41 PM ET a maritime security notice of a tanker struck near Qatar, and between 4:35 PM ET and 4:37 PM ET a statement that Iran and Oman agreed coordinates for safe transit routes through the Strait of Hormuz. A post-close wrap on the feed said the record-setting rally halted as high oil prices raised inflation concerns. These are statements carried by the news feed and were not confirmed.
4.5 Cross-Asset and Volatility
The dollar index rose 0.40 percent to 102.24. November crude settled at 88.28, down 1.16, and December gold at 4,140.7, down 46.4. The S&P 500 cash index closed at 7,801.77, down 0.22 percent. The measured closing basis, the December settlement of 31,402.25 less the 31,160.08 cash close, both from the provider for the completed session, is 242.17 points, against 258.78 on Tuesday.
4.6 Institutional Positioning
No weekly positioning report figure was captured for the Nasdaq contract, so no positioning change is asserted. Wednesday's volume was 500,010 contracts against Tuesday's 478,622. The open-interest column on the daily record shows 281,627 on Wednesday's 2026-10-07 row, the same figure the record carried for Tuesday before revision (Tuesday's 2026-10-06 row now reads 282,834), so the column appears lagged one session and no open-interest change is asserted.
5. QQQ Options Flow Context (Proxy)
The desk note read for this section is the 6:21 PM ET edition for Wednesday, read at about 8:38 PM ET. Its reference prices are the prior session's closes, not Wednesday's: NDX 31,224 equals Tuesday's 31,224.47 cash close and QQQ 759 equals Tuesday's 759.66 fund close, so every level below is read against Wednesday's 31,160.08 cash close and not against the reference column.
On the Nasdaq-100 index the primary call side ceiling and the largest gamma concentration both sit at NDX 31,500, the modeled volatility threshold at NDX 30,990, the modeled gamma-flip level at NDX 30,449 and the primary put side support base at NDX 30,200. The 31,160.08 cash close sits 339.92 points beneath the 31,500 ceiling, 170.08 points above the threshold and 711.08 points above the flip level. The note lists NDX 31,500, 31,000, 30,000 and 32,000 as key strikes. Gamma tilt reads 1.893 for the index and 1.174 for the fund, and gamma notional reads plus 17.11 million for the index and plus 387.989 million for the fund.
On the QQQ proxy the primary call side ceiling and the largest gamma concentration sit at 760, the modeled volatility threshold at 759, the modeled gamma-flip level at 752 and the primary put side support base at 700. The fund's positioning console, marked as updated 2026-10-07, showed a 758.18 quote, beneath the 759 threshold and above the 752 flip level, with call gamma of minus 723 million against put gamma of minus 2.5 billion and 12.59 percent of gamma attributed to the nearest expiration. The console's high and low volatility point fields are treated as low-confidence and excluded.
At the measured closing basis of 242.17 points, the December settlement of 31,402.25 less the 31,160.08 cash close, NDX 31,500 corresponds to 31,742.17 on the December contract, the modeled volatility threshold at NDX 30,990 to 31,232.17, the modeled gamma-flip level at NDX 30,449 to 30,691.17 and NDX 30,200 to 30,442.17. These are conversions made by this review; the source publishes no Nasdaq futures pair, and the modeled threshold and flip level are model outputs, not option strikes.
The note's narrative said the S&P 500 and the Nasdaq pulled back from all-time highs, that semiconductors fell about 1 percent and software about 1 percent while memory shares rose about 1 percent, and that the S&P 500 hedging-flow measure finished at plus 12 billion dollars of delta, mostly from same-day put selling. In this review's interpretation positive index gamma above the flip level argues for contained ranges, while a December price beneath the 31,232.17 threshold equivalent leaves the contract in the less dampened zone, which the setup in section 8 accounts for.
6.1 Night Session (6:00 PM ET Wednesday to 3:00 AM ET Thursday, Globex and Asia)
The contract reopened at 6:00 PM ET Wednesday with the minutes and the 4:37 PM ET Hormuz transit statement already released. Japanese current account data are listed at 7:50 PM ET, per the news-feed calendar and unconfirmed. Bias neutral above the 31,355.42 Pivot Point, expected Globex band roughly 31,250 to 31,520 absent a headline shock.
6.2 London Session (3:00 AM to 8:00 AM ET Thursday)
A Federal Reserve governor speaks on the economic outlook at 4:30 AM ET on Thursday, October 8, 2026, as the calendar lists it, and the European Central Bank's meeting account is listed at 7:30 AM ET, per the news-feed calendar and unconfirmed. Expected band roughly 31,190 to 31,570.
6.3 Morning Session (9:30 AM to 12:00 PM ET Thursday, RTH Open)
Weekly jobless claims are listed at 8:30 AM ET, per the news-feed calendar and unconfirmed, before the cash open at 9:30 AM ET, and wholesale inventories follow at 10:00 AM ET on Thursday, October 8, 2026, as the calendar lists it. A regional Federal Reserve president is listed at 10:40 AM ET, per the news-feed calendar and unconfirmed. Expected band roughly 31,100 to 31,600, with Pivot S1 at 31,189.83 the first meaningful support.
6.4 Afternoon Session (12:00 PM to 4:00 PM ET Thursday)
A thirty-year bond auction is listed at 1:00 PM ET, per the news-feed calendar and unconfirmed, and the same regional Federal Reserve president is listed again at 1:40 PM ET, per the news-feed calendar and unconfirmed. Yields set the tone for the index on Wednesday. Expected band roughly 31,100 to 31,600.
6.5 Night Session Forward (6:00 PM ET Thursday)
Japanese household spending is listed at 7:30 PM ET Thursday, per the news-feed calendar and unconfirmed. The University of Michigan preliminary survey is listed at 10:00 AM ET on Friday, per the news-feed calendar and unconfirmed.
6.6 Expected Range (Thursday Full Session)
Low-range scenario: 31,250 to 31,520; Mid-range scenario (most likely): 31,100 to 31,620; High-range scenario: 30,950 to 31,850.
6.7 Most Likely Path
In this review's analyst judgment the most probable path holds the contract above Pivot S1 at 31,189.83, with a pullback into the 31,189.83 to 31,205.10 band of Pivot S1 and the 5-day settlement average weighted as a buying area, because the settle sits above every computed average, positive direction leads on the 9-day and 14-day directional systems and the composite reads 88 percent buy. A 14-day stochastic %K of 93.73 percent and a 9-day relative strength of 72.25 argue that upside extension beyond the 31,616.50 high needs a catalyst. The alternative that would invalidate this reading is a further rise in yields after the 1:00 PM ET thirty-year auction, per the news-feed calendar and unconfirmed, that takes the contract beneath one standard deviation support at 31,107.66 and toward Pivot S2 at 30,977.42.
7. Thursday Economic Calendar
The Thursday session reopened at 6:00 PM ET Wednesday. German trade data are listed at 2:00 AM ET Thursday, per the news-feed calendar and unconfirmed. A Federal Reserve governor speaks on the economic outlook at 4:30 AM ET on Thursday, October 8, 2026, as the calendar lists it. The European Central Bank's meeting account is listed at 7:30 AM ET and the Bank of England governor at 8:15 AM ET, both per the news-feed calendar and unconfirmed.
Weekly initial jobless claims are listed at 8:30 AM ET with a forecast of 200 thousand against 197 thousand, per the news-feed calendar and unconfirmed. The cash open is at 9:30 AM ET. Wholesale inventories are scheduled for 10:00 AM ET on Thursday, October 8, 2026, as the calendar lists it. A regional Federal Reserve president is listed at 10:40 AM ET and again at 1:40 PM ET, and a thirty-year bond auction at 1:00 PM ET, all per the news-feed calendar and unconfirmed. The captured calendars carry no mega-capitalisation earnings entry for Thursday.
Looking a week forward, large bank earnings begin before the open on Tuesday, October 13, 2026, as the calendar lists it, and the consumer price index for September is scheduled for 8:30 AM ET on Wednesday, October 14, 2026, as the calendar lists it. In this review's judgment the single first-order event for the Nasdaq-100 contract on Thursday is the 1:00 PM ET thirty-year bond auction, per the news-feed calendar and unconfirmed, because yields set the tone on Wednesday.
8. Primary Trade Setup
Direction: Long
Rationale: The settle sits above every average from the 5-day to the 200-day, positive direction leads on the 9-day and 14-day directional systems, and the composite reads 88 percent buy; a pullback into Pivot S1 at 31,189.83 and the 5-day settlement average at 31,205.10 offers a long with a defined risk point beneath one standard deviation support and Wednesday's low. The entry band sits just beneath 31,232.17, the December equivalent of the modeled volatility threshold at NDX 30,990, so a reclaim of that level after entry is part of the thesis. The six-session advance that ended Wednesday and a 14-day stochastic %K of 93.73 percent mean the setup is an analyst judgment that pullbacks stay shallow while yields stabilise, not a measured edge.
Entry Zone: 31,180 to 31,220
Stop Loss: 31,050 (beneath one standard deviation support at 31,107.66 and Wednesday's 31,143.00 low)
Target 1 (T1): 31,350 (5.42 beneath the Pivot Point at 31,355.42)
Target 2 (T2): 31,500 (9.11 beneath the published target price of 31,509.11)
Target 3 (T3, extended): 31,650 (above Pivot R1 at 31,567.83 and the 31,616.50 52-week high)
Risk-to-Reward: Approximately 1:1 to T1, 1:2 to T2, 1:3 to T3
Invalidation: A settle beneath Pivot S2 at 30,977.42 negates the thesis. Short of that, the edge is removed by acceptance beneath 31,107.66 and not by a touch, defined as two consecutive 30-minute closes beneath 31,107.66.
Macro override: A sharp rise in yields after the thirty-year auction or an escalation in the Gulf would invalidate the long in real time. In that scenario a gap beneath the 31,050 stop removes the setup, and Pivot S2 at 30,977.42 and three standard deviations support at 30,892.00 become the references within one 14-day average true range of 449.67 points.
Alternate setup: the session review states none.
Sources and methodology
This outlook is built from our session review of the December E-mini Nasdaq-100 contract, NQZ26, the December ’26 contract, prepared after Wednesday's close on October 7, 2026 for the Thursday, October 8 session. The contract was verified before any level was used: the daily chart's completed Wednesday bar equals the provider's settlement row for the December contract, the chart's current Thursday bar opened at 31,403.00, equal to the provider's day open, and the provider's published previous close of 31,402.25 equals the settlement, so chart and provider are on the same December contract. The Globex session reopened at 6:00 PM ET Wednesday, so the day high, day low and open on the provider's overview belong to the Thursday session and are not used as Wednesday's range. Wednesday's extremes are the completed-session inputs behind the published pivot ladder, back-solved from the outer pivot pairs, verified against all seven published rungs, and reproduced by the chart's daily bar and the settlement row. Only selected 30-minute bars were preserved: they place the high inside the 6:00 PM ET bar of Tuesday evening and the low inside the 9:30 AM ET bar, and the 31,238.00 and 31,254.75 closes of the 9:30 AM ET and 10:00 AM ET bars used to score the prior card come from the same chart record. No other order within Wednesday's session is stated.
The settlement averages were computed from the provider's 259-row daily settlement series, which excludes the incomplete Thursday row, and are shown to two decimals; their gaps from the settle are measured from the unrounded averages. That series also supplies the seven closes charted above. Volume and open interest come from the provider's daily record: the 2026-10-07 row reads volume of 500,010 contracts and open interest of 281,627, a column that appears lagged one session, and the 2026-10-06 row now reads volume of 478,622 and open interest of 282,834, where Wednesday's outlook carried 470,004 and 281,627 for Tuesday. The oscillator readings are cited as published. The crude, gold and two volatility-gauge percentages are computed from the provider's closes and stated changes. The 52-week high cited is Tuesday's 31,616.50. Every key level comes from published pivot arithmetic, published standard-deviation bands, published moving-average projections, settlement averages computed from the provider's daily record, or the completed-session extremes; the four positioning conversions are added. The desk note is the 6:21 PM ET edition for Wednesday, read at about 8:38 PM ET; its reference prices are Tuesday's closes and are used as such, and the fund console is marked as updated 2026-10-07. Cash-denominated levels are translated with the measured 242.17 point basis, the settlement against the 4:00 PM ET cash close; the modeled threshold and flip level are model outputs with no listed strike behind them. Scenario ranges, session bands and the path weighting are analyst judgment and carry no calibration. Items marked unconfirmed come from the news-feed calendar or press reports and were not matched on the calendar used for confirmed times, and every catalyst whose time had passed by the 6:17 PM ET start of collection is recorded as completed.
Wednesday’s outlook for this contract is here and the broad-index outlook for the same date is here. Outlooks for ES, NQ, GC and CL are collected on the market outlook page, and our forward trading record is on the performance statement.