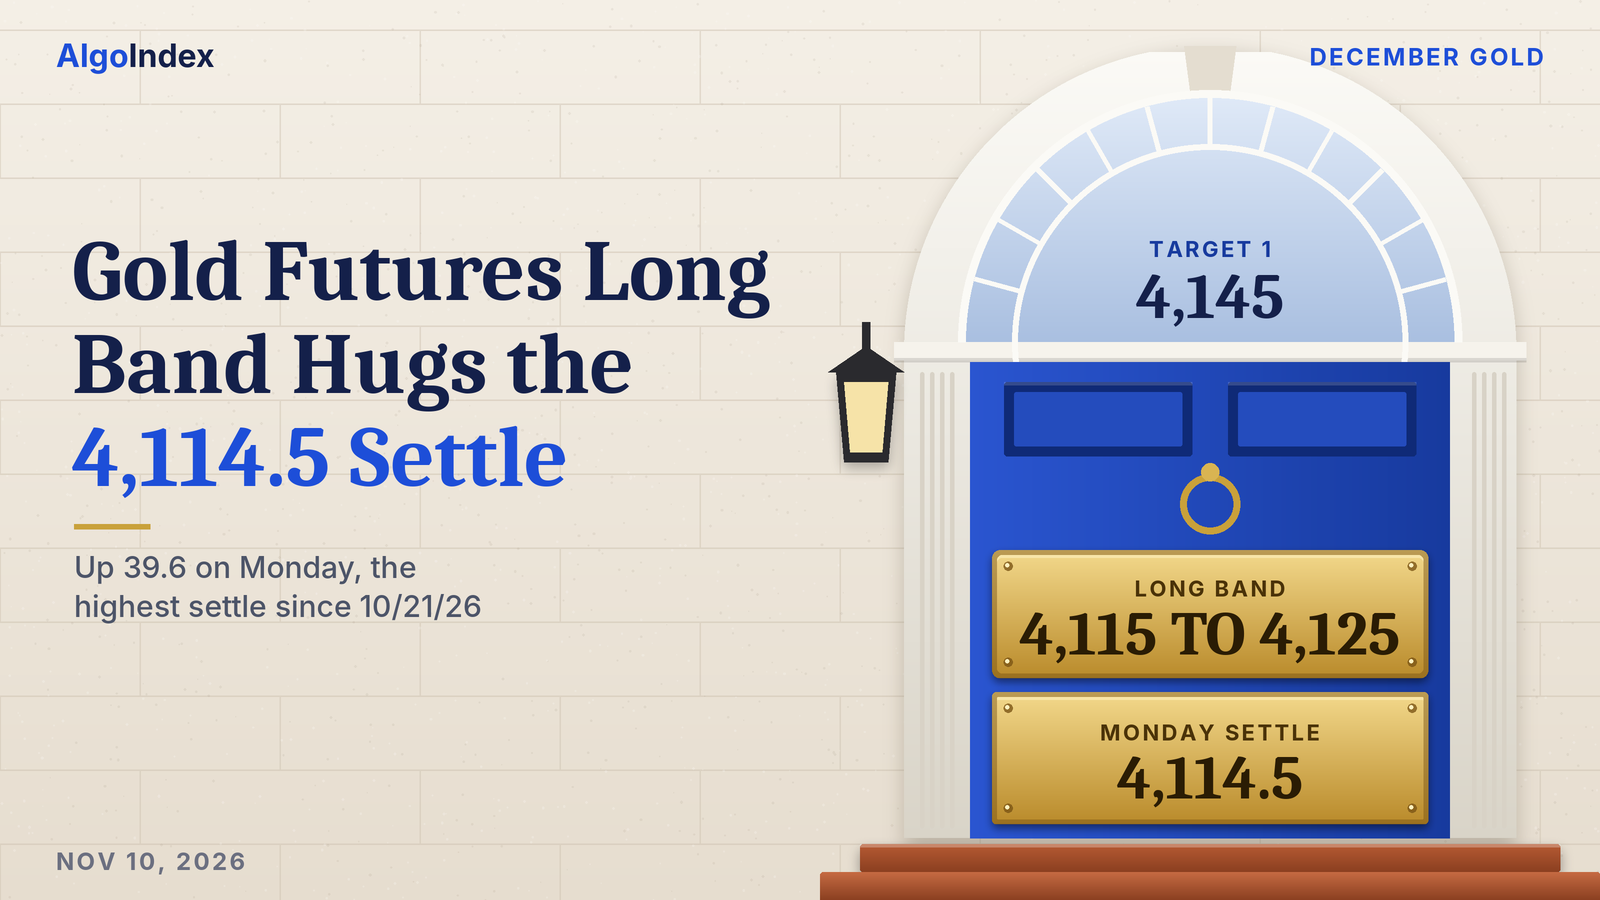
At 8:30 PM ET on Sunday, a 30-minute bar in December gold rose to 4,136.1. That went through the 4,135 stop on the short we had set for Monday. The 4,105 to 4,115 band had traded an hour earlier, in the 7:30 PM ET bar. No bar between them reached the 4,085 first target. The contract went on to a 4,157.7 high in the 3:00 PM ET bar and settled at 4,114.5, up 39.6 points, or 0.97 percent.
Monday printed a higher high and a higher low against Friday. The dollar index fell 0.64 percent to 101.65. The settle is back above the 20-day average and is the highest since 10/21/26. Tuesday's primary setup turns long, from 4,115 to 4,125. Its bottom sits 0.5 above the settle. The consumer price index is scheduled for 8:30 AM ET, as the calendar lists it.
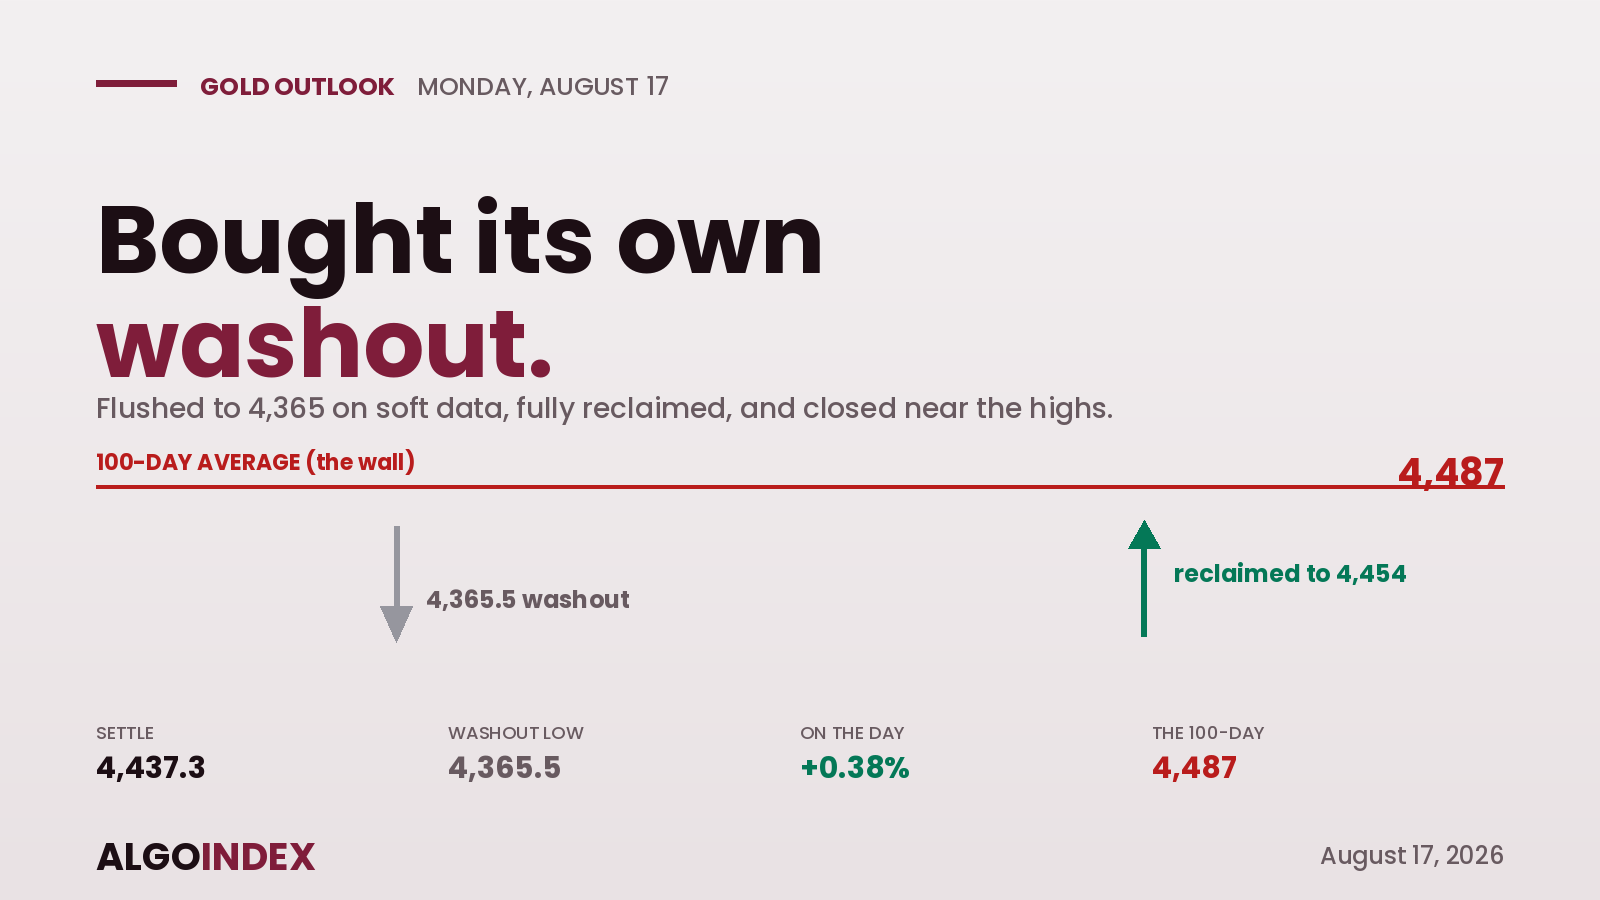
December gold settled at 4,114.5 on Monday, up 39.6 or 0.97 percent, after a 4,062.5 to 4,157.7 range, at 54.6 percent of that range. It sits above the 5-day, 9-day and 20-day averages. It sits beneath the 50-day at 4,222.1 and the longer averages. The primary setup for Tuesday is a long from 4,115 to 4,125, stop 4,095, with targets at 4,145, 4,170 and an extended 4,195. The band sits just above the settle, its bottom 0.5 above it, and all three targets sit above it. The composite reads "16% SELL" with strength "Minimum" and direction "Weakening". The consumer price index is scheduled for 8:30 AM ET on Tuesday, as the calendar lists it.
Monday traded the 4,105 to 4,115 short band, then its stop
In Monday’s outlook we set a short from 4,105 to 4,115 at Friday's settle, with a stop at 4,135 and targets at 4,085, 4,060 and an extended 4,035. The card covered Monday's whole session. Monday's bar, from the review and the dated 2026-11-09 row of the provider's daily record, opened at 4,074.3 at the Sunday 6:00 PM ET reopen. It marked a high of 4,157.7 and a low of 4,062.5 and settled at 4,114.5.
The first target printed first, without the band. The 6:00 PM ET bar fell to 4,065.7, through 4,085, while the band sat 30.7 points above the reopen. None of that counts for the card. The 6:30 PM ET bar made the 4,062.5 low, 2.5 above the 4,060 second target. Neither 4,060 nor the extended 4,035 traded at any point.
Then the band traded. The 7:30 PM ET bar rose 31.7, from 4,081.5 to 4,113.2, and its 4,114.8 high sat 9.8 inside the band. The 8:00 PM ET bar went through the 4,115 band top, to 4,121.2. Its 4,107.8 low stayed well above 4,085.
The stop followed. The 8:30 PM ET bar rose to 4,136.1, 1.1 above the 4,135 stop. It and the 9:00 PM ET bar closed at 4,132.9 and 4,137.3, the first two consecutive closes above 4,115, which is the card's acceptance test. We grade the card as written: the band traded, then the stop, before any target. No fill and no result is asserted.
The settle test never came into play. Monday settled at 4,114.5, 42.0 beneath the 4,156.5 Pivot R2 line and 0.5 beneath the band top. The 4,157.7 high went 1.2 above that line during the session. It went 7.9 above one standard deviation resistance at 4,149.8, the reference our macro override named.
The override named weekend headline risk or a softer dollar at the reopen. The contract reopened at 4,074.3, 0.6 beneath Friday's settle. The dollar index closed 0.64 percent lower on the day. The series here does not show the dollar's path at the reopen. The moves coincided with gold's gain, and no series here separates their effects.
The path call split. Our Monday outlook held the contract between Pivot S1 at 4,034.6 and Pivot R1 at 4,115.7. It weighted a rebound toward 4,103.6 to 4,115.7 that stalls beneath Pivot R1 above a settle through Friday's 4,116.2 high. The high went 42.0 through that Pivot R1. The settle held 1.2 beneath it and 1.7 beneath Friday's high.
Only the wider range cases held. The 4,157.7 high went 32.7 above the 4,125 top of the most likely case. It stayed 2.3 beneath the 4,160 top of the high-range case and 3.8 beneath the 4,161.5 top of the average-true-range envelope. The settle sat inside the most likely and high-range cases, 4.5 above the 4,110 top of the low-range case.
Every session band broke higher. From the reopen to 3:00 AM ET the contract traded from 4,062.5 to 4,143.3, 33.3 above the 4,110 top of the night band. London traded from 4,094.4 to 4,133.7, 23.7 above its 4,110 top. The morning ran 4,113.5 to 4,140.3 against 4,030 to 4,120. The afternoon ran 4,109.1 to 4,157.7 against 4,030 to 4,115.
One row anchors the score. The dated 2026-11-09 row reads 4,074.3, 4,157.7, 4,062.5 and 4,114.5 on 179,796 contracts, and the review states the same. Monday's open interest was not yet reported. Friday's 2026-11-06 row was revised. It now carries 178,024 contracts against the preliminary 166,431 our Monday outlook carried. Its open interest reads 255,460, which that outlook listed as not yet reported.
A Sunday-evening low, a high after the settle, and the levels around 4,115 to 4,125
The gain started on Sunday evening. The 6:30 PM ET bar made the 4,062.5 low and closed at 4,063.8. The 7:30 PM ET bar then rose 31.7, the largest gain of any 30-minute bar in the session. The 9:00 PM ET bar made the 4,143.3 high of the overnight window. The 2:30 AM ET bar fell 13.2, from 4,108.1 to 4,094.9. That was the largest decline of any bar, and its close ended the window.
The pre-open hours held a narrower span. From 3:00 AM ET to the 9:30 AM ET cash open the contract traded between 4,094.4 and 4,139.8. The 9:00 AM ET bar closed that window at 4,136.6. Across the cash hours the bars held between 4,109.1 and 4,157.7. The 12:30 PM ET bar made the 4,109.1 cash-hours low.
A quiet stretch carried the settle. The 1:30 PM ET bar closed at 4,113.1 as the settlement window fixed 4,114.5. The 2:00 PM ET bar closed at 4,119.5. The 2:30 PM ET bar rose 26.1 to 4,145.5. It contained a 2:38 PM ET news-feed item, a regional broadcaster's report, citing sources, on the terms of US and Iran diplomacy. The bar and the report coincided. The report is sourced and unconfirmed, and no cause is drawn from it. The 3:00 PM ET bar made the 4,157.7 high and closed at 4,153.9. The 4:30 PM ET bar closed at 4,149.5, 35.0 above the settle.
The four-hour bars show the shape. The first, from 6:00 PM ET, rose 54.7 to 4,129.0, the largest move. The rest read minus 13.2, minus 7.9, plus 22.2, minus 16.5 and plus 36.3. Their closes ran 4,129.0, 4,115.7, 4,107.6, 4,129.8, 4,113.1 and 4,149.5. The last block, from 2:00 PM ET, came after the settle.
The bar widened. Its 95.2 point range was 1.08 times the 14-day average daily range of 87.8, the widest since the 153.0 point range of 11/04. The settle finished at 54.6 percent of it, 52.0 above the low and 43.2 beneath the high. It sat 40.2 above the 4,074.3 open, which came 0.6 beneath Friday's settle. The high sat 41.5 above Friday's 4,116.2, and the low 27.4 above Friday's 4,035.1.
Swing lows turned up again. Since the 3,879.3 low of 10/30 they read 3,889.0, 3,904.1, 3,928.2 and 4,067.0 through Thursday. Friday's 4,035.1 was a lower low. Monday's 4,062.5 was a higher one. Its 4,157.7 high sits 1.9 above Thursday's 4,155.8. The settle sits 1.0 above Thursday's 4,113.5 and is the highest since the 4,150.0 settle of 10/21/26.
Resistance starts inside the setup band. Friday's 4,116.2 high and the 4,119.5 close of the 2:00 PM ET bar both sit in it. Above the 4,125 band top come the 4,136.6 close of the 9:00 AM ET bar, the 4,139.8 pre-open high and the 4,142.5 published target price. The 4,143.3 overnight high follows. The reopened session's 4,143.6 low and 4,149.0 open, read at 6:19 PM ET, sit just above it.
Among those prints sits the first target. At 4,145 it sits 0.5 beneath the 4,145.5 close of the 2:30 PM ET bar and 4.5 beneath the 4,149.5 close of the 4:30 PM ET bar. The 4,150.0 settle of 10/21 and the 4,150.1 price where the 3-day and 10-day crossover stalls follow. The 4,153.9 close of the 3:00 PM ET bar, Thursday's 4,155.8 high and Monday's 4,157.7 high cap that group. Pivot R1 at 4,160.6 and the 4,164.0 price that would cross the 40-day average come next. The second target, 4,170, sits 0.1 beneath the 4,170.1 price where the 18-day crossing stalls.
Higher up, one standard deviation resistance sits at 4,186.0. The extended 4,195 target sits 9.0 above it and 11.8 beneath Pivot R2 at 4,206.8, with the 4,201.7 average-true-range mark between them. The 4,213.8 retracement from the 13-week low and two deviations at 4,215.7 follow. The 50-day sits at 4,222.1, three deviations at 4,238.4, the one-month high at 4,242.3, the 100-day at 4,247.6 and Pivot R3 at 4,255.8. The 200-day sits at 4,564.5. The provider publishes 4,755.0 as the 13-week high and 5,781.8 as the 52-week high.
Support starts just beneath the settle. Thursday's 4,113.5 settle, the 4,113.2 close of the 7:30 PM ET bar and the 4,113.1 close of the 1:30 PM ET bar sit within 1.4 points of it. The Pivot Point at 4,111.6 and the 4,111.0 price for a 50 percent 14-day relative strength follow. Then come the 4,109.1 cash-hours low, the 4,108.1 open of the 2:30 AM ET bar and the 4,107.3 projection for an 80 percent raw stochastic. The 4,103.6 retracement from the four-week high sits 8.6 above the stop.
At 4,095 the stop sits just above Monday's prints. That is 0.1 above the 4,094.9 close of the 2:30 AM ET bar and 0.6 above the 4,094.4 pre-open low. Beneath it come the 4,081.5 open of the 7:30 PM ET bar, Friday's 20-day of 4,080.7, the 4,078.8 projection for a 70 percent raw stochastic and the 20-day at 4,076.9. Friday's 4,074.9 settle, Monday's 4,074.3 open and the 4,073.0 settle of 11/04 follow.
Lower, five marks sit within 6.2 points. They are Thursday's 4,067.0 low, Pivot S1 at 4,065.4, the 5-day at 4,063.3, Monday's 4,062.5 low and the 4,060.8 midpoint of the four-week range. One standard deviation support at 4,043.0 and Friday's 4,035.1 low come next. Friday's 5-day of 4,034.3, the 9-day at 4,029.8 and the 4,027.3 average-true-range mark sit beneath them.
Deeper down sit Pivot S2 at 4,016.4, two deviations at 4,013.3, three deviations at 3,990.6 and Pivot S3 at 3,970.2. The 3,969.6 settle of 11/02, the 3,940.4 settle of 11/03 and the lows of 3,928.2, 3,904.1 and 3,889.0 lead to the 3,879.3 low of 10/30. The provider publishes that as the 52-week, 13-week and one-month low.
The averages split around the settle. It sits 51.2 above the 5-day at 4,063.3, 84.7 above the 9-day at 4,029.8 and 37.6 above the 20-day at 4,076.9. It sits 107.6 beneath the 50-day at 4,222.1, 133.1 beneath the 100-day at 4,247.6 and 450.0 beneath the 200-day at 4,564.5. Monday's settle went back above the 20-day after one settle beneath it. It was the 34th straight settle beneath the 50-day. The last settle above it came on 09/22/26.
The 5-day rose 29.0 from 4,034.3 as Monday's settle replaced the 11/02 settle of 3,969.6. The 20-day eased 3.8 from 4,080.7. Older settlements explain the order. The 30 older ones in the 50-day window averaged 4,318.9, the 50 older ones in the 100-day window 4,273.1 and the 100 older ones in the 200-day window 4,881.4. The February contract's premium over December widened to 33.9 from 32.6.
Momentum sits near the midline. Relative strength reads 54.84 on the 9-day, 50.28 on the 14-day and 47.93 on the 20-day. The raw stochastics read 84.48 percent on the 9-day, 82.53 percent on the 14-day and 68.08 percent on the 20-day. The 14-day %K at 73.09 percent sits 11.09 above %D at 62.00 percent. Direction splits. On the 9-day positive direction leads, 25.62 against 21.18, with the ADX at 29.95. On the 14-day negative direction leads narrowly, 22.70 against 21.77, with the ADX at 26.42. Historic volatility reads 28.56 percent on the 9-day and 25.84 percent on the 14-day. These are the provider's published readings, read at 6:19 PM ET on Monday after the Globex reopen. They may include the live price of the reopened session.
The composite sell reading halved. Published on Monday evening, on a page titled for Tuesday, it reads "16% SELL", with strength "Minimum" and direction "Weakening". The prior session read "32% SELL", a week ago "88% SELL" and a month ago "64% SELL". The short-term group reads "40% BUY", the medium-term "25% SELL" and the long-term "67% SELL". The trend composite reads "SELL".
Over five sessions the contract is up 144.9 from the 3,969.6 settle of 11/02. The provider also publishes that as a 3.65 percent five-day change. Settlements over six sessions ran 3,969.6, 3,940.4, 4,073.0, 4,113.5, 4,074.9 and 4,114.5. Monday recovered Friday's decline. Its settle sits 174.1 above the 11/03 settle. Changes over ten sessions ran plus 36.2, minus 23.0, minus 20.2, minus 132.5, plus 70.7, minus 29.2, plus 132.6, plus 40.5, minus 38.6 and plus 39.6. Daily ranges ran 77.8, 60.3, 65.4, 158.9, 91.8, 77.6, 153.0, 88.8, 81.1 and 95.2 points.
The 14-day average true range stands at 87.2 points, with the 14-day average daily range at 87.8. The 9-day figures are 89.2 and 96.9, and the 20-day 87.8 and 80.7. One average true range either side of the settle spans 4,027.3 to 4,201.7. The deviation bands are built from five settlements. They run 4,043.0 to 4,186.0, 4,013.3 to 4,215.7 and 3,990.6 to 4,238.4, and describe dispersion, not intraday reach. The inflation data at 8:30 AM ET adds event risk that a single-session band does not reflect.
The dollar fell 0.64 percent and gold rose 0.97 percent
The dollar softened. The dollar index's daily record closed at 101.65, down 0.64 percent from 102.30. The ten-year yield index closed at 4.86 percent, up one basis point from 4.85 percent. Gold rose 0.97 percent across the same session. The moves coincided, and no series here separates their effects. Inflation-protected real yields were not available for this review.
Commentary ran alongside. A macro-feed headline at 3:30 PM ET said gold topped 4,100 dollars despite Fed rate-increase expectations as the decline in oil weighed on the dollar, which is attributed commentary. The provider's commentary quoted a Federal Reserve official as saying inflation is starting to kick up in services. It quoted another as saying rates would need to go higher at a careful pace. It put the market-implied chance of a quarter-point increase at the next policy meeting at 83 percent, attributed commentary and not a probability computed for this review. At 2:00 PM ET the macro feed carried a headline that the second official saw rates near neutral and offered no December signal.
Monday's data were light. Wholesale trade data was released at 10:00 AM ET, as the calendar lists it. The provider's commentary put September wholesale trade sales up 2.8 percent against an expected 1.1 percent. At 3:15 PM ET the news feed reported a three-year note auction yield of 4.627 percent against 4.932 percent previously, a feed item unconfirmed against the calendar.
Headline risk on diplomacy runs into Tuesday. The 2:38 PM ET item was a regional broadcaster's report, citing sources, on the terms of US and Iran diplomacy, and it remains unconfirmed. A tentative diplomatic meeting on Russia and Ukraine, per the news-feed calendar, is listed for Tuesday.
Equities rose and crude fell. The S&P 500 cash index rose 2.35 percent to 7,549.94 and the Nasdaq-100 3.40 percent to 27,907.63. The semiconductor index rose 6.85 percent to 10,033.93. The volatility index closed at 19.92. December crude fell 4.38 percent to 86.85 and January Brent 5.85 percent to 92.57. These moves coincided with gold's gain, and no series separates their effects.
Silver rose more. Its December contract rose 1.45 percent to 52.693, so the gold-to-silver ratio eased to 78.08 from 78.45.
No structural demand figure was available. The feeds for Monday carried no central-bank purchase figures and no fund-holdings data. The latest weekly positioning report covers the week to Tuesday, November 3, 2026. It shows managed money at 122,283 long, down 225, against 18,669 short, up 1,723, as listed on the provider's overview and not recomputed. Monday's December volume was 179,796 contracts against a revised 178,024 on Friday, up 1,772 or 1.0 percent. Open interest stood at 255,460 on Friday 11/06 against 260,278 on Thursday 11/05, down 4,818. Monday's open interest was not yet reported.
The fund console comes next. The gold fund's options console was read at 6:23 PM ET on Monday, after the close, with a page date of 2026-11-09; every figure below is that evening read. The fund is a proxy, used qualitatively only and never translated into futures prices. It tracks bullion at a different scale with a fee drag and has no clean basis to the December contract. The console carried Friday's 372.55 as its previous close. It showed a current price of 379.40, up 1.84 percent, a console reading and not a settlement.
Modeled call gamma read minus 541.83 million against put gamma of minus 486.31 million on the proxy. Modeled gamma on a proxy is a non-directional lens. Call volume of 114.36 thousand against put volume of 98.45 thousand and a put-to-call open-interest ratio of 0.5 show calls ahead of puts in the day's volume and open interest, an observation only. Options volume says nothing about direction or demand. One-month implied volatility read 23.07 percent against realised volatility of 24.42 percent, 1.35 points beneath it. The implied-volatility rank read 20.49 percent and the skew rank 25.60 percent. The options-implied move was 5.42 dollars, about 1.43 percent of the 379.40 current price.
The console's largest call concentration sits at 400 on the fund's own scale and its put-side support base at 350, both well away from the fund's price. Its high and low volatility point fields are excluded. These readings were taken after the close, so there is no reading of what options priced before or during Monday's session, and no inference about that is drawn. No fund figure sets a futures level here.
The trade map for Tuesday
The primary setup is a long. Its band runs 4,115 to 4,125, just above the settle: the bottom sits 0.5 above 4,114.5 and the top 10.5 above it. The band sits 3.4 above the Pivot Point at 4,111.6. It holds Friday's 4,116.2 high and the 4,119.5 close of the 2:00 PM ET bar. The contract printed a higher high and a higher low and settled back above the 20-day average, at its highest since 10/21/26. Positive direction leads on the 9-day system. The 4,149.0 reopen print sits 24.0 above the band top. The long needs a pullback from there first.
Risk sits beneath the Pivot Point. The 4,095 stop sits 19.5 beneath the settle, 16.6 beneath the Pivot Point and 8.6 beneath the 4,103.6 retracement. It sits 16.2 above the 4,078.8 projection. Targets step up. The first, 4,145, sits 30.5 above the settle and 4.5 beneath the 4,149.5 close of the 4:30 PM ET bar. Then comes 4,170, 9.4 above Pivot R1 at 4,160.6 and 0.1 beneath the 4,170.1 stall. The extended 4,195 sits 9.0 above one standard deviation resistance at 4,186.0 and 11.8 beneath Pivot R2 at 4,206.8. The review names the main risks. They are the 50-day average overhead and an inflation print that firms the dollar. So the review calls the setup an analyst judgment that pullbacks toward the Pivot Point at 4,111.6 are bought, with no measured edge behind it.
The night session runs from the 6:00 PM ET reopen on Monday to 3:00 AM ET Tuesday. The overview showed a 4,149.0 open, 34.5 above the settle and 0.5 beneath the 4,149.5 close of the 4:30 PM ET bar. Headline risk on diplomacy is the main overnight exposure. The review's night bias is neutral to higher above the Pivot Point at 4,111.6. Its expected band runs roughly 4,125 to 4,165. Its bottom meets the band top.
European trading opens at 3:00 AM ET. Remarks by a Federal Reserve official are scheduled for 4:00 AM ET, as the calendar lists it. The review's London bias is neutral between the Pivot Point at 4,111.6 and Pivot R1 at 4,160.6. Its band runs roughly 4,115 to 4,165.
Data arrive at 8:30 AM ET. The consumer price index is scheduled then, with real earnings, as the calendar lists it. The news-feed calendar lists forecasts of 0.3 percent for the monthly headline index, against 0.6 percent previously. The same news-feed calendar lists 0.2 percent for the monthly core, against 0.3 percent. Remarks by a Federal Reserve official at 10:50 AM ET are listed by the news-feed calendar, unconfirmed. The morning band runs roughly 4,095 to 4,175. The setup band sits inside it, beneath the reopen print.
Gold settles at 1:30 PM ET, fixing the reference ahead of the Veterans Day holiday on Wednesday. A ten-year note auction at 1:00 PM ET and remarks by a Federal Reserve official at 1:30 PM ET are listed by the news-feed calendar, unconfirmed. Remarks by a Federal Reserve official are scheduled for 3:30 PM ET, as the calendar lists it, with a second appearance at 6:30 PM ET. The afternoon band runs roughly 4,100 to 4,175. Globex keeps normal hours on the holiday, per the calendar's exchange notice. The producer price index follows at 8:30 AM ET on Friday, November 13, 2026, as the calendar lists it.
For the full session the review sets a low-range case of 4,120 to 4,165 and a high-range case of 4,060 to 4,210. Its mid-range case, the most likely, runs 4,100 to 4,180. The low-range bottom sits inside the entry band, 5.0 beneath its top. The high-range top sits 8.3 above the 4,201.7 average-true-range mark.
One path is weighted. In the review's analyst judgment the most probable path holds the contract above the Pivot Point at 4,111.6 and tests Pivot R1 at 4,160.6. Within it, a pullback toward the 4,115 to 4,125 band that holds above the Pivot Point is weighted above a settle beneath it. No measured frequency backs it. In the review's interpretation, the higher high and higher low, the settle back above the 20-day, the composite's move to "16% SELL" from "32% SELL" and positive direction on the 9-day system favour a long on a pullback over a long at the extension after the settle. The 50-day, 100-day and 200-day averages sit overhead.
The alternative that would invalidate the reading is a settle beneath Pivot S1 at 4,065.4. That could bring Monday's 4,062.5 low and Friday's 4,035.1 low into play. On the other side, a softer inflation print and a weaker dollar could carry the contract through Pivot R1 at 4,160.6 toward Pivot R2 at 4,206.8, without the pullback the setup needs.
Monday's short band traded ninety minutes after the reopen. Tuesday's long band starts half a point above the settle.
The complete data picture
Every number behind Tuesday’s plan, charted first, then the full level lists, then the complete numeric reference underneath.
Full numeric reference, every remaining figure from the session review
1. Executive Summary
The December gold contract settled at 4,114.5 on Monday, up 39.6 or 0.97 percent from Friday's settle of 4,074.9, after trading between 4,157.7 and 4,062.5, a 95.2 point daily range. The settle finished at 54.6 percent of the range, and the range was 1.08 multiples of the 14-day average daily range of 87.8 points. Monday printed a higher high, 41.5 above Friday's 4,116.2, and a higher low, 27.4 above Friday's 4,035.1. The settle is the highest since 10/21/26, when the contract settled at 4,150.0, and the 95.2 point range is the widest since the 153.0 point range of 11/04/26. Over five sessions the contract is up 144.9 from the 3,969.6 settle of 11/02/26, a gain of 3.65 percent.
The low came in the first hour of the Sunday evening session and the high after the settlement. The contract made the 4,062.5 low in the 6:30 PM ET bar on Sunday, the 7:30 PM ET bar rose 31.7, the largest gain of any 30-minute bar in the session, and the contract held between 4,094.4 and 4,139.8 from 3:00 AM ET to the 9:30 AM ET cash open. After the 1:30 PM ET settlement window the 2:30 PM ET bar rose 26.1 to 4,145.5, a bar that contained a 2:38 PM ET news-feed item, a regional broadcaster's report, citing sources, on the terms of US and Iran diplomacy, and the 3:00 PM ET bar made the 4,157.7 high; the move and the item coincided, and the item is a sourced, unconfirmed report from which no cause is drawn.
The dollar index closed at 101.65, down 0.64 percent, and the ten-year yield index at 4.86 percent, up one basis point. December crude fell 4.38 percent to 86.85, silver's December contract rose 1.45 percent and the S&P 500 cash index rose 2.35 percent. A macro-feed headline at 3:30 PM ET said gold topped 4,100 dollars despite Fed rate-increase expectations as the decline in oil weighed on the dollar, which is attributed commentary.
The composite multi-indicator read published on Monday evening is "16% SELL" with strength "Minimum" and direction "Weakening", against "32% SELL" a session earlier. The settle sits above the 5-day, 9-day and 20-day settlement averages and beneath the 50-day, 100-day and 200-day, back above the 20-day after one settle beneath it. The Primary Setup in section 8 is a long from the 4,115 to 4,125 band, above the Pivot Point at 4,111.6 and the 4,114.5 settle, stopped at 4,095, with objectives at 4,145, 4,170 and an extended 4,195. The consumer price index is scheduled for 8:30 AM ET on Tuesday, November 10, 2026, as the calendar lists it.
2. Price Action & Technical Structure
2.1 Intraday and Session Review
The Monday session opened at 4,074.3 at the Sunday 6:00 PM ET reopen, 0.6 beneath Friday's settle, and the 30-minute series for the continuous contract places the low of 4,062.5 in the 6:30 PM ET bar on Sunday and the high of 4,157.7 in the 3:00 PM ET bar on Monday. Between the 6:00 PM ET reopen and 3:00 AM ET the bars held between 4,062.5 and 4,143.3, with the 9:00 PM ET bar making the high of that window; the 7:30 PM ET bar rose 31.7, from 4,081.5 to 4,113.2, the largest gain of any 30-minute bar, and the 2:30 AM ET bar fell 13.2, from 4,108.1 to 4,094.9, the largest decline of any 30-minute bar, closing that window.
From 3:00 AM ET to the 9:30 AM ET cash open the contract traded between 4,094.4 and 4,139.8, and the 9:00 AM ET bar closed that window at 4,136.6. Across the cash hours, from 9:30 AM ET to 4:00 PM ET, the bars held between 4,109.1 and 4,157.7. The 12:30 PM ET bar made the 4,109.1 low of that window, and the 1:30 PM ET bar closed at 4,113.1 as the 1:30 PM ET settlement window fixed the 4,114.5 settle. The 2:00 PM ET bar closed at 4,119.5, the 2:30 PM ET bar rose 26.1 to 4,145.5, and the 3:00 PM ET bar made the 4,157.7 high and closed at 4,153.9. The 4:30 PM ET bar closed at 4,149.5, 35.0 above the settle.
The provider's overview page, read at 6:19 PM ET, is titled for Tuesday, November 10, 2026, and its open of 4,149.0, high of 4,149.0 and low of 4,143.6 belong to the Globex session that reopened at 6:00 PM ET on Monday, not to Monday's completed session; its previous close field reads 4,114.5. Monday's completed range is instead recovered from the published pivot ladder. Pivot R3 at 4,255.8 minus Pivot S3 at 3,970.2, divided by three, returns 95.2, and Pivot R2 at 4,206.8 minus Pivot S2 at 4,016.4, divided by two, returns the same 95.2. Three times the Pivot Point of 4,111.6 less the 4,114.5 settle gives a high plus low sum of 8,220.3, which with the 95.2 range solves to a high of 4,157.75 and a low of 4,062.55, which at the one-decimal rounding of the published Pivot Point at 4,111.6 correspond to 4,157.7 and 4,062.5; that pair reproduces all seven published rungs. These are the completed-session inputs behind the published pivot ladder, and they are corroborated by the provider's settlement row, the chart's completed daily bar and the 30-minute series, which carry the same 4,074.3 open, 4,157.7 high, 4,062.5 low and 4,114.5 settle.
2.2 Daily Structure
Monday printed a higher high and a higher low against Friday and settled 39.6 higher, recovering Friday's 38.6 point decline. Settlements over the last six sessions read 3,969.6, 3,940.4, 4,073.0, 4,113.5, 4,074.9 and 4,114.5, so Monday's settle sits 1.0 above Thursday's 4,113.5 and 174.1 above the 3,940.4 settle of 11/03. Over five sessions the contract is up 144.9 from the 3,969.6 settle of 11/02, which the provider also publishes as a 3.65 percent five-day change.
The settle is the highest since the 4,150.0 settle of 10/21/26. The provider publishes 5,781.8 as the 52-week high, 4,755.0 as the 13-week high, 4,242.3 as the one-month high and 3,879.3 as the 52-week, 13-week and one-month low. The settle sits 10.9 above the 4,103.6 level published as the 38.2 percent retracement from the four-week high and 99.3 beneath the 4,213.8 level published as the 38.2 percent retracement from the 13-week low.
2.3 4-Hour and Swing Structure
Daily ranges for the last ten sessions, from 10/27, ran 77.8, 60.3, 65.4, 158.9, 91.8, 77.6, 153.0, 88.8, 81.1 and 95.2, so Monday's range expanded after two narrower sessions and was the widest since 11/04/26. In the 30-minute series no bar moved more than 31.7 from open to close.
The swing sequence since the 3,879.3 low of 10/30 shows higher lows at 3,889.0, 3,904.1, 3,928.2 and 4,067.0 through Thursday, a lower low at 4,035.1 on Friday and a higher low at 4,062.5 on Monday, while Monday's 4,157.7 high sits 1.9 above Thursday's 4,155.8. The published grid places the 18-day average crossing stall at 4,170.1, the 40-day average crossing at 4,164.0 and the 3-10 day average crossover stall at 4,150.1.
2.4 Moving Averages
The averages cited here were computed for this review from the provider's daily settlement series for the December contract, which holds 259 completed sessions from 10/29/25 through Monday; the partial row dated Tuesday, opened by the 6:00 PM ET Globex reopen, was excluded before counting, and each average is carried at full precision and rounded once to the tenth. The 5-day average stands at 4,063.3, the 9-day at 4,029.8, the 20-day at 4,076.9, the 50-day at 4,222.1, the 100-day at 4,247.6 and the 200-day at 4,564.5.
The 4,114.5 settle sits 51.2 above the 5-day average, 84.7 above the 9-day and 37.6 above the 20-day, and 107.6 beneath the 50-day, 133.1 beneath the 100-day and 450.0 beneath the 200-day. It is back above the 20-day average after Friday's settle beneath it, and it is the 34th consecutive settle beneath the 50-day average, the last settle above it coming on 09/22/26. The 5-day average rose from Friday's 4,034.3 as Monday's settle replaced the 11/02 settle of 3,969.6, and the 20-day average eased from 4,080.7.
The 20-day average sits beneath the 50-day because the 30 older settlements in the 50-day window averaged higher, at 4,318.9. The 50-day sits beneath the 100-day because the 50 older settlements in the 100-day window averaged higher, at 4,273.1, and the 100-day sits beneath the 200-day because the 100 older settlements in the 200-day window averaged higher, at 4,881.4.
2.5 Oscillator and Trend Readings
The oscillator figures below are as published on the provider's technical page, read at 6:19 PM ET on Monday after the Globex reopen, so they may include the live price of the reopened session; they are the provider's readings, not computations made for this review. The 9-day relative strength reads 54.84, the 14-day relative strength 50.28 and the 20-day relative strength 47.93.
The 9-day raw stochastic reads 84.48 percent, the 14-day 82.53 percent and the 20-day 68.08 percent, while the 14-day stochastic %K reads 73.09 percent and the 14-day stochastic %D 62.00 percent. The 9-day directional index ADX reads 29.95 with the 9-day +DI at 25.62 and the 9-day -DI at 21.18, and the 14-day directional index ADX reads 26.42 with the 14-day +DI at 21.77 and the 14-day -DI at 22.70, so positive direction leads on the 9-day system and negative direction narrowly on the 14-day. The 9-day historic volatility reads 28.56 percent and the 14-day historic volatility 25.84 percent.
The composite multi-indicator read published on Monday evening, on a page titled for Tuesday, November 10, 2026, is "16% SELL", with signal strength "Minimum" and direction "Weakening". The snapshot history reads "32% SELL" for the prior session, "88% SELL" a week ago and "64% SELL" a month ago. The short horizon group averages "40% BUY", the medium group "25% SELL" and the long group "67% SELL", and the trend composite reads "SELL".
2.6 Volatility and Expected Range
The published 14-day average true range stands at 87.2 points and the 14-day average daily range at 87.8 points; the 9-day average true range is 89.2 with a 9-day average daily range of 96.9, and the 20-day average true range is 87.8 with a 20-day average daily range of 80.7. Monday's 95.2 point range was 1.08 multiples of the 14-day average daily range.
Adding and subtracting the 14-day average true range of 87.2 from the 4,114.5 settle frames Tuesday between 4,027.3 and 4,201.7. The published standard-deviation bands, built from five settlements, span 4,043.0 to 4,186.0 at one deviation, 4,013.3 to 4,215.7 at two and 3,990.6 to 4,238.4 at three. These bands describe dispersion, not intraday reach, and the inflation data at 8:30 AM ET adds event risk that a single-session band does not reflect.
3. Key Levels
3.1 Resistance
Above the 4,114.5 settle, the first references are the 4,142.5 published target price, the 4,149.5 close of the 4:30 PM ET bar and the 4,150.1 stall of the 3-10 day average crossover. Monday's 4,157.7 high, Pivot R1 at 4,160.6 and the 4,164.0 price that would cross the 40-day average form the next band, with the 4,170.1 stall of the 18-day crossing just above. One standard deviation resistance at 4,186.0, Pivot R2 at 4,206.8 and the 4,213.8 retracement from the 13-week low follow.
3.2 Support
Beneath the settle sits the Pivot Point at 4,111.6, with the 4,111.0 price for a 50 percent 14-day relative strength and the 4,107.3 projection for the 80 percent raw stochastic beside it, and the 4,103.6 retracement from the four-week high beneath. The 4,078.8 projection for the 70 percent raw stochastic, the 20-day average at 4,076.9, Pivot S1 at 4,065.4, Monday's 4,062.5 low and the 4,060.8 midpoint of the four-week range form the next band, with one standard deviation support at 4,043.0 and Friday's 4,035.1 low beyond.
4. Macro Drivers
4.1 Dollar and Real Yields
The dollar index's daily record closed at 101.65, down 0.64 percent, and the ten-year yield index closed at 4.86 percent, up one basis point on the session. Gold rose 0.97 percent across the same session. These moves coincided, and no series here separates their effects. At 3:15 PM ET the news feed reported a three-year note auction yield of 4.627 percent against 4.932 percent previously, a feed item unconfirmed against the calendar. Inflation-protected real yields were not available for this review.
4.2 Fed and Monetary Policy
The provider's commentary quoted a Federal Reserve official as saying inflation is starting to kick up in services and another as saying interest rates would need to go higher at a careful pace, and it put the market-implied chance of a quarter-point increase at the next policy meeting at 83 percent; that is attributed commentary, not a probability computed for this review. At 2:00 PM ET the macro feed carried a headline that the second official saw rates near neutral and offered no December signal, which is a feed headline. The consumer price index is scheduled for 8:30 AM ET on Tuesday, November 10, 2026, as the calendar lists it, with the news-feed calendar listing forecasts of 0.3 percent for the monthly headline index and 0.2 percent for the monthly core index.
4.3 Geopolitical Backdrop
At 2:38 PM ET the market-moving feed carried a regional broadcaster's report, citing sources, on the terms of US and Iran diplomacy; that is a sourced report and unconfirmed. A tentative diplomatic meeting on Russia and Ukraine, per the news-feed calendar, is listed for Tuesday, November 10, 2026, unconfirmed. Headline risk on diplomacy carries into the Tuesday session.
4.4 Structural Demand
The feeds available for Monday carry no central-bank purchase figures and no fund-holdings data.
4.5 Energy and Cross-Asset
December crude fell 4.38 percent to 86.85. Brent's January contract fell 5.85 percent to 92.57. The S&P 500 cash index rose 2.35 percent, the Nasdaq-100 3.40 percent and the semiconductor index 6.85 percent, and the volatility index closed at 19.92. Silver's December contract rose 1.45 percent to 52.693, so the gold to silver ratio eased to 78.08 from 78.45. These moves coincided with gold's gain, and no series here separates their effects.
4.6 Institutional Positioning
The latest weekly positioning report, for the week to Tuesday, November 3, 2026, shows managed money at 122,283 long, down 225, against 18,669 short, up 1,723, as listed on the provider's overview and not recomputed. Exchange-traded fund holdings were not available for this review. Monday's December volume was 179,796 contracts against 178,024 on Friday, per the settlement record; Friday's figure is the revised one, against the preliminary 166,431 in our Monday outlook. Friday's open interest reads 255,460 in the revised 2026-11-06 row, and Monday's open interest is not yet reported. February's premium over December widened to 33.9 from 32.6.
5. Gold Fund Options Context (Proxy)
The gold fund's options console was read at 6:23 PM ET on Monday, after the close, with a page date of 2026-11-09; every figure in this section is that evening read. The fund proxy is used qualitatively only and is never translated into futures prices; the fund tracks bullion at a different scale with a fee drag and has no clean basis to the December contract.
The console carried Friday's 372.55 as its previous close and showed a current price of 379.40, up 1.84 percent, which is a console reading and not a settlement. Modeled call gamma reads minus 541.83 million against put gamma of minus 486.31 million. Call volume of 114.36 thousand against put volume of 98.45 thousand and a put-to-call open-interest ratio of 0.5 show calls ahead of puts in the day's volume and open interest, an observation only; options volume is never a direction or demand read.
One-month implied volatility reads 23.07 percent against realised volatility of 24.42 percent, the implied-volatility rank 20.49 percent and the skew rank 25.60 percent, with an options-implied move of 5.42 dollars. The console's largest call concentration sits at 400 on the fund's own scale and its put-side support base at 350, both well away from the fund's price; its high and low volatility point fields are excluded.
These are readings taken after the close and describe the fund's options surface at that time only; no inference is drawn about what options priced before or during Monday's session. Nothing in this section is used to set a futures level; every level in this review originates in published pivot arithmetic, published standard-deviation bands, published retracement and moving-average projections, settlement averages computed from the provider's daily record, or the completed-session extremes described in section 2.1.
6. Forecast
6.1 Night Session (6:00 PM ET Monday to 3:00 AM ET Tuesday, Globex/Asia)
Globex reopened at 6:00 PM ET on Monday with the overview showing a 4,149.0 open, 34.5 above the settle and near the 4,149.5 close of the 4:30 PM ET bar. Remarks by a Federal Reserve official at 6:30 PM ET on Tuesday are scheduled, as the calendar lists it, outside this window, and headline risk on diplomacy remains the main exposure. Bias neutral to higher above the Pivot Point at 4,111.6, expected band roughly 4,125 to 4,165.
6.2 London Session (3:00 AM ET to 8:00 AM ET Tuesday)
Remarks by a Federal Reserve official at 4:00 AM ET on Tuesday, November 10, 2026 are scheduled as the calendar lists it. Bias neutral between the Pivot Point at 4,111.6 and Pivot R1 at 4,160.6, expected band roughly 4,115 to 4,165.
6.3 Morning Session (9:30 AM ET to 12:00 PM ET Tuesday, US Open)
The consumer price index is scheduled for 8:30 AM ET on Tuesday, November 10, 2026, as the calendar lists it, and the dollar's response to it carries into this window. Remarks by a Federal Reserve official at 10:50 AM ET are listed by the news-feed calendar, unconfirmed. Expected band roughly 4,095 to 4,175, with the 4,115 to 4,125 setup band beneath the reopen price.
6.4 Afternoon Session (12:00 PM ET to 4:00 PM ET Tuesday)
A ten-year note auction at 1:00 PM ET is listed by the news-feed calendar, unconfirmed, and the 1:30 PM ET settlement window fixes the reference ahead of the Veterans Day holiday. Remarks by a Federal Reserve official are scheduled for 3:30 PM ET on Tuesday, November 10, 2026, as the calendar lists it. Expected band roughly 4,100 to 4,175.
6.5 Night Session Forward (6:00 PM ET Tuesday)
The Tuesday evening session carries into the Veterans Day holiday on Wednesday, November 11, 2026, when Globex keeps normal hours per the calendar's exchange notice, and into the producer price index scheduled for 8:30 AM ET on Friday, November 13, 2026, as the calendar lists it.
6.6 Expected Range (Tuesday Full Session)
Low-range scenario: 4,120 to 4,165
Mid-range scenario (most likely): 4,100 to 4,180
High-range scenario: 4,060 to 4,210
6.7 Most Likely Path
In this review's analyst judgment, the most probable path holds the contract above the Pivot Point at 4,111.6 and tests Pivot R1 at 4,160.6, with a pullback toward the 4,115 to 4,125 band that holds above the Pivot Point at 4,111.6 weighted above a settle beneath it. The settle is back above the 20-day average with a higher high and a higher low, the composite improved to "16% SELL" from "32% SELL" and positive direction leads on the 9-day system, while the 50-day, 100-day and 200-day averages sit overhead, which in this review's interpretation favours a long on a pullback over a long at the post-settlement extension.
The alternative that would invalidate this reading is a settle beneath Pivot S1 at 4,065.4, which would bring Monday's 4,062.5 low and Friday's 4,035.1 low into play. On the other side, a softer inflation print and a weaker dollar could carry the contract through Pivot R1 at 4,160.6 toward Pivot R2 at 4,206.8 without the pullback the setup needs.
7. Tuesday Economic Calendar
Monday's releases are complete. Wholesale trade data was released at 10:00 AM ET on Monday, November 9, 2026, as the calendar lists it, and the provider's commentary put September wholesale trade sales up 2.8 percent against an expected 1.1 percent. The news feed reported a three-year note auction yield of 4.627 percent at 3:15 PM ET, a feed item unconfirmed against the calendar. December gold settled in the 1:30 PM ET settlement window.
Remarks by a Federal Reserve official are scheduled for 4:00 AM ET on Tuesday, November 10, 2026, as the calendar lists it. The consumer price index is scheduled for 8:30 AM ET on Tuesday, November 10, 2026, as the calendar lists it, together with real earnings. The news-feed calendar lists forecasts of 0.3 percent for the monthly headline index, against 0.6 percent previously, and 0.2 percent for the monthly core index, against 0.3 percent previously. Remarks by a Federal Reserve official are scheduled for 3:30 PM ET on Tuesday, November 10, 2026, as the calendar lists it, with a second appearance at 6:30 PM ET. A ten-year note auction at 1:00 PM ET and remarks by Federal Reserve officials at 10:50 AM ET and 1:30 PM ET are listed by the news-feed calendar, unconfirmed.
Later in the week, Wednesday, November 11, 2026 is the Veterans Day holiday with Globex on normal hours and the producer price index is scheduled for 8:30 AM ET on Friday, November 13, 2026, both as the calendar lists it. In this review's judgment the first-order event for gold on Tuesday is the consumer price index at 8:30 AM ET, through the dollar and yields.
8. Primary Trade Setup
Direction: Long
Rationale: The contract printed a higher high and a higher low, settled back above the 20-day average at its highest since 10/21/26, and the composite improved to "16% SELL" from "32% SELL" with positive direction leading on the 9-day system while the dollar index closed at 101.65. A pullback into the 4,115 to 4,125 band, above the Pivot Point at 4,111.6 and the 4,114.5 settle, offers a long with a defined risk point beneath the 4,103.6 retracement. The 50-day average overhead and an inflation print that firms the dollar are the main risks, so the setup is an analyst judgment that pullbacks toward the Pivot Point at 4,111.6 are bought, with no measured edge behind it.
Entry Zone: 4,115 to 4,125
Stop Loss: 4,095 (beneath the Pivot Point at 4,111.6 and the 4,103.6 retracement, above the 4,078.8 projection)
Target 1 (T1): 4,145 (beneath the 4,149.5 close of the 4:30 PM ET bar)
Target 2 (T2): 4,170 (above Pivot R1 at 4,160.6, beneath the 4,170.1 stall)
Target 3 (T3, extended): 4,195 (above one standard deviation resistance at 4,186.0, beneath Pivot R2 at 4,206.8)
Risk-to-Reward: Approximately 1:1 to T1, 1:2 to T2, 1:3 to T3
Invalidation: A settle beneath Pivot S1 at 4,065.4 negates the thesis. Short of that, the edge is removed by acceptance beneath the entry band, defined as two consecutive 30-minute closes beneath 4,115; a touch alone does not remove it.
Macro override: A firmer inflation print that lifts the dollar and yields, or headline risk on diplomacy, could weigh on the contract. In that scenario a move through the 4,095 stop invalidates the long before the targets, and the 4,078.8 projection becomes the reference, 16.2 beyond the stop and well inside one 14-day average true range of 87.2.
Sources and methodology
This outlook is built from our session review of the December gold contract, the December ’26 contract, prepared after Monday's close on November 9, 2026 for the Tuesday, November 10, 2026 session. Monday's completed extremes are the inputs behind the published pivot ladder for Tuesday: Pivot R3 at 4,255.8 less Pivot S3 at 3,970.2, divided by three, and Pivot R2 at 4,206.8 less Pivot S2 at 4,016.4, divided by two, both return 95.2. Three times the 4,111.6 Pivot Point less the settle gives 8,220.3, which with that range solves to 4,157.75 and 4,062.55, the 4,157.7 high and the 4,062.5 low at the Pivot Point's one-decimal rounding. The provider's settlement row and the chart's completed Monday bar carry the same open, extremes and settle. Only those figures, the dated 2026-11-09 row of the provider's daily record, Monday's 30-minute bars and the review's statements are used to grade Monday's card, which was set at Friday's settle and covers the whole session from the Sunday 6:00 PM ET reopen. The 30-minute bars run from that reopen to the bar that opened at 4:30 PM ET on Monday, labelled in Eastern standard time. Each timed statement here names the bar in which a price first traded; the order of prices inside a single bar is not stated.
The provider's daily record also carries a partial row dated Tuesday, opened by the 6:00 PM ET Globex reopen; it is excluded. Friday's 2026-11-06 row has been revised since our Monday outlook: volume now reads 178,024 contracts against the preliminary 166,431, and open interest 255,460, which that outlook listed as not yet reported; Friday's prices are unchanged. The ten-year yield index's Friday close now reads 4.85 percent, against the 4.86 percent our Monday outlook carried. Monday's open interest was not yet reported, so none is stated. The moving averages were computed from the provider's daily settlement series of 259 completed sessions through Monday and rounded once to the 0.1 tick. The oscillators and range measures are cited as published, read at 6:19 PM ET on Monday after the Globex reopen, and the composite strings are quoted verbatim. The gold fund is a proxy used qualitatively; its gamma figures are modeled, its high and low volatility point fields were not used, and no fund level is translated into a futures price. The volume and open interest changes, the fund's implied move as a percent, the semiconductor index's percent change and the gold and silver comparison are computed from the stated figures. Scenario ranges are analyst judgment, and items marked unconfirmed come from the news-feed calendar or the news feed.
Monday’s outlook for this contract is here, and the crude oil contract’s Monday outlook covers the December WTI contract. Outlooks for ES, NQ, GC and CL are collected on the market outlook page, and our forward trading record is on the performance statement.